
 Global Maritime Freight Transport Market | 2026-2036
Global Maritime Freight Transport Market Size, Share, and Industry Trends Forecast 2026-2036
Global Maritime Freight Transport Market Foresight
The Asia-Europe liner network is reconfiguring around mega-vessel deployment and transshipment consolidation. Mediterranean Shipping Company anchors its strategy through aggressive fleet expansion and terminal asset control across strategic hubs. A.P. Moller-Maersk differentiates via integrated logistics offerings that extend beyond port-to-port service into inland distribution. CMA CGM leverages its regional subsidiary brands to compete across multiple trade lanes without diluting premium positioning.
Maritime freight transport encompasses the commercial movement of goods via ocean-going vessels, utilizing containerized unit loads typically measured in twenty-foot equivalent units or bulk commodity tonnage moved through specialized hull designs. The primary purpose is to connect production centers with consumption markets across transoceanic distances at unit costs below air or land alternatives. Container ships dominate value capture on east-west trunk routes where manufacturing exporters in China and Southeast Asia supply retailers in the United States and Europe. Bulk carriers sustain mature margin structures serving commodity traders moving iron ore and coal from Australia and Brazil to steel mills in East Asia. Tanker operations fluctuate with energy market volatility, reflecting spot freight exposure to crude oil and refined product movements.
The International Maritime Organization enforces carbon intensity indicator standards that mandate documented emissions reductions across existing fleets, reshaping capital allocation toward dual-fuel engine investments and hull efficiency retrofits. The European Union extends emissions trading system coverage to maritime routes entering EU ports, creating direct cost exposure for carriers serving Rotterdam, Hamburg, and Antwerp. The United States Coast Guard implements ballast water management and subchapter M towing vessel regulations that affect operational compliance for domestic feeder services. Stakeholders must monitor regulatory divergence between IMO global standards and regional unilateral measures when positioning fleet renewal programs and route deployment decisions.
Market Dynamics
The International Maritime Organization's carbon intensity indicator mandates are compressing vessel utilization economics and forcing capital reallocation toward dual-fuel propulsion systems across the global fleet.
Growth Catalysts
- EU Emissions Trading System extension:Maritime routes entering Rotterdam, Hamburg, and Antwerp now face direct carbon cost exposure, accelerating scrubber retrofits and LNG-ready newbuild orders among European-serving operators.
- East Asian manufacturing export volumes:Containerized goods flows from Shanghai, Ningbo, and Shenzhen to Los Angeles and Long Beach sustain vessel deployment density on the transpacific corridor.
- Methanol dual-fuel engine technology:Engine manufacturers are scaling production of methanol-capable two-stroke designs, enabling carriers to meet 2030 carbon intensity reduction targets without full fleet replacement.
Market Restraints
- Shipyard capacity concentration in South Korea and China:Newbuild slot scarcity through 2028 limits fleet renewal velocity and inflates vessel acquisition premiums for operators seeking compliant tonnage.
- Green methanol and ammonia supply deficit:Bunkering infrastructure for alternative fuels remains undeveloped at most transshipment hubs, constraining operational range for early-adopter vessels.
- Ballast water management system retrofit costs:The United States Coast Guard's subchapter M enforcement timeline imposes unplanned drydock expenditure on domestic feeder operators.
Strategic Opportunities
- Indian container transshipment expansion:Jawaharlal Nehru Port and Mundra are developing hub capacity to capture cargo currently relayed through Colombo and Singapore, offering tariff and logistics cost advantages.
- Cold chain pharmaceutical logistics:Temperature-controlled container services for vaccine and biologic shipments command rate premiums and long-term contract structures distinct from commodity box trades.
- Port call optimization software:Machine learning platforms that compress berth turnaround times are penetrating the intra-Asia feeder segment where schedule reliability drives carrier selection.
Industry Challenges
- Maritime engineer and dual-fuel technician shortages:Training pipelines for methanol and ammonia engine operations lag fleet deployment schedules, creating crew certification bottlenecks.
- Legacy container fleet stranded asset risk:Conventional diesel vessels face accelerating residual value decline as carbon intensity regulations tighten through 2030, complicating balance sheet management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Maritime Freight Transport Market |
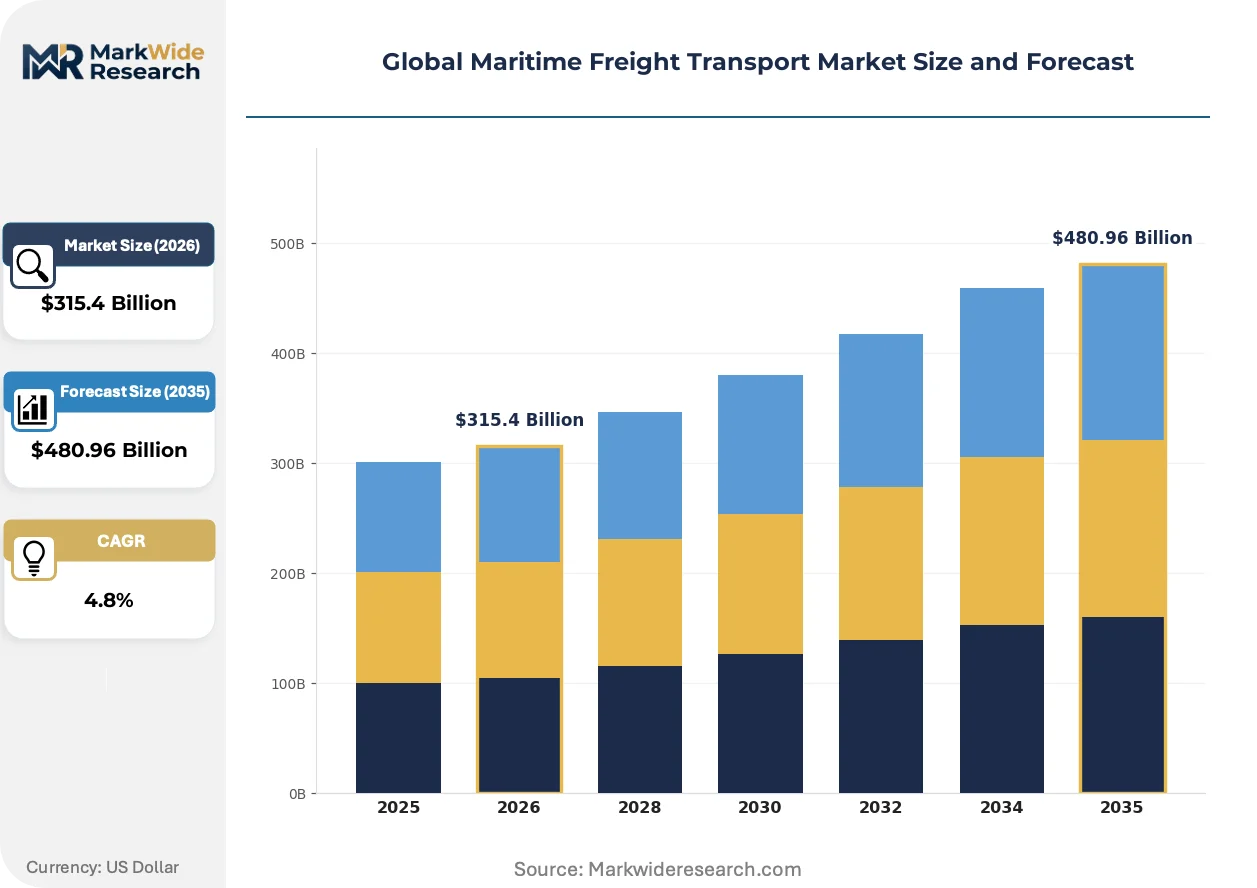
| Market Size in 2026 | $315.4 Billion |
| Market Size in 2035 | $480.96 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vessel Type: Container Ship, Bulk Carrier, Tanker, Roll-on/Roll-off, General Cargo Cargo Type: Dry Bulk, Liquid Bulk, Breakbulk, Refrigerated Cargo, Project Cargo Service Mode: Scheduled, Non-Scheduled, Charter, Contractual, Spot Freight Customer Segment: Manufacturers, Exporters, Freight Forwarders, Third-Party Logistics, Retailers |
| Companies Covered | Mediterranean Shipping Company (MSC), A.P. Moller-Maersk, CMA CGM, COSCO Shipping Lines, Hapag-Lloyd, Ocean Network Express (ONE), Evergreen Marine Corporation, HMM Co. Ltd., Yang Ming Marine Transport, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Maritime Freight Transport Market Shifts & Advancements
Digital platforms and alternative fuel pathways are restructuring how vessel capacity is deployed, priced, and consumed across ocean trade networks.
Blockchain-enabled cargo documentation systems are digitizing bill-of-lading processing and customs clearance workflows. Major retailers and automotive manufacturers are piloting paperless trade corridors between East Asia and North America. This technology stack is digitizing document-handling cost structures and compressing working capital cycles for cargo owners.
The European Union's extension of emissions trading system coverage to maritime transport is creating direct carbon price exposure for carriers serving EU ports. Steel mills and chemical producers in Germany and the Netherlands are now factoring maritime carbon costs into supplier selection criteria. Container lines are responding with premium "green corridor" services marketed to shippers with scope 3 disclosure obligations.
Cargo owners are consolidating procurement volumes with fewer carrier partners to secure capacity allocation priority during peak seasons. Retailers in the United States are negotiating multi-year contracts with dedicated vessel space commitments, displacing the spot market reliance that characterized procurement patterns from 2015 to 2020. This concentration is most visible among North American importers of furniture and electronics.
Global Maritime Freight Transport Market Segmentation
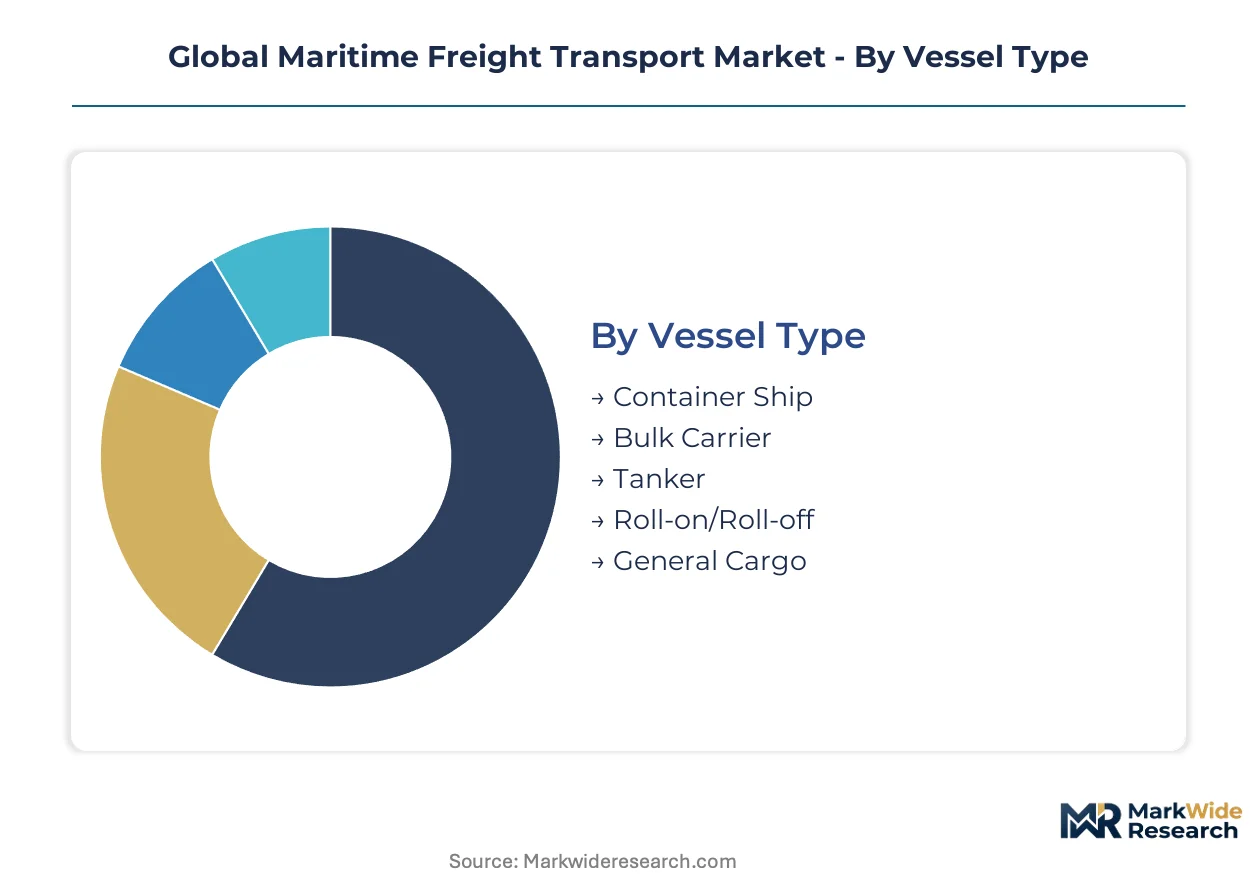
Segmentation in maritime freight transport reveals how capital allocation, operational specialization, and regulatory exposure concentrate across distinct vessel configurations and cargo categories. Understanding these divisions exposes where carbon intensity mandates bite hardest and where alternative fuel investments yield earliest returns.
Vessel Type:
Cost tier differentiation across hull designs determines fuel efficiency investment horizons and residual value trajectories for fleet operators.
- Container Ship:Cellular hulls with standardized TEU capacity dominate east-west trunk routes. Shanghai-to-Los Angeles volumes absorb the largest newbuild tonnage as retailers demand schedule reliability for inventory replenishment cycles.
- Bulk Carrier:Single-deck designs with large hatch openings move iron ore and coal from Port Hedland and Tubarão to steel mills in Ningbo and Gwangyang. Capesize fixtures face mounting scrutiny under IMO carbon intensity tracking.
- Tanker:Segregated cargo tanks transport crude and refined products with spot freight exposure to energy market volatility.
- Roll-on/Roll-off:Stern and side ramps enable wheeled cargo loading for automotive manufacturers shipping finished vehicles from Bremerhaven and Nagoya.
- General Cargo:Multi-purpose tweendeckers serve project logistics and breakbulk movements where containerization remains uneconomical.
Container ships command the established base. The steepest expansion runs through dual-fuel LNG and methanol-ready tonnage.
Cargo Type:
Physical commodity characteristics dictate stowage requirements, port infrastructure needs, and vulnerability to temperature or contamination losses.
- Dry Bulk:Unpacked commodities including iron ore, coal, and grain move in dedicated holds with grab unloading systems. Australian and Brazilian mining exporters anchor volume concentration on routes to East Asian steel and feed mills.
- Liquid Bulk:Crude oil, chemicals, and edible oils require tank segregation and pumping systems. Rotterdam and Houston refining clusters generate the densest fixture activity with direct EU emissions trading exposure.
- Breakbulk:Non-containerized manufactured goods and bagged commodities utilize general cargo vessels for project-specific handling.
- Refrigerated Cargo:Temperature-controlled reefer containers and dedicated reefer ships transport perishables from Ecuadorian banana plantations and Chilean salmon farms.
- Project Cargo:Oversized industrial components including turbines and modules demand heavy-lift vessel chartering with port engineering coordination.
Dry bulk retains the volume base. Refrigerated cargo is climbing the fastest as cold chain pharmaceutical specifications tighten.
Service Mode:
Contractual commitment depth shapes pricing volatility exposure and capital planning horizons for vessel operators.
- Scheduled:Fixed-day liner services with published sailing frequencies offer reliability premiums. Transpacific alliance networks deploy this model exclusively for retail and automotive shippers.
- Non-Scheduled:Tramp operations without fixed itineraries match vessel position to cargo availability in grain and minor bulk trades.
- Charter:Voyage and time charter structures transfer operational control to cargo interests for specific cargo movements.
- Contractual:Multi-year volume commitments with dedicated space allocation are displacing spot reliance among North American furniture importers.
- Spot Freight:Single-voyage fixtures at market-clearing rates dominate tanker and dry bulk segments with immediate price discovery.
Scheduled services command the established base. Contractual arrangements are gaining share fastest as procurement consolidation deepens.
Customer Segment:
Supply chain position determines service requirements, from production-integrated logistics to final-mile distribution coordination.
- Manufacturers:Industrial producers of electronics and machinery in Shenzhen and Ho Chi Minh City negotiate direct carrier contracts to secure export capacity allocation during peak seasons.
- Exporters:Commodity traders and agricultural cooperatives charter bulk tonnage for single-voyage movements with price hedging through forward freight agreements.
- Freight Forwarders:Non-vessel-operating common carriers aggregate less-than-containerload shipments and purchase slot capacity from liner operators.
- Third-Party Logistics:Integrated providers including A.P. Moller-Maersk extend ocean transport into inland distribution and customs brokerage.
- Retailers:Big-box and e-commerce importers in the United States are consolidating procurement with fewer carrier partners for multi-year dedicated space agreements.
Freight forwarders command the established base. Third-party logistics providers are expanding most quickly through end-to-end integration mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Carbon border adjustments and port infrastructure subsidies are redistributing maritime freight flows across major economies. The European Union's emissions trading system extension to shipping routes has altered carrier economics on transatlantic services. East Asian manufacturing clusters continue anchoring containerized export volumes despite supply chain diversification initiatives.
United States
Import demand from big-box retailers and e-commerce platforms sustains vessel deployment density on the transpacific corridor. The United States Coast Guard enforces ballast water management regulations under subchapter M, imposing compliance costs on domestic feeder operators. The Los Angeles-Long Beach port complex processes the highest container volumes, though berth congestion periodically disrupts schedule reliability for transpacific alliance services.
China
Manufacturing exporters in Shanghai, Ningbo, and Shenzhen generate the densest containerized cargo flows to North American and European consumer markets. The Ministry of Ecology and Environment implements dual carbon goals that pressure state-owned carriers to accelerate fleet renewal timelines. The Yangtze River Delta cluster concentrates newbuild vessel construction, with shipyards in Jiangsu and Zhejiang provinces capturing the majority of global container ship orders.
Germany
Industrial importers and chemical producers in the Rhine-Ruhr region factor maritime carbon costs into supplier selection criteria under EU emissions trading system coverage. The Federal Maritime and Hydrographic Agency enforces port state control inspections that detain non-compliant vessels entering Hamburg and Bremerhaven. The Port of Hamburg anchors northern European container transshipment, though hinterland rail connectivity constraints limit throughput expansion.
Singapore
Strategic positioning at the Malacca Strait chokepoint sustains bunker fuel sales and vessel repair services for east-west trunk route operators. The Maritime and Port Authority of Singapore mandates low-carbon fuel adoption timelines that accelerate LNG and methanol bunkering infrastructure investment. The Tuas megaport development consolidates terminal capacity, displacing older facilities and capturing transshipment cargo currently relayed through regional competitors.
India
Pharmaceutical and textile exporters in Gujarat and Maharashtra negotiate direct carrier contracts to secure capacity allocation during peak seasons. The Directorate General of Shipping implements tonnage tax schemes and shipbuilding subsidies under the Maritime India Vision 2030 initiative. Jawaharlal Nehru Port and Mundra are developing hub capacity to capture container transshipment currently relayed through Colombo and Singapore, offering tariff advantages for Indian cargo interests.
Global Maritime Freight Transport Market Competitive Landscape
On the supply side, the industry is consolidating around alliance networks and terminal asset control. Three carrier groupings dominate east-west trunk routes through vessel sharing agreements and coordinated capacity deployment. Strategic archetypes include integrated logistics providers extending beyond port-to-port service, asset-heavy operators prioritizing fleet scale, and regional specialists leveraging subsidiary brand portfolios. Competitive moves concentrate on dual-fuel newbuild orders and terminal acquisition programs.
Within the integrated logistics tier, A.P. Moller-Maersk exemplifies end-to-end supply chain positioning, while Mediterranean Shipping Company occupies a position emphasizing fleet expansion and hub control. Among Asia-based operators, COSCO Shipping Lines and Evergreen Marine Corporation represent state-affiliated and independent growth strategies respectively. These entities anchor competitive dynamics without exhaustive enumeration of market participants.
| Leading Market Players |
|---|
| Mediterranean Shipping Company (MSC) |
| A.P. Moller-Maersk |
| CMA CGM |
| COSCO Shipping Lines |
| Hapag-Lloyd |
| Ocean Network Express (ONE) |
| Evergreen Marine Corporation |
| HMM Co. Ltd. |
| Yang Ming Marine Transport |
| Others |
Supply & Pricing Matrix
IMO carbon intensity enforcement creates the primary risk vector that compresses vessel utilization economics while simultaneously widening spreads between compliant dual-fuel tonnage and legacy diesel assets. This regulatory chokepoint determines both the premium commanded by LNG-ready newbuilds and the geographic clustering of shipyard orders around South Korean and Chinese facilities.
Pricing Analysis
Carbon intensity certification tier creates the primary spread between premium dual-fuel vessels and standard conventional tonnage. Contract-based long-term offtake structures dominate as retailers negotiate multi-year dedicated space agreements to secure capacity allocation. Price differentiation hinges on fuel flexibility and EU emissions trading compliance status. Cost compression in the spot freight tier is intensifying because cargo owners are consolidating procurement volumes with fewer carrier partners. Freight forwarders exhibit the highest price sensitivity, while integrated third-party logistics providers absorb premiums for end-to-end service bundling.
Supply Chain Analysis
Extended payment terms from cargo owners and supply-chain finance facilities from terminal operators are restructuring working capital cycles across the maritime ecosystem. Vessel manufacturing concentrates in South Korea, China, and Japan, with Jiangsu and Zhejiang provinces anchoring container ship construction. Steel plate and marine engine components feed from specialized foundries in these same clusters. Single-source vulnerability runs through the concentrated shipyard slot availability through 2028. Distribution runs through alliance networks and vessel sharing agreements rather than independent carrier operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Maritime freight transport is approaching a platform-economics inflection where digital cargo documentation interoperability and blockchain-enabled trade corridors are consolidating information flows around carrier-neutral standards.
For Market Incumbents: Entrench terminal asset control at strategic transshipment hubs to defend against alliance network fragmentation. Accelerate dual-fuel engine investments to preempt IMO carbon intensity enforcement tightening. Vertical integration into inland distribution networks extends service differentiation beyond port-to-port competition.
For New Entrants and Emerging Players: Indian container transshipment expansion offers the most penetrable white-space opportunity as Jawaharlal Nehru Port and Mundra develop hub capacity to capture cargo currently relayed through Colombo and Singapore. Cold chain pharmaceutical logistics commands rate premiums and long-term contract structures distinct from commodity box trades. A go-to-market angle targeting vaccine and biologic shippers with temperature-controlled container expertise bypasses entrenched carrier relationships.
For Investors and Strategic Acquirers: Regional terminal operators with LNG bunkering infrastructure development rights represent the acquisition target archetype with embedded optionality on alternative fuel adoption timelines. Long-term viability frames around the 2030 carbon intensity reduction milestone and the stranded asset risk accumulating in conventional diesel fleets. The signal to watch is methanol and ammonia bunkering infrastructure deployment velocity at major transshipment hubs.
| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Fuel Fleet Renewal | LNG and methanol-ready newbuild orders from South Korean shipyards secure IMO compliance pathways. |
| Terminal Asset Acquisition | Hub control at Rotterdam and Singapore consolidates transshipment volume capture for alliance networks. |
| Digital Platform Integration | Blockchain-enabled bill-of-lading systems compress working capital cycles for automotive manufacturers. |
| Green Corridor Service Launch | Premium carbon-neutral routes to EU ports attract shippers with scope 3 disclosure obligations. |
| Cold Chain Capability Expansion | Reefer container investment targets pharmaceutical exporters in Gujarat and Maharashtra. |
Research Methodology
Initial hypotheses were tested against primary input from fleet operations directors, shipyard procurement managers, terminal engineering heads, and maritime regulatory affairs leads, and refined through secondary validation. Primary research combined structured interviews with liner alliance network planners and port authority infrastructure officers. Secondary sources included Lloyd's List vessel fixture databases, IMO greenhouse gas study submissions, EU emissions trading registry filings, and customs trade statistics from major container corridors. Bottom-up vessel deployment modeling and top-down trade flow analysis were triangulated to cross-validate volume estimates.
Demand-supply balance framing anchored the analytical approach across the projection horizon. Segmentation dimensions modeled encompassed vessel type, cargo category, service mode contractual depth, and customer supply chain position. CAGRs were derived from trade volume elasticity analysis and fleet capacity absorption rates. Industry-specific forecast inputs incorporated shipyard orderbook schedules and alternative fuel bunkering infrastructure development timelines.
The forecast holds incumbent behavior within observed patterns; aggressive fleet expansion moves by state-affiliated carriers would shift outcomes beyond modeled ranges. Forecasts reflect documented assumptions about regulatory enforcement timelines and shipyard delivery schedules. Macroeconomic trade contraction, unilateral regional carbon measures beyond IMO standards, or breakthrough ammonia propulsion technology would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
GCC Cigarette Market
Others
Global Telemetry Market
Others
Convenience Stores Market
Others
Wingboards Market
Others
Global Electroshock Weapons Market
Others
Italy Feed Additives Market
Others
Global B2B Enterprise and Industrial Wearables Market
Others
Global Laser Defense Eyewear Market
Others
Mainframe Market
Others
Rope Market
Others
Air Separation Plant Market
Others
AI in Precision Medicine Market
Others
UK Real Estate Hospitality Market
Others
Europe Digital Experience Platform Market
Others
Connected TV Market
Others
India 3D Printing Construction Market