
 South America Orange Market | 2026-2036
South America Orange Market Size, Share, and Industry Trends Forecast 2026-2036
South America Orange Market Analytics
GlobalGAP certification is rotating as the decisive gatekeeper for export market access, disqualifying smaller growers lacking integrated traceability systems. Cutrale Citrus leverages captive grove-to-port infrastructure across São Paulo and Minas Gerais to sustain year-round supply consistency. Citrosuco anchors its position through proprietary not-from-concentrate processing technology that commands premium placement in European retail channels. Dafruta competes aggressively on private-label juice concentrate contracts, extending its reach into Middle Eastern and Asian import markets.
The South America orange comprises Citrus sinensis cultivars harvested primarily for juice extraction, fresh consumption, and essential oil distillation, with Brix levels and acid ratios determining processing suitability. Valencia oranges dominate industrial offtake due to superior juice yield and extended harvest windows, while Navel cultivars occupy premium fresh export slots with their seedless profile and lower limonene bitterness. Organic grade production is accelerating fastest among certification tiers, though Standard and Conventional grades still control the bulk volume pool through food processing and beverage industry contracts.
Brazil's MAPA phytosanitary export protocols and the EU's F-Gas Regulation on cold chain refrigerants are tightening compliance costs for storage and transit operators. ANVISA's updated food additive and labeling standards for processed citrus products are forcing reformulation investments across juice concentrate lines. Stakeholders must monitor how pending EU deforestation-free supply chain due diligence rules reshape sourcing requirements for Brazilian orange derivatives.
Market Dynamics
Brazil's MAPA phytosanitary export protocols are compressing cold chain logistics timelines and disqualifying smaller growers lacking integrated traceability infrastructure, forcing consolidation around São Paulo's processing belt.
Growth Catalysts
- Not-from-concentrate processing technology:Proprietary NFC systems command premium placement in European retail channels, pulling investment toward higher-margin juice extraction capabilities.
- ANVISA's updated food additive standards:Reformulation mandates are accelerating R&D spend across concentrate lines, filtering out non-compliant processors.
- Minas Gerais grove expansion:Captive port-to-orchard infrastructure in this secondary belt extends harvest windows beyond São Paulo's seasonal constraints.
Market Restraints
- EU F-Gas Regulation:Cold chain refrigerant compliance costs are squeezing storage and transit operator margins, particularly for exporters serving Northern European markets.
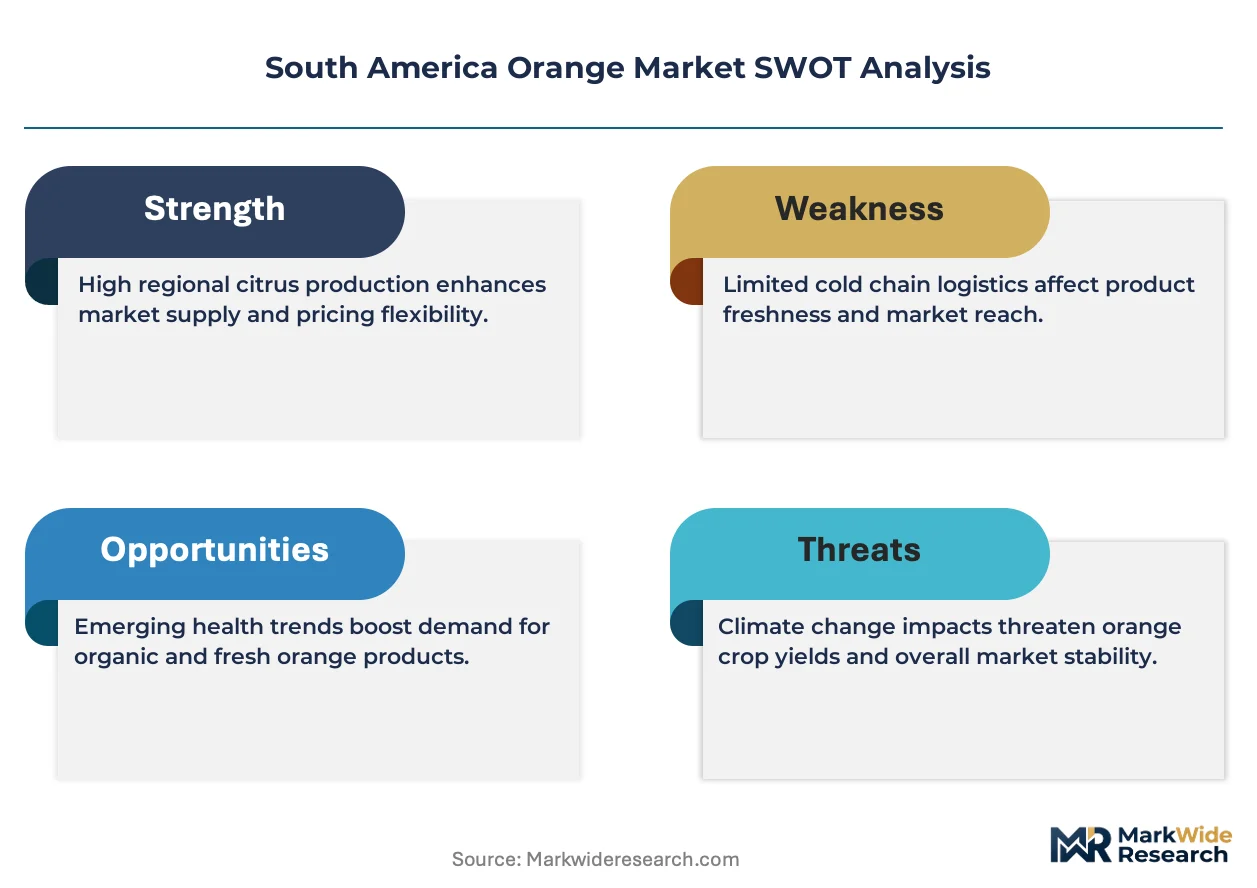
- GlobalGAP certification concentration:Export market access now hinges on integrated traceability systems that smaller independent growers cannot finance, reducing supplier diversity.
- Limonene bitterness in Navel cultivars:Lower juice yield and flavor profile limitations restrict Navel oranges to fresh export slots, capping processing flexibility.
Strategic Opportunities
- Private-label concentrate contracts:Middle Eastern and Asian import markets show unmet demand for bulk juice concentrate with flexible specification tolerances.
- Organic grade acceleration:Certification tier premiums are widening fastest in this segment, rewarding early conversion of conventional grove acreage.
- Essential oil distillation co-location:Peel oil extraction integrated with juice processing captures fuller value from Valencia harvests, a capability gap in current infrastructure.
Industry Challenges
- Phytosanitary compliance timelines:MAPA protocol updates require rapid documentation system overhauls that strain legacy farm management software.
- Cold chain capex intensity:Refrigerant retrofitting and monitoring sensor deployment demand capital that mid-tier exporters struggle to access.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Orange Market |
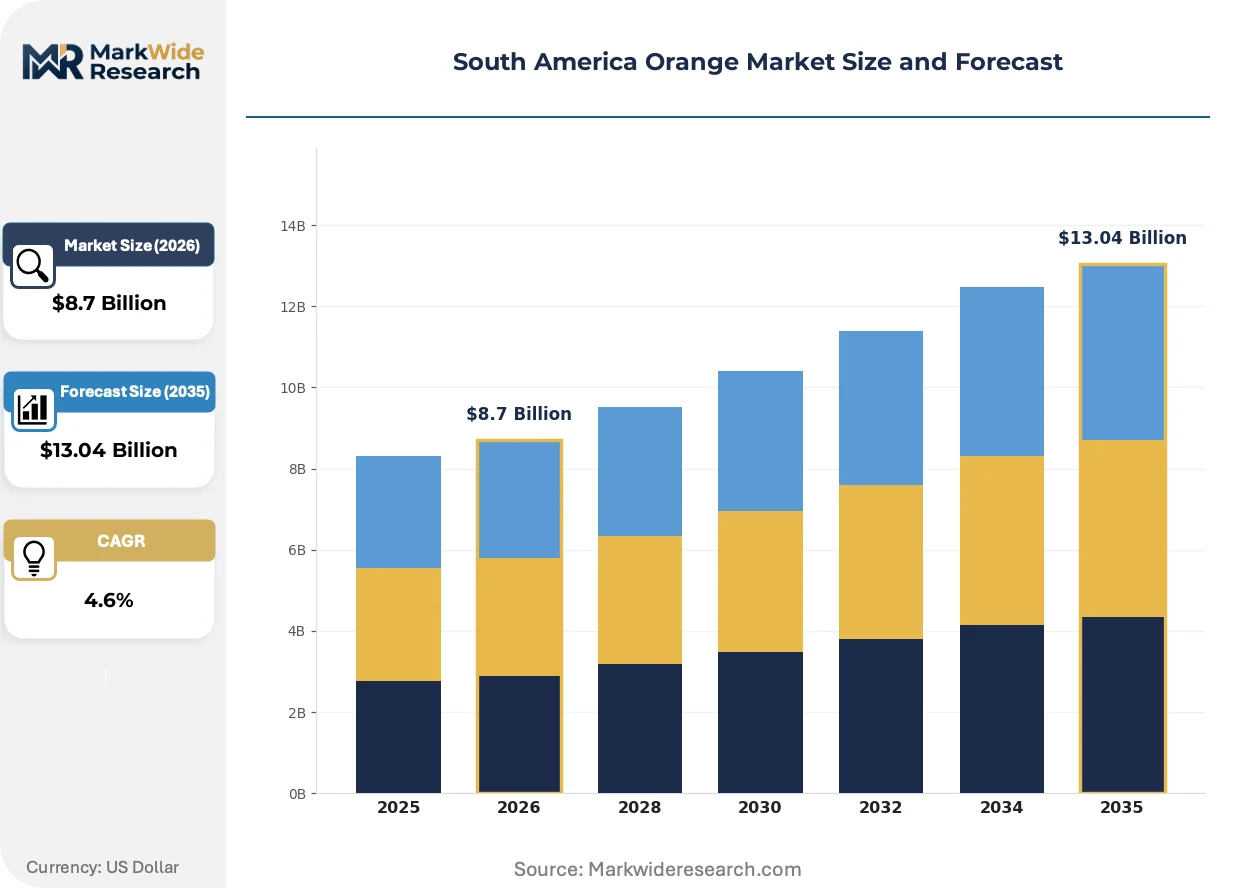
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
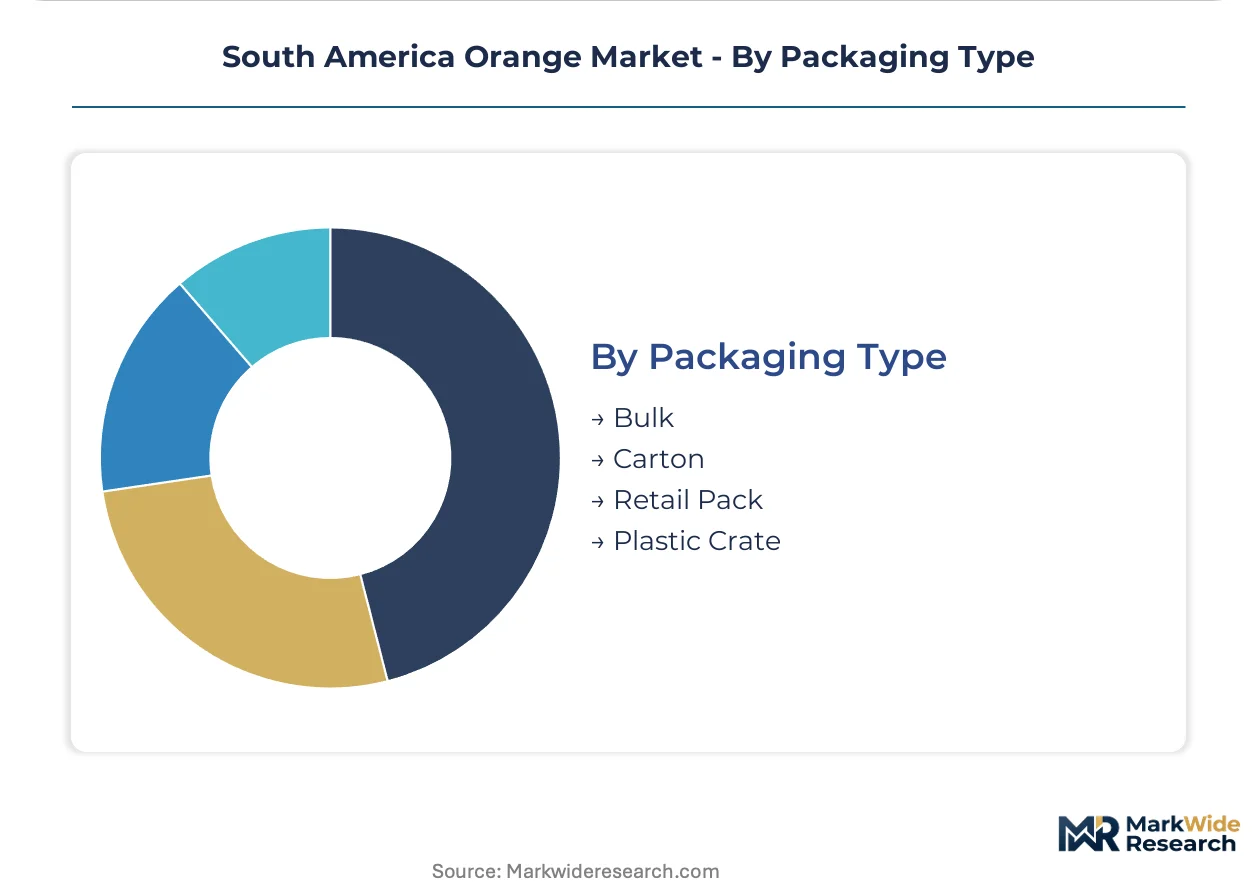
| Segmentation | Product Type: Navel, Valencia, Blood Orange, Mandarin End User: Food Processing, Beverage Industry, Fresh Market, Export Grade: Premium, Standard, Organic, Conventional Packaging Type: Bulk, Carton, Retail Pack, Plastic Crate |
| Companies Covered | Cutrale Citrus, Citrosuco, Louis Dreyfus Citrus, Dafruta, Sucocítrico Cutrale, Citrolanda, Turmalina Agropecuaria, Fischer S/A Agroindustria, Montecitrus, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Orange Market Evolving Landscape
Digital traceability platforms and climate-responsive processing technologies are compressing traditional supply chain hierarchies while regulatory pressure on cold chain emissions accelerates equipment turnover.
Blockchain-enabled grove-to-bottle tracking is decomposing opacity in provenance verification. Multinational beverage bottlers are mandating real-time temperature and origin data feeds as contract prerequisites. This transparency infrastructure is decomposing the information advantage historically held by vertically integrated processors, forcing mid-tier operators to adopt comparable systems or exit export channels.
The EU's pending deforestation-free supply chain due diligence rules are tightening sourcing documentation requirements for Brazilian orange derivatives. Processors must now geolocate every contracted grove and verify land-use change histories. European retail channels are most exposed, with several major chains already demanding satellite-verified compliance ahead of formal enforcement.
Certification-driven procurement is fragmenting traditional volume-based contracting. Buyers now segment orders across GlobalGAP, organic, and conventional tiers with distinct pricing and traceability requirements. This behavior shift is most visible in German and Dutch retail procurement, where sustainability scorecards now override historical supplier relationships in allocation decisions.
South America Orange Market Segmentation
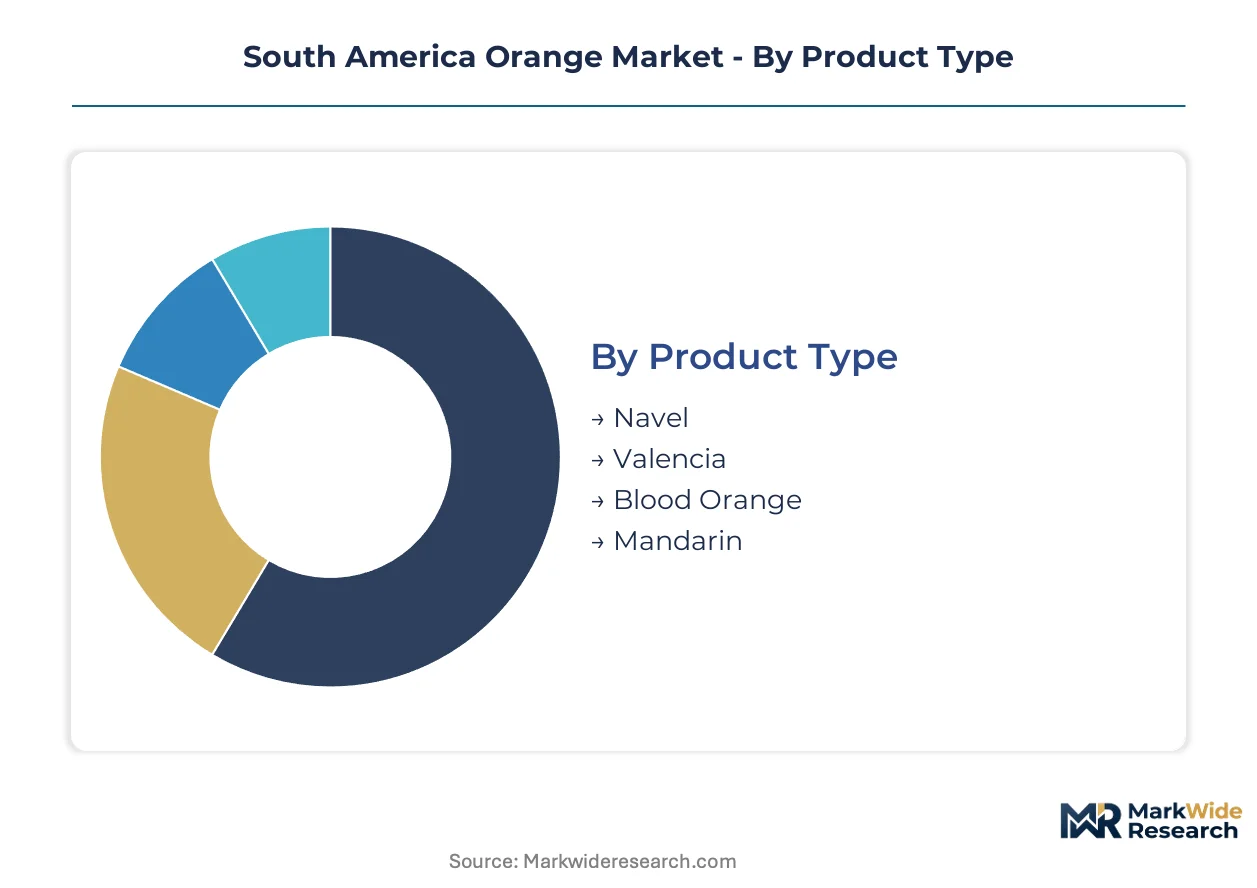
Segmentation in the South America orange market determines processing infrastructure allocation and cold chain investment priorities. Distinct product specifications, certification tiers, and packaging formats command divergent margin profiles across São Paulo's citrus belt and secondary growing zones.
Product Type:
Valencia oranges face intensifying substitution pressure from Mandarin hybrids in juice extraction applications, while Navel cultivars defend fresh export slots through seedless differentiation.
- Navel:Seedless profile and lower limonene bitterness command premium placement in European fresh retail channels. São Paulo's export-oriented packhouses concentrate procurement here for German and Dutch supermarket chains demanding GlobalGAP verification.
- Valencia:Superior Brix-acid ratios and extended harvest windows dominate industrial offtake for not-from-concentrate processing. Citrosuco and Cutrale Citrus anchor their proprietary extraction systems around this cultivar for year-round supply consistency.
- Blood Orange:Anthocyanin pigmentation and distinct flavor profile serve niche fresh consumption and specialty juice segments. Limited grove acreage in Minas Gerais restricts volume scalability.
- Mandarin:Easier peeling characteristics and sweeter taste profile compete for fresh market share, particularly in domestic Brazilian consumption and Middle Eastern import markets.
Valencia retains volume leadership; Mandarin holds the steepest expansion curve.
End User:
Cost tier stratification separates capital-intensive beverage industry contracts from fragmented fresh market procurement with divergent traceability requirements.
- Beverage Industry:Multinational bottlers mandate real-time temperature monitoring and blockchain-enabled provenance tracking as contract prerequisites. NFC technology premiums reward processors with proprietary extraction capabilities serving European retail channels.
- Food Processing:Juice concentrate and essential oil distillation demand concentrates around São Paulo's processing belt where infrastructure density exceeds secondary zones. ANVISA reformulation standards filter non-compliant operators from contract pools.
- Fresh Market:Domestic Brazilian consumption absorbs Navel and Mandarin grades through wholesale distribution networks with minimal certification overhead.
- Export:EU F-Gas Regulation compliance costs and MAPA phytosanitary documentation requirements compress margins for Northern European-bound shipments.
Beverage Industry commands the highest certification burden; Export faces the most complex regulatory layering.
Grade:
Margin dispersion across certification tiers rewards early organic conversion while Standard grade defends volume through food processing contracts.
- Organic:Certification premiums widen fastest as European retail procurement shifts toward sustainability scorecards. German and Dutch chains now override historical supplier relationships based on organic tier compliance.
- Premium:GlobalGAP verification and superior Brix specifications serve not-from-concentrate bottlers commanding placement in high-margin retail channels.
- Standard:Conventional traceability meets bulk juice concentrate specifications for private-label contracts in Middle Eastern and Asian import markets.
- Conventional:Ungraded volume supplies domestic food processing with minimal documentation overhead.
Standard retains volume leadership; Organic climbs the fastest.
Packaging Type:
Supply concentration in São Paulo's port-to-orchard infrastructure favors bulk and carton formats for export-oriented processors.
- Bulk:Tanker and flexitank configurations dominate juice concentrate shipments to beverage bottlers. Dafruta's private-label contracts rely on this format for cost-efficient Middle Eastern and Asian distribution.
- Carton:Retail-ready packaging for European supermarkets demands integrated cold chain monitoring from São Paulo through Rotterdam and Hamburg ports.
- Retail Pack:Consumer-facing formats serve domestic Brazilian supermarket chains with shorter distribution radii and lower compliance costs.
- Plastic Crate:Reusable logistics containers circulate within São Paulo state's citrus belt for fresh market distribution to wholesale terminals.
Bulk retains volume leadership; Carton gains share fastest in export channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Multinational beverage bottlers and European retail chains command procurement decisions across South America's orange belt, concentrating investment in São Paulo's processing corridor while Minas Gerais emerges as a secondary supply node.
Brazil
São Paulo state's citrus belt hosts the densest concentration of not-from-concentrate processing infrastructure, with MAPA's updated phytosanitary protocols compressing cold chain timelines and disqualifying smaller growers lacking integrated traceability. ANVISA's reformulation standards for processed citrus products filter non-compliant operators from contract pools. Minas Gerais grove expansion extends harvest windows through captive port-to-orchard infrastructure.
Argentina
Entre Ríos and Tucumán provinces supply fresh export volumes to Brazilian processing facilities and Chilean transshipment hubs, with Valencia cultivars dominating industrial offtake. The country's national agricultural regulator enforces export certification aligned with EU F-Gas cold chain requirements. Mendoza's emerging citrus zones target premium fresh segments for Andean domestic consumption.
Chile
Valparaíso and Metropolitan Region packhouses serve as consolidation points for Argentine and Uruguayan fresh orange exports to Pacific Rim markets, leveraging the country's phytosanitary reputation for GlobalGAP verification. The national agricultural service enforces strict cold treatment protocols for Mediterranean fruit fly exclusion. Santiago-based logistics operators specialize in temperature-controlled transshipment for Asian-bound Navel shipments.
Uruguay
Colonia and Salto departments supply early-season fresh volumes to Brazilian processors and Argentine exporters, with smaller grove scale limiting vertical integration potential. The country's food safety authority maintains equivalence agreements with Brazilian MAPA for cross-border citrus movement. Montevideo port infrastructure handles limited but growing reefer container volumes for European spot markets.
Peru
Ica and La Libertad valleys exploit counter-seasonal harvest windows to supply North American fresh markets during Brazilian off-seasons, with seedless Navel cultivars commanding premium placement. The national agricultural health service enforces HLB disease exclusion zones that restrict grove expansion. Lima-based export packers invest in forced-air cooling systems for extended transit to US West Coast terminals.
South America Orange Market Competitive Landscape
Player mix skews toward vertically integrated processors with captive grove holdings and proprietary extraction technology. Three structural tiers define competitive positioning: multinational processors commanding European retail channels, mid-tier concentrate suppliers serving private-label contracts, and regional fresh exporters with limited processing footprint. Dominant competitive moves include backward integration into grove acquisition and technology licensing for not-from-concentrate systems.
Among São Paulo-based integrated processors, Cutrale Citrus and Citrosuco exemplify the captive supply archetype, while Dafruta occupies a position within the private-label concentrate tier. These three anchors demonstrate how scale and certification infrastructure determine export market access under tightening EU and Brazilian regulatory frameworks.
| Leading Market Players |
|---|
| Cutrale Citrus |
| Citrosuco |
| Louis Dreyfus Citrus |
| Dafruta |
| Sucocítrico Cutrale |
| Citrolanda |
| Turmalina Agropecuaria |
| Fischer S/A Agroindustria |
| Montecitrus |
| Others |
Value Network & Pricing Analysis
Forty-five-day harvest-to-concentrate turnaround windows in São Paulo's citrus belt concentrate pricing power among processors with captive cold chain infrastructure, while smaller independent growers face margin compression from MAPA documentation burdens and EU F-Gas retrofit costs. This lead-time compression rewards vertically integrated operators able to bridge grove-to-port logistics without third-party cold storage intermediaries.
Pricing Analysis
Cost-plus contracts indexed to FCOJ futures and spot Brix differentials dominate beverage industry procurement, with Citrosuco and Cutrale Citrus commanding premium placement through proprietary NFC technology. Price differentiation hinges on GlobalGAP certification tier and organic grade conversion status, with German retail chains paying sustainability scorecard premiums. Pricing pressure stems from Mandarin hybrid substitution in juice extraction applications, eroding Valencia processor margins. Private-label concentrate buyers in Middle Eastern markets exhibit highest price sensitivity, while European NFC bottlers show inelastic demand for certified supply.
Supply Chain Analysis
Brazil and Argentina anchor South American orange supply, with São Paulo state's processing belt hosting densest juice extraction infrastructure and Entre Ríos supplying fresh export volumes to Brazilian facilities. Raw material flows draw from Valencia and Navel cultivar acreage, with cold chain refrigerants and flexitank packaging as critical inputs. Supply chain risk centers on single-source vulnerability to HLB disease spread in São Paulo's concentrated grove zones. Distribution runs through São Paulo port terminals for European-bound concentrate, with Santiago and Montevideo serving Pacific Rim and spot market transshipment nodes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mandarin hybrid encroachment on juice extraction applications threatens Valencia-dominant processor margins, requiring incumbents to defend NFC technology premiums and organic certification tier positioning against substitute fruit substitution.
For Market Incumbents: Fortify captive supply consistency through backward integration into Minas Gerais grove expansion, extending harvest windows beyond São Paulo's seasonal constraints. Deepen blockchain-enabled traceability infrastructure to meet EU deforestation-free due diligence documentation requirements ahead of formal enforcement, locking in German and Dutch retail channel access against emerging concentrate competitors. For New Entrants and Emerging Players: Differentiate on organic grade certification and essential oil distillation co-location capabilities, capturing fuller value from Valencia peel oil extraction that incumbent processors underutilize. Target Middle Eastern private-label concentrate contracts with flexible specification tolerances, leveraging Dafruta's market position as proof of concept for bulk juice concentrate penetration without European retail channel certification burdens. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because MAPA phytosanitary compliance timelines and cold chain capex intensity are filtering non-compliant operators from export contract pools, concentrating supplier diversity reduction. Acquire mid-tier processors with GlobalGAP infrastructure and São Paulo port access. Monitor EU deforestation-free supply chain due diligence rule enforcement timing as inflection indicator for certification-premium sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Grove Acquisition | Captive supply secures year-round Valencia harvest consistency for NFC processing lines serving European retail. |
| Blockchain Traceability Platform Deployment | Real-time provenance verification meets multinational bottler contract prerequisites and EU due diligence documentation. |
| Organic Certification Conversion Program | Sustainability scorecard alignment unlocks German and Dutch retail procurement premium tiers. |
| Cold Chain Refrigerant Retrofit Investment | F-Gas Regulation compliance preserves Northern European market access for São Paulo export shipments. |
| Essential Oil Distillation Co-location | Peel oil extraction integration captures fuller value from Valencia harvests currently underutilized by concentrate-focused processors. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across São Paulo's citrus belt and secondary growing zones, combining structured interviews with juice extraction plant managers, MAPA compliance officers at export packhouses, European retail procurement directors, and cold chain logistics operators with secondary validation. Trade flow data from Brazilian customs authorities, ANVISA regulatory filings, EU F-Gas implementation reports, and industry association harvest statistics anchored bottom-up volume modeling against top-down market sizing.
Across the analysis window, forecasts triangulate product type segmentation by cultivar, certification tier stratification across organic and GlobalGAP grades, end-user channel splits between beverage industry and fresh export, and packaging format differentiation. CAGRs derive from historical harvest yield trajectories, processing capacity expansion announcements, and substitution elasticity estimates for Mandarin hybrid displacement. Modeled inputs include São Paulo grove acreage conversion rates and European retail sustainability scorecard adoption curves.
Material uncertainties — HLB disease spread velocity, EU deforestation-free rule enforcement timing, and F-Gas refrigerant cost pass-through acceptance — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding MAPA protocol stability and concentrate demand from multinational bottlers. Recalibration cycles align with material shifts in phytosanitary regulatory frameworks and cold chain emission compliance thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
High Voltage Measuring Equipment Market
Others
ASEAN Agricultural Logistics Market
Others
Tripod Market
Others
Latin America Travel Retail Market
Others
Space Cables Market
Others
Europe Military 4D Printing Market
Others
Mobile Computer Market
Others
Lepidolite Market
Others
Global Essential Oils and Plant Extracts for Livestock Market
Others
Japan 3D Printing Construction Market
Others
Advertising Intelligence Solution Market
Others
Space Power Supply Market
Others
Grna Market
Others
Construction Fabrics Market
Others
Hookah Tobacco Market
Others
Architectural Fabrics Market