
 Commercial Aircraft Angle of Attack Sensors Market | 2026-2036
Commercial Aircraft Angle of Attack Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
Commercial Aircraft Angle of Attack Sensors Market Insights
Aftermarket sensor refurbishment and recalibration revenue is tilting toward OEM-authorized channels as fleet operators prioritize traceable certification. Honeywell International Inc. leverages its integrated flight deck ecosystem to capture recurring calibration contracts. Thales Group anchors European retrofit demand through EASA-certified repair stations. Collins Aerospace competes on platform-specific sensor integration across Boeing and Airbus programs.
Commercial aircraft angle of attack sensors measure airflow incidence relative to wing chord, typically employing vane mechanisms with resolutions below 0.1 degree to trigger stall warning systems and automated pitch correction. These devices prevent aerodynamic stall through real-time data feed to flight control computers and pilot displays. Conventional vane sensors dominate installed base maintenance, while fiber optic architectures attract next-generation fly-by-wire programs for electromagnetic immunity. Electrostatic and piezoelectric technologies gain traction as manufacturers seek solid-state alternatives to mechanical vanes in high-vibration environments.
FAA airworthiness directives mandate redundant AOA indication and expanded stall warning system testing intervals, compelling carriers to upgrade legacy single-sensor configurations. EASA aligns with FAA standards through CS-25 certification requirements, while China's CAAC enforces equivalent compliance for imported and domestically certified aircraft. Stakeholders must monitor evolving flight control automation standards as regulators weigh mandatory AOA disagree alerts against installation cost burdens on aging fleets.
Market Dynamics
FAA airworthiness directives mandating redundant angle of attack monitoring are forcing fleet-wide retrofits across aging narrowbody and widebody platforms, compressing replacement cycles and elevating certification requirements for sensor suppliers.
Growth Catalysts
- CS-25 Certification Alignment:EASA harmonization with FAA stall-warning system standards compels European carriers to upgrade single-sensor configurations, expanding addressable retrofit demand across Airbus-operated fleets.
- China's Indigenous Aircraft Programs:COMAC C919 production ramp and ARJ21 fleet expansion create captive demand for domestically certified AOA sensor suppliers serving state-owned airlines.
- Fiber Optic Architectures:Electromagnetic immunity requirements in next-generation fly-by-wire programs accelerate solid-state sensor adoption over conventional vane mechanisms.
Market Restraints
- Titanium Alloy Input Volatility:Sensor housing and vane fabrication depends on aerospace-grade titanium supply concentrated in Russian and Chinese smelters, exposing OEMs to price swings and export restriction risks.
- Dual-Source Certification Burden:FAA and EASA require independent validation of redundant sensor configurations, doubling qualification timelines and engineering overhead for retrofit programs.
- Piezoelectric Substitution Threat:Solid-state piezoelectric airflow sensors offer reduced moving-part maintenance, threatening vane-based incumbent technologies in high-vibration engine-nacelle installations.
Strategic Opportunities
- India Narrowbody Fleet Expansion:IndiGo and Air India Airbus A320neo order backlogs create sustained aftermarket sensor demand through 2035 as domestic traffic doubles.
- Automated AOA Disagree Alerts:Pending FAA mandates for cockpit disagreement warnings open retrofit revenue for flight deck integrators bundling sensors with display systems.
- Blockchain Certification Tracking:Distributed ledger systems for sensor calibration records enable MRO providers to offer traceable refurbishment services outside OEM-authorized channels.
Industry Challenges
- Avionics Systems Integration Talent:Shortage of engineers qualified in ARINC 429 and CAN bus protocols for sensor-to-flight-computer interfacing delays retrofit deployment timelines.
- Legacy Boeing 737NG Certification Pathways:Aging fleets require waivers or supplemental type certificates for redundant AOA installations, creating regulatory uncertainty for cost-sensitive operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commercial Aircraft Angle of Attack Sensors Market |
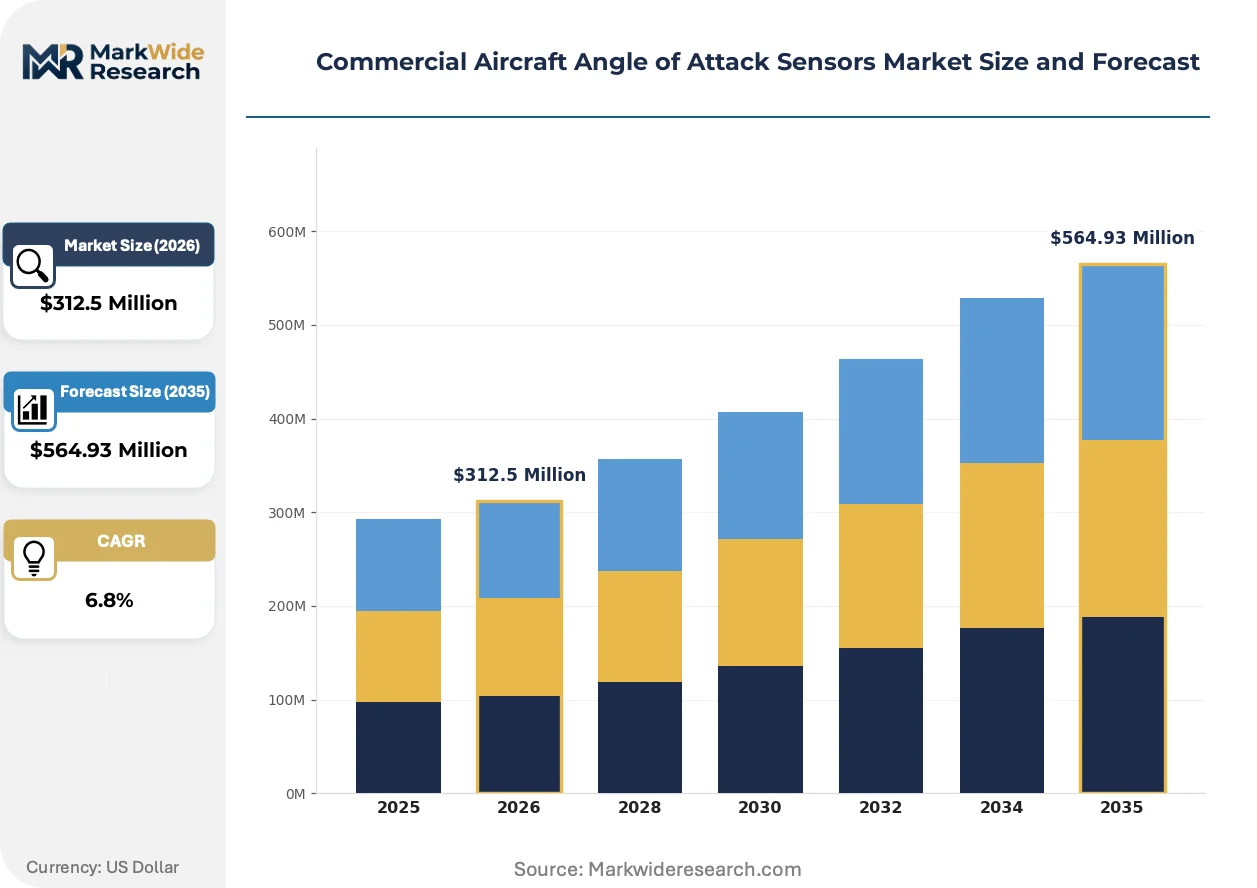
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $564.93 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Conventional Sensor, Ultrasonic Sensor, Laser Sensor, Radar Sensor, Fiber Optic Sensor Technology: Mechanical, Electrostatic, Thermal, Optical, Magnetic, Piezoelectric Application: Commercial Jets, Cargo Aircraft, Business Jets, Training Aircraft, Surveillance Aircraft End User: Airlines, MRO Providers, Aircraft Manufacturers, Defense Contractors |
| Companies Covered | Honeywell International Inc., Thales Group, Collins Aerospace, AMETEK Inc., Raytheon Technologies Corporation, Garmin Ltd., BAE Systems Plc, TransDigm Group Inc., Dynon Avionics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commercial Aircraft Angle of Attack Sensors Market Trends and Innovations
Sensor architectures are converging toward solid-state designs as electromagnetic interference resilience becomes non-negotiable in modern fly-by-wire platforms. Three developments are compressing technology refresh cycles.
MEMS-based thermal anemometry is virtualizing traditional vane mechanisms by measuring airflow incidence through heated-element resistance changes rather than mechanical deflection. Airbus A350 and Boeing 787 operators are specifying these packages for pitot-static replacement programs. The technology is virtualizing maintenance schedules by eliminating moving-part wear and enabling predictive health monitoring through embedded diagnostics.
REACH restrictions on hexavalent chromium surface treatments are compelling European sensor manufacturers to adopt trivalent chrome and plasma electrolytic oxidation coatings for vane corrosion protection. Thales and Safran suppliers face reformulation deadlines affecting repair station processes. Widebody programs with 25-year service lives are prioritizing coating compatibility with existing depot repair infrastructure.
Airline technical procurement teams are consolidating sensor purchases through flight deck OEMs rather than independent component suppliers, bundling AOA units with integrated avionics suites. This channel compression disadvantages standalone sensor vendors lacking Collins or Honeywell ecosystem relationships. Asia-Pacific carriers with expanding A320neo fleets are most aggressively pursuing single-source flight control procurement contracts.
Commercial Aircraft Angle of Attack Sensors Market Segmentation
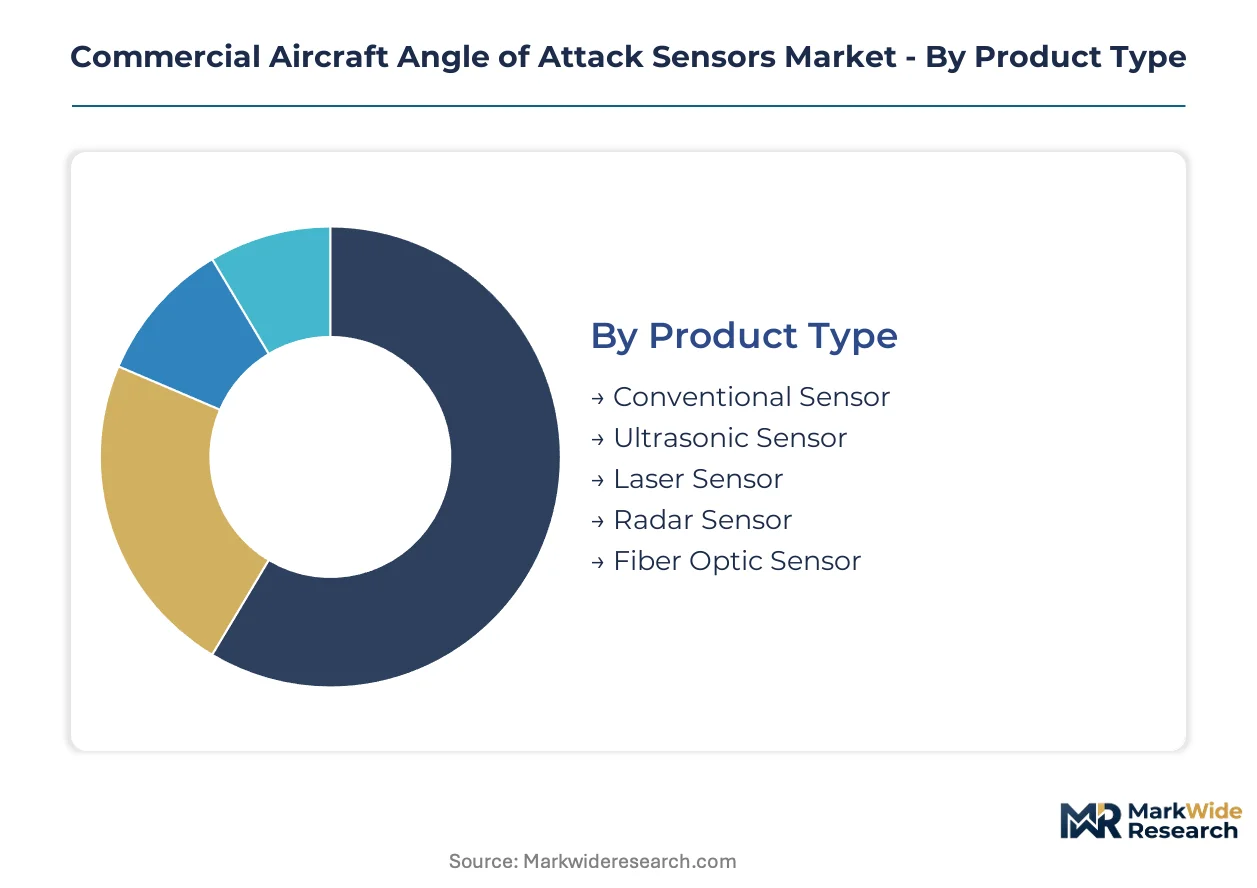
Segmentation in the commercial aircraft angle of attack sensors market reveals divergent replacement cycles across sensing technologies and platform applications. Mechanical vane sensors installed on legacy narrowbody fleets require 3-5 year overhaul intervals, while solid-state fiber optic units on next-generation platforms extend service lives beyond 10 years. Understanding these temporal patterns shapes supplier capacity planning and aftermarket revenue forecasting.
Product Type:
Replacement velocity varies dramatically by sensing architecture, with electromechanical units turning over fastest and photonic systems slowest due to wear characteristics.
- Conventional Sensor:Vane-actuated mechanical assemblies with titanium alloy housings dominate installed base maintenance across Boeing 737NG and Airbus A320ceo fleets. Airlines in India and China prioritize these units for cost-sensitive retrofit programs where dual-source certification burdens strain engineering budgets.
- Fiber Optic Sensor:Solid-state architectures employing interferometric strain measurement deliver electromagnetic immunity for fly-by-wire flight control systems. Airbus A350 and Boeing 787 operators in Japan and South Korea specify these packages for extended mean-time-between-failures in high-interference avionics bays.
- Ultrasonic Sensor:Time-of-flight airflow measurement units serve auxiliary applications on regional turboprops.
- Laser Sensor:Coherent light-based incidence detection remains developmental for supersonic platforms.
- Radar Sensor:Microwave Doppler systems face weight penalties limiting adoption outside military derivatives.
Conventional sensors anchor the volume base while fiber optic sensors gain share at the steepest rate.
Technology:
Cost tier stratification separates mature electromechanical methods from premium solid-state alternatives, with qualification overhead driving procurement decisions.
- Mechanical:Pivoting vane mechanisms with potentiometric or synchro position encoding represent the lowest unit cost but highest lifecycle maintenance burden. FAA airworthiness directives mandating redundant configurations compel US carriers to double mechanical sensor counts on aging Boeing 737NG fleets rather than migrate to solid-state architectures.
- Piezoelectric:Crystal-based airflow strain detection eliminates moving parts for high-vibration engine-nacelle installations. Thales and Safran suppliers in France pursue EASA certification for these units as REACH restrictions on hexavalent chromium coatings increase mechanical sensor refurbishment costs.
- Electrostatic:Capacitive displacement sensing offers intermediate reliability for regional jet applications.
- Thermal:MEMS-based anemometry packages are virtualizing maintenance through heated-element resistance monitoring.
- Optical:Photonic architectures command premium pricing for electromagnetic immunity.
- Magnetic:Hall-effect and magnetoresistive configurations serve niche compass-integrated systems.
Mechanical technology commands the largest installed base though piezoelectric alternatives are climbing the fastest as vibration tolerance becomes decisive.
Application:
Platform utilization intensity determines sensor degradation rates, with high-cycle narrowbodies demanding more frequent replacement than low-utilization business jets.
- Commercial Jets:Single-aisle and widebody passenger aircraft operating 8-12 daily cycles impose maximum wear on vane bearings and pivot seals. IndiGo and Air India in India drive concentrated demand as A320neo fleet expansion doubles domestic traffic capacity through 2035.
- Training Aircraft:High-stall-maneuver flight schools accelerate sensor fatigue through repetitive angle-of-attack excursions. CAAC-certified aeroclubs in China replace mechanical units at 40% shorter intervals than airline operators due to intensive touch-and-go patterns.
- Cargo Aircraft:Freighter conversions of passenger airframes reuse existing sensor configurations with recalibration protocols.
- Business Jets:Low-utilization corporate fleets extend sensor service lives through gentile operational profiles.
- Surveillance Aircraft:Special-mission platforms require hardened variants for extended loiter endurance.
Commercial jets generate the dominant revenue pool while training aircraft exhibit the most compressed replacement cycles.
End User:
Procurement authority concentration varies by customer type, with airlines controlling aftermarket decisions and OEMs dictating new aircraft specifications.
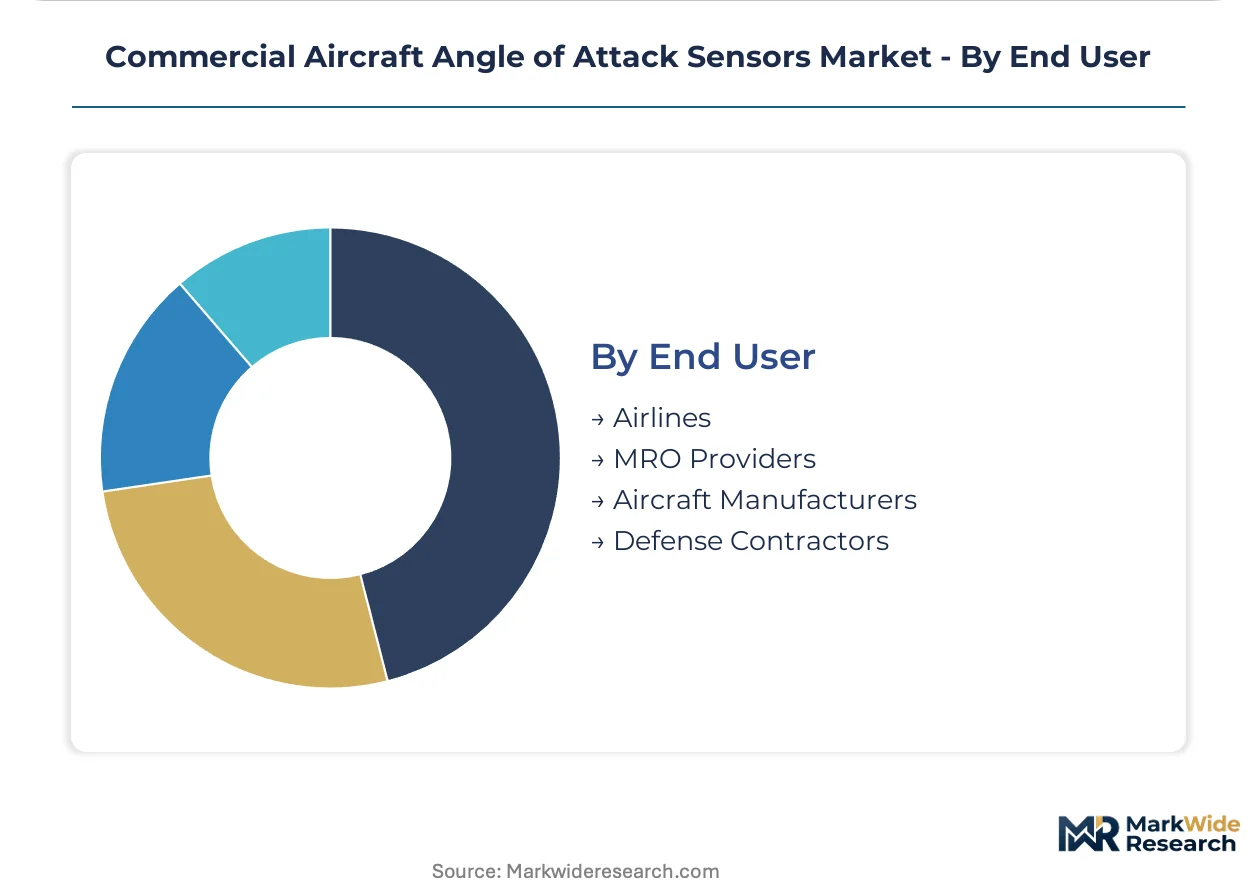
- Airlines:Fleet operators with in-house engineering capabilities manage sensor replacement through direct OEM contracts or MRO provider agreements. Asia-Pacific carriers consolidating purchases through flight deck integrators like Honeywell and Collins disadvantage standalone sensor vendors lacking ecosystem relationships.
- MRO Providers:Independent repair stations and OEM-authorized depots compete for refurbishment and recalibration revenue. EASA-certified stations in Germany and France capture European retrofit demand as traceable certification becomes non-negotiable for fleet operators.
- Aircraft Manufacturers:Boeing and Airbus specify sensor configurations for new production lines, with COMAC in China developing captive supplier relationships for C919 and ARJ21 programs.
- Defense Contractors:Military derivative platforms require ITAR-controlled supply chains with restricted vendor pools.
Airlines command the largest procurement volume while MRO providers are expanding most quickly as fleet operators outsource technical capabilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial aircraft angle of attack sensor deployment varies sharply by geography. North American carriers favor redundant retrofit configurations for aging narrowbodies, while Asia-Pacific operators prioritize fiber optic integration on new-generation fleets. European demand concentrates on REACH-compliant refurbishment protocols.
United States
FAA airworthiness directives mandate redundant AOA monitoring across Boeing 737NG and 737 MAX fleets operated by American Airlines, Delta, and United. The FAA's 2023 expanded stall-warning system testing intervals compel carriers to upgrade legacy single-sensor installations. Seattle-Tacoma aerospace cluster hosts Honeywell and Collins Aerospace calibration facilities serving domestic retrofit programs.
China
COMAC C919 production ramp and ARJ21 fleet expansion generate captive demand for domestically certified AOA sensors at state-owned airlines including Air China and China Eastern. CAAC enforces FAA-equivalent compliance standards for imported and indigenously certified aircraft. Shanghai Pudong aerospace manufacturing corridor concentrates Thales joint venture operations serving narrowbody assembly lines.
India
IndiGo and Air India Airbus A320neo order backlogs drive sustained aftermarket sensor demand through 2035 as domestic passenger traffic doubles. DGFT import certification requirements for avionics components create procedural friction for foreign suppliers. Bengaluru-Hyderabad aviation maintenance corridor expands MRO capacity for sensor recalibration and refurbishment services.
France
Thales Group anchors European retrofit demand through EASA-certified repair stations serving Air France-KLM and Transavia fleets. REACH restrictions on hexavalent chromium surface treatments compel sensor manufacturers to adopt trivalent chrome coatings for vane corrosion protection. Toulouse-Blagnac aerospace cluster coordinates Safran supplier networks for A350 and A320neo production integration.
Japan
All Nippon Airways and Japan Airlines specify fiber optic AOA architectures for Boeing 787 and Airbus A350 fleets operating high-interference Pacific routes. METI industrial standards harmonize with FAA electromagnetic immunity requirements for fly-by-wire flight control systems. Nagoya aerospace manufacturing district hosts Mitsubishi Heavy Industries component integration facilities serving regional sensor procurement.
Commercial Aircraft Angle of Attack Sensors Market Competitive Landscape
Capability concentration sits with integrated flight deck OEMs; scale advantage sits with diversified aerospace conglomerates. The market structures around three tiers: avionics ecosystem integrators commanding bundled procurement contracts, independent sensor specialists competing on platform-specific certification, and emerging domestic suppliers serving captive indigenous aircraft programs. Consolidation pressure intensifies as airlines consolidate sensor purchases through single-source flight control agreements. Strategic moves center on dual-source certification partnerships and MRO channel capture for recurring calibration revenue.
Within the avionics integrator tier, Honeywell International Inc., Thales Group, and Collins Aerospace exemplify contrasting geographic and structural positioning. Honeywell leverages its integrated flight deck ecosystem to anchor North American retrofit demand. Thales occupies a position within European regulatory frameworks through EASA-certified repair station networks. Collins represents the platform-specific integration archetype across Boeing and Airbus production lines. Each exemplifies how ecosystem relationships determine procurement channel access in consolidated airline technical purchasing environments.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Thales Group |
| Collins Aerospace |
| AMETEK Inc. |
| Raytheon Technologies Corporation |
| Garmin Ltd. |
| BAE Systems Plc |
| TransDigm Group Inc. |
| Dynon Avionics |
| Others |
Pricing and Supply Chain Analysis
Titanium alloy smelter concentration in Russia and China anchors margin capture downstream, with aerospace-grade material scarcity translating directly into sensor housing cost premiums for OEMs and tiered aftermarket pricing for fleet operators.
Pricing Analysis
Long-term offtake agreements dominate procurement between major airlines and flight deck integrators, locking in volume commitments for A320neo and 787 sensor suites across multi-year fleet renewal cycles. Price differentiation separates FAA-certified redundant configurations from single-sensor legacy units, with certification grade and electromagnetic immunity specifications commanding substantial premiums. Pricing pressure stems from airline technical procurement teams consolidating purchases through Honeywell and Collins ecosystem bundles, squeezing standalone sensor vendors on unit economics. Low-cost carriers in India exhibit highest price sensitivity, prioritizing conventional vane sensors for cost-sensitive retrofit programs, while Japanese operators on Pacific routes show least sensitivity when specifying fiber optic architectures for interference resilience.
Supply Chain Analysis
Upstream feedstock for aerospace-grade titanium alloys draws from Russian VSMPO-AVISMA and Chinese Baoji Titanium smelters, with Western alternative capacity concentrated in TIMET's US operations and ATI's specialty materials division. Sensor housing fabrication rests on titanium billet supply, precision machining capabilities, and REACH-compliant surface treatment chemicals. Single-source vulnerability runs through Russian titanium export restrictions triggered by geopolitical sanctions, exposing OEMs to qualification delays for alternative suppliers. Distribution runs through OEM-authorized depots and EASA-certified repair stations, with blockchain-enabled MRO providers emerging as traceable refurbishment alternatives to captive channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market fragmentation creates entry niches as regulatory divergence between FAA airworthiness directives and CAAC indigenous certification requirements splinters procurement standards across geographic clusters.
For Market Incumbents: Insulate calibration revenue streams by deepening backward integration into sensor refurbishment infrastructure at Seattle-Tacoma and Toulouse-Blagnac aerospace clusters. Secure dual-source certification partnerships with Thales and Safran networks to preempt piezoelectric substitution threats in high-vibration engine-nacelle applications. Channel control through flight deck ecosystem bundling remains the critical defensive lever against standalone vendor price erosion. For New Entrants and Emerging Players: Establish a beachhead in India's narrowbody aftermarket through DGFT-compliant import pathways serving IndiGo and Air India A320neo expansion programs. Target CAAC certification for COMAC C919 and ARJ21 captive supplier relationships as the most penetrable geography, leveraging state-owned airline procurement concentration. A go-to-market angle centered on blockchain-enabled calibration record transparency can dislodge incumbent MRO relationships among cost-sensitive regional carriers. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated sensor specialists with EASA-certified repair station networks and established Boeing or Airbus platform integration credentials. Long-term viability across the projection horizon favors suppliers with demonstrated electromagnetic immunity qualification for fly-by-wire programs. The signal to watch is pending FAA mandates for automated AOA disagree alerts, which would force retrofit spending inflection across aging 737NG fleets.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Source Certification Partnership | EASA-FAA harmonization accelerates qualification timelines for redundant sensor configurations. |
| Backward Integration into Titanium Machining | In-house housing fabrication mitigates VSMPO-AVISMA supply disruption risks for Western OEMs. |
| Blockchain Calibration Tracking Deployment | Distributed ledger systems enable MRO providers to compete for traceable refurbishment outside OEM channels. |
| Fiber Optic Architecture Scale-Up | Electromagnetic immunity specifications for A350 and 787 programs displace conventional vane units. |
| CAAC Certification Investment | COMAC C919 production ramp creates captive demand at Air China and China Eastern. |
Research Methodology
A standing panel of flight deck integration engineers, airline technical procurement directors, EASA certification specialists, and MRO station managers provided ongoing calibration against secondary validation from FAA airworthiness directive filings, EASA CS-25 certification databases, COMAC supplier disclosure records, and customs trade data for aerospace-grade titanium imports. Bottom-up sensor unit demand estimates triangulated against top-down fleet projection models across narrowbody and widebody platform categories.
Scenario-bracketing framed projections across conservative, baseline, and accelerated regulatory compliance pathways, with segmentation dimensions spanning sensing technology, platform application, and end-user procurement authority. CAGRs derived from installed base turnover rates, replacement cycle compression from redundant configuration mandates, and penetration curves for solid-state architectures. Industry-specific forecast inputs incorporated CS-25 certification alignment timelines and COMAC production ramp schedules.
Stress conditions across titanium supply disruption severity, FAA mandate implementation pacing, and airline fleet renewal acceleration were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory harmonization and indigenous aircraft program maturity. Material shifts in export restriction regimes or flight control automation standards would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Aerospace Engineering Services Outsourcing Market
Others
Global Molded Plastics Market
Others
Hybrid Switchgear Market
Others
Allogeneic T Cell Therapies Market
Others
Global Augmented Reality in Retail Market
Others
Insoluble Sulfur Market
Others
Aerospace Tester Market
Others
Binoculars and Mounting Solutions Market
Others
Internet of Things Testing Market
Others
Mainframe Computers Market
Others
Global Contactless Biometrics Technology Market
Others
Japan Automotive LED Lighting Market
Others
Paraffin Physical Therapy Market
Others
North America Forklift Truck Market
Others
North America Micro Market
Others
Europe Flow Battery Market