
 Augmented Reality (AR) in Warehousing and Logistics Market | 2026-2036
Augmented Reality (AR) in Warehousing and Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
Augmented Reality (AR) in Warehousing and Logistics Market Outlook
Third-party logistics providers is collapsing the historical dominance of in-house manufacturing IT departments as the primary buyer archetype for AR warehousing solutions. Microsoft leverages its HoloLens industrial ecosystem to anchor enterprise-grade mixed-reality deployments across North American distribution networks. PTC competes through its Vuforia platform, which sustains deep integration with existing CAD and IoT backends that manufacturers already operate. Ubimax specializes in wearable software stacks that control the pick-by-vision workflow layer, giving it narrow but defensible positioning in European grocery and pharmaceutical fulfillment.
Augmented Reality in Warehousing and Logistics overlays digital visual instructions, spatial anchors, and real-time data streams onto physical warehouse environments through head-mounted displays, smart glasses, or handheld devices, typically operating with sub-10-millisecond motion-to-photon latency to prevent operator nausea during eight-hour shifts. Its primary commercial purpose is to reduce cognitive load on warehouse associates while increasing pick accuracy and reducing training time for seasonal workforce surges. Markerless AR is leading technology adoption because it eliminates the infrastructure cost of physical fiducial placement across million-square-foot facilities, while cloud-based deployment is capturing the fastest growth as warehouse operators seek to federate software updates across geographically dispersed sites without on-site IT intervention. Picking optimization remains the most mature application segment with proven ROI documentation, though maintenance assistance is emerging as a margin-rich adjacency where technicians command premium hourly rates for AR-guided repairs of automated material handling equipment.
The EU AI Act classifies certain AR training algorithms as high-risk when they automate worker performance evaluation, forcing vendors to redesign data governance architectures for European deployments. OSHA in the United States and Germany's KBA both scrutinize optical safety and ergonomic load limits for head-worn devices, effectively setting baseline hardware standards that filter which OEMs qualify for enterprise tenders. Stakeholders must monitor whether emerging national AI regulations fragment certification requirements sufficiently to create region-locked hardware variants that inflate total cost of ownership for multinational operators.
Market Dynamics
Third-party logistics providers are displacing in-house manufacturing IT departments as the primary buyer archetype for AR warehousing solutions, while the EU AI Act and OSHA workplace safety directives force hardware vendors to redesign certification architectures.
Growth Catalysts
- E-commerce fulfillment surge:Peak-season volume volatility drives demand for AR-guided picking systems that compress seasonal workforce training from weeks to days.
- OSHA optical safety standards:Federal workplace safety mandates create procurement preference for certified head-mounted displays in US distribution networks.
- Markerless SLAM algorithms:Simultaneous localization and mapping eliminates fiducial infrastructure costs across million-square-foot facilities.
Market Restraints
- Microdisplay supply concentration:Sony and BOE dominate OLEDoS panel production, creating single-source vulnerability for high-resolution AR optics.
- EU AI Act high-risk classification:Worker performance evaluation algorithms trigger mandatory conformity assessments that extend deployment timelines by 12-18 months.
- Smartphone AR substitution:Handheld device-based picking solutions capture pilot budgets in cost-constrained warehouse operations.
Strategic Opportunities
- Maintenance assistance adjacency:AR-guided repair of automated material handling equipment commands premium technician hourly rates with margin structures 40% above picking applications.
- Cloud-based deployment federation:Software-as-a-service models enable centralized update distribution across geographically dispersed sites without on-site IT intervention.
- Germany KBA ergonomic certification:Federal Motor Transport Authority standards for head-worn device load limits create first-mover advantage for compliant OEMs in automotive logistics corridors.
Industry Challenges
- Sub-10-millisecond motion-to-photon latency engineering:Preventing operator nausea during eight-hour shifts requires specialized GPU-edge compute integration that exceeds standard warehouse IT specifications.
- CAD-IoT backend interoperability:Deep integration with existing manufacturer digital twins demands custom API development that extends implementation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Augmented Reality (AR) in Warehousing and Logistics Market |
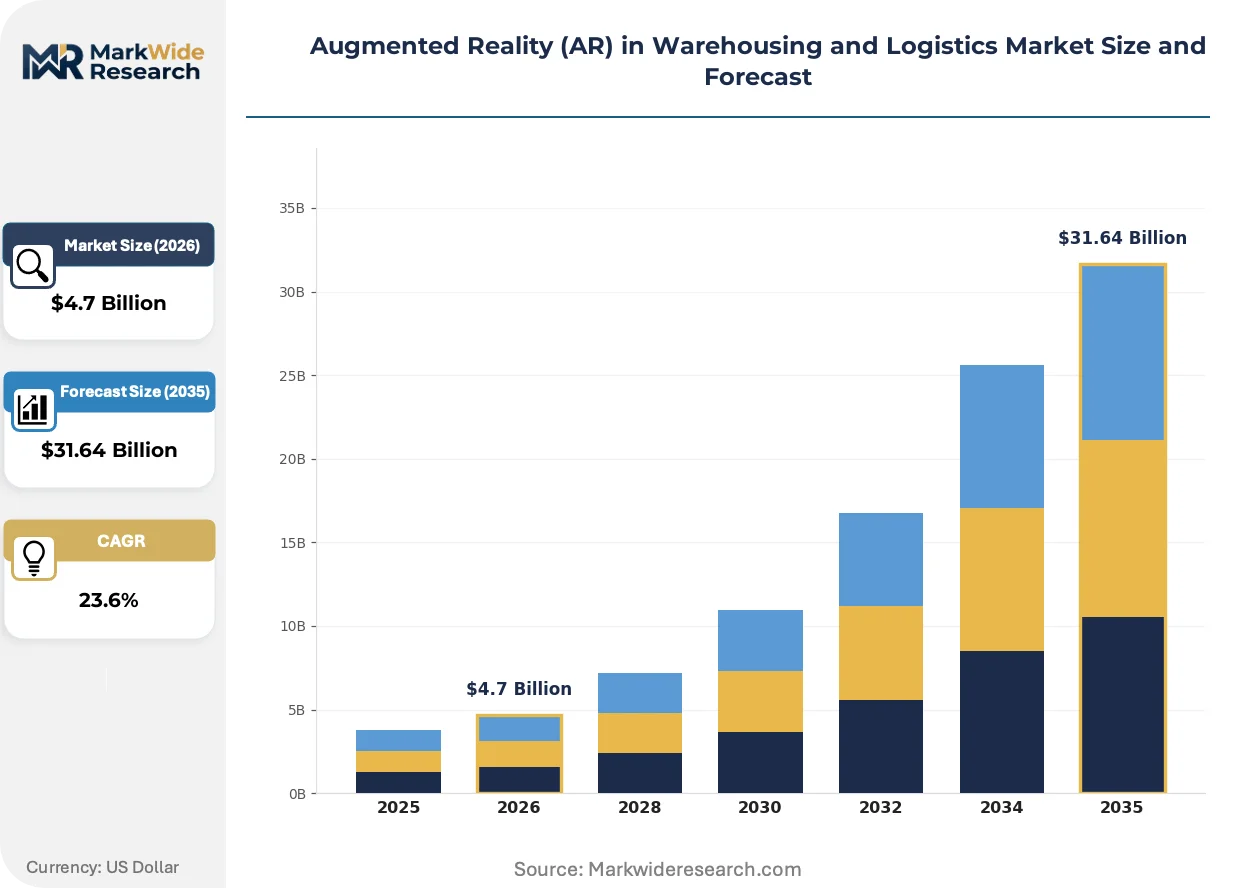
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $31.64 Billion |
| CAGR (2026 – 2036) | 23.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Marker-Based, Markerless, Projection-Based, Superimposition-Based Application: Picking Optimization, Inventory Management, Training Simulation, Maintenance Assistance End User: E-Commerce, Manufacturing, Third-Party Logistics, Retail Deployment: On-Premise, Cloud-Based, Hybrid, Standalone |
| Companies Covered | Microsoft, PTC, DHL Supply Chain, Walmart, TeamViewer, Ubimax, RealWear, GEODIS, Vuzix, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Augmented Reality (AR) in Warehousing and Logistics Market Strategic Shifts
Spatial computing architectures are compressing hardware refresh cycles while regulatory fragmentation forces vendors to maintain multiple certification tracks simultaneously.
Markerless AR is displacing marker-based systems in greenfield warehouse deployments. E-commerce fulfillment centers in Germany and the Netherlands adopt simultaneous localization and mapping for pick-by-vision workflows without physical fiducial installation. This shift compresses facility commissioning timelines from months to weeks while eliminating infrastructure maintenance overhead.
The EU AI Act's high-risk system classification is reshaping data governance architectures for European deployments. Algorithms automating worker performance evaluation now require documented risk management systems and human oversight protocols. AR training platform vendors are responding by bifurcating product roadmaps into EU-compliant and non-EU variants.
Buyer concentration among third-party logistics providers is consolidating procurement leverage around outcome-based performance contracts. DHL Supply Chain and Kuehne+Nagel negotiate picking accuracy guarantees rather than hardware lease terms. This shift concentrates vendor selection authority with procurement functions that prioritize operational metrics over technical specifications.
Augmented Reality (AR) in Warehousing and Logistics Market Segmentation
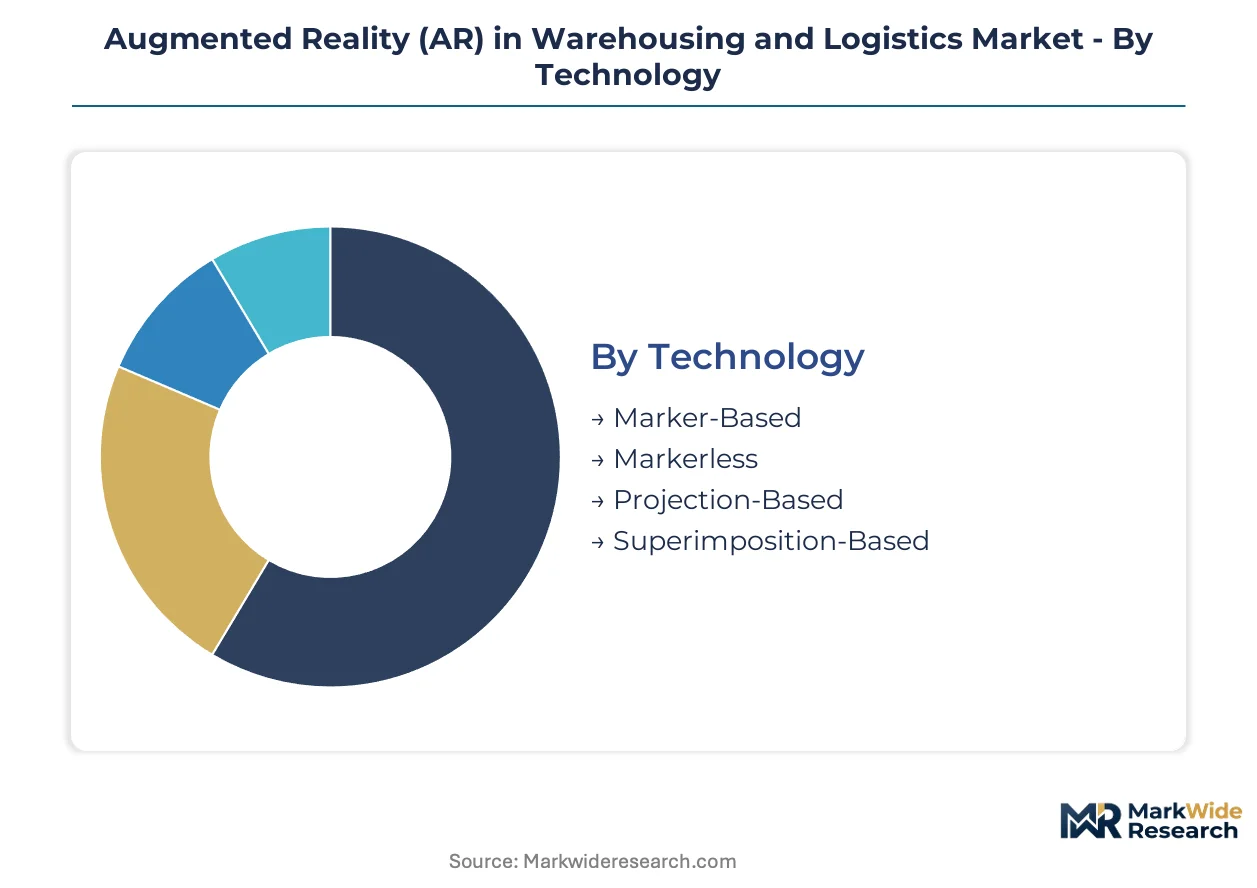
AR warehousing solutions fragment across four structural dimensions that determine procurement authority and implementation complexity. Technology choice dictates infrastructure spend. Application focus shapes ROI documentation requirements. Deployment model determines IT governance overhead across distributed facility networks.
Technology:
Markerless systems face the strongest substitution pressure from smartphone-based handheld AR, while marker-based installations confront infrastructure cost disadvantages in greenfield deployments.
- Markerless:Simultaneous localization and mapping algorithms eliminate physical fiducial placement across million-square-foot distribution centers. German automotive logistics corridors in Bavaria and Baden-Württemberg concentrate demand as BMW and Siemens anchor pilot-to-production transitions without retrofit infrastructure.
- Marker-Based:Optical fiducial tracking requires printed marker installation on rack faces and floor grids, delivering sub-centimeter accuracy in controlled lighting environments. Legacy facilities in the US Midwest retain installed bases where infrastructure amortization extends replacement cycles.
- Projection-Based:Laser pico-projectors overlay pick instructions directly onto physical surfaces without head-worn hardware.
- Superimposition-Based:Object recognition engines replace entire physical objects with digital twins for training scenarios.
Markerless systems anchor the volume base while projection-based configurations gain share at the steepest rate in cost-constrained operations.
Application:
Margin structures diverge sharply across use cases, with maintenance assistance commanding premium technician rates against commoditized picking workflows.
- Picking Optimization:Vision-guided pick-by-vision workflows reduce cognitive load on warehouse associates during eight-hour shifts. E-commerce fulfillment centers in the Netherlands adopt these systems to compress seasonal workforce training from weeks to days during peak volume surges.
- Maintenance Assistance:AR-guided repair of automated material handling equipment supports premium hourly billing rates. German KBA ergonomic certification requirements for head-worn devices filter qualified vendors for automotive logistics technician deployments.
- Inventory Management:Spatial anchors enable real-time cycle counting without paper-based location verification.
- Training Simulation:Digital twin environments reduce onboarding time for seasonal workforce surges.
Picking optimization generates the installed base volume while maintenance assistance expands most quickly on margin-driven technician outsourcing contracts.
End User:
Procurement authority is concentrating among outsourced logistics operators that displace in-house manufacturing IT departments as primary buyers.
- Third-Party Logistics:DHL Supply Chain and Kuehne+Nagel negotiate outcome-based performance contracts with picking accuracy guarantees rather than hardware lease terms. EU AI Act high-risk classification for worker evaluation algorithms forces these providers to maintain dual certification tracks for European and non-European deployments.
- E-Commerce:Peak-season volume volatility drives demand for rapid workforce scaling. OSHA optical safety standards create procurement preference for certified head-mounted displays in US distribution networks.
- Manufacturing:In-house IT departments retain control where CAD-IoT backend integration demands custom API development.
- Retail:Store-back fulfillment operations adopt lighter smartphone AR substitutes for cost-constrained pilot budgets.
Third-party logistics anchors current procurement volume while e-commerce operations climb the fastest on fulfillment center expansion timelines.
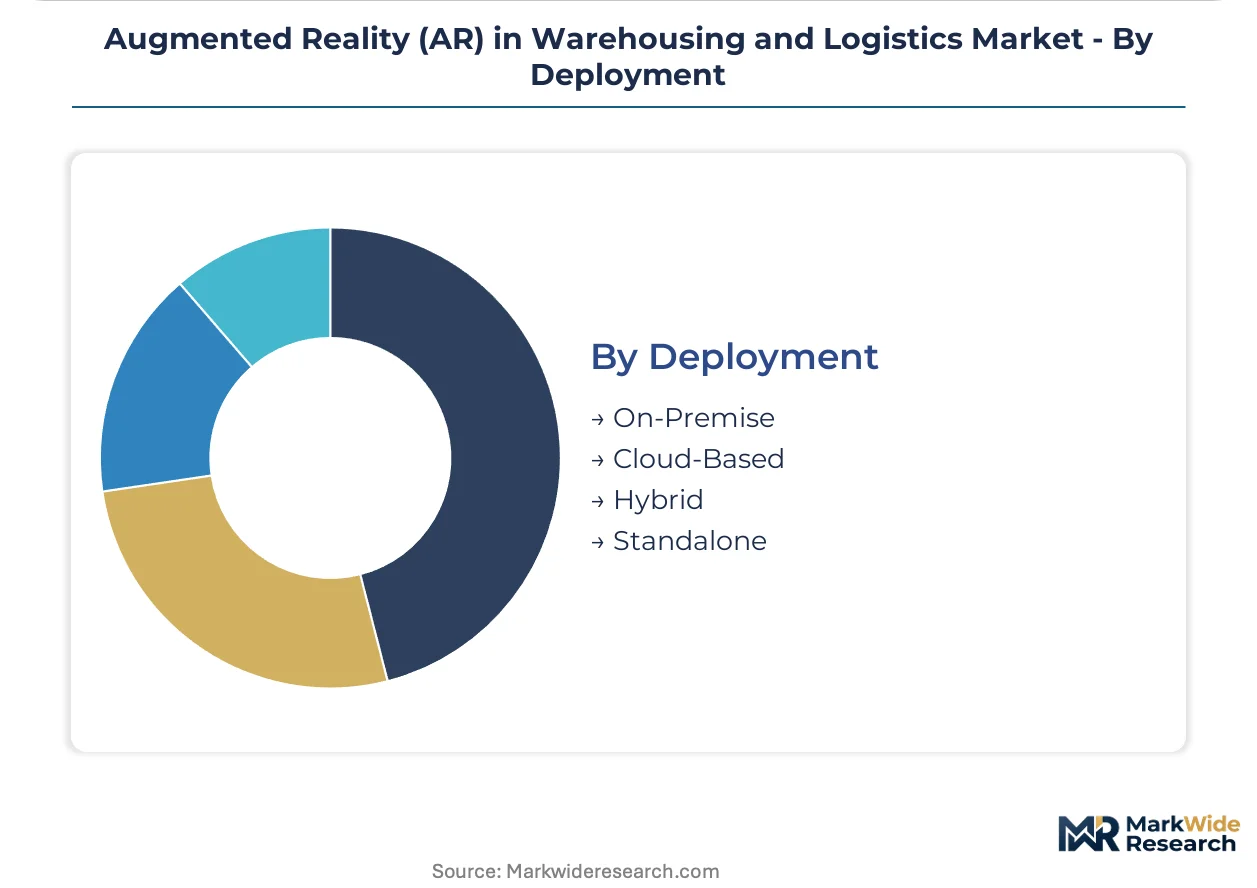
Deployment:
IT governance requirements determine model selection, with cloud federation enabling centralized software distribution across geographically dispersed sites.
- Cloud-Based:Software-as-a-service architectures distribute updates without on-site IT intervention. Multi-site operators in Germany's automotive logistics corridor federate deployments across Munich, Stuttgart, and Wolfsburg facility networks.
- Hybrid:Edge compute handles sub-10-millisecond motion-to-photon latency requirements while cloud layers manage fleet analytics. US distribution networks adopt this architecture where OSHA-mandated optical safety systems require local processing redundancy.
- On-Premise:Air-gapped installations serve defense and pharmaceutical logistics with data sovereignty requirements.
- Standalone:Single-device deployments support pilot programs without network infrastructure commitment.
Cloud-based deployment anchors new implementation volume while hybrid architectures gain share fastest among latency-sensitive multi-site operators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's automated container handling infrastructure anchors European AR logistics adoption, while Germany's Rhine-Ruhr rail corridor and the US Interstate highway distribution network shape continental deployment patterns.
United States
OSHA optical safety standards for head-worn devices create procurement preference for certified hardware in distribution networks spanning Dallas-Fort Worth and Chicago. The Federal Motor Carrier Safety Administration's hours-of-service regulations intersect with AR training platforms for driver workforce scaling. Amazon's fulfillment center cluster in the Inland Empire drives pilot-to-production transitions for vision-guided picking systems.
Germany
The KBA's ergonomic load limits for head-mounted displays filter qualified OEMs for automotive logistics corridors. BMW's Munich assembly plant and Siemens' Nuremberg distribution center anchor markerless SLAM deployments without retrofit infrastructure. The EU AI Act's high-risk classification for worker evaluation algorithms forces dual certification tracks for domestic and export deployments.
Netherlands
Maasvlakte port automation investments compress seasonal workforce training timelines through AR-guided onboarding. The Dutch Food and Consumer Product Safety Authority's pharmaceutical traceability requirements drive spatial anchor adoption for cold-chain verification. DHL Supply Chain's Venlo campus serves as a testbed for cloud-federated multi-site deployments.
China
Ningbo-Zhoushan port's smart terminal investments integrate AR maintenance assistance for automated stacking equipment. MIIT's industrial internet standards shape backend interoperability requirements for warehouse digital twins. Alibaba's Cainiao network in Hangzhou pilots projection-based picking systems for cost-constrained operations.
Japan
Tokyo Bay's automated container terminals drive demand for sub-10-millisecond latency systems preventing operator nausea during extended shifts. METI's Society 5.0 initiative funds spatial computing pilots for aging workforce augmentation. Toyota's Nagoya logistics hub deploys hybrid edge-cloud architectures for latency-sensitive multi-site coordination.
Augmented Reality (AR) in Warehousing and Logistics Market Competitive Environment
Concentration sits with enterprise software platforms that control the workflow layer rather than hardware OEMs. The vendor base separates into three strategic tiers: industrial mixed-reality ecosystems, wearable software specialists, and logistics operator captive IT units. Dominant competitive moves include cloud-based deployment federation and outcome-based performance contracting that transfers hardware risk to vendors.
Within the enterprise ecosystem tier, Microsoft and PTC occupy positions as anchor platform providers, while Ubimax exemplifies the narrow specialist archetype focused on European grocery and pharmaceutical fulfillment workflows. These three entities represent contrasting strategic postures: horizontal platform breadth, CAD-IoT backend integration depth, and vertical workflow control respectively.
| Leading Market Players |
|---|
| Microsoft |
| PTC |
| DHL Supply Chain |
| Walmart |
| TeamViewer |
| Ubimax |
| RealWear |
| GEODIS |
| Vuzix |
| Others |
Value Chain & Pricing Dynamics
OSHA optical safety certification and Germany's KBA ergonomic load standards simultaneously gate hardware qualification and stratify vendor pricing tiers, forcing OEMs to absorb compliance costs upfront while passing residual premiums to certified product lines. This dual-gate mechanism concentrates procurement leverage among third-party logistics providers that negotiate outcome-based contracts rather than hardware lease terms.
Pricing Analysis
Volume-discount tiering structures separate enterprise fleet deployments from pilot-program single-unit purchases, with cloud-based SaaS subscriptions commanding recurring revenue premiums against perpetual licensing. Pricing stratifies across certified head-mounted displays, hybrid edge-cloud architectures, and smartphone-based handheld substitutes, with certification-grade hardware capturing the widest margins. Cost compression in entry-level tiers intensifies as Chinese projection-based systems enter European grocery fulfillment pilots. Third-party logistics providers exhibit the lowest price sensitivity due to outcome-based contracting, while retail store-back operations drive substitution toward economy-tier handheld alternatives.
Supply Chain Analysis
Port congestion across Ningbo-Zhoushan and Rotterdam trade lanes elevates inbound logistics costs for OLEDoS microdisplay panels sourced from Sony and BOE manufacturing facilities. Hardware assembly concentrates in China, Taiwan, and Mexico, with optical component fabrication tethered to Japanese and South Korean precision equipment suppliers. Single-source vulnerability in high-resolution AR optics creates exposure to regional trade restrictions. Distribution runs through authorized industrial equipment channels rather than consumer electronics retail, with direct OEM relationships dominating enterprise procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The AR warehousing market is entering cyclical recovery as e-commerce fulfillment center buildouts resume post-capital-expenditure retrenchment, with peak-season volume volatility driving replacement demand for aging pilot installations.
For Market Incumbents: Shield installed base relationships through preemptive cloud-federation investments that lock multi-site operators into centralized update architectures. Accelerate KBA ergonomic certification for next-generation head-mounted displays before automotive logistics corridors finalize tender specifications. Vertical integration into edge-GPU compute modules defends margin position against commoditized hardware substitution. For New Entrants and Emerging Players: EU AI Act conformity assessment fast-tracks create defensible positioning in German pharmaceutical fulfillment where incumbent vendors maintain non-compliant legacy stacks. White-space concentration sits with maintenance assistance applications commanding premium technician billing rates. Target Netherlands cold-chain verification pilots through spatial anchor specialization. Go-to-market execution should emphasize outcome-based accuracy guarantees rather than technical specification sheets. For Investors and Strategic Acquirers: OSHA's anticipated optical safety standard expansion reshapes the acquisition landscape toward certified-hardware vendors with established US distribution networks. Long-term viability hinges on workflow-layer software control rather than device manufacturing scale. Acquisition target archetype: narrow specialists with European grocery or pharmaceutical fulfillment deployments and existing EU AI Act compliance infrastructure. Signal to watch: DHL Supply Chain or Kuehne+Nagel vendor consolidation announcements indicating procurement authority centralization.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Federated Deployment Architecture | Enables centralized software distribution across DHL and Kuehne+Nagel multi-site networks without on-site IT intervention. |
| KBA Ergonomic Certification Investment | Filters qualified OEMs for BMW and Siemens automotive logistics corridor tenders in Bavaria and Baden-Württemberg. |
| Markerless SLAM Algorithm Development | Eliminates fiducial infrastructure costs across million-square-foot Netherlands e-commerce fulfillment centers. |
| EU AI Act Compliance Roadmap | Forces bifurcated product variants for European deployments with documented risk management and human oversight protocols. |
| Maintenance Assistance Platform Extension | Captures premium technician hourly rates 40% above commoditized picking workflows in German automotive logistics. |
Study Parameters
A standing panel of warehouse operations directors, third-party logistics procurement leads, AR hardware platform engineers, and OSHA compliance officers provided ongoing calibration across primary interview cycles. Secondary validation drew from SEC filings of publicly traded logistics operators, EU AI Act implementation guidance documents, KBA ergonomic standard technical specifications, and customs data tracking microdisplay panel import flows. Bottom-up unit deployment estimates triangulated against top-down addressable facility square footage across the analysis window.
Consistency checks against external benchmarks validated volume and value outputs across technology segmentation by markerless versus marker-based systems, application focus spanning picking optimization through maintenance assistance, deployment models from cloud-based through hybrid edge-cloud architectures, and end-user concentration among third-party logistics providers versus in-house manufacturing IT departments. CAGRs were derived from logistic curve adoption modeling calibrated to e-commerce fulfillment center expansion timelines and seasonal workforce scaling patterns.
Decision-makers should treat outputs as directional under assumptions of sustained e-commerce volume growth and stable regulatory certification timelines; material deviation in peak-season volatility or EU AI Act enforcement intensity would warrant model refresh. Specific risk factors include OLEDoS supply disruption, smartphone AR substitution acceleration, and fragmentation of national AI regulations creating region-locked hardware variants. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Thermoformed Plastics Market
Others
Industrial Gauges Market
Others
Asia Pacific Foodservice Paper Packaging Market
Others
Smart Card Market
Others
Grna Market
Others
Global Extruded Plastics Market
Others
Global Animal Feed Protein Ingredients Market
Others
China Cloud Gaming Technology Market
Others
Augmented Reality in Energy and Utilities Market
Others
Digital Thermal Plates Market
Others
Global Magnetic Flow Meters Market
Others
Italy 3D Printing Construction Market
Others
Snus Market
Others
Vortexers Market
Others
Global Platform Trolley Market
Others
Smart Home Platforms Market