
 Refractometer Market | 2026-2036
Refractometer Market Size, Share, and Industry Trends Forecast 2026-2036
Refractometer Market Intelligence
Aftermarket service revenue is narrowing as manufacturers bundle calibration contracts with initial hardware sales. Anton Paar GmbH leverages its Graz headquarters to sustain premium positioning in laboratory-grade Abbe refractometers. Thermo Fisher Scientific Inc. anchors North American distribution through its Waltham service infrastructure. Atago Co., Ltd. dominates handheld digital units across Asia-Pacific food processing corridors.
A refractometer measures the refractive index of a substance to determine its composition, concentration, or purity, typically operating at wavelengths of 589 nm with temperature compensation to 0.1°C precision. Digital imaging technology now displaces optical eyepiece designs in high-throughput pharmaceutical laboratories where automated sample handling reduces operator variability. Benchtop systems capture the largest margin pool in chemical concentration measurement, while handheld units grow fastest among field-based aquaculture monitoring operations.
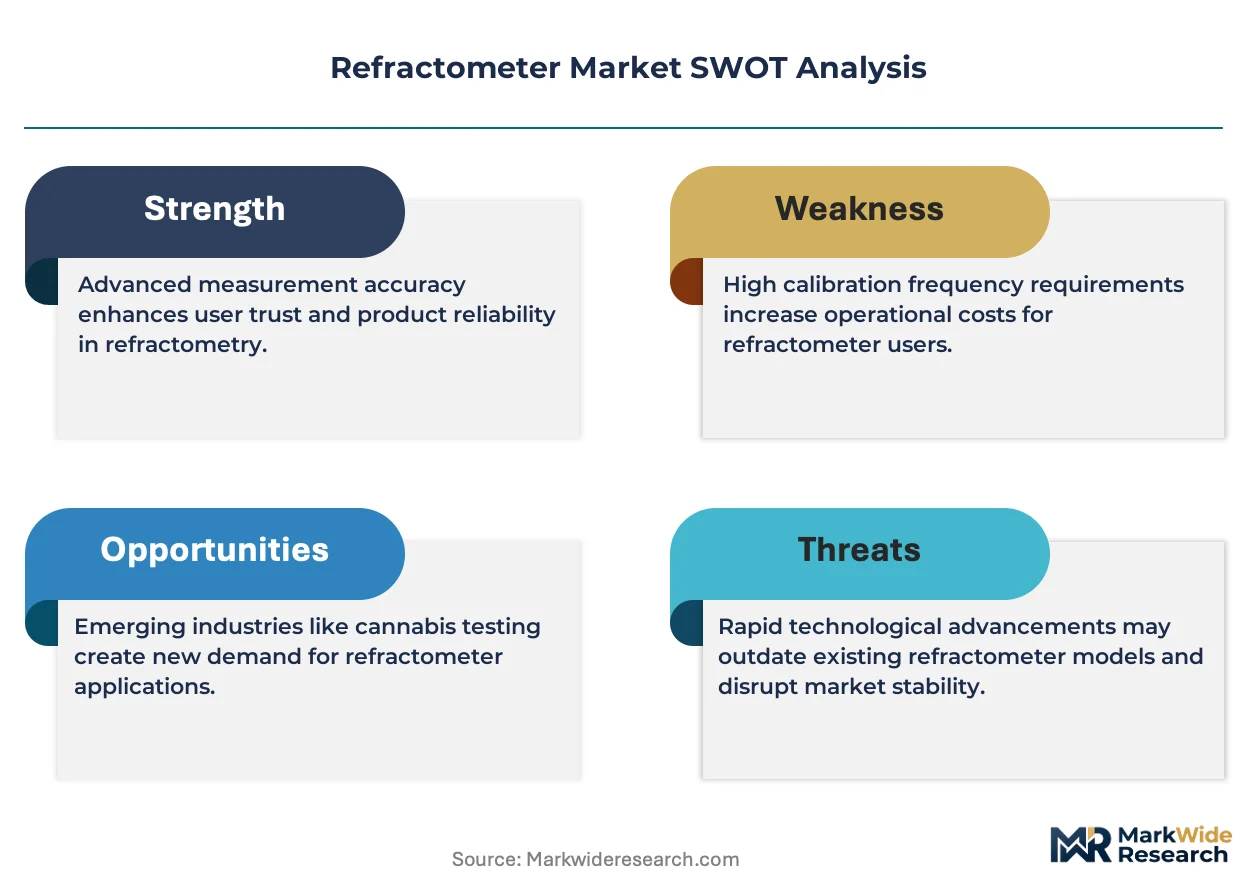
FDA process analytical technology guidelines and EU GMP Annex 15 validation requirements together reshape instrument procurement toward inline-capable digital refractometers with full audit trails. ISO 17025 accreditation pressures drive laboratories toward manufacturers offering certified reference materials and traceable calibration protocols. Stakeholders must weigh captive service network depth against third-party calibration flexibility when selecting long-term instrument partners.
Market Dynamics
Inline digital refractometry is displacing benchtop optical units as pharmaceutical manufacturers retool for FDA process analytical technology compliance, compressing validation cycles and rewiring procurement criteria toward audit-trail-ready systems.
Growth Catalysts
- FDA Process Analytical Technology:Real-time release testing mandates drive pharmaceutical manufacturers toward inline refractometers with automated data logging. This regulatory pressure accelerates replacement cycles for legacy optical units.
- Food Safety Modernization Act:US food processors deploy digital Brix measurement systems to satisfy preventive control requirements for juice concentration and syrup formulation verification.
- EU GMP Annex 15:European pharmaceutical validation standards compel laboratories to adopt digital refractometers with certified reference materials and traceable calibration protocols.
Market Restraints
- Optical-grade sapphire prism costs:Raw material volatility in synthetic corundum supply constrains margin expansion for precision instrument manufacturers.
- German manufacturing concentration:Stuttgart and Greifensee precision clusters create geographic supply risk for specialized optical components and temperature-compensated sensor modules.
- Benchtop unit substitution:Lower-cost handheld digital units from Asia-Pacific suppliers erode pricing power in food processing quality control applications.
Strategic Opportunities
- Cell and gene therapy manufacturing:Bioprocess monitoring for viral vector concentration creates demand for single-use inline refractometry in US and European contract development facilities.
- Carbonated beverage reformulation:Sugar-reduction trends drive investment in precision Brix measurement for stevia and allulose blend verification in North American bottling plants.
- ISO 17025 laboratory accreditation:Certification mandates in emerging analytical service markets create pull for bundled calibration-contract hardware sales.
Industry Challenges
- Metrology technician scarcity:Specialized skills for refractive index standard preparation and interferometric calibration are concentrating in aging workforce pools across European instrument service networks.
- Legacy LIMS integration:Digital refractometer data formats often require middleware development for connection to established laboratory information management systems in pharmaceutical quality control departments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Refractometer Market |
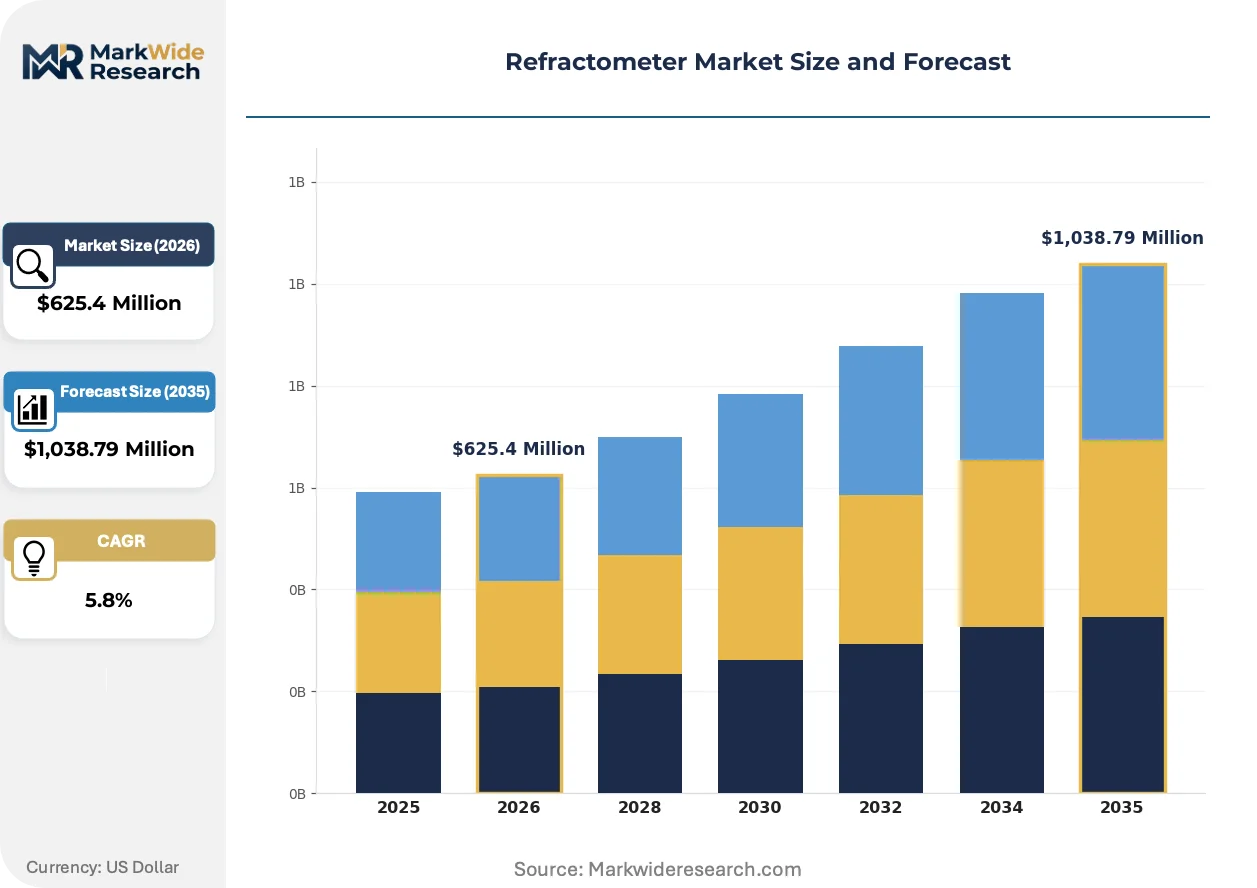
| Market Size in 2026 | $625.4 Million |
| Market Size in 2035 | $1,038.79 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Digital, Analog, Handheld, Benchtop, Portable Application: Food & Beverage Quality Control, Chemical Concentration Measurement, Gemstone Identification, Aquaculture Monitoring, Pharmaceutical Analysis End User Industry: Laboratories, Quality Assurance Facilities, Research Institutes, Water Treatment Plants, Educational Institutions Technology: Critical Angle, Abbe, Pulfrich, Optical, Digital Imaging |
| Companies Covered | Thermo Fisher Scientific Inc., Anton Paar GmbH, Mettler-Toledo International Inc., AMETEK, Inc., Shimadzu Corporation, Vaisala, Atago Co., Ltd., Reichert, Inc., Hanna Instruments, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Refractometer Market Strategic Shifts & Innovations
Refractometer technology is converging with spectroscopic methods and wireless data transmission, enabling distributed quality control architectures that bypass centralized laboratory workflows.
Multi-wavelength digital refractometry is digitizing concentration measurement across pharmaceutical manufacturing lines. Thermo Fisher Scientific and Anton Paar anchor this transition in North American and European facilities. The technology is digitizing batch release decisions by embedding refractive index sensors directly into bioreactor outlet streams.
EU MDR and FDA 21 CFR Part 11 harmonization pressures are forcing instrument firmware upgrades for electronic signature compatibility. Medical device manufacturers now demand embedded audit trails in inline refractometers used for dialysate and infusion solution concentration verification. German and Swiss pharmaceutical clusters are responding fastest, with validation protocols compressing from 18-month to 9-month cycles.
Service contract bundling is restructuring buyer-supplier relationships in laboratory instrumentation. Pharmaceutical procurement departments now favor five-year total-cost-of-ownership agreements over capital purchase models. This shift is most visible in US East Coast biotech corridors, where contract research organizations negotiate captive calibration networks with single-source instrument vendors.
Refractometer Market Segmentation
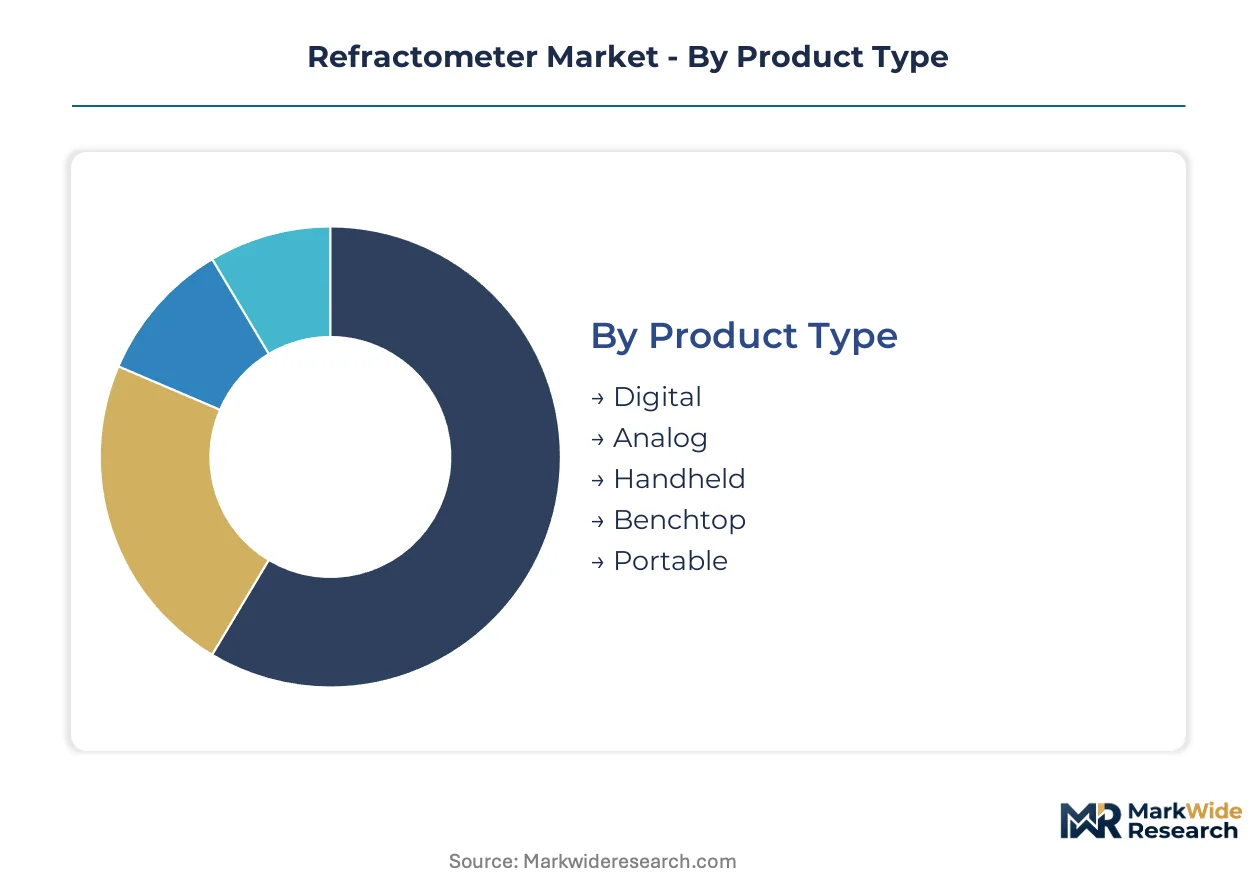
Refractometer procurement patterns diverge sharply across product architectures, with service contract bundling intensity varying from five-year pharmaceutical agreements to ad-hoc food processing calibrations. Segment boundaries are blurring as digital imaging modules penetrate handheld units and inline systems displace benchtop workflows in regulated manufacturing environments.
Product Type:
After-sales service intensity peaks with benchtop laboratory systems requiring annual interferometric calibration and certified reference material traceability, while handheld units operate on break-fix models with minimal preventive maintenance.
- Digital:Solid-state photodiode arrays and embedded microprocessors enable automated temperature compensation to 0.1°C precision. Pharmaceutical manufacturers in Germany and Switzerland specify these for FDA process analytical technology compliance, with firmware requiring biannual validation updates to maintain 21 CFR Part 11 audit trails.
- Analog:Optical eyepiece designs with manual prism compensation persist in educational institutions and developing economy laboratories where capital constraints outweigh throughput requirements. Maintenance concentrates on mechanical wear of the Amici prism assembly and ocular lens degradation.
- Handheld:Compact units with LED illumination and simplified sample interfaces dominate Asia-Pacific food processing corridors for rapid Brix screening.
- Benchtop:High-precision Abbe configurations with circulating thermostats command premium positioning in ISO 17025-accredited analytical service laboratories.
- Portable:Battery-operated field units with ruggedized casings serve aquaculture monitoring operations requiring dissolved solids measurement at remote pond sites.
Benchtop systems hold the largest share; momentum sits with handheld digital units penetrating quality control workflows.
Application:
Margin structure varies dramatically across use cases, with pharmaceutical real-time release testing commanding calibration-inclusive pricing fivefold above food processing spot checks.
- Food & Beverage Quality Control:Brix measurement for juice concentration and syrup formulation verification operates under US Food Safety Modernization Act preventive control mandates. North American bottling plants are retrofitting inline sensors for stevia and allulose blend verification as sugar-reduction trends accelerate.
- Chemical Concentration Measurement:Process refractometry for acid, alkali, and solvent strength monitoring requires explosion-proof housing and Hastelloy wetted parts in petrochemical corridors.
- Gemstone Identification:Refractive index determination distinguishes synthetic from natural corundum and beryl specimens in Bangkok and Mumbai trading hubs.
- Aquaculture Monitoring:Salinity and dissolved solids tracking supports shrimp and salmon farm operations across Vietnamese coastal provinces.
- Pharmaceutical Analysis:Viral vector concentration monitoring in cell and gene therapy manufacturing demands single-use flow cells and gamma-stable sensor materials.
Food and beverage quality control dominates volume; pharmaceutical analysis climbs the fastest as bioprocess monitoring expands.
End User Industry:
Procurement sophistication separates captive calibration networks in multinational pharmaceutical quality assurance from transactional purchasing in municipal water treatment.
- Laboratories:Analytical service providers and R&D facilities require multi-wavelength capability and LIMS integration middleware.
- Quality Assurance Facilities:Manufacturing-embedded metrology departments prioritize inline digital refractometry with automated data logging for batch release documentation.
- Research Institutes:Academic and government laboratories balance precision requirements against grant-funded capital constraints.
- Water Treatment Plants:Municipal and industrial facilities monitor coagulant concentration and dissolved organic load with simplified maintenance protocols.
- Educational Institutions:University chemistry departments train students on fundamental optical principles using entry-level Abbe instruments.
Quality assurance facilities command the largest equipment budgets; research institutes represent the steepest expansion trajectory as analytical service outsourcing proliferates.
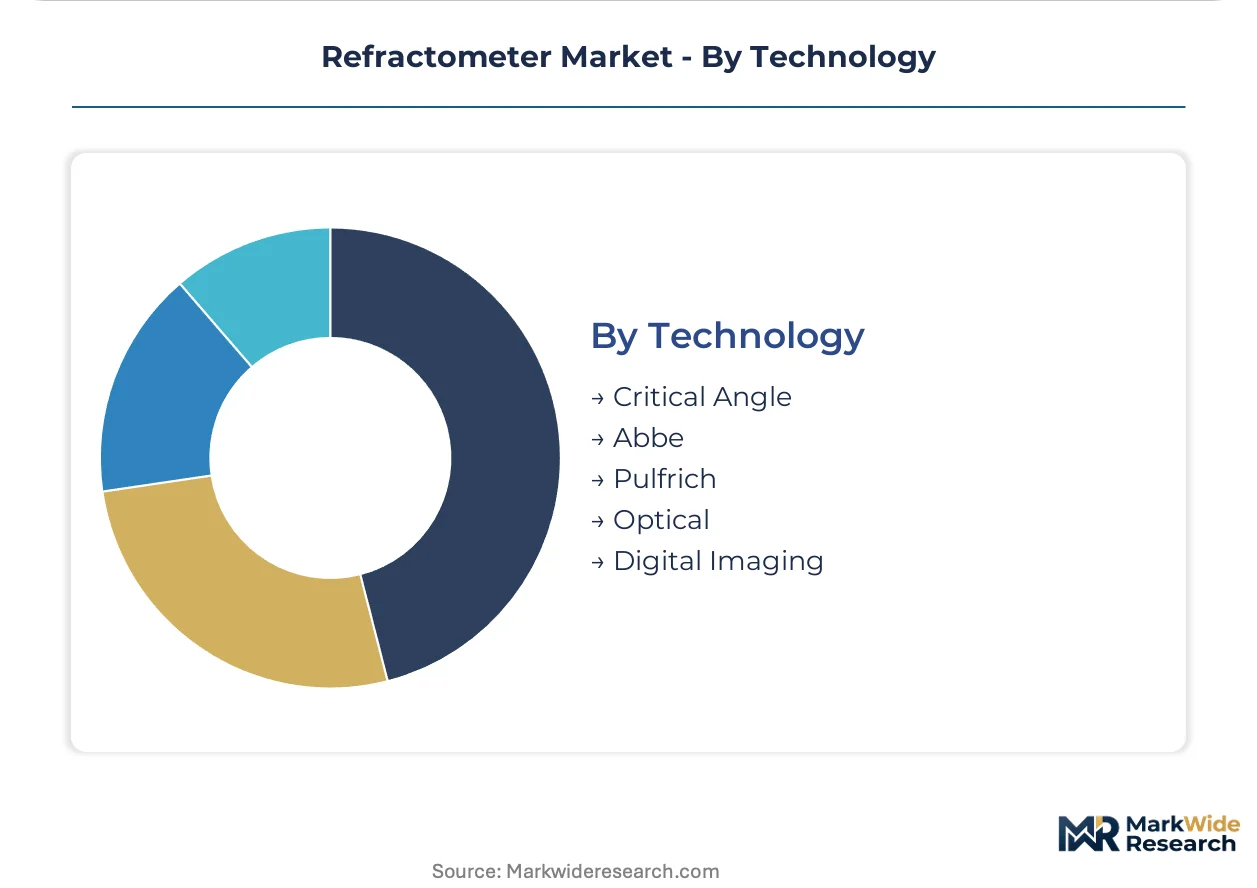
Technology:
Intellectual property concentration in critical angle and digital imaging architectures is reshaping competitive positioning among German and Japanese instrument manufacturers.
- Critical Angle:Prism-based detection of total internal reflection boundary delivers high-precision refractive index determination for pharmaceutical concentration verification. Stuttgart-area manufacturers anchor production of synthetic sapphire prism substrates for these systems.
- Digital Imaging:CCD and CMOS sensor arrays capture refractive index gradients without operator interpretation, eliminating variability in high-throughput pharmaceutical laboratories. Thermo Fisher Scientific and Anton Paar anchor this transition in North American and European facilities.
- Abbe:Classical optical geometry with compensating prisms for dispersion correction persists in reference standard applications.
- Pulfrich:Specialized geometry for refractive index measurement of solids and films serves optical materials research.
- Optical:Traditional visual observation methods retain niche positioning in gemstone identification and educational demonstrations.
Critical angle technology retains the dominant installed base; digital imaging gains share fastest as automated sample handling reduces operator variability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German pharmaceutical manufacturers deploy inline refractometers for real-time release testing, while Asia-Pacific food processors favor handheld digital units for rapid Brix screening. This consumption-mix differential separates precision-driven European laboratory markets from volume-oriented Asian quality control corridors.
United States
FDA process analytical technology mandates accelerate pharmaceutical manufacturer upgrades to digital refractometers with automated data logging. The Food Safety Modernization Act compels juice bottlers across Florida and California to install inline Brix verification systems. Boston-area biotech clusters negotiate five-year total-cost-of-ownership agreements bundling hardware with captive calibration networks.
Germany
EU GMP Annex 15 validation standards drive Stuttgart and Greifensee precision instrument manufacturing clusters toward certified reference material traceability. The country's national pharmaceutical regulator enforces stringent audit trail requirements for batch release documentation. Baden-Württemberg hosts concentrated production of synthetic sapphire prism substrates for critical angle refractometry systems.
Japan
PMDA guidelines harmonize with FDA 21 CFR Part 11 standards, forcing firmware upgrades for electronic signature compatibility in pharmaceutical quality control. METI industrial policy supports digital imaging technology development for high-throughput laboratories. Osaka-based analytical service providers expand ISO 17025-accredited calibration capabilities for regional food and beverage manufacturers.
China
NMPA medical device regulations tighten documentation requirements for infusion solution concentration verification equipment. The country's dual carbon goals push chemical manufacturers toward process refractometry for solvent recovery monitoring. Yangtze River Delta pharmaceutical corridors retrofit bioreactor outlet streams with multi-wavelength digital sensors.
India
CDSCO pharmaceutical manufacturing standards elevate demand for traceable calibration protocols in contract development facilities. FSSAI food safety mandates expand Brix measurement deployment across Maharashtra and Gujarat juice processing plants. Bangalore analytical service markets drive ISO 17025 accreditation pressures for bundled hardware-calibration procurement models.
Refractometer Market Key Industry Players
Capability concentration sits with precision instrument specialists; scale advantage sits with diversified laboratory technology conglomerates. The vendor base organizes around three tiers: German and Swiss precision manufacturers, Japanese digital imaging specialists, and diversified North American life science platforms. Strategic moves center on service contract bundling to capture recurring revenue and validation protocol compression to accelerate replacement cycles.
Within the precision manufacturing tier, Anton Paar GmbH and Mettler-Toledo International Inc. exemplify geographic anchoring in Central European instrument clusters. Among diversified life science platforms, Thermo Fisher Scientific Inc. represents the scale-driven model with extensive North American distribution infrastructure. Atago Co., Ltd. occupies a distinct position as a handheld digital specialist serving Asia-Pacific food processing corridors.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| Anton Paar GmbH |
| Mettler-Toledo International Inc. |
| AMETEK, Inc. |
| Shimadzu Corporation |
| Vaisala |
| Atago Co., Ltd. |
| Reichert, Inc. |
| Hanna Instruments, Inc. |
| Others |
Cost & Logistics Intelligence
Single-source dependency on synthetic sapphire prism substrates from Baden-Württemberg production clusters compresses pricing tier spreads while amplifying geographic supply risk for precision instrument manufacturers. This concentration simultaneously elevates premium-tier calibration-inclusive contracts and erodes margin flexibility across standard-tier benchtop systems.
Pricing Analysis
Long-term offtake agreements bundling five-year calibration contracts dominate pharmaceutical procurement, separating premium-tier vendors with captive service networks from standard-tier suppliers competing on hardware-only transactions. Price differentiation rests on ISO 17025 certification grade and after-sales service depth, with FDA 21 CFR Part 11 compliance tiers commanding substantial premia. Cost compression in handheld digital units is intensifying because Asia-Pacific suppliers are flooding food processing corridors with break-fix service models. Municipal water treatment facilities exhibit highest price sensitivity; biotech contract research organizations show least sensitivity due to validation protocol rigidity.
Supply Chain Analysis
Export-control regimes on precision optical manufacturing equipment limit technology flows into emerging analytical service markets, constraining local production capacity development. Geographic supply concentration centers on Germany, Japan, and Switzerland for critical angle prism substrates and temperature-compensated sensor modules. Raw material dependencies draw from synthetic corundum suppliers, specialized glass foundries, and CMOS sensor fabricators. Single-source vulnerability in Stuttgart-area sapphire substrate production creates systemic exposure. Distribution runs through manufacturer-direct channels for pharmaceutical accounts and regional distributor networks for food processing and aquaculture segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among consolidated pharmaceutical procurement departments negotiating enterprise-wide instrument agreements, fragmenting vendor pricing autonomy and compressing margin pools for undifferentiated hardware suppliers.
For Market Incumbents: Build captive calibration network moats through five-year total-cost-of-ownership contracts that embed firmware validation updates and certified reference material traceability. Deepen backward integration into synthetic sapphire prism production to insulate margin structure from raw material volatility. Secure channel control by acquiring regional service providers in US East Coast biotech corridors where contract research organizations are consolidating vendor panels. For New Entrants and Emerging Players: Pursue white-space penetration in Indian and Southeast Asian ISO 17025 accreditation-driven analytical service markets where bundled hardware-calibration procurement models are displacing transactional purchasing. Target Vietnamese aquaculture monitoring operations with ruggedized portable units featuring simplified maintenance protocols. Attack through direct digital sales channels bypassing established distributor markups in price-sensitive municipal water treatment segments. For Investors and Strategic Acquirers: FDA process analytical technology harmonization with EU GMP Annex 15 reshapes the acquisition landscape toward inline-capable digital refractometer specialists with embedded audit trail firmware. Five-to-ten year viability favors precision instrument manufacturers with validation protocol compression capabilities and pharmaceutical captive service network density. Monitor CDSCO and NMPA regulatory alignment timelines as inflection indicators for emerging market expansion trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| Service Contract Bundling | Five-year calibration-inclusive agreements capture recurring revenue from pharmaceutical quality assurance departments. |
| Backward Integration into Sapphire Substrates | In-house synthetic corundum production insulates margin structure from Baden-Württemberg supply concentration risk. |
| Firmware Validation Compression | Nine-month validation cycles accelerate replacement demand from FDA process analytical technology compliance mandates. |
| ISO 17025 Accreditation Partnership | Certified reference material programs penetrate emerging analytical service markets in India and Southeast Asia. |
| Single-Use Flow Cell Development | Gamma-stable sensor materials capture viral vector concentration monitoring in cell and gene therapy manufacturing. |
Research Approach
The analysis maps digital imaging, critical angle, Abbe, and Pulfrich technology architectures, each validated through instrument procurement managers, metrology technicians, pharmaceutical quality assurance directors, and aftermarket service heads. Primary interviews with laboratory accreditation bodies and regulatory affairs specialists combined with secondary validation from FDA guidance documents, EU GMP Annex 15 texts, ISO 17025 accreditation records, and SEC filings from listed instrument manufacturers. Bottom-up unit demand modeling triangulates against top-down market sizing across product type, application, end user industry, and technology segmentation dimensions.
Assumptions held fixed include regulatory compliance timelines and synthetic sapphire substrate pricing; variables tested include pharmaceutical capital expenditure cycles and food processor automation adoption rates. The projection framework segments by digital versus analog product architecture, food and beverage versus pharmaceutical application, and laboratory versus quality assurance facility end user, with CAGRs derived from replacement cycle compression analysis and inline system penetration curves. Forecast inputs incorporate FDA process analytical technology implementation velocity and EU MDR harmonization pressures on electronic signature requirements.
Macroeconomic conditions sit as an overlay; deviation in pharmaceutical R&D funding levels or chemical manufacturing capital expenditure trajectories would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and supply chain geographic concentration persistence. Material shifts in export control regimes for precision optical manufacturing equipment or abrupt synthetic corundum supply disruptions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Security Envelopes Market
Others
Solar Animal Repeller Market
Others
Europe Digital Experience Platform Market
Others
Air Separation Unit Market
Others
Gesture Recognition for Smart TV Market
Others
Digital Thermal Plates Market
Others
Asia-Pacific Medical Simulation Market
Others
Content Experience Platforms Market
Others
Hip Tendinitis Market
Others
Video Conferencing Hardware Market
Others
Dry Washer Market
Others
Tunnel Lighting Market
Others
Magnetic Stripe Readers Market
Others
Brazil Cane Sugar Market
Others
Mexico 3D Printing Construction Market
Others
Global Mobile Video Optimization Market