
 Smart Doorbell Market | 2026-2036
Smart Doorbell Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Doorbell Market Intelligence
A reliance on off-the-shelf sensor and processor components is pivoting towards in-house semiconductor design to improve on-device AI performance. Ring (Amazon) leverages its parent company’s vast cloud infrastructure to offer integrated services. Google Nest differentiates through its advanced machine learning capabilities for familiar face detection. Arlo competes on premium hardware specifications and a comprehensive subscription security model.
A smart doorbell is an internet-connected device, typically featuring a high-definition camera with a wide-angle lens, that replaces a conventional push-button unit. Its primary function is to provide homeowners with remote audio-visual communication with visitors through a mobile application. Within the technology segment, facial recognition is a key feature for premium models, while cloud storage services create recurring revenue streams. The residential housing application dominates volume, but adoption in commercial buildings for access control is an expanding frontier.
Product compliance is shaped by multiple regulatory frameworks. In the United States, devices must secure FCC certification for wireless communication, while in Europe, the GDPR strictly governs the processing of personal data captured by video. Navigating the divergent requirements for data privacy and local storage mandates versus cloud-based models will define future platform strategies for manufacturers.
Market Dynamics
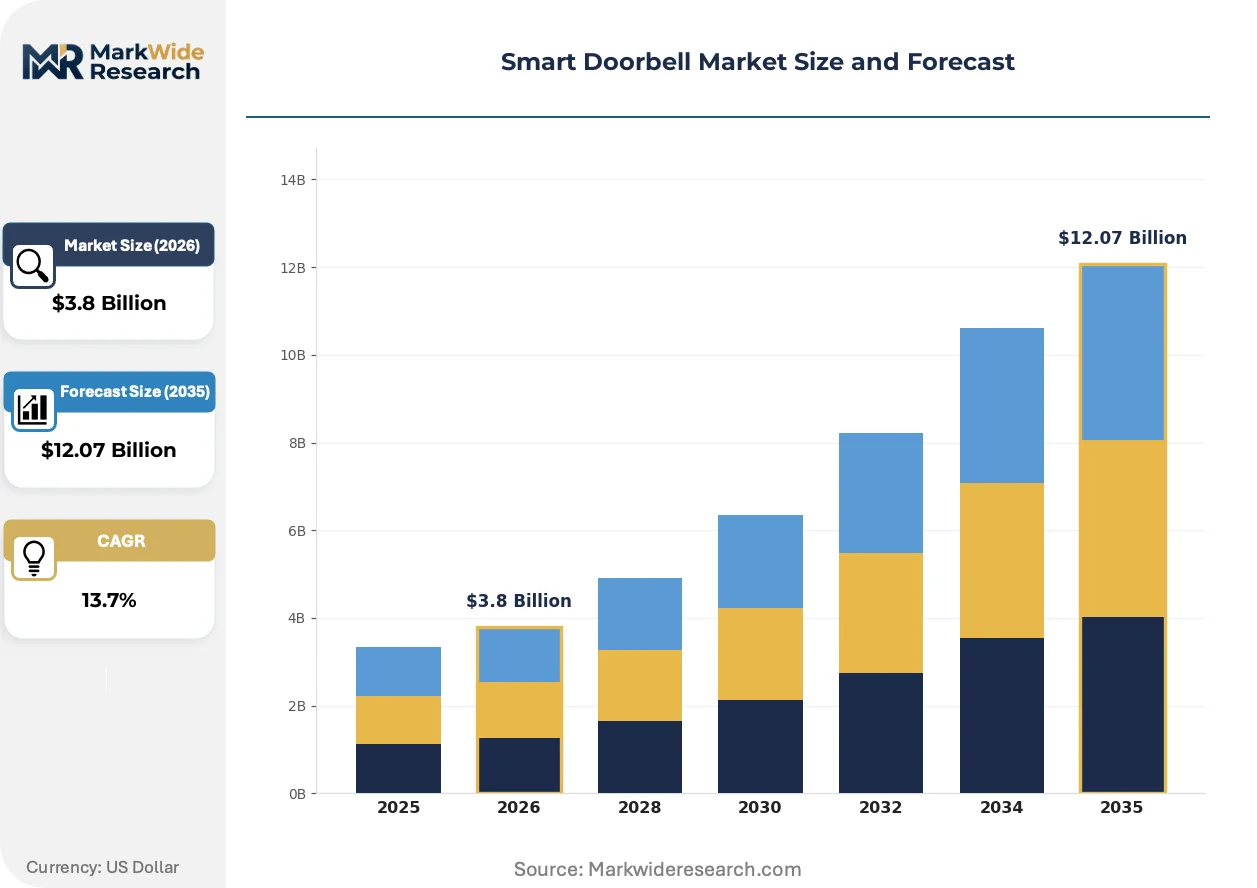
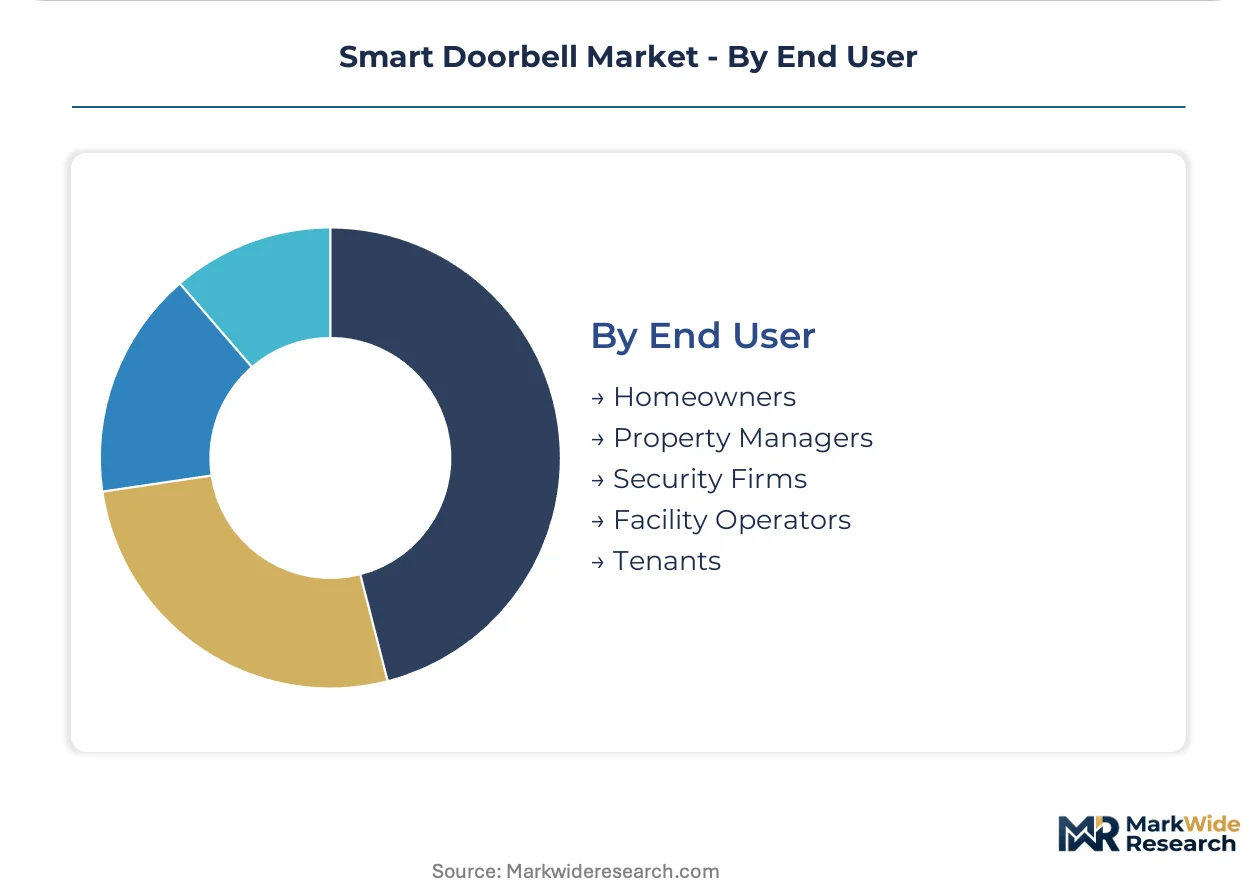
The market's central dynamic is the tension between the demand for sophisticated on-device AI capabilities, like facial recognition, and the reliance on cloud infrastructure for data storage and processing, which creates recurring revenue but also privacy concerns.
Growth Catalysts
- AI-Powered Features:The integration of advanced facial recognition and package detection algorithms enhances user value and security, driving upgrades from basic models and stimulating demand in the premium residential segment.
- New Housing Construction:Expansion of new housing estates, particularly in the United Kingdom and suburban United States, creates a significant built-in market for smart doorbell installations as a standard or optional feature.
- Suburban Security Focus:Heightened consumer awareness regarding property security and the prevention of package theft in suburban communities provides a strong, ongoing demand driver for remote monitoring capabilities offered by these devices.
Market Restraints
- Subscription Model Resistance:Consumer reluctance to commit to recurring monthly fees for cloud storage and advanced features limits the total addressable market for premium services, capping lifetime customer value for manufacturers.
- Data Privacy Regulation:Stringent data protection laws, such as the GDPR in Europe, impose significant compliance costs and design constraints on how manufacturers handle video data, potentially limiting feature rollouts across regions.
- Connectivity Dependence:Device functionality entirely depends on stable home Wi-Fi networks and internet access, making performance unreliable in areas with poor connectivity and creating a critical point of failure.
Strategic Opportunities
- Commercial Building Access:Adapting smart doorbell technology for access control in small businesses, multi-tenant offices, and apartment buildings represents an underpenetrated commercial application beyond the core residential market.
- Ecosystem Integration:Deeper integration with whole-home security ecosystems, including smart locks and alarm systems, offers a pathway for manufacturers to capture greater share-of-wallet through bundled service offerings.
- Expansion in Southeast Asia:Rapid urbanization and a growing middle class with increasing disposable income in countries like Malaysia and Singapore present new growth frontiers for residential smart security adoption.
Industry Challenges
- Platform Interoperability:Ensuring seamless performance across a fragmented landscape of mobile operating systems, Wi-Fi router hardware, and varying internet service provider configurations presents a persistent technical support challenge.
- Data Security and Hacking Threats:Maintaining robust cybersecurity to protect devices from being compromised and safeguarding user data from breaches requires continuous, significant investment in software development and security audits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Doorbell Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.07 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Video Doorbells, Audio Doorbells, Wi-Fi Enabled Doorbells, Battery-Powered Doorbells, Wired Doorbells Technology: Motion Detection, Facial Recognition, Two-Way Audio, Night Vision, Cloud Storage Application: Residential Housing, Commercial Buildings, Gated Communities, Educational Institutions, Government Facilities End User: Homeowners, Property Managers, Security Firms, Facility Operators, Tenants |
| Companies Covered | Eufy (Anker), Botslab, Ring (Amazon), ADT, SimpliSafe, Google Nest, EZVIZ, Wyze, Arlo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Doorbell Market Strategic Shifts & Innovations
The market's competitive positioning is reshaping around the intelligence of the underlying software platform and its integration with cloud services. This transition prioritizes recurring revenue from subscriptions over one-time hardware sales, transforming business models for all participants.
On-device AI processing via custom semiconductors enables faster, more private analysis of video feeds directly on the doorbell. Premium segment buyers are adopting these advanced models for their improved responsiveness and reduced reliance on internet bandwidth. This shift is absorbing functions previously handled exclusively in the cloud, such as familiar face alerts, thereby improving user privacy and device performance.
Regulatory divergence between the United States' FCC rules for wireless communication and Europe's GDPR for data privacy is forcing manufacturers to adopt dual-track product development. This bifurcation increases operational complexity and research and development costs for firms aiming for a global footprint. The premium product tier is most affected, often requiring different software configurations for deployment in the European Union versus North America.
Consumer purchasing behavior is evolving from acquiring a single product to subscribing to a comprehensive security service. The traditional one-time hardware sale model is being challenged by bundled offerings that include professional monitoring, extended cloud storage, and multiple connected devices. This trend is most prominent in the United States, where competition now centers on the value and breadth of subscription plans.
Smart Doorbell Market Segmentation
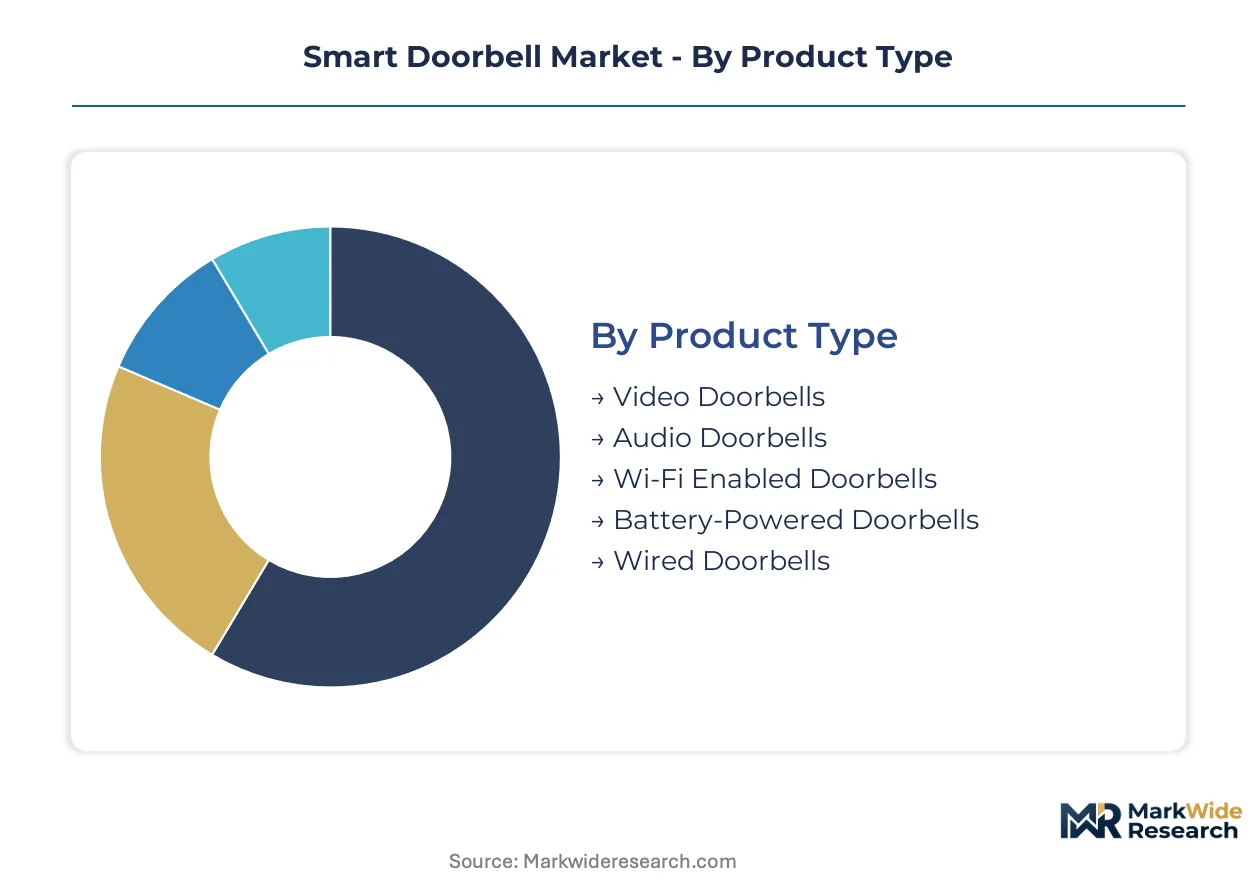
Market segmentation provides a granular understanding of the Smart Doorbell Market, revealing distinct product preferences, technological drivers, application areas, and end-user demands. This detailed breakdown helps manufacturers tailor product development and market strategies to specific consumer needs and operational environments.
Product Type:
Smart doorbell product types dictate the upgrade cycle for consumers seeking enhanced security and convenience features.
- Video Doorbells:These devices integrate a high-definition camera and microphone, allowing visual and audio communication with visitors. Demand concentrates in suburban United States households, driven by heightened property security awareness.
- Wi-Fi Enabled Doorbells:These units connect directly to a home's wireless network, enabling remote access and mobile application control. New housing construction in the United Kingdom integrates these doorbells as standard, leveraging existing network infrastructure.
- Battery-Powered Doorbells:These offer installation flexibility without requiring existing doorbell wiring, appealing to retrofit markets.
- Wired Doorbells:These utilize existing electrical connections for continuous power, ensuring reliable operation without battery concerns.
- Audio Doorbells:These basic smart doorbells provide two-way audio communication without video, often serving budget-conscious consumers.
Video Doorbells sit at the top of the volume ranking, with Wi-Fi Enabled Doorbells climbing the fastest.
Technology:
The underlying technology determines the functional capabilities and often the premium pricing tier for smart doorbell offerings.
- Facial Recognition:This advanced feature uses AI algorithms to identify familiar individuals, providing personalized alerts and access control. Premium residential segments globally seek this technology for enhanced security and seamless user experience.
- Cloud Storage:This service stores recorded video footage remotely, allowing users to review events and access historical data from anywhere. Homeowners in the United States subscribe to cloud storage for extended video retention and incident review.
- Motion Detection:This fundamental technology triggers recording and alerts upon detecting movement near the doorbell unit.
- Night Vision:Infrared sensors enable clear video capture in low-light conditions, providing 24/7 monitoring capabilities.
- Two-Way Audio:This allows real-time voice communication between the homeowner and visitors through the doorbell's integrated speaker and microphone.
Facial Recognition technology exhibits the steepest expansion trajectory, while Cloud Storage underpins recurring revenue models.
Application:
Application segments delineate where smart doorbell installations generate the most significant volume and revenue streams.
- Residential Housing:This segment encompasses single-family homes and multi-dwelling units, where smart doorbells enhance personal security and convenience. Suburban communities across the United States are primary drivers for residential smart doorbell adoption.
- Commercial Buildings:Smart doorbells in this segment provide access control, visitor management, and perimeter security for offices and small businesses. Small businesses and multi-tenant offices in urban centers adopt these systems for enhanced security protocols.
- Gated Communities:These installations provide enhanced access management and visitor screening for controlled residential areas.
- Educational Institutions:Smart doorbells contribute to campus security by monitoring entrances and managing visitor access.
- Government Facilities:These applications support controlled access points and perimeter surveillance for public sector buildings.
Residential Housing dominates current installations, with Commercial Buildings representing a significant future growth pathway.
End User:
End user classification highlights the diverse customer base driving demand for smart doorbell solutions across various operational contexts.
- Homeowners:Individuals living in private residences use smart doorbells for personal security, package monitoring, and remote visitor interaction. Suburban homeowners in the United States prioritize smart doorbells for enhanced property surveillance and theft prevention.
- Property Managers:These professionals oversee multi-unit dwellings and commercial properties, leveraging smart doorbells for access control and tenant communication. Apartment complexes and multi-tenant office spaces in urban areas increasingly deploy smart doorbells for streamlined operations.
- Security Firms:These companies integrate smart doorbells into comprehensive security systems for clients, offering professional monitoring services.
- Facility Operators:Personnel managing commercial or institutional buildings use smart doorbells for visitor screening and access point control.
- Tenants:Individuals residing in rental properties utilize smart doorbells for personal security and convenience, often with landlord approval.
Homeowners generate the highest volume demand, while Property Managers represent a rapidly expanding customer segment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The divergence in product compliance standards and data privacy mandates across regions creates regulatory arbitrage opportunities. Manufacturers adapt platform strategies to balance local storage requirements against cloud-based models. This dynamic influences investment decisions and market entry strategies for smart doorbell producers.
United States
Heightened consumer awareness regarding property security and package theft prevention drives smart doorbell demand in the United States. Devices must secure FCC certification for wireless communication before market entry. Suburban communities across the United States, particularly in new housing estates, lead significant smart doorbell adoption for enhanced remote monitoring capabilities.
United Kingdom
New housing construction and suburban security focus stimulate strong smart doorbell demand in the United Kingdom. Devices operating here must comply with GDPR, strictly governing personal data processing captured by video. New housing estates across the United Kingdom integrate Wi-Fi enabled doorbells as standard, leveraging existing network infrastructure for seamless connectivity.
Germany
Demand for advanced security features and smart home integration drives smart doorbell adoption within Germany's premium residential segment. GDPR compliance remains paramount for manufacturers handling video data, influencing product design. Urban centers in Germany see adoption for smart home ecosystems, integrating advanced machine learning capabilities for familiar face detection.
China
Rapid urbanization and increasing disposable income propel smart doorbell demand across China's residential housing segment. National cybersecurity laws and data localization requirements shape product development for local markets. Major cities like Shenzhen and Hangzhou serve as manufacturing hubs, driving innovation in AI-powered facial recognition and cloud storage solutions.
Singapore
High urbanization rates and government initiatives for a smart nation drive smart doorbell adoption in Singapore. The Personal Data Protection Act (PDPA) governs data collection and usage, influencing local storage solutions. New residential developments in Singapore frequently incorporate smart security devices, benefiting from advanced ecosystem integration and reliable internet infrastructure.
Smart Doorbell Market Key Industry Players
Established producers occupy the standard tier, focusing on reliable hardware; emerging entrants pursue integrated security ecosystems and advanced AI features. The market exhibits a tiered structure, with premium providers emphasizing on-device AI and subscription services. Strategic archetypes include hardware-focused manufacturers, cloud-service integrators, and comprehensive security solution providers. Companies primarily engage in portfolio diversification and strategic partnerships to expand their market reach and feature sets.
Within the cloud-integrated segment, Ring (Amazon) exemplifies leveraging a parent company's vast infrastructure to offer integrated services and extensive data storage. Google Nest anchors the advanced machine learning tier, known for its sophisticated familiar face detection capabilities and deep integration into smart home ecosystems. Arlo occupies a position among premium hardware providers, offering robust specifications and a comprehensive subscription security model that includes professional monitoring. These entities represent distinct approaches to product development and recurring revenue generation, shaping competitive dynamics through their unique value propositions and ecosystem strategies.
| Leading Market Players |
|---|
| Eufy (Anker) |
| Botslab |
| Ring (Amazon) |
| ADT |
| SimpliSafe |
| Google Nest |
| EZVIZ |
| Wyze |
| Arlo |
| Others |
Cost & Logistics Intelligence
The bifurcation between premium smart doorbells and basic models influences both pricing strategies and component sourcing across the supply chain.
Pricing Analysis
Retailer markups significantly impact the final consumer price for smart doorbells. A hybrid pricing model combines one-time hardware sales with recurring subscription fees for cloud storage and advanced AI features. Price differentiation stems from advanced features like facial recognition and comprehensive cloud storage plans, alongside premium hardware specifications. Pricing softness affects basic video doorbells due to market saturation and increased competition. Budget-conscious consumers exhibit high price sensitivity for entry-level models, while premium residential buyers prioritize feature sets over cost.
Supply Chain Analysis
Workforce availability in major manufacturing hubs across China directly influences smart doorbell production volumes and costs. Component manufacturing concentrates heavily in China, particularly for integrated circuits and camera modules. The industry relies on a consistent supply of custom semiconductors, high-definition camera sensors, and Wi-Fi communication modules. Single-source vulnerability for specialized AI-enabled semiconductors presents a structural risk for premium product lines. Distribution runs primarily through online retail channels and consumer electronics stores, with security system integrators handling bundled offerings.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Smart Doorbell Market presents a clear margin-expansion story, driven by a sustained shift towards premium models with advanced AI features.
For Market Incumbents: Deepen integration with existing smart home ecosystems to counter fragmentation and enhance user stickiness. Invest in proprietary on-device AI for facial recognition, reducing reliance on cloud processing and addressing data privacy concerns (GDPR). This strategy mitigates the threat from emerging entrants focusing solely on low-cost hardware. Leverage parent company cloud infrastructure, like Ring (Amazon), to offer comprehensive, integrated security services and subscription plans.
For New Entrants and Emerging Players: Begin with targeted entry into underpenetrated commercial building access control applications. Small businesses and multi-tenant offices represent a white-space opportunity beyond the saturated residential market. Focus on providing cost-effective, scalable solutions that integrate with existing access systems. A subscription-first model, bundling hardware with managed services, provides a clear go-to-market angle for recurring revenue.
For Investors and Strategic Acquirers: Consolidation pressure builds where regulatory divergence (FCC vs. GDPR) creates operational complexity for global players. Long-term viability hinges on platforms capable of adapting to varied data privacy mandates while offering advanced features. Acquisition targets should be agile software-centric firms with strong on-device AI capabilities or established regional market share. The signal to watch is the successful deployment of dual-track product lines across Europe and North America by smaller innovators.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Custom AI Semiconductors | Improves on-device AI performance for facial recognition, enhancing privacy and reducing cloud dependency. |
| Expand Commercial Access Control | Diversifies revenue streams beyond residential housing, targeting small businesses and multi-tenant offices. |
| Develop Dual-Track Software Platforms | Ensures product compliance with GDPR in Europe and FCC in the US, facilitating global market entry. |
| Strengthen Ecosystem Integrations | Bundles smart doorbells with smart locks and alarm systems, increasing customer lifetime value for homeowners. |
| Penetrate Southeast Asian Markets | Captures new residential demand in rapidly urbanizing regions like Singapore and Malaysia. |
Research Approach
Direct dialogue with smart doorbell manufacturers, security system integrators, and property managers informed primary data collection. Secondary validation drew from FCC certification documents, GDPR compliance reports, and consumer electronics market analyses. Interviews targeted product development leads, sales directors, and smart home technology specialists. A bottom-up estimation and top-down validation process triangulated market size and growth drivers.
The quantitative model produced granular volume and value projections across the analysis window. Segmentation dimensions included product type, underlying technology, application area, end-user, and key geographic regions. Compound annual growth rates were derived from historical trends, technological adoption curves, and projected infrastructure investments. Key forecast inputs included new housing construction rates and consumer spending on home security solutions.
Several conditions sit outside the modeled scope, including unforeseen geopolitical shifts and rapid changes in raw material costs. Forecasts reflect assumptions regarding stable regulatory environments and consistent technological innovation within the smart home sector. Material deviation in data privacy legislation or semiconductor supply chain stability warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Construction Wearables Market
Others
IoT Testing Market
Others
Next Gen Video Codecs Market
Others
Rotary Union Market
Others
Electric Chainsaw Market
Others
Europe Electric Forklift Market
Others
Paraffin Physical Therapy Market
Others
Healthcare Bioconvergence Market
Others
Nuclear Power Cables Market
Others
Tobacco Packaging Market
Others
Profilometer Market
Others
Inorganic Tin Chemicals Market
Others
Griffin Beaker Market
Others
Durian Market
Others
Boston Round Bottle Market
Others
Gas Holders Market