
 Global Simulation in Healthcare Market | 2026-2036
Global Simulation in Healthcare Market Size, Share, and Industry Trends Forecast 2026-2036
Global Simulation in Healthcare Market Foresight
Subscription-based software licensing for scenario authoring and curriculum management is realigning how vendors monetize hardware deployments. CAE Healthcare leverages its digital ecosystem to sustain recurring revenue beyond simulator sales. Laerdal Medical anchors its position through intensive R&D investment in patient physiology modeling. Kyoto Kagaku specializes in anatomical fidelity for Asian medical education markets, differentiating its product line through regional anatomical variations.
Healthcare simulation encompasses manikin-based, virtual reality, screen-based, and mixed reality systems that replicate physiological responses, anatomical structures, and clinical scenarios for training without patient risk. These platforms integrate haptic feedback mechanisms, physiological modeling algorithms, and debriefing software to enable repeatable skill acquisition and team-based crisis resource management. Manikin-based simulators retain the largest installed base and margin pool across academic medical centers, while mixed reality systems represent the fastest-expanding segment as headset hardware costs decline and surgical visualization demands intensify. Cloud-based deployment models are gaining traction among nursing colleges and continuing medical education providers seeking distributed access to standardized curricula.
The FDA Center for Devices and Radiological Health exercises oversight of simulator hardware classified as medical devices, while the EU Medical Device Regulation mandates clinical validation documentation for products entering European markets. ISO 9001 and ISO 13485 quality management standards govern manufacturing processes for simulation equipment sold across multiple jurisdictions. Stakeholders must monitor evolving regulatory distinctions between educational tools and diagnostic devices, as reclassification would reshape compliance burdens and market access pathways for mixed reality surgical trainers.
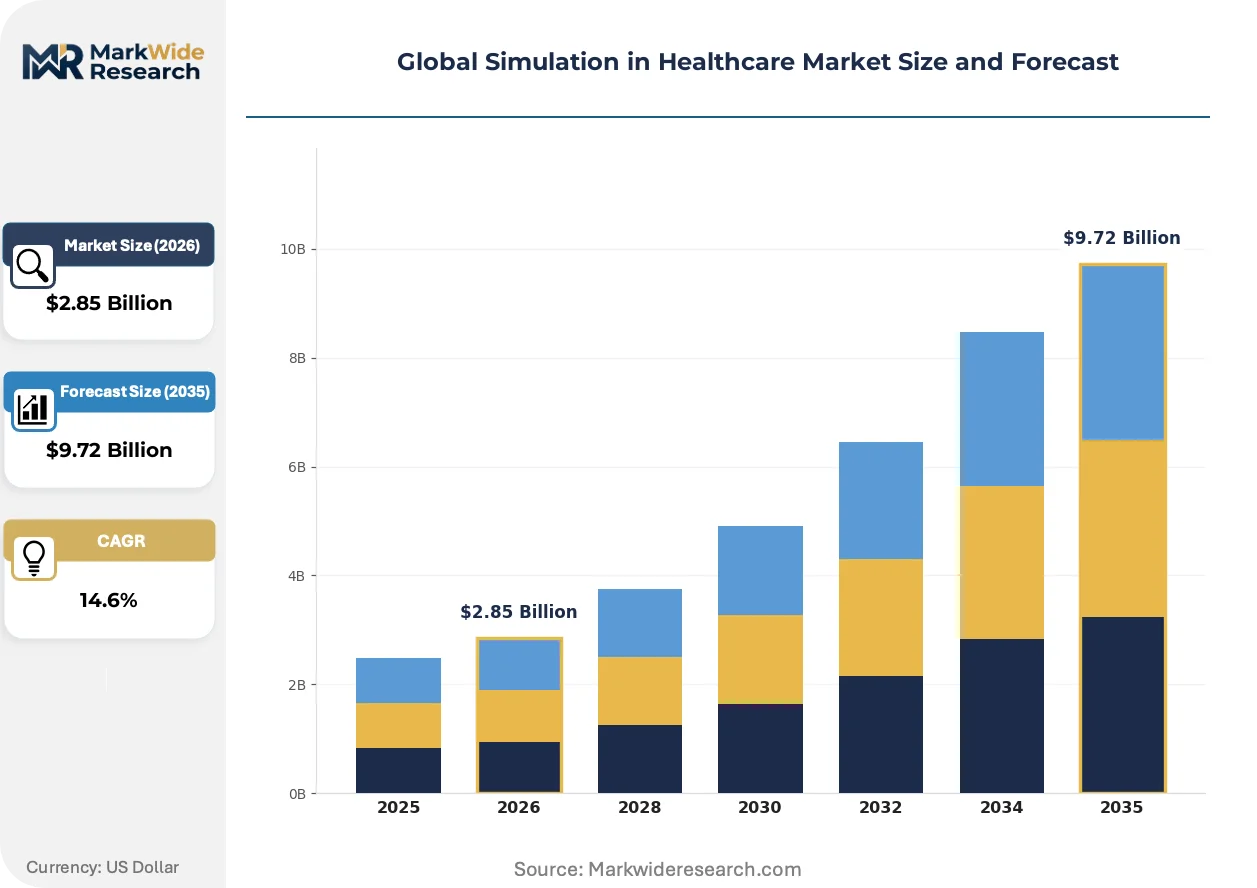
Market Dynamics
Subscription-based software licensing is restructuring vendor economics across manikin-based and virtual reality training systems, compressing upfront hardware margins while extending customer lifetime value through recurring scenario authoring and curriculum management fees.
Growth Catalysts
- FDA guidance on simulation-based medical education:Tightened validation requirements for clinical training tools are accelerating institutional procurement of certified systems that demonstrate measurable competency outcomes.
- Academic medical centers:These facilities in the United States, Germany, and Japan are expanding dedicated simulation training infrastructure to meet accreditation standards for graduate medical education.
- Headset hardware cost declines:Reduced pricing for mixed reality devices is enabling surgical visualization training programs previously constrained by capital budgets.
Market Restraints
- EU Medical Device Regulation compliance costs:Clinical validation documentation requirements for products entering European markets impose substantial regulatory friction on smaller equipment manufacturers.
- High-fidelity manikin component concentration:Specialized pneumatic actuators and sensor arrays for physiological modeling rely on limited supplier bases in precision manufacturing clusters.
- Screen-based simulation substitution:Lower-cost computer-based training modules compete for budget allocation in nursing colleges and continuing medical education programs.
Strategic Opportunities
- Cloud-based deployment models:Distributed access architectures enable nursing colleges and continuing medical education providers to standardize curricula across multiple campus locations without capital-intensive hardware replication.
- Regional anatomical variations:Product lines differentiated for Asian medical education markets address underpenetrated demand for culturally specific patient physiology representation.
- ISO 13485 quality certification:Manufacturers achieving this medical device quality management standard gain preferential access to institutional procurement processes requiring documented manufacturing rigor.
Industry Challenges
- Debriefing software integration complexity:Institutions struggle to synchronize performance analytics from disparate simulator platforms with existing learning management systems.
- Simulation technician workforce scarcity:Specialized personnel capable of operating high-fidelity manikins and troubleshooting mixed reality hardware remain concentrated in major academic medical centers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Simulation in Healthcare Market |
| Market Size in 2026 | $2.85 Billion |
| Market Size in 2035 | $9.72 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Virtual Reality Simulators, Manikin-Based Simulators, Task Trainers, Mixed Reality Systems, Screen-Based Simulators Therapy Area: Surgical Training, Emergency Response, Anesthesia Simulation, Obstetrics & Gynecology, Cardiology Training End User: Medical Schools, Research Institutes, Military Medical Training, Nursing Colleges, Continuing Medical Education Providers Deployment: On-Premise Solutions, Cloud-Based Platforms, Hybrid Models, Mobile Application Integration, Remote Access Systems |
| Companies Covered | Laerdal Medical, CAE Healthcare, Gaumard Scientific, 3D Systems, Simulab Corporation, Limbs & Things Ltd, Surgical Science Sweden AB, Mentice, Kyoto Kagaku Co., Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Simulation in Healthcare Market Shifts & Advancements
Physiological modeling algorithms and haptic feedback mechanisms are advancing in parallel, enabling more responsive patient simulators that replicate crisis scenarios with greater anatomical fidelity and measurable training outcomes.
Haptic feedback mechanisms are advancing rapidly in surgical training applications. Teaching hospitals in Germany and Japan are deploying force-feedback devices that replicate tissue resistance during laparoscopic procedures. This tactile technology is converging with mixed reality visualization systems to compress the gap between simulated and live operative environments.
The EU Medical Device Regulation is reclassifying certain mixed reality surgical trainers as diagnostic devices rather than educational tools. This regulatory shift forces manufacturers to submit clinical validation studies previously unnecessary for training-only products. European academic medical centers are responding by consolidating procurement around vendors with established MDR compliance infrastructure.
Hospital procurement committees are unbundling after-sales service contracts from hardware purchases. Large health systems in the United States now negotiate simulator maintenance and scenario library updates through separate vendor relationships. This purchasing pattern shift is most visible among integrated delivery networks seeking to standardize training curricula across geographically dispersed facilities.
Global Simulation in Healthcare Market Segmentation
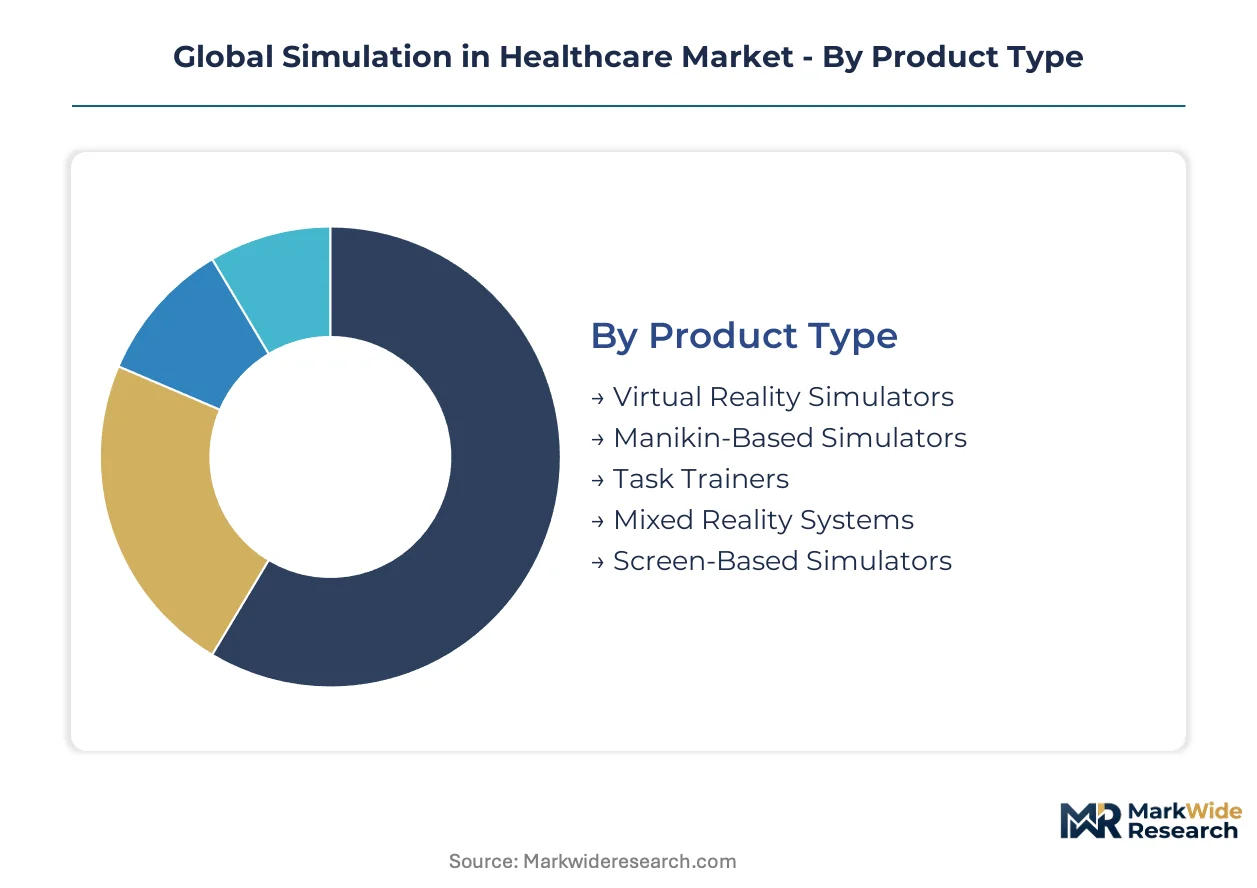
Product architecture in healthcare simulation determines capital intensity, software licensing economics, and regulatory classification pathways. Vendors structure portfolios across hardware fidelity tiers and deployment models to capture distinct budget cycles in academic and military training environments.
Product Type:
Supply concentration in pneumatic actuators and physiological sensor arrays favors established manufacturers with captive component sourcing.
- Manikin-Based Simulators:Full-body patient replicas integrate pneumatic-driven respiratory systems, circulatory pulse mechanisms, and pharmacological response modeling. Academic medical centers in the United States and Germany anchor procurement volumes as graduate medical education accreditation mandates expand hands-on crisis training requirements.
- Mixed Reality Systems:Headset-based surgical visualization platforms combine haptic feedback peripherals with three-dimensional anatomical rendering. Demand concentrates in Japanese teaching hospitals where laparoscopic procedure volumes drive investment in immersive operative environments.
- Virtual Reality Simulators:Immersive environments for procedural training without physical patient models.
- Task Trainers:Anatomical models for isolated skill acquisition such as intubation or catheterization.
- Screen-Based Simulators:Computer-based clinical decision-making scenarios with lower capital requirements.
Today's leader: Manikin-Based Simulators. Tomorrow's challenger: Mixed Reality Systems.
Therapy Area:
Application concentration tracks procedure complexity and malpractice exposure rather than pure procedure volume.
- Surgical Training:Laparoscopic, endoscopic, and open procedure simulation with force-feedback instrumentation. German university hospitals and Japanese medical centers drive specialized procurement as minimally invasive surgery adoption intensifies training demands for tactile skill transfer.
- Emergency Response:Crisis resource management scenarios for trauma, cardiac arrest, and mass casualty events. Military medical training facilities in the United States sustain dedicated budgets for repeatable high-stress team coordination exercises.
- Anesthesia Simulation:Airway management and pharmacological response training environments.
- Obstetrics & Gynecology:Delivery complications and neonatal resuscitation scenarios.
- Cardiology Training:Cardiac catheterization and electrophysiology procedure simulation.
Surgical Training commands the largest absolute spend. Emergency Response is climbing the fastest as military and civilian disaster preparedness budgets converge.
End User:
Customer-type segmentation reveals divergent procurement authority structures and replacement cycle timing.
- Medical Schools:Comprehensive simulation centers with dedicated technical staff and curriculum integration mandates. United States allopathic and osteopathic institutions lead capital deployment as LCME accreditation standards tighten clinical skills assessment requirements.
- Nursing Colleges:Scaled deployments across multiple campus locations with standardized competency tracking. Cloud-based platform adoption accelerates among these institutions seeking distributed access without hardware replication at every site.
- Research Institutes:Specialized physiological modeling and device validation applications.
- Military Medical Training:Deployable field simulation and combat casualty care scenarios.
- Continuing Medical Education Providers:Certification maintenance and skills refresher programs for practicing clinicians.
Medical Schools dominate capital allocation. Nursing Colleges are expanding most quickly as RN workforce growth strains training capacity.
Deployment:
Infrastructure configuration determines recurring revenue potential and data sovereignty compliance burdens.
- Cloud-Based Platforms:Centralized scenario libraries with multi-site curriculum synchronization and performance analytics. EU nursing colleges and continuing medical education providers accelerate adoption despite GDPR-mandated data residency requirements for patient-representative training content.
- On-Premise Solutions:Local hardware and software installations with institutional data control. Japanese academic medical centers prefer this architecture given METI guidance on healthcare data localization and cybersecurity standards for connected medical devices.
- Hybrid Models:Combined local processing with cloud-based content delivery and updates.
- Mobile Application Integration:Smartphone and tablet-based supplemental training modules.
- Remote Access Systems:Distributed instructor oversight and debriefing for geographically dispersed learners.
On-Premise Solutions retain the largest installed base. Cloud-Based Platforms are gaining share fastest as subscription licensing restructures vendor economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States academic medical centers deploy simulation infrastructure at triple the density of German university hospitals, while Japanese teaching hospitals concentrate investment in mixed reality surgical platforms rather than manikin-based systems.
United States
LCME accreditation mandates and military medical training budgets drive procurement of high-fidelity manikins and crisis resource management facilities. FDA guidance on simulation-based medical education tightens validation requirements for institutional purchasing decisions. Texas Medical Center in Houston and Massachusetts General Hospital in Boston operate the largest dedicated simulation training complexes with multi-million dollar annual technology refresh cycles.
Germany
Minimally invasive surgery adoption accelerates demand for haptic-enabled laparoscopic trainers across university hospital networks. EU Medical Device Regulation compliance costs filter smaller vendors from public procurement processes. Heidelberg and Berlin academic medical centers anchor specialized procurement for force-feedback surgical simulation systems with integrated debriefing analytics.
Japan
METI guidance on healthcare data localization shapes preference for on-premise deployment architectures in connected medical devices. Kyoto Kagaku's regional anatomical specialization addresses demand for culturally specific patient physiology representation. Tokyo and Osaka teaching hospitals lead headset-based surgical visualization adoption as laparoscopic procedure volumes intensify immersive training requirements.
United Kingdom
Nursing college expansion strains training capacity and accelerates cloud-based platform adoption for distributed curriculum standardization. MHRA oversight aligns with EU MDR transitional provisions for simulation equipment classification. London and Manchester academic clusters consolidate procurement around vendors with established quality management certifications.
South Korea
MFDS regulatory frameworks for medical device software influence validation documentation requirements for imported simulation platforms. Seoul National University Hospital and Samsung Medical Center drive specialized procurement for cardiology and anesthesia simulation systems with integrated physiological modeling algorithms.
Global Simulation in Healthcare Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated solution providers capturing premium pricing in academic medical centers while component suppliers serve price-sensitive nursing college deployments. The vendor base concentrates around three strategic archetypes: physiology modeling specialists, anatomical fidelity manufacturers, and software-centric platform operators. M&A activity targets scenario authoring capabilities and debriefing analytics integration. Geographic expansion into Asian medical education markets represents the dominant competitive vector.
Among the established specialist tier, Laerdal Medical and CAE Healthcare exemplify divergent monetization strategies through hardware-centric versus software-recurring revenue models. Kyoto Kagaku Co., Ltd occupies a distinct position serving regional anatomical variation demand. These three anchors demonstrate how vendor origin and organizational structure shape competitive positioning without requiring uniform technology portfolios or customer targeting approaches.
| Leading Market Players |
|---|
| Laerdal Medical |
| CAE Healthcare |
| Gaumard Scientific |
| 3D Systems |
| Simulab Corporation |
| Limbs & Things Ltd |
| Surgical Science Sweden AB |
| Mentice |
| Kyoto Kagaku Co., Ltd |
| Others |
Supply & Pricing Matrix
ISO 13485 quality certification gates both qualified supply and premium-tier pricing access in healthcare simulation, as academic medical centers and military training facilities restrict procurement to vendors demonstrating documented manufacturing rigor while commanding substantial price premiums for validated systems.
Pricing Analysis
Capacity additions in Germany and Japan are reshaping price floors for haptic-enabled surgical trainers as regional manufacturers expand production of force-feedback peripherals. Pricing stratifies across premium, standard, and economy tiers based on physiological modeling fidelity and FDA validation tier. Cost compression in screen-based modules is intensifying because nursing colleges substitute lower-fidelity alternatives for budget-constrained deployments. Medical schools exhibit least price sensitivity given accreditation-mandated procurement timelines, while continuing medical education providers demonstrate highest sensitivity to per-seat licensing costs.
Supply Chain Analysis
Direct-to-academic-medical-center channels handle hyperscale buyer demand for integrated simulation center deployments. Component sourcing concentrates in Germany, Japan, and the United States for pneumatic actuators, physiological sensor arrays, and precision-machined anatomical molds. Manufacturing draws from specialized suppliers of silicone tissue analogs, microfluidic circulatory systems, and mixed reality headset optics. Single-source vulnerability in high-fidelity manikin pneumatic systems poses structural risk given limited qualified suppliers in precision manufacturing clusters. Distribution runs through authorized dealer networks with embedded technical service capabilities for complex hardware installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Simulation in Healthcare Market operates as a stable compounder where recurring software licensing revenue from scenario authoring platforms generates predictable cash flows that offset capital-intensive hardware replacement cycles.
For Market Incumbents: Acquire debriefing analytics software capabilities to address integration complexity that institutions face when synchronizing performance data across disparate simulator platforms. Consolidate scenario authoring talent pools to defend against cloud-native entrants offering modular, API-first curriculum management. Prioritize ISO 13485 certification maintenance as EU MDR compliance costs filter smaller competitors from institutional procurement processes. For New Entrants and Emerging Players: The price-point gap between premium manikin-based systems and economy screen-based modules creates entry space for mid-fidelity hybrid offerings targeting nursing colleges with distributed campus architectures. White-space concentration exists in regional anatomical variation products for Asian medical education markets currently underserved by Western physiology models. Cloud-based deployment with subscription-tiered pricing offers the most penetrable go-to-market angle against incumbent hardware-centric incumbents. For Investors and Strategic Acquirers: Roll-up economics work for specialized debriefing software providers because hospital procurement committees are unbundling after-sales service contracts from hardware purchases, creating fragmented vendor relationships ripe for consolidation. Five-to-ten-year viability rests on recurring revenue attachment rates rather than one-time simulator sales. Acquisition target archetype: scenario authoring platforms with established curriculum libraries and multi-site synchronization capabilities. Monitor mixed reality surgical trainer reclassification under EU MDR as inflection signal for regulatory compliance infrastructure valuations.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR reclassification of mixed reality trainers as diagnostic devices mandates clinical validation documentation for European market access. |
| Hospital System Partnership | Integrated delivery networks in the United States consolidate procurement around vendors offering standardized curricula across geographically dispersed facilities. |
| Software Companion Development | Cloud-based scenario authoring platforms enable nursing colleges to synchronize competency tracking across multiple campus locations without hardware replication. |
| FDA Submission | Tightened FDA guidance on simulation-based medical education accelerates institutional demand for certified systems demonstrating measurable competency outcomes. |
| Reimbursement Strategy | Graduate medical education accreditation mandates for hands-on crisis training create budget line-item security for high-fidelity manikin procurement. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with simulation center directors, biomedical engineers, hospital purchasing committee members, and GPO contracts managers with secondary validation against FDA guidance documents, EU MDR regulatory filings, hospital procurement databases, and ISO certification registries. Bottom-up installation base modeling and top-down expenditure flow analysis provided cross-check triangulation.
Historical reference periods anchored the projection horizon to observed replacement cycles and technology refresh patterns across academic medical centers. Segmentation dimensions modeled include product architecture fidelity tier, therapy area procedural complexity, end-user procurement authority structure, and deployment infrastructure configuration. CAGRs were derived from installed base expansion rates and per-unit software licensing attachment trends, with surgical visualization demand intensity and cloud platform adoption velocity serving as key forecast inputs.
Caveats apply where EU MDR enforcement discretion, mixed reality hardware cost trajectories, or simulation technician workforce availability could materially shift the outlook. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Pollen Allergy Market
Others
DIY Smart Home Market
Others
Quadrant Scale Market
Others
US Quantum Computing Market
Others
Augmented Reality (AR) in Warehousing and Logistics Market
Others
Durian Fruit Market
Others
Cremation Furnace Market
Others
Europe Indoor LBS Market
Others
Brazil Passenger Vehicles Lubricants Market
Others
Allogeneic T Cell Therapies Market
Others
Global Cigarette Packaging Market
Others
Latin America Travel Retail Market
Others
Turkey Health and Medical Insurance Market
Others
Corn Fiber Market
Others
Fiber to the X (Fttx) Tester Market
Others
Asia Pacific Video Conferencing Hardware Market