
 Europe Meditation Market | 2026-2036
Europe Meditation Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Meditation Market Foresight
The Europe meditation sector is recalibrating around a widening gap between premium clinical-grade platforms and commoditized freemium apps. Headspace leverages its NHS partnerships to anchor credibility in healthcare reimbursement pathways. Petit BamBou sustains dominance in French-speaking markets through localized content depth. Meditopia competes aggressively on price across Southern and Eastern European markets where employer wellness budgets remain constrained.
Meditation encompasses structured mental training protocols delivered through audio, visual, or immersive interfaces to reduce stress, improve attention regulation, and support emotional health outcomes. European platforms increasingly integrate heart rate variability biofeedback and EEG-responsive audio modulation to personalize session pacing. Guided Sessions command the deepest margin pools as corporate buyers negotiate multi-year enterprise licenses. Wearable delivery modes represent the fastest-expanding channel as Apple Watch and Oura Ring APIs enable real-time stress-intervention triggers. Meditation Apps remain the most mature segment with saturation visible in English-language markets.
GDPR imposes strict consent architectures on apps processing biometric data from wearable integrations, while France's CNIL actively audits meditation platforms for excessive health data retention. The EU AI Act will classify emotion-recognition algorithms in meditation apps as high-risk systems requiring conformity assessments. Stakeholders must monitor whether national health technology assessment bodies in Germany and the Netherlands will expand reimbursement codes to cover prescription digital therapeutics incorporating meditation protocols.
Market Dynamics
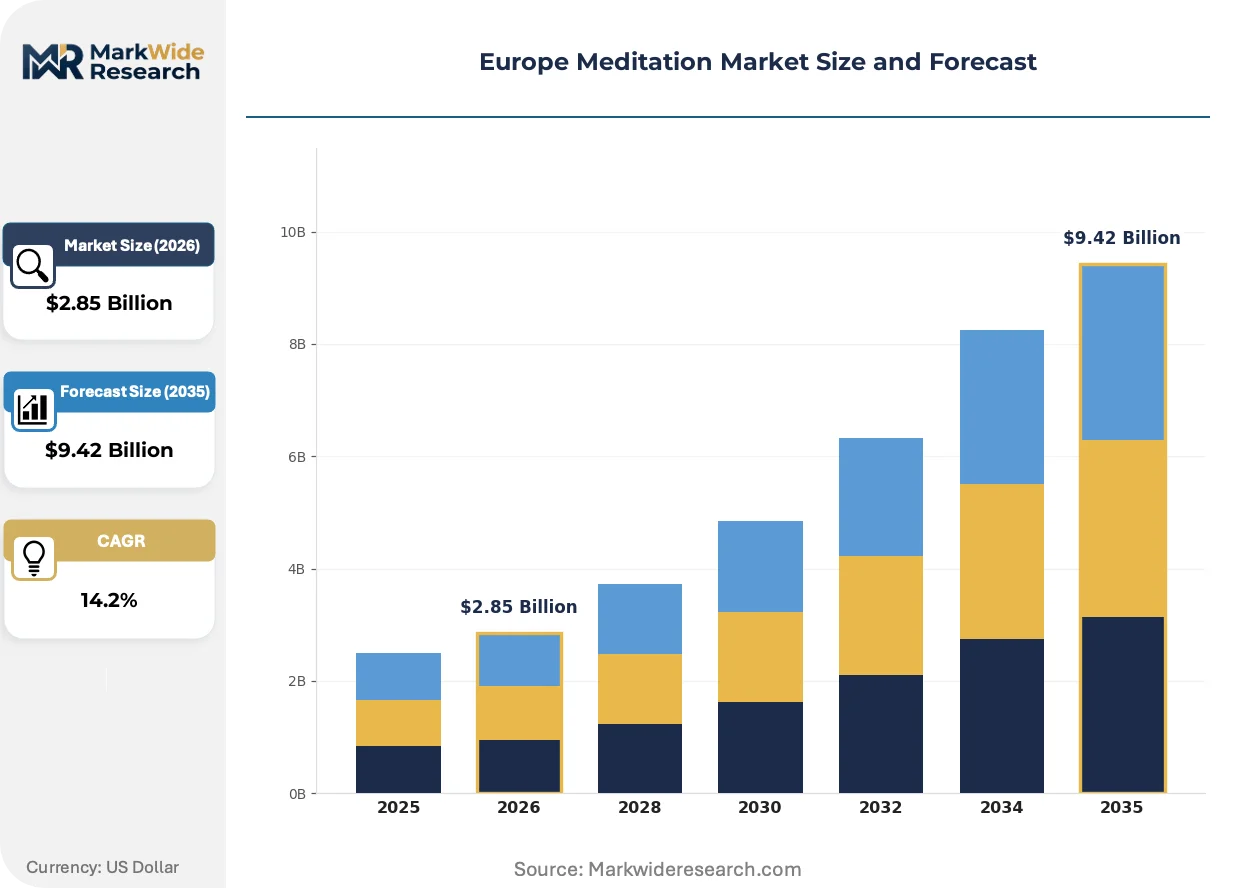
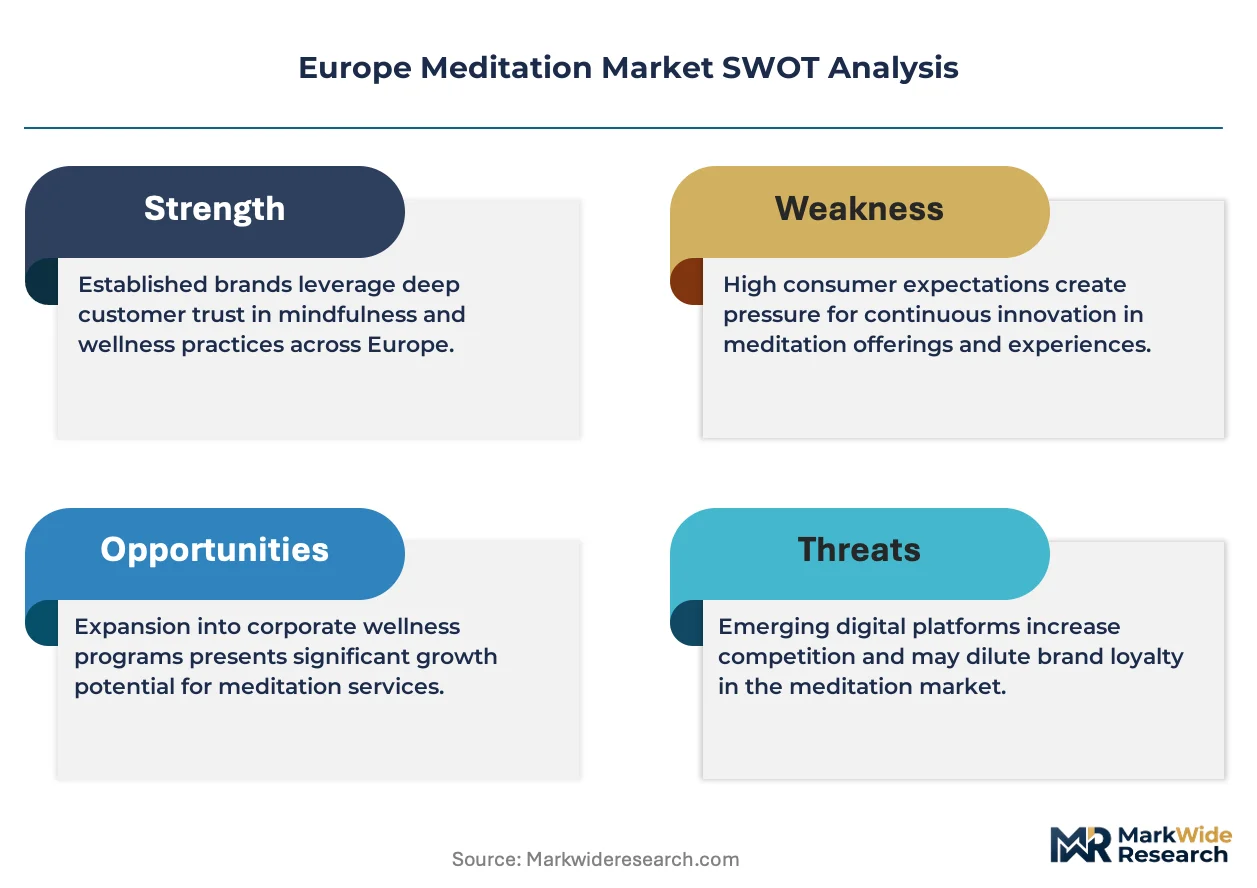
The Europe meditation market is bifurcating sharply between clinical-grade platforms seeking healthcare reimbursement and freemium apps racing to the bottom on price, with GDPR and the EU AI Act forcing costly compliance architectures that favor well-capitalized incumbents.
Growth Catalysts
- GDPR-mandated data transparency:France's CNIL audits have elevated consumer trust in compliant platforms, accelerating enterprise procurement of certified wellness subscriptions by HR departments in Paris and Lyon.
- Wearable biofeedback convergence:Apple Watch and Oura Ring APIs enable real-time heart rate variability interventions, pulling hardware-software bundles into corporate wellness contracts across Germany.
- NHS reimbursement pathways:United Kingdom health technology assessment bodies now evaluate meditation apps for prescription digital therapeutic status, opening clinical revenue streams distinct from consumer subscriptions.
Market Restraints
- Biometric data retention limits:GDPR Article 5 storage limitation principles force platforms to purge stress data faster than longitudinal research protocols require, degrading personalization algorithm training.
- English-language content saturation:Freemium apps have flooded British and Irish markets with undifferentiated guided sessions, compressing price points and subscriber lifetime value.
- Emotion-recognition algorithm classification:The EU AI Act designates affective computing in meditation apps as high-risk, imposing conformity assessment costs that exclude smaller developers from the French and German markets.
Strategic Opportunities
- Eastern European employer wellness gaps:Poland and Romania show minimal corporate meditation penetration despite EU-mandated workplace mental health obligations, creating first-mover terrain for localized platforms.
- Clinical psychology service bundling:Paris and Lyon startups demonstrate viable models combining meditation with licensed therapy, suggesting expansion paths into Netherlands and Belgium reimbursement systems.
- Prescription digital therapeutic codes:Germany's Federal Institute for Drugs and Medical Devices is evaluating category creation for software-based mental health interventions, potentially unlocking statutory health insurance coverage.
Industry Challenges
- EEG-responsive audio engineering talent scarcity:Neurofeedback-informed session modulation requires specialized signal processing expertise concentrated in Swiss and Dutch university clusters, creating recruitment bottlenecks.
- Cross-border data transfer complexity:Meditation platforms serving French users from Irish data centers face Schrems II litigation exposure, forcing infrastructure duplication that strains mid-cap balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Meditation Market |
| Market Size in 2026 | $2.85 Billion |
| Market Size in 2035 | $9.42 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Meditation Apps, Guided Sessions, Retreats, Audio Programs Delivery Mode: Online, Offline, Mobile, Wearable End User: Individuals, Corporates, Healthcare Facilities, Educational Institutions Age Group: Children, Young Adults, Adults, Seniors |
| Companies Covered | 7Mind, FITCOMPANY, Headspace, B-Reel, NeuropilotVR, Meditopia, Mindgram, XRHealth, Petit BamBou, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Meditation Market Shifts & Advancements
European meditation platforms are pivoting from content libraries toward closed-loop biometric systems, with regulatory compliance and clinical credibility emerging as the primary axes of differentiation.
Real-time heart rate variability biofeedback is rewriting how session pacing adapts to physiological state. Corporate wellness buyers in Germany now specify HRV-responsive audio modulation in procurement tenders. This capability is compressing competitive differentiation to sensor integration depth and clinical validation rigor.
The EU AI Act's high-risk classification for emotion-recognition algorithms is forcing platform architects to redesign affective computing pipelines. Developers must submit conformity assessments to notified bodies before deploying stress-detection models. French-speaking markets show earliest adaptation, with CNIL pre-certification becoming a de facto market access requirement.
Employer wellness departments are consolidating vendor relationships around multi-year enterprise licenses that bundle meditation with broader mental health benefits. British NHS trusts and German Betriebskrankenkassen now negotiate these contracts directly, displacing individual app store purchases. This concentration is most visible in London and Berlin, where procurement teams favor platforms with existing healthcare reimbursement traction.
Europe Meditation Market Segmentation
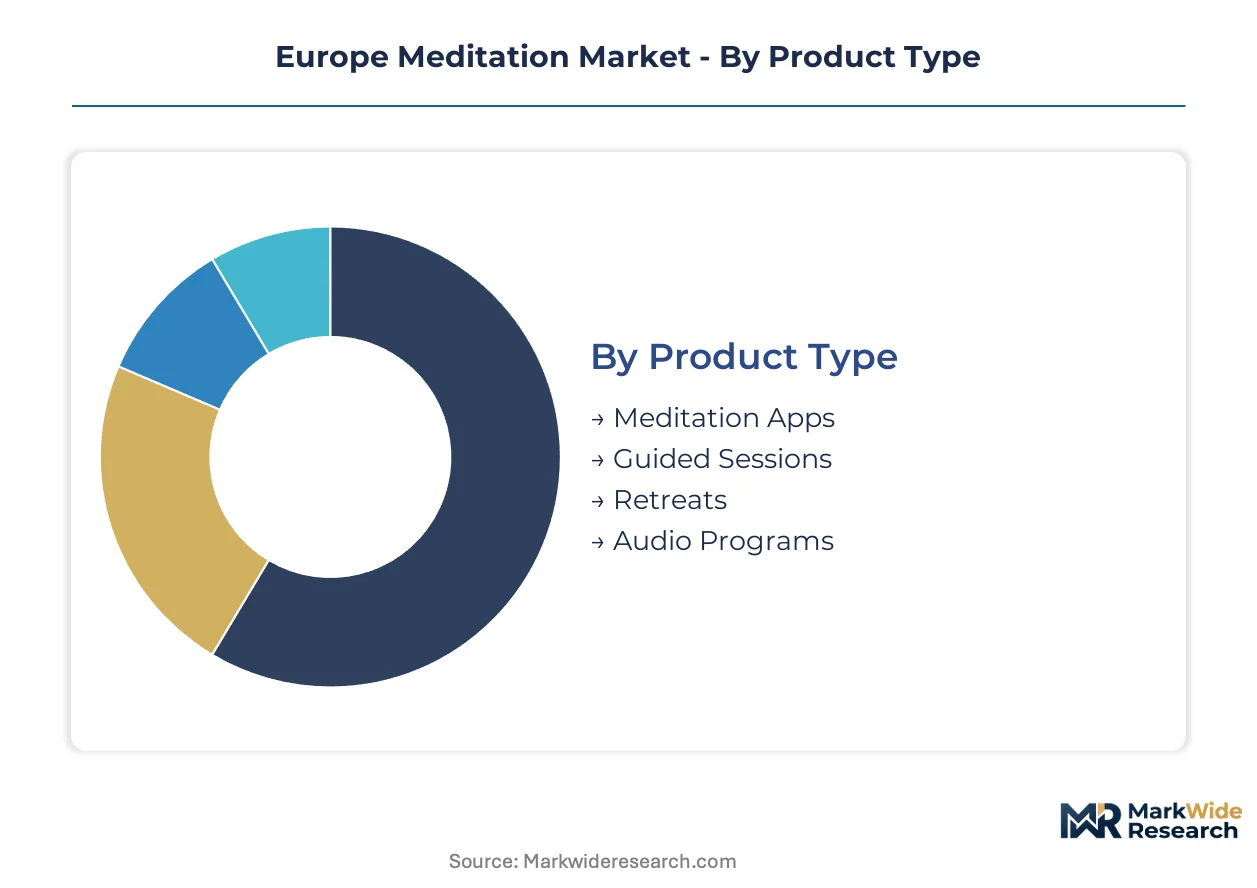
Segmentation reveals how capital deployment and regulatory exposure vary sharply across the Europe meditation market. Product type determines content production costs, while delivery mode shapes GDPR compliance architecture and hardware integration requirements.
Product Type:
Capital intensity concentrates in platforms requiring continuous content production and clinical validation infrastructure.
- Meditation Apps:Software platforms delivering on-demand libraries through iOS and Android ecosystems. German and French corporate wellness buyers now mandate GDPR-compliant data architectures as table stakes for procurement. Most installed capacity flows through Meditation Apps. Expansion is steepest in Guided Sessions.
- Guided Sessions:Structured audio or video protocols led by instructors, often bundled into enterprise multi-year licenses. Paris and Lyon startups blend these with licensed psychology services to access reimbursement pathways. These command premium pricing in corporate contracts across Germany.
- Retreats:In-person immersive experiences requiring physical venue investment and instructor certification overhead. Portuguese and Spanish wellness tourism clusters absorb significant fixed-cost infrastructure.
- Audio Programs:Downloadable or streaming content libraries with lower marginal distribution costs. Polish and Romanian markets show rising demand for localized language versions.
Corporate procurement concentrates purchasing power in Guided Sessions. Audio Programs gain share fastest in price-sensitive Southern and Eastern European markets.
Delivery Mode:
Hardware-software integration depth separates margin tiers, with wearable biofeedback requiring the steepest engineering investment.
- Wearable:Real-time physiological monitoring through Apple Watch and Oura Ring APIs enabling adaptive session pacing. German corporate wellness tenders now specify HRV-responsive audio modulation as a mandatory feature.
- Mobile:Smartphone-native delivery through iOS and Android applications representing the most mature distribution channel. GDPR consent flows and biometric data retention limits constrain personalization algorithm development.
- Online:Browser-based platforms accessible across devices with lower development overhead than mobile-native apps. British and Irish markets show saturation in undifferentiated freemium offerings.
- Offline:Location-based delivery including studio sessions and retreat centers requiring physical presence. French CNIL audits have elevated trust in compliant offline providers handling minimal digital biometric data.
Enterprise contracts flow predominantly through Mobile and Wearable channels. Wearable delivery climbs the fastest as hardware-software bundles penetrate German corporate wellness programs.
End User:
Buyer sophistication and contract scale vary dramatically, with healthcare procurement requiring clinical-grade evidence packages.
- Corporates:Employer wellness departments negotiating multi-year enterprise licenses as standard benefits across Germany and France. NHS trusts and German Betriebskrankenkassen now consolidate vendor relationships around bundled mental health offerings.
- Healthcare Facilities:Hospitals and clinics evaluating meditation platforms for prescription digital therapeutic status. United Kingdom health technology assessment bodies actively review clinical validation data for reimbursement eligibility.
- Individuals:Direct-to-consumer subscribers purchasing through app stores, concentrated in English-saturated British and Irish markets with compressed price points.
- Educational Institutions:Universities and schools adopting meditation for student mental health support, with EU-mandated workplace mental health obligations driving adoption in tertiary settings.
Revenue concentration sits with Corporate buyers. Healthcare Facilities represent the steepest expansion trajectory as reimbursement codes emerge in Germany and the Netherlands.
Age Group:
Content localization and therapeutic framing requirements differ substantially across developmental stages.
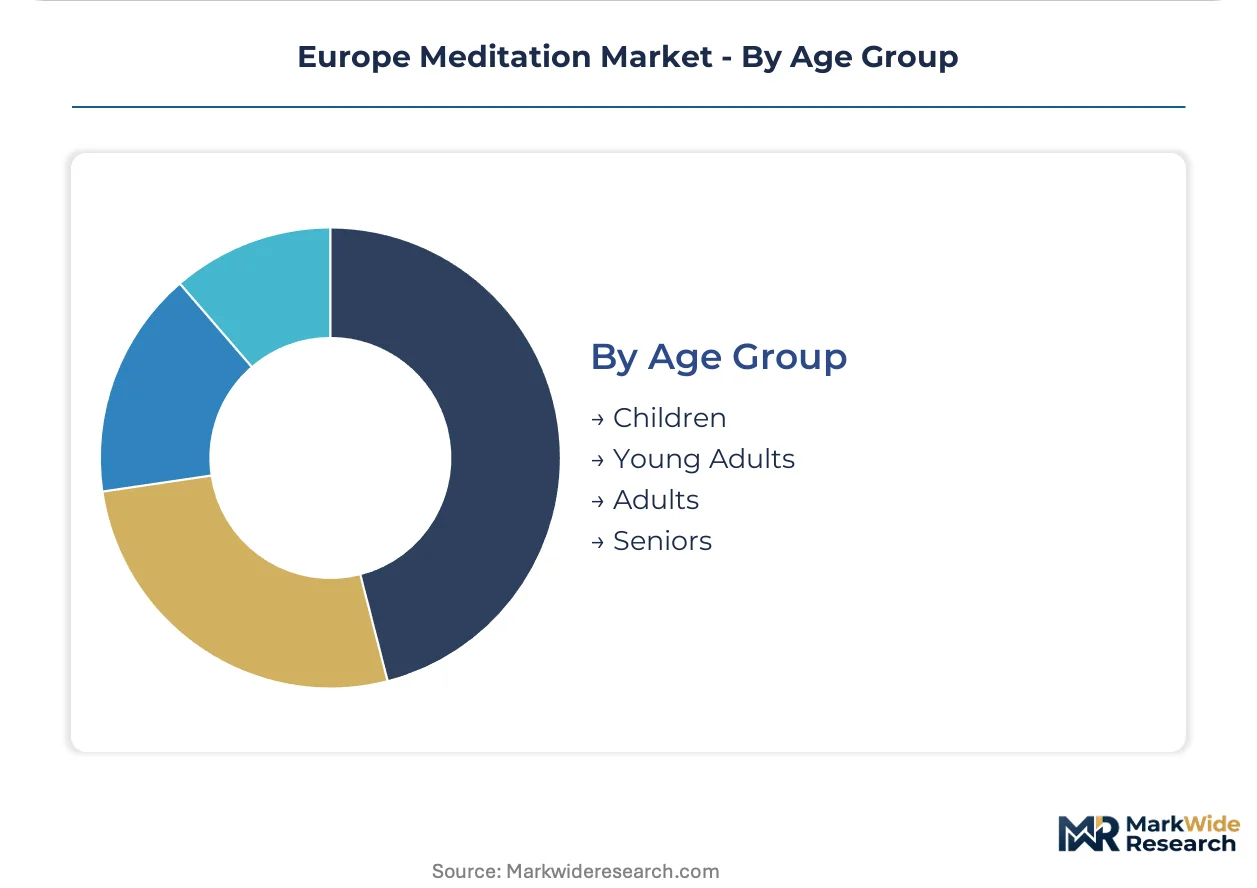
- Adults:Working-age professionals driving corporate wellness subscription volumes across German and French employer programs. Stress management and productivity enhancement dominate value propositions.
- Young Adults:University students and early-career professionals targeted through educational institution partnerships and digital-native platform design. Southern European markets show particular concentration in this cohort.
- Seniors:Aging populations in France and Germany accessing meditation through healthcare referrals for cognitive health and isolation mitigation. Clinical psychology bundling models in Paris demonstrate viable service integration.
- Children:School-based programs and pediatric healthcare integrations requiring specialized content moderation and parental consent architectures under GDPR.
Adult segments absorb the majority of current spending. Seniors gain share fastest as clinical credibility unlocks healthcare reimbursement channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Clinical psychology talent clusters in Paris, Lyon, and Berlin anchor the continent's meditation innovation capacity. These cities host dense networks of digital health startups blending mental training protocols with licensed therapy services. Employer wellness procurement concentrates purchasing power in German and French metropolitan corridors.
Germany
Betriebskrankenkassen corporate health insurance funds now negotiate multi-year enterprise meditation licenses as standard employee benefits. The Federal Institute for Drugs and Medical Devices evaluates prescription digital therapeutic categories for software-based mental health interventions. Berlin and Munich host hardware-software integration engineering teams developing HRV-responsive audio modulation for Apple Watch and Oura Ring APIs.
France
Paris and Lyon startups demonstrate viable clinical psychology bundling models combining guided sessions with licensed therapy services. CNIL audits have elevated consumer trust in GDPR-compliant platforms, accelerating HR procurement of certified wellness subscriptions. The Île-de-France region absorbs significant venture deployment into emotion-recognition algorithm development subject to EU AI Act high-risk classification.
United Kingdom
NHS trusts actively evaluate meditation platforms for prescription digital therapeutic status through health technology assessment pathways. London procurement teams favor vendors with existing healthcare reimbursement traction when consolidating vendor relationships. English-language content saturation has compressed price points in British and Irish consumer markets.
Netherlands
Dutch university clusters concentrate scarce EEG-responsive audio engineering expertise for neurofeedback-informed session modulation. Health technology assessment bodies review clinical validation data for potential statutory insurance coverage expansion. Amsterdam and Eindhoven host wearable biofeedback integration development teams serving German corporate wellness tenders.
Poland
Minimal corporate meditation penetration persists despite EU-mandated workplace mental health obligations, creating first-mover terrain for localized platforms. Polish employers show rising demand for localized language audio program versions at price points below Western European corporate wellness budgets. Warsaw and Krakow emerging as Eastern European service delivery hubs for regional platform expansion.
Europe Meditation Market Competitive Landscape
Capital-heavy clinical-grade platforms compete with asset-light freemium content aggregators across diverging margin tiers. The vendor base separates into three strategic archetypes: NHS reimbursement pathway specialists, French-speaking market localization leaders, and aggressive price competitors in constrained Southern and Eastern European budgets. M&A activity concentrates on clinical validation data assets and wearable API integration capabilities. Geographic expansion into underpenetrated employer wellness markets represents the dominant competitive move.
Within the clinical credibility tier, Headspace anchors positioning through NHS partnership infrastructure, while Petit BamBou exemplifies French-speaking market dominance through localized content depth. Meditopia occupies the price-competitive position across Southern and Eastern European markets where employer wellness budgets remain constrained. These three entities represent distinct strategic vectors: healthcare reimbursement anchoring, linguistic-cultural localization, and geographic price arbitrage.
| Leading Market Players |
|---|
| 7Mind |
| FITCOMPANY |
| Headspace |
| B-Reel |
| NeuropilotVR |
| Meditopia |
| Mindgram |
| XRHealth |
| Petit BamBou |
| Others |
Supply & Pricing Matrix
Clinical-grade platform certification separates premium reimbursement-track providers from commoditized freemium apps, with this divergence manifesting in enterprise subscription pricing power and supply chain investments in GDPR-compliant biometric data infrastructure. German corporate wellness buyers now mandate HRV-responsive audio engineering as a procurement threshold, forcing supply chain concentration around Swiss and Dutch neurofeedback talent clusters while compressing margins for undifferentiated content libraries.
Pricing Analysis
Bundled clinical psychology services command enterprise premiums against unbundled freemium subscriptions. Three-tier pricing structure across premium, standard, and economy levels reflects certification depth, with NHS reimbursement traction and CNIL pre-certification driving price differentiation. Cost compression in the freemium tier intensifies because English-language content saturation has collapsed subscriber lifetime value in British and Irish markets. Healthcare Facilities demonstrate the least price sensitivity, while Individual consumers in Southern and Eastern Europe show acute responsiveness to subscription costs.
Supply Chain Analysis
Freight and cloud infrastructure costs for biometric data residency compliance strain mid-cap platform balance sheets. Engineering talent concentrates in Switzerland, the Netherlands, and Germany, while content production localizes in France and the United Kingdom. Raw material dependencies include EEG hardware components, cloud compute for emotion-recognition algorithms, and licensed clinical psychology labor. Single-source vulnerability sits with Apple Watch and Oura Ring API access terms. Distribution runs through direct enterprise sales teams serving HR departments and NHS procurement committees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where corporate wellness buyers are consolidating vendor relationships around platforms with demonstrated clinical validation and reimbursement traction.
For Market Incumbents: Deploy GDPR-compliant biometric data architectures as a defensive moat against freemium price erosion. Incumbents should deepen clinical psychology service bundling to anchor enterprise contract renewals and acquire wearable API integration capabilities to neutralize hardware-software bundle threats from emerging entrants. For New Entrants and Emerging Players: EEG-responsive audio modulation expertise offers a technology-first wedge into the supply-constrained neurofeedback segment. White-space targets include Polish and Romanian employer wellness markets with EU-mandated mental health obligations but minimal platform penetration. A direct B2B sales model targeting HR departments bypasses saturated app store channels. For Investors and Strategic Acquirers: Consolidation pressure builds where clinical validation data assets and wearable integration capabilities concentrate in fragmented mid-cap developers. Long-term viability favors platforms with statutory health insurance reimbursement pathways in Germany and the Netherlands. The signal to watch is Federal Institute for Drugs and Medical Devices prescription digital therapeutic category decisions.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Validation Investment | NHS health technology assessment submissions unlock prescription digital therapeutic revenue streams. |
| GDPR Compliance Architecture | CNIL pre-certification becomes mandatory market access in French-speaking regions. |
| Wearable API Integration | Apple Watch and Oura Ring biofeedback capabilities anchor German corporate wellness tenders. |
| Clinical Psychology Bundling | Paris and Lyon models demonstrate viable reimbursement pathway expansion into Belgium and the Netherlands. |
| Eastern European Localization | Polish and Romanian language content captures first-mover advantage in underpenetrated employer markets. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with corporate wellness procurement managers, digital health startup founders, clinical psychology service directors, and NHS trust technology assessment officers with secondary validation. Sources included EU Digital Services Act regulatory filings, CNIL audit reports, health technology assessment body evaluations, and corporate wellness contract disclosure databases. Bottom-up subscription revenue modeling and top-down sector expenditure estimates were triangulated for convergence.
Historical reference periods anchored the projection horizon to observed adoption curves across reimbursement pathway maturation and wearable hardware penetration cycles. Segmentation dimensions modeled include product type, delivery mode, end user category, and regional regulatory cluster. CAGRs were derived from fitted growth curves against enterprise license expansion and consumer subscription decay patterns. Forecast inputs incorporated EU AI Act implementation timelines and German statutory insurance coverage evaluation schedules.
The model holds under stable regulatory enforcement and reimbursement code expansion; deviation in GDPR interpretation stringency or AI Act conformity assessment delays would shift trajectory assumptions. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Dental Ceramics Market
Others
Bitcoin Mining Servers Market
Others
Traditional PC Market
Others
France Smart Home Market
Others
Australia Content Services Platform Market
Others
UAE Location-Based Services Market
Others
Mini Pcs Market
Others
Rotary Evaporators Market
Others
Aircraft Lighting Market
Others
Dry Washer Market
Others
Tripod Market
Others
Underwater Communication System Market
Others
Indoor LBS Market
Others
AI in Precision Medicine Market
Others
Durian Fruit Market
Others
Vacuum Evaporators Market