
 Basketball Apparel Market | 2026-2036
Basketball Apparel Market Size, Share, and Industry Trends Forecast 2026-2036
Basketball Apparel Market Analytics
Modular kit bundling is realigning how amateur leagues and school programs purchase basketball apparel. Nike leverages its vertical control over design and manufacturing to sustain premium positioning across team contracts. Adidas differentiates through specialized performance fabrics that anchor its technical credibility with elite athletes.
Basketball apparel encompasses engineered garments designed for the biomechanical demands of court sports, typically constructed from moisture-managing polyester blends with four-way stretch recovery and reinforced seam structures to withstand repetitive lateral movement and contact. Its commercial purpose centers on optimizing thermoregulation, mobility, and durability during high-intensity play. Jerseys and footwear command the largest revenue pools, while socks represent the fastest-expanding category as players prioritize compression and cushioning technologies. Polyester dominates material sourcing due to cost efficiency and print compatibility, though spandex blends are gaining share in fitted base-layer applications.
FIBA equipment standards, the U.S. Consumer Product Safety Commission (CPSC) flammability rules, and the EU REACH chemical restrictions collectively shape material compliance and market access requirements for basketball apparel sold across major economies. These frameworks elevate testing costs for new entrants while rewarding established suppliers with certified supply chains. Stakeholders must monitor how evolving sustainability mandates and performance certification thresholds reshape supplier qualification criteria and sourcing geography decisions.
Market Dynamics
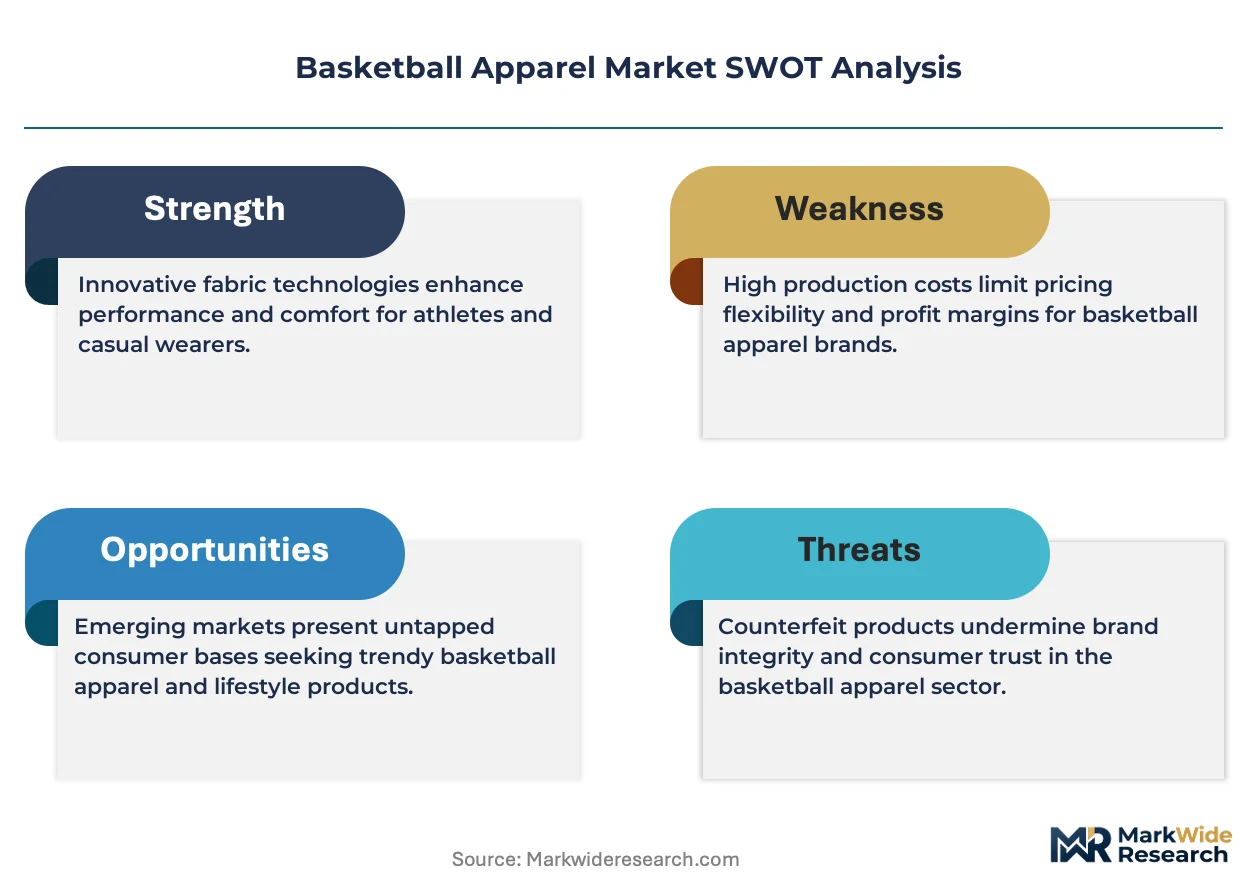
Moisture-wicking textile technologies and FIBA performance fabric standards are compressing supplier margins while elevating technical barriers for amateur league procurement. Youth league participation expansion in China and North America is redirecting manufacturing capacity toward mid-tier polyester-spandex blends.
Growth Catalysts
- REACH chemical restrictions:EU compliance requirements are filtering out low-cost Asian suppliers, creating certification premiums for European manufacturers with certified dyeing facilities.
- Four-way stretch recovery fabrics:Biomechanical engineering advances in base-layer construction are opening substitution opportunities against cotton alternatives in school athletic programs.
- China basketball infrastructure:Provincial court construction initiatives are accelerating domestic brand adoption and local manufacturing scale.
Market Restraints
- Polyester price volatility:Petrochemical feedstock fluctuations compress margin predictability for cut-and-sew contractors serving amateur leagues.
- Zhejiang province concentration:Dyeing and finishing capacity clustering in eastern China creates single-point vulnerability for moisture-management fabric supply.
- CPSC flammability testing:US certification timelines extend product launch cycles by 4-8 weeks for new market entrants.
Strategic Opportunities
- India school sports mandate:National physical education requirements are expanding addressable demand for budget jersey sets in secondary institutions.
- Direct-to-team digital platforms:Customization tools are bypassing traditional sporting goods distributors for amateur league bulk orders.
- Spandex blend convergence:Compression sock technology migration into basketball-specific calf sleeves opens adjacent category expansion.
Industry Challenges
- OEKO-TEX certification backlog:Testing laboratory capacity constraints delay sustainable product line launches for mid-tier suppliers.
- Legacy ERP integration:Made-to-order customization platforms require expensive SAP module reconfiguration for established manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Basketball Apparel Market |
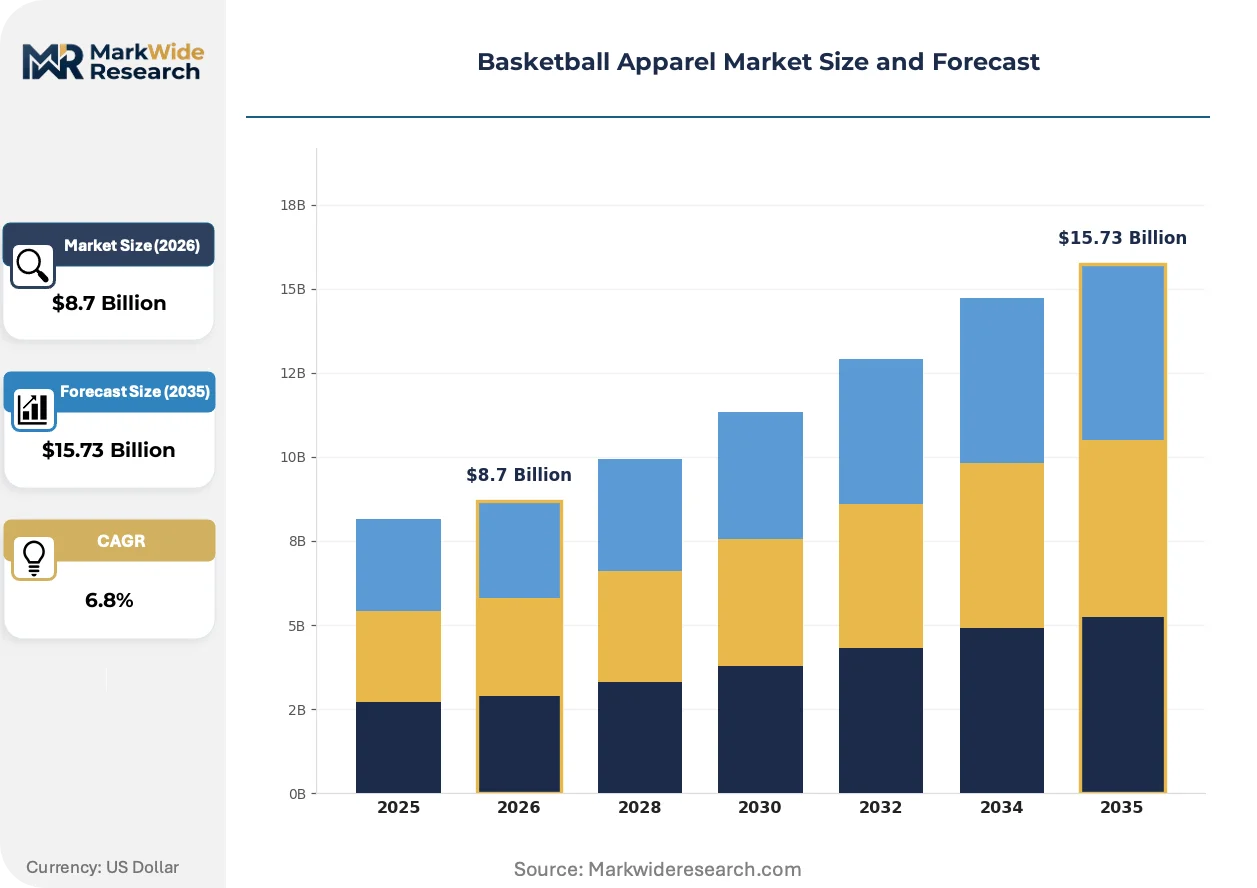
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Jerseys, Shorts, Socks, Footwear Material: Polyester, Cotton, Nylon, Spandex End User: Men, Women, Kids, Teams Distribution Channel: Online, Specialty Stores, Department Stores, Sports Retailers |
| Companies Covered | PUMA, Li-Ning, Nike, ASICS, ANTA, Adidas, New Balance, Point 3 Basketball, Under Armour, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Basketball Apparel Market Evolving Landscape
Digital customization platforms and bioceramic-infused fabrics are restructuring how amateur leagues source team kits. Regulatory chemical restrictions and biomechanical engineering advances are simultaneously elevating technical specifications and supplier qualification costs.
Bioceramic particle infusion in polyester base layers is consolidating thermoregulation performance across price tiers. Youth leagues in Texas and California are adopting these fabrics at 18-month replacement cycles versus traditional 24-month cotton rotations. The technology is consolidating supplier differentiation around mineral additive sourcing rather than weave construction alone.
EU REACH Annex XVII restrictions on azo dyes are forcing reformulation of sublimation printing inks used in jersey production. German and French textile finishers are absorbing 12-15% cost increases for compliant pigment alternatives. Elite team suppliers are responding by consolidating print operations in Portugal and Turkey to maintain EU market access.
Team managers are consolidating seasonal purchases through league-level procurement cooperatives rather than individual school transactions. This aggregation is displacing independent sporting goods retailers in the Midwest and Southeast United States. The consolidation is most visible in Ohio and Georgia, where regional league associations now contract directly with cut-and-sew manufacturers for standardized kit bundles.
Basketball Apparel Market Segmentation
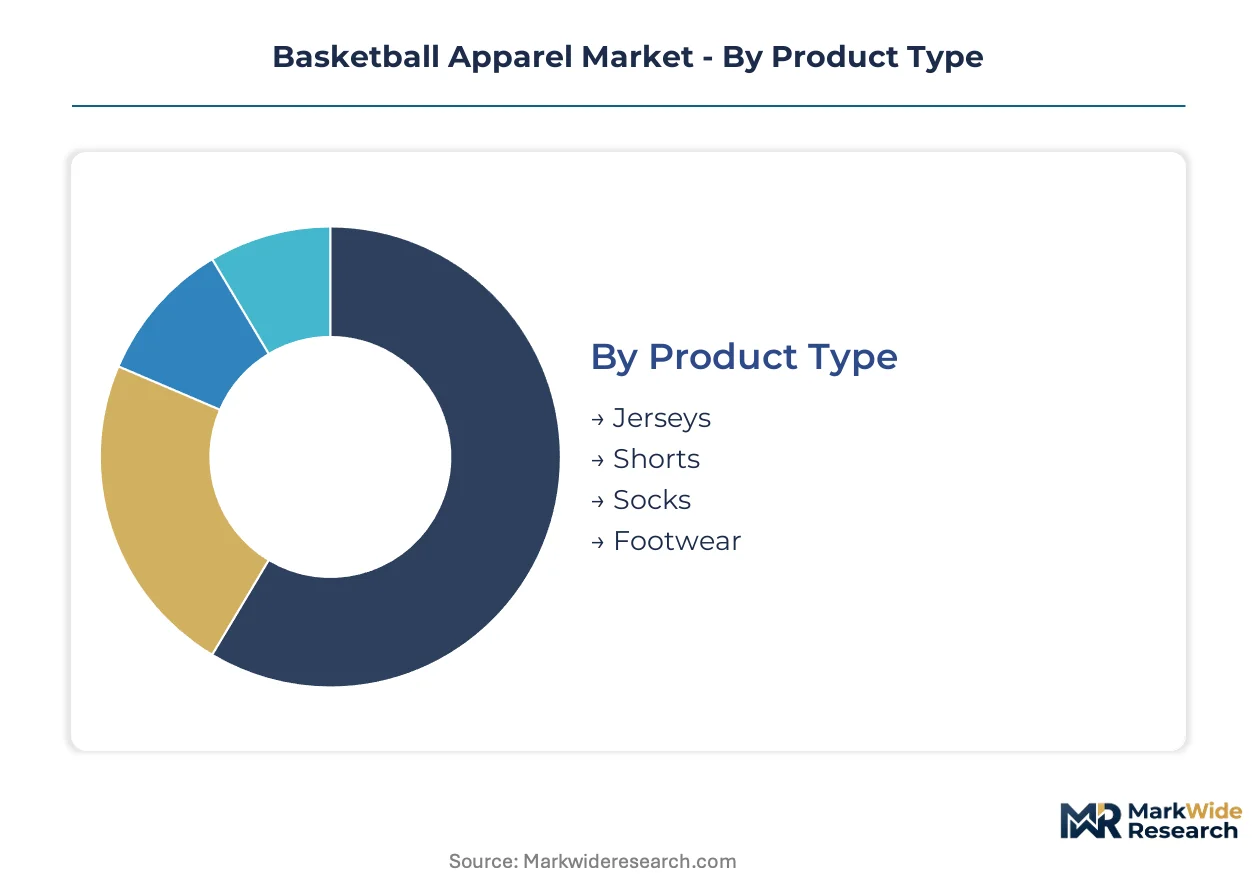
Basketball apparel segmentation reveals how product architecture, material science, and channel economics fragment procurement patterns across amateur leagues, school programs, and elite competition tiers. Understanding these divisions exposes where technical specifications drive premium pricing versus where standardization enables volume scaling.
Product Type:
Standalone garments dominate recreational procurement, while integrated kit systems capture institutional contracts requiring uniform standardization across roster sizes.
- Jerseys:Engineered from moisture-managing polyester with sublimation-ready surfaces for number and logo durability. Demand concentrates in Texas and Ohio school districts where league-level procurement cooperatives now bypass traditional retailers for direct manufacturer contracts.
- Footwear:Biomechanically constructed with lateral stability plates and energy-return midsoles designed for hardwood court impact. China provincial basketball infrastructure investments are accelerating domestic brand adoption for mid-tier performance tiers.
- Shorts:Four-way stretch construction with reinforced side seams for contact durability during defensive slides.
- Socks:Compression-grade calf sleeves with graduated pressure zones migrating from running technology into basketball-specific applications.
Volume placements concentrate in Jerseys; the faster expansion belongs to Socks.
Material:
Cost tiers separate commodity synthetics from performance-engineered blends, with certification requirements filtering supplier participation at each level.
- Polyester:Dominates sourcing through cost efficiency and print compatibility for sublimation graphics. REACH chemical restrictions are filtering out low-cost Asian dyeing facilities, creating certification premiums for European finishers with compliant pigment operations.
- Spandex:Delivers four-way stretch recovery in fitted base-layer applications where biomechanical engineering advances open substitution opportunities against cotton alternatives.
- Cotton:Retains presence in practice-wear segments where breathability outweighs moisture-management priorities.
- Nylon:Provides abrasion resistance in high-contact zones of reinforced shorts and outer layers.
Polyester commands the largest procurement volumes; Spandex blends are gaining share fastest in compression applications.
End User:
Customer type determines specification intensity, with team procurement aggregating individual demand into standardized contract structures.
- Teams:League-level purchasing cooperatives in the Midwest and Southeast United States now contract directly with cut-and-sew manufacturers for standardized kit bundles, displacing independent sporting goods retailers.
- Kids:Youth league participation expansion in China and North America redirects manufacturing capacity toward mid-tier polyester-spandex blends with accelerated replacement cycles.
- Men:Individual recreational players purchasing through direct-to-team digital platforms with customization tools.
- Women:Fastest-growing participant segment driving demand for fitted cuts and specialized size grading.
Team contracts generate the highest revenue per transaction; Kids segments are climbing the fastest through league mandate expansion.
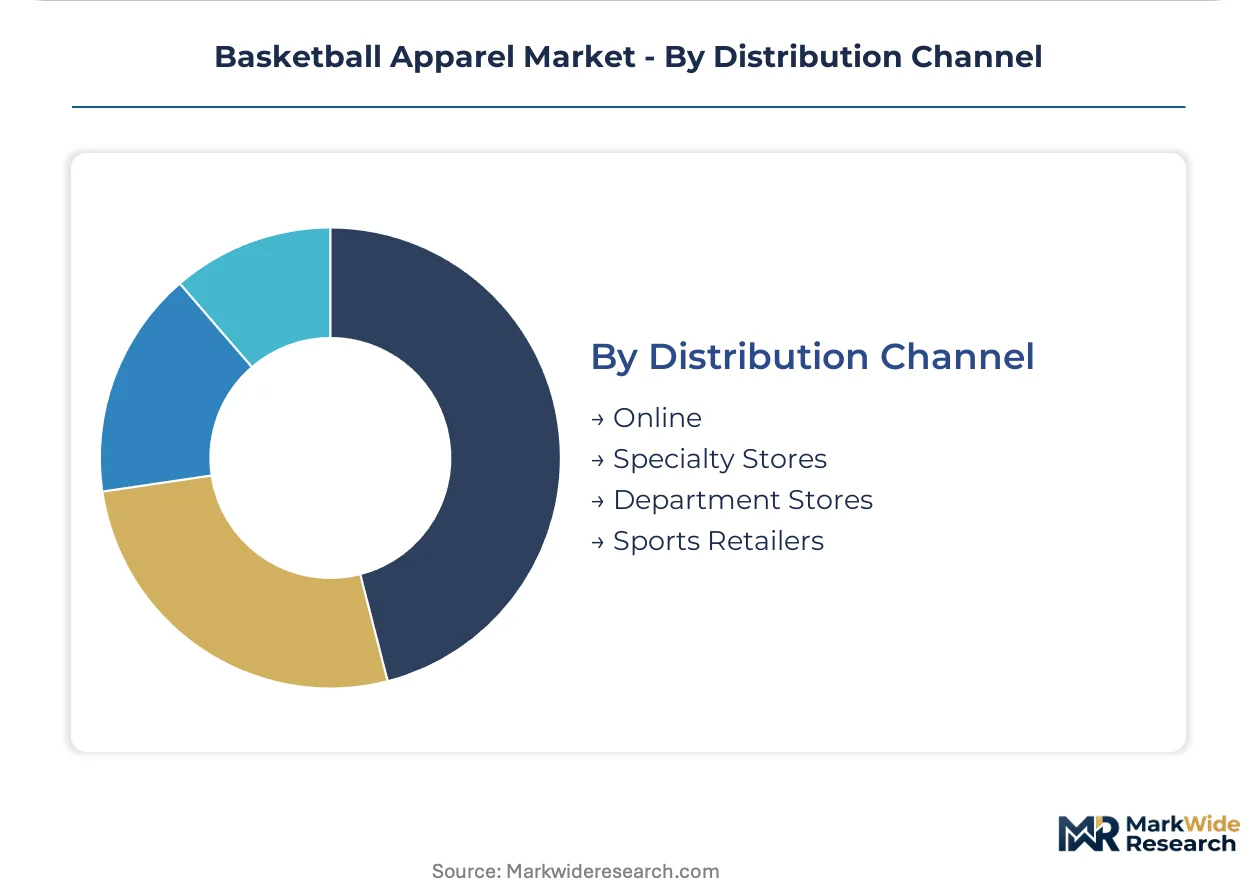
Distribution Channel:
Channel selection reflects order scale and customization requirements, with digital platforms eroding traditional retail intermediation in bulk procurement.
- Online:Direct-to-team digital platforms with customization tools bypass traditional sporting goods distributors for amateur league bulk orders, consolidating seasonal purchases through league-level procurement cooperatives.
- Sports Retailers:Specialty basketball-focused retailers retain relevance in elite athlete fitting and immediate replacement needs.
- Specialty Stores:Local independent operators losing share to aggregated league contracts in Ohio and Georgia regional associations.
- Department Stores:Mass-market presence for entry-level recreational purchasers with limited technical specification requirements.
Sports Retailers retain the highest margin per unit; Online channels are expanding most quickly through procurement aggregation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing concentrates in eastern China's textile belt while consumption spreads across North American school districts and Chinese provincial leagues. This geographic split shapes inventory positioning and compliance investments differently across supplier bases.
United States
Texas and Ohio school districts now aggregate procurement through league-level cooperatives, bypassing traditional sporting goods retailers. The CPSC flammability testing requirements extend product launch cycles by 4-8 weeks for new market entrants. Cut-and-sew contractors in the Southeast and Midwest face margin compression from polyester price volatility tied to petrochemical feedstock fluctuations.
China
Provincial basketball infrastructure investments accelerate domestic brand adoption and local manufacturing scale. The MIIT oversees GB standards compliance for textile finishing operations in Zhejiang province dyeing clusters. Zhejiang's concentration of moisture-management fabric capacity creates single-point vulnerability for global supply.
Germany
REACH Annex XVII azo dye restrictions force reformulation of sublimation printing inks, absorbing 12-15% cost increases for compliant pigment alternatives. The ECHA chemical framework filters out low-cost Asian suppliers lacking certified dyeing facilities. Textile finishers in Portugal and Turkey now serve as consolidated print operations for EU market access.
India
National physical education mandates expand addressable demand for budget jersey sets in secondary institutions. The BIS certification requirements for textile imports create compliance premiums for domestic manufacturers with certified facilities. Maharashtra and Gujarat industrial corridors attract cut-and-sew capacity serving school sports procurement.
Japan
Elite athlete fitting requirements sustain specialty retailer relevance against digital platform encroachment. The METI oversees JIS standards for performance fabric specifications in competitive applications. Osaka-based textile engineers develop four-way stretch recovery blends for base-layer substitution against cotton alternatives.
Basketball Apparel Market Competitive Landscape
The competitive structure tilts toward brand-led vertical control over design and manufacturing. Nike and Adidas anchor premium positioning through team contract consolidation, while domestic Chinese brands capture mid-tier volume from provincial infrastructure investments. Three archetypes dominate: vertically integrated sportswear giants, regional specialists with certified supply chains, and direct-to-team digital platforms. M&A activity concentrates on customization technology assets; capacity expansion targets polyester-spandex blend manufacturing in Zhejiang and Vietnam.
Among the vertically integrated tier, Nike and Adidas occupy positions defined by technical credibility and league contract scale. Li-Ning exemplifies the domestic Chinese archetype leveraging provincial basketball infrastructure for manufacturing scale and local brand equity. Point 3 Basketball represents the specialist segment focused on basketball-specific product architecture rather than multi-sport diversification.
| Leading Market Players |
|---|
| PUMA |
| Li-Ning |
| Nike |
| ASICS |
| ANTA |
| Adidas |
| New Balance |
| Point 3 Basketball |
| Under Armour |
| Others |
Value Network & Pricing Analysis
Petrochemical feedstock benchmarks cascade through polyester-spandex blend manufacturing, compressing margin predictability for cut-and-sew contractors while amplifying pricing power for vertically integrated suppliers with captive polymer sourcing.
Pricing Analysis
Margin tightening in mid-tier amateur league procurement reflects polyester price volatility tied to crude oil derivatives. Three-tier pricing structure across premium, standard, and economy levels separates FIBA-certified performance kits from school athletic program bundles and recreational practice wear. Certification premiums for REACH-compliant dyeing facilities widen spreads between European finishers and unqualified Asian competitors. Youth league cooperatives in Ohio and Texas exhibit highest price sensitivity; elite team contracts anchored by Nike and Adidas show lowest elasticity.
Supply Chain Analysis
Certification gating through OEKO-TEX and REACH Annex XVII restrictions filters supplier participation at each cost tier. Manufacturing gravity centers on China's Zhejiang province for dyeing and finishing, Vietnam for cut-and-sew assembly, and Portugal for EU-compliant print operations. Raw material dependencies span petrochemical-derived polyester, elastane fiber for stretch recovery, and bioceramic mineral additives for thermoregulation. Single-source vulnerability concentrates in Zhejiang's moisture-management fabric capacity. Distribution runs through direct-to-team digital platforms for bulk orders and specialty basketball retailers for elite fitting services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU REACH chemical restrictions construct a formidable compliance moat, elevating qualification costs for new entrants while rewarding established suppliers with certified European dyeing partnerships.
For Market Incumbents: Anticipate consolidation pressure from domestic Chinese brands leveraging provincial basketball infrastructure investments. Defend position by deepening backward integration into polyester-spandex blend manufacturing in Vietnam and securing OEKO-TEX certification ahead of backlog constraints. Prioritize SAP module reconfiguration for made-to-order customization platforms to capture league-level procurement cooperative demand.
For New Entrants and Emerging Players: Enter via India's national physical education mandate expansion for budget jersey sets in secondary institutions. Target Maharashtra and Gujarat industrial corridors for cut-and-sew capacity placement. Pursue direct-to-team digital platform partnerships with customization tools to bypass traditional sporting goods distributor intermediation.
For Investors and Strategic Acquirers: Distressed-cycle entries favor regional specialists with certified supply chains in Portugal and Turkey amid REACH-driven print operation consolidation. Long-term viability hinges on mineral additive sourcing relationships for bioceramic fabric differentiation. Watch for CPSC flammability testing timeline extensions as inflection indicator for new entrant capacity constraints.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Sourcing | Captive polyester supply insulates margin predictability from petrochemical feedstock volatility. |
| REACH-Compliant Dyeing Facility Investment | Certified European finishing operations command premium positioning in EU market access. |
| Direct-to-Team Digital Platform Launch | Customization tools aggregate league-level procurement cooperatives away from traditional retailers. |
| Bioceramic Fabric Technology Licensing | Mineral additive sourcing relationships differentiate thermoregulation performance across price tiers. |
| India Manufacturing Footprint Expansion | Maharashtra and Gujarat corridors capture budget jersey demand from national physical education mandates. |
Research Methodology
Independent corroboration across apparel procurement directors, textile finishing plant managers, league association administrators, and sporting goods retail buyers underwrites the qualitative findings. Primary fieldwork combined structured interviews with secondary validation through customs trade data, FIBA equipment standard filings, SEC 10-K apparel segment disclosures, and OEKO-TEX certification registry records. Bottom-up demand modeling across youth league participation rates and top-down supply assessment through Zhejiang province capacity estimates enabled triangulation.
Comparable-period anchoring to historical replacement cycle data for cotton versus bioceramic base layers structured the projection horizon. Segmentation dimensions modeled include product architecture, material grade tier, end-user procurement structure, and regional regulatory cluster. CAGRs derived from volume-weighted average of segment growth rates across the analysis window. Industry-specific inputs incorporated school sports mandate expansion timelines and provincial basketball infrastructure investment trajectories.
Forecast precision tightens around the base case; tail outcomes carry wider variance under polyester price volatility spikes and REACH enforcement escalation scenarios. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
AI In Government And Public Services Market
Others
Super Computer Market
Others
Germany Smart Home Market
Others
Storage Dewar and Dry Shipper Market
Others
Global Car Wax Market
Others
Sprockets Market
Others
Europe Military 4D Printing Market
Others
Smart TV Platforms Market
Others
Pollen Allergy Market
Others
Asia Pacific Contract Packaging Market
Others
North America Halal Food and Beverage Market
Others
Printed Leather Market
Others
Managed Video As a Service Market
Others
United States Printed Signage Market
Others
Underwater Light Market
Others
8K Technology Market