
 United States Printed Signage Market | 2026-2036
United States Printed Signage Market Size, Share, and Industry Trends Forecast 2026-2036
United States Printed Signage Market Analytics
Market Context
The dealer-direct channel is fragmenting as national sign networks, e-commerce platforms, and independent fabricators compete for the same commercial accounts. Avery Dennison Corporation leverages its materials science portfolio to supply premium substrates and adhesives across multiple signage formats. Fastsigns International Inc. anchors its position through a franchise model that standardizes production quality while allowing local market adaptation. Cimpress plc competes via centralized digital manufacturing platforms that compress turnaround times for customized orders.
Technical and Segment Structure
Printed signage encompasses graphic displays produced through mechanical reproduction processes on rigid or flexible substrates, typically employing UV-curable, solvent, or latex ink systems at resolutions between 300 and 1440 dpi for outdoor durability and color fidelity. The primary commercial purpose spans brand communication, wayfinding, regulatory compliance, and promotional activation in physical environments. Banners and displays lead volume within product type segments, though fabric-based solutions are gaining traction in hospitality and corporate interiors where acoustic and aesthetic performance matter. Vinyl dominates material demand for exterior applications, while metal substrates command premium positioning in architectural and long-term wayfinding installations.
Regulatory Environment and Outlook
OSHA workplace safety standards govern installation protocols for elevated and construction-adjacent signage, while the EPA regulates volatile organic compound emissions from solvent-based printing operations through National Emission Standards for Hazardous Air Pollutants. State-level building codes in California and New York impose additional structural load and wind-resistance requirements on exterior displays. Stakeholders must monitor evolving state energy codes that increasingly restrict illuminated sign wattage and mandate LED retrofits, as these rules will reshape capital allocation between printed and digital display formats.
Market Dynamics
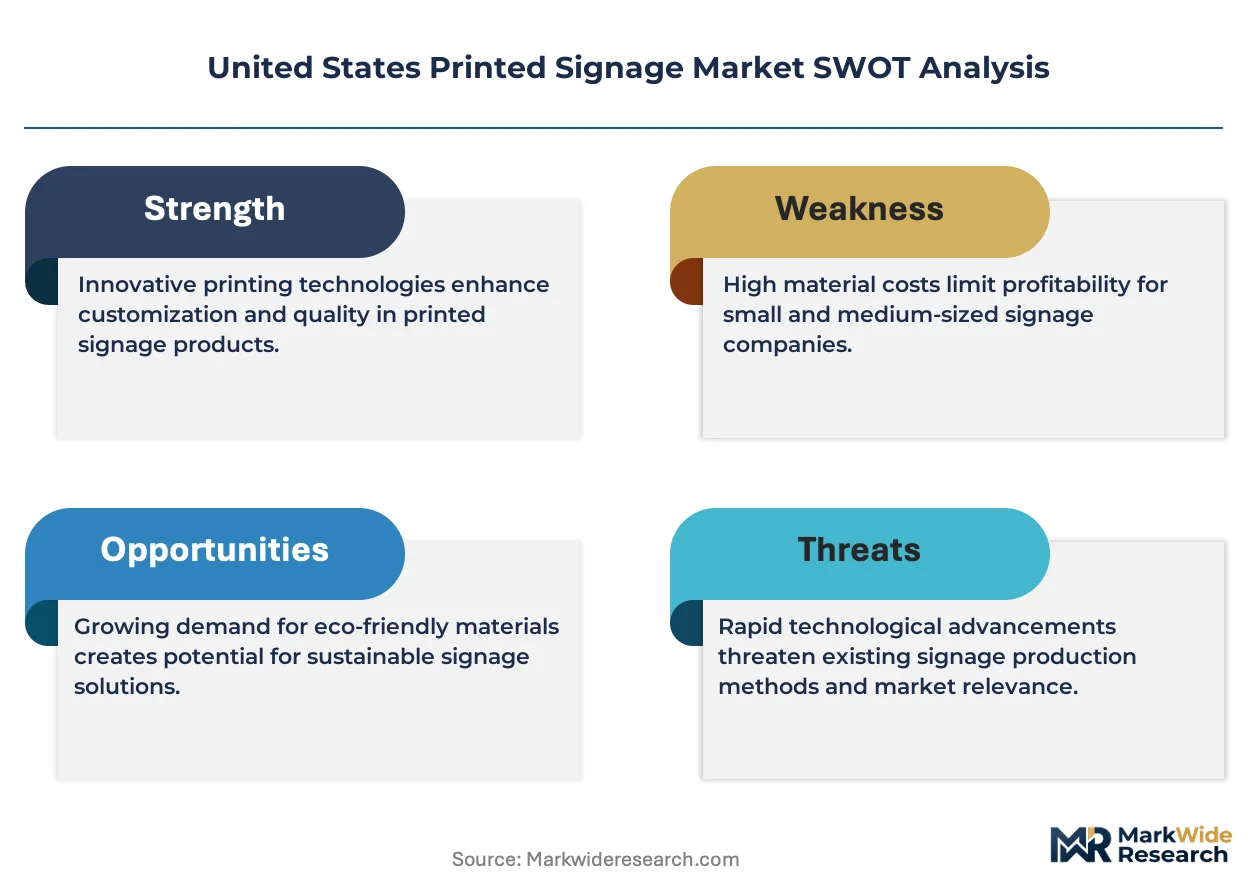
EPA enforcement of National Emission Standards for Hazardous Air Pollutants is forcing converters to abandon solvent-based ink systems. This regulatory pressure is compressing margins for smaller fabricators while advantaging capitalized operators with UV-curing and water-based infrastructure already deployed.
Growth Catalysts
- Franchise retail expansion:National chains are standardizing in-store promotional signage programs across Texas, Florida, and California, creating recurring volume for regional fabricators with multi-location service capability.
- LED retrofit mandates:State energy codes in California and New York are restricting illuminated sign wattage, accelerating replacement cycles that bundle printed substrates with new LED modules.
- UV-curable ink maturation:Advances in low-energy UV curing are reducing power consumption and enabling faster throughput on rigid substrates, improving unit economics for short-run custom work.
Market Restraints
- Petrochemical substrate volatility:Vinyl film pricing fluctuates with ethylene supply chain disruptions, compressing gross margins for banner and display producers without forward contracting.
- Concentrated adhesive supply:Pressure-sensitive adhesive formulations for exterior signage rely on a narrow base of specialty chemical suppliers, creating vulnerability to force majeure events.
- Digital display substitution:LED screen technology is capturing share in high-traffic urban corridors where content refresh requirements exceed printed signage economics.
Strategic Opportunities
- Acoustic fabric signage:Hospitality and corporate interior designers are specifying tension fabric systems with sound-absorbing properties, opening premium positioning beyond traditional vinyl.
- Water-based ink conversion:EPA VOC compliance timelines are creating first-mover advantage for converters investing in aqueous inkjet systems ahead of enforcement deadlines.
- Dealer-direct channel fragmentation:E-commerce platforms and independent fabricators are disintermediating traditional sign networks, enabling niche specialists to capture direct commercial relationships.
Industry Challenges
- Color management expertise scarcity:ICC profiling and substrate-specific ink linearization require specialized prepress talent that smaller shops struggle to recruit and retain.
- OSHA elevated work certification:Installation crews performing high-rise exterior mounting must maintain current fall-protection training, adding administrative overhead and liability exposure.
- Legacy RIP software integration:Print shops with embedded EFI or Onyx workflows face friction migrating to cloud-based job management platforms that coordinate distributed production.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Printed Signage Market |
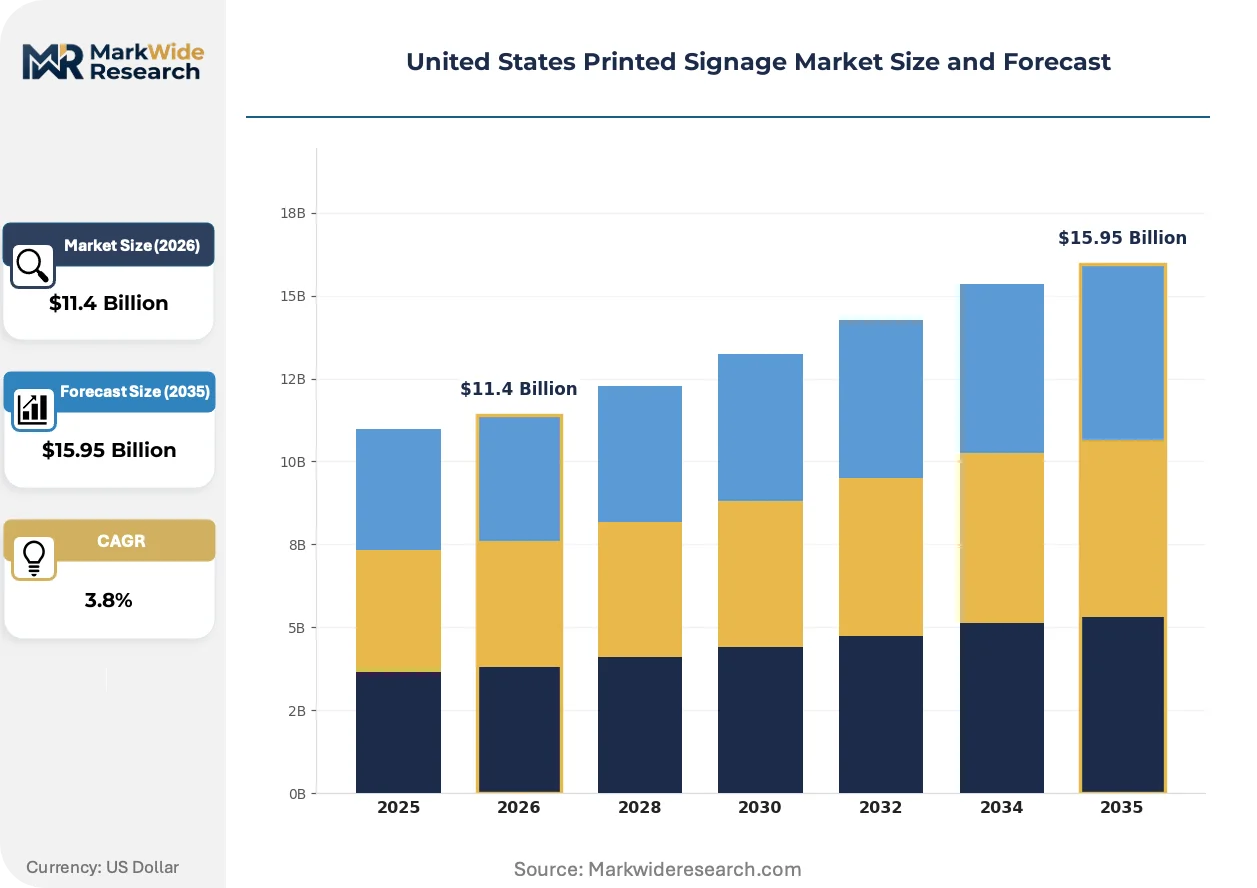
| Market Size in 2026 | $11.4 Billion |
| Market Size in 2035 | $15.95 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Banners, Posters, Billboards, Displays Material: Vinyl, Paper, Metal, Fabric End User: Retail, Hospitality, Education, Entertainment Printing Technology: Digital, Flexography, Offset, Screen |
| Companies Covered | 3A Composites USA Inc., Chandler Signs Holdings Inc., Avery Dennison Corporation, Image360, Signarama, Fastsigns International Inc., Kelly Signs Inc., Sabre Digital Creative Inc., Cimpress plc, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Printed Signage Market Evolving Landscape
Digital production workflows are compressing job turnaround from days to hours, reshaping competitive dynamics between centralized manufacturing platforms and local fabricators. Three developments are accelerating this structural shift.
Wide-format inkjet technology is digitizing prepress and platemaking steps that previously required days of setup. Quick-service restaurant chains and event marketing agencies are adopting same-day proofing cycles, collapsing the traditional bid-specify-produce timeline. This compression is enabling fabricators to capture rush-premium pricing while reducing inventory carrying costs.
EPA enforcement of NESHAP standards for printing operations is mandating emissions capture systems or solvent elimination. Converters in California and New York are retrofitting facilities with regenerative thermal oxidizers or migrating to latex and UV-curable alternatives. The regulatory burden falls heaviest on small-to-mid-size operations lacking capital reserves for compliance infrastructure.
Buyers are consolidating vendor relationships around full-service providers capable of design, production, and installation coordination. Property management firms and retail franchise operators are reducing supplier counts from dozens to handfuls, favoring networks with national coverage and standardized quality systems. This concentration is visible most acutely in Sun Belt metropolitan markets where commercial construction velocity supports volume commitments.
United States Printed Signage Market Segmentation
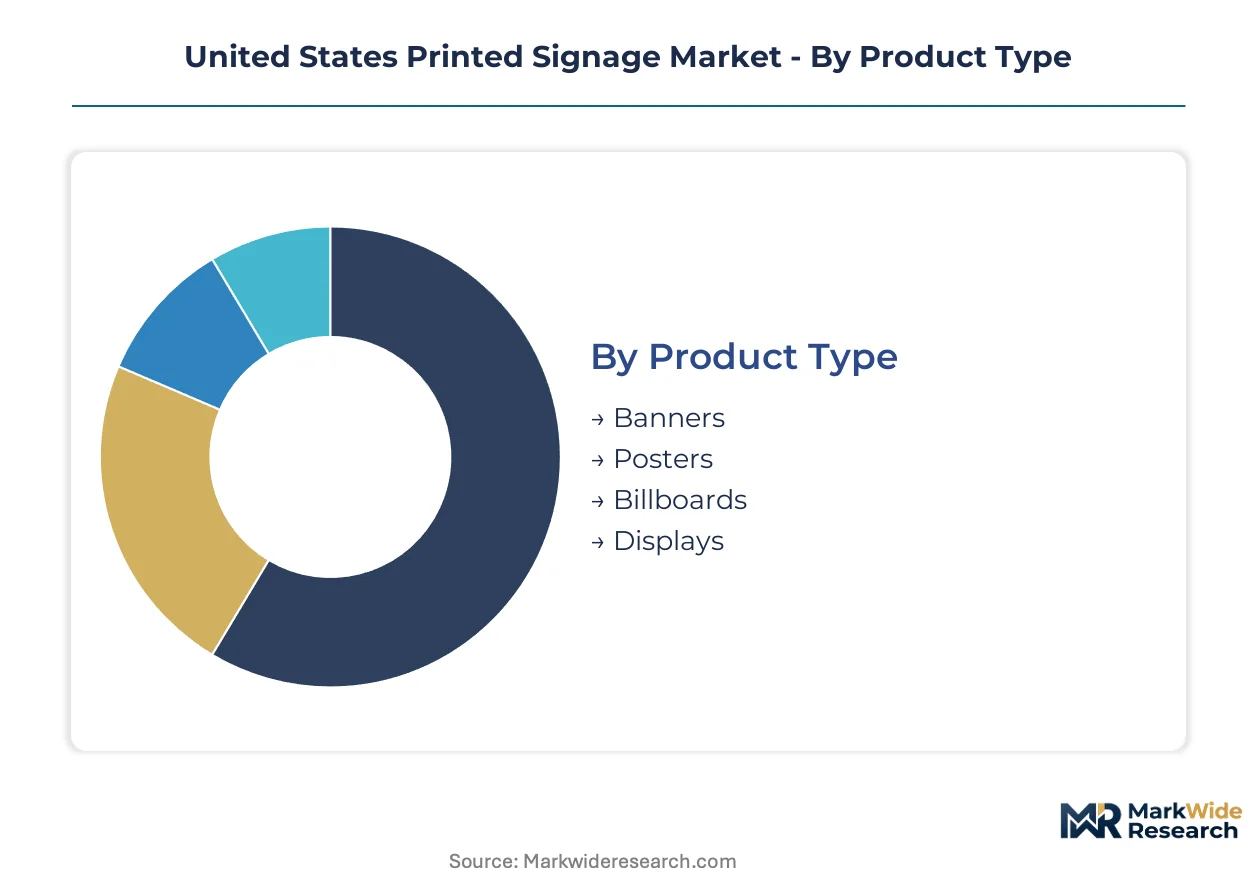
Segmentation in the United States printed signage market reveals distinct procurement patterns across substrate durability requirements, installation environments, and brand refresh cycles. Understanding these divisions enables fabricators to align production capacity with the divergent technical specifications and service expectations of each buyer category.
Product Type:
Application context determines format selection, with exterior durability demands and interior aesthetic priorities driving fundamentally different specification paths.
- Banners:Flexible vinyl or fabric substrates reinforced with welded hems and grommets enable temporary outdoor deployment for event marketing and construction site branding. Demand concentrates in Texas and Florida where festival circuits and commercial development velocity sustain high replacement frequency.
- Displays:Rigid substrate systems including pop-up frames, tension fabric structures, and modular exhibition hardware serve trade show and retail activation programs. Corporate interior designers in California are specifying acoustic fabric variants for hospitality lobbies and co-working spaces.
- Posters:Paper-based graphics with aqueous or latex ink systems dominate indoor promotional applications with shorter display lifecycles.
- Billboards:Large-format vinyl faces printed at 10-30 dpi effective resolution prioritize weather resistance over fine detail for highway-adjacent visibility.
Banners hold installed capacity. Displays are rotating up the share rankings.
Material:
Substrate economics trace directly to petrochemical feedstock exposure and installation longevity requirements.
- Vinyl:PVC films with UV-stabilized face stocks and permanent or removable adhesive backings dominate exterior applications requiring 3-5 year durability. Price volatility in ethylene supply chains compresses margins for banner producers without forward contracting capability.
- Fabric:Polyester and cotton-poly blends with dye-sublimation or direct-disperse printing enable lightweight shipping and acoustic performance in interior environments. Hospitality designers in California and New York are specifying tension fabric systems for lobby installations.
- Metal:Aluminum composite panels and routed aluminum substrates command premium positioning for architectural wayfinding and long-term corporate identification.
- Paper:Coated and uncoated stocks with aqueous ink compatibility serve short-term promotional applications where substrate cost minimization outweighs durability concerns.
Vinyl holds installed capacity. Fabric is rotating up the share rankings.
End User:
Customer procurement sophistication varies sharply, with national retail chains demanding vendor consolidation while independent hospitality operators prioritize design flexibility.
- Retail:Franchise networks standardize in-store promotional programs across multi-location footprints, creating recurring volume for fabricators with national service capability. Texas, Florida, and California anchor concentration where chain expansion velocity remains highest.
- Hospitality:Hotel and restaurant operators specify branded environmental graphics with accelerated refresh cycles tied to property renovation schedules.
- Entertainment:Venue operators and event marketing agencies require rush production capability with same-day turnaround for tour launches and seasonal programming.
- Education:K-12 districts and university systems procure wayfinding and safety compliance signage through cooperative purchasing agreements with extended bid cycles.
Retail holds installed capacity. Hospitality is rotating up the share rankings.
Printing Technology:
Capital equipment decisions lock fabricators into distinct operating cost structures and substrate versatility profiles.
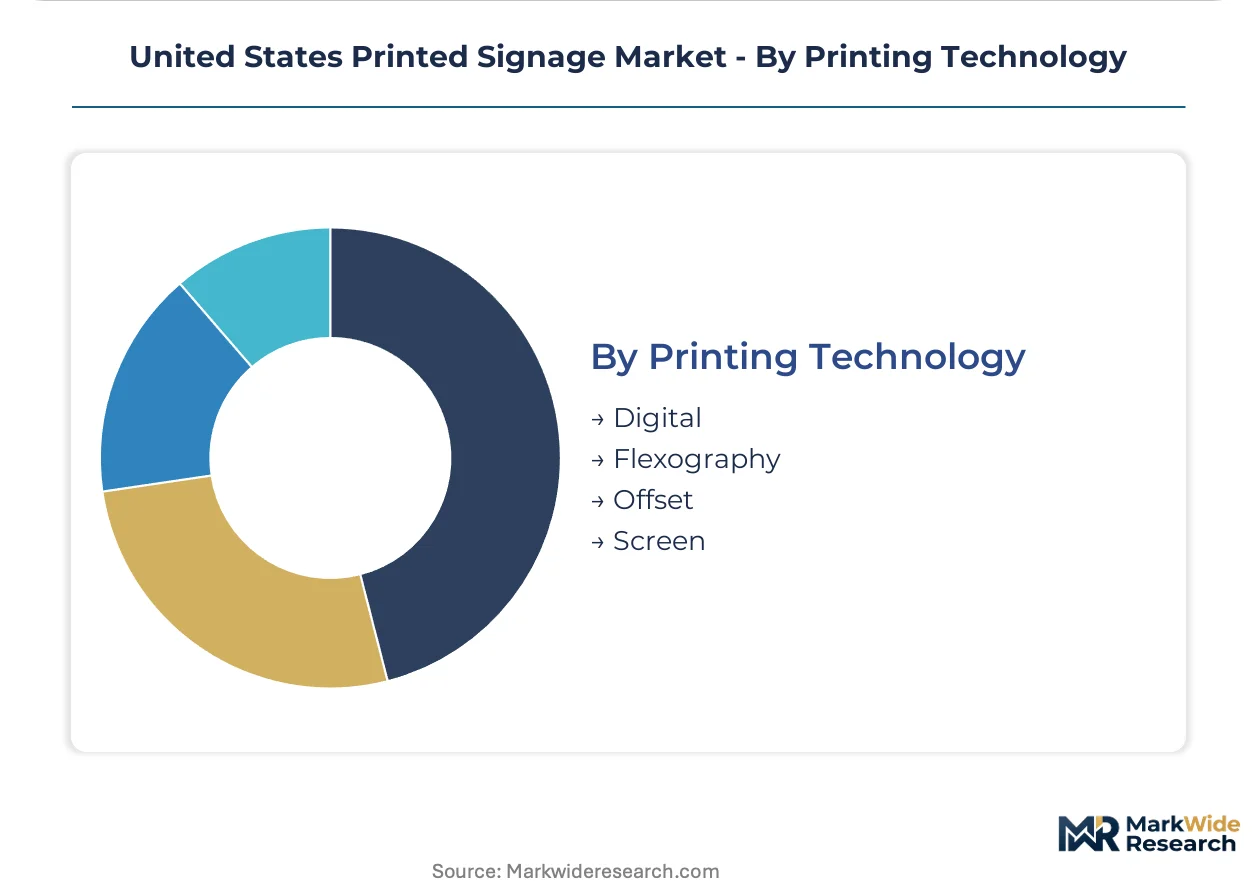
- Digital:Wide-format inkjet systems employing UV-curable, solvent, or latex ink sets enable variable-data printing and short-run economics without platemaking overhead. EPA NESHAP enforcement is accelerating migration from solvent-based configurations to UV and aqueous alternatives.
- Screen:Stencil-based printing with thick-film ink deposits delivers opacity and durability for exterior applications with long production runs.
- Flexography:Rotary letterpress analogs with photopolymer plates serve high-volume label and packaging-adjacent signage with substrate flexibility.
- Offset:Lithographic transfer systems dominate paper-based poster production where color consistency across long runs justifies platemaking investment.
Digital holds installed capacity. Screen is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Texas commands pricing premiums for rush-turnaround banner production that Florida fabricators struggle to match, while California's regulatory compliance costs create margin asymmetries across the Sun Belt corridor.
Texas
Festival circuits and commercial construction velocity sustain high replacement frequency for temporary outdoor signage. The Texas Commission on Environmental Quality enforces state-level VOC regulations that parallel federal EPA standards. Dallas-Fort Worth anchors the state's largest concentration of regional fabricators serving multi-location retail chains.
California
Hospitality interior designers specify acoustic fabric systems for lobby installations and co-working spaces. The California Energy Commission mandates LED retrofit requirements that accelerate replacement cycles for illuminated displays. Los Angeles and San Diego metropolitan areas concentrate premium substrate converters with aqueous inkjet capabilities.
Florida
Event marketing agencies demand same-day proofing cycles for seasonal programming and tourism activation. The Florida Department of Environmental Protection administers air quality permits for printing operations with solvent-based configurations. Miami and Orlando host the state's densest clusters of banner producers serving entertainment venue operators.
New York
Corporate headquarters and financial services drive architectural wayfinding specifications with premium durability requirements. The New York State Department of Environmental Conservation enforces structural load and wind-resistance standards for exterior displays. New York City commands the Northeast's highest concentration of metal substrate specialists serving long-term corporate identification programs.
Illinois
Manufacturing and logistics facilities procure safety compliance signage through cooperative purchasing agreements with extended bid cycles. The Illinois Environmental Protection Agency coordinates with OSHA on elevated work certification requirements for installation crews. Chicago anchors the Midwest's largest network of screen printing operations serving industrial end users.
United States Printed Signage Market Competitive Landscape
Materials-science conglomerates and franchise-network operators split the market along the capital-intensity spectrum. The vendor base concentrates around three strategic archetypes: substrate suppliers with adhesive formulation capabilities, distributed service networks with standardized quality systems, and centralized digital manufacturing platforms with compressed turnaround economics. Dominant competitive moves include portfolio diversification into adjacent display formats and geographic expansion through acquisition of regional fabricators.
Among materials-science specialists, Avery Dennison Corporation anchors premium substrate supply across multiple signage formats. Fastsigns International Inc. exemplifies the franchise-network archetype with standardized production quality and local market adaptation. Cimpress plc occupies a position within centralized digital manufacturing, compressing turnaround times for customized orders through platform-based coordination.
| Leading Market Players |
|---|
| 3A Composites USA Inc. |
| Chandler Signs Holdings Inc. |
| Avery Dennison Corporation |
| Image360 |
| Signarama |
| Fastsigns International Inc. |
| Kelly Signs Inc. |
| Sabre Digital Creative Inc. |
| Cimpress plc |
| Others |
Value Network & Pricing Analysis
I-35 corridor freight costs from Dallas-Fort Worth to Houston distribution hubs compress margins for regional banner producers while amplifying price differentiation between rush-turnaround specialists and standard-delivery competitors. This logistics geography concentrates supply-side power among fabricators with captive trucking fleets or rail-served facilities, enabling tiered pricing power that smaller operators cannot match.
Pricing Analysis
The customization-premium spread separates configured-to-order project pricing from standard banner catalog pricing by roughly 40-60 percent. Three-tier pricing structure across premium, standard, and economy levels tracks substrate durability grade and installation service bundling. Pricing pressure stems from vinyl resin cost volatility tied to ethylene supply disruptions, compressing gross margins for non-integrated producers. Franchise retail chains exhibit lowest price sensitivity due to brand consistency requirements, while independent event marketers drive hardest bargain on per-unit basis.
Supply Chain Analysis
Contract-manufacturing concentration sits with regional fabricators in Texas, Florida, and California that operate multi-location production networks. Raw material dependencies center on PVC resin from Gulf Coast petrochemical complexes, pressure-sensitive adhesive formulations from specialty chemical suppliers, and aluminum composite panels from domestic rolling mills. Single-source vulnerability in adhesive supply chains creates force majeure exposure for exterior signage producers. Distribution runs through dealer-direct channels, e-commerce platforms, and franchise networks serving commercial end users with varying service level requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a defensive-moat story anchored in regulatory entrenchment. EPA NESHAP compliance timelines and state-level VOC enforcement create switching costs that lock customers into qualified supplier relationships.
For Market Incumbents: Harden market position by deepening aqueous inkjet capabilities ahead of enforcement deadlines in California and New York. Acquire regional fabricators in Texas and Florida to capture franchise retail expansion volume and consolidate multi-location service capability against digital display substitution threat. For New Entrants and Emerging Players: Interior hospitality markets in secondary California metros and Austin-Dallas corridor present underpenetrated white space for acoustic fabric signage specialists. Target co-working space designers and boutique hotel operators with design-forward tension fabric systems. Go-to-market angle should emphasize same-day digital proofing capability to differentiate from legacy screen printing operations. For Investors and Strategic Acquirers: Mid-size converters with EPA-compliant UV-curing infrastructure and established OSHA-certified installation crews represent priority acquisition targets. Long-term viability hinges on regulatory compliance moat durability and digital workflow integration depth. Watch LED retrofit mandate enforcement velocity in California and New York as inflection indicator for replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Water-Based Ink Conversion | EPA NESHAP compliance creates first-mover advantage for aqueous-capable fabricators in regulated states. |
| Acoustic Fabric Capability Investment | Hospitality interior specifications in California and New York drive premium positioning beyond commodity vinyl. |
| Franchise Network Expansion | Standardized quality systems with local adaptation capture recurring volume from national retail chains. |
| LED Retrofit Service Bundling | California Energy Commission mandates accelerate replacement cycles combining printed substrates with LED modules. |
| Regional Fabricator Acquisition | Multi-location service capability consolidation addresses vendor reduction trends among property management firms. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with sign fabricator owners, franchise operations directors, hospitality procurement managers, and EPA compliance officers; and secondary validation through OSHA enforcement records, state environmental agency permit databases, and customs trade data on vinyl film imports. Bottom-up capacity estimates from regional production clusters were triangulated against top-down demand projections from construction spending and retail expansion indicators.
Forecast inputs across the analysis window incorporated substrate material segmentation, printing technology migration curves, and end-user procurement pattern shifts. Modeled dimensions included product type durability tiers, material feedstock exposure, geographic regulatory cluster intensity, and installation service bundling evolution. CAGRs were derived from regression analysis of historical volume trends against construction permit velocity and franchise location growth rates. Industry-specific inputs captured LED retrofit mandate compliance timelines and UV-curable ink adoption curves.
Practitioners should monitor EPA enforcement intensity in non-attainment areas and ethylene supply chain disruption frequency for early signals of margin compression or compliance cost escalation. Quarterly review of state energy code amendment dockets and OSHA elevated work citation trends is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Delumper Market
Others
Europe Indoor LBS Market
Others
Healthcare Bioconvergence Market
Others
Banknote Printing Machine Market
Others
Aerospace Engineering Services Outsourcing Market
Others
Augmented Shopping Market
Others
Underwater Communication System Market
Others
Three Proofing Rugged Tablet Market
Others
Ammeters Market
Others
Space Power Supply Market
Others
Senior Cat Food Market
Others
Aerospace and Defense Fiber Optic Cables Market
Others
Durian Market
Others
Astrology Market
Others
Global Electronic Filters Market
Others
India Data Center Physical Security Market