
 United States Smart Homes Market | 2026-2036
United States Smart Homes Market Size, Share, and Industry Trends Forecast 2026-2036
United States Smart Homes Market Analytics
Buyer concentration among multifamily developers and build-to-rent operators is expanding as institutional landlords standardize smart building packages across portfolios. Amazon.com, Inc. leverages its Alexa ecosystem to control device interoperability across partner hardware. Google LLC anchors its position through Nest thermostats and Thread protocol leadership. Samsung Electronics Co., Ltd competes via SmartThings platform integration with its appliance lineup.
Smart homes encompass residential environments where networked sensors, actuators, and controllers automate lighting, climate, security, and entertainment functions through centralized or distributed intelligence architectures. Systems typically communicate via Zigbee, Z-Wave, Wi-Fi, or Thread protocols with latency thresholds under 100 milliseconds for real-time responsiveness. Home Security Systems command premium service attach rates through recurring monitoring subscriptions. Smart Thermostats generate outsized energy savings visibility that drives retrofit replacement cycles. IoT Devices fragment across proprietary ecosystems, creating integration services as a distinct margin pool.
FCC governs wireless spectrum allocation for device connectivity while NHTSA-adjacent privacy frameworks influence vehicle-to-home data flows. The Inflation Reduction Act directs USDA and DOE incentives toward electrification upgrades that bundle smart panel and load-management hardware. EPA ENERGY STAR certification shapes thermostat and lighting procurement specifications for rebate eligibility. Stakeholders must weigh ecosystem lock-in risks against interoperability mandates as Matter protocol adoption accelerates.
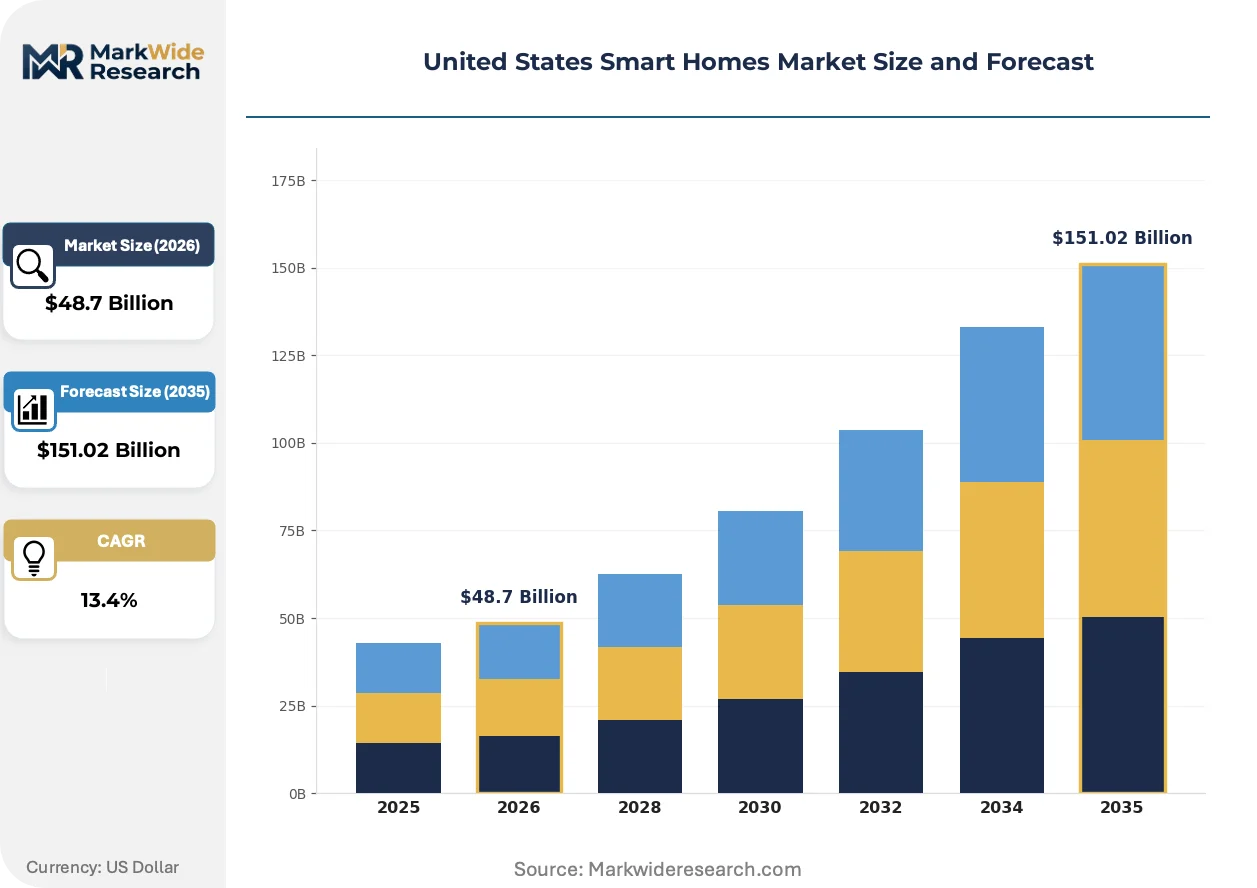
Market Dynamics
Whole-building automation mandates from institutional landlords are compressing procurement cycles across multifamily portfolios, forcing hardware vendors to abandon point-solution sales in favor of integrated platform contracts.
Growth Catalysts
- Inflation Reduction Act electrification incentives:USDA and DOE rebates for smart electrical panels and load-management hardware accelerate retrofit installations in existing housing stock.
- Thread protocol maturation:Low-latency mesh networking under 100 milliseconds enables real-time device coordination that Zigbee and Z-Wave cannot match.
- Sun Belt construction concentration:Pre-wired smart infrastructure in Texas, Florida, and Arizona new builds creates captive demand for compatible device ecosystems.
Market Restraints
- Silicon supply concentration:Taiwan and South Korea semiconductor fabrication bottlenecks constrain microcontroller availability for OEM thermostat and sensor production.
- Copper and lithium carbonate volatility:Battery-backed security devices and smart panel wiring face input cost swings that compress hardware margins.
- FCC spectrum congestion:Unlicensed 2.4 GHz band saturation in dense urban deployments degrades Wi-Fi and Zigbee reliability, forcing costly infrastructure upgrades.
Strategic Opportunities
- Midwestern retrofit underpenetration:Ohio, Michigan, and Illinois housing stock lacks pre-wired infrastructure, creating white space for wireless retrofit solutions.
- Vehicle-to-home integration:Bidirectional EV charging protocols converge with smart panel load management to enable residential microgrid participation.
- Matter protocol adoption:Cross-platform interoperability standard breaks ecosystem lock-in, allowing independent device manufacturers to access previously closed channels.
Industry Challenges
- Certification timeline compression:EPA ENERGY STAR and FCC Part 15 testing backlogs delay product launches by six to nine months, freezing working capital in pre-certified inventory.
- Legacy HVAC integration complexity:24-volt furnace control signals and proprietary heat pump communication buses require custom hardware adapters that fragment product roadmaps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Smart Homes Market |
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $151.02 Billion |
| CAGR (2026 – 2036) | 13.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: IoT Devices, Smart Lighting, Home Security Systems, Smart Thermostats Application: Energy Management, Home Security, Entertainment, Comfort Control End User: Residential, Multifamily Dwellings, Homeowners Associations, Rentals Service Type: Installation, Maintenance, Subscription Services, Integration |
| Companies Covered | Amazon.com, Inc., Google LLC, Apple Inc., Honeywell International Inc., Schneider Electric SE, Samsung Electronics Co., Ltd, Johnson Controls Inc., ADT Inc., LG Electronics Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Smart Homes Market Evolving Landscape
Protocol unification and electrification policy are dismantling the walled-garden model that has structured competition since the sector's emergence, redistributing power toward interoperable hardware specialists.
Thread networking is overtaking legacy mesh protocols in new construction specifications. The IPv6-native stack eliminates hub dependencies for battery-powered sensors. Multifamily developers in Arizona and Texas now specify Thread-certified hardware as standard, compressing deployment timelines for property-wide automation.
EPA ENERGY STAR certification requirements for smart thermostats tighten hardware efficiency thresholds annually. Manufacturers must redesign power management circuits to maintain rebate eligibility. The 2024 specification revision most affects retrofit replacement cycles in the Northeast, where utility rebate programs gate purchase decisions.
Builder-direct procurement models displace retail channel dominance for whole-home packages. Lennar, D.R. Horton, and other national builders negotiate multi-year platform contracts that preselect device ecosystems before ground breaks. This concentration is most visible in Florida master-planned communities, where standardized smart home packages now appear in 80 percent of new single-family listings.
United States Smart Homes Market Segmentation
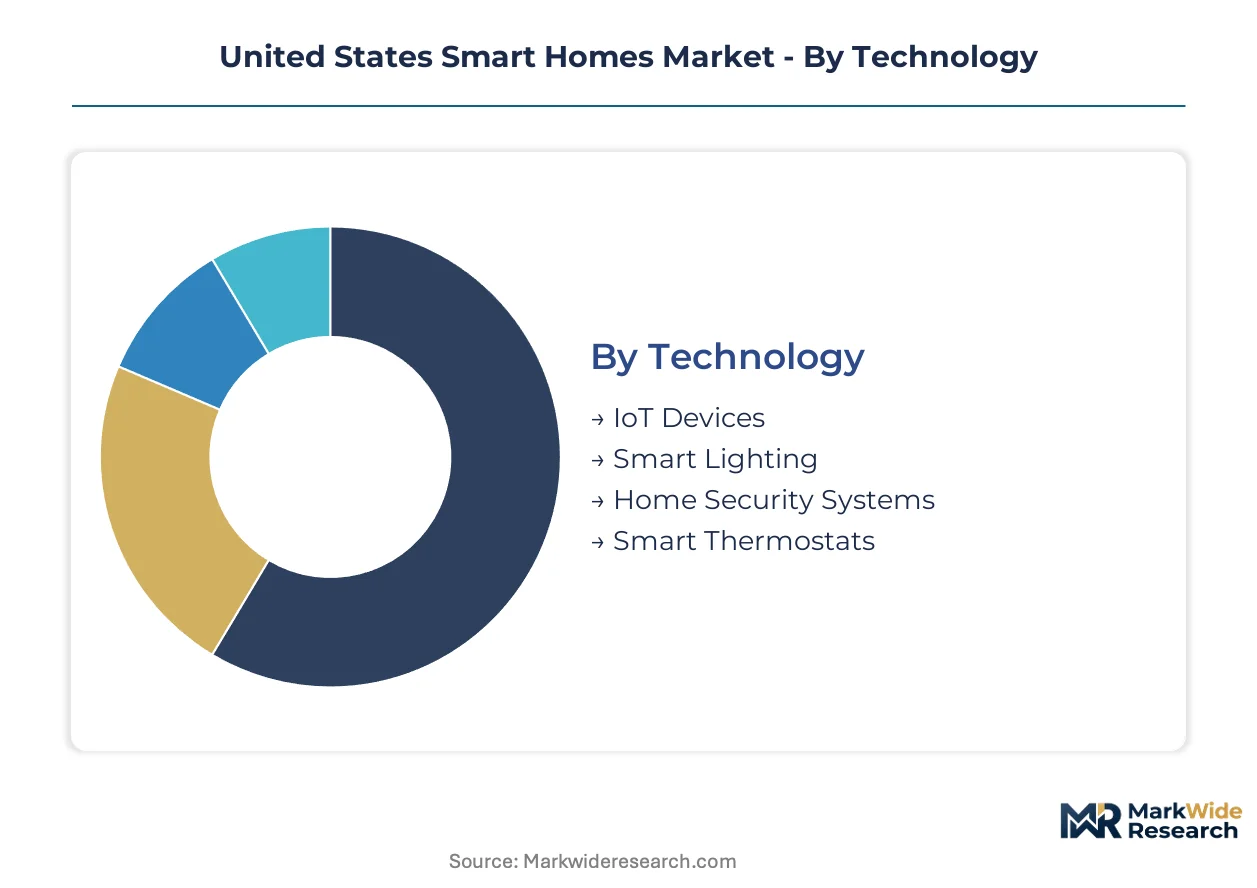
Segmentation in the United States Smart Homes Market reveals how procurement patterns diverge between institutional landlords and individual homeowners. Technology choices, application priorities, and service models fragment across these buyer types, creating distinct margin pools and competitive dynamics.
Technology:
Standardization pressure from Matter protocol adoption sits at one pole; proprietary ecosystem lock-in anchors the other, with vendors calibrating hardware architectures between interoperability premiums and captive revenue streams.
- IoT Devices:Battery-powered sensors and actuators communicate via Thread, Zigbee, or Z-Wave protocols with sub-100-millisecond latency requirements. Demand concentrates in Sun Belt new construction where Lennar and D.R. Horton specify pre-certified hardware bundles. FCC Part 15 certification backlogs constrain launch timelines for smaller OEMs.
- Smart Lighting:LED fixtures with embedded wireless controllers enable circadian programming and occupancy-based dimming. Retrofit replacement cycles accelerate in the Northeast where EPA ENERGY STAR rebates gate utility program eligibility. Thread-native bulbs eliminate hub dependencies in multifamily deployments.
- Home Security Systems:Cameras, motion detectors, and entry sensors with cellular backup command premium monitoring subscriptions.
- Smart Thermostats:24-volt HVAC controllers with learning algorithms generate visible energy savings that drive replacement demand.
Most installed capacity flows through IoT Devices. Expansion is steepest in Home Security Systems.
Application:
Cost tier stratification separates whole-building automation mandates from point-solution retrofits, with institutional buyers prioritizing centralized management and homeowners responding to visible utility bill reductions.
- Energy Management:Smart panels and load-management hardware coordinate with utility demand-response programs. Inflation Reduction Act electrification incentives through USDA and DOE accelerate deployment in existing housing stock across Ohio and Michigan. Real-time consumption visibility drives homeowner engagement.
- Home Security:Perimeter monitoring, access control, and video verification integrate with professional monitoring services. Multifamily operators in Texas and Florida standardize these packages across build-to-rent portfolios. Recurring subscription revenue commands valuation premiums from institutional investors.
- Entertainment:Distributed audio and video systems with voice control integration.
- Comfort Control:Climate zoning and automated shading systems.
Most installed capacity flows through Energy Management. Comfort Control is gaining share fastest among luxury single-family segments.
End User:
Customer type concentration shifts procurement scale from individual transactions to multi-year platform contracts, rewiring vendor sales organizations toward builder-direct and property-management channels.
- Residential:Single-family homeowners purchasing through retail or installer channels. Demand fragments across DIY wireless retrofits and professional integration services. Midwestern underpenetration creates white space for battery-powered solutions that bypass pre-wired infrastructure requirements.
- Multifamily Dwellings:Institutional landlords and REITs deploying whole-building automation across portfolios. Procurement compresses into standardized packages specified at construction. Arizona and Texas master-planned communities now include smart infrastructure in 80 percent of new listings.
- Homeowners Associations:Common-area automation with resident opt-in for unit-level upgrades.
- Rentals:Build-to-rent operators seeking operational efficiency through centralized device management.
Most installed capacity flows through Residential. Multifamily Dwellings show the steepest expansion trajectory as institutional capital concentrates in Sun Belt housing.
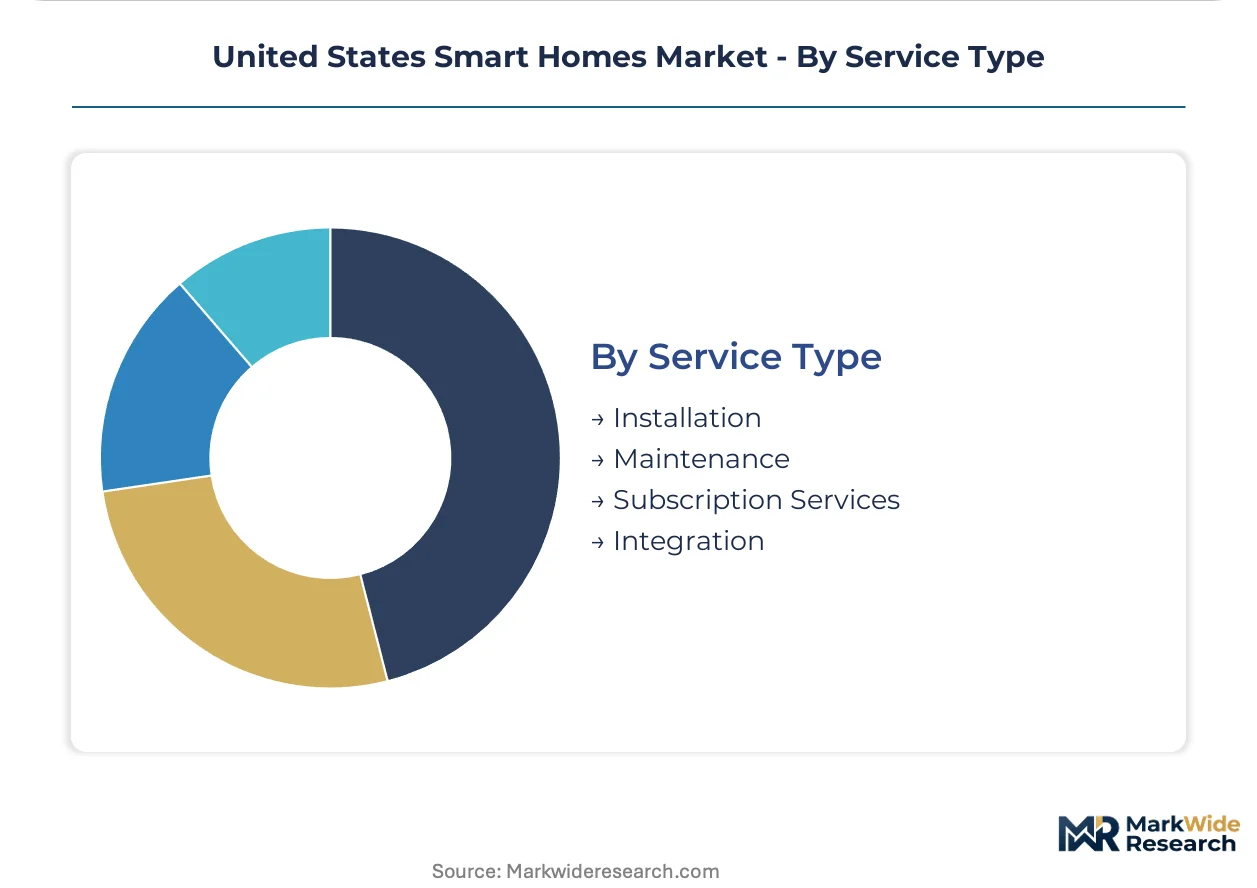
Service Type:
Margin structure differentiates one-time hardware installation from recurring revenue streams, with integration services emerging as a distinct profit pool amid ecosystem fragmentation.
- Installation:Professional deployment of hardware including electrical panel upgrades and device commissioning. Demand concentrates in retrofit markets where legacy HVAC integration requires custom adapters. EPA ENERGY STAR and FCC certification requirements extend project timelines.
- Subscription Services:Cloud-based monitoring, software updates, and premium feature access. Home Security Systems command highest attach rates. Multifamily operators negotiate enterprise pricing across thousands of units.
- Maintenance:Firmware updates, battery replacement, and hardware troubleshooting.
- Integration:Cross-platform connectivity services bridging proprietary ecosystems.
Most installed capacity flows through Installation. Subscription Services are climbing the fastest as vendors pivot toward recurring revenue models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled electrical trades and IoT integration specialists concentrate in Sun Belt metro areas where new construction volumes support dedicated smart home installation workforces.
Southwest
Texas and Arizona master-planned communities specify Thread-certified hardware in 80 percent of new single-family listings. The Inflation Reduction Act's USDA rural electrification incentives extend into exurban counties surrounding Houston and Dallas-Fort Worth. Austin's tech corridor attracts smart panel manufacturers establishing regional distribution hubs.
Southeast
Florida's build-to-rent operators standardize whole-building automation across institutional portfolios from Miami to Tampa. The EPA ENERGY STAR certification requirements shape thermostat procurement for utility rebate programs administered by the Florida Public Service Commission. Orlando's construction labor market specializes in pre-wired smart infrastructure deployment.
Northeast
Retrofit replacement cycles accelerate where legacy housing stock lacks pre-wired infrastructure. The Inflation Reduction Act's DOE weatherization assistance flows through state energy offices in Massachusetts and New York. Boston's integration service providers bridge proprietary ecosystems for high-end residential clients.
Midwest
Ohio and Michigan present white space for wireless retrofit solutions bypassing infrastructure requirements. The USDA's rural development electrification grants target smart panel upgrades in agricultural counties. Chicago's electrical contractor networks pivot toward load-management hardware installation.
Pacific Coast
California's Title 24 building efficiency standards mandate smart thermostat compatibility in new construction. The CPUC's demand-response programs create utility procurement channels for smart panel vendors. Silicon Valley's protocol engineering talent concentrates around Thread and Matter certification laboratories.
United States Smart Homes Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across hardware, platform, and service layers. The vendor base organizes into three strategic archetypes: ecosystem orchestrators controlling interoperability standards, appliance manufacturers leveraging installed base conversion, and security-centric operators monetizing recurring subscriptions. Consolidation pressures intensify as builder-direct procurement models favor multi-year platform contracts over point-solution sales. Strategic partnerships and technology licensing arrangements dominate competitive moves as vendors seek Matter protocol certification advantages.
Among ecosystem orchestrators, Amazon.com, Inc. and Google LLC represent the platform-centric tier where voice control and protocol leadership anchor competitive positioning. Samsung Electronics Co., Ltd exemplifies the appliance-integrated archetype leveraging SmartThings platform reach across consumer electronics categories. These three occupy positions where ecosystem lock-in risks intersect with interoperability mandates from the Matter standard.
| Leading Market Players |
|---|
| Amazon.com, Inc. |
| Google LLC |
| Apple Inc. |
| Honeywell International Inc. |
| Schneider Electric SE |
| Samsung Electronics Co., Ltd |
| Johnson Controls Inc. |
| ADT Inc. |
| LG Electronics Inc. |
| Others |
Value Network & Pricing Analysis
Thread protocol maturation in new construction specifications simultaneously compresses hardware margins through standardization and concentrates procurement leverage among national builders who negotiate multi-year platform contracts. This technology transition reshapes cost economics by eliminating hub dependencies while tethering device pricing to bundled whole-home packages rather than point-solution retail sales.
Pricing Analysis
Bundled service contracts versus unbundled hardware transactions define the dominant pricing split in this market. Subscription-based monitoring services for Home Security Systems command premium recurring revenue, while smart thermostat and lighting sales stratify across EPA ENERGY STAR certification tiers that gate utility rebate eligibility. Pricing pressure stems from builder-direct procurement concentration, as Lennar and D.R. Horton negotiate volume discounts that compress margins for OEMs. Individual homeowners in the Northeast exhibit highest price sensitivity due to retrofit cost barriers, whereas institutional landlords in Texas and Florida prioritize operational efficiency over unit economics.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan and South Korea for semiconductor fabrication, where foundry bottlenecks constrain microcontroller availability for thermostat and sensor OEMs. Copper wiring and lithium carbonate for battery-backed security devices draw from Chilean mining operations and Chinese processing facilities. Tariff exposure on Chinese-manufactured LED controllers and wireless modules presents structural risk amid ongoing trade policy uncertainty. Distribution runs through builder-direct channels for new construction, while retail and professional installer networks serve retrofit replacement cycles in legacy housing stock.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States Smart Homes Market functions as a stable compounder where electrification policy and protocol unification generate durable replacement demand across decades-long housing stock turnover.
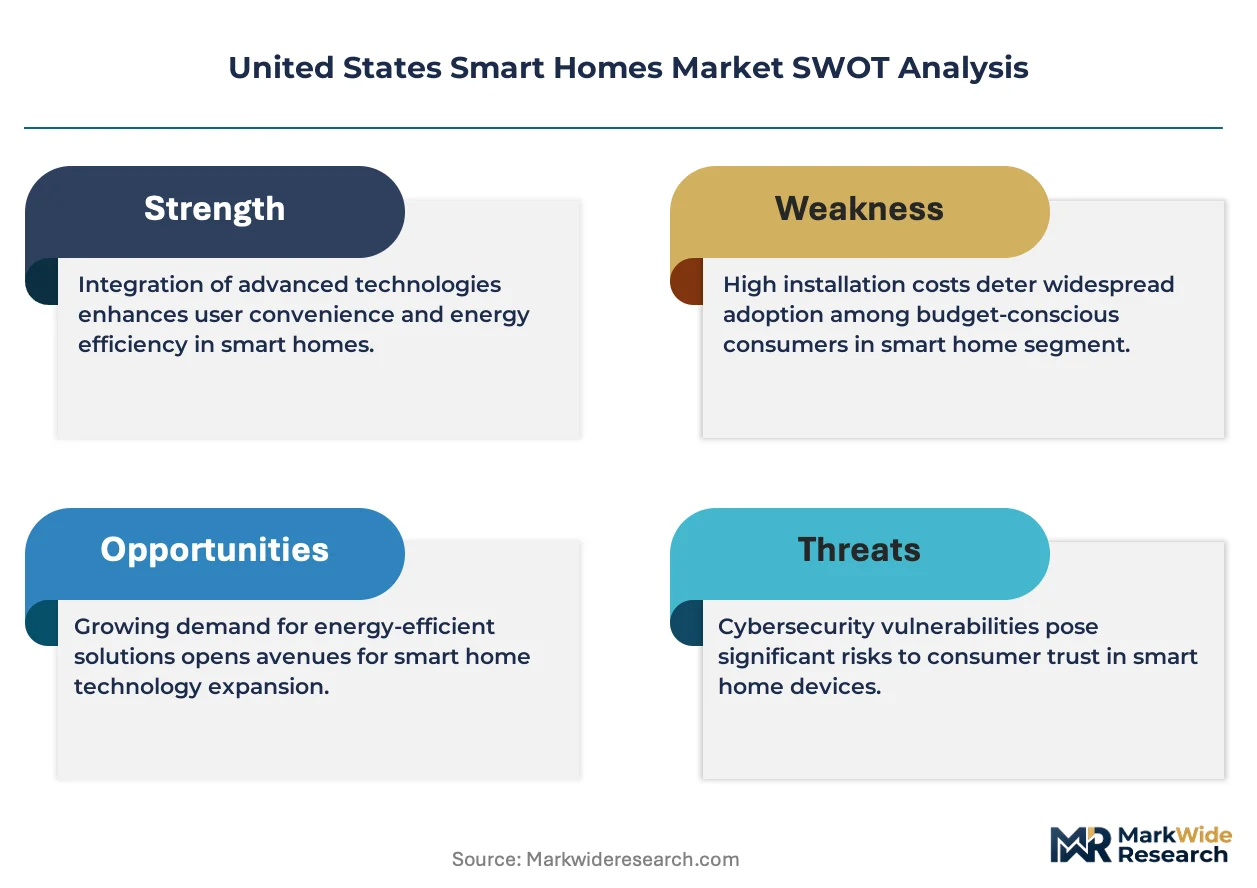
For Market Incumbents: Hedge ecosystem lock-in erosion by accelerating Matter protocol certification for core device portfolios before interoperability mandates harden. Backward integration into smart panel manufacturing captures Inflation Reduction Act electrification incentives flowing through USDA and DOE channels. Prioritize multi-year platform contracts with D.R. Horton and Lennar to defend against emerging hardware specialists gaining Thread certification.
For New Entrants and Emerging Players: Midwestern single-family homeowners in Ohio and Michigan represent the most penetrable buyer archetype, as wireless retrofit solutions bypass pre-wired infrastructure requirements that Sun Belt competitors exploit. Battery-powered sensor systems with Thread-native stacks eliminate hub dependencies that fragment incumbent offerings. Target professional installer channels in Chicago and Detroit where electrical contractor networks pivot toward load-management hardware deployment.
For Investors and Strategic Acquirers: Valuations sit cheapest among integration service providers bridging proprietary ecosystems, as ecosystem fragmentation creates persistent demand for cross-platform connectivity expertise. Long-term viability centers on recurring revenue attach rates rather than hardware shipment volumes. Monitor EPA ENERGY STAR specification revisions as inflection indicators that accelerate replacement cycles in rebate-dependent Northeast markets.
| Strategic Initiative | Industry Significance |
|---|---|
| Matter Protocol Certification | Cross-platform interoperability breaks Amazon and Google ecosystem lock-in for independent device manufacturers. |
| Builder-Direct Platform Contracts | Multi-year agreements with Lennar and D.R. Horton displace retail channel dominance in Sun Belt new construction. |
| Backward Integration into Smart Panels | In-house production of load-management hardware captures USDA and DOE electrification rebates under the Inflation Reduction Act. |
| Subscription Service Expansion | Recurring monitoring revenue for Home Security Systems commands valuation premiums from institutional REIT investors. |
| Midwest Retrofit Channel Development | Wireless retrofit solutions in Ohio and Michigan bypass pre-wired infrastructure requirements that Sun Belt competitors exploit. |
Research Methodology
Direct dialogue with multifamily developers, smart home platform engineers, electrical contractors, and utility demand-response program managers anchored the qualitative foundation. Secondary validation drew from FCC Part 15 equipment authorization databases, EPA ENERGY STAR certified product listings, USDA rural development electrification grant disclosures, and builder procurement contract filings. Bottom-up and top-down triangulation cross-referenced device shipment estimates against housing construction permits and retrofit replacement cycle data.
Bottom-up modeling segmented the market by technology, application, end user, and service type across the projection horizon. Analysts derived CAGRs from housing stock turnover rates, electrification incentive uptake curves, and protocol adoption timelines. Forecast inputs incorporated Thread certification penetration in new construction specifications, ENERGY STAR specification revision impacts on replacement demand, and institutional landlord portfolio standardization trajectories.
Underlying measurement precision varies by segment; IoT Devices and Smart Thermostats carry tighter precision than Integration Services where informal labor markets complicate quantification. Forecasts reflect assumptions about Inflation Reduction Act incentive continuity, semiconductor supply normalization, and Matter protocol adoption velocity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Canada 3D Printing Construction Market
Others
Middle East and Africa Electric Vehicle Battery Electrolyte Market
Others
Bamboo Straws Market
Others
Thermoformed Plastics Market
Others
North America Thermoformed Plastics Market
Others
Process Instrumentation Equipment Market
Others
UK Cat Food Market
Others
China Smart Home Market
Others
Shear Testing Equipment Market
Others
Global Solder Balls Market
Others
Folding Mobile Phone Market
Others
Global Recruitment and Staffing Market
Others
Coconut Activated Carbon Market
Others
Connected Homes Market
Others
Latin America Fire Sprinklers Market
Others
Asia-Pacific Eyelash Serum Market