
 System Integration Market | 2026-2036
System Integration Market Size, Share, and Industry Trends Forecast 2026-2036
System Integration Market Analysis
Enterprise buyer demand is rotating from siloed departmental IT projects toward unified operational-technology convergence programs. Accenture leverages its industrial IoT practice to anchor large-scale manufacturing transformation engagements. Tata Consultancy Services sustains competitive intensity through captive delivery centers and sector-specific solution templates. IBM differentiates via hybrid cloud middleware that bridges legacy SCADA with modern analytics layers.
System integration denotes the engineering discipline of interconnecting heterogeneous hardware, software, networking, and data assets into unified operational environments, typically requiring protocol translation, middleware orchestration, and real-time data normalization across disparate vendor stacks. Its primary purpose is to eliminate information silos and enable automated decision flows across enterprise functions. Enterprise application integration retains the largest revenue footprint among solution types, though cloud integration commands the fastest expansion as lift-and-shift migrations yield to cloud-native refactoring. Within deployment models, hybrid architectures capture disproportionate capital allocation as regulated industries seek to retain sensitive workloads on-premises while bursting analytics to public infrastructure.
FDA validation requirements for healthcare IT interoperability, EU GDPR data-localization mandates, and NIST cybersecurity framework obligations collectively shape procurement specifications and vendor qualification criteria across buyer segments. EMA medical-device software guidance and SEC disclosure rules for financial infrastructure further tighten compliance thresholds for integration deliverables. Stakeholders must weigh sovereign data requirements against cloud economics when architecting multi-jurisdiction integration backbones.
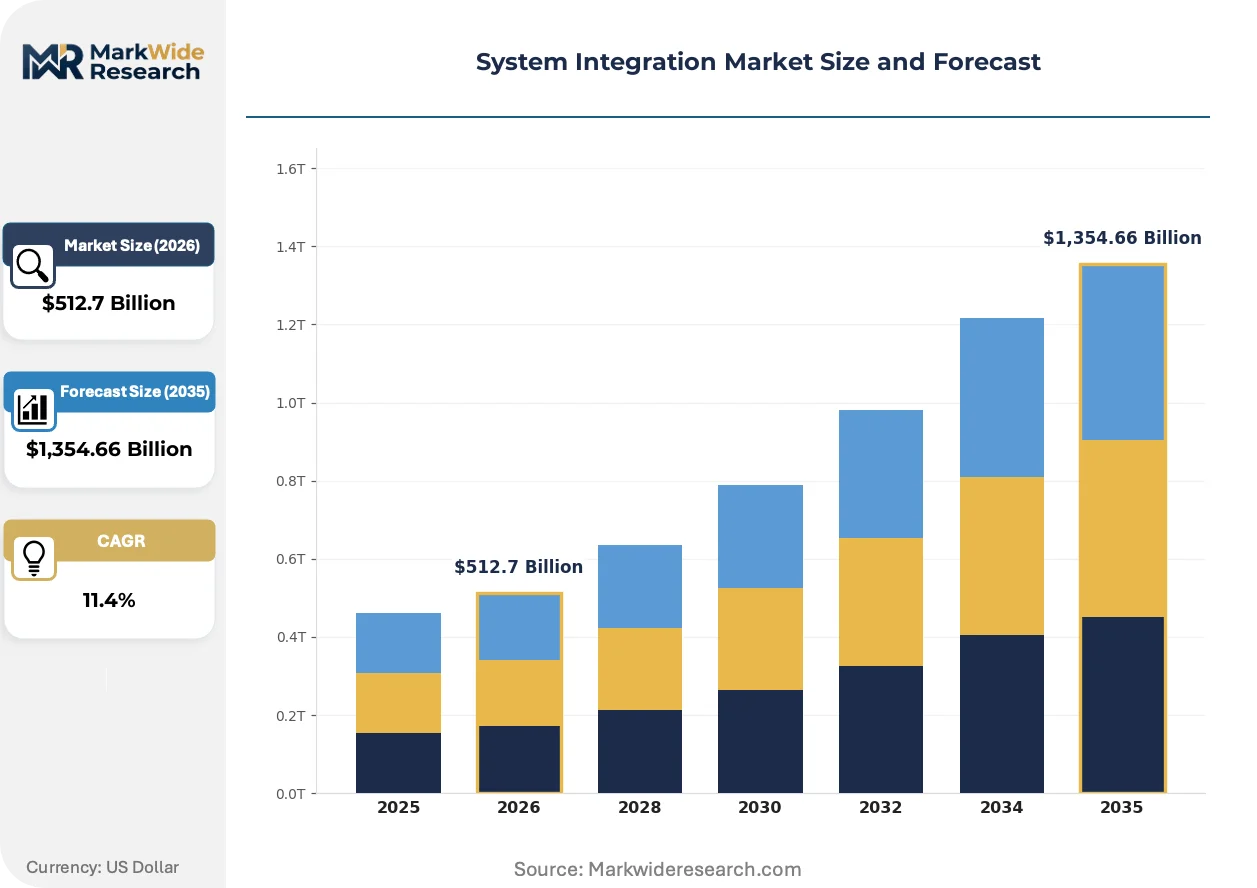
Market Dynamics
Manufacturing firms are accelerating adoption of connected production systems, forcing integration vendors to bridge operational technology with enterprise IT stacks while navigating tightening data sovereignty requirements under GDPR and national equivalents.
Growth Catalysts
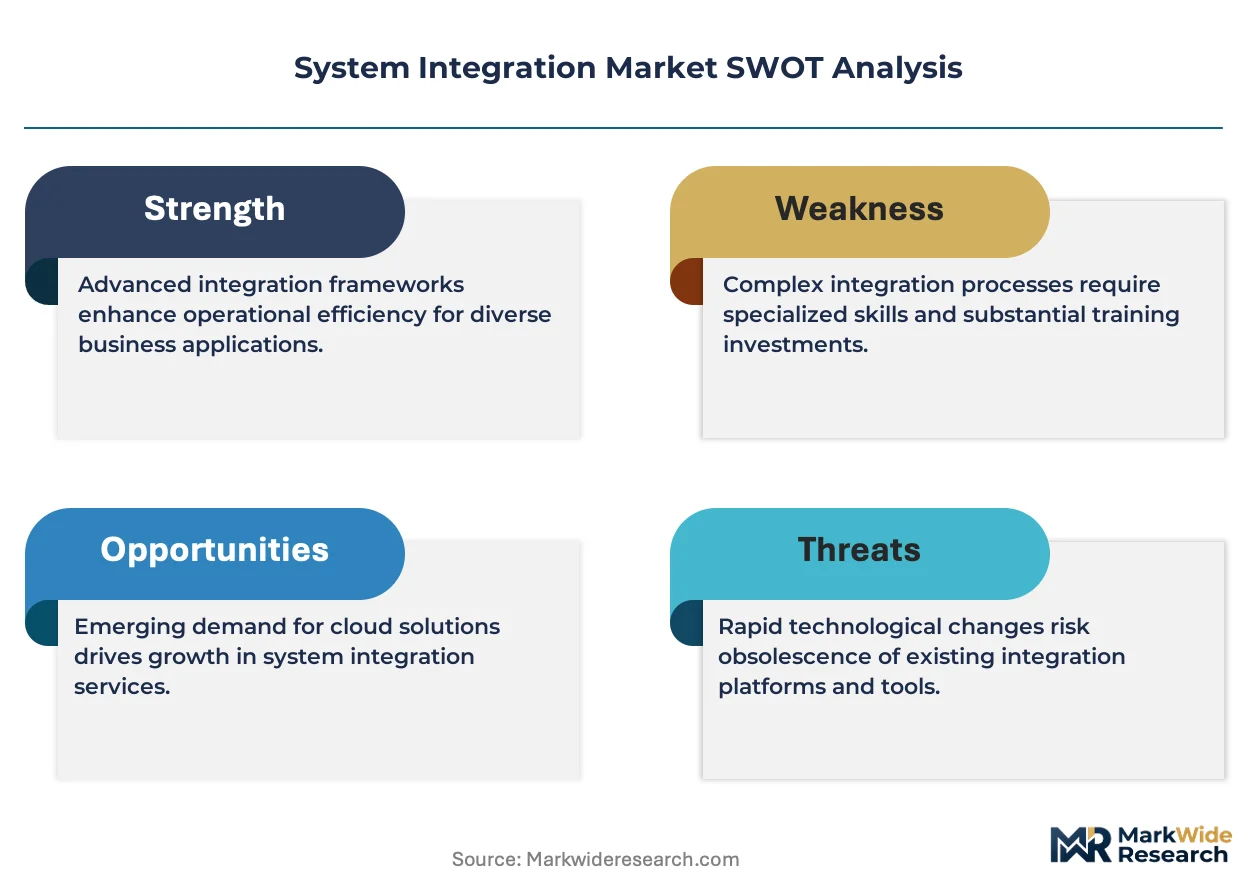
- Industrial IoT proliferation:Smart factory mandates in Germany's Industrie 4.0 program and India's PLI scheme for electronics manufacturing are driving demand for protocol translation layers that unify legacy SCADA with cloud analytics.
- Healthcare interoperability mandates:FDA validation requirements for medical device software integration are compelling hospital systems to modernize electronic health record connectivity, creating sustained procurement cycles.
- Hybrid cloud normalization:Financial services firms under SEC disclosure rules for infrastructure resilience are deploying middleware that bursts sensitive workloads to on-premises infrastructure while routing analytics to public clouds.
Market Restraints
- Specialized engineering talent scarcity:Protocol engineering expertise in OPC-UA and MQTT broker configuration concentrates in Germany, the United States, and India, inflating project delivery costs elsewhere.
- Input cost volatility:Semiconductor shortages for industrial edge gateways and networking hardware are compressing system integrator margins on fixed-price contracts.
- Regulatory fragmentation:Divergent EU GDPR data-localization mandates, China's GB standards for cross-border data flows, and US state-level privacy laws are forcing vendors to maintain jurisdiction-specific deployment architectures.
Strategic Opportunities
- Greenfield manufacturing clusters:India's semiconductor fabrication incentives and industrial corridor development are creating demand for integrated automation systems without legacy technical debt.
- Edge-to-cloud orchestration:Convergence of 5G private networks with containerized microservices is enabling real-time predictive maintenance platforms for automotive and aerospace production lines.
- EU AI Act compliance services:Risk management system documentation requirements for high-risk AI applications are opening advisory and technical implementation revenue streams for integration specialists.
Industry Challenges
- Cyber-physical security certification timelines:NIST cybersecurity framework obligations and IEC 62443 conformity assessments are extending project handover schedules by four to eight months in critical infrastructure sectors.
- Heterogeneous system reconciliation:Brownfield manufacturing environments require protocol gateways that normalize data from thirty-year-old proprietary PLCs alongside modern REST APIs, multiplying integration testing cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | System Integration Market |
| Market Size in 2026 | $512.7 Billion |
| Market Size in 2035 | $1,354.66 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Enterprise Application Integration, Cloud Integration, API Management, Data Integration End User: Healthcare Providers, Retail Chains, Financial Institutions, Manufacturing Firms Deployment Model: On-Premises, Cloud-Based, Hybrid, Managed Services Technology: IoT Integration, Middleware, Robotics Process Automation, AI Solutions |
| Companies Covered | Wunderlich-Malec, Capgemini, Accenture, Cognizant, Tata Consultancy Services, Deloitte, Grantek, Infosys, IBM, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
System Integration Market Emerging Trajectories
Integration architectures are shifting from point-to-point connectors toward API-first platforms that enable continuous deployment pipelines across operational and information technology boundaries.
Containerized middleware is decomposing monolithic enterprise service buses into modular, Kubernetes-orchestrated microservices. Automotive manufacturers in Germany and the United States are deploying these architectures at scale to enable over-the-air software updates across distributed supplier networks. This decomposition is compressing vendor lock-in by standardizing on open-source service meshes and reducing switching costs between cloud providers.
EU GDPR data-localization mandates and the Digital Operational Resilience Act are compelling financial institutions to maintain audit-ready data lineage across hybrid infrastructures. Banks in Frankfurt and Amsterdam are investing in sovereign cloud zones that satisfy residency requirements while preserving API connectivity to international payment networks. Asset managers under SEC custody rule modernization are extending these architectures to trade execution systems.
Buyer procurement patterns are favoring outcome-based engagement models over time-and-materials contracts. German automotive OEMs and US defense primes are shifting toward fixed-fee transformation programs with gain-sharing clauses tied to production uptime metrics. This reconfiguration is most advanced in aerospace supply chains, where tier-one suppliers assume integration risk for multi-site MES deployments.
System Integration Market Segmentation
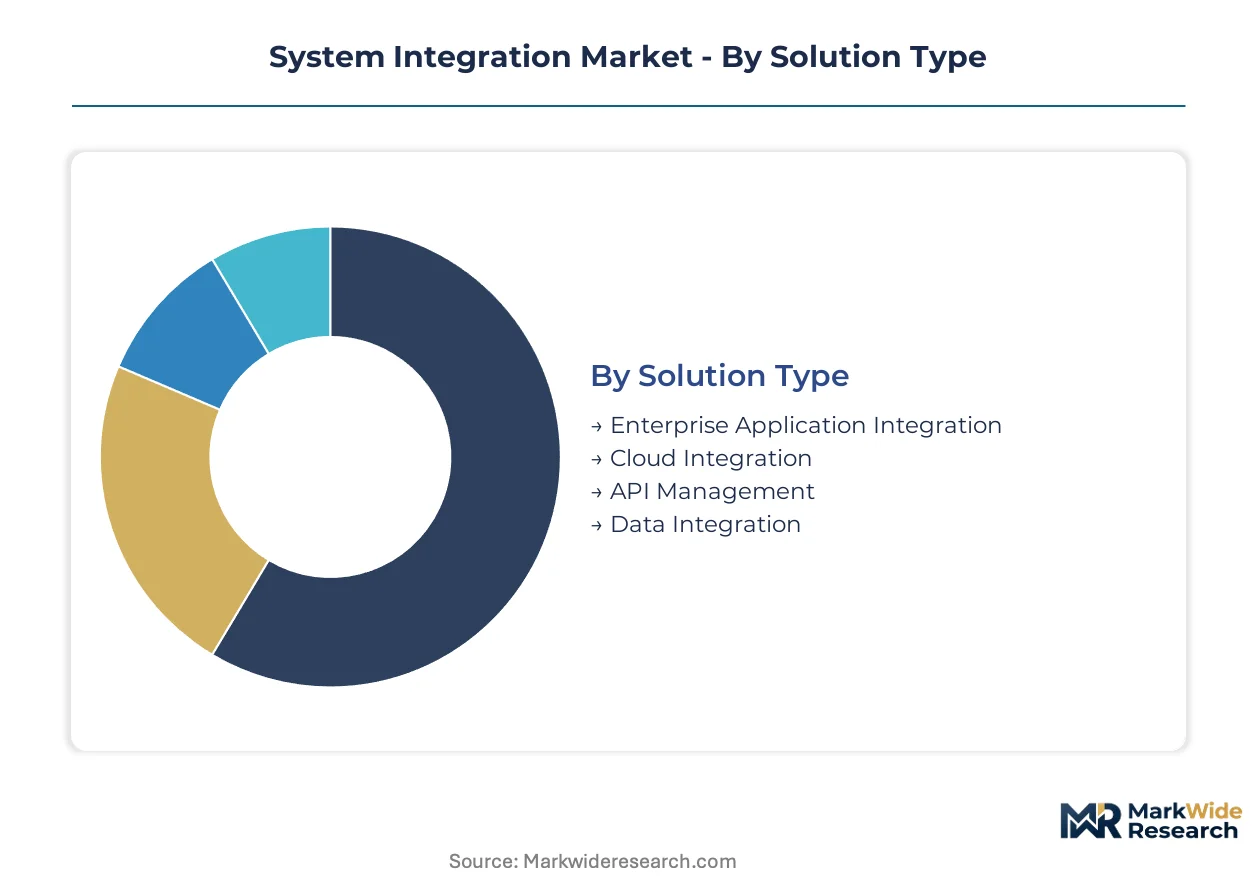
System integration procurement patterns diverge sharply across solution architectures and deployment models, with regulatory compliance requirements dictating technology selection in healthcare and financial services while manufacturing buyers prioritize operational-technology convergence.
Solution Type:
FDA validation protocols for healthcare IT and SEC disclosure obligations for financial infrastructure create divergent certification burdens across integration solution categories.
- Enterprise Application Integration:Middleware orchestration layers synchronize ERP, CRM, and SCM systems through standardized message buses. German automotive OEMs and US defense primes anchor procurement volumes here, driven by legacy system consolidation mandates and multi-site operational visibility requirements.
- Cloud Integration:Lift-and-shift migration tooling and cloud-native refactoring platforms enable workload portability across hyperscale providers. India's PLI scheme for electronics manufacturing and Germany's Industrie 4.0 program are accelerating adoption, though GDPR data-localization mandates constrain architecture choices.
- API Management:Gateway platforms govern service discovery, rate limiting, and security policy enforcement across distributed microservices.
- Data Integration:ETL pipelines and real-time streaming architectures normalize heterogeneous data formats for analytics consumption.
Established volume favors Enterprise Application Integration; emerging adoption favors Cloud Integration.
End User:
Customer procurement sophistication varies by sector maturity, with financial services demanding sovereign cloud architectures and healthcare prioritizing FDA-validated interoperability stacks.
- Healthcare Providers:Electronic health record connectivity and medical device software integration require IEC 62304 conformity and FDA 21 CFR Part 820 quality system documentation. Hospital systems in the United States and Germany are modernizing HL7 FHIR implementations under tightening EMA medical-device guidance.
- Manufacturing Firms:Connected production systems unify SCADA, MES, and ERP layers through OPC-UA protocol translation. Smart factory investments in Germany's Industrie 4.0 framework and India's industrial corridor development are driving greenfield automation procurement without legacy technical debt.
- Financial Institutions:Hybrid cloud middleware bursts sensitive workloads to on-premises infrastructure while routing analytics to public clouds under SEC infrastructure resilience disclosure rules.
- Retail Chains:Omnichannel inventory synchronization and POS integration dominate procurement specifications.
Procurement maturity concentrates in Healthcare Providers; expansion velocity concentrates in Manufacturing Firms.
Deployment Model:
Capital allocation patterns reflect risk tolerance for data sovereignty, with regulated industries accepting higher operational complexity to retain sensitive workloads on-premises.
- Hybrid:Architectures partition workloads across on-premises infrastructure and public cloud zones, enabling compliance with EU GDPR localization mandates while preserving burst capacity. Frankfurt and Amsterdam financial institutions are deploying sovereign cloud zones to satisfy residency requirements.
- Cloud-Based:Fully managed SaaS integration platforms eliminate infrastructure ownership but constrain customization for proprietary protocol requirements.
- On-Premises:Self-managed integration stacks retain complete data control for classified defense and intelligence applications.
- Managed Services:Third-party operational responsibility transfers cybersecurity and availability risk to specialized vendors.
Current deployment favors Hybrid architectures; cloud-native refactoring is displacing On-Premises legacy.
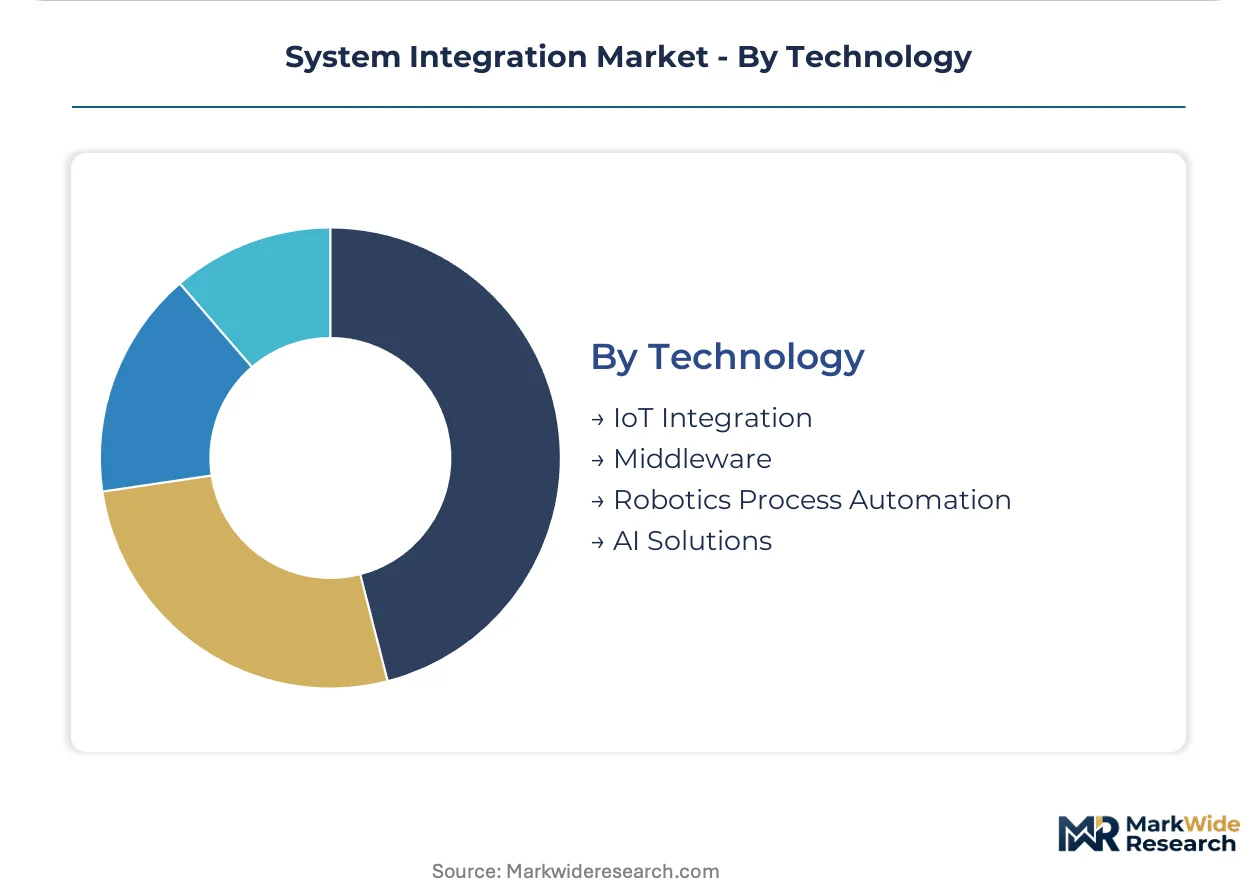
Technology:
Technology selection criteria weigh open-source standardization against vendor-specific performance optimizations, with automotive and aerospace supply chains driving containerized microservices adoption.
- IoT Integration:Edge-to-cloud orchestration platforms collect, filter, and transmit sensor telemetry from distributed industrial assets. 5G private network convergence with Kubernetes-orchestrated microservices is enabling real-time predictive maintenance for German and US automotive production lines.
- Middleware:Message brokers and service buses provide protocol translation between disparate vendor stacks, remaining essential for brownfield manufacturing environments with thirty-year-old proprietary PLCs.
- Robotics Process Automation:Software bots automate repetitive data entry and system navigation tasks across legacy applications.
- AI Solutions:Machine learning pipelines for anomaly detection and predictive analytics require EU AI Act risk management system documentation for high-risk deployments.
Middleware retains the largest installed base; IoT Integration is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German system integrators export industrial IoT platforms to manufacturing clients across the United States and India, establishing a dominant trade-flow corridor in connected production technology.
United States
Defense primes and automotive OEMs drive demand for hybrid cloud middleware that bridges legacy SCADA with modern analytics layers. SEC disclosure rules for infrastructure resilience mandate sovereign data architectures in financial services. Detroit's automotive corridor and Seattle's cloud engineering clusters anchor procurement volumes for operational-technology convergence programs.
Germany
Industrie 4.0 smart factory mandates accelerate protocol translation layer deployments across automotive and precision engineering supply chains. GDPR data-localization requirements constrain cloud architecture choices for exporters serving EU clients. Stuttgart's manufacturing automation cluster and Munich's industrial software ecosystem concentrate engineering talent for OPC-UA broker configuration.
India
Electronics manufacturing incentives under the PLI scheme create greenfield demand for integrated automation systems without legacy technical debt. RBI guidelines on data localization shape financial services integration specifications. Bengaluru's software engineering hub and Gujarat's industrial corridor development attract captive delivery center investments from global integrators.
China
Domestic semiconductor fabrication investments drive demand for edge-to-cloud orchestration platforms in advanced manufacturing zones. GB standards for cross-border data flows force jurisdiction-specific deployment architectures for multinational clients. Yangtze River Delta electronics clusters and Pearl River Delta industrial automation hubs concentrate smart factory implementation projects.
United Kingdom
Financial services firms under FCA operational resilience requirements deploy hybrid integration stacks for payment infrastructure modernization. Post-Brexit data adequacy arrangements complicate EU-UK cloud workload portability for banking clients. London's fintech corridor and Manchester's industrial software development centers sustain middleware engineering capacity.
System Integration Market Vendor Landscape
Listed leaders compete with private specialists across delivery model differentiation, with publicly traded consultancies leveraging balance sheet capacity for large-scale transformation engagements while private engineering boutiques capture niche protocol engineering contracts. The vendor base stratifies into three tiers: global IT consultancies with industrial IoT practices, mid-scale automation specialists with sector-specific templates, and regional system integrators with captive delivery networks. Dominant competitive moves include strategic partnerships with hyperscale cloud providers and geographic expansion through acquisition of boutique OT engineering firms.
Within the global consultancy tier, Accenture, Capgemini, and IBM exemplify scale-driven positioning through hybrid cloud middleware investments and industrial digitization program leadership. These publicly traded entities anchor competitive intensity in manufacturing transformation engagements across Germany, the United States, and India. Tata Consultancy Services and Infosys occupy positions within the India-origin delivery specialist archetype, leveraging captive engineering centers and sector-specific solution templates to sustain cost-competitive positioning in enterprise application integration markets.
| Leading Market Players |
|---|
| Wunderlich-Malec |
| Capgemini |
| Accenture |
| Cognizant |
| Tata Consultancy Services |
| Deloitte |
| Grantek |
| Infosys |
| IBM |
| Others |
Supply Flow & Price Mechanics
Sixteen-week lead times for industrial edge gateways and OPC-UA protocol stacks concentrate procurement leverage among German and US engineering houses, compressing margin buffers for fixed-price integration contracts while amplifying pricing power for vendors with captive semiconductor inventories.
Pricing Analysis
Legacy-to-cloud migration pricing gaps separate three distinct tiers: brownfield protocol translation services command premium rates against greenfield cloud-native deployments, while next-generation AI-augmented integration platforms sit at the apex. Project-based pricing dominates manufacturing engagements, with FDA-validated healthcare stacks carrying certification-grade premiums over standard enterprise application integration. Cost compression in cloud integration tiers is intensifying because hyperscale providers are bundling middleware into base infrastructure offerings. Mid-market manufacturing firms exhibit highest price sensitivity, whereas defense primes and regulated financial institutions prioritize compliance assurance over unit economics.
Supply Chain Analysis
Strategic stockpiling of industrial networking hardware and edge computing modules characterizes buyer behavior, displacing just-in-time preferences after semiconductor shortage disruptions. Supply concentrates in Taiwan for advanced edge processors, Germany for precision automation components, and India for software engineering capacity. Raw material dependencies span silicon wafers, rare-earth magnets for servo motors, and copper for industrial cabling. Single-source vulnerability in Taiwan-sourced edge AI chips presents structural risk. Distribution runs through direct vendor relationships for large enterprises and regional system integrator networks for mid-market accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
System integration functions as a defensive-moat market where regulatory certification entrenchment and customer switching costs protect incumbent positioning against pure-play technology disruption.
For Market Incumbents: Compound switching-cost advantages by embedding proprietary protocol adapters deeper into client operational technology stacks, particularly in brownfield manufacturing environments where thirty-year-old PLC replacement cycles extend vendor tenure. Acquire boutique OPC-UA engineering specialists in Stuttgart and Bengaluru to preempt talent scarcity threats. Prioritize IEC 62443 cybersecurity certification investment to extend project handover timelines that competitors cannot match.
For New Entrants and Emerging Players: Anchor in India's greenfield semiconductor fabrication corridors where PLI scheme incentives eliminate legacy technical debt and enable cloud-native integration architectures from inception. Target electronics manufacturing services clusters in Gujarat and Tamil Nadu with sovereign cloud zone offerings that satisfy RBI data-localization guidelines. Lead with API-first microservices platforms rather than monolithic enterprise service bus replacements.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because mid-scale automation specialists with sector-specific templates in automotive and healthcare command scarcity premiums against generic IT consultancies. Acquisition target archetype: German industrial IoT boutiques with Industrie 4.0 reference architectures and captive OPC-UA engineering benches. Watch for inflection when EU AI Act risk-management documentation requirements trigger compliance-service procurement spikes among high-risk AI deployers.
| Strategic Initiative | Industry Significance |
|---|---|
| Acquisition of Specialist Firm | Boutique OPC-UA engineering teams in Stuttgart and Bengaluru preempt talent scarcity and accelerate brownfield protocol translation capabilities. |
| Platform Integration | Kubernetes-orchestrated microservices decompose monolithic service buses and compress vendor lock-in for automotive supply chains. |
| Geographic Expansion | Captive delivery centers in Gujarat's industrial corridor capture PLI-driven greenfield automation demand without legacy technical debt. |
| Strategic Partnership | Sovereign cloud alliances with Frankfurt and Amsterdam financial institutions satisfy GDPR residency while preserving API connectivity. |
| Product Launch | EU AI Act compliance documentation services open advisory revenue streams for high-risk AI integration deployments. |
Methodological Framework
Operator-level perspectives from plant engineers, OT-IT convergence leads, system integration procurement officers, and regulatory compliance directors anchored the qualitative base. Primary interview findings triangulated against secondary sources including SEC infrastructure resilience disclosures, EMA medical-device software guidance, FDA 21 CFR Part 820 quality system documentation, and EU GDPR localization enforcement patterns. Bottom-up project pipeline analysis and top-down industrial digitization budget forecasts were reconciled to validate sizing.
Sensitivity analysis across deployment model, end-user vertical, solution architecture, and regional regulatory cluster informed the analytical framework over the projection horizon. CAGRs were derived from segment-level adoption curve modeling and technology substitution elasticity estimates. Forecast inputs incorporated Industrie 4.0 investment trajectories, PLI scheme disbursement schedules, and semiconductor availability constraints on edge gateway deployment.
Decision-makers should treat outputs as directional under assumptions of sustained industrial digitization program funding and stable cross-border data flow regulatory frameworks; material deviation in geopolitical trade policy or AI Act enforcement intensity would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Global Process Orchestration Market
Digital Solutions
Digital BSS Market
Digital Solutions
Cloud Project Portfolio Management (CPPM) Market
Digital Solutions
Europe Digital Signage Market
Digital Solutions
Product Prototyping Market
Digital Solutions
Voice Remote Control Market
Digital Solutions
Smart and Mobile Supply Chain Solutions Market
Digital Solutions
Global Freight Software Market
Digital Solutions
Data Extraction Market
Digital Solutions
Cloud Logistics Software Market
Digital Solutions
Digital Evidence Management System Market
Digital Solutions
UK and Germany Diet and Nutrition Apps Market
Digital Solutions
Global Smart Offices Market
Digital Solutions
Utility App Market
Digital Solutions
Echo Reduction Software Market
Digital Solutions
Australia Digital Twin Market