
 TWS Micro-Battery Market | 2026-2036
TWS Micro-Battery Market Size, Share, and Industry Trends Forecast 2026-2036
TWS Micro-Battery Market Insights
The EU Battery Regulation is restructuring the cost-of-entry calculus for TWS micro-battery suppliers by imposing strict due diligence, recycled content mandates, and replaceability requirements on small-format cells. Panasonic Corporation leverages its vertically integrated material supply chain to sustain cost discipline across European certification pathways. Samsung SDI anchors its position through proprietary stacked electrode architectures that dominate premium TWS audio tiers. VARTA AG specializes in German-engineered micro-cylindrical formats that command channel control among European audio OEMs.
TWS micro-batteries are compact electrochemical cells typically rated below 100 mAh, engineered with lithium cobalt oxide or lithium nickel manganese cobalt oxide cathodes and graphite or silicon-composite anodes to deliver high volumetric energy density in sub-gram form factors. Their primary commercial purpose is to power wireless audio earbuds, fitness wearables, and augmented reality glasses where space constraints and cycle life requirements exceed what conventional coin cells provide. Rechargeable lithium-ion configurations lead volume shipments due to their established manufacturing scale and declining cost curve, while solid-state technology captures the fastest-growing margin pool as manufacturers chase higher energy density without flammability risks. The audio devices application concentrates the largest demand share, though smart glasses represent the emerging frontier where cell shape flexibility and ultra-low self-discharge rates command pricing premiums.
REACH compliance and RoHS substance restrictions govern chemical composition and material disclosure across European supply chains, while the FCC in the United States regulates electromagnetic compatibility for devices incorporating these cells. China's GB standards and MIIT circular economy directives shape domestic manufacturing protocols and export eligibility for cell producers serving global TWS brands. Stakeholders must monitor how divergent recycling obligations and carbon border adjustments will reshape supplier qualification criteria and regional sourcing decisions.
Market Dynamics
EU Battery Regulation mandates on replaceability and recycled content thresholds are forcing cell architects to redesign cylindrical formats around disassembly protocols and material traceability systems.
Growth Catalysts
- TWS Earbud Shipment Surge:Audio device manufacturers are expanding procurement of micro-batteries as hearable unit volumes climb across consumer electronics channels.
- REACH Compliance Pathways:Chemical composition disclosure requirements under ECHA frameworks are accelerating supplier qualification upgrades among European cell producers.
- Silicon-Composite Anode Adoption:Lithium nickel manganese cobalt oxide cathodes paired with advanced anode materials are extending cycle life in sub-gram form factors.
Market Restraints
- Cobalt Price Volatility:Raw material cost swings in lithium cobalt oxide supply chains compress margin buffers for premium cell tiers.
- Assembly Concentration Risk:China, Vietnam, and India collectively concentrate fastest assembly demand, creating geographic vulnerability to logistics disruption.
- Energy Density Ceiling:Conventional lithium-ion configurations face physical limits on volumetric improvement without solid-state architecture migration.
Strategic Opportunities
- Smart Glasses Integration:Augmented reality wearable manufacturers are specifying ultra-low self-discharge cells with shape flexibility for frame-embedded power.
- India PLI Scheme Access:Domestic manufacturing incentives under the country's production-linked incentive framework attract cell producers serving export markets.
- GB Standards Alignment:China's MIIT circular economy directives create certification pathways for producers targeting dual domestic and European qualification.
Industry Challenges
- Solid-State Manufacturing Scale-Up:Thin-film deposition expertise scarcity constrains yield rates at pilot production lines.
- Replaceability Design Integration:Mechanical disassembly features add dimensional overhead that conflicts with sub-gram weight targets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | TWS Micro-Battery Market |
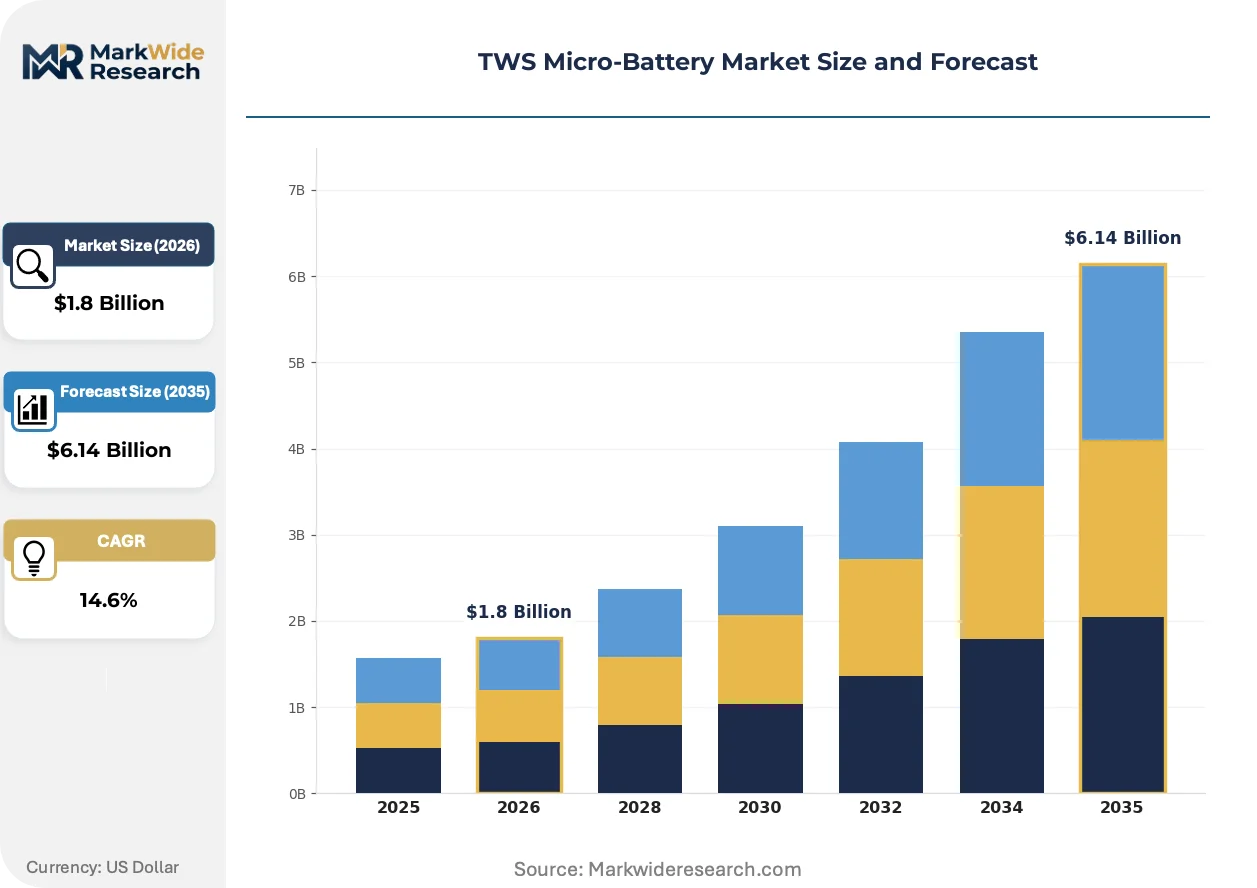
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rechargeable, Non-Rechargeable, Hybrid, Smart Technology: Lithium-Ion, Nickel-Metal Hydride, Solid-State, Lead-Acid End User: Consumer Electronics, Medical Devices, Wearable Technology, Industrial Equipment Application: Audio Devices, Fitness Trackers, Smart Glasses, Communication Devices |
| Companies Covered | Murata Manufacturing Co., Ltd., Panasonic Corporation, Samsung SDI, TDK Corporation, Cymbet Corporation, Ultralife Corporation, Maxell Ltd., VARTA AG, Enfucell, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
TWS Micro-Battery Market Trends and Innovations
Electrochemical architectures are pivoting toward solid-state platforms while regulatory compliance frameworks reshape supplier qualification criteria across major demand centers.
Solid-state electrolyte technology is converging with stacked electrode manufacturing to eliminate flammability risks in compact lithium cells. Premium TWS audio tiers are piloting these configurations for 40% energy density gains over conventional liquid-electrolyte designs. The structural consequence is compressing development timelines for silicon-anode integration as manufacturers race to commercialize solid-state formats before 2030 qualification windows.
EU Battery Regulation recycled content mandates are restructuring material sourcing protocols for small-format cells entering European supply chains. Cell producers must now document due diligence across cobalt and lithium supply chains to maintain market access. German-engineered micro-cylindrical formats face the steepest compliance ramps given their channel dominance among European audio OEMs.
Direct procurement relationships between audio device manufacturers and cell producers are displacing tiered distributor networks in high-volume TWS segments. Contract structures now specify cycle-life guarantees and carbon footprint disclosure rather than spot-price flexibility. This pattern concentrates most visibly in Vietnam and India assembly corridors where vertically integrated hearable brands negotiate captive supply agreements.
TWS Micro-Battery Market Segmentation
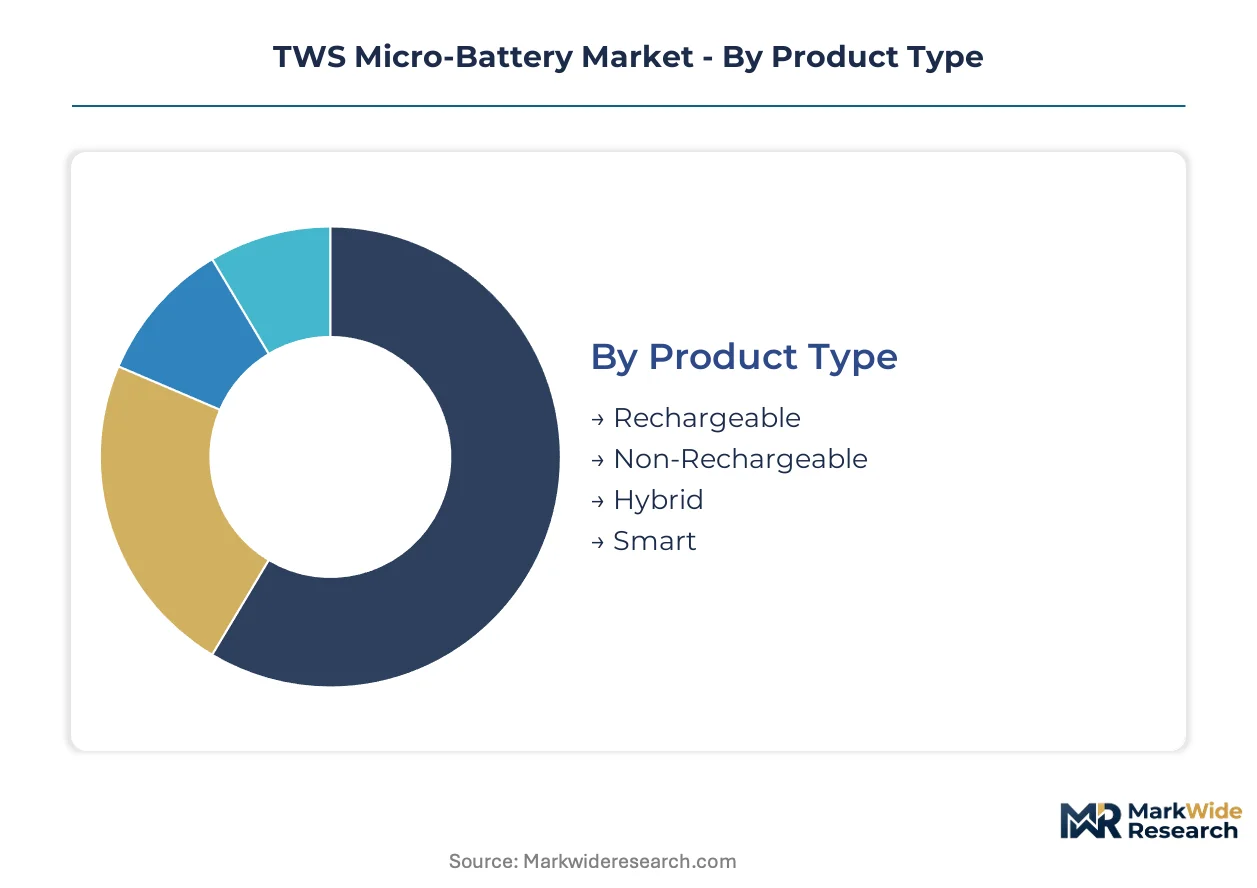
TWS micro-battery procurement patterns diverge sharply across electrochemical configurations and device integration requirements. Each segmentation axis reveals distinct margin pools, certification burdens, and supplier qualification thresholds that reshape competitive positioning.
Product Type:
Standardization pressure intensifies toward the rechargeable end of this spectrum, while premium tiers demand customized smart-cell architectures with embedded battery management systems.
- Rechargeable:Lithium-ion cells rated 30-100 mAh dominate TWS earbud volumes through established cylindrical and pouch formats. Panasonic Corporation and Samsung SDI anchor supply relationships with audio OEMs in Vietnam and India assembly corridors.
- Smart:Integrated protection circuits and fuel-gauge telemetry command pricing premiums in premium hearable tiers. VARTA AG engineers German micro-cylindrical variants with embedded management systems for European audio brands navigating EU Battery Regulation replaceability mandates.
- Non-Rechargeable:Primary lithium manganese dioxide cells serve disposable medical and industrial niches where charging infrastructure is absent.
- Hybrid:Dual-chemistry architectures combine primary backup with rechargeable cycling for mission-critical wearable applications.
Most installed capacity flows through Rechargeable. Expansion is steepest in Smart.
Technology:
Cost tier stratification separates mature liquid-electrolyte platforms from emerging solid-state architectures chasing energy density breakthroughs.
- Lithium-Ion:Liquid-electrolyte lithium cobalt oxide and lithium nickel manganese cobalt oxide configurations deliver proven volumetric density in sub-gram form factors. Chinese and Vietnamese contract manufacturers concentrate assembly demand for these cells serving mid-tier TWS brands.
- Solid-State:Thin-film ceramic electrolytes eliminate flammability risks while enabling silicon-anode integration for 40% density gains. Samsung SDI pilots stacked electrode solid-state formats for premium audio tiers targeting commercialization before qualification windows tighten.
- Nickel-Metal Hydride:Mature chemistry persists in cost-sensitive fitness tracker segments where energy density requirements are modest.
- Lead-Acid:Micro-format variants occupy negligible TWS share, limited to industrial backup applications outside consumer hearables.
Volume concentrates in Lithium-Ion. Solid-State claims the steepest expansion trajectory as manufacturers race yield improvement timelines.
End User:
Application maturity and regulatory exposure separate consumer-scale procurement from medical-grade certification burdens.
- Consumer Electronics:TWS earbuds and hearables concentrate the largest demand share through direct procurement relationships between audio brands and cell producers. Vietnam and India PLI corridors attract vertically integrated supply agreements specifying cycle-life guarantees and carbon footprint disclosure.
- Medical Devices:Hearing aids and diagnostic wearables impose FDA and EMA biocompatibility standards that extend qualification timelines. VARTA AG leverages German engineering protocols to sustain channel control among European medical OEMs.
- Wearable Technology:Fitness bands and health monitors bridge consumer and medical tiers with intermediate reliability requirements.
- Industrial Equipment:Ruggedized headsets and communication gear prioritize thermal stability over energy density in harsh-environment deployments.
Consumer Electronics absorbs most cell output. Medical Devices is climbing the fastest as hearing aid digitization accelerates micro-battery integration.
Application:
Form factor flexibility requirements distinguish audio-centric cylindrical formats from shape-constrained smart glass architectures.
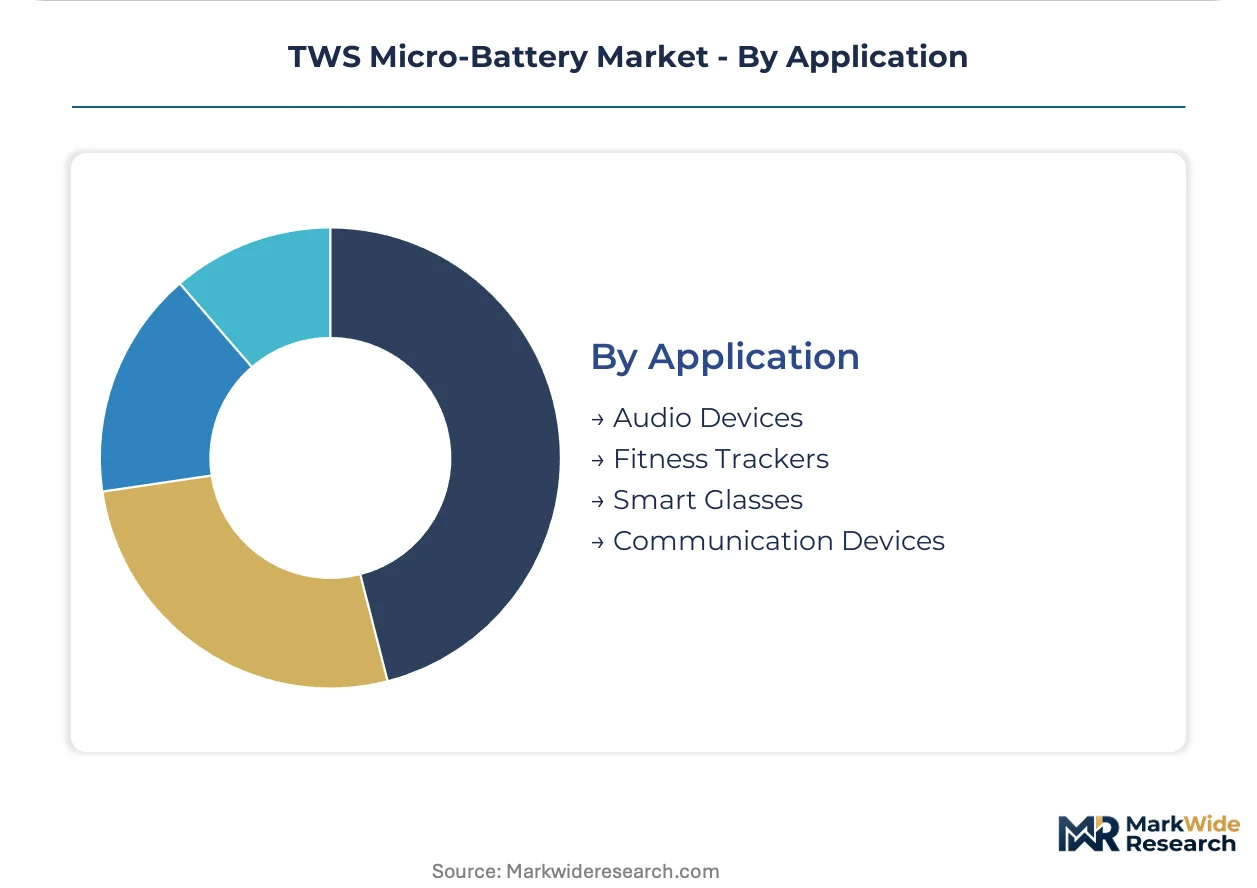
- Audio Devices:TWS earbuds specify cylindrical and button cells optimized for charging case integration with 500+ cycle life targets. China, Vietnam, and India collectively concentrate fastest assembly demand for these compact lithium-ion configurations.
- Smart Glasses:Augmented reality frames demand ultra-thin curved cells with sub-1% monthly self-discharge rates. Solid-state technology captures emerging margin pools as manufacturers chase frame-embedded power without flammability risks.
- Fitness Trackers:Rectangular pouch cells dominate wrist-worn form factors with moderate energy density requirements.
- Communication Devices:Push-to-talk headsets and professional audio gear prioritize thermal runaway protection in continuous-use scenarios.
Audio Devices channels most production volume. Smart Glasses is gaining share fastest as AR hardware shipments accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engineering talent pools in battery electrochemistry and precision manufacturing anchor geographic competitiveness across three continents. Cell producers cluster near hearable assembly corridors to minimize logistics friction and accelerate qualification cycles. Regulatory divergence between EU, Chinese, and Indian frameworks is fragmenting supplier certification requirements.
China
GB standards alignment and MIIT circular economy directives shape domestic cell production protocols for export eligibility. Shenzhen and Dongguan industrial clusters concentrate cylindrical lithium-ion capacity serving mid-tier TWS brands. The Yangtze River Delta hosts thin-film deposition specialists advancing solid-state pilot lines for premium audio tiers.
Vietnam
Production-linked incentive frameworks attract vertically integrated hearable brands negotiating captive supply agreements. Bac Ninh and Bac Giang provinces anchor the fastest-growing assembly demand for compact lithium-ion cells. Samsung SDI maintains supply relationships with audio OEMs operating in these northern industrial corridors.
Germany
EU Battery Regulation replaceability mandates and ECHA due diligence requirements restructure cost-of-entry calculus for European cell suppliers. VARTA AG engineers micro-cylindrical formats in Ellwangen and Nördlingen for audio OEMs navigating recycled content thresholds. The Baden-Württemberg precision manufacturing cluster sustains channel control through German-engineered qualification protocols.
India
PLI scheme access attracts cell producers targeting export markets from domestic manufacturing bases. Tamil Nadu and Karnataka host emerging assembly corridors where audio brands specify cycle-life guarantees and carbon footprint disclosure. BIS certification pathways align with MIIT directives for producers seeking dual domestic and European qualification.
United States
FCC electromagnetic compatibility regulations govern device integration requirements for cells entering consumer electronics channels. California and Texas industrial clusters concentrate on medical-grade hearing aid battery qualification under FDA biocompatibility standards. The Southwest hosts specialty cell producers serving ruggedized industrial headset applications prioritizing thermal stability.
TWS Micro-Battery Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across a bifurcated supplier base. Panasonic Corporation and Samsung SDI anchor premium tiers through material supply chain control and proprietary electrode architectures. Three strategic archetypes dominate: Japanese and Korean diversified electronics groups, German precision engineering specialists, and emerging thin-film technology ventures. Competitive moves concentrate on backward integration into cathode material production and strategic partnerships with audio OEMs for captive supply allocation.
Within the diversified electronics tier, Panasonic Corporation and Samsung SDI exemplify scale-driven positioning through upstream control over material supply chains. VARTA AG occupies a specialist position among German-engineered micro-cylindrical producers serving European medical and audio OEMs with embedded battery management systems. These three anchors represent distinct competitive vectors: conglomerate scale, geographic regulatory proximity, and precision engineering specialization.
| Leading Market Players |
|---|
| Murata Manufacturing Co., Ltd. |
| Panasonic Corporation |
| Samsung SDI |
| TDK Corporation |
| Cymbet Corporation |
| Ultralife Corporation |
| Maxell Ltd. |
| VARTA AG |
| Enfucell |
| Others |
Pricing and Supply Chain Analysis
EU Battery Regulation recycled content mandates gate qualified supply access and premium-tier pricing eligibility for TWS micro-battery producers serving European audio OEMs. Panasonic Corporation and Samsung SDI leverage upstream cathode material control to sustain margin buffers against compliance cost inflation, while VARTA AG commands German-engineered pricing premiums through embedded battery management systems that satisfy replaceability thresholds.
Pricing Analysis
Bundled certification-and-cycle-life guarantees versus unbundled spot procurement splits the TWS micro-battery pricing landscape. Three-tier pricing structure across premium, standard, and economy levels reflects differentiation by EU Battery Regulation compliance grade and silicon-anode performance tier. Pricing pressure stems from cobalt price volatility in lithium cobalt oxide supply chains, compressing margins for mid-tier cylindrical formats. Contract manufacturers in Vietnam and India exhibit highest price sensitivity, while European medical OEMs accept premium pricing for FDA and EMA biocompatibility-certified cells.
Supply Chain Analysis
Dual-sourcing requirements from audio OEMs mandate multi-supplier qualification across China, Vietnam, and India assembly corridors. Raw material dependencies center on lithium cobalt oxide cathodes, silicon-composite anodes, and ceramic electrolyte precursors for solid-state pilot lines. Single-source vulnerability concentrates in thin-film deposition equipment for solid-state manufacturing, where yield improvement expertise remains scarce. Distribution runs through direct procurement relationships displacing tiered distributor networks, with vertically integrated hearable brands negotiating captive supply agreements in Bac Ninh and Tamil Nadu industrial clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The TWS micro-battery market represents a late-cycle quality story as audio device manufacturers shift procurement specifications toward solid-state energy density and EU Battery Regulation replaceability compliance.
For Market Incumbents: Hedge against solid-state yield improvement timelines by maintaining parallel liquid-electrolyte capacity in Vietnam and India PLI corridors. Samsung SDI and Panasonic Corporation should deepen backward integration into silicon-anode material production to defend margin buffers against cobalt price volatility. Certification investment in ECHA due diligence documentation preserves channel control among European audio OEMs navigating recycled content mandates. For New Entrants and Emerging Players: Capture white-space in smart glasses ultra-thin curved cell specifications where shape flexibility commands pricing premiums absent established supplier relationships. India PLI scheme access offers the most penetrable geography for producers targeting export markets with BIS certification alignment. Go-to-market positioning should emphasize sub-1% monthly self-discharge rate guarantees for augmented reality frame-embedded power applications. For Investors and Strategic Acquirers: Roll-up economics work for thin-film deposition technology specialists because solid-state manufacturing scale-up constraints fragment yield improvement capabilities across multiple pilot-stage ventures. Five-to-ten-year viability hinges on commercialization timelines preceding tightened qualification windows. The signal to watch is audio OEM direct procurement contract structures specifying carbon footprint disclosure rather than spot-price flexibility.| Strategic Initiative | Industry Significance |
|---|---|
| Solid-State Pilot Line Scale-Up | Samsung SDI advances stacked electrode architectures toward commercial viability before regulatory qualification windows tighten. |
| Backward Integration into Cathode Materials | Panasonic Corporation sustains cost discipline across European certification pathways through in-house lithium nickel manganese cobalt oxide production. |
| EU Battery Regulation Compliance Certification | VARTA AG preserves German-engineered channel control among European audio OEMs via ECHA due diligence documentation systems. |
| India PLI Manufacturing Footprint | Cell producers attract vertically integrated hearable brands specifying cycle-life guarantees and carbon footprint disclosure in Tamil Nadu. |
| Smart Glasses Cell Form Factor Development | Solid-state technology captures emerging margin pools as augmented reality manufacturers specify frame-embedded curved cell architectures. |
Research Methodology
Bottom-up audio device procurement modeling reconciled against top-down cell production capacity tracking forms the analytical core of this study. Primary interviews with cell engineering directors, audio OEM procurement leads, ECHA regulatory affairs specialists, and Vietnam PLI scheme administrators combined with secondary validation from MIIT circular economy directives, BIS certification databases, and EMA biocompatibility filings. Top-down triangulation against customs trade data and SEC 10-K supply chain disclosures verified volume assumptions.
Historical trendline analysis of cylindrical and pouch cell shipment patterns informed projection framework construction across the analysis window. Segmentation dimensions modeled include electrochemical configuration, end-use application maturity, and regional regulatory cluster. CAGRs derived from weighted average of technology adoption curves and assembly corridor expansion rates incorporate silicon-anode integration timelines and solid-state yield improvement trajectories as industry-specific forecast inputs.
Cobalt price volatility, solid-state manufacturing yield breakthrough delays, and EU Battery Regulation enforcement variance are the dominant revision risks to forecast assumptions. Deviation in solid-state commercialization timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Asia Pacific Foodservice Paper Packaging Market
Others
Italy Automotive Adaptive Lighting System Market
Others
Industrial Air Purifiers Market
Others
Synthetic Leather Market
Others
Brazil Lime Market
Others
Solar Lighting Tower Market
Others
North America Wiring Duct Market
Others
Military Sensors Market
Others
Spain Automotive LED Lighting Market
Others
Profiling Floats Market
Others
Bimodal Identity Management Solutions Market
Others
Content Experience Platforms Market
Others
Cloud DVR Market
Others
Convertible Shipper Display Market
Others
Pollen Allergy Market
Others
Digital Tattoos Market