
 Italy 3D Printing Construction Market | 2026-2036
Italy 3D Printing Construction Market Size, Share, and Industry Trends Forecast 2026-2036
Italy 3D Printing Construction Market Insights
Modular wall-panel bundling is rebalancing contractor procurement decisions across Italian construction sites. WASP S.r.l. leverages its proprietary Crane WASP system to anchor large-format earth-based printing for low-cost housing prototypes. COBOD International A/S competes through its BOD2 gantry platform, which dominates European concrete printing specifications. Sika AG extends its chemical admixture portfolio to control rheology in 3D-printable cementitious mixes, sustaining material consistency under extrusion stress.
Italy 3D Printing Construction encompasses the additive fabrication of building elements through layer-by-layer deposition of concrete, polymer, or metal feedstocks, typically achieving compressional strengths of 30–60 MPa in cementitious outputs depending on mix design and curing protocol. The technology serves to compress construction timelines, reduce formwork waste, and enable geometric complexity impractical with conventional cast-in-place methods. Concrete product types occupy the dominant volume position due to established supply chains with Italian ready-mix producers, while powder bed fusion in metals captures concentrated margin pools in custom structural connectors and architectural hardware. Material extrusion technology leads deployment counts among Italian contractors, though binder jetting is expanding fastest in precast factory settings where throughput economics favor bed-based processing.
Italy's Ministry of Infrastructure and Transport enforces Eurocode-aligned structural verification for non-standard construction methods, while the National Recovery and Resilience Plan channels public funding toward decarbonized building techniques including additive manufacturing. BIS and CE marking requirements shape material qualification pathways for imported printing equipment and feedstock formulations. Stakeholders must monitor how pending updates to the Italian Building Code integrate performance criteria for layered concrete elements, as this will determine whether public infrastructure tenders open to additive methods or preserve conventional procurement thresholds.
Market Dynamics
Italy's National Recovery and Resilience Plan is redirecting public procurement budgets toward certified additive manufacturing processes, compressing contractor decision timelines and forcing rapid upskilling across Lombardy and Emilia-Romagna construction clusters.
Growth Catalysts
- Green building incentives:Italy's updated National Recovery and Resilience Plan channels public funding toward decarbonized building techniques including additive manufacturing, redirecting municipal infrastructure tenders toward layered concrete methods.
- Material extrusion dominance:Concrete product types leverage established supply chains with Italian ready-mix producers, accelerating adoption timelines for residential developers seeking formwork waste reduction.
- Lombardy demand concentration:Milan's architectural innovation district generates concentrated pilot-project demand, creating demonstration effects that diffuse toward Bologna's construction technology corridor.
Market Restraints
- Structural verification complexity:Italy's Ministry of Infrastructure and Transport enforces Eurocode-aligned structural verification for non-standard construction methods, extending project approval timelines for layered concrete elements.
- Equipment import dependency:BIS and CE marking requirements shape material qualification pathways for imported printing equipment, concentrating supply risk among European gantry platform manufacturers.
- Substitution by conventional precast:Established Italian precast concrete producers compete on unit economics for standardized geometric forms, limiting additive manufacturing to complex or custom architectural elements.
Strategic Opportunities
- Emilia-Romagna corridor expansion:Bologna's construction technology corridor offers underpenetrated demand for earth-based printing prototypes targeting low-cost housing applications.
- Binder jetting factory integration:Bed-based processing technologies capture expanding throughput economics in Italian precast factory settings where batch consistency outweighs field-deployment flexibility.
- Building Code revision anticipation:Pending updates to the Italian Building Code may integrate performance criteria for layered concrete elements, potentially unlocking public infrastructure tenders currently preserving conventional procurement thresholds.
Industry Challenges
- Skilled operator scarcity:Layer-by-layer deposition protocols require specialized training in rheology control and extrusion stress management, creating recruitment bottlenecks for contractors scaling beyond pilot projects.
- Certification timeline compression:CE marking and BIS compliance pathways for novel cementitious mix designs extend material qualification cycles, delaying project mobilization for developers targeting fast-track delivery.
- Legacy system integration:Building information modeling workflows and conventional structural engineering software require adaptation to accommodate non-standard geometric outputs from additive fabrication systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy 3D Printing Construction Market |
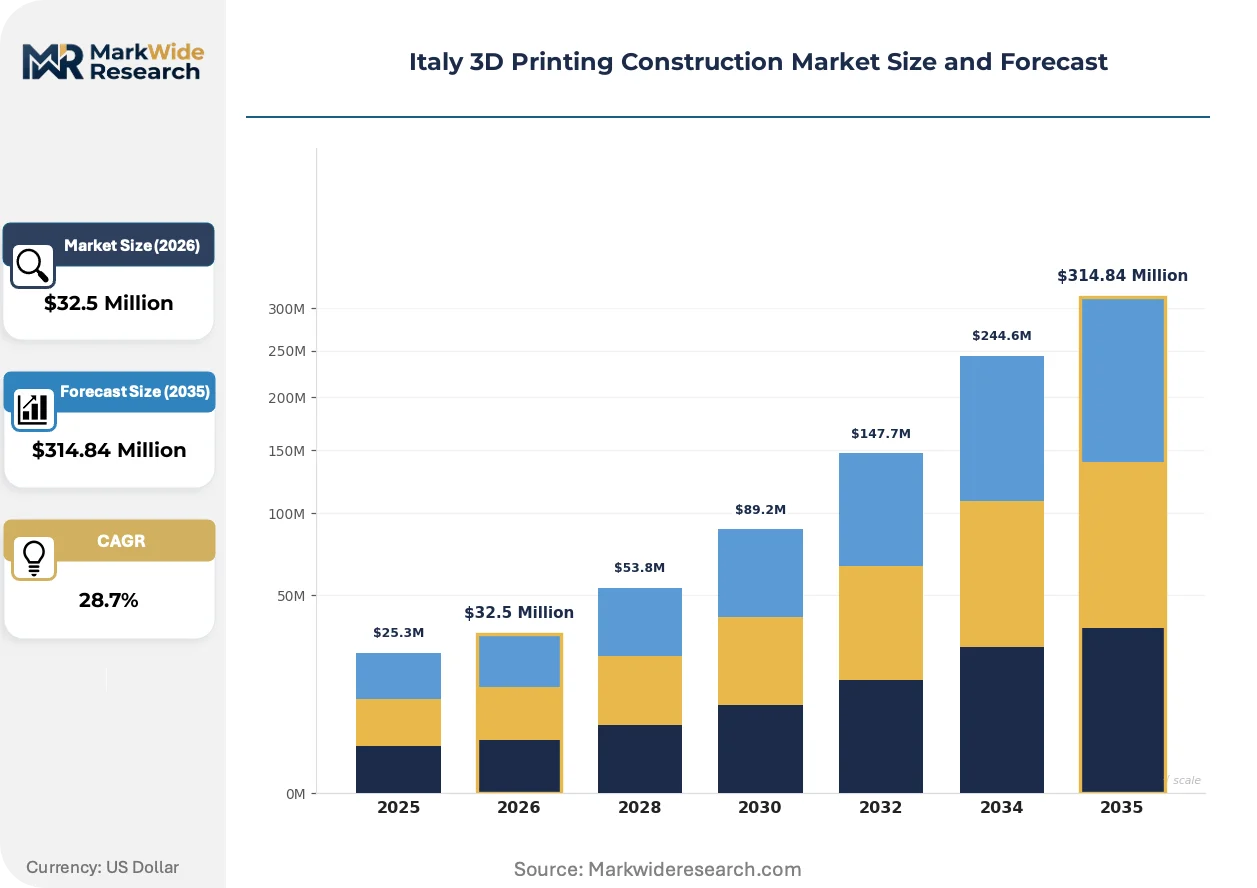
| Market Size in 2026 | $32.5 Million |
| Market Size in 2035 | $314.84 Million |
| CAGR (2026 – 2036) | 28.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Concrete, Plastics, Metals, Composites Technology: Material Extrusion, Powder Bed Fusion, Binder Jetting, Vat Photopolymerization Application: Residential Structures, Commercial Buildings, Infrastructure, Art Installations End User: Contractors, Architects, Developers, Government Agencies |
| Companies Covered | Sika AG, Apis Cor Engineering LLC, WASP S.r.l., MX3D, PERI GmbH, CSP S.r.l., CyBe Construction B.V., BATIPRINT 3D, COBOD International A/S, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy 3D Printing Construction Market Trends and Innovations
Material science advances and regulatory framework evolution are compressing the gap between additive manufacturing demonstration projects and commercial-scale deployment across Italian residential and infrastructure segments.
Earth-based printing formulations are decentralizing construction material sourcing by enabling on-site utilization of locally excavated soils, reducing transport emissions and material cost structures. Rural housing cooperatives in Tuscany and Umbria are piloting these systems for affordable dwelling prototypes. This technology is decentralizing supply chain dependencies that previously tethered remote projects to centralized ready-mix concrete batching plants.
Italy's pending Building Code updates for layered concrete performance criteria are forcing structural engineering consultancies to develop specialized verification protocols ahead of formal adoption. The industrial consequence is preemptive capability building among Milan-based engineering firms serving public infrastructure clients. Public procurement offices in northern Italy are most affected, responding by embedding additive manufacturing clauses into future tender specifications.
Architectural design studios are unbundling geometric complexity from cost premiums by specifying printed structural walls for non-orthogonal facade elements. Custom residential developers in Lombardy are displacing traditional stone cladding and GFRC panel systems with monolithic printed walls. This shift is most visible in Milan's architectural innovation district, where competition for signature building envelopes drives specification experimentation.
Italy 3D Printing Construction Market Segmentation
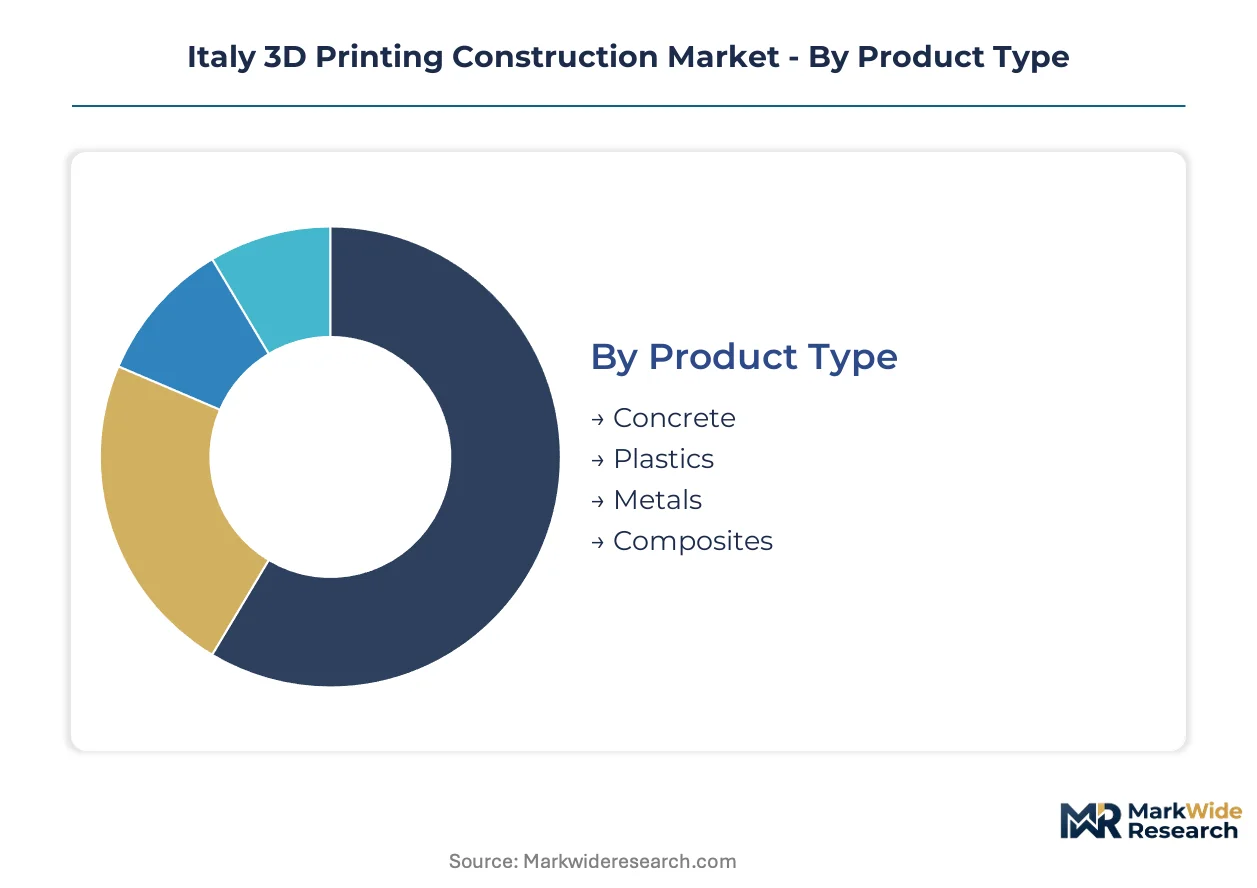
Segmentation in Italy's 3D printing construction market reveals how material choices, technology platforms, and procurement authority distribute across distinct value pools. Understanding these boundaries helps identify where additive methods displace conventional construction and where they remain confined to demonstration projects.
Product Type:
Concrete formulations anchor standalone field deployments, while polymer and metal systems embed into prefabrication workflows or structural connection details. Integration depth varies sharply by material chemistry and supply chain maturity.
- Concrete:Cementitious mixes achieve 30–60 MPa compressional strength through controlled rheology and curing protocols. Lombardy residential developers favor printed structural walls for geometric complexity unattainable with cast-in-place methods, though ready-mix supply chain dependencies concentrate procurement among established Italian producers.
- Metals:Powder bed fusion produces custom structural connectors and architectural hardware with concentrated margin capture. Milan-based engineering consultancies specify titanium and aluminum nodes for signature facade elements where conventional fabrication costs escalate.
- Plastics:Polymer extrusion serves formwork molds and temporary structural shrouds rather than permanent load-bearing elements. Emilia-Romagna contractors deploy these for rapid-prototyping bridge components before committing to concrete pours.
- Composites:Fiber-reinforced thermosets occupy niche applications in corrosion-resistant cladding and non-structural architectural features. Tuscany housing cooperatives pilot these for earth-based printing hybrid systems.
Volume placements concentrate in Concrete; the faster expansion belongs to Metals.
Technology:
Cost tier stratification separates gantry-based field systems from capital-intensive factory platforms, with distinct customer bases and margin structures at each level.
- Material Extrusion:Layer-by-layer deposition of paste or filament feedstocks dominates Italian contractor deployment counts. WASP S.r.l.'s Crane WASP system anchors earth-based printing for low-cost housing prototypes across rural Emilia-Romagna.
- Binder Jetting:Bed-based powder processing captures expanding throughput economics in precast factory settings. Bologna construction technology corridor manufacturers favor these systems where batch consistency outweighs field-deployment flexibility.
- Powder Bed Fusion:Selective laser sintering of metals produces high-precision structural hardware. Milan architectural innovation district specifications drive demand for titanium connector geometries impossible through machining.
- Vat Photopolymerization:Resin-based stereolithography remains confined to detailed architectural modeling and mold fabrication. Italian design studios deploy these for client visualization before committing to full-scale concrete printing.
Capital deployment clusters in Material Extrusion; Binder Jetting gains share fastest as factory integration accelerates.
Application:
Customer type segmentation distinguishes speculative residential development from public infrastructure procurement, with divergent risk tolerances and certification timelines.
- Residential Structures:Single-family and multi-unit housing projects exploit geometric freedom for non-orthogonal walls and integrated mechanical chases. Lombardy custom home builders displace GFRC panel systems with monolithic printed envelopes.
- Commercial Buildings:Office and retail facades leverage additive methods for signature architectural expression. Milan's architectural innovation district generates concentrated pilot demand for complex facade elements.
- Infrastructure:Bridges, retaining walls, and utility structures face extended approval timelines under Italy's Ministry of Infrastructure and Transport Eurocode verification requirements. Pending Building Code updates may unlock public tender participation.
- Art Installations:Temporary and permanent sculptural elements bypass structural load-bearing certification. Tuscany and Umbria cultural commissions fund these as technology demonstration vehicles.
Project flow concentrates in Residential Structures; Infrastructure exhibits the steepest expansion trajectory contingent on regulatory clarity.
End User:
Maturity gradients separate early-adopter architects from risk-averse government procurement offices, with contractors occupying the intermediate adoption position.
- Contractors:Construction firms integrate printing systems for formwork waste reduction and timeline compression. Skilled operator scarcity creates recruitment bottlenecks for Lombardy and Emilia-Romagna clusters scaling beyond pilot projects.
- Developers:Real estate sponsors underwrite technology premiums for marketing differentiation and permitting speed. Milan residential developers spec printed walls to accelerate foundation-to-envelope schedules.
- Architects:Design studios specify additive methods to unbundle geometric complexity from cost escalation. Bologna-based firms serving Emilia-Romagna corridor clients build specialized BIM-to-print workflows.
- Government Agencies:Public procurement offices respond to National Recovery and Resilience Plan incentives by embedding additive manufacturing clauses into future tender specifications. Northern Italian municipalities lead this transition.
Procurement authority concentrates among Contractors; Government Agencies are expanding most quickly as public funding redirects toward certified additive processes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Italian 3D printing construction activity concentrates in northern industrial clusters where equipment manufacturers and material suppliers co-locate, while southern regions remain supply-constrained despite housing demand pressures.
Lombardy
Milan's architectural innovation district generates concentrated pilot-project demand for printed structural walls. The National Recovery and Resilience Plan channels public funding toward decarbonized building techniques, redirecting municipal infrastructure tenders. Custom residential developers in the metropolitan area displace GFRC panel systems with monolithic printed envelopes to accelerate construction schedules.
Emilia-Romagna
Bologna's construction technology corridor offers underpenetrated demand for earth-based printing prototypes targeting low-cost housing applications. Italy's Ministry of Infrastructure and Transport enforces Eurocode-aligned structural verification, extending approval timelines for layered concrete elements. Rural housing cooperatives in the Apennine foothills pilot WASP S.r.l. Crane WASP systems utilizing locally excavated soils.
Piedmont
Turin's industrial heritage supports metal powder bed fusion capabilities for custom structural connectors. CE marking requirements shape material qualification pathways for imported printing equipment, concentrating supply risk among European gantry platform manufacturers. Engineering consultancies in the metropolitan area develop specialized verification protocols for titanium and aluminum architectural hardware.
Veneto
Padua and Verona host precast concrete producers competing on unit economics for standardized geometric forms. BIS compliance pathways for novel cementitious mix designs extend material qualification cycles, delaying project mobilization. Binder jetting systems capture expanding throughput economics in regional factory settings where batch consistency outweighs field-deployment flexibility.
Tuscany
Rural housing cooperatives pilot earth-based printing hybrid systems utilizing fiber-reinforced thermosets for corrosion-resistant cladding. Tuscany cultural commissions fund art installations as technology demonstration vehicles, bypassing structural load-bearing certification. Siena and Florence architectural studios deploy resin-based stereolithography for client visualization before committing to full-scale concrete printing.
Italy 3D Printing Construction Market Competitive Landscape
The competitive structure tilts toward specialized equipment fabricators with proprietary gantry systems and chemical admixture suppliers controlling material rheology. Italian contractors face equipment import dependency concentrated among Danish and Dutch platform manufacturers, while domestic players anchor earth-based printing niches. Three archetypes dominate: gantry system specialists, chemical formulation providers, and hybrid material innovators. Capacity expansion and strategic partnerships represent the dominant competitive moves, with technology licensing emerging as a secondary vector for market access.
Within the equipment fabrication tier, COBOD International A/S and WASP S.r.l. occupy distinct positioning archetypes, with the former exemplifying scale-driven concrete platform deployment and the latter representing specialized earth-based system development. Sika AG anchors the chemical admixture provider category, sustaining material consistency architectures for extrusion-based processes. Among construction technology integrators, PERI GmbH and CyBe Construction B.V. sit within the European gantry platform supply base that Italian contractors depend upon for field-deployment capabilities.
| Leading Market Players |
|---|
| Sika AG |
| Apis Cor Engineering LLC |
| WASP S.r.l. |
| MX3D |
| PERI GmbH |
| CSP S.r.l. |
| CyBe Construction B.V. |
| BATIPRINT 3D |
| COBOD International A/S |
| Others |
Pricing and Supply Chain Analysis
Family-owned mid-cap Italian construction firms anchor regional pricing discipline through captive relationships with local ready-mix concrete suppliers, while their limited balance-sheet capacity constrains bulk purchasing leverage against imported gantry platform manufacturers. This ownership structure reinforces supply loyalty over cost optimization, embedding regional price premiums that persist until public procurement scale breaks material procurement thresholds.
Pricing Analysis
Cost-down pressure on concrete feedstock accelerates as Lombardy residential developers consolidate purchase volumes through consortium structures, compressing margins for independent contractors. Project-based pricing dominates field deployments, with differentiation hinging on CE marking tier and after-sales calibration support. Price erosion runs through standard-grade material extrusion systems as Bologna corridor manufacturers achieve batch consistency economies. Government procurement offices exhibit lowest price sensitivity, prioritizing certification compliance over unit cost.
Supply Chain Analysis
Direct-to-contractor channels handle hyperscale gantry platform demand from Lombardy and Emilia-Romagna construction clusters, bypassing distribution intermediaries for field-service integration. Equipment supply concentrates in Denmark, the Netherlands, and Italy, with COBOD International A/S and WASP S.r.l. anchoring opposing technology archetypes. Raw material dependencies center on Portland cement clinker, chemical admixtures from Sika AG, and precision-milled metal powders for structural connectors. Single-source vulnerability in gantry control systems creates procurement risk for Italian contractors scaling beyond pilot projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Italy's 3D printing construction market operates under acute skilled operator scarcity, with trained rheology technicians commanding wage premiums that prop equipment utilization pricing across Lombardy and Emilia-Romagna clusters.
For Market Incumbents: Lock in supply agreements with Emilia-Romagna earth-based printing cooperatives before National Recovery and Resilience Plan funding redirects procurement toward certified additive processes. Prioritize backward integration into chemical admixture formulation to defend margin position against Sika AG's rheology control dominance. Counter COBOD International A/S's BOD2 platform expansion by embedding proprietary Crane WASP servicing capabilities within regional contractor training programs. For New Entrants and Emerging Players: Binder jetting factory integration offers the most penetrable wedge for precast manufacturers in Veneto seeking throughput economics without field-deployment complexity. Target Tuscany rural housing cooperatives with earth-based printing hybrid systems utilizing locally excavated soils, bypassing ready-mix supply chain dependencies that tether established competitors. Lead with BIM-to-print workflow specialization as the go-to-market angle for Bologna-based architectural studios serving Emilia-Romagna corridor clients. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap equipment fabricators with proprietary gantry systems and installed base in northern Italy's construction technology corridor. Long-term viability hinges on regulatory clarity from pending Italian Building Code updates for layered concrete performance criteria. Monitor CE marking acceleration timelines for novel cementitious mix designs as the inflection signal for public infrastructure tender participation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Chemical Admixture Production | Captures rheology control value pool from Sika AG's current dominance in printable cementitious formulations. |
| Regional Training Center Establishment | Addresses skilled operator scarcity bottleneck constraining Lombardy contractor scaling beyond pilot projects. |
| CE Marking Fast-Track Investment | Accelerates material qualification cycles for novel earth-based printing formulations targeting Tuscany housing cooperatives. |
| Precast Factory Binder Jetting Deployment | Captures throughput economics in Veneto batch-processing settings where consistency outweighs field flexibility. |
| BIM-to-Print Workflow Certification | Unlocks specification preference from Milan architectural studios competing for signature facade element commissions. |
Research Methodology
Italian Ministry of Infrastructure and Transport regulatory filings, Eurocode-aligned structural verification protocols, and National Recovery and Resilience Plan procurement documentation formed the secondary backbone for market sizing and policy trajectory assessment. Primary interviews with construction technology integrators, ready-mix concrete procurement leads, gantry platform field engineers, and architectural specification directors validated deployment counts and pricing structures. Bottom-up equipment shipment tallies from Lombardy and Emilia-Romagna clusters were triangulated against top-down public funding allocation disclosures.
Historical trendline analysis of material extrusion system deployments across the projection horizon informed adoption curve modeling for residential and infrastructure segments. Segmentation dimensions included product type, technology platform, application category, and end-user maturity gradient. CAGRs were derived from equipment capacity utilization rates and public procurement clause penetration. Industry-specific inputs incorporated Italian Building Code revision anticipation effects and CE marking pathway timelines for novel cementitious formulations.
Several conditions sit outside the modeled scope, including potential retroactive Eurocode enforcement changes and sovereign debt stress impacts on municipal infrastructure budgets. Forecasts reflect assumptions regarding regulatory clarity timelines and skilled labor training program scaling. Periodic stress-testing of base assumptions is recommended against Ministry of Infrastructure and Transport certification acceleration or deceleration signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
US Mobile MRI Services Market
Others
Cathode Battery Material Market
Others
Consumer Video Feedback Software Market
Others
Solar Animal Repeller Market
Others
Heavy Duty Vacuum Bottle Market
Others
Infant Positioning Aids Market
Others
Vortexers Market
Others
Asia-Pacific Air Separation Unit Market
Others
Football Sportswear Market
Others
France Automotive LED Lighting Market
Others
Calendered Polyvinyl Chloride Flexible Films Market
Others
Shisha Tobacco Market
Others
Global Lavender Extracts Market
Others
High Voltage Measuring Equipment Market
Others
South Korea Intellectual Property Market
Others
Global Smartphone ODM Market