
 Portable Valve Actuator Market | 2026-2036
Portable Valve Actuator Market Size, Share, and Industry Trends Forecast 2026-2036
Portable Valve Actuator Market Analytics
German actuator foundries and precision-machining clusters are broadening output capacity for battery-powered portable units. Rotork leverages its Bristol headquarters to sustain R&D intensity in intelligent actuator electronics. Emerson Electric anchors North American demand through its deep channel presence in oilfield services. Auma competes aggressively on modular electric designs for water infrastructure retrofit programs.
A portable valve actuator is a self-contained, transportable electromechanical or fluid-power device that generates specified torque output—typically 10 to 100,000 Nm—to rotate or linearly stroke a valve stem without permanent installation; it enables temporary or emergency flow intervention across pipelines, tanks, and process skids. Electrical actuators dominate unit shipments due to their plug-and-play compatibility with existing power infrastructure, while pneumatic variants retain margin strength in explosive atmospheres where intrinsically safe operation is mandatory. Safety shutoff applications command premium pricing because failure-mode certification to functional safety standards represents a significant barrier to supplier entry.
The EU Machinery Directive and ATEX framework shape product design rules for portable actuators sold into European process industries, while the EPA's lead and copper rule revisions in the United States accelerate municipal investment in non-invasive valve automation that avoids excavation. ISO 5210 and IEC 61508 provide the global baseline for mounting interfaces and safety integrity levels that manufacturers must satisfy for cross-border market access. Stakeholders should monitor how battery energy density improvements and wireless position-feedback integration alter the total-cost-of-ownership calculus against fixed-installation alternatives.
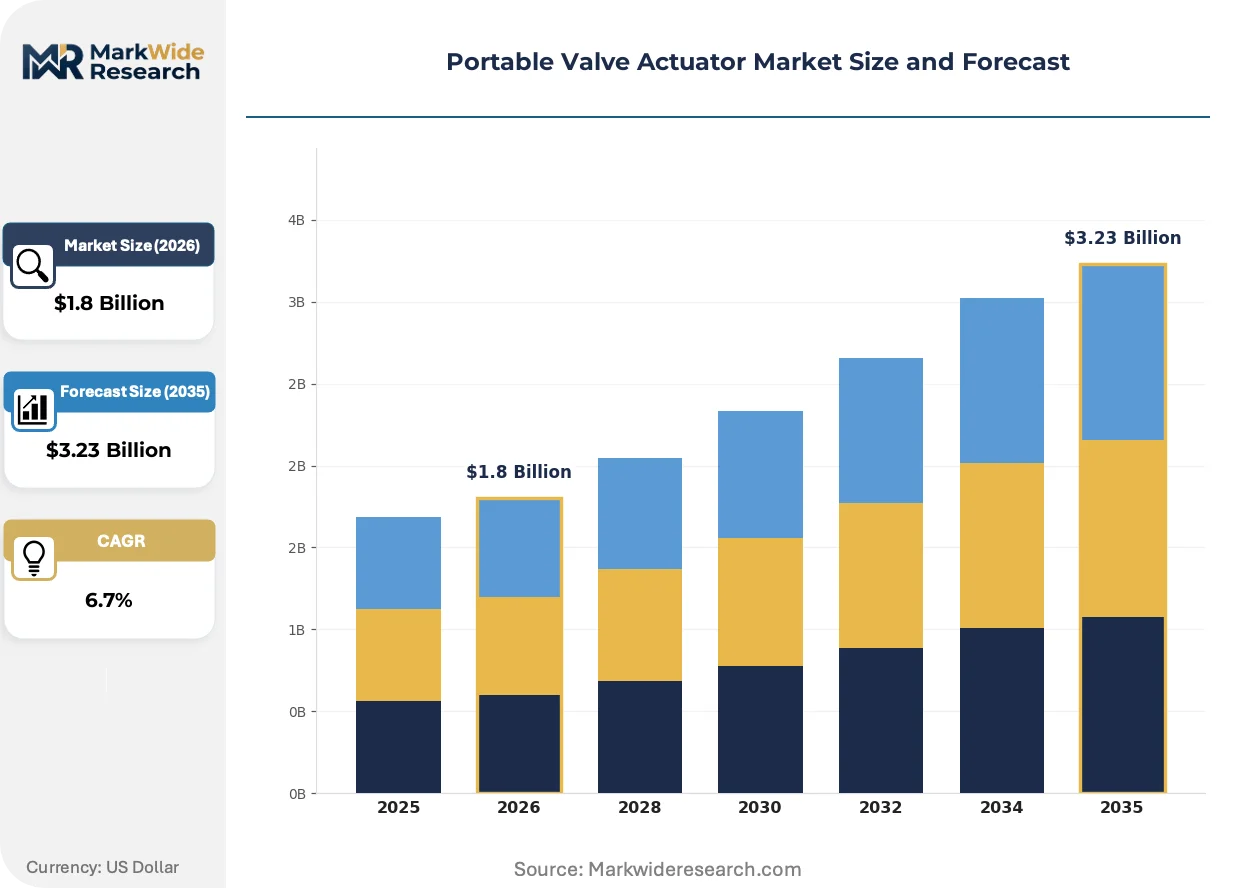
Market Dynamics
The portable valve actuator market faces intensifying pressure from municipal leakage mandates that force utilities toward rapid valve automation without pipeline excavation, compressing deployment timelines and favoring modular battery-powered architectures over fixed-installation alternatives.
Growth Catalysts
- EU Green Deal leakage mandates:German and Australian water utilities are expanding portable actuator fleets to meet stricter distribution-loss targets, creating fleet-scale demand for battery-powered units with wireless feedback.
- Aging US distribution infrastructure:Municipal retrofit programs across the United States require non-invasive valve automation that eliminates shutdown costs, concentrating procurement in electrically actuated portable systems.
- Lithium-ion energy density gains:Improved battery chemistry is extending operational runtime between charges, enabling extended field deployments in remote pipeline segments previously unreachable by cabled power.
Market Restraints
- Rare-earth magnet supply concentration:High-performance electric actuator motors depend on neodymium supply chains centered in China, exposing manufacturers to export restriction risk and price volatility.
- ATEX certification barriers:The EU Machinery Directive and ATEX framework impose extended testing timelines for intrinsically safe pneumatic variants, delaying market entry for new suppliers.
- Fixed-installation substitution:Permanent electric actuators retain total-cost advantages in new-build pipelines, limiting portable unit penetration to retrofit-only applications.
Strategic Opportunities
- India municipal water modernization:The country's urban water distribution networks remain largely manually operated, presenting first-mover potential for portable automation vendors under the Jal Jeevan Mission.
- Wireless position-feedback integration:Convergence of IoT sensors with battery management systems enables predictive maintenance contracts, shifting revenue from hardware sales to recurring service streams.
- EPA lead and copper rule acceleration:Revised US regulations are forcing faster valve replacement cycles, expanding rental and lease channels for temporary actuators during infrastructure upgrades.
Industry Challenges
- Functional safety certification timelines:IEC 61508 SIL verification for safety shutoff applications requires 12-18 month validation cycles, constraining product launch velocity for specialized variants.
- Legacy valve interface incompatibility:Pre-ISO 5210 valve stem geometries in aging US and European infrastructure demand custom adapter fabrication, complicating standardized product rollouts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Portable Valve Actuator Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electrical Actuators, Pneumatic Actuators, Hydraulic Actuators, Manual Actuators End User: Manufacturing, Oil & Gas, Water Treatment, Power Generation Application: Flow Control, Pressure Control, Safety Shutoff, Throttling Installation: On-Site, Off-Site, Remote, Fixed |
| Companies Covered | ABB, Parker-Hannifin Corporation, Rotork, El-O-Matic, Auma, Emerson Electric, Crane Holdings, Easytork Automation Corp, Flowserve Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Portable Valve Actuator Market Evolving Landscape
Battery-powered architectures are displacing pneumatic and hydraulic alternatives across hazardous and remote deployment contexts, while regulatory pressure on leakage and safety integrity compresses procurement cycles toward certified plug-and-play solutions.
Brushless DC motor systems paired with lithium-iron-phosphate battery packs are electrifying torque delivery in compact portable form factors. Water utilities in Germany and Australia are adopting these configurations for extended field operations. This electrification is compressing maintenance intervals and enabling predictive failure alerts through integrated current-signature analysis.
REACH substance restrictions and the EU F-Gas Regulation are phasing out hydraulic fluids with high global-warming potential in European process industries. Manufacturers are reformulating sealed pneumatic circuits and dry-electromechanical alternatives to maintain ATEX compliance. Portable actuator suppliers serving North Sea oilfield services are accelerating electric platform development to preempt regulatory displacement.
Asset-light rental models are displacing capital purchase in municipal water infrastructure programs. German and Australian utilities now specify multi-year lease arrangements with bundled calibration and firmware update services. Equipment distributors in Texas and California are building captive rental fleets to capture recurring revenue from EPA-mandated valve replacement cycles.
Portable Valve Actuator Market Segmentation
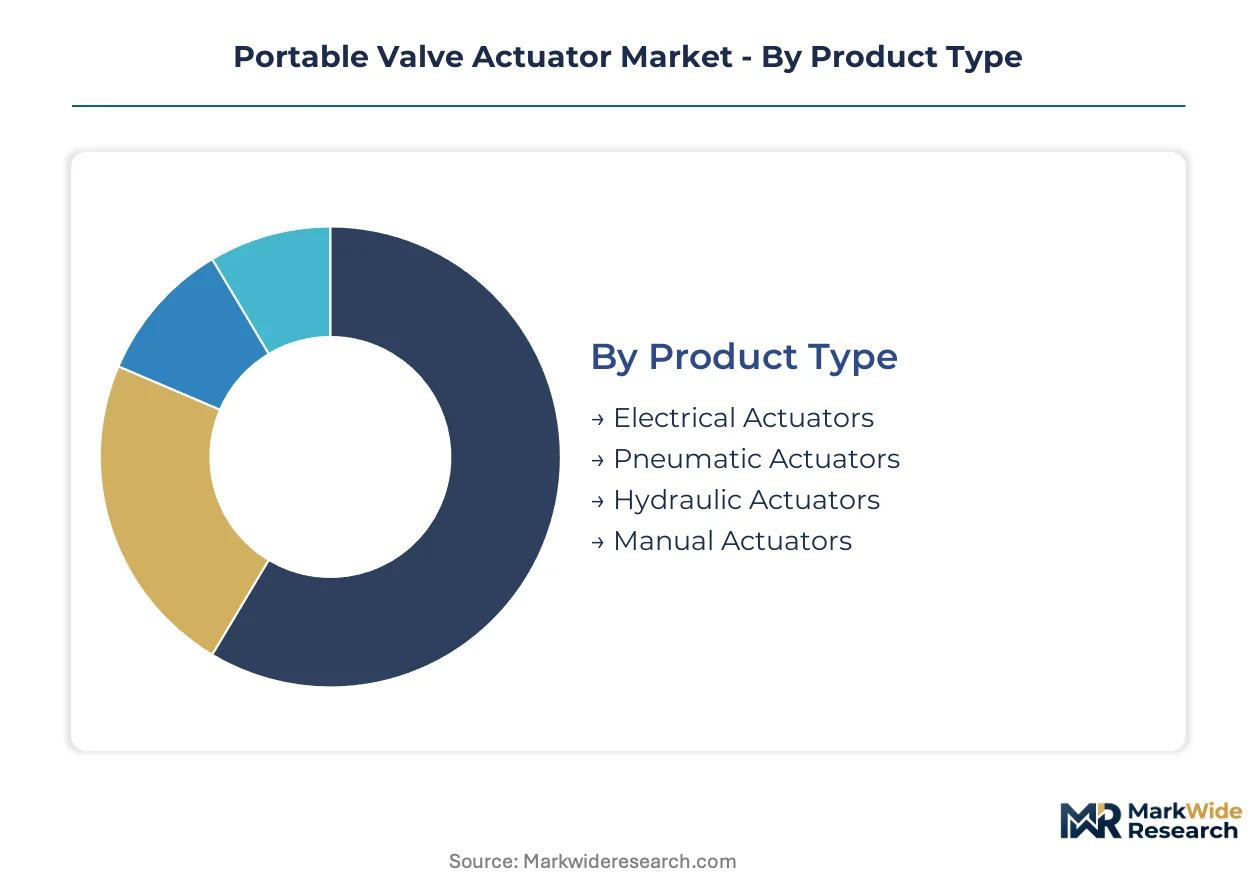
Portable valve actuator segmentation reveals how torque delivery mechanisms, deployment contexts, and safety requirements shape procurement patterns. Understanding these dimensions clarifies why electrical architectures dominate municipal retrofits while pneumatic systems retain defensive positions in explosive atmospheres.
Product Type:
Standalone battery-powered units serve intermittent intervention needs across distributed infrastructure, whereas embedded actuator modules integrate permanently into process skids and treatment trains.
- Electrical Actuators:Brushless DC motor systems paired with lithium-iron-phosphate battery packs deliver 10 to 100,000 Nm torque in self-contained housings. German and Australian water utilities specify these for multi-day field deployments along remote distribution mains, driven by EU Green Deal leakage mandates that prohibit pipeline shutdowns.
- Pneumatic Actuators:Compressed-air systems with spring-return fail-safe configurations operate without ignition sources in ATEX Zone 1 environments. North Sea oilfield services in Norway and the United Kingdom specify these for temporary wellhead interventions, constrained by extended ATEX certification timelines that delay supplier entry.
- Hydraulic Actuators:Fluid-power units generating extreme torque density for large-bore isolation valves in hydroelectric facilities.
- Manual Actuators:Handwheel or lever mechanisms for low-torque emergency override in electrically compromised situations.
Volume placements concentrate in electrical actuators; the faster expansion belongs to battery-powered variants displacing pneumatic alternatives in hazardous zones.
End User:
Capital intensity and regulatory exposure vary sharply across customer categories, with water utilities prioritizing fleet standardization while oilfield operators emphasize rental flexibility.
- Water Treatment:Municipal utilities managing aging distribution networks across the United States deploy portable electrical actuators for non-invasive valve automation. EPA lead and copper rule revisions compress replacement cycles, forcing procurement through lease channels that bundle calibration services.
- Oil & Gas:Upstream operators and midstream pipeline companies rent pneumatic and hydraulic units for temporary flow isolation during maintenance turnarounds. Permian Basin operators in Texas favor asset-light rental models that avoid capital commitment to intermittently used equipment.
- Manufacturing:Process plants requiring rapid valve automation for batch changeovers without line shutdowns.
- Power Generation:Thermal and hydroelectric facilities using portable actuators for turbine isolation during unplanned outages.
Procurement scale tilts toward water treatment; the steepest expansion trajectory runs through oil and gas rental channels.
Application:
Functional safety requirements stratify pricing and certification burdens, with safety-critical applications commanding premium margins due to IEC 61508 compliance costs.
- Safety Shutoff:Fail-safe actuators certified to SIL 2 or SIL 3 integrity levels isolate hazardous flows upon instrument air or power loss. Offshore platforms in the United Kingdom and Norway specify these for emergency isolation valve automation, facing 12-18 month validation cycles that constrain supplier proliferation.
- Flow Control:Modulating actuators with position feedback maintain setpoint throughput in variable-demand distribution networks. German utilities integrate wireless IoT sensors for predictive maintenance, converting hardware transactions into recurring service revenue.
- Pressure Control:Fast-acting actuators responding to transient overpressure events in pipeline surge protection.
- Throttling:Precision positioning systems for process optimization in chemical manufacturing.
Revenue concentration sits with safety shutoff; wireless-enabled flow control is gaining share fastest.
Installation:
Deployment location determines power architecture and connectivity requirements, with remote installations driving battery chemistry innovation.
- On-Site:Portable units transported to valve locations for temporary attachment via ISO 5210 mounting interfaces. Australian utilities deploy these across suburban Sydney and Melbourne networks, avoiding excavation costs under national leakage reduction frameworks.
- Remote:Battery-powered systems operating beyond grid access in rural pipeline segments or offshore installations. Improved lithium-ion energy density enables multi-day runtime in Western Australian mining corridors previously unreachable by cabled power.
- Off-Site:Actuator testing and calibration facilities preparing units for field deployment.
- Fixed:Semi-permanent installations bridging temporary and permanent automation needs.
Deployment frequency clusters in on-site applications; remote configurations are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rare-earth magnet processing clusters in Jiangxi Province anchor upstream supply for electric actuator motors, while precision-machining districts in Germany and foundry corridors in the United States shape downstream assembly capacity across three continents.
United States
Municipal water utilities in Texas and California are scaling rental fleets for EPA-mandated valve replacement cycles under revised lead and copper rules. The EPA's enforcement timeline compresses procurement windows toward asset-light lease models. Equipment distributors in Houston and Los Angeles are building captive rental inventories to capture recurring service revenue from accelerated infrastructure upgrades.
Germany
Water treatment operators in Bavaria and North Rhine-Westphalia are expanding battery-powered portable actuator deployments to meet EU Green Deal leakage reduction targets. The EU Machinery Directive and ATEX framework shape product certification requirements for intrinsically safe variants. Stuttgart-area precision-machining clusters are broadening output capacity for lithium-iron-phosphate battery pack integration in compact electromechanical housings.
Australia
Utilities across suburban Sydney and Melbourne networks are adopting on-site portable units to avoid excavation costs under national water loss frameworks. The country's infrastructure regulators are tightening distribution-main integrity standards comparable to EU benchmarks. Western Australian mining corridors are driving remote-installation demand where improved battery energy density enables multi-day runtime beyond grid access.
United Kingdom
North Sea oilfield services in Aberdeen and Norwegian adjacent waters specify pneumatic actuators for temporary wellhead interventions in ATEX Zone 1 environments. The UK's offshore safety regulator enforces extended certification timelines that delay supplier market entry. Bristol-headquartered engineering groups are sustaining R&D intensity in intelligent actuator electronics for safety-critical applications.
India
Urban water distribution networks in Maharashtra and Gujarat remain largely manually operated, presenting first-mover automation potential under the Jal Jeevan Mission. The country's Bureau of Indian Standards is developing alignment with ISO 5210 mounting interfaces for cross-border equipment compatibility. Mumbai and Ahmedabad municipal corporations are piloting portable electric units for non-invasive valve automation in dense urban corridors.
Portable Valve Actuator Market Competitive Landscape
Global majors compete with regional champions across certification depth and channel proximity to municipal procurement offices. The supplier base organizes into three tiers: integrated industrial conglomerates with multi-product process automation portfolios, specialized actuator houses with deep valve-interface engineering heritage, and emerging battery-system integrators attacking the electrification vector. Competitive moves center on strategic partnerships with water utility fleet operators and geographic expansion through distributor captive rental programs.
Among diversified industrial technology groups, ABB and Emerson Electric exemplify scale-driven archetypes with broad channel presence across oilfield services and municipal infrastructure segments. Rotork occupies a position within the specialized engineering tier, leveraging UK-based electronics development capabilities. Auma represents the modular electric design specialist competing aggressively on water infrastructure retrofit specifications. These three anchors illustrate how competitive positioning stratifies between conglomerate breadth and focused actuator engineering depth.
| Leading Market Players |
|---|
| ABB |
| Parker-Hannifin Corporation |
| Rotork |
| El-O-Matic |
| Auma |
| Emerson Electric |
| Crane Holdings |
| Easytork Automation Corp |
| Flowserve Corporation |
| Others |
Value Network & Pricing Analysis
Certification-grade divergence between SIL-rated safety shutoff units and standard flow-control variants manifests in both procurement premiums and supply chain sourcing strategies, with German and Australian water utilities absorbing extended lead times for IEC 61508-validated components while municipal buyers in Texas prioritize unbundled hardware to minimize capital outlay.
Pricing Analysis
Warranty and calibration bundling separates German utility lease arrangements from spot-market transactions in North American oilfield services. Three-tier pricing structure across premium, standard, and economy levels reflects SIL certification grade and battery chemistry sophistication. Pricing pressure stems from lithium-iron-phosphate cell cost compression as Chinese cathode capacity expands. Municipal water treatment operators exhibit highest price sensitivity, whereas North Sea offshore platforms accept substantial premiums for ATEX-validated fail-safe configurations.
Supply Chain Analysis
Single-source vulnerability sits with Jiangxi Province rare-earth magnet processing for brushless DC motor stators. Neodymium feedstock draws from Chinese separation facilities, lithium carbonate from Chilean salares, and precision-machined housings from Stuttgart-area metalworking clusters. Export restriction risk on magnetic alloys constitutes the dominant supply chain exposure. Distribution runs through captive rental fleets built by Houston and Los Angeles equipment distributors serving EPA-mandated replacement cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Portable valve actuator competition has become a vertical-integration race, with upstream control over battery pack assembly and downstream captive rental channels representing the decisive margin levers separating consolidated leaders from component assemblers.
For Market Incumbents: Extend firmware development capabilities to capture recurring service revenue from predictive maintenance contracts, while adding lithium-iron-phosphate cell integration capacity in Germany or the United States to reduce exposure to Chinese cathode supply concentration. Battery-system integrators and specialized actuator houses threaten margin compression through modular electric designs. For New Entrants and Emerging Players: Equipment rental distributors represent the critical channel partner for penetrating municipal water infrastructure programs in Texas and California. White-space opportunity concentrates in India's Jal Jeevan Mission pilot corridors, where ISO 5210-compatible portable electric units face minimal installed-base competition. Asset-light lease positioning with bundled calibration services offers the most penetrable go-to-market angle. For Investors and Strategic Acquirers: Re-rating potential sits with battery-system integrators possessing lithium-iron-phosphate pack assembly expertise given electrification displacement of pneumatic alternatives in hazardous zones. Long-term viability favors suppliers with dual capability in SIL-certified safety electronics and wireless IoT feedback integration. Watch for EPA enforcement acceleration on lead and copper rule timelines as the inflection signal for rental fleet expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Chemistry Integration | In-house lithium-iron-phosphate pack assembly reduces supply concentration risk from Chinese cathode processors. |
| Captive Rental Fleet Buildout | Houston and Los Angeles distributors capture recurring revenue from EPA-mandated valve replacement cycles. |
| SIL Certification Investment | IEC 61508 validation creates 12-18 month barriers against commoditized flow-control competitors. |
| Wireless IoT Platform Development | Predictive maintenance contracts convert hardware transactions into recurring service revenue streams. |
| Geographic Expansion Through Local Assembly | Stuttgart-area precision machining clusters support EU Green Deal leakage mandate compliance with reduced logistics exposure. |
Research Methodology
Document review covered regulatory filings with EPA and EU Machinery Directive databases, complemented by interviews with municipal water utility maintenance directors, oilfield services procurement managers, and precision-machining cluster operations heads. Secondary validation drew from customs trade data, SEC 10-K disclosures, and Bureau of Indian Standards technical committee records. Bottom-up unit shipment estimates triangulated against top-down infrastructure investment projections across the analysis window.
Segmentation outputs reflect torque delivery mechanism, end-user capital intensity, functional safety requirement, and deployment location dimensions modeled throughout the forecast period. CAGRs derived from regression analysis against municipal leakage mandate enforcement timelines and battery energy density improvement curves. Forecast inputs incorporated EU Green Deal implementation pace and EPA lead and copper rule revision acceleration scenarios.
Caveats apply where rare-earth export restrictions, ATEX certification timeline extensions, or fixed-installation substitution in new-build pipelines could materially shift the outlook. Forecasts reflect documented assumptions about regulatory enforcement intensity and battery chemistry cost trajectories. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Valves
Global Valves in Oil and Gas Industry Market
Valves
Valve Seat Inserts Market
Valves
Steel Cylinder Market
Valves
Pressure Gauge Market
Valves
Europe Vacuum Insulated Pipe Market
Valves
Global Stainless Steel Control Valves Market
Valves
Industrial Valves and Actuators Market
Valves
Railway Emergency Valves Market
Valves
US Water & Wastewater Valves Market
Valves
Cathodic Protection Market
Valves
Asia-Pacific Medium Voltage Switchgear Market
Valves
Global Plug Valve Market
Valves
Pup Joint Market
Valves
Explosion Isolation Valves Market
Valves
Axial and Radial Seals Market
Valves
Fluid Handling Systems Market