
 Europe Butterfly Valve Market | 2026-2036
Europe Butterfly Valve Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Butterfly Valve Market Intelligence
Digital valve monitoring and predictive maintenance integration is fragmenting traditional supply relationships across the Europe butterfly valve landscape. Emerson Electric Co. leverages its automation portfolio to bundle intelligent valve diagnostics with hardware sales. KSB SE & Co. KGaA anchors its position through backward integration into precision casting operations in Germany. Alfa Laval Corporate AB differentiates via hygienic design expertise serving pharmaceutical and food processing installations.
A butterfly valve is a quarter-turn rotational motion valve employing a disc-mounted shaft to regulate, throttle, or isolate fluid flow, with pressure ratings typically spanning PN10 to PN40 and temperature ranges from -40°C to 200°C depending on seat material and metallurgy. Triple offset designs command premium positioning due to metal-to-metal sealing capability under extreme pressure-temperature cycles, while stainless steel material grades capture expanding share in corrosive chemical processing environments. Wafer-style configurations dominate volume in water treatment retrofit applications where space constraints and cost sensitivity shape procurement.
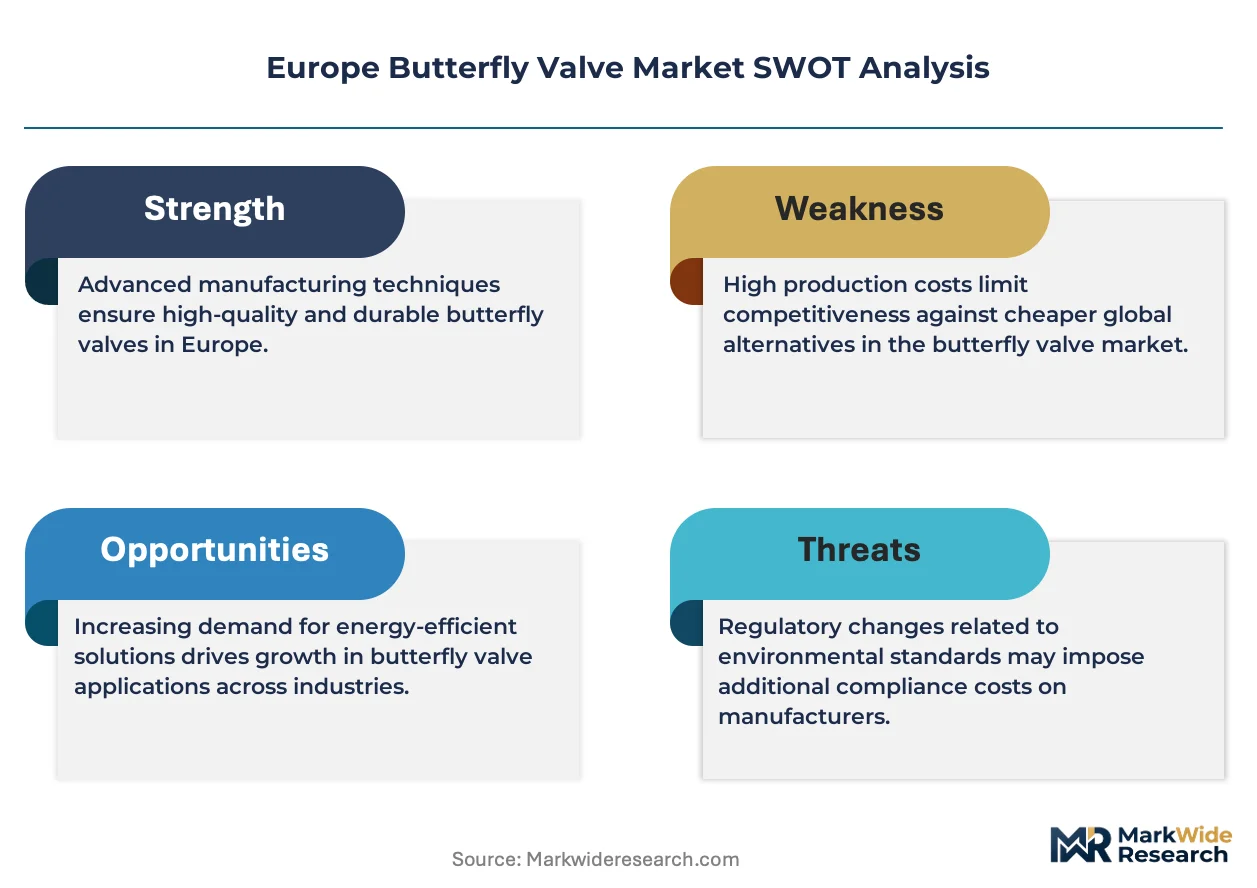
CE marking under the EU Pressure Equipment Directive, REACH compliance for elastomeric seat compounds, and the F-Gas Regulation governing fluorinated polymer emissions collectively tighten product qualification thresholds for market access. ECHA substance restrictions are forcing reformulation of conventional PTFE-based seals toward bio-based or low-GWP alternatives. Stakeholders must weigh certification lead times against the accelerating pace of utility infrastructure modernization across the continent.
Market Dynamics
The EU F-Gas Regulation is compressing traditional fluoropolymer sealing supply chains while accelerating bio-based elastomer qualification programs across continental utilities. Water treatment operators in Germany and France are bundling valve replacement cycles with SCADA upgrades, reshaping supplier qualification criteria.
Growth Catalysts
- Decarbonization mandates:The EU Green Deal and national net-zero targets are forcing industrial process operators to retrofit steam and cooling systems with low-leakage triple offset butterfly valves.
- Water infrastructure modernization:Utilities in Italy and Spain are expanding multi-year valve replacement frameworks to address aging distribution networks.
- REACH compliance:ECHA substance restrictions on conventional PTFE compounds are creating first-mover advantages for suppliers with certified bio-based seal portfolios.
Market Restraints
- Specialty alloy cost volatility:Nickel and molybdenum price swings in stainless steel grades 316L and Duplex 2205 are compressing margin visibility for precision casting operations.
- Foundry concentration:Premium-grade sand casting capacity clusters in northern Italy and western Germany, creating geographic supply vulnerability.
- Technical substitution:Metal bellows seals in high-cycling nuclear applications are displacing conventional butterfly configurations in specific pressure-temperature envelopes.
Strategic Opportunities
- Polish industrial corridor:Petrochemical expansion along the Baltic coast is generating demand for corrosion-resistant stainless steel valves in sulfuric acid service.
- Hydrogen infrastructure:The European Hydrogen Backbone initiative is opening specification windows for high-pressure butterfly valves in compressor station isolation duty.
- Digital retrofit kits:Wireless position sensing modules are creating attach-rate revenue streams independent of new valve hardware sales.
Industry Challenges
- Certification timeline compression:CE marking under the EU Pressure Equipment Directive requires 8-14 month lead times that lag behind utility procurement cycles.
- Legacy system integration:Brownfield installations in French chemical plants require custom actuator mounting adaptations that erode standard product economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Butterfly Valve Market |
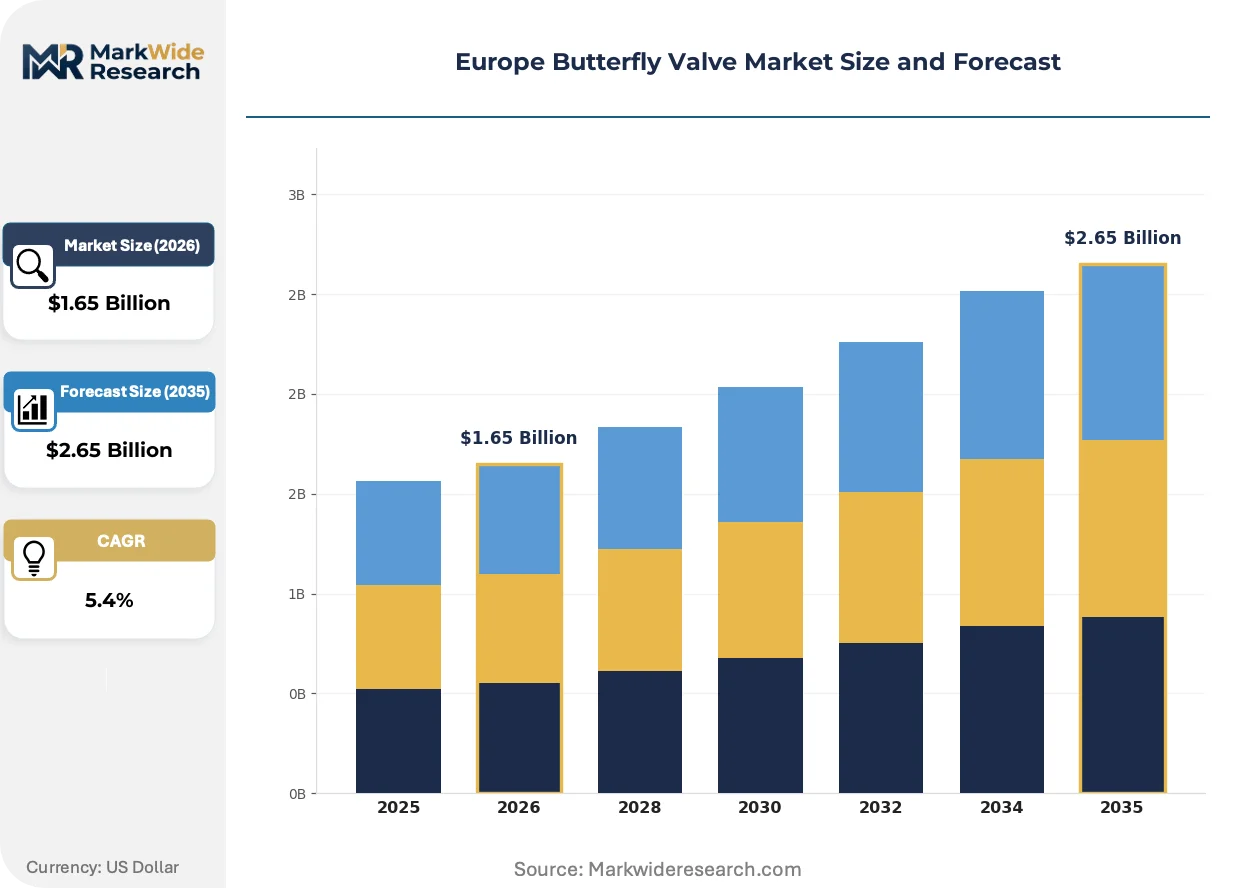
| Market Size in 2026 | $1.65 Billion |
| Market Size in 2035 | $2.65 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wafer, Lug, Double Flanged, Triple Offset Material: Cast Iron, Stainless Steel, PVC, Bronze End User: Water Treatment, Oil & Gas, Power Generation, Chemical Processing Size: 2 inch, 4 inch, 6 inch, 8 inch |
| Companies Covered | AVK Group A/S, Alfa Laval Corporate AB, Flowserve Corporation, Emerson Electric Co., Crane Company, Velan, Inc., KSB SE & Co. KGaA, Weir Group PLC, Zwick Armaturen, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Butterfly Valve Market Strategic Shifts & Innovations
Intelligent valve diagnostics are migrating from premium project specifications to standard utility procurement requirements. The convergence of edge computing and predictive algorithms is compressing traditional maintenance paradigms across European water and energy infrastructure.
Smart positioners with embedded vibration and temperature sensors are digitizing condition monitoring in rotating equipment fleets. Municipal water utilities in the Netherlands and Denmark are deploying these devices at scale to shift from calendar-based to condition-based maintenance. The resulting data streams are digitizing supplier-customer relationships and enabling performance-guarantee contracting models.
The F-Gas Regulation is forcing systematic reformulation of PTFE and FKM seal compounds toward low-GWP alternatives. Compounders in Germany and Belgium are accelerating bio-based fluoroelastomer development to maintain market access. Pharmaceutical and food processing installations face the tightest compliance windows due to hygienic design certification dependencies.
Utility procurement departments are consolidating valve categories into framework agreements with embedded lifecycle service obligations. Engineering contractors in France and Germany are losing specification influence to direct utility-procurement relationships. This consolidation is most visible in German water treatment retrofits where operators now bundle valve, actuator, and monitoring hardware under single-source accountability.
Europe Butterfly Valve Market Segmentation
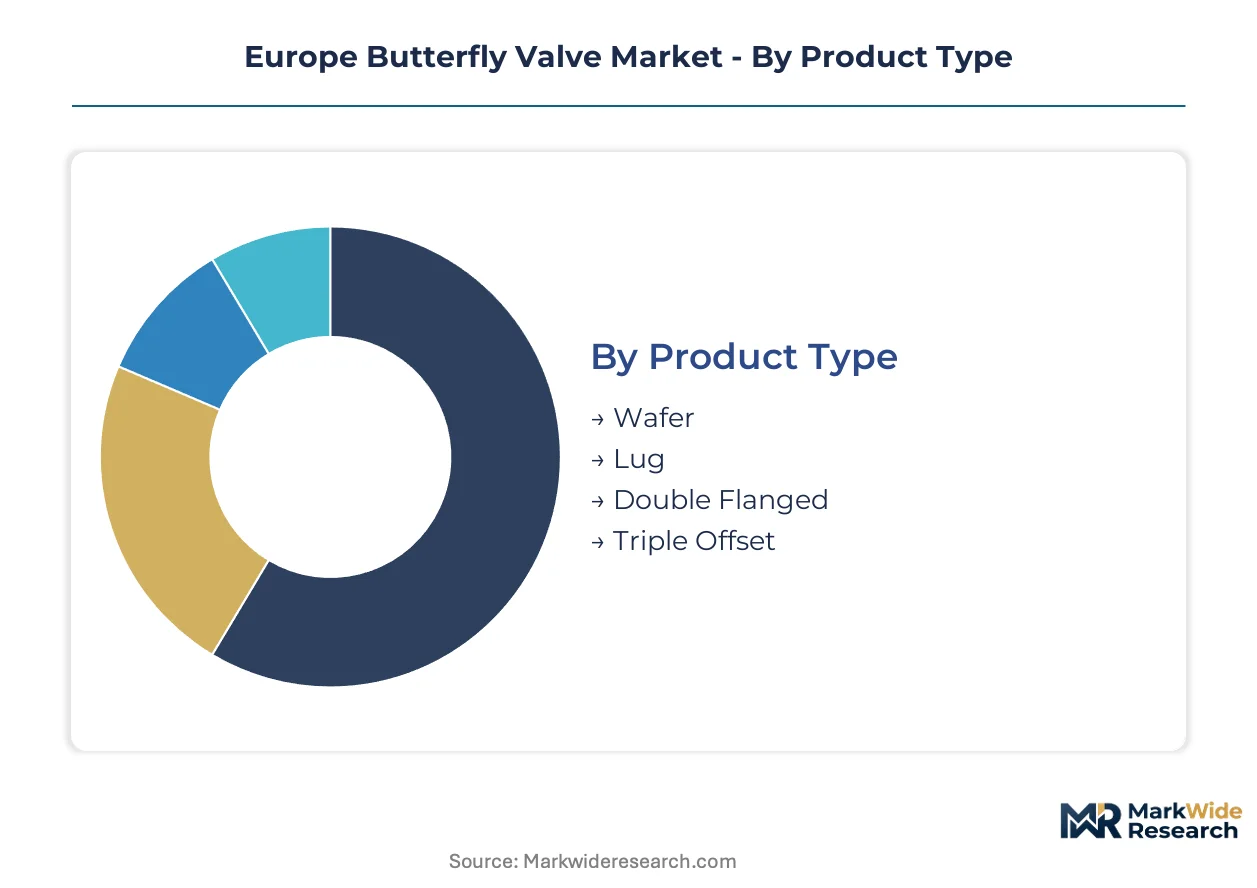
Butterfly valve procurement across Europe fragments along pressure-temperature requirements, corrosion exposure, and installation geometry. Specification engineers weigh initial capital cost against lifecycle sealing performance when mapping segments to utility infrastructure programs.
Product Type:
Mature wafer and lug configurations dominate retrofit volumes while triple offset designs emerge in critical isolation duty.
- Wafer:Compact face-to-face dimensions suit space-constrained water treatment galleries. German utilities specify wafer valves for DN50-DN300 retrofits where actuator access is limited. Municipal procurement frameworks in North Rhine-Westphalia bundle wafer replacements with SCADA actuator upgrades.
- Triple Offset:Metal-to-metal sealing geometry tolerates steam service beyond 200°C. French chemical processors deploy triple offset valves in catalytic reformer isolation loops where fugitive emissions face tightening Bureau Veritas inspection protocols. CE marking under the Pressure Equipment Directive extends lead times for these high-integrity configurations.
- Lug:Threaded insert construction permits dead-end service and downstream maintenance isolation. Italian water authorities favor lug patterns for distribution network sectionalization.
- Double Flanged:Full bolt circle engagement suits high-axial-load piping in petrochemical service. Polish refineries along the Baltic corridor specify double flanged bodies for sulfuric acid transfer lines.
Wafer handles the majority of throughput; triple offset is expanding most quickly on share as decarbonization mandates tighten leakage tolerance.
Material:
Cost tiers separate commodity cast iron from premium alloys, with stainless steel capturing corrosive service migration.
- Stainless Steel:Grades 316L and Duplex 2205 resist chloride attack in desalination and chemical processing. Spanish desalination plants on the Mediterranean coast specify super-duplex trim for seawater intake isolation. Nickel price volatility compresses margin visibility for foundries in northern Italy.
- Cast Iron:Gray and ductile iron bodies serve low-pressure water distribution with epoxy interior linings. Dutch drinking water utilities standardize on EN-GJS-400-15 bodies for transmission mains below 10 bar.
- PVC:Thermoplastic construction eliminates galvanic corrosion in swimming pool and aquarium filtration. Belgian aquaculture installations specify PVC butterfly valves for marine recirculation systems.
- Bronze:Naval brass and aluminum bronze alloys tolerate seawater without cathodic protection. Portuguese shipyards source bronze valves for ballast system retrofit programs.
Cast iron moves the highest unit volumes; stainless steel climbs the fastest as chemical processors replace carbon steel in acid service.
End User:
Application severity determines specification grade, with water treatment standardizing faster than hydrocarbon sectors.
- Water Treatment:Municipal utilities drive scheduled replacement cycles across distribution and treatment infrastructure. Danish water companies bundle valve, actuator, and positioner procurement under ten-year framework agreements. Predictive maintenance integration is shifting from pilot to standard specification.
- Chemical Processing:Aggressive media demand corrosion-resistant metallurgy and specialized seat compounds. REACH compliance deadlines are forcing German chemical parks to audit PTFE-based seal inventories for ECHA-restricted substances.
- Oil & Gas:Pipeline isolation and tank farm duty require fire-safe certification to API 607. Norwegian offshore platforms specify tested configurations for hydrocarbon containment.
- Power Generation:Steam condensate and cooling water circuits balance thermal cycling against cost. Combined cycle plants in Italy source resilient-seated valves for heat recovery steam generator bypass.
Water treatment handles the majority of throughput; chemical processing shows the steepest specification upgrade trajectory as ECHA restrictions tighten.
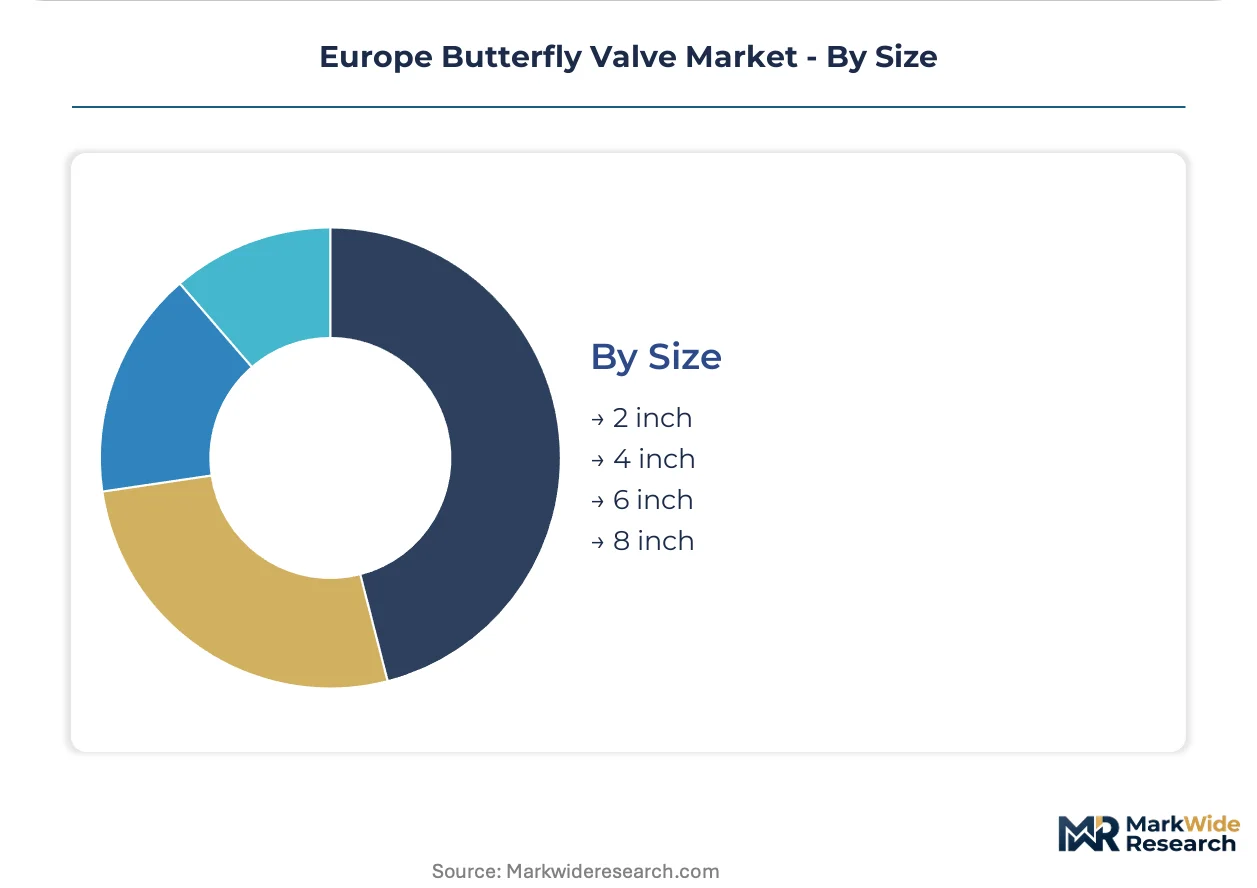
Size:
Volume concentration sits at mid-range diameters where manufacturing economies intersect with installation prevalence.
- 6 inch:DN150 dimensions dominate municipal water branch connections and industrial process laterals. French regional water authorities specify 6-inch resilient-seated valves for district metered area isolation. Foundry tooling amortization favors this diameter for batch production efficiency.
- 4 inch:DN100 service covers building services and small-bore process piping. German HVAC retrofit programs specify 4-inch lug patterns for chilled water isolation.
- 2 inch:DN50 dimensions serve sampling points and instrument isolation. Pharmaceutical cleanrooms in Switzerland specify 2-inch hygienic designs with polished internals.
- 8 inch:DN200 transmission mains require flanged end connections and gear-operated actuation. Spanish irrigation districts source 8-inch double flanged valves for canal distribution networks.
6 inch carries the highest shipment volumes; 8 inch is gaining share fastest as irrigation infrastructure modernization accelerates in southern Europe.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Europe's butterfly valve trade flows reflect a net export position in precision-cast stainless steel components balanced against imports of high-pressure forged bodies from Asian fabricators. Germany and Italy concentrate foundry capacity for premium grades, while utility procurement across the continent drives cross-border equipment flows.
Germany
Municipal water utilities in North Rhine-Westphalia and Bavaria are bundling valve replacement programs with SCADA modernization under ten-year framework agreements. The EU F-Gas Regulation is accelerating bio-based seal qualification timelines for chemical processors in the Ruhr industrial corridor. Foundries in western Germany maintain captive precision casting operations for Duplex 2205 alloy bodies serving desalination projects.
France
French chemical parks in Normandy and the Rhône corridor face REACH compliance deadlines forcing audit of PTFE-based seal inventories for ECHA-restricted substances. Bureau Veritas inspection protocols are tightening fugitive emissions standards for catalytic reformer isolation loops. Regional water authorities in Provence-Alpes-Côte d'Azur are specifying resilient-seated valves for district metered area isolation at scale.
Italy
Italian water authorities are expanding multi-year valve replacement frameworks to address aging distribution networks in Lombardy and Emilia-Romagna. CE marking lead times under the Pressure Equipment Directive extend 8-14 months for high-integrity triple offset configurations. Foundry capacity for premium-grade sand casting clusters in northern Italy, creating geographic supply concentration for European chemical processors.
Spain
Desalination plants on the Mediterranean coast are specifying super-duplex trim for seawater intake isolation as drought intensifies infrastructure investment. Spanish irrigation districts are sourcing double-flanged valves for canal distribution network modernization in Andalusia and Valencia. The national recovery plan is channeling funds toward water transmission main upgrades in high-agriculture regions.
Poland
Petrochemical expansion along the Baltic coast is generating demand for corrosion-resistant stainless steel valves in sulfuric acid service. Polish refineries are specifying double-flanged bodies for high-axial-load piping in new process units. The industrial corridor from Gdańsk to Szczecin is attracting valve distributor investment to serve upstream chemical capacity additions.
Europe Butterfly Valve Market Key Industry Players
On the supply side, the industry is structured around three tiers: multinational automation conglomerates bundling intelligent diagnostics, mid-cap foundry-integrated specialists controlling alloy supply, and regional fabricators serving utility maintenance channels. Strategic archetypes include backward-integrated metallurgy players, hygiene-certified pharmaceutical specialists, and digital retrofit service providers. Dominant competitive moves center on framework agreement consolidation with European utilities and qualification of low-GWP seal compounds ahead of regulatory deadlines.
Among automation-anchored conglomerates, Emerson Electric Co. and Flowserve Corporation exemplify the intelligent valve diagnostics tier where hardware-software bundling is reshaping supplier-utility relationships. KSB SE & Co. KGaA occupies a distinct position through its German foundry-integrated structure, representing the captive metallurgy archetype that insulates margin exposure from nickel price volatility. Alfa Laval Corporate AB sits within the hygienic design specialization vector serving pharmaceutical and food processing installations with polished internal configurations.
| Leading Market Players |
|---|
| AVK Group A/S |
| Alfa Laval Corporate AB |
| Flowserve Corporation |
| Emerson Electric Co. |
| Crane Company |
| Velan, Inc. |
| KSB SE & Co. KGaA |
| Weir Group PLC |
| Zwick Armaturen |
| Others |
Cost & Logistics Intelligence
Foundry undercapacity in northern Italy is compressing lead times for Duplex 2205 castings while simultaneously hardening price postures among precision casting suppliers serving German chemical processors. This utilization squeeze transmits directly into valve body pricing tiers, forcing procurement departments to choose between extended delivery schedules and premium expedite fees.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on CE marking tier and stainless steel grade certification, with triple offset configurations commanding substantial premiums over wafer-style alternatives. Cost compression in standard-grade cast iron segments is intensifying because Dutch water utilities are consolidating procurement into framework agreements with embedded volume discounts. Municipal buyers exhibit highest price sensitivity due to public tender requirements, while pharmaceutical processors prioritize hygienic certification over unit cost.
Supply Chain Analysis
Extended payment terms from 60 to 90 days are becoming standard among German valve distributors sourcing from Italian foundries. Geographic supply concentration clusters in Germany, Italy, and Poland for precision casting capacity. Raw material dependencies draw from nickel, molybdenum, and chromium feedstocks. Single-source vulnerability concentrates in northern Italy's sand casting corridor for premium alloy grades. Distribution runs through authorized distributor networks serving utility maintenance channels and direct framework agreements with municipal operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating across European water utilities as ten-year framework agreements consolidate valve, actuator, and monitoring procurement under single-source accountability. This procurement consolidation fragments supplier influence and compresses margin capture for non-integrated fabricators.
For Market Incumbents: Insulate margin positions through backward integration into precision casting operations in Germany or Poland, countering nickel price volatility that threatens foundry economics. Prioritize bio-based seal qualification ahead of ECHA REACH compliance deadlines to capture first-mover certification advantages as PTFE compound restrictions tighten. For New Entrants and Emerging Players: Build out digital retrofit service capabilities targeting mid-sized French chemical plants with legacy actuator installations requiring custom mounting adaptations. The Polish petrochemical corridor along the Baltic coast represents the most penetrable geography, with sulfuric acid service specifications creating entry points for corrosion-resistant stainless steel specialists lacking incumbent relationships. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across triple offset manufacturing as CE marking timelines extend and metallurgy requirements tighten. Target acquisition candidates include mid-cap foundry-integrated specialists with captive Duplex 2205 supply and established utility framework positions. Monitor ECHA substance restriction announcements as the critical signal for seal compound reformulation inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precision Casting | Captive Duplex 2205 supply insulates KSB and similar players from nickel volatility in northern Italy. |
| Bio-Based Seal Compound Qualification | ECHA REACH compliance deadlines force systematic PTFE replacement ahead of F-Gas Regulation enforcement windows. |
| Digital Retrofit Kit Development | Wireless position sensing modules create attach-rate revenue independent of new valve hardware sales cycles. |
| Framework Agreement Consolidation | Ten-year utility procurement bundles in Germany and Denmark displace engineering contractor specification influence. |
| Hydrogen Infrastructure Certification | European Hydrogen Backbone specifications open high-pressure isolation duty for qualified butterfly valve suppliers. |
Research Approach
Desk research of trade association filings, EU regulatory databases, and foundry capacity registries preceded structured interviews with maintenance directors at municipal water utilities, procurement leads at German chemical parks, and aftermarket service heads at valve distributors. Primary fieldwork with plant engineers and OEM procurement teams was cross-validated against customs data for stainless steel casting imports and SEC disclosures from listed automation conglomerates. Bottom-up shipment estimates by product type and material grade were triangulated against top-down infrastructure investment forecasts.
Forecast assumptions held EU F-Gas Regulation implementation timelines and ECHA substance restriction schedules as fixed boundary conditions across the projection horizon. The analytical framework modeled segmentation dimensions spanning pressure-temperature rating, metallurgy grade, end-use industry, and regional procurement cluster. CAGRs were derived from utility capital expenditure trajectories and replacement cycle analysis. Industry-specific inputs included desalination project pipelines along the Mediterranean coast and hydrogen backbone compressor station specifications.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Asian forged body fabricators or accelerated bio-based compound adoption by compounders in Belgium would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Valves
Directional Control Valves Market
Valves
Motorized Valves Market
Valves
Global Pressure Relief Valves Market
Valves
North America Residential Ball Valves Market
Valves
Air Heated Vaporizer Market
Valves
Asia-Pacific Industrial Valves Market
Valves
Flanges Market
Valves
Valve Remote Control System Market
Valves
Explosion Vents Market
Valves
Expansion Valves Market
Valves
Lined Valves Market
Valves
India Industrial Valves Market
Valves
GCC and MENA Valves Market
Valves
Total Containment Vessels Market
Valves
Pressure Reducing Valve Market
Valves
Emergency Shutdown Valves Market