
 Butterfly Valves Market | 2026-2036
Butterfly Valves Market Size, Share, and Industry Trends Forecast 2026-2036
Butterfly Valves Market Intelligence
Buyer concentration in the municipal water sector is shifting as regional utilities consolidate procurement across metropolitan water districts. Alfa Laval AB leverages its hygienic equipment expertise to anchor positions in pharmaceutical and food-grade valve applications. Emerson Electric Co. competes through its automation-integrated valve portfolios that merge digital positioners with pneumatic actuators. Flowserve Corporation sustains global aftermarket service density across refinery and chemical processing installations.
A butterfly valve employs a circular disc mounted on a rotating shaft to regulate, throttle, or isolate fluid flow within piping systems, with pressure ratings typically spanning ANSI Class 150 through 600 and bore sizes from two inches to over one hundred inches for hydroelectric applications. Triple eccentric designs achieve metal-to-metal sealing with graphite laminates, enabling cryogenic and high-temperature service beyond five hundred degrees Celsius where resilient seats degrade. Stainless steel material grades dominate margin pools in corrosive chemical processing and offshore marine environments, while cast iron variants occupy cost-sensitive water treatment and HVAC distribution networks. Flanged-type configurations lead in oil and gas transmission lines due to pipeline integrity requirements, though wafer-type installations accelerate in building services where space constraints and weight reduction govern specification.
The American Water Works Association publishes C504 standards governing butterfly valve pressure testing and seat leakage rates that shape municipal procurement specifications across North American water authorities. EPA enforcement of maximum contaminant levels under the Safe Drinking Water Act compels utilities to specify corrosion-resistant materials and low-lead bronze alloys in potable water applications. China's Ministry of Ecology and Environment enforces GB national standards for industrial valve emissions that filter market access for imported equipment. Stakeholders must monitor evolving interoperability requirements between intelligent valve actuators and distributed control systems as process industries advance operational technology cybersecurity protocols.
Market Dynamics
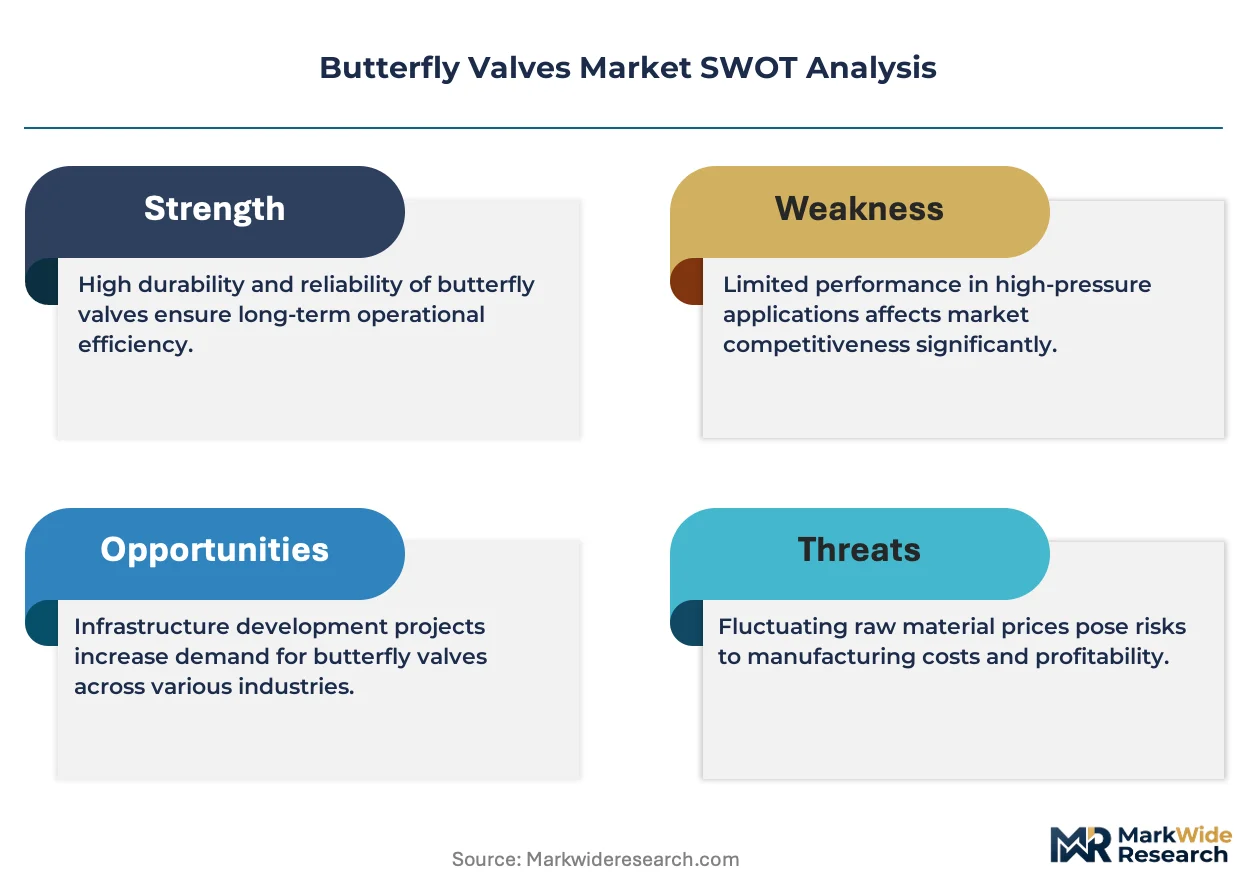
Water infrastructure replacement mandates are compressing procurement cycles as utilities accelerate valve procurement to comply with tightening lead contamination thresholds. Municipal buyers now prioritize corrosion-resistant alloys and intelligent actuator integration over first-cost minimization.
Growth Catalysts
- EPA Lead and Copper Rule Revisions:US water utilities face mandatory lead service line replacement deadlines, triggering bulk orders for low-lead bronze and stainless steel butterfly valve configurations.
- China's Municipal Pipeline Modernization:Cities including Shanghai and Guangzhou are replacing cast-iron distribution networks with resilient-seated valves rated for higher pressure cycling.
- Triple Eccentric Metal Sealing:Graphite-laminated metal-to-metal designs now penetrate cryogenic LNG terminals and high-temperature refinery applications where resilient seats fail.
Market Restraints
- Stainless Steel Price Volatility:Nickel and chromium input cost swings compress margin pools for corrosion-resistant valve grades serving chemical processing.
- Foundry Concentration in China:Over half of global cast valve body production clusters in Shandong and Hebei provinces, exposing supply chains to regional emissions enforcement shutdowns.
- Ball Valve Substitution:Quarter-turn ball designs capture share in high-pressure gas transmission where bubble-tight shutoff outweighs butterfly valve cost advantages.
Strategic Opportunities
- India's Smart City Mission:Urban water automation projects in Pune and Hyderabad specify intelligent butterfly valves with digital positioners for remote pressure management.
- Hydrogen Economy Infrastructure:Pipeline operators in Germany and the Netherlands test cryogenic-rated triple eccentric valves for liquid hydrogen transport at minus 253 degrees Celsius.
- EU F-Gas Regulation Phase-Down:Refrigeration system retrofits accelerate demand for compact wafer-type valves in HVAC replacement cycles across commercial building stock.
Industry Challenges
- Actuator-DCS Integration Complexity:Process industries demand seamless interoperability between intelligent valve positioners and legacy distributed control systems, stretching engineering timelines.
- AWWA C504 Certification Bottlenecks:Municipal procurement specifications require third-party pressure testing documentation that extends qualification periods for new valve designs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Butterfly Valves Market |
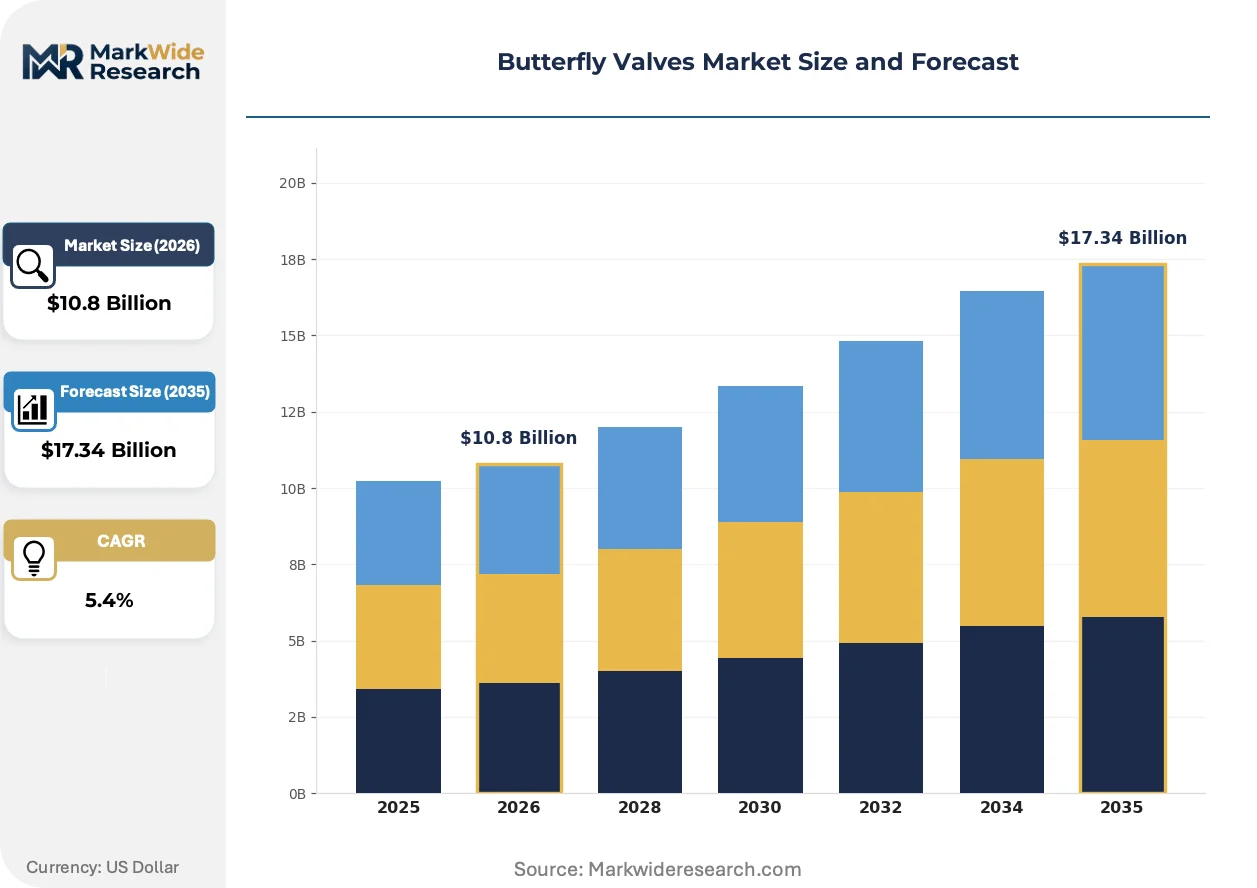
| Market Size in 2026 | $10.8 Billion |
| Market Size in 2035 | $17.34 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
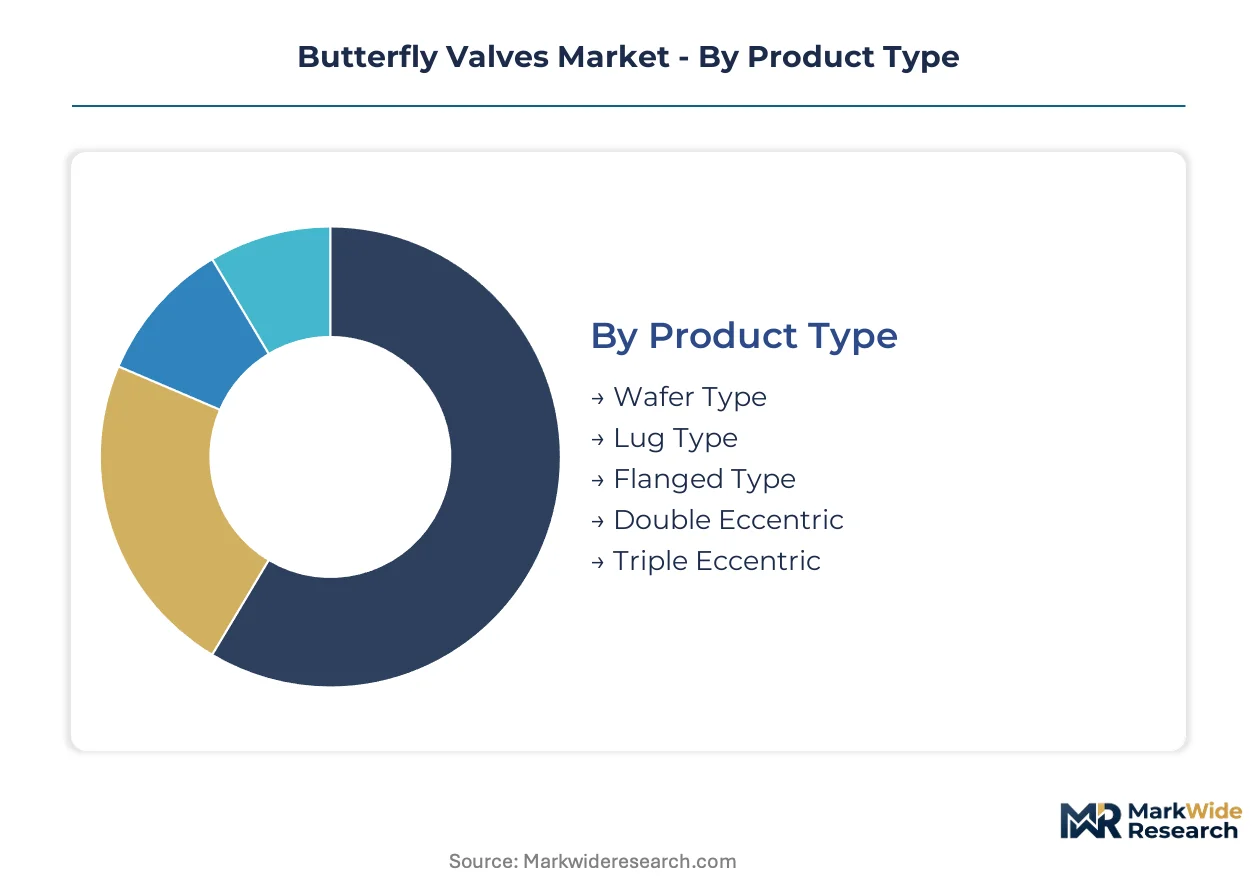
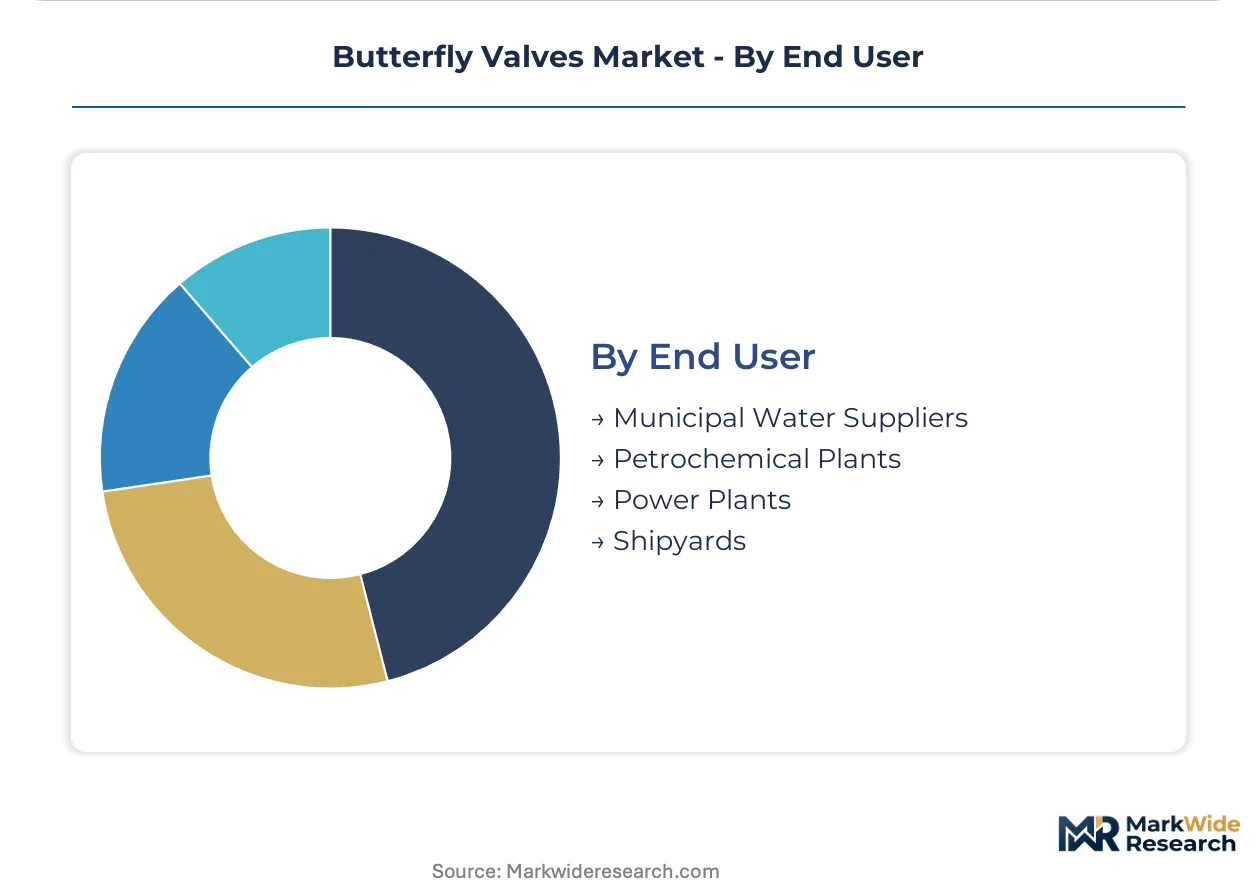
| Segmentation | Product Type: Wafer Type, Lug Type, Flanged Type, Double Eccentric, Triple Eccentric Material: Stainless Steel, Cast Iron, Aluminum Bronze, PVC, Carbon Steel Application: Water Treatment, Chemical Processing, Oil & Gas, Power Generation, Marine End User: Municipal Water Suppliers, Petrochemical Plants, Power Plants, Shipyards |
| Companies Covered | Alfa Laval AB, Crane Company, Emerson Electric Co., KSB SE and Co. KGaA, KITZ Corp., Flowserve Corporation, AVK Holding AS, Georg Fischer Ltd., Bray International Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Butterfly Valves Market Strategic Shifts & Innovations
Digitalization of fluid control infrastructure is redefining valve specification criteria as buyers embed predictive maintenance capabilities into procurement requirements. Electrification of actuation systems and materials science advances are converging to reshape competitive positioning.
Electromechanical actuation is electrifying valve control architectures across water treatment and building automation applications. Municipal utilities in Denmark and Singapore specify 24V DC motorized actuators with Modbus feedback to eliminate compressed air infrastructure. This shift compresses total installed cost for remote valve stations while enabling precise flow modulation for demand-responsive distribution networks.
China's GB national standards for industrial valve emissions are tightening material traceability and fugitive emission testing protocols. The Ministry of Ecology and Environment now requires mill certificates and helium leak testing documentation for imported equipment. European and Japanese manufacturers are responding by establishing local calibration laboratories in Shanghai and Tianjin to accelerate compliance verification.
Metropolitan water districts are consolidating procurement through cooperative purchasing agreements that bypass traditional distributor networks. The Southern California Metropolitan Water District and similar authorities now issue multi-year framework contracts directly to valve manufacturers. This disintermediation concentrates volume with suppliers capable of aftermarket service density across thousands of installation points.
Butterfly Valves Market Segmentation
Butterfly valve specification criteria diverge sharply across pressure ratings, temperature extremes, and corrosion resistance requirements. Procurement patterns in each segment reflect distinct engineering trade-offs between first-cost economics and lifecycle reliability in critical infrastructure.
Product Type:
Design geometry determines sealing integrity, torque requirements, and suitability for bidirectional flow isolation across industrial applications.
- Triple Eccentric:Metal-to-metal sealing with graphite laminates achieves cryogenic and high-temperature service beyond five hundred degrees Celsius. LNG terminals in Germany and the Netherlands specify these designs for liquid hydrogen transport at minus 253 degrees Celsius where resilient seats degrade.
- Wafer Type:Compact face-to-face dimensions and reduced weight dominate building services where space constraints govern specification. Singapore's municipal utilities specify 24V DC motorized wafer valves with Modbus feedback to eliminate compressed air infrastructure in remote stations.
- Flanged Type:Pipeline integrity requirements in oil and gas transmission lines favor bolted flange connections over wafer installations.
- Double Eccentric:Off-center shaft mounting reduces seat wear in high-cycle throttling applications.
- Lug Type:Threaded lugs enable dead-end service and downstream piping removal without system drainage.
Triple eccentric designs lead on momentum; flanged type leads on scale in established hydrocarbon infrastructure.
Material:
Alloy selection balances corrosion resistance against raw material cost volatility and foundry capacity constraints.
- Stainless Steel:Grades 316 and 316L dominate margin pools in corrosive chemical processing and offshore marine environments. Nickel and chromium input cost swings compress margin pools for these corrosion-resistant grades serving refineries along the US Gulf Coast.
- Cast Iron:Ductile iron variants occupy cost-sensitive water treatment and HVAC distribution networks. China's municipal pipeline modernization in Shanghai and Guangzhou favors resilient-seated cast iron replacements rated for higher pressure cycling.
- Carbon Steel:ASTM A216 WCC bodies serve moderate-pressure steam and hydrocarbon applications.
- Aluminum Bronze:Seawater resistance specifies this alloy for desalination intake and marine ballast systems.
- PVC:Thermoplastic construction eliminates galvanic corrosion in aggressive chemical dosing lines.
Cast iron dominates unit volume; stainless steel commands premium positioning in specification-driven process industries.
Application:
End-use severity dictates material grade, actuator integration depth, and aftermarket service density requirements.
- Water Treatment:EPA Lead and Copper Rule revisions mandate low-lead bronze and stainless steel configurations for potable water applications. US utilities face mandatory lead service line replacement deadlines triggering bulk procurement of corrosion-resistant alloys.
- Oil & Gas:Pipeline integrity standards specify flanged metal-seated designs for high-pressure transmission. Aftermarket service density concentrates around refinery clusters in Texas and Louisiana.
- Chemical Processing:Aggressive media specify Hastelloy or titanium trim in acid service.
- Power Generation:Combined-cycle plants specify high-temperature triple eccentric designs for steam isolation.
- Marine:Classification society rules govern material traceability for shipyard installations.
Water treatment leads on volume acceleration; oil and gas retains the steepest expansion trajectory in metal-sealed severe service.
End User:
Procurement concentration and technical specification authority vary sharply across buyer categories.
- Municipal Water Suppliers:Consolidated purchasing through metropolitan water districts bypasses traditional distributor networks. The Southern California Metropolitan Water District issues multi-year framework contracts directly to manufacturers capable of aftermarket density across thousands of installation points.
- Petrochemical Plants:Operational technology cybersecurity protocols demand seamless interoperability between intelligent valve positioners and legacy distributed control systems.
- Power Plants:Cycling duty specifications accelerate demand for triple eccentric metal sealing in combined-cycle facilities.
- Shipyards:Classification society certification timelines extend qualification periods for new valve designs entering marine applications.
Municipal water suppliers lead on procurement consolidation; petrochemical plants drive specification complexity in automation integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States compresses procurement cycles faster than Germany as EPA lead contamination deadlines force bulk valve orders, while China's municipal pipeline replacement outpaces India's nascent smart city automation in absolute volume terms.
United States
Metropolitan water districts in California and Texas consolidate procurement through multi-year framework contracts that bypass traditional distributor networks. The EPA's Lead and Copper Rule revisions mandate mandatory lead service line replacement deadlines. Southern California Metropolitan Water District issues direct manufacturer contracts requiring aftermarket service density across thousands of installation points.
China
Cities including Shanghai and Guangzhou replace cast-iron distribution networks with resilient-seated valves rated for higher pressure cycling. The Ministry of Ecology and Environment enforces GB national standards for industrial valve emissions that filter market access for imported equipment. Foundry concentration in Shandong and Hebei provinces exposes supply chains to regional emissions enforcement shutdowns.
Germany
Pipeline operators test cryogenic-rated triple eccentric valves for liquid hydrogen transport at minus 253 degrees Celsius. The EU F-Gas Regulation phase-down accelerates refrigeration system retrofits demanding compact wafer-type valves. Industrial clusters in the Ruhr and Bavaria anchor hydrogen economy infrastructure development.
India
Urban water automation projects in Pune and Hyderabad specify intelligent butterfly valves with digital positioners for remote pressure management. The Smart City Mission channels central government funding into integrated water distribution networks. Municipal corporations in Maharashtra and Telangana prioritize 24V DC motorized actuators to eliminate compressed air infrastructure.
Singapore
Municipal utilities specify 24V DC motorized wafer valves with Modbus feedback to eliminate compressed air infrastructure in remote stations. The national water agency PUB mandates corrosion-resistant alloys for desalination intake systems. Jurong Island's chemical processing complex drives specification for high-cycle throttling applications.
Butterfly Valves Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. The vendor base stratifies between automation-integrated portfolio providers and fabrication-centric equipment suppliers. Strategic archetypes include electromechanical actuator integrators, severe-service metal-sealing specialists, and municipal water aftermarket service networks. Dominant competitive moves encompass geographic calibration laboratory establishment and cooperative purchasing agreement penetration.
Among diversified industrial conglomerates, Emerson Electric Co. and Flowserve Corporation exemplify automation-integrated positioning. Alfa Laval AB represents hygienic equipment specialization. KSB SE and Co. KGaA and KITZ Corp. occupy positions within pump and valve integrated portfolios. AVK Holding AS, Georg Fischer Ltd., and Bray International Inc. sit within dedicated valve fabrication tiers.
| Leading Market Players |
|---|
| Alfa Laval AB |
| Crane Company |
| Emerson Electric Co. |
| KSB SE and Co. KGaA |
| KITZ Corp. |
| Flowserve Corporation |
| AVK Holding AS |
| Georg Fischer Ltd. |
| Bray International Inc. |
| Others |
Cost & Logistics Intelligence
China's GB national standards for industrial valve emissions now gate qualified supply access and premium-tier pricing power, as compliance documentation requirements filter market entry and concentrate volume with certified manufacturers capable of aftermarket service density across thousands of installation points.
Pricing Analysis
Capacity additions in China's Shandong and Hebei provinces are reshaping price floors for cast iron valve bodies serving cost-sensitive water treatment applications. Three-tier pricing structure across premium, standard, and economy levels separates stainless steel severe-service configurations from ductile iron municipal replacements and PVC thermoplastic dosing lines. Cost compression in standard-grade cast iron intensifies because foundry concentration exposes supply chains to regional emissions enforcement shutdowns. Municipal water suppliers exhibit highest price sensitivity in first-cost procurement, while petrochemical plants prioritize lifecycle reliability over unit economics.
Supply Chain Analysis
Nickel and chromium supply rests on Indonesian mining operations and Chinese refining capacity, with graphite laminate sourcing concentrated among Japanese and German specialty materials producers. Raw material dependencies span nickel alloys for corrosion-resistant grades, ductile iron for municipal water infrastructure, and aluminum bronze for marine ballast systems. Single-source vulnerability in helium leak testing equipment creates qualification bottlenecks for imported valve assemblies entering Chinese market access protocols. Distribution runs through cooperative purchasing agreements that disintermediate traditional distributor networks in favor of direct manufacturer contracts with metropolitan water districts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The butterfly valves market reads as a late-cycle quality story, with procurement patterns shifting toward premium specifications as EPA lead contamination deadlines and China's pipeline modernization compress replacement cycles and elevate corrosion-resistant alloy demand.
For Market Incumbents: Cement aftermarket service density across refinery clusters in Texas and Louisiana to defend against ball valve substitution in high-pressure gas transmission. Deepen backward integration into graphite laminate production to secure supply continuity for triple eccentric metal-sealing designs. Prioritize calibration laboratory establishment in Shanghai and Tianjin to accelerate GB standards compliance verification for imported equipment.
For New Entrants and Emerging Players: Direct-to-utility digital procurement platforms offer white-space penetration around India's Smart City Mission automation projects in Pune and Hyderabad, where municipal corporations prioritize 24V DC motorized actuators with Modbus feedback. Target cryogenic-rated triple eccentric configurations for liquid hydrogen transport infrastructure in Germany and the Netherlands, where pipeline operators test designs at minus 253 degrees Celsius. Lead with electromechanical actuation integration as the primary go-to-market angle.
For Investors and Strategic Acquirers: Roll-up economics work for municipal water aftermarket service specialists because metropolitan district consolidation concentrates procurement volume with suppliers capable of installation base coverage across thousands of points. Long-term viability centers on hydrogen economy infrastructure buildout and smart water automation penetration. Acquisition target archetype: regional valve fabricators with AWWA C504 certification and established utility relationships. Watch EPA enforcement intensity on lead service line replacement deadlines as the primary demand inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Graphite Laminate Production | Secures supply continuity for triple eccentric metal-sealing designs serving cryogenic LNG terminals. |
| Calibration Laboratory Establishment in China | Accelerates GB national standards compliance verification for imported equipment accessing municipal procurement. |
| Electromechanical Actuator Portfolio Expansion | Captures municipal utility demand for 24V DC motorized valves with Modbus feedback in remote stations. |
| Cooperative Purchasing Agreement Penetration | Bypasses distributor networks to secure multi-year framework contracts with Southern California Metropolitan Water District. |
| Hydrogen Economy Infrastructure Qualification | Positions triple eccentric designs for liquid hydrogen transport at minus 253 degrees Celsius in Germany and Netherlands. |
Research Approach
Multiple input streams — primary interviews with plant engineers and OEM procurement teams, aftermarket service heads and municipal water district contracting officers — were reconciled against customs and trade data, AWWA technical standards documentation, and SEC filings from diversified industrial conglomerates. Bottom-up unit shipment estimates across pressure rating tiers and material grades were triangulated with top-down value projections derived from capital expenditure disclosures in water infrastructure and hydrocarbon processing.
Historical shipment patterns were cross-referenced against expert panel input from valve fabricators and actuator integrators to anchor growth trajectory assumptions across the projection horizon. Segmentation dimensions modeled include product geometry, alloy grade, end-use severity, and actuator integration depth. CAGRs were derived from elasticity-adjusted demand curves incorporating EPA regulatory compliance deadlines and China's municipal pipeline replacement schedules.
The model assumes a particular technology adoption path; alternative pathways for electromechanical actuation displacement of pneumatic systems would alter the outlook. Forecasts reflect assumptions around nickel price stability and foundry capacity continuity in China's industrial heartland. A small set of named triggers — EPA enforcement intensity, GB standards expansion, hydrogen infrastructure commissioning timelines — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Valves
Directional Control Valves Market
Valves
Valve Sack Market
Valves
Dense Phase Vessels Market
Valves
Global Level Gauge Market
Valves
Valve Driver Market
Valves
Air Jet Ejectors Market
Valves
Electronic Expansion Valves Market
Valves
North America High Voltage Switchgear Market
Valves
Sanitary Valves Market
Valves
Isolator Valves Market
Valves
Pressure Control Equipment Market
Valves
Air Heated Vaporizer Market
Valves
Insulation Flanges Market
Valves
Transmission Overload Protectors Market
Valves
Liner Regulators Market
Valves
Pipeline Pigging Valves Market