
 Industrial Safety Valves Market | 2026-2036
Industrial Safety Valves Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Safety Valves Market Analytics
The EPA's Risk Management Plan amendments is shifting procurement priorities across downstream processing facilities. Emerson Electric Co. leverages its Fisher valve portfolio to dominate digital positioner integration. Flowserve Corporation anchors its position through specialized alloy casting capabilities for sour service. Baker Hughes competes via its consolidated OneSubsea and surface pressure control heritage.
Industrial safety valves are spring-loaded or pilot-operated mechanical devices engineered to open at predetermined set pressures, typically constructed from ASTM A216 WCC carbon steel or ASTM A351 CF8M stainless steel with elastomer or metal-to-metal seating, designed to vent excess pressure and prevent catastrophic vessel rupture. Relief valves and safety valves occupy the largest installed base due to mandatory overpressure protection in ASME Boiler and Pressure Vessel Code jurisdictions, while control valves capture margin concentration through smart positioner attach rates and diagnostic software subscriptions. Stainless steel material grades lead specification sheets in offshore and corrosive service, though carbon steel sustains volume dominance in standard refinery and power plant steam circuits.
ASME Section VIII and API 526 standards govern set pressure tolerances and orifice designations across North American installations, while the EPA's RMP and OSHA PSM frameworks mandate mechanical integrity programs that force replacement cycles and documentation rigor. The EU Pressure Equipment Directive and ATEX certification requirements shape product access for suppliers serving European chemical clusters. Stakeholders must monitor evolving hydrogen embrittlement standards as ammonia and hydrogen infrastructure scales, since existing valve metallurgy assumptions face recertification pressure.
Market Dynamics
Refinery operators in the Texas and Louisiana petrochemical corridors are accelerating safety valve replacement cycles as EPA Risk Management Plan amendments tighten release prevention documentation requirements and mandate mechanical integrity audits.
Growth Catalysts
- EPA Risk Management Plan Amendments:The EPA's RMP amendments force downstream processing facilities into documented replacement programs, creating pull-through demand for certified relief valve assemblies and digital monitoring packages.
- Hydrogen Infrastructure Scaling:Ammonia crackers and hydrogen pipelines in the Gulf Coast region require recertified valve metallurgies resistant to hydrogen embrittlement, opening specification upgrades across existing installed bases.
- ASME Section VIII Jurisdiction Expansion:Pressure vessel code adoption in emerging chemical processing clusters extends mandatory overpressure protection requirements to new facility constructions and retrofit mandates.
Market Restraints
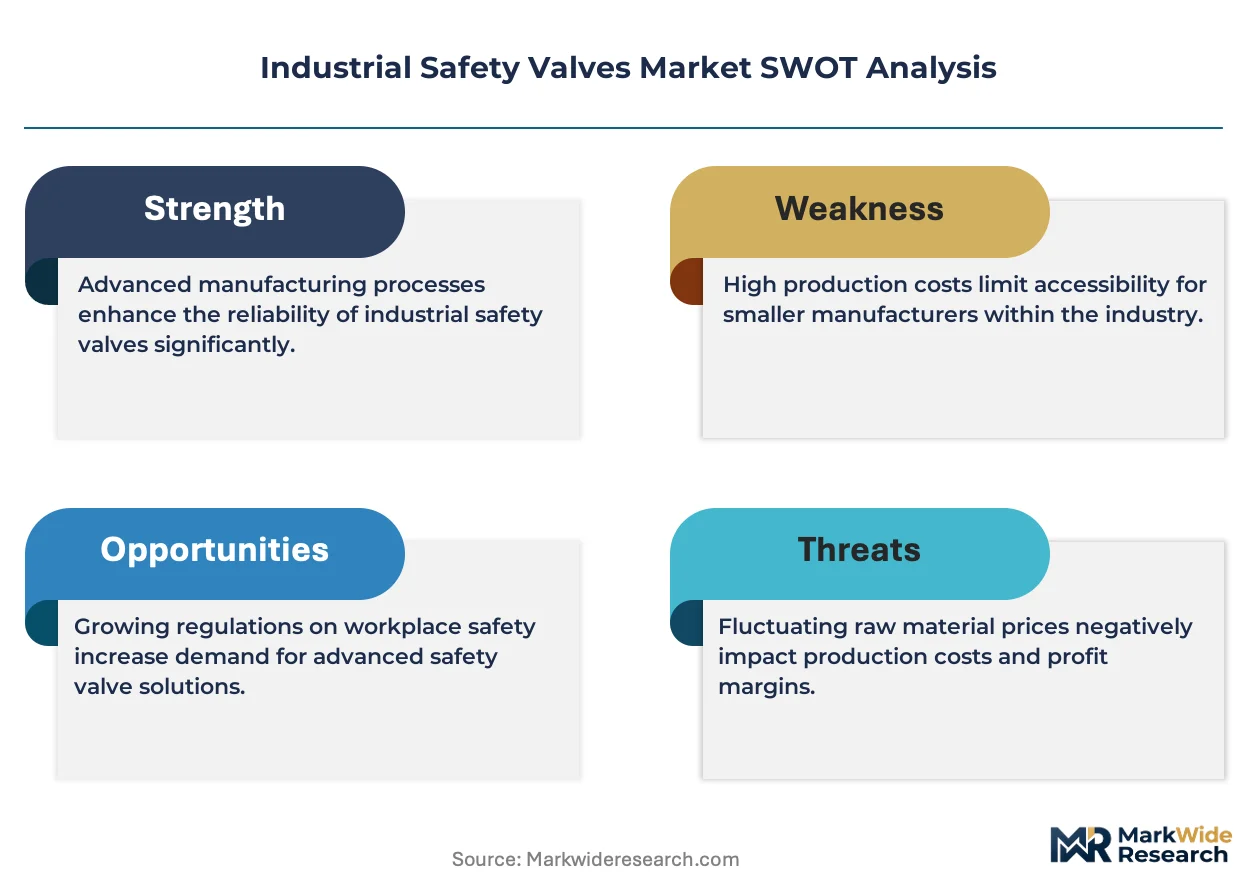
- Specialized Alloy Supply Concentration:Sour service valve castings depend on a limited base of foundries capable of ASTM A217 WC9 and duplex stainless production, creating bottleneck risk in high-nickel alloy procurement.
- Certification Timeline Friction:API 526 and ASME stamp recertification cycles extend 12-18 months for modified designs, slowing product iteration velocity against evolving hydrogen service standards.
- Substitute Pressure Protection:Rupture disk assemblies compete in clean-service applications where zero leakage tolerance outweighs the reusability advantage of spring-loaded relief valves.
Strategic Opportunities
- Digital Positioner Attach Rates:Smart valve diagnostics integrating HART and Foundation Fieldbus protocols enable predictive maintenance subscriptions, shifting revenue toward recurring software and service contracts.
- European Chemical Cluster Access:ATEX certification and EU Pressure Equipment Directive compliance open specification opportunities in Antwerp and Rotterdam refining corridors for suppliers with existing PED module H approvals.
- Ammonia and Hydrogen Service Recertification:Evolving ISO 19880 and regional hydrogen codes create first-mover advantage for valve manufacturers with validated 316L and alloy 625 embrittlement test data.
Industry Challenges
- Welding Inspector Certification Scarcity:ASME Section IX qualified welders and NDE technicians for high-pressure alloy fabrication command premium wages, constraining capacity expansion at specialty foundries.
- Legacy Control System Integration:Digital positioner retrofits into existing DCS architectures require protocol translation gateways, compling deployment timelines and raising commissioning costs.
- Documentation Rigor Under OSHA PSM:Mechanical integrity programs mandate valve testing records spanning equipment lifecycles, forcing distributors and end-users into database migrations and audit trail investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Safety Valves Market |
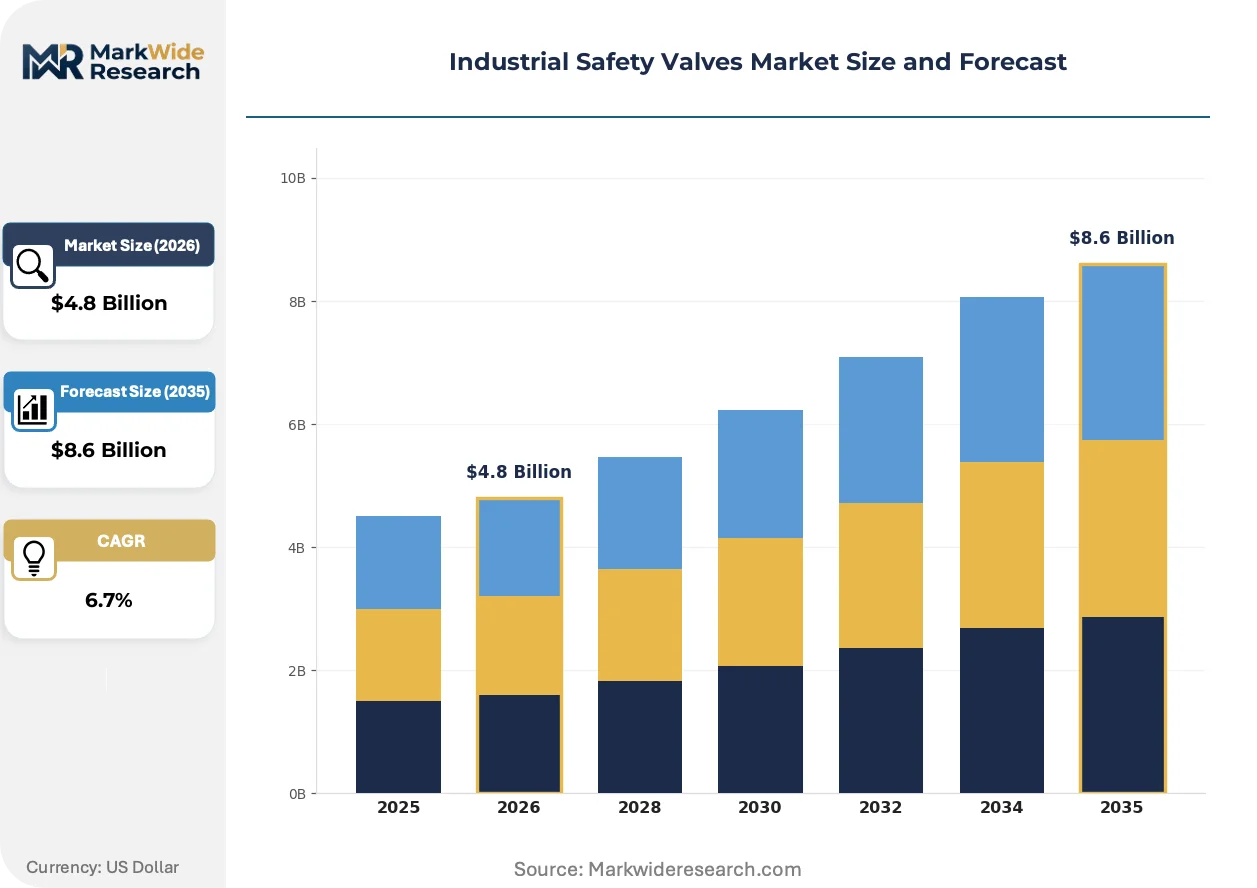
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Relief Valves, Safety Valves, Control Valves, Shut-off Valves Material: Stainless Steel, Carbon Steel, Titanium, Bronze End User: Oil & Gas, Chemical, Water Treatment, Power Generation Application: Pressure Protection, Flow Control, Temperature Control, Isolation |
| Companies Covered | Emerson Electric Co., Flowserve Corporation, Weir Group PLC, LESER GmbH & Co. KG, Parker Hannifin Corporation, Baker Hughes, IMI PLC, Alfa Laval, Bosch Rexroth, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Safety Valves Market Evolving Landscape
Intelligent valve diagnostics and predictive maintenance architectures are displacing calendar-based inspection regimes across hazardous chemical processing environments.
WirelessHART-enabled smart positioners are converging with cloud-based asset management platforms to transmit real-time stem position, packing leakage, and set pressure drift data. Offshore platform operators in the North Sea and Gulf of Mexico deploy these systems to reduce manned inspection visits. This convergence is compressing maintenance intervals from fixed schedules to condition-triggered interventions, reducing unplanned shutdown frequency.
The EPA's Risk Management Plan amendments impose stricter release prevention requirements and third-party audit obligations on facilities handling threshold quantities of regulated substances. Chemical manufacturers must now document safety valve testing frequencies and failure modes in mechanical integrity programs. Downstream refineries in Texas and Louisiana are responding by consolidating supplier relationships toward vendors with integrated digital documentation capabilities.
Buyer consolidation among integrated supermajors is concentrating procurement authority into centralized engineering technical centers. Specialized distributors and local valve shops are losing specification influence to corporate preferred vendor lists and frame agreements. This shift is most visible in Gulf Coast petrochemical expansions where owner-operators mandate Fisher, Masoneilan, or consolidated OEM direct relationships for critical pressure relief applications.
Industrial Safety Valves Market Segmentation
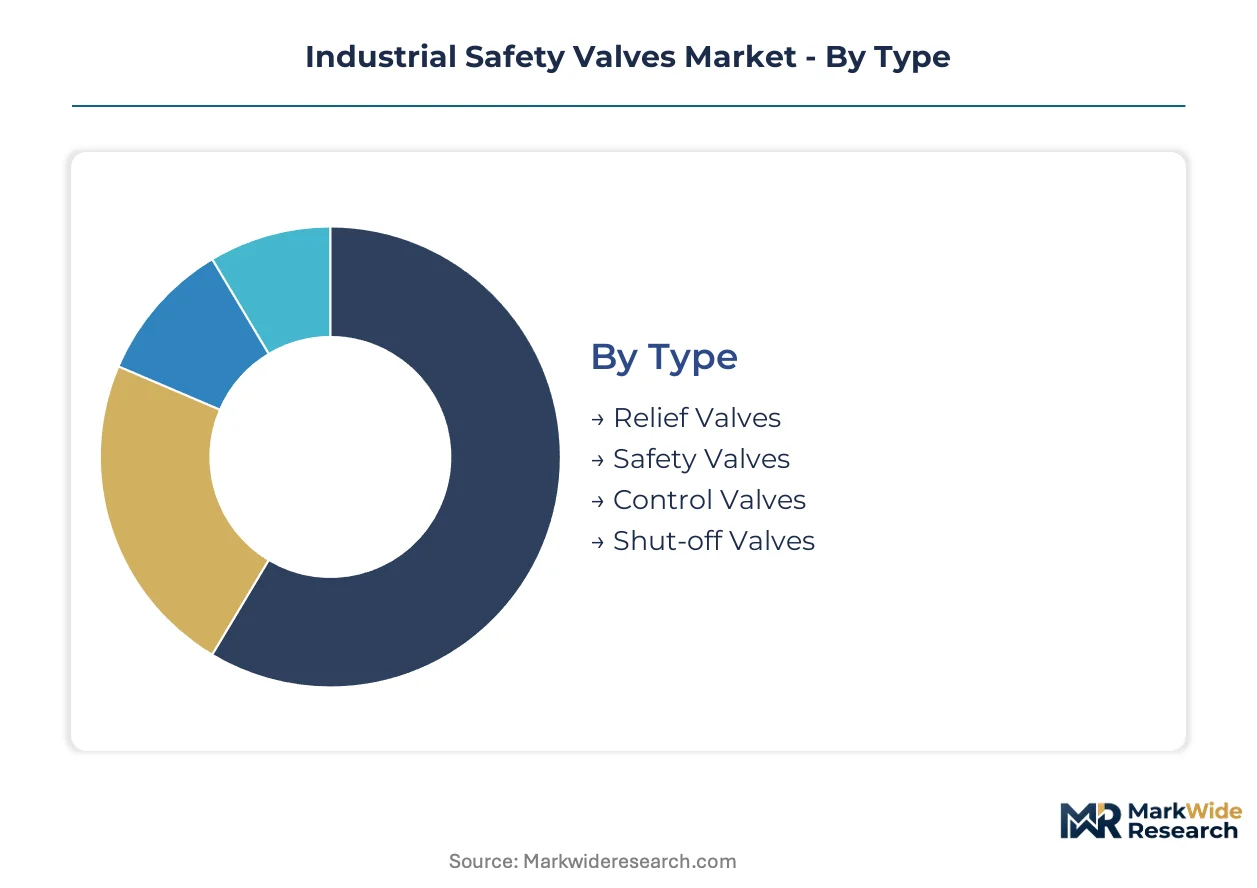
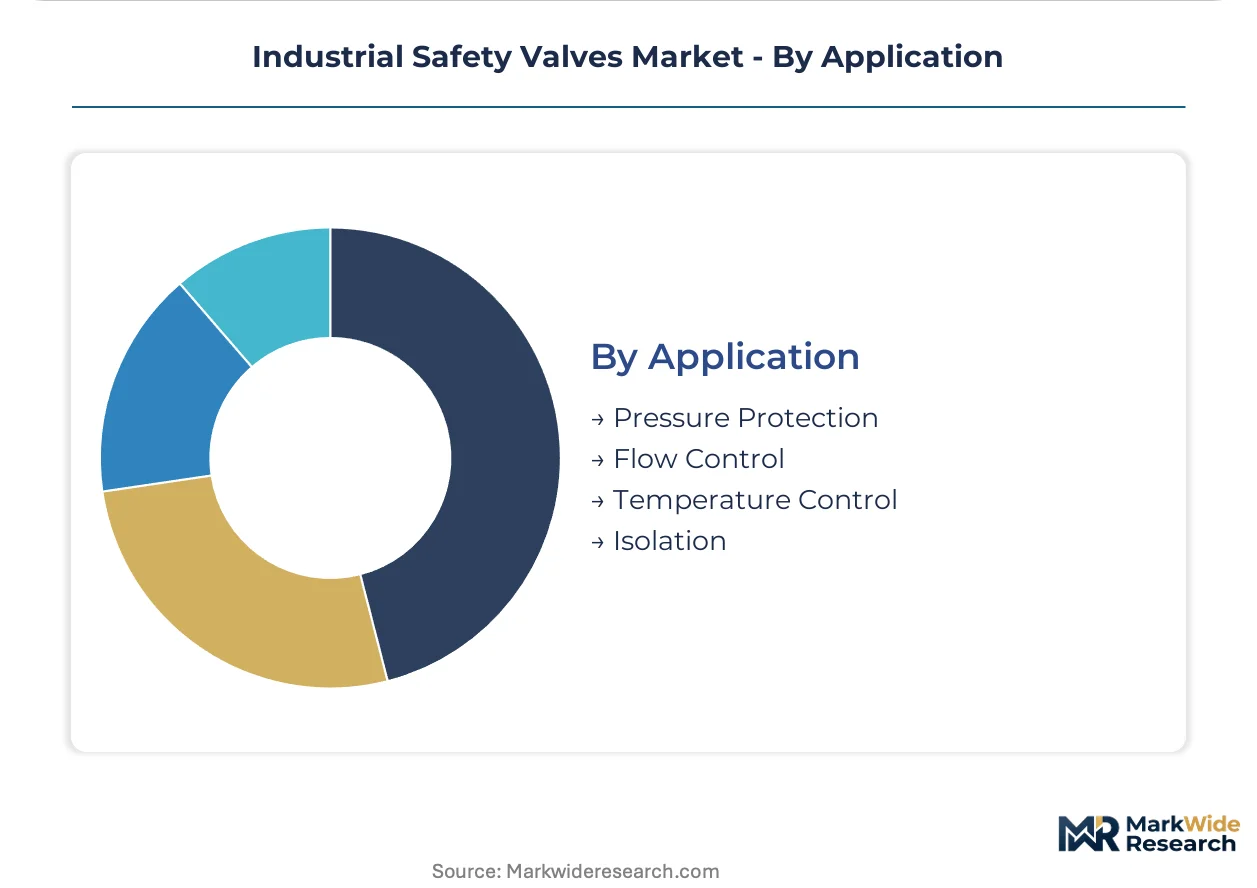
Industrial safety valve procurement follows distinct technical and commercial logics across type, material, end user, and application dimensions. Specification engineers weight pressure-temperature ratings, corrosion resistance, and code compliance differently depending on service severity and regulatory jurisdiction.
Type:
Supply concentration in spring-loaded relief valve manufacturing centers on foundries with ASME Section VIII stamp authority, creating tiered availability across conventional and pilot-operated designs.
- Relief Valves:Spring-loaded or pilot-operated devices venting excess pressure through lift mechanisms, typically specified with API 526 orifice designations. Texas and Louisiana refineries dominate replacement demand as EPA RMP amendments force documented mechanical integrity programs.
- Safety Valves:Rapid-opening pop-action devices engineered for compressible fluid service with full lift at set pressure. Offshore platforms in the Gulf of Mexico specify these for gas compression trains where instantaneous overpressure protection prevents vessel rupture.
- Control Valves:Throttling devices with smart positioner integration enabling flow modulation rather than binary relief.
- Shut-off Valves:Isolation devices providing positive sealing for maintenance and emergency isolation.
Relief valves absorb the bulk of installed capacity; control valves are expanding most quickly through digital positioner attach rates and diagnostic software subscriptions.
Material:
Raw material cost tiers stratify procurement decisions between commodity carbon grades and premium alloys requiring specialized foundry capabilities.
- Stainless Steel:ASTM A351 CF8M and 316L grades resist chloride stress corrosion in offshore and chemical service. Ammonia and hydrogen infrastructure projects in the Gulf Coast corridor specify these for embrittlement resistance under evolving ISO 19880 protocols.
- Carbon Steel:ASTM A216 WCC dominates standard refinery and power plant steam circuits where sour gas exposure is minimal. Volume concentration in conventional applications sustains foundry throughput for commodity castings.
- Titanium:Grades 2 and 5 serve seawater cooling and aggressive acid service where weight reduction justifies premium pricing.
- Bronze:C95800 and similar alloys address low-pressure steam and potable water applications with moderate corrosion exposure.
Carbon steel captures the greatest volume share; stainless steel is climbing the fastest on hydrogen service recertification and offshore specification upgrades.
End User:
Customer concentration patterns reflect capital intensity and regulatory exposure across process industries.
- Oil & Gas:Upstream production, midstream transport, and downstream refining operations mandate overpressure protection across wellheads, pipelines, and fractionation units. Gulf Coast petrochemical corridors drive replacement cycles as integrated supermajors consolidate procurement authority.
- Chemical:Batch and continuous processing of regulated substances triggers OSHA PSM mechanical integrity requirements. Facilities handling threshold quantities maintain documented valve testing records spanning equipment lifecycles.
- Water Treatment:Municipal and industrial desalination plants specify corrosion-resistant alloys for membrane system protection.
- Power Generation:Combined cycle and nuclear steam circuits require ASME Boiler and Pressure Vessel Code compliance for turbine protection.
Oil and gas commands the dominant share of premium alloy procurement; chemical processing is gaining share fastest on EPA RMP amendment compliance spending.
Application:
Functional requirements determine valve architecture selection and certification pathways.
- Pressure Protection:ASME Section VIII and API 526 governed devices preventing vessel rupture through automatic relief at predetermined set pressures. Mandatory across all pressure-containing equipment in code jurisdictions.
- Flow Control:Throttling applications requiring modulating response rather than binary open/close action.
- Temperature Control:Thermal relief and bypass configurations managing heat transfer fluid systems.
- Isolation:Positive shut-off for maintenance access and emergency containment.
Pressure protection accounts for the largest installed base; flow control is expanding fastest on smart positioner retrofits and predictive maintenance platform integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity clusters in specialized foundries across Germany, the United States, and Japan, while consumption concentrates in Gulf Coast petrochemical corridors and European chemical processing hubs. This geographic split creates supply chain tensions around alloy procurement and certification timelines.
United States
Texas and Louisiana petrochemical corridors drive replacement demand as EPA Risk Management Plan amendments tighten release prevention documentation. OSHA Process Safety Management frameworks mandate mechanical integrity programs with valve testing records spanning equipment lifecycles. Gulf Coast refiners in Houston and Lake Charles consolidate procurement toward vendors with integrated digital documentation capabilities.
Germany
Industrial valve fabricators in the Ruhr region and Baden-Württemberg serve chemical clusters along the Rhine with ASME-stamped and PED-compliant assemblies. The EU Pressure Equipment Directive and ATEX certification requirements shape product access for suppliers serving Ludwigshafen and Antwerp refining corridors. German foundries specialize in duplex stainless and high-nickel alloy castings for sour service applications.
China
Domestic valve manufacturers scale production of carbon steel and standard stainless grades for power plant and refinery construction. GB standards and evolving pressure equipment regulations align with ASME code adoption in coastal chemical processing zones. Yangtze River Delta clusters around Shanghai and Ningbo concentrate demand for imported premium alloys in offshore and hydrogen service.
Japan
Precision casting capabilities in Nagoya and Osaka support nuclear and high-integrity steam circuit applications with JIS-compliant and ASME-stamp dual certification. METI industrial safety guidelines reinforce mechanical integrity requirements across petrochemical and power generation installations. Japanese fabricators lead in titanium and superalloy valve production for aggressive corrosion service.
Saudi Arabia
Jubail and Yanbu industrial cities anchor demand for sour service valves in gas processing and petrochemical complexes. The country's national industrial regulator mandates ASME and API compliance for pressure-containing equipment in hydrocarbon facilities. Domestic fabrication joint ventures with European and American partners localize alloy casting and final assembly capacity.
Industrial Safety Valves Market Competitive Landscape
The competitive structure tilts toward diversified industrial conglomerates with foundry ownership and code certification authority. Tier-one positions concentrate in hands of players controlling ASME Section VIII stamp facilities and digital positioner technology. Three archetypes dominate: integrated valve-and-instrumentation conglomerates, specialized pressure relief fabricators with captive foundries, and regional alloy casting specialists serving multiple OEMs. Consolidation moves center on foundry acquisition for alloy supply security and frame agreement capture with integrated supermajors.
Among diversified industrial conglomerates, Emerson Electric Co. and Flowserve Corporation exemplify the integrated archetype combining valve manufacturing with digital automation platforms. LESER GmbH & Co. KG represents the specialized pressure relief fabricator model with European foundry integration and global certification reach. These three anchors illustrate how competitive position depends on alloy supply chain control and code stamp breadth rather than product differentiation alone.
| Leading Market Players |
|---|
| Emerson Electric Co. |
| Flowserve Corporation |
| Weir Group PLC |
| LESER GmbH & Co. KG |
| Parker Hannifin Corporation |
| Baker Hughes |
| IMI PLC |
| Alfa Laval |
| Bosch Rexroth |
| Others |
Value Network & Pricing Analysis
Digital positioner integration and smart valve diagnostics are compressing maintenance economics while concentrating procurement authority among integrated OEMs with captive foundry capacity. This technology shift simultaneously elevates software attach rates and locks out distributors lacking certification breadth, reshaping both cost structures and supplier power dynamics.
Pricing Analysis
Margin tightening in standard carbon steel grades reflects foundry overcapacity in commodity castings and buyer consolidation among Gulf Coast supermajors. Three-tier pricing structure across premium alloy, certified standard, and economy grades separates sour service specifications from conventional steam circuits. Price differentiation hinges on ASME Section VIII stamp authority and digital documentation capabilities. Chemical processors show highest price sensitivity on replacement cycles, while offshore operators absorb premiums for corrosion-resistant metallurgies.
Supply Chain Analysis
ASME Section IX qualified welders and NDE technicians command premium wages in Houston, Lake Charles, and Ruhr Valley fabrication clusters, constraining capacity expansion at specialty foundries. Supply concentrates in Germany, the United States, and Japan for high-integrity alloy castings. Raw material flows draw from nickel ore processing in Indonesia, chromium supply from South Africa, and molybdenum from Chilean concentrates. Single-source vulnerability in ASTM A217 WC9 and duplex stainless production creates procurement risk for sour service programs. Distribution runs through OEM-direct frame agreements with integrated supermajors, bypassing traditional distributor channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized alloy foundry capacity serves as the binding constraint propping pricing power for ASME-stamped fabricators. Limited qualified welding inspector pools and 12-18 month certification timelines protect incumbent margins against rapid capacity expansion.
For Market Incumbents: To counter distributor disintermediation by supermajor procurement consolidation, deepen direct frame agreement capture with integrated owner-operators and accelerate backward integration into nickel alloy foundry capacity. Prioritize digital documentation platform investments that satisfy EPA RMP amendment audit requirements. Secure captive supply of ASTM A217 WC9 and duplex stainless castings to defend against specialty alloy procurement bottlenecks. For New Entrants and Emerging Players: Launch via hydrogen service recertification specialization targeting ammonia cracker and pipeline projects in the Gulf Coast corridor where ISO 19880 validation gaps create specification windows. Target European chemical clusters in Antwerp and Rotterdam with PED Module H and ATEX certification as faster pathways than ASME stamp acquisition. Pursue white-label alloy casting partnerships with established foundries to bypass 12-18 month certification timelines. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by diversified industrial conglomerates seeking foundry ownership and code certification breadth. Long-term viability favors suppliers with validated hydrogen embrittlement test data and smart positioner integration capabilities. Monitor EPA enforcement intensity on RMP mechanical integrity audits as the critical signal for replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alloy Foundry Capacity | Captive supply of ASTM A217 WC9 castings secures sour service valve production against nickel procurement bottlenecks. |
| Digital Documentation Platform Deployment | Integrated valve testing records satisfy EPA RMP amendment audit requirements for Gulf Coast petrochemical operators. |
| Hydrogen Service Recertification Investment | Validated 316L and alloy 625 embrittlement data opens specification opportunities in ammonia cracker infrastructure. |
| Frame Agreement Capture with Supermajors | Direct OEM relationships bypass distributor channels and lock in replacement cycle revenue across Texas and Louisiana corridors. |
| PED Module H and ATEX Certification | EU Pressure Equipment Directive compliance enables access to Antwerp and Rotterdam refining corridors without ASME stamp delays. |
Research Methodology
Multi-period observation of EPA enforcement patterns, ASME certification timelines, and alloy foundry capacity utilization anchored the trend analysis, supplemented by interviews with plant engineers at Gulf Coast refineries, procurement leads at integrated supermajors, aftermarket service heads at valve distributors, and technical directors at specialty foundries. Secondary validation drew from EPA RMP enforcement data, SEC filings of diversified industrial conglomerates, ASME stamp registry records, and customs trade data on nickel alloy imports. Bottom-up segment sizing triangulated against top-down industry expenditure estimates.
Input-output matrices modeled valve demand across type, material grade, end-use industry, and application function throughout the forecast period. CAGRs derived from regression analysis against capital expenditure cycles in downstream processing and hydrogen infrastructure buildout rates. Industry-specific forecast inputs incorporated EPA RMP amendment implementation pace and ISO 19880 hydrogen code adoption trajectories.
Regulatory enforcement intensity shifts, hydrogen infrastructure investment delays, and specialty alloy supply disruptions are the dominant revision risks to the projection framework. Forecasts reflect assumptions on code adoption timelines and foundry capacity expansion feasibility. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Valves
High-Purity Fluoropolymer Valves Market
Valves
Penstock Market
Valves
Pneumatic Needle Valves Market
Valves
Fluid Handling Systems Market
Valves
Pulsation Dampeners Market
Valves
Oil Drain Valves Market
Valves
Sliding Sleeves Market
Valves
GCC and MENA Valves Market
Valves
Pipeline Equipment Market
Valves
Pipeline Pigging Valves Market
Valves
Valve Sack Market
Valves
North America Residential Ball Valves Market
Valves
APAC Valves Market
Valves
United States Valves Market
Valves
Fin Tube Market
Valves
Pressure Reducing Valve Market