
 GCC and MENA Valves Market | 2026-2036
GCC and MENA Valves Market Size, Share, and Industry Trends Forecast 2026-2036
GCC and MENA Valves Market Foresight
Multi-source procurement is restructuring supply relationships across the GCC and MENA Valves Market as end users reduce dependency on single vendors for critical infrastructure. Flowserve Corporation leverages its regional service network to sustain aftermarket revenue streams in Saudi Aramco-linked projects. Emerson Electric Co. anchors its position through digital valve monitoring platforms integrated with distributed control systems. KSB Group competes on engineered pump-valve packages for desalination and water transmission schemes.
GCC and MENA Valves are mechanical flow-control devices manufactured from cast or forged materials including carbon steel, stainless steel, and specialized alloys, designed to regulate, isolate, or throttle fluid streams under pressures ranging from vacuum to ultra-high-pressure wellhead service. Ball valves and gate valves dominate volume in oil and gas processing applications where full-bore flow and positive shutoff are mandatory. Stainless steel and alloy steel segments command premium positioning due to sour service requirements in Gulf petrochemical corridors, while butterfly valves gain share in water treatment and HVAC applications where space constraints and actuation speed matter.
Saudi Arabia's SASO technical regulations, the UAE's ESMA conformity assessment schemes, and Qatar's QS standards collectively enforce pressure-equipment safety and material traceability across Gulf valve supply chains. SFDA and MOHAP requirements in Saudi Arabia and the UAE respectively extend to process valves in pharmaceutical and food-contact applications, narrowing the field of qualified suppliers. Stakeholders must monitor evolving national content requirements and in-country value programs that are redirecting procurement toward localized assembly and testing capabilities.
Market Dynamics
Multi-source procurement is restructuring supply relationships across the GCC and MENA Valves Market as end users reduce dependency on single vendors for critical infrastructure. Flowserve Corporation leverages its regional service network to sustain aftermarket revenue streams in Saudi Aramco-linked projects. Emerson Electric Co. anchors its position through digital valve monitoring platforms integrated with distributed control systems. KSB Group competes on engineered pump-valve packages for desalination and water transmission schemes.
Growth Catalysts
- Downstream capacity additions:Oil and gas processing facilities across Saudi Arabia and the UAE are expanding valve procurement for refinery and petrochemical expansions.
- SASO technical regulations:Saudi Arabia's pressure-equipment safety standards are mandating material traceability and quality certifications that favor qualified suppliers.
- Sour gas service demand:Petrochemical clusters in Saudi Arabia's Eastern Province require specialized alloy and corrosion-resistant valve systems.
Market Restraints
- Alloy steel input volatility:Specialized nickel-chromium-molybdenum alloys face price swings tied to mining supply constraints and energy-intensive smelting costs.
- Single-source forging concentration:Critical large-diameter valve bodies depend on a limited set of European and East Asian forging houses, creating supply vulnerability.
- QS standard compliance friction:Qatar's national conformity assessment schemes add certification layers that extend qualification timelines for new market entrants.
Strategic Opportunities
- Oman industrial corridor development:Duqm Special Economic Zone petrochemical investments are creating fresh demand for high-pressure isolation valves.
- Digital valve monitoring convergence:Integration of wireless sensor networks with predictive maintenance platforms opens service revenue streams.
- In-country value programs:Saudi Arabia's localization mandates are redirecting procurement toward regional assembly and testing capabilities.
Industry Challenges
- Weld procedure qualification scarcity:Certified welders for exotic alloy valve fabrication remain concentrated in European and North American labor pools.
- Legacy DCS integration complexity:Digital valve positioners must interface with decades-old distributed control systems common in Gulf refineries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC and MENA Valves Market |
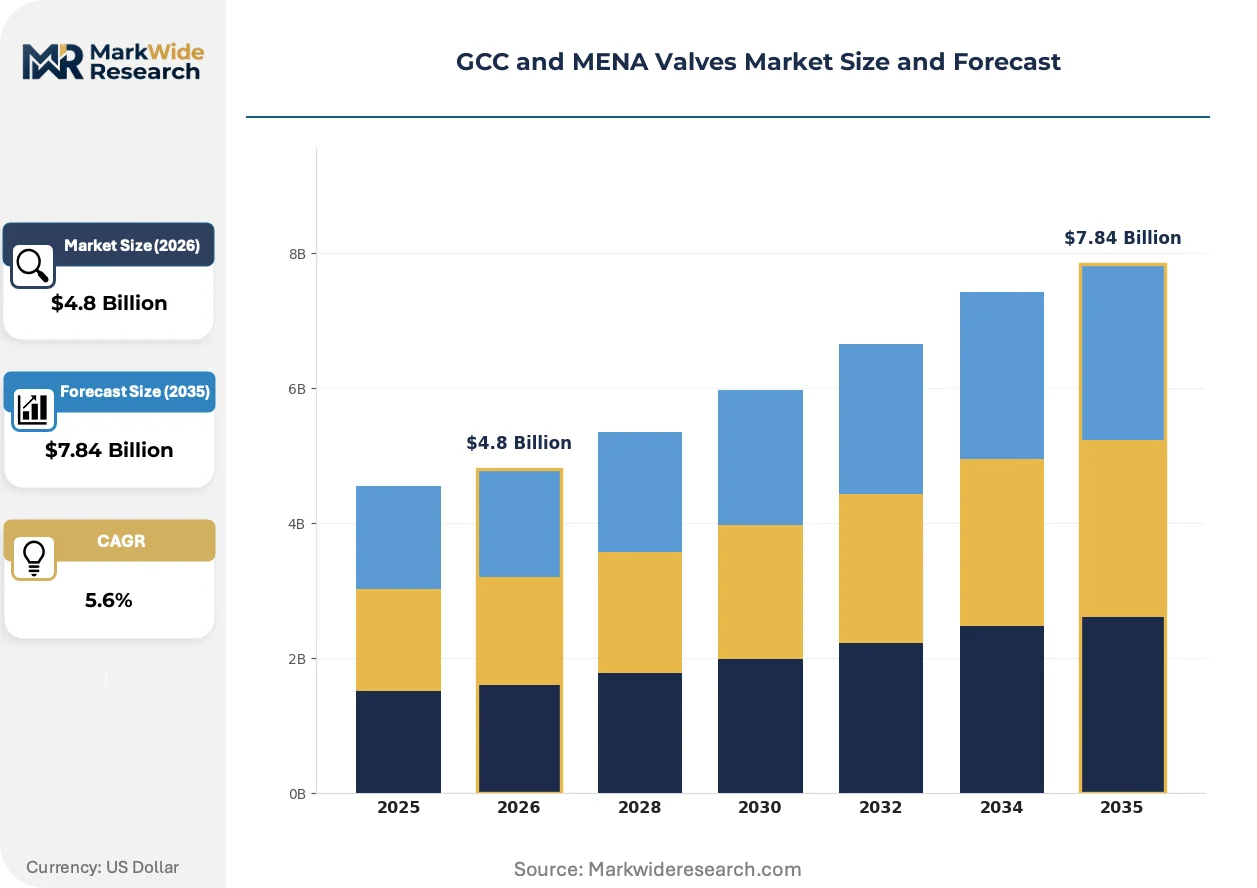
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.84 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ball Valves, Gate Valves, Globe Valves, Butterfly Valves, Check Valves Material: Carbon Steel, Stainless Steel, Brass, Cast Iron, Bronze, Alloy Steel Application: Oil & Gas Processing, Power Generation, Water Treatment, Chemical Processing, HVAC End User: Petrochemical Plants, Power Stations, Municipal Water Authorities, Construction Firms, Mining Companies |
| Companies Covered | Baker Hughes, a GE Company, Pentair, Flowserve Corporation, IMI Critical Engineering, KSB Group, Emerson Electric Co., Alfa Laval AB, AVK Gulf And Watecom International Water Network LLC, Schlumberger Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC and MENA Valves Market Shifts & Advancements
Digitalization and material science advances are reshaping valve specification patterns across Gulf industrial corridors. End users now prioritize predictive maintenance compatibility and emissions containment alongside traditional pressure ratings.
Metal-seated ball valve technology is consolidating market share in severe service applications previously dominated by gate valve architectures. Saudi Aramco and ADNOC-linked processors specify these for high-cycle catalytic cracking units. The shift is consolidating procurement volumes around suppliers with in-house hard-facing and coating capabilities.
UAE's Ministry of Climate Change and Environment is tightening fugitive emissions standards for valve packing and sealing systems. This regulatory pressure is accelerating adoption of low-emission graphite packing and live-loaded gland designs. Downstream petrochemical facilities in Abu Dhabi's Ruwais complex face the steepest compliance deadlines.
Buyer concentration among national oil companies is compressing supplier qualification cycles and unbundling aftermarket service contracts. Engineering-procurement-construction firms now separately source valve actuation and condition monitoring from specialist providers. This pattern is most pronounced in Saudi Arabia's Eastern Province megaproject pipeline.
GCC and MENA Valves Market Segmentation
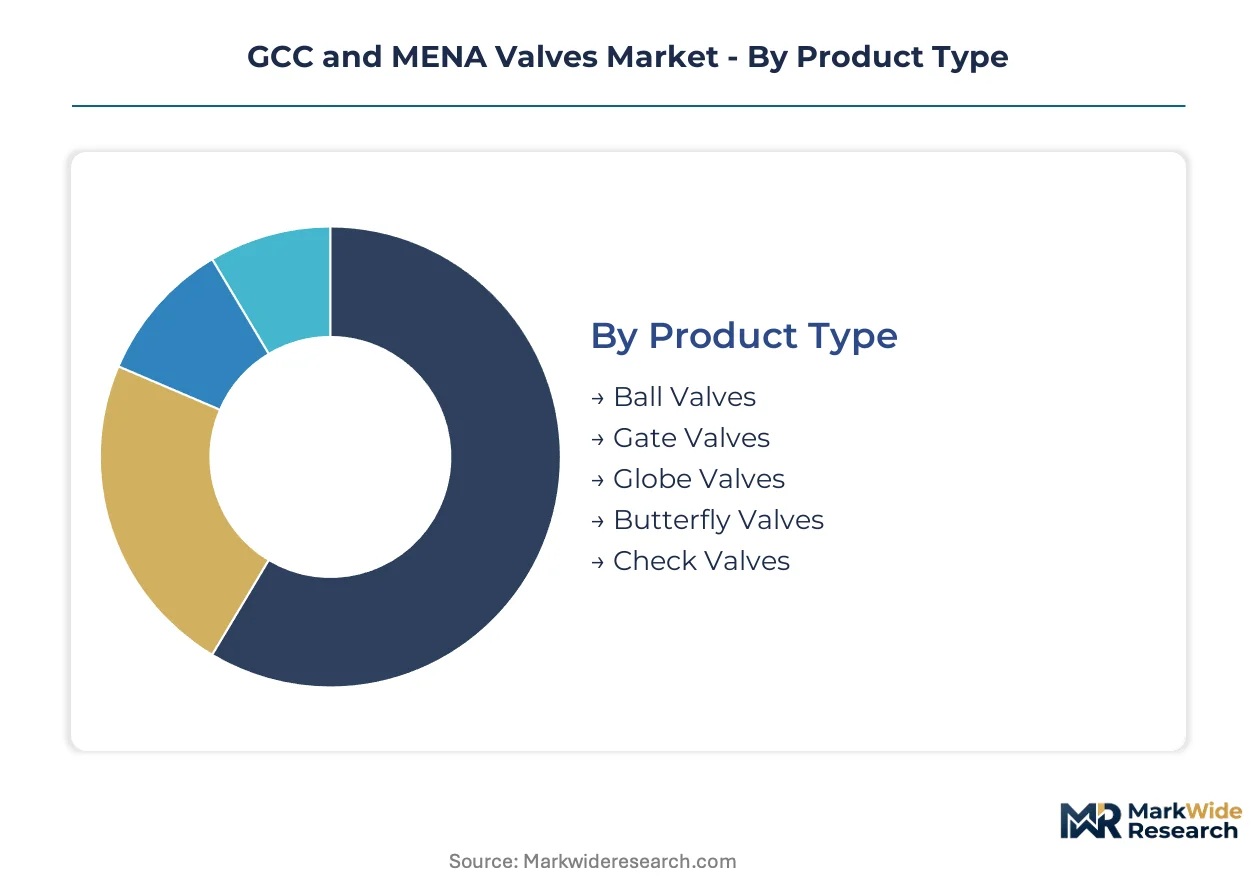
Valve specification patterns across the GCC and MENA region diverge sharply by pressure rating, corrosion resistance, and digital integration capability. Procurement teams segment purchases by material grade and service severity rather than unit cost alone.
Product Type:
Capital intensity escalates with pressure class and cycle frequency, with severe-service isolation valves commanding multiples over standard commodity units.
- Ball Valves:Full-bore floating and trunnion-mounted designs deliver tight shutoff across high-cycle catalytic cracking units. Saudi Aramco-linked processors in Jubail Industrial City specify metal-seated variants for thermal cycling resistance. Alloy steel construction pushes unit costs upward for sour gas service.
- Gate Valves:Wedge and parallel-slide architectures dominate wellhead and pipeline isolation where minimal pressure drop is mandatory. UAE onshore fields require expanding gate designs for thermal growth accommodation. These units absorb substantial forging capacity from European supply bases.
- Globe Valves:Throttling precision suits steam conditioning and bypass loops in combined-cycle power blocks.
- Butterfly Valves:Compact face-to-face dimensions and rapid actuation respond to space constraints in Dubai district cooling plants.
- Check Valves:Piston and swing configurations protect rotating equipment in desalination intake systems.
Ball valves absorb the bulk of installed capacity; butterfly valves are expanding most quickly.
Material:
Material selection traces directly to hydrogen sulfide partial pressure and chloride content in process streams, with exotic alloys carrying 4-6x premiums over carbon grades.
- Carbon Steel:ASTM A216 WCB and WCC grades satisfy low-pressure water and steam applications where corrosion allowances suffice. Municipal distribution networks across Riyadh and Jeddah standardize on these specifications for cost containment. Volume procurement compresses per-unit pricing.
- Stainless Steel:CF8M and CF3M castings resist chloride-induced pitting in offshore platform seawater cooling circuits. ADNOC's Upper Zakum development specifies super-austenitic grades for splash zone exposure. SASO material traceability mandates extend qualification timelines.
- Brass:Dezincification-resistant alloys serve potable water plumbing in Abu Dhabi residential towers.
- Cast Iron:Gray and ductile iron bodies support HVAC isolation in Qatar's Lusail City development.
- Bronze:Naval brass compositions handle seawater strainer applications in Omani desalination trains.
- Alloy Steel:WC6 and WC9 chrome-moly grades sustain elevated temperatures in Saudi ethylene crackers.
Carbon steel dominates procurement tonnage; stainless steel climbs fastest on sour service specifications.
Application:
Application segmentation tracks national industrial priorities, with hydrocarbon processing absorbing the majority of high-pressure alloy demand.
- Oil & Gas Processing:Upstream wellheads through downstream refining impose the most severe pressure-temperature ratings. Saudi Arabia's Eastern Province petrochemical corridor concentrates demand for API 6A and 6D certified products. Fugitive emissions compliance tightens packing specifications.
- Power Generation:Combined-cycle blocks and solar thermal plants require steam conditioning and isolation valve suites. Dubai's Mohammed bin Rashid Al Maktoum Solar Park drives procurement for high-temperature isolation. Water-steam chemistry dictates material selection.
- Water Treatment:Reverse osmosis and thermal desalination plants specify duplex stainless steels for seawater exposure.
- Chemical Processing:SABIC affiliate complexes in Jubail drive demand for corrosion-resistant alloy systems.
- HVAC:District cooling networks in Doha and Manama prioritize butterfly and balancing valve configurations.
Oil and gas processing anchors alloy consumption; power generation shows the steepest expansion trajectory.
End User:
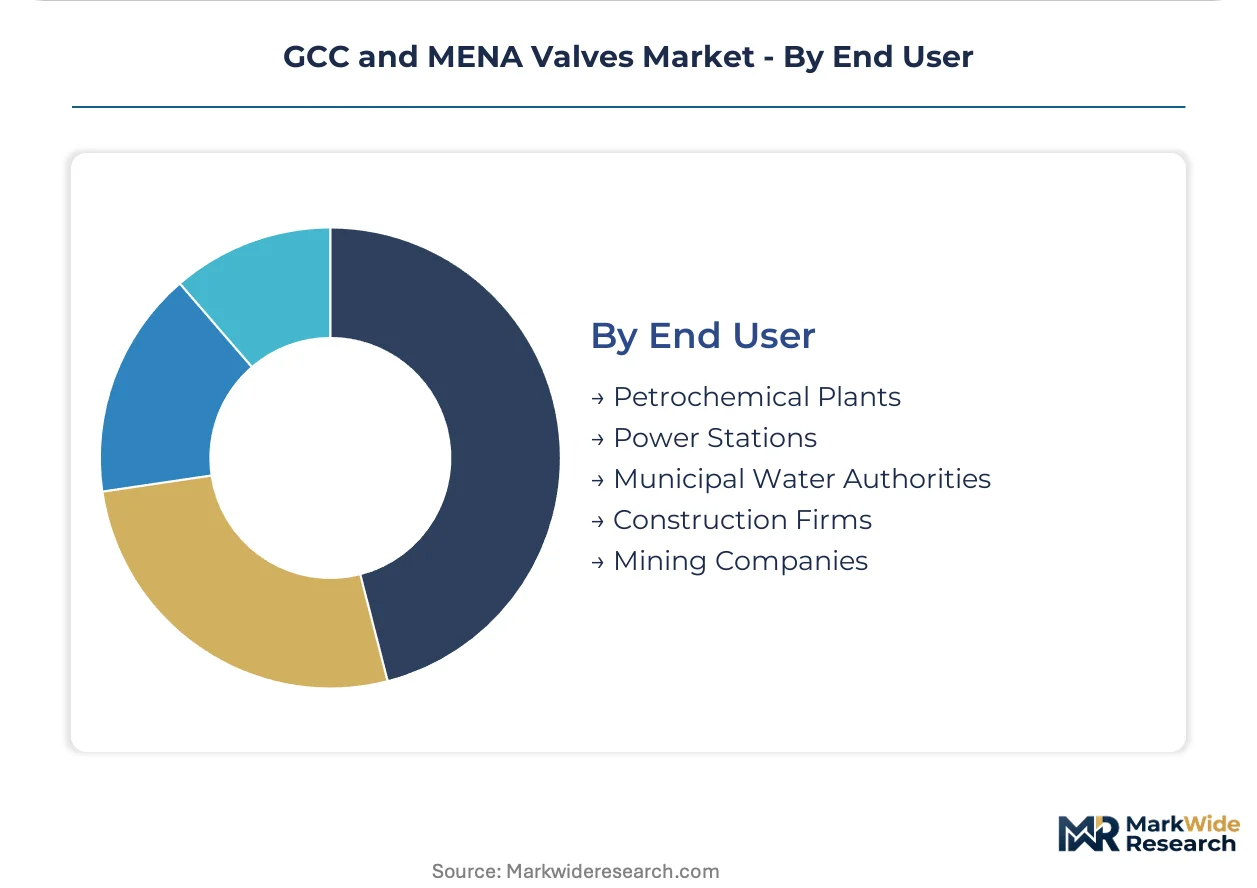
End-user concentration among national oil companies and sovereign utilities compresses supplier qualification cycles and unbundles service contracts.
- Petrochemical Plants:Integrated refining-petrochemical complexes in Jubail and Ruwais specify valve systems for continuous 5-year run lengths. SABIC's crude-to-chemicals investments are redirecting procurement toward severe-service metal-seated designs. In-country value mandates favor regional assembly.
- Power Stations:IWPP developers across the UAE and Saudi Arabia package valve procurement within EPC contracts. Taqa and Acwa Power procurement frameworks emphasize lifecycle cost over initial capital. Steam turbine bypass systems require rapid-actuation capability.
- Municipal Water Authorities:Saudi Water Partnership Company and Qatar General Electricity and Water Corporation standardize on ductile iron and stainless steel for transmission networks.
- Construction Firms:Mega-project developers in NEOM and Red Sea Global specify building services valves for hospitality and residential clusters.
- Mining Companies:Ma'aden phosphate and bauxite operations require abrasion-resistant slurry valve configurations.
Petrochemical plants command the largest project scale; power stations are broadening procurement fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chromite deposits in Oman and phosphate reserves in Morocco anchor raw-material linkages for alloy valve fabrication across the GCC and MENA corridor. National oil companies concentrate procurement authority, redirecting supply relationships toward localized assembly and testing capabilities.
Saudi Arabia
Saudi Aramco's crude-to-chemicals investments at Jubail Industrial City are redirecting procurement toward severe-service metal-seated valve designs. SASO technical regulations enforce material traceability and pressure-equipment safety certifications that extend supplier qualification timelines. The Eastern Province petrochemical corridor concentrates demand for API 6A and 6D certified products in sour gas applications.
United Arab Emirates
ADNOC's Upper Zakum offshore development specifies super-austenitic stainless steel grades for splash zone valve exposure. The Ministry of Climate Change and Environment is tightening fugitive emissions standards for valve packing and sealing systems. Downstream facilities in Abu Dhabi's Ruwais complex face accelerated compliance deadlines for low-emission graphite packing adoption.
Qatar
North Field expansion projects are absorbing high-pressure isolation valves for gas processing train additions. QS standards add certification layers that extend qualification timelines for new market entrants. Ras Laffan Industrial City concentrates procurement for LNG and gas-to-liquids facilities requiring specialized alloy systems.
Oman
Duqm Special Economic Zone petrochemical investments are creating fresh demand for high-pressure isolation valves in refinery configurations. The Special Economic Zone Authority is incentivizing localized valve assembly and testing capabilities. Port and logistics infrastructure development is positioning Duqm as an alternative procurement hub to Jebel Ali.
Kuwait
Al-Zour refinery and petrochemical complex expansions are absorbing large-diameter gate and ball valve suites. The Kuwait Authority for Partnership Projects is packaging valve procurement within integrated water and power project contracts. The Shuaiba industrial area maintains concentrated demand for corrosion-resistant alloy systems in sour service applications.
GCC and MENA Valves Market Competitive Landscape
Global majors compete with regional champions across aftermarket service networks and digital integration capabilities. The vendor base stratifies between full-line diversified industrials, specialized severe-service fabricators, and regional water infrastructure specialists. Three archetypes dominate: integrated flow-control conglomerates with in-house hard-facing capabilities, pump-valve package specialists targeting desalination verticals, and regional assemblers capturing in-country value mandates. Competitive moves concentrate on strategic partnerships for digital valve monitoring platforms and backward integration into alloy forging supply.
Among integrated flow-control conglomerates, Flowserve Corporation and Emerson Electric Co. exemplify the premium-tier positioning around aftermarket service networks and digital monitoring convergence. KSB Group occupies a position within the pump-valve package specialist archetype, anchoring engineered system procurement for water transmission schemes. These three companies represent the dominant competitive anchors across Saudi Aramco-linked projects, ADNOC offshore developments, and regional desalination infrastructure respectively.
| Leading Market Players |
|---|
| Baker Hughes, a GE Company |
| Pentair |
| Flowserve Corporation |
| IMI Critical Engineering |
| KSB Group |
| Emerson Electric Co. |
| Alfa Laval AB |
| AVK Gulf And Watecom International Water Network LLC |
| Schlumberger Limited |
| Others |
Supply & Pricing Matrix
Nickel-chromium-molybdenum alloy ingots move from European and East Asian forging houses through three distinct pricing tiers before reaching Saudi Aramco-linked processors, with each tier capturing margin proportional to metallurgical certification depth and traceability documentation.
Pricing Analysis
Warranty bundling separates premium-tier suppliers from commodity competitors across the GCC and MENA Valves Market, with full lifecycle service contracts commanding substantial premiums over transactional unit sales. Price differentiation hinges on SASO material traceability certification and API 6A qualification tier, with unbundled aftermarket service contracts compressing margins for pure-play fabricators. Cost compression in carbon steel commodity valves intensifies as regional assemblers capture in-country value mandates, while petrochemical plants demonstrate lowest price sensitivity due to five-year continuous run specifications.
Supply Chain Analysis
Certified welders for exotic alloy valve fabrication remain concentrated in German and North American labor pools, constraining expansion of indigenous forging capacity across the Gulf. Critical valve body production draws from Italy, South Korea, and Japan, with nickel-chromium-molybdenum alloy feedstock sourcing from chromite deposits in Oman and phosphate-linked supply chains in Morocco. Single-source vulnerability pervades large-diameter forging capacity, with distribution running through Jebel Ali and Duqm port logistics hubs serving Eastern Province and Ruwais industrial corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The GCC and MENA Valves Market operates under sustained supply constraint, with European forging house capacity absorption propping alloy valve pricing premiums regardless of carbon steel commodity softness.
For Market Incumbents: Acquire captive hard-facing and coating capabilities to defend against metal-seated ball valve technology displacement. Backward integration into alloy forging supply anchors margin protection from single-source concentration risk, while SASO certification investment deepens qualification moats against emerging regional assemblers. For New Entrants and Emerging Players: Launch via digital valve monitoring platform partnerships to bypass incumbent aftermarket service lock-in. Duqm Special Economic Zone presents the most penetrable geography, with localized assembly and testing capabilities satisfying Oman in-country value incentives while avoiding saturated Eastern Province procurement cycles. For Investors and Strategic Acquirers: Distressed-cycle entries favor pump-valve package specialists with desalination vertical exposure in UAE and Saudi Arabia water transmission schemes. Long-term viability centers on predictive maintenance convergence and wireless sensor network integration, with digital valve monitoring adoption rates serving as the critical inflection signal for platform valuation repricing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alloy Forging | Captive nickel-chromium-molybdenum supply secures margin protection from European forging house volatility. |
| Digital Valve Monitoring Platform Launch | Emerson Electric's distributed control system integration sets interoperability benchmark for aftermarket capture. |
| Localized Assembly and Testing Investment | Saudi in-country value mandates redirect procurement toward Eastern Province regional capabilities. |
| Metal-Seated Ball Valve Technology Expansion | Saudi Aramco crude-to-chemicals specifications consolidate procurement around hard-facing competence. |
| Desalination Pump-Valve Package Development | KSB Group's engineered system positioning anchors water transmission vertical across UAE and Saudi projects. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with valve procurement managers at national oil companies, EPC contractors, aftermarket service directors, and metallurgical certification specialists. SASO technical regulation databases, API certification registries, and GCC customs import records provided demand-side validation, with bottom-up project pipeline tracking reconciled against top-down industrial capacity assessments.
Data-stream reconciliation across shipment volumes, certification timelines, and procurement contract values generated segment-level projections over the analysis window. Modeled dimensions span product type, material grade, application severity, and end-user concentration tier, with CAGRs derived from weighted average of capacity expansion schedules and regulatory compliance cycle impacts. Alloy input cost trajectories and digital adoption curves informed price and technology pathway assumptions.
The model assumes a particular technology adoption path; alternative pathways for wireless sensor network integration would alter the outlook for predictive maintenance revenue streams. Forecasts reflect documented assumptions regarding SASO enforcement timelines and in-country value program expansion. Material deviation in European forging house capacity utilization or Gulf national oil company procurement centralization warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Valves
Fluid Transfer Solutions Market
Valves
Global Plastic Valves Market
Valves
Refrigeration Valves Market
Valves
Safety Valve Test Benches Market
Valves
Chemical Injection Metering Pumps and Valves Market
Valves
Global Marine Actuators and Valves Market
Valves
Tubing Heads Market
Valves
Hydraulic Valves Market
Valves
Valve Cover Gasket Market
Valves
Valve Driver Market
Valves
North America Irrigation Valves Market
Valves
Pigging Valves Market
Valves
Pipeline Pigging Equipment Market
Valves
Air Jet Ejectors Market
Valves
Global Pressure Relief Valves Market
Valves
Gas Equipment Market