
 Pinch Valve Market | 2026-2036
Pinch Valve Market Size, Share, and Industry Trends Forecast 2026-2036
Pinch Valve Market Outlook
Aftermarket sleeve replacement and predictive maintenance contracts is hardening into a distinct revenue layer alongside original equipment sales. Red Valve Company leverages its proprietary elastomer compounding expertise to sustain premium positioning in abrasive slurry applications. Flowrox Oy anchors its competitiveness through integrated process valve systems for mining and minerals processing.
A pinch valve is a flow control device that uses a flexible elastomer sleeve compressed by mechanical or fluid pressure to regulate, throttle, or shut off process media, with sleeve wall thickness typically ranging from 3 mm to 25 mm depending on pressure class and abrasion duty. Its primary industrial purpose is to isolate aggressive, corrosive, or solids-laden fluids without exposing metal components to the process stream. Pneumatic actuation dominates installed base volumes due to its reliability in dusty and wet industrial environments, while polyurethane sleeves represent the fastest-expanding material category as processors seek extended service life in abrasive duties. The pharmaceuticals end-use segment commands the highest margin pool because of validation requirements and FDA-compliant documentation burdens that limit supplier switching.
EPA effluent guidelines in the United States and REACH chemical restrictions in Europe are elevating sleeve material compliance costs while simultaneously disqualifying lower-tier suppliers from municipal water treatment and chemical processing procurement. ISO 9001 quality certification and CE marking under the Pressure Equipment Directive constitute baseline market access requirements for European industrial buyers. Stakeholders must monitor evolving per- and polyfluoroalkyl substance restrictions across multiple jurisdictions, as these compounds appear in some high-performance sleeve formulations and face prospective phase-outs that would force material reformulation investments.
Market Dynamics
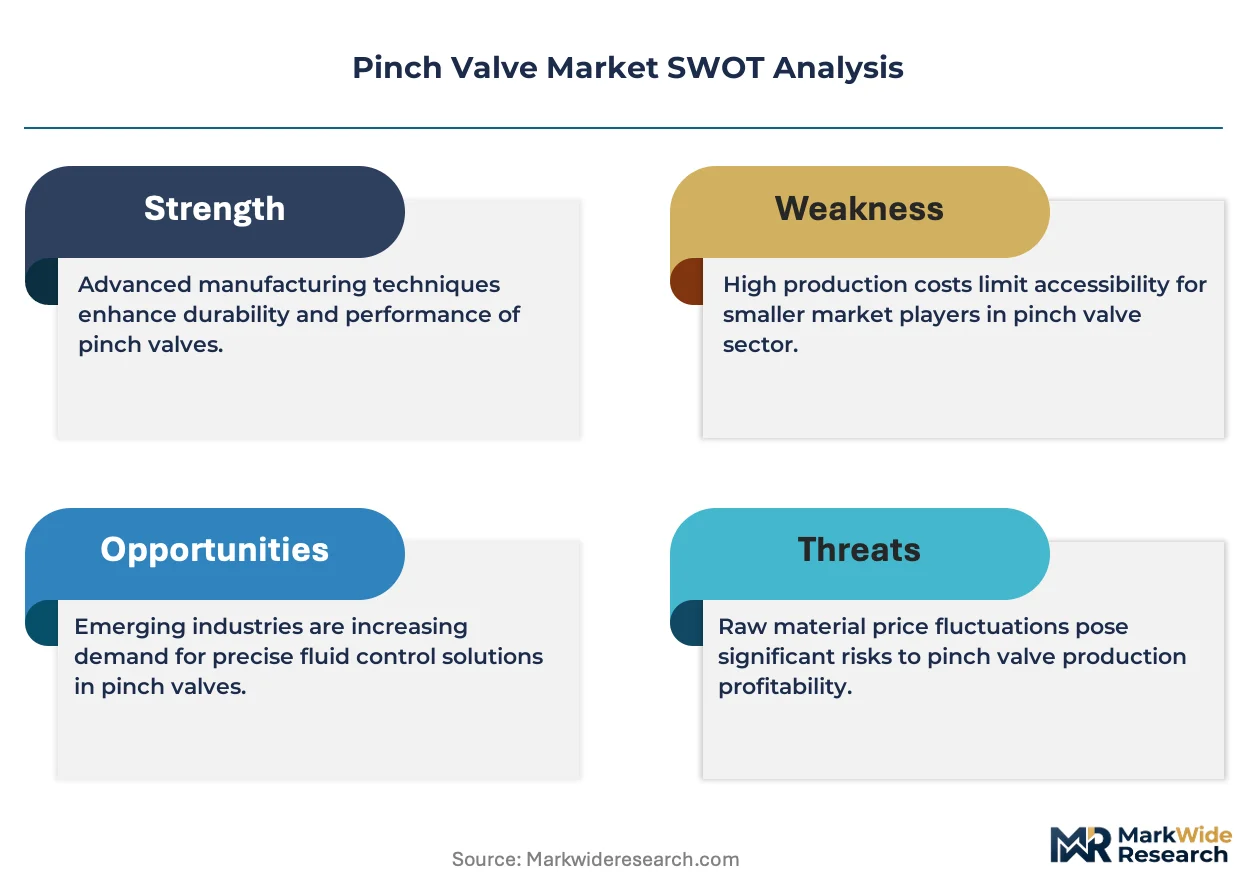
REACH compliance in Europe is forcing sleeve material reformulation across the supply base, compressing margins for non-specialist compounders while elevating qualified suppliers into premium procurement tiers. Mining slurry intensification is simultaneously pulling heavy-duty elastomer demand toward higher abrasion specifications.
Growth Catalysts
- REACH chemical restrictions:European ECHA enforcement is disqualifying lower-tier suppliers from municipal water treatment and chemical processing procurement, concentrating demand among certified compounders.
- Mining slurry handling:Ore processing intensification in copper and lithium extraction operations is expanding adoption of heavy-duty elastomer sleeves rated for 25 mm wall thickness.
- Pneumatic actuation reliability:Dusty and wet industrial environments favor compressed-air systems over electromechanical alternatives, sustaining installed base volumes in minerals processing.
Market Restraints
- Natural rubber price volatility:Crude oil-linked synthetic elastomer feedstocks and weather-dependent natural rubber harvests create input cost unpredictability for sleeve manufacturers.
- German chemical corridor concentration:Demand clustering around Ludwigshafen and Leverkusen creates geographic supply vulnerability and logistics cost premiums for distant buyers.
- Peristaltic pump substitution:Low-pressure fluid transfer applications increasingly specify peristaltic pumps where precise flow control outweighs pinch valve abrasion resistance.
Strategic Opportunities
- Predictive maintenance contracts:Aftermarket sleeve replacement bundled with vibration monitoring and failure forecasting is hardening into a distinct revenue layer beyond original equipment sales.
- Polyurethane sleeve expansion:Processors seeking extended service life in abrasive duties are migrating from natural rubber to polyurethane formulations, opening premium material substitution headroom.
- Pharmaceuticals validation services:FDA-compliant documentation burdens and batch validation requirements limit supplier switching, creating sticky margin pools for qualified providers.
Industry Challenges
- Elastomer compounding expertise scarcity:Formulation chemists capable of balancing abrasion resistance, chemical compatibility, and regulatory compliance command premium compensation and limited talent pools.
- CE marking timeline compression:Pressure Equipment Directive conformity assessment delays and notified body backlogs extend product launch cycles for European market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pinch Valve Market |
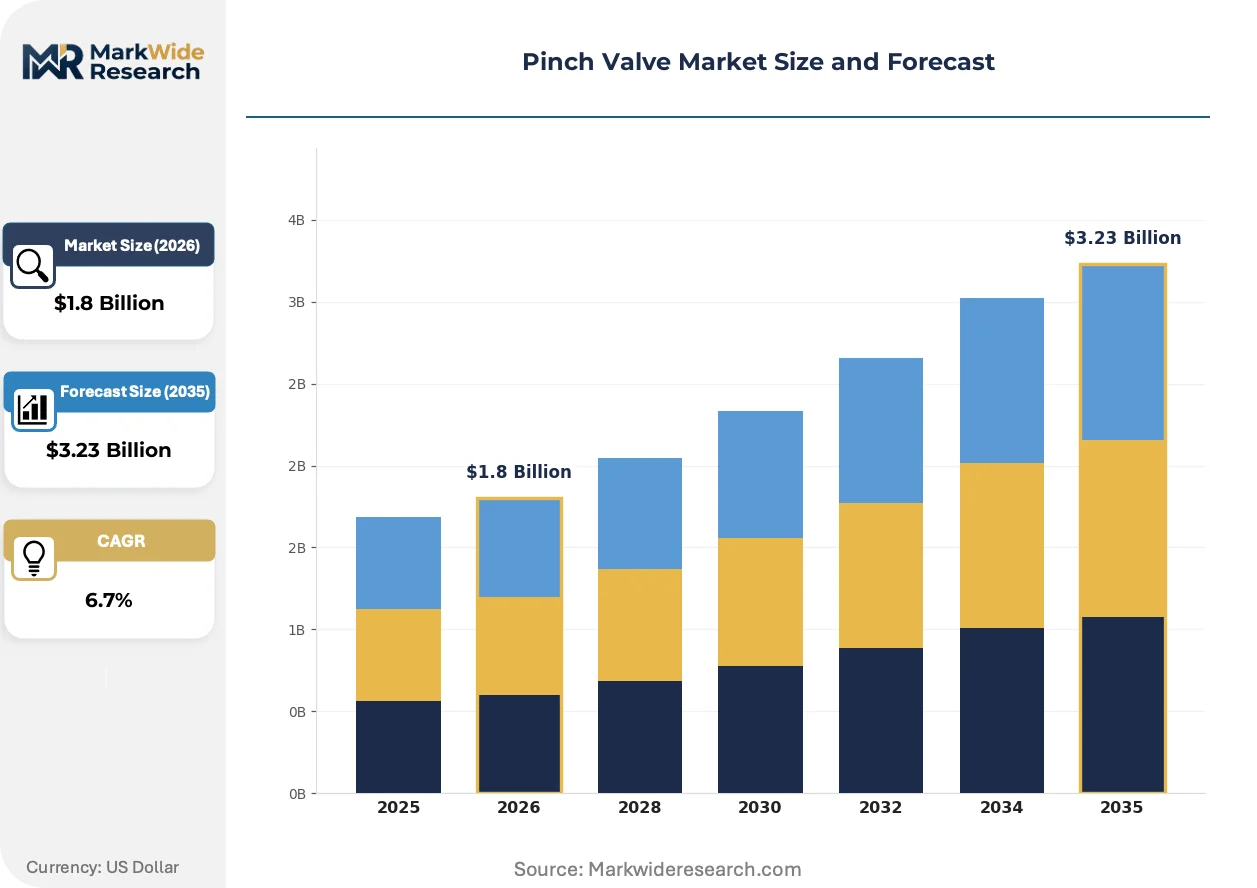
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pneumatic, Electric, Manual, Hydraulic Material: Rubber, Stainless Steel, PVC, Polyurethane End User: Water Treatment, Food & Beverage, Pharmaceuticals, Chemicals Operating Principle: Single Acting, Double Acting, Normally Closed, Normally Open |
| Companies Covered | Red Valve Company, Inc., Flowrox Oy, AKO Armaturen & Separationstechnik GmbH, Emerson Electric Co., Festo Group, Parker Hannifin Corporation, SMC Corporation, Bürkert Fluid Control Systems, Watson-Marlow Fluid Technology Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pinch Valve Market Strategic Shifts
Modular sleeve-actuator architectures are displacing integrated valve designs, enabling field-replaceable components that reduce maintenance downtime and inventory carrying costs. Material science advances and regulatory pressure are converging to reshape competitive positioning around compliance documentation rather than price alone.
Smart sleeve monitoring is modularizing predictive maintenance into discrete sensor packages that retrofit existing pneumatic actuators without full valve replacement. Mining operators in Chile and Australia are piloting these systems to schedule sleeve changes before catastrophic failure. The technology is modularizing service revenue from emergency repair into scheduled subscription contracts.
EPA effluent guidelines in the United States are tightening discharge limits for mining and chemical processing facilities. Municipal water treatment operators must now document sleeve material compliance with NSF/ANSI 61 drinking water system standards. Western US states with severe drought conditions are most affected, accelerating specification upgrades for zero-leakage isolation requirements.
Buyer consolidation among multinational mining houses is compressing supplier panels and extending contract durations. Procurement teams at Rio Tinto and BHP now mandate five-year total cost of ownership evaluations rather than upfront capital cost comparisons. Western Australian iron ore operations exemplify this shift, where predictive maintenance clauses have become standard tender requirements.
Pinch Valve Market Segmentation
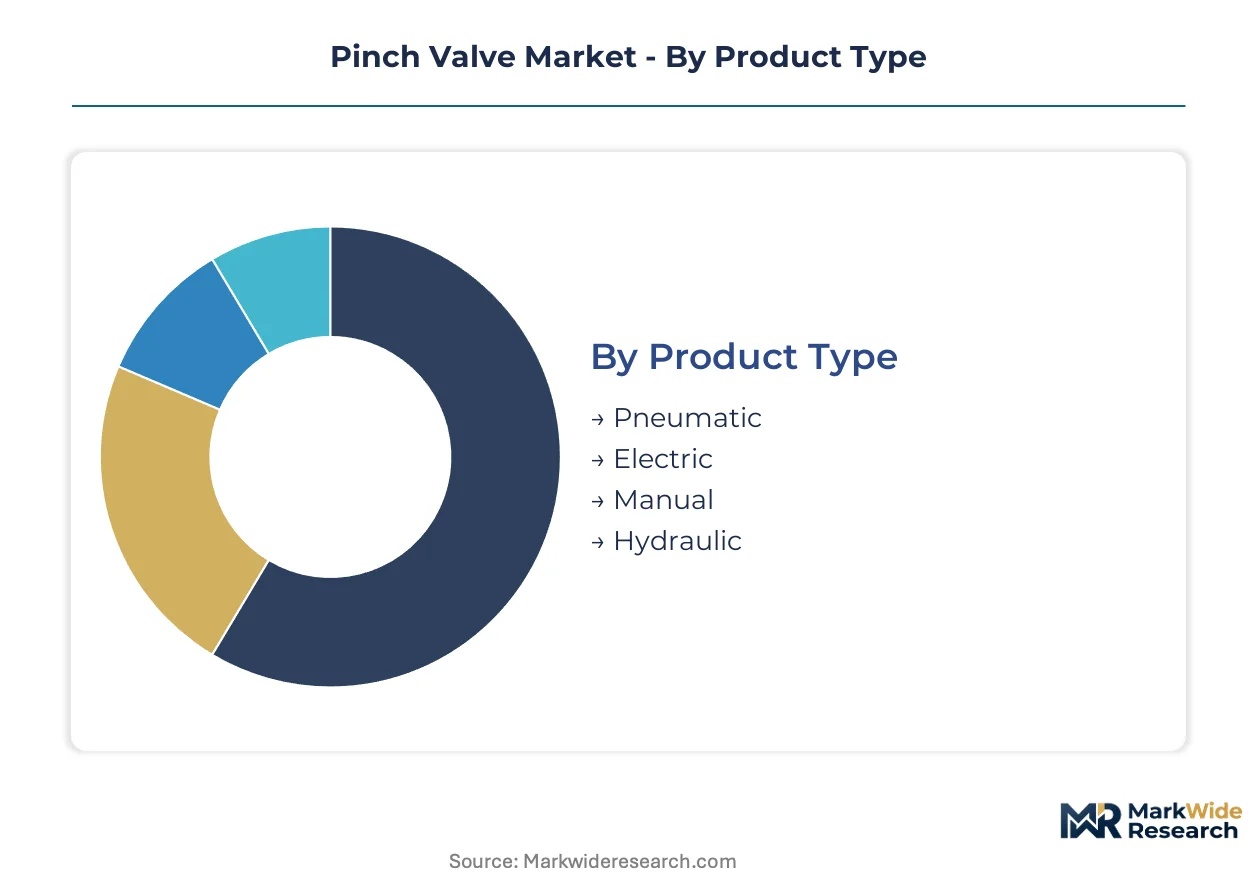
Pinch valve procurement patterns diverge sharply across actuation methods, sleeve materials, and regulatory exposure levels. Buyers prioritize abrasion resistance in mining, chemical compatibility in pharmaceuticals, and total cost of ownership in municipal water treatment.
Product Type:
Actuation choice separates buyers by maintenance infrastructure, power availability, and response speed requirements in dusty or wet environments.
- Pneumatic:Compressed-air systems dominate minerals processing and chemical plants where electromechanical components risk spark ignition or moisture ingress. Rio Tinto and BHP procurement panels now mandate five-year total cost of ownership evaluations that favor pneumatic reliability over upfront capital savings.
- Electric:Servo-motor actuation delivers precise positioning for pharmaceutical batching and food-grade dosing where flow modulation accuracy outweighs abrasion duty. FDA validation documentation burdens limit supplier switching, creating sticky relationships for qualified electric actuator providers.
- Manual:Handwheel or lever operation serves isolated bypass lines and emergency isolation points where automation infrastructure is uneconomical. These configurations concentrate in developing economy water treatment retrofits and small-scale chemical handling.
- Hydraulic:High-pressure fluid power actuation addresses subsea mining and deep-well applications where pneumatic pressure is insufficient. Australian iron ore operations pilot hydraulic systems for slurry isolation at depth.
Volume sits with Pneumatic; growth tilts toward Electric as pharmaceutical and food automation intensifies.
Material:
Sleeve compound selection directly determines service life, regulatory compliance burden, and replacement frequency in abrasive or chemically aggressive media.
- Polyurethane:Thermoplastic elastomer formulations extend service life in copper and lithium extraction slurries where natural rubber degrades prematurely. REACH compliance in Europe is disqualifying lower-tier compounders from specification, concentrating demand among certified suppliers with proprietary formulation expertise.
- Rubber:Natural and synthetic elastomer sleeves retain cost advantage in municipal water treatment and low-abrasion chemical transfer. Crude oil-linked feedstock prices and weather-dependent harvests create margin pressure for non-integrated manufacturers.
- Stainless Steel:Metal-reinforced or all-metal construction serves high-temperature steam applications and nuclear-grade isolation where elastomer creep is unacceptable. German chemical corridor demand clusters around Ludwigshafen and Leverkusen for these specifications.
- PVC:Thermoplastic sleeves address cost-sensitive water treatment and low-pressure chemical dosing with limited temperature range. NSF/ANSI 61 drinking water system compliance documentation is tightening procurement standards in drought-affected US Western states.
Polyurethane gains share fastest from Rubber in mining applications; Stainless Steel commands premium pricing in nuclear and pharmaceutical steam isolation.
End User:
Industry verticals separate buyers by validation intensity, leakage tolerance, and total cost of ownership calculation horizons.
- Pharmaceuticals:FDA-compliant batch validation and documentation burdens create the highest margin pool. Supplier switching costs are prohibitive once validation protocols are established, generating recurring revenue from sleeve replacement and audit support services.
- Chemicals:Aggressive media handling demands elastomer formulations balancing chemical compatibility with abrasion resistance. ECHA enforcement of REACH restrictions is compressing margins for non-specialist compounders while elevating qualified suppliers.
- Water Treatment:Municipal operators prioritize zero-leakage isolation and NSF/ANSI 61 material compliance under tightening EPA effluent guidelines. Procurement concentrates on lifecycle cost rather than upfront capital expenditure.
- Food & Beverage:Hygienic design standards and clean-in-place compatibility drive specification. European EFSA food contact material regulations and US FDA food additive compliance create dual-jurisdiction documentation requirements for multinational processors.
Revenue concentrates in Pharmaceuticals; expansion accelerates in Chemicals as European regulatory enforcement tightens.
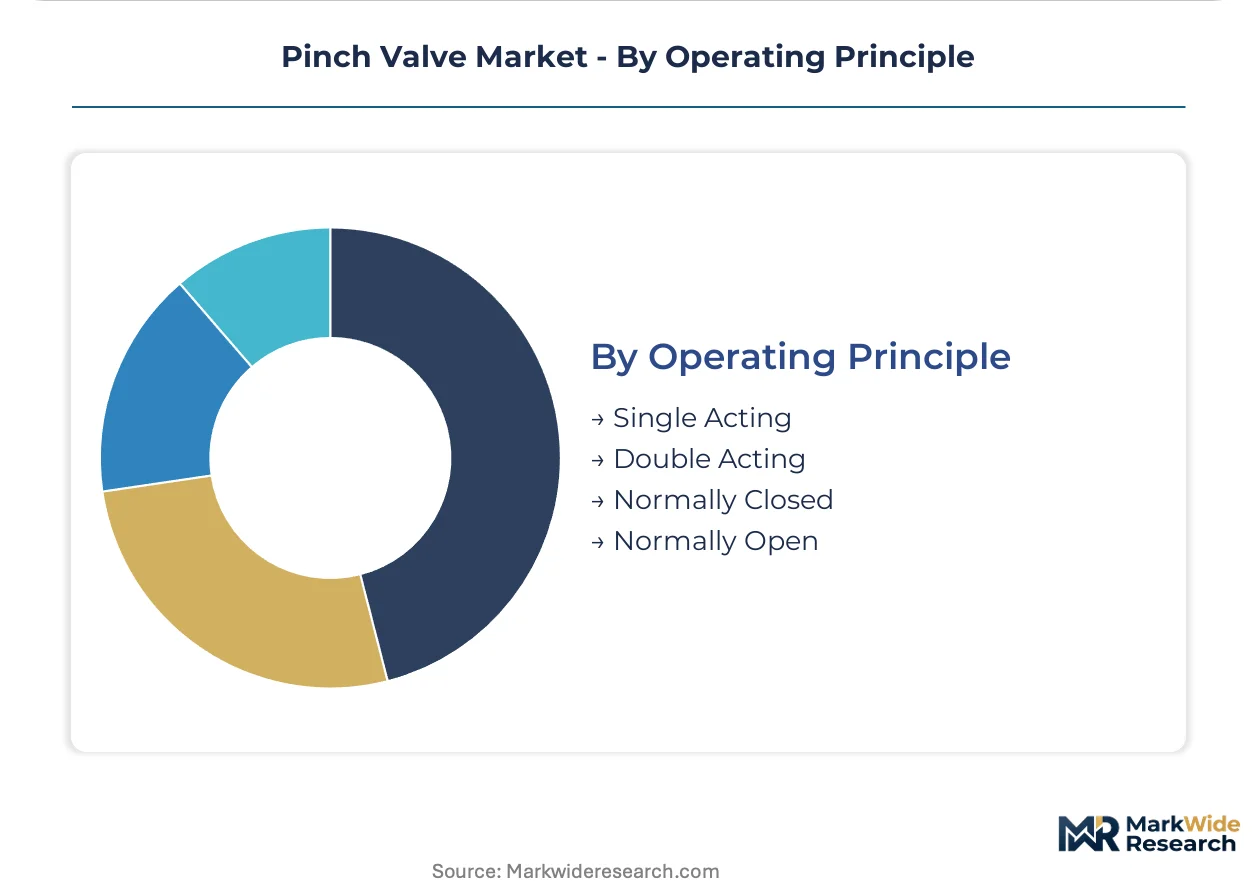
Operating Principle:
Fail-safe behavior and actuation directionality determine specification for safety-critical isolation and process automation architectures.
- Normally Closed:Spring-return or pressure-fail designs ensure automatic shutoff on air or power loss. Mining slurry lines and chemical containment systems mandate this configuration for environmental protection.
- Normally Open:Default-flow configurations suit cooling water and ventilation systems where obstruction risks exceed leakage risks. These applications concentrate in power generation and HVAC integration.
- Single Acting:One-directional pressure application simplifies actuator design and reduces maintenance points. Pneumatic single-acting systems dominate installed base volumes in dusty minerals processing environments.
- Double Acting:Bidirectional pressure control delivers faster response and positive positioning in both directions. Pharmaceutical dosing and food metering applications specify double-acting electric actuation for precision.
Single Acting commands installed base volume; Double Acting expands fastest in precision automation segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pinch valve manufacturing concentrates in Germany and the United States, while consumption pulls toward mining-intensive economies. The geographic split creates trade flows from industrial valve fabrication centers to ore processing sites.
United States
EPA effluent guidelines tighten discharge limits for mining and chemical facilities, driving specification upgrades. NSF/ANSI 61 drinking water system compliance documentation accelerates procurement in drought-affected Western states. Municipal water treatment operators in California and Arizona prioritize zero-leakage isolation requirements.
Germany
REACH chemical restrictions enforced by ECHA disqualify lower-tier sleeve compounders from specification. CE marking under the Pressure Equipment Directive constitutes baseline market access. Demand clusters around Ludwigshafen and Leverkusen in the chemical corridor for heavy-duty elastomer applications.
Chile
Copper and lithium extraction intensification expands adoption of heavy-duty elastomer sleeves rated for extreme abrasion duty. Mining operators pilot smart sleeve monitoring systems to schedule replacements before catastrophic failure. Antofagasta and Atacama regions anchor slurry handling equipment demand.
Australia
Western Australian iron ore operations mandate five-year total cost of ownership evaluations in procurement panels. Predictive maintenance clauses have become standard tender requirements for multinational mining houses. Perth-based engineering services support remote mine site valve maintenance.
China
Domestic ore processing capacity expansion drives demand for pneumatic actuation in dusty environments. The country's national environmental regulator tightens industrial discharge standards. Shandong and Hebei provinces concentrate minerals processing infrastructure requiring abrasion-resistant flow control.
Pinch Valve Market Competitive Environment
Top-tier vendors anchor premium elastomer compounding expertise, while mid-scale fabricators compete on lead times and regional service. The supply base stratifies between formulation specialists with proprietary rubber chemistry and assembly-focused operators sourcing sleeves from third-party compounders. Two strategic archetypes dominate: integrated valve-actuator system providers and sleeve-focused component specialists. Competitive moves concentrate on predictive maintenance service bundling and REACH-compliant material reformulation investments.
Among German-based fluid control specialists, AKO Armaturen & Separationstechnik GmbH and Bürkert Fluid Control Systems exemplify the premium-tier positioning built on regulatory compliance documentation and pharmaceutical validation capabilities. Finnish Flowrox Oy occupies a position representing the integrated process systems archetype for mining and minerals processing. These three companies illustrate how geographic origin and organizational structure correlate with competitive positioning in a market where ECHA enforcement and FDA validation requirements create defensible market segments.
| Leading Market Players |
|---|
| Red Valve Company, Inc. |
| Flowrox Oy |
| AKO Armaturen & Separationstechnik GmbH |
| Emerson Electric Co. |
| Festo Group |
| Parker Hannifin Corporation |
| SMC Corporation |
| Bürkert Fluid Control Systems |
| Watson-Marlow Fluid Technology Solutions |
| Others |
Value Chain & Pricing Dynamics
Natural rubber futures on the Tokyo Commodity Exchange cascade through three distinct pricing tiers as sleeve compounders pass feedstock volatility downstream to valve assemblers and end-users in mining and chemical processing. REACH compliance investments in Europe and ECHA enforcement actions compress margins for non-specialist compounders while elevating certified suppliers into premium procurement positions.
Pricing Analysis
Margin tightening in standard-grade sleeves reflects crude oil-linked synthetic elastomer feedstock volatility and weather-dependent natural rubber harvests. Three-tier pricing structure across premium REACH-certified, standard ISO-compliant, and economy-grade non-certified levels separates buyers by validation burden and abrasion duty. Pricing pressure intensifies in municipal water treatment as EPA effluent guidelines tighten and NSF/ANSI 61 documentation requirements escalate. Mining procurement panels at Rio Tinto and BHP demonstrate lowest price sensitivity through five-year total cost of ownership evaluations that prioritize predictive maintenance bundling over upfront capital cost.
Supply Chain Analysis
Formulation chemist scarcity in Germany's chemical corridor and pneumatic actuator manufacturing clusters in the United States constrain capacity expansion for qualified suppliers. Sleeve compounding concentrates in Germany, the United States, and Finland where proprietary elastomer expertise anchors competitive positioning. Raw material sourcing draws from Malaysian natural rubber plantations, Middle Eastern petrochemical feedstocks for synthetic elastomers, and Chinese rare earth catalysts for polyurethane polymerization. Single-source vulnerability around Ludwigshafen and Leverkusen chemical corridor concentration creates geographic supply risk. Distribution runs through OEM valve assemblers, authorized aftermarket service networks, and direct mining house procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH enforcement and FDA validation requirements are consolidating the pinch valve supply base by disqualifying undercapitalized compounders from specification tiers, forcing acquisition or exit for non-compliant players.
For Market Incumbents: Anchor premium positioning through proprietary elastomer compounding expertise and predictive maintenance service bundling that locks mining houses into recurring revenue streams. Defend against peristaltic pump substitution in low-pressure applications by emphasizing abrasion resistance and smart sleeve monitoring retrofits. Invest in REACH-compliant material reformulation ahead of PFAS restrictions to maintain European chemical processing access. For New Entrants and Emerging Players: Capture white-space in pharmaceutical validation services where FDA documentation burdens and batch protocol establishment create sticky supplier relationships with prohibitive switching costs. Target drought-affected Western US states where municipal water treatment operators prioritize zero-leakage isolation and NSF/ANSI 61 compliance documentation. Enter through aftermarket sleeve replacement contracts bundled with vibration monitoring sensor packages rather than competing for original equipment tenders. For Investors and Strategic Acquirers: The window for entry favors sleeve-focused component specialists with proprietary formulation chemistry and established ECHA compliance documentation over assembly-focused valve fabricators sourcing third-party elastomers. Long-term viability hinges on captive compounding expertise and pharmaceutical validation capabilities that sustain margin pools through regulatory barrier construction. Watch ECHA enforcement intensity and per- and polyfluoroalkyl substance restriction timelines as inflection indicators for material reformulation investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Elastomer Compounding | Captures margin pool from sleeve manufacturing and insulates against natural rubber price volatility. |
| Predictive Maintenance Service Bundling | Transforms emergency repair revenue into scheduled subscription contracts with mining operators in Chile and Australia. |
| REACH-Compliant Material Reformulation | Maintains European chemical processing market access as ECHA enforcement disqualifies lower-tier suppliers. |
| Smart Sleeve Monitoring Retrofit Packages | Enables field-installable sensor systems that schedule replacements before catastrophic failure in abrasive slurry duty. |
| Pharmaceutical Validation Documentation Investment | Creates defensible market position through FDA-compliant batch protocols that limit supplier switching. |
Study Parameters
Independent corroboration across plant engineers at mining operations, procurement leads at multinational mining houses, and aftermarket service directors underwrites the qualitative findings on specification priorities and total cost of ownership evaluation practices. Primary interviews with maintenance directors, OEM valve procurement teams, and elastomer compounding R&D heads combined with secondary validation from SEC filings, customs trade data, and ECHA substance restriction notifications. Bottom-up sleeve replacement frequency modeling and top-down valve system expenditure analysis triangulate market sizing.
Comparable-period anchoring to historical mining capex cycles and chemical processing capacity expansion waves structures the projection horizon. Segmentation modeling spans actuation method, sleeve material grade, end-use industry vertical, and regional regulatory cluster. CAGRs derive from installed base growth, replacement frequency intensification, and average selling price trajectory analysis. Forecast inputs incorporate pneumatic actuator reliability premiums in dusty environments and polyurethane sleeve substitution rates in copper and lithium extraction.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to natural rubber price volatility, ECHA enforcement intensity, and peristaltic pump technology advancement. Forecasts reflect documented assumptions on mining slurry handling intensification and REACH compliance timeline adherence. A small set of triggers—PFAS restriction finalization, notified body backlog resolution for CE marking, and smart sleeve monitoring adoption rates—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Valves
Europe Valves Market
Valves
Cryogenic Valve Market
Valves
Isolator Valves Market
Valves
Railway Emergency Valves Market
Valves
Motorized Valves Market
Valves
Wind Energy Fasteners Market
Valves
Sand Control System Market
Valves
Rising Stem Ball Valve Market
Valves
Air Jet Ejectors Market
Valves
Total Containment Vessels Market
Valves
Global Plug Valve Market
Valves
Large Bore Vacuum Insulated Pipe Market
Valves
North America Irrigation Valves Market
Valves
Pipeline Integrity Management (PIM) Market
Valves
Global Gate Valve Market
Valves
APAC Valves Market