
 Steam Trap Market | 2026-2036
Steam Trap Market Size, Share, and Industry Trends Forecast 2026-2036
Steam Trap Market Intelligence
Project finance and equipment-leasing arrangements for steam system retrofits is fragmenting competitive access across mid-sized industrial facilities. Spirax Group plc leverages its captive service network to anchor long-term maintenance contracts in European process industries. Emerson Electric Co. competes through instrumentation-integrated trap designs that extend digital monitoring capabilities into legacy plant infrastructure.
A steam trap is a self-acting automatic valve that discharges condensate, air, and non-condensable gases from steam systems while preventing live steam loss, typically operating at pressures from vacuum to over 100 bar and temperatures exceeding 500°C depending on metallurgy. Its primary industrial purpose centers on thermal efficiency protection and waterhammer prevention across continuous-process steam circuits. Mechanical traps, particularly float and inverted-bucket configurations, dominate mature utility applications where reliability metrics override first-cost considerations. Thermodynamic traps lead fastest growth in compact skid-mounted systems for chemical processing and offshore platforms where space constraints and simplified maintenance protocols command premium positioning. Stainless steel material grades concentrate margin pools in food processing and pharmaceutical steam networks where surface-finish standards and corrosion resistance dictate specification authority.
The US Department of Energy's Better Plants program and EPA energy-efficiency guidelines shape domestic retrofit incentives, while EU Ecodesign requirements and F-Gas Regulation enforcement drive replacement demand across member-state industrial clusters. Japan's METI energy-conservation standards and China's GB/T national efficiency codes add compliance layers for multinational facility operators sourcing across manufacturing footprints. Stakeholders must monitor how carbon-border adjustment mechanisms and evolving efficiency benchmarks reshape total-cost-of-ownership calculations against initial equipment outlays.
Market Dynamics
Binding carbon-reduction mandates across German industrial clusters are compressing replacement cycles for aging boiler infrastructure, forcing facility operators to prioritize thermal efficiency upgrades over extended equipment lifecycles.
Growth Catalysts
- EU F-Gas Regulation:Enforcement of fluorinated gas phase-down schedules accelerates steam system retrofits across member-state chemical processing facilities seeking compliance credits.
- Mechanical trap reliability metrics:Float and inverted-bucket configurations dominate utility procurement specifications where unplanned downtime costs override capital expenditure thresholds.
- German industrial clusters:Binding national climate law targets concentrate replacement demand in Rhine-Ruhr and Bavarian manufacturing corridors with 2030 emission benchmarks.
Market Restraints
- Stainless steel input volatility:Grade 316L price swings compress margin pools for food-grade and pharmaceutical trap manufacturers dependent on surface-finish certification.
- Supply concentration in East Asian foundries:Casting capacity for high-pressure trap bodies clusters in specific Chinese and South Korean metallurgical zones, creating geographic vulnerability.
- Technical limitation in ultra-high-pressure applications:Thermodynamic trap designs face reliability thresholds above 150 bar where mechanical alternatives retain specification authority.
Strategic Opportunities
- India's PLI scheme for capital goods:Domestic manufacturing incentives create localized assembly opportunities for mid-pressure trap variants serving process industries.
- Digital monitoring convergence:Integration of wireless acoustic sensors with legacy mechanical traps opens predictive maintenance revenue streams without full system replacement.
- Offshore platform compact skids:Space-constrained North Sea and Gulf of Mexico installations favor thermodynamic trap configurations with simplified maintenance protocols.
Industry Challenges
- Certified welder scarcity:ASME Section IX-qualified technicians for high-pressure trap repair face demographic retirement waves across US Gulf Coast refining corridors.
- Legacy DCS integration complexity:Digital trap monitoring systems require protocol translation layers for 1980s-era distributed control architectures still operating in mature chemical plants.
- Extended factory acceptance testing:Pharmaceutical-grade surface-finish validation adds 8-14 week lead times to stainless steel trap deliveries, compressing project scheduling flexibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Steam Trap Market |
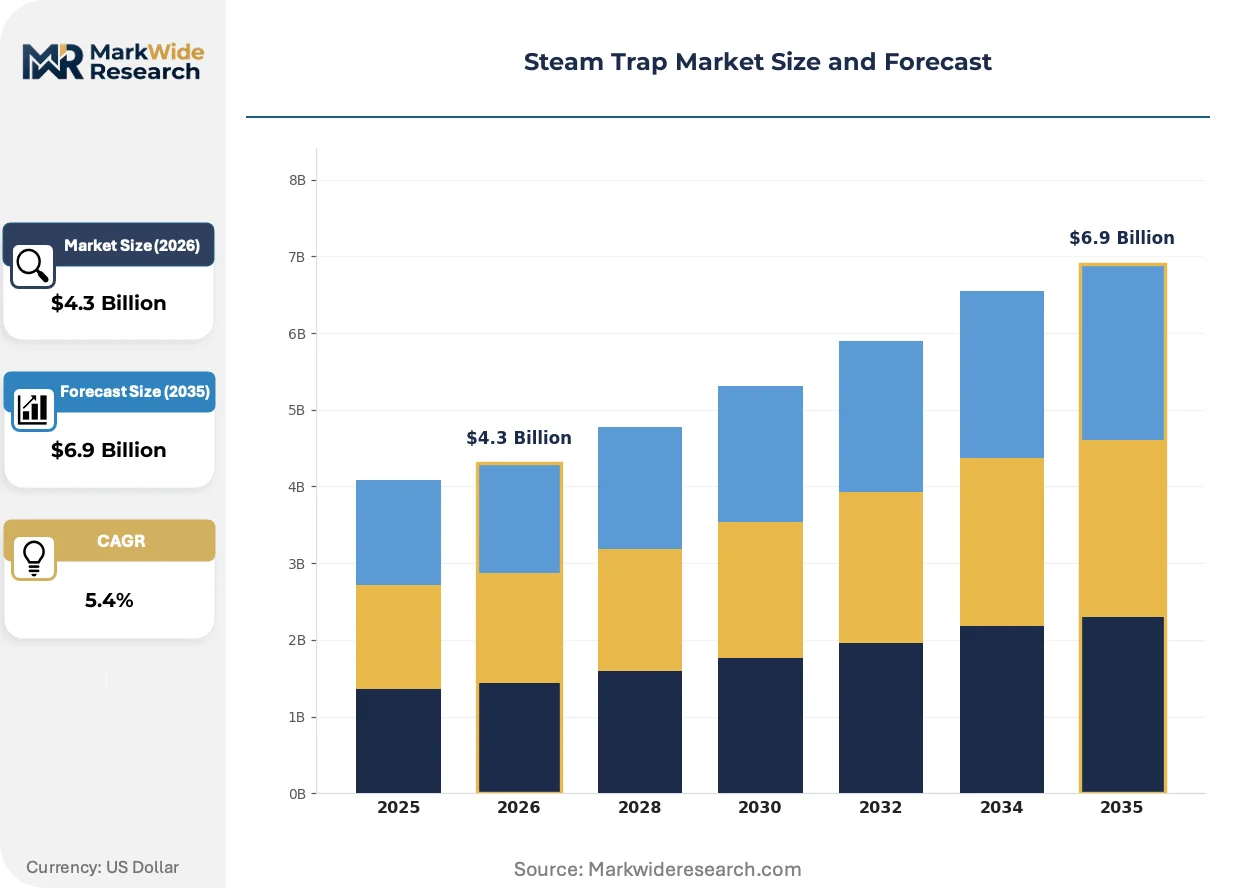
| Market Size in 2026 | $4.3 Billion |
| Market Size in 2035 | $6.9 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thermodynamic Traps, Mechanical Traps, Float Traps, Bucket Traps End User: Food Processing, Textile, Power Generation, Chemical Processing Installation Type: Onshore, Offshore, Industrial, Commercial Material: Cast Iron, Stainless Steel, Carbon Steel, Bronze |
| Companies Covered | Spirax Group plc, Emerson Electric Co., Armstrong International Inc., TLV Co., Ltd., Thermax Limited, Velan Inc., Watts Water Technologies Inc., Forbes Marshall Pvt. Ltd., SLB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Steam Trap Market Strategic Shifts & Innovations
Steam trap architecture is bifurcating between embedded intelligence layers and stripped-down mechanical reliability, with specification authority shifting from maintenance departments to energy-management offices.
Acoustic emission monitoring is collapsing the traditional inspection interval for mechanical trap failure detection. Refinery operators in the US Gulf Coast deploy permanently mounted sensors transmitting ultrasonic signatures to centralized reliability dashboards. This capability compresses steam loss detection from quarterly manual surveys to real-time alerts, enabling condition-based replacement rather than calendar-driven maintenance.
Japan's METI energy-conservation standards now mandate documented steam system efficiency audits for designated manufacturing facilities above thermal consumption thresholds. Compliance requires installed base surveys identifying failed or leaking traps, with penalty structures for uncorrected deficiencies. Chemical processors in Kansai and Chukyo industrial zones accelerate replacement programs to avoid surcharge exposure under the 2024 enforcement schedule.
Service contract unbundling disrupts traditional captive maintenance relationships in European process industries. End-users separately procure trap hardware, installation, and predictive monitoring from distinct vendors rather than accepting bundled OEM service agreements. German chemical clusters in Ludwigshafen and Leverkusen pioneer this fragmentation, using competitive tendering for each value-chain segment to compress total cost of ownership.
Steam Trap Market Segmentation
Steam trap specification authority shifts between maintenance departments and energy-management offices depending on segment characteristics. Material selection and product architecture determine aftermarket service intensity, creating divergent margin profiles across replacement cycles.
Product Type:
Aftermarket service intensity varies sharply across trap architectures, with mechanical designs demanding scheduled inspection protocols while thermodynamic variants minimize field intervention.
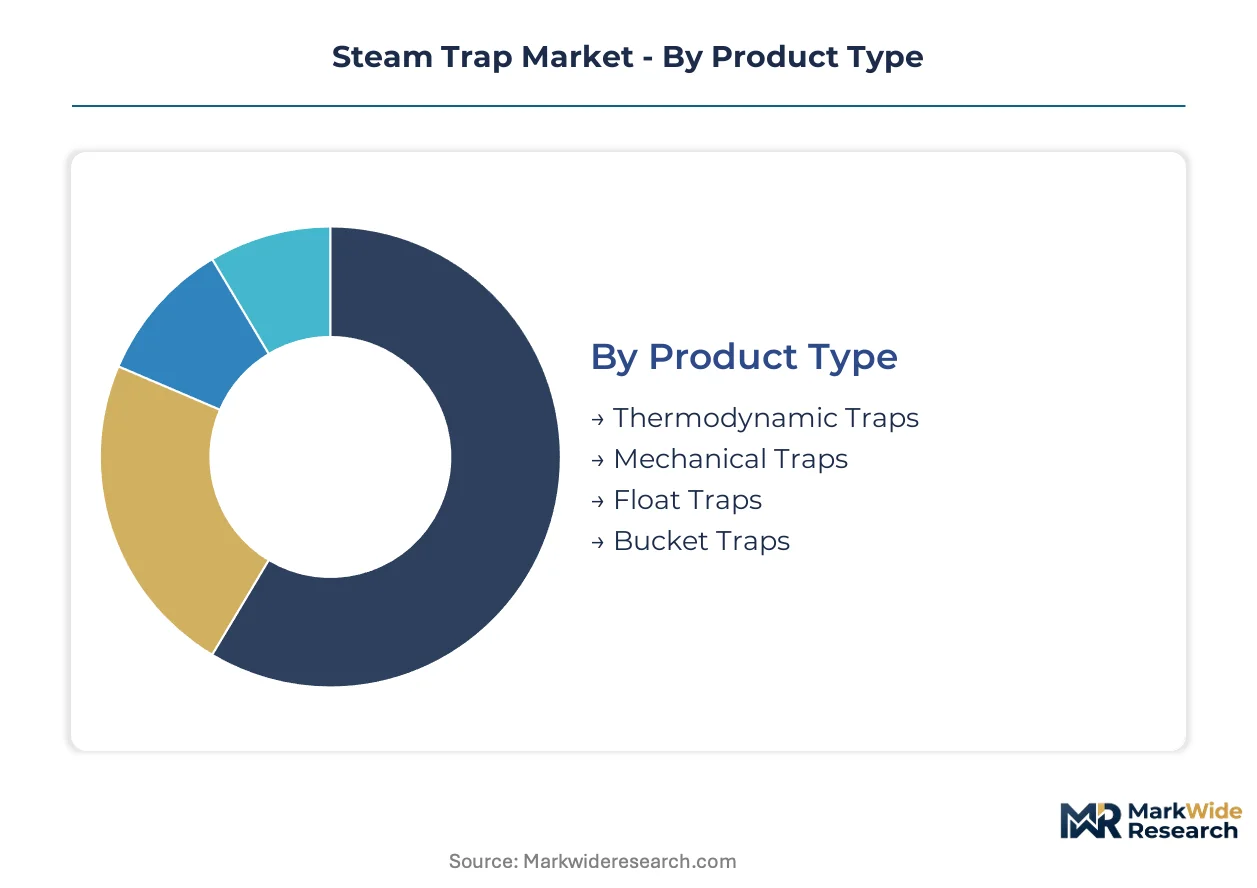
- Thermodynamic Traps:Compact disc-based designs operate through pressure-velocity dynamics without moving parts, eliminating wear-prone components. Chemical processing facilities in the US Gulf Coast specify these for offshore platform skids where maintenance access is restricted and space constraints command premium positioning. Thermodynamic traps are expanding most quickly.
- Mechanical Traps:Float and inverted-bucket mechanisms leverage buoyancy and mechanical leverage to discharge condensate with precise temperature tracking. German power utilities prioritize these configurations for continuous-process boiler circuits where unplanned downtime costs override capital expenditure thresholds. By volume, mechanical traps lead.
- Float Traps:Ball-float mechanisms modulate discharge through rising condensate levels, dominating food processing applications requiring steady condensate removal without live steam loss.
- Bucket Traps:Inverted-bucket designs tolerate high pressure differentials and aggressive condensate conditions, concentrating in refinery and petrochemical steam headers.
By volume, mechanical traps lead. By growth pace, thermodynamic traps are ahead.
End User:
End-use concentration maps directly to regulatory enforcement intensity, with carbon-reduction mandates compressing replacement cycles in emissions-intensive sectors.
- Power Generation:Central station boilers and combined-cycle plants operate continuous steam circuits where trap failure triggers immediate efficiency penalties. US utilities under EPA guidelines accelerate inspection frequencies across aging coal and gas-fired infrastructure.
- Chemical Processing:Process steam networks face EU F-Gas Regulation compliance deadlines, forcing facility operators in German industrial clusters to prioritize thermal efficiency upgrades over extended equipment lifecycles.
- Food Processing:Sanitary steam applications demand stainless steel construction with surface-finish certification, extending lead times and concentrating procurement among qualified suppliers.
- Textile:Dyeing and finishing operations consume substantial process steam, with Asian manufacturing hubs driving volume demand for standard-grade cast iron traps.
Power generation commands the largest installed base. Chemical processing shows the steepest replacement acceleration.
Installation Type:
Installation environment dictates material specification and maintenance protocol complexity, with offshore applications commanding specialized corrosion-resistant designs.
- Offshore:North Sea and Gulf of Mexico platforms require compact skid-mounted systems with simplified maintenance access, favoring thermodynamic configurations and premium metallurgy to withstand salt-laden atmospheres.
- Onshore:Refinery and petrochemical complexes along the US Gulf Coast and in German Rhine-Ruhr corridors represent mature demand centers with established maintenance infrastructures.
- Industrial:Manufacturing facilities across process industries constitute the volume core, with replacement cycles tied to energy audit findings and efficiency incentive programs.
- Commercial:District heating and institutional boiler systems operate at lower pressures with less critical uptime requirements, concentrating demand for standard-grade mechanical traps.
Onshore installations dominate current revenue. Offshore applications generate the highest unit margins.
Material:
Material selection governs corrosion resistance, pressure rating, and surface-finish compliance, creating tiered pricing structures across application requirements.
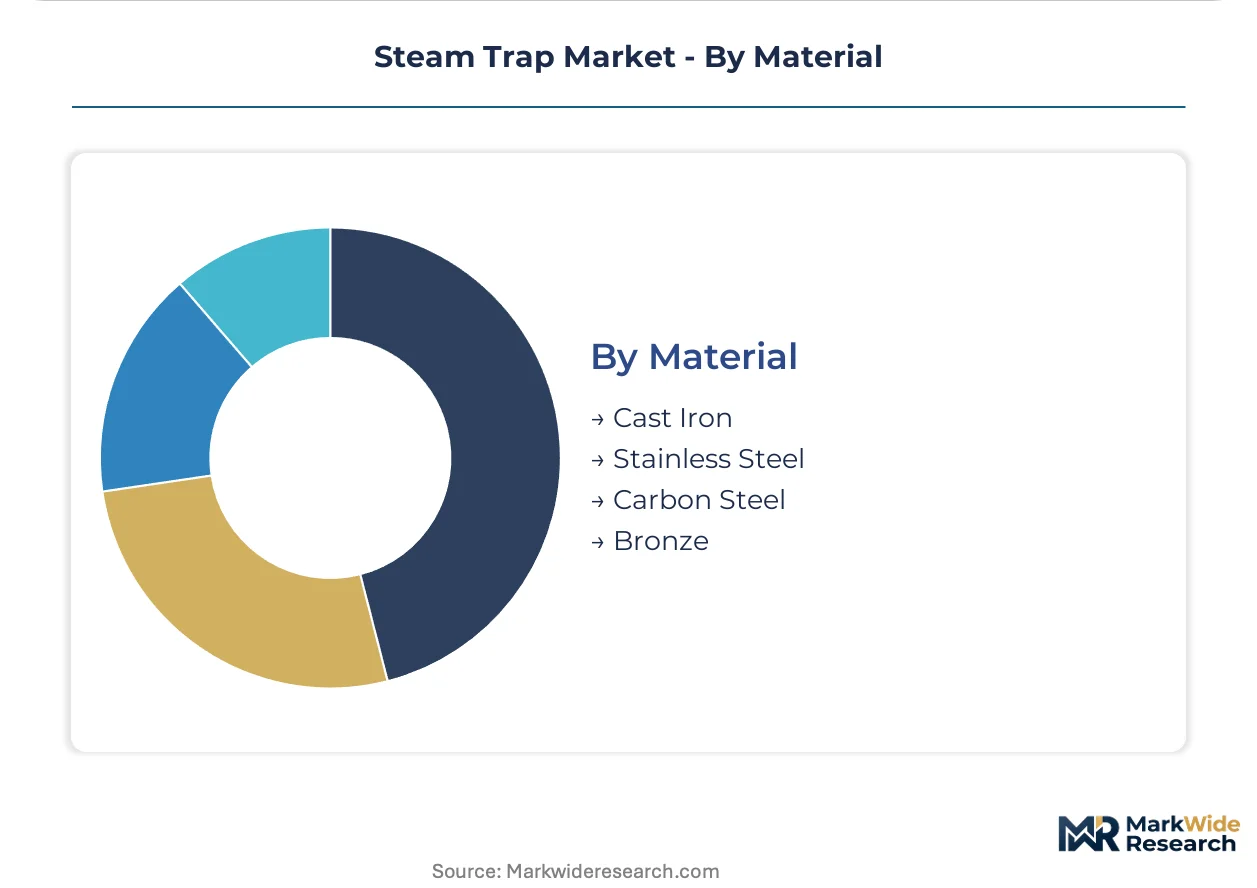
- Stainless Steel:Grade 316L and 304 variants satisfy pharmaceutical and food-grade surface-finish standards, with price volatility compressing margin pools for certified manufacturers.
- Carbon Steel:Standard-grade construction dominates utility and general industrial applications where cost efficiency outweighs corrosion resistance requirements.
- Cast Iron:Traditional material for low-pressure steam systems in textile and commercial heating applications, with supply concentrating in East Asian foundries.
- Bronze:Naval brass and bronze alloys serve marine and coastal installations requiring superior salt-water corrosion resistance.
Carbon steel accounts for the greatest tonnage. Stainless steel captures the highest value per unit.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU F-Gas Regulation enforcement and national carbon-reduction mandates are compressing replacement cycles across industrial clusters. Facility operators prioritize thermal efficiency upgrades to avoid penalty exposure under binding emission benchmarks.
Germany
Rhine-Ruhr and Bavarian manufacturing corridors face 2030 emission benchmarks under national climate law. The EU Ecodesign Directive drives specification upgrades across chemical processing facilities in Ludwigshafen and Leverkusen. German industrial clusters concentrate replacement demand for mechanical trap configurations in continuous-process boiler circuits.
United States
US Gulf Coast refineries accelerate inspection frequencies under EPA energy-efficiency guidelines. The Department of Energy's Better Plants program shapes domestic retrofit incentives for aging coal and gas-fired infrastructure. Houston and Beaumont petrochemical complexes represent mature demand centers with established maintenance infrastructures.
Japan
METI energy-conservation standards mandate documented steam system efficiency audits for designated manufacturing facilities. Kansai and Chukyo industrial zones accelerate replacement programs to avoid surcharge exposure under 2024 enforcement schedules. Osaka-based chemical processors prioritize compliance-driven thermal system upgrades.
China
GB/T national efficiency codes add compliance layers for multinational facility operators sourcing across manufacturing footprints. Yangtze River Delta industrial zones drive volume demand for standard-grade cast iron traps in textile and dyeing operations. Shanghai and Jiangsu process industries face dual carbon goal pressure through provincial implementation frameworks.
India
The PLI scheme for capital goods creates localized assembly opportunities for mid-pressure trap variants. Maharashtra and Gujarat process industries expand steam infrastructure under domestic manufacturing incentives. Mumbai and Ahmedabad industrial corridors represent emerging demand centers for thermodynamic trap configurations in compact skid-mounted systems.
Steam Trap Market Key Industry Players
Channel-controlling players compete with product-specialist players across fragmented procurement patterns in mid-sized industrial facilities. Spirax Group plc anchors long-term maintenance contracts through captive service networks in European process industries. Emerson Electric Co. extends digital monitoring capabilities into legacy plant infrastructure through instrumentation-integrated designs. Strategic moves concentrate on service contract unbundling and predictive maintenance technology licensing rather than capacity expansion.
Within the instrumentation-integrated tier, Emerson Electric Co. occupies a position exemplifying digital convergence with legacy mechanical systems. Spirax Group plc represents the service-network archetype, anchoring bundled maintenance relationships. TLV Co., Ltd. and Armstrong International Inc. sit within the reliability-specialist category, occupying positions tied to float and inverted-bucket configuration authority in utility procurement specifications.
| Leading Market Players |
|---|
| Spirax Group plc |
| Emerson Electric Co. |
| Armstrong International Inc. |
| TLV Co., Ltd. |
| Thermax Limited |
| Velan Inc. |
| Watts Water Technologies Inc. |
| Forbes Marshall Pvt. Ltd. |
| SLB |
| Others |
Cost & Logistics Intelligence
Jiangsu Province foundry capacity for Grade 316L stainless steel casting sets the baseline for pharmaceutical-grade trap pricing, with Yangtze River Delta metallurgical output fluctuations transmitting directly to European food-processing procurement budgets.
Pricing Analysis
Certification level creates the primary spread between economy and premium tiers, with ASME Section IX weld qualification and pharmaceutical surface-finish standards commanding substantial premiums over standard industrial grades. Three-tier pricing structure across premium, standard, and economy levels reflects material grade, after-sales service bundling, and geographic delivery cost differentials. Cost compression in standard carbon steel segments is intensifying because East Asian foundry overcapacity floods commodity trap markets. Textile processors in Bangladesh and Vietnam exhibit highest price sensitivity, while German chemical clusters under binding emission mandates show lowest sensitivity due to penalty avoidance calculus.
Supply Chain Analysis
Extended payment terms from 60 to 90 days now dominate procurement negotiations, with supply-chain finance facilities bridging working capital gaps for mid-tier foundries. Casting capacity clusters in China, South Korea, and India, with high-pressure body forging drawing from specialized metallurgical zones in each geography. Raw material dependencies rest on nickel ore sourcing, chromium alloy supply, and energy-intensive heat treatment capacity. Single-source vulnerability concentrates in ASME-certified welding consumables. Distribution runs through OEM captive service networks, industrial distributors, and direct specification sales to EPC contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Steam trap demand tracks industrial capital expenditure cycles, with aging boiler infrastructure replacement and regulatory compliance deadlines creating sustained recovery momentum across process industries.
For Market Incumbents: Build predictive maintenance data moats through acoustic sensor integration and cloud-based trap monitoring platforms. Deepen backward integration into stainless steel casting to insulate margin pools from Grade 316L price volatility. Anchor long-term service contracts in German industrial clusters facing 2030 emission benchmarks, locking out instrumentation competitors through bundled hardware-software offerings. For New Entrants and Emerging Players: Establish a beachhead in India's PLI-subsidized domestic assembly market for mid-pressure thermodynamic variants. Target offshore platform compact skid applications in the Gulf of Mexico where simplified maintenance protocols command premium positioning and incumbent service networks offer weaker coverage. Pursue white-label manufacturing partnerships with European distributors seeking alternatives to captive OEM supply agreements. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors instrumentation-integrated trap specialists with proven legacy DCS protocol translation capabilities. Five-to-ten year viability hinges on digital monitoring convergence rather than pure mechanical reliability plays. Monitor ASME Section IX welder demographic trends as inflection indicator for aftermarket service scarcity premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Stainless Casting | Captive Grade 316L supply secures pharmaceutical certification authority against raw material volatility. |
| Acoustic Sensor Platform Development | Real-time condensate detection collapses inspection intervals for US Gulf Coast refinery operators. |
| PLI Scheme Domestic Assembly | Localized Maharashtra production qualifies for Indian capital goods incentives serving process industries. |
| ASME Welder Training Pipeline Investment | Certified technician scarcity in US refining corridors creates captive repair revenue lock-in. |
| Legacy DCS Protocol Translation Layer | 1980s-era distributed control integration opens digital monitoring penetration in mature chemical plants. |
Research Approach
Findings reconcile primary fieldwork against secondary review of trade customs data, SEC manufacturing disclosures, and national energy-efficiency program documentation. Interviews with maintenance directors at process facilities, OEM procurement teams, and aftermarket service heads informed operational assumptions. Secondary validation drew from EPA Better Plants program filings, EU Ecodesign Directive implementation reports, and METI energy audit compliance databases. Bottom-up installed base estimates triangulated against top-down capital expenditure projections across power generation, chemical processing, and food manufacturing verticals.
Forecast inputs include product type substitution rates, material grade demand shifts, and regulatory enforcement intensity across German, US, and Japanese industrial clusters. Segmentation dimensions encompass trap architecture, end-use industry, installation environment, and material specification tier. CAGRs were derived from replacement cycle compression analysis and efficiency incentive program scaling. Industry-specific inputs incorporate carbon-border adjustment mechanism evolution and certified welder demographic trajectories.
Stress conditions across stainless steel price volatility, regulatory deadline delays, and offshore platform investment cycles were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding emission benchmark stringency and energy audit enforcement schedules. Macroeconomic contraction, regulatory rollback, or breakthrough trapless condensate removal technology would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Valves
Blasting Stemming Plugs Market
Valves
Magnetic Coupler Market
Valves
Transmission Overload Protectors Market
Valves
Off-Highway Hydraulic Valve Actuator Systems Market
Valves
Pneumatic Needle Valves Market
Valves
Compressor Valves Market
Valves
HVAC Valves Market
Valves
Blow - Off Valves Market
Valves
Pneumatic Slide Gates Market
Valves
Butterfly Valves Market
Valves
Global Gate Valve Market
Valves
Pipeline Integrity Management (PIM) Market
Valves
Christmas Tree Valves Market
Valves
Battery Pack Cooling Valve Actuator Systems Market
Valves
Industrial Hydraulic Filters Market
Valves
Pipeline and Process Services Market