
 United States Clean Coal Technologies Market | 2026-2036
United States Clean Coal Technologies Market Size, Share, and Industry Trends Forecast 2026-2036
United States Clean Coal Technologies Market Intelligence
A specialized workforce of carbon capture engineers and gasification process operators is reorganizing deployment timelines across the United States Clean Coal Technologies Market. General Electric Company leverages its turbine integration expertise to anchor carbon capture retrofit projects at legacy coal facilities. Babcock and Wilcox Enterprises Inc. sustains its position through specialized boiler and environmental equipment manufacturing for utility-scale installations. Siemens Energy competes on advanced gasification system design, extending its technology portfolio into integrated polygeneration configurations.
Clean coal technologies encompass systems that reduce sulfur dioxide, nitrogen oxides, particulate matter, and carbon dioxide emissions from coal combustion through flue gas desulfurization, selective catalytic reduction, electrostatic precipitation, and post-combustion carbon capture processes. These systems typically operate at combustion temperatures between 1300°C and 1500°C while capturing 90% or more of targeted pollutants to meet stationary source emission limits. Carbon Capture technology leads investment flows as utilities face incremental compliance obligations under federal performance standards. Gasification segments attract concentrated R&D spending due to higher efficiency potential and polygeneration flexibility. Power Generation applications dominate current deployment, though Industrial Processes represent the fastest-growing demand channel as manufacturing facilities seek on-site emission reductions.
The EPA greenhouse gas performance standards and the Department of Energy's carbon management programs shape technology qualification and project finance access for clean coal deployments. FERC interconnection and rate recovery rulings determine whether captured carbon infrastructure achieves commercial scale across regulated utility territories. OSHA process safety mandates and state-level air quality implementation plans add layered compliance complexity for facility operators. Stakeholders must monitor pending federal carbon accounting rules and regional transmission organization capacity market reforms that will determine retrofit economics.
Market Dynamics
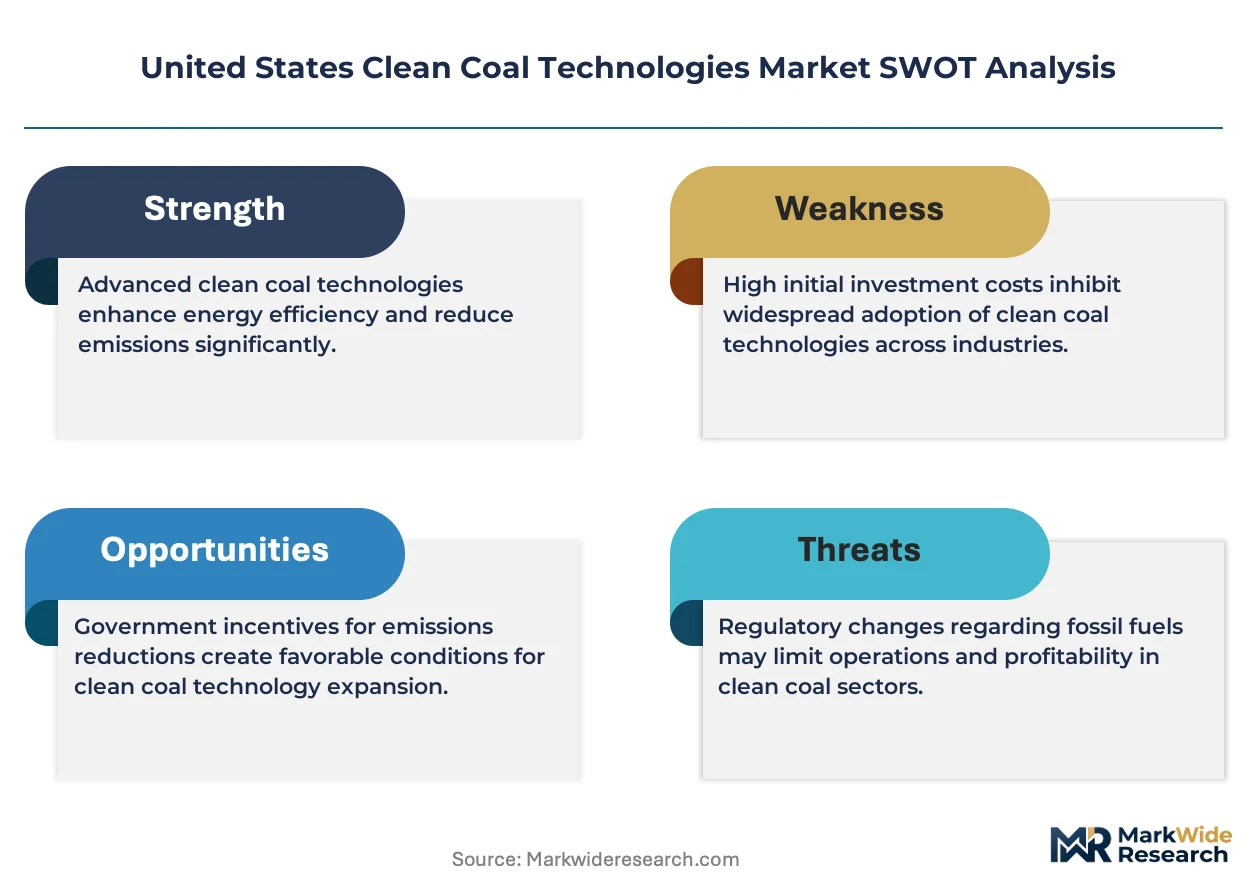
The EPA's revised greenhouse gas performance standards for power plants are compressing deployment timelines for carbon capture retrofits at existing coal-fired baseload facilities across the United States. Electric utilities now face binding compliance obligations that restructure capital allocation toward emission control systems rather than plant retirement decisions.
Growth Catalysts
- IRA Carbon Capture Tax Credits:The Inflation Reduction Act's enhanced Section 45Q incentives reduce project payback periods for post-combustion capture installations at utility-scale generators.
- Powder River Basin Grid Embeddedness:Wyoming and Montana coal plants remain structurally essential to regional transmission organization capacity markets, preserving retrofit economics against renewable displacement.
- Gasification R&D Concentration:Department of Energy carbon management programs direct federal funding toward integrated polygeneration systems with higher efficiency potential than conventional combustion.
Market Restraints
- Amine Solvent Cost Volatility:Post-combustion carbon capture depends on proprietary chemical absorbents whose pricing fluctuates with petrochemical feedstock markets.
- Specialized Equipment Supply Concentration:Fabrication of large-scale gasification reactors and advanced turbine integrations concentrates among a limited supplier base in the Ohio River Valley manufacturing corridor.
- FERC Rate Recovery Uncertainty:Interconnection rulings and cost-of-service determinations for captured carbon infrastructure create regulatory friction that delays utility investment commitments.
Strategic Opportunities
- Industrial Process On-Site Capture:Cement and steel manufacturing facilities in the Gulf Coast petrochemical corridor represent underpenetrated demand for modular pre-combustion systems.
- EPA Performance Standard Compliance Deadlines:The 2028-2030 implementation window for revised power plant rules creates a regulatory tailwind for engineering procurement construction contracts.
- Carbon Capture-Enhanced Oil Recovery Convergence:Pipeline networks connecting capture facilities to Permian Basin CO2-flood operations unlock revenue stacking beyond tax credit monetization.
Industry Challenges
- Carbon Capture Engineer Scarcity:The specialized workforce required for solvent system design and gasification process operation remains insufficient to meet compressed deployment schedules.
- Legacy Boiler Integration Complexity:Retrofitting post-combustion capture trains onto subcritical and supercritical units built in the 1970s-1990s requires extensive heat integration redesign.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Clean Coal Technologies Market |
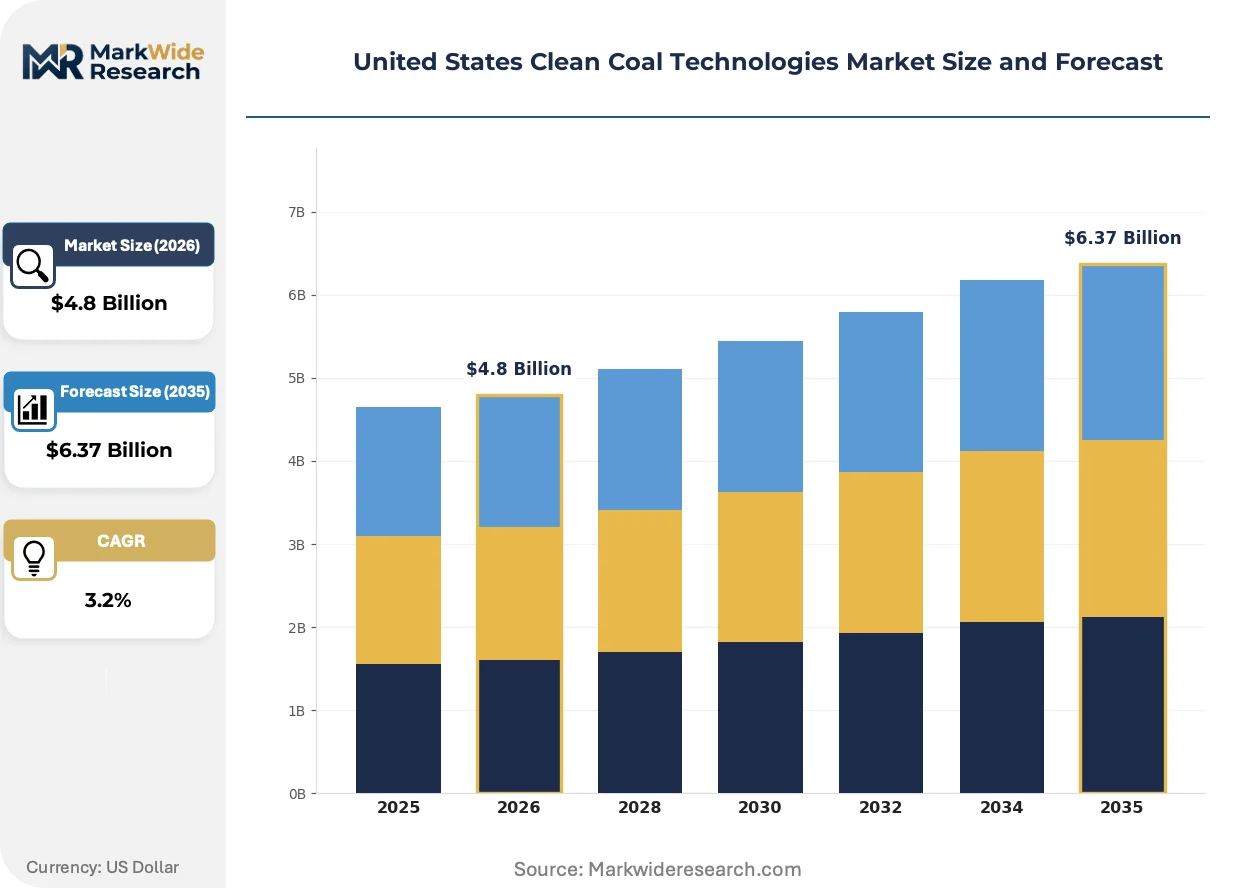
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.37 Billion |
| CAGR (2026 – 2036) | 3.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Carbon Capture, Gasification, Clean Combustion, Integrated Gasification Application: Power Generation, Industrial Processes, Carbon Trading, Environmental Compliance End User: Utilities, Manufacturers, Energy Providers, Government Agencies Solution: Consulting Services, Equipment Supply, Maintenance Services, Training Programs |
| Companies Covered | Clean Coal Technologies Inc., General Electric Company, Babcock and Wilcox Enterprises Inc., Siemens Energy, ExxonMobil, Shell, GreatPoint Energy, Duke Energy Corporation, JES Energy, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Clean Coal Technologies Market Strategic Shifts & Innovations
Technology trajectories in the United States Clean Coal Technologies Market center on modular system architectures that reduce project-specific engineering requirements and accelerate deployment velocity. These shifts compress the traditional utility procurement cycle while expanding addressable facility types.
Solid sorbent carbon capture is decomposing the market dominance of liquid amine absorption systems. Developers including utility engineering departments and independent power producers are piloting metal-organic framework and zeolite-based capture units at 10-50 MW slipstream demonstrations. This technology is decomposing the scale threshold for economic capture, enabling smaller industrial boilers and combined heat and power plants to achieve cost-effective emission reductions previously reserved for baseload generators above 500 MW.
The EPA's greenhouse gas performance standards for existing fossil fuel-fired electric generating units are mandating emission rate reductions that effectively require carbon capture or co-firing at affected facilities. Coal plant operators must evaluate retrofit compliance against retirement alternatives under state implementation plan timelines. The Powder River Basin and Appalachian coal corridors face the most concentrated compliance pressure, with state environmental agencies scrambling to align permitting processes with federal deadlines.
Utility procurement departments are unbundling engineering-procurement-construction contracts for carbon capture retrofits from traditional turbine and boiler supplier relationships. Integrated EPC consortia with process technology specialization are displacing incumbent power equipment vendors in competitive solicitations. This reconfiguration is most visible in regulated utility territories where state public utility commissions scrutinize cost recovery for non-traditional supplier selections.
United States Clean Coal Technologies Market Segmentation
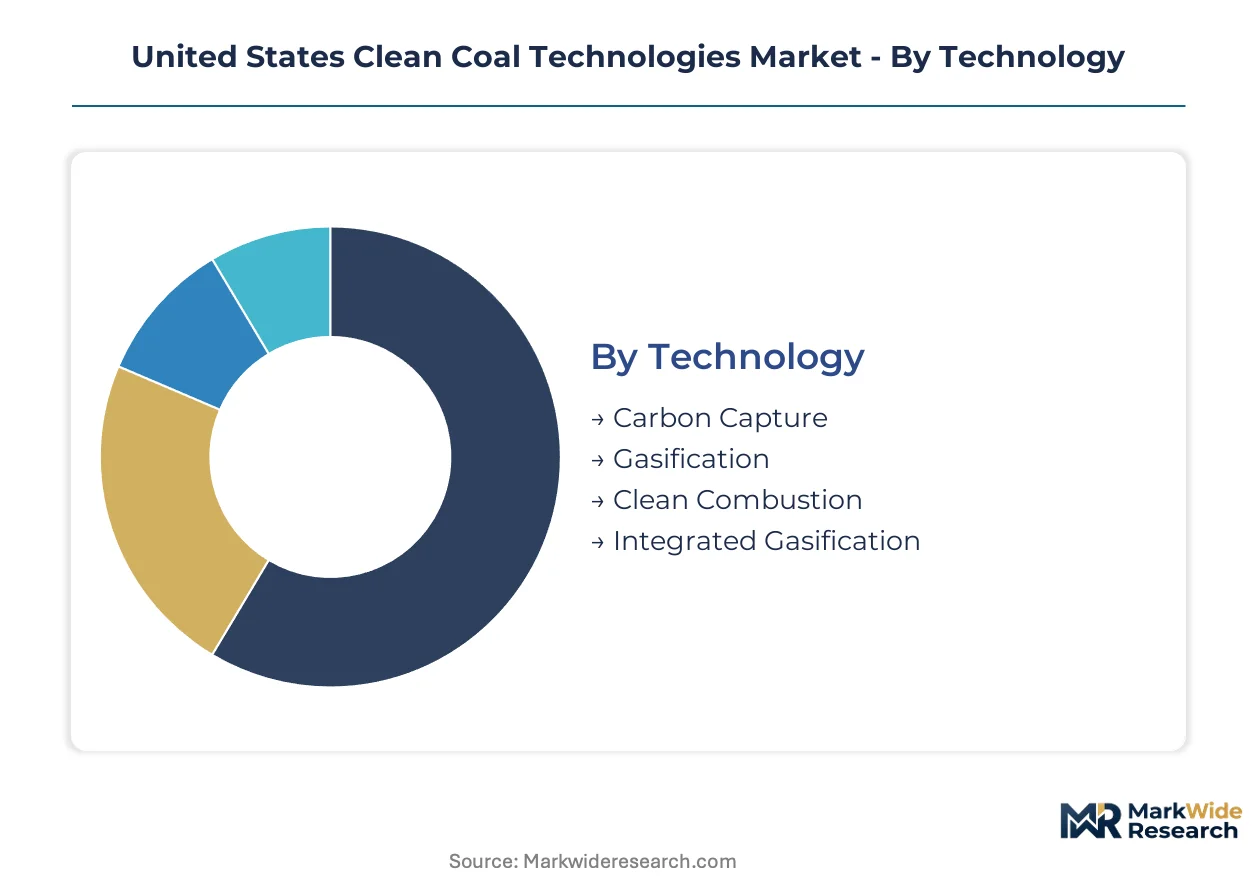
Clean coal technology deployment patterns diverge sharply across technology maturity, end-use economics, and procurement complexity. Segment boundaries determine capital allocation timelines, regulatory compliance pathways, and supplier specialization requirements for project developers and equipment vendors.
Technology:
Domestic deployment concentrates in post-combustion retrofits at existing baseload facilities, while gasification systems draw export-oriented engineering services to overseas markets.
- Carbon Capture:Post-combustion solvent absorption and solid sorbent systems strip CO2 from flue gas streams at 90%+ capture rates. Demand clusters at Powder River Basin coal plants where EPA performance standards mandate emission reductions and IRA Section 45Q credits improve project returns.
- Gasification:High-pressure partial oxidation converts coal into synthesis gas for power generation or chemical feedstock production. R&D spending concentrates at Department of Energy carbon management program sites, with integrated polygeneration configurations attracting federal demonstration funding.
- Clean Combustion:Advanced burner designs and combustion optimization reduce NOx and particulate formation without downstream scrubbing.
- Integrated Gasification:Combined-cycle configurations merge gasification with turbine generation for efficiency gains above conventional pulverized coal units.
Carbon Capture commands the established base. The steepest expansion runs through Gasification.
Application:
Cost tier segmentation separates billion-dollar utility retrofits from modular industrial installations with sub-50 MW thermal footprints.
- Power Generation:Utility-scale retrofits at coal-fired baseload plants above 500 MW capacity dominate capital deployment. Wyoming and Montana facilities face compressed compliance timelines under EPA greenhouse gas performance standards.
- Industrial Processes:Cement kilns and steel furnaces in the Gulf Coast petrochemical corridor adopt pre-combustion capture for on-site emission reductions. Manufacturing facilities seek smaller-scale solutions bypassing utility interconnection queues.
- Carbon Trading:Compliance offset generation and voluntary credit monetization create secondary revenue streams for capture project developers.
- Environmental Compliance:Stationary source permitting requirements drive scrubber and selective catalytic reduction installations at legacy facilities.
Power Generation absorbs the majority of current capital. Industrial Processes are climbing the fastest as manufacturing decarbonization accelerates.
End User:
Customer type determines procurement sophistication, with regulated utilities navigating rate recovery proceedings while industrial offtakers pursue merchant structures.
- Utilities:Investor-owned and public power entities dominate carbon capture retrofit procurement, with state public utility commissions scrutinizing cost-of-service treatment for captured carbon infrastructure.
- Manufacturers:Energy-intensive industrial facilities seek behind-the-meter capture systems to manage scope 1 emission liabilities.
- Energy Providers:Independent power producers and retail energy suppliers evaluate co-firing and capture options for merchant generation assets.
- Government Agencies:Federal and state entities fund demonstration projects and operate directly owned generation facilities subject to executive order emission targets.
Utilities anchor the current installed base. Manufacturers show the steepest adoption curve as industrial climate obligations tighten.
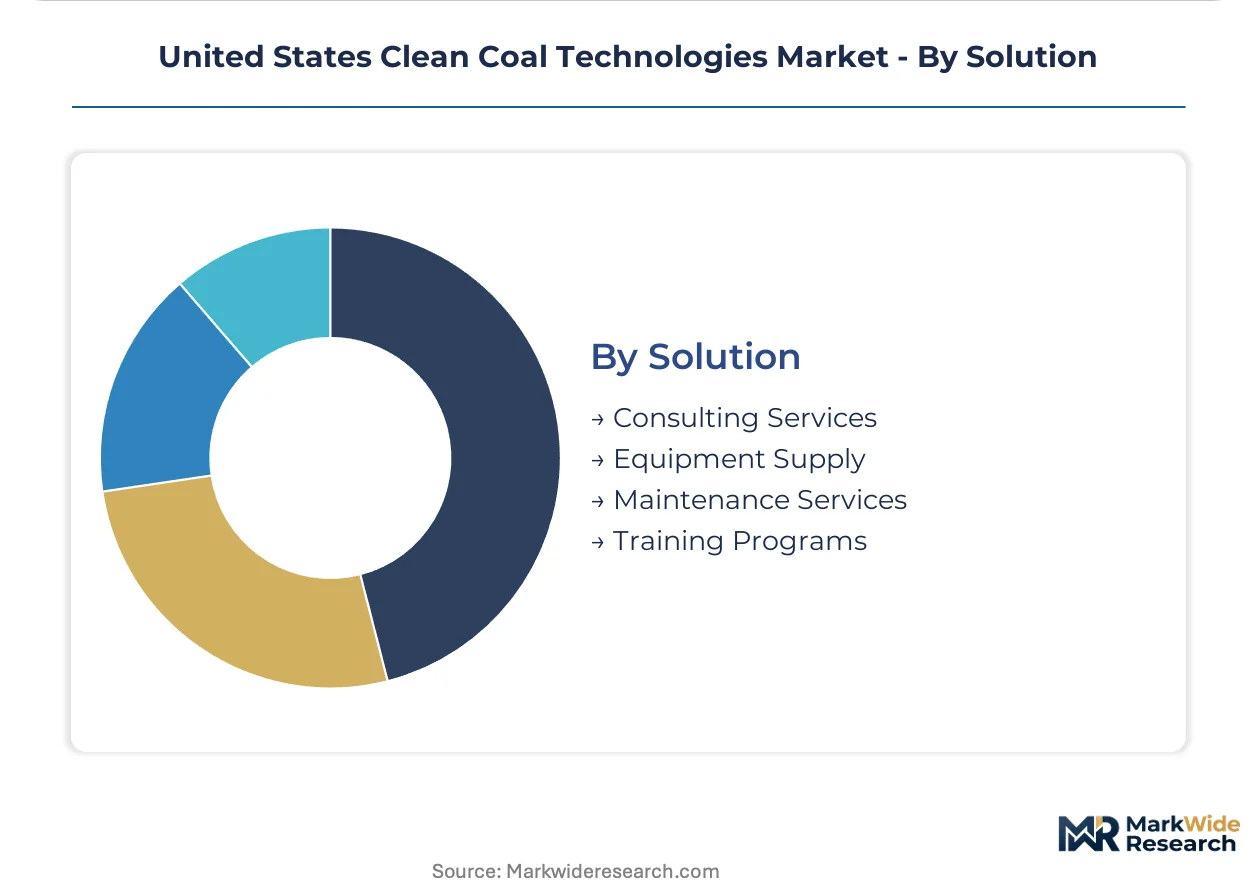
Solution:
Supply concentration varies by service type, with equipment fabrication limited to Ohio River Valley manufacturing corridors while consulting and training services fragment nationally.
- Consulting Services:Engineering feasibility studies, permitting support, and technology selection advisory for project developers navigating EPA and FERC compliance requirements.
- Equipment Supply:Fabrication of gasification reactors, solvent absorption trains, and turbine integration hardware concentrates among specialized suppliers with legacy power sector relationships.
- Maintenance Services:Post-commissioning solvent management, catalyst replacement, and system optimization contracts extend across multi-decade asset lifecycles.
- Training Programs:Workforce development for carbon capture engineers and gasification process operators addresses specialized labor scarcity compressing deployment timelines.
Equipment Supply captures the dominant revenue share. Training Programs are expanding most quickly as workforce constraints intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Powder River Basin states deploy carbon capture retrofits at utility scale, while Appalachian corridors favor gasification R&D and Gulf Coast industrial clusters pursue modular pre-combustion systems for cement and steel applications.
Powder River Basin
Wyoming and Montana coal plants anchor regional grid capacity, preserving retrofit economics against renewable displacement. EPA greenhouse gas performance standards compress compliance timelines for facilities above 500 MW. Basin Electric Power Cooperative and NorthWestern Energy evaluate post-combustion capture trains at multiple Gillette-area stations.
Appalachian Coal Corridor
West Virginia and Kentucky operators confront mine-mouth plant retirement decisions versus carbon capture conversion. Department of Energy carbon management programs direct demonstration funding toward integrated polygeneration pilots. The National Energy Technology Laboratory near Pittsburgh anchors federal R&D coordination with regional utilities.
Texas Gulf Coast
Petrochemical manufacturers seek behind-the-meter capture for refinery and chemical complex emissions. Pipeline networks connecting capture facilities to Permian Basin CO2-flood operations unlock revenue stacking beyond IRA Section 45Q tax credits. Houston and Port Arthur industrial clusters host slipstream demonstrations of solid sorbent systems.
Ohio River Valley
Legacy supercritical units built during the 1970s-1990s require extensive heat integration redesign for capture retrofit compatibility. FERC rate recovery proceedings determine cost-of-service treatment for captured carbon infrastructure across regulated utility territories. Cincinnati and Louisville manufacturing corridors concentrate specialized fabrication capacity for gasification reactors.
Southwest Industrial Belt
Arizona and New Mexico utilities evaluate co-firing and capture options for remaining coal assets under state implementation plan timelines. Regional transmission organization capacity market reforms determine whether retrofit investments outcompete renewable plus storage configurations. The Four Corners Power Plant near Farmington represents a concentrated compliance pressure point.
United States Clean Coal Technologies Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, with turbine integrators and boiler fabricators commanding premium positions in utility-scale retrofits while process technology boutiques capture modular industrial applications. The market structure reflects supply concentration in the Ohio River Valley manufacturing corridor, where fabrication of large-scale gasification reactors and advanced turbine integrations concentrates among legacy power sector suppliers. Two strategic archetypes dominate: integrated equipment vendors with captive EPC capabilities, and pure-play carbon capture technology licensors seeking utility partnerships. Competitive moves center on unbundling traditional supplier relationships and forming integrated EPC consortia with process specialization.
Among diversified energy conglomerates, General Electric Company and Siemens Energy occupy positions anchoring turbine integration and advanced gasification system design respectively. Babcock and Wilcox Enterprises Inc. exemplifies the specialized boiler and environmental equipment archetype sustaining relevance through utility-scale fabrication relationships. These three entities represent distinct competitive vectors: power equipment incumbency, European technology licensing, and domestic environmental engineering heritage.
| Leading Market Players |
|---|
| Clean Coal Technologies Inc. |
| General Electric Company |
| Babcock and Wilcox Enterprises Inc. |
| Siemens Energy |
| ExxonMobil |
| Shell |
| GreatPoint Energy |
| Duke Energy Corporation |
| JES Energy |
| Others |
Cost & Logistics Intelligence
Capacity utilization at Ohio River Valley fabrication facilities for gasification reactors and turbine integration hardware sets price floors for utility-scale carbon capture retrofits. Scale advantages among incumbent boiler and environmental equipment manufacturers concentrate supply-side pricing power, while compressed EPA compliance timelines force buyers toward long-term offtake structures that lock in component availability.
Pricing Analysis
Long-term engineering-procurement-construction contracts dominate carbon capture retrofit procurement, with utilities favoring bundled pricing for heat integration redesign and solvent absorption train installation over discrete component sourcing. Price differentiation rests on project scale and FERC rate recovery certainty, with Powder River Basin baseload facilities above 500 MW commanding premium engineering resources while smaller industrial installations face cost compression from modular solid sorbent competition. Margins are tightening due to specialized carbon capture engineer scarcity and amine solvent feedstock volatility. Merchant industrial offtakers in the Gulf Coast petrochemical corridor exhibit highest price sensitivity, whereas regulated utilities with assured cost-of-service treatment show lowest.
Supply Chain Analysis
Inbound logistics costs for large-scale gasification reactor components concentrate fabrication decisions along Ohio River barge corridors connecting Pittsburgh, Cincinnati, and Louisville manufacturing clusters. Domestic supply draws from United States-based specialty steel foundries and precision turbine component machine shops, with critical amine solvents and metal-organic framework precursors sourced from German and Japanese chemical suppliers. Single-source vulnerability runs through concentrated fabrication capacity for supercritical boiler integration hardware. Distribution runs through utility procurement departments unbundling traditional supplier relationships in favor of integrated EPC consortia with process technology specialization.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Carbon capture technology deployment is reaching a platform-economics inflection as pipeline network interoperability and CO2 offtake aggregation create ecosystem lock-in effects for early infrastructure movers.
For Market Incumbents: Shield market position by deepening captive fabrication capacity for gasification reactor components in the Ohio River Valley corridor, countering emerging modular solid sorbent suppliers. Secure FERC rate recovery precedents for captured carbon infrastructure across multiple state public utility commission jurisdictions to establish regulatory moats against technology substitution.
For New Entrants and Emerging Players: Differentiate on modular pre-combustion system architectures for cement and steel manufacturing facilities in the Texas Gulf Coast industrial belt, where utility interconnection queue delays create white-space demand. Target industrial process on-site capture as the most penetrable segment, leveraging merchant structures that bypass regulated utility procurement cycles.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated EPC consortia with process specialization and established Department of Energy carbon management program relationships. Long-term viability hinges on pipeline network access and CO2 offtake contract duration rather than equipment manufacturing scale. Monitor EPA state implementation plan approval velocity as the critical inflection signal for retrofit deployment acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Carbon Capture Retrofit EPC Consolidation | Integrated consortia with FERC rate recovery expertise displace incumbent power equipment vendors in utility solicitations. |
| Pipeline Network Infrastructure Buildout | CO2 transport capacity connecting Powder River Basin capture sites to Permian Basin enhanced oil recovery operations unlocks revenue stacking. |
| Solid Sorbent Technology Licensing | Metal-organic framework and zeolite-based capture systems decompose scale thresholds for industrial boiler applications below 50 MW. |
| Workforce Development Program Expansion | Training partnerships with regional technical colleges address carbon capture engineer scarcity compressing deployment timelines. |
| Industrial Process Capture Joint Venture | Pre-combustion system deployments at Gulf Coast cement and steel facilities bypass utility interconnection queues and FERC jurisdiction. |
Research Approach
A spread of perspectives from utility planning officers, EPC contractors, carbon capture technology licensors, and state environmental agency officials converged on the working assumptions for deployment timeline and cost recovery modeling. Primary fieldwork combined structured interviews with secondary validation through EPA regulatory filings, FERC interconnection and rate case dockets, Department of Energy carbon management program disclosures, and EIA generation capacity databases. Bottom-up project pipeline aggregation and top-down regulatory compliance obligation modeling were triangulated to establish market size and growth trajectory.
Segmentation dimensions modeled include technology type, application sector, end-user category, and solution delivery mode across the projection horizon. CAGRs were derived from deployment obligation schedules under EPA greenhouse gas performance standards and IRA Section 45Q credit monetization pathways. Forecast inputs incorporated state implementation plan timeline variations, regional transmission organization capacity market reform scenarios, and amine solvent cost volatility assumptions.
The analysis sits within stated boundaries; outcomes outside sustained federal carbon capture incentive structures and FERC rate recovery precedents would require recalibration. Forecasts reflect documented assumptions regarding EPA compliance deadline adherence and specialized workforce availability. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Emerging Energy Technologies
Global Microreactor Technology Market
Emerging Energy Technologies
Decarbonization Market
Emerging Energy Technologies
Energy Transition Market
Emerging Energy Technologies
Cryogenic Technology Market
Emerging Energy Technologies
Global Power-To-X Market
Emerging Energy Technologies
Europe Clean Coal Technologies Market
Emerging Energy Technologies
Multi Energy Systems Market
Emerging Energy Technologies
Clean Coal Technologies Sales Market
Emerging Energy Technologies
Advanced Energy Market
Emerging Energy Technologies
Clean Technology Market
Emerging Energy Technologies
Methanation Technology Market
Emerging Energy Technologies
Nanotechnology in Energy Market