
 Manual Control Valve Market | 2026-2036
Manual Control Valve Market Size, Share, and Industry Trends Forecast 2026-2036
Manual Control Valve Market Insights
Utility providers is collapsing as the dominant buyer archetype while petrochemical companies gain procurement share for turnaround and expansion projects. Emerson sustains technology leadership in severe-service valve designs for high-pressure refining environments. Parker Hannifin leverages its distributed manufacturing footprint to compete on lead times across North American energy infrastructure. SMC Corporation specializes in compact precision valves for automated process skids in chemical processing.
A manual control valve is a fluid power device operated by physical actuation rather than automated control signals, typically constructed with cast iron, stainless steel, or brass bodies featuring threaded, flanged, or welded end connections rated for pressures from 150 to 2500 psi class. Its primary purpose is to start, stop, or throttle flow in pipelines where operator oversight, cost constraints, or safety isolation requirements preclude automated actuation. Ball valves dominate maintenance budgets in oil and gas processing due to their quarter-turn sealing reliability in high-cycle isolation service. Stainless steel material grades command premium positioning in food and beverage applications where sanitary surface finishes and corrosion resistance determine procurement specifications.
EPA regulations under the Safe Drinking Water Act and NSF/ANSI 61 standards in the United States, plus REACH material restrictions in Europe, compel manufacturers to certify lead-free bronze compositions and document alloy traceability for potable water applications. OSHA process safety management requirements and ISO 9001 quality frameworks further shape valve qualification protocols for chemical processing and refining end users. Stakeholders must monitor evolving F-Gas Regulation amendments in Europe and state-level lead service line replacement mandates in the United States to anticipate material specification shifts and certification renewal cycles.
Market Dynamics
Material specification mandates from EPA and NSF/ANSI 61 are forcing systematic replacement of legacy cast iron valve inventories across United States municipal water systems, compressing procurement cycles and elevating stainless steel alloy demand.
Growth Catalysts
- Lead-free alloy mandates:EPA Safe Drinking Water Act amendments and NSF/ANSI 61 certification requirements in the United States are compelling utilities to upgrade from cast iron to compliant bronze and stainless steel compositions.
- Energy sector maintenance cycles:Refinery turnaround schedules and pipeline integrity management programs are generating replacement volumes for quarter-turn isolation valves in high-pressure hydrocarbon service.
- Water treatment infrastructure:Municipal system upgrades across Germany, China, and India are expanding procurement of corrosion-resistant ball valves for filtration and distribution networks.
Market Restraints
- Raw material volatility:Nickel and chromium price swings directly compress margins on stainless steel valve production, forcing inventory risk onto distributors.
- Foundry capacity concentration:Specialized casting capabilities for high-pressure valve bodies cluster in select industrial regions, creating lead time vulnerability during demand surges.
- Manual actuation limitations:Operator presence requirements restrict deployment in remote or hazardous environments where automated isolation is preferred.
Strategic Opportunities
- Sanitary process expansion:Food and beverage processors in Brazil and India are adopting surface-finished stainless steel valves to meet tightening hygiene protocols.
- REACH compliance exports:European F-Gas Regulation amendments and material traceability requirements are creating certified-supplier advantages for documented alloy sourcing.
- Digital channel development:Direct specification platforms and 3D configuration tools are compressing distributor layers for standard catalog products.
Industry Challenges
- Welding certification scarcity:Qualified orbital welders for high-purity valve installation remain concentrated in established industrial clusters, constraining project execution timelines.
- Legacy system integration:Retrofitting manual isolation points into automated process skids requires custom adapter fabrication and extended commissioning periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Manual Control Valve Market |
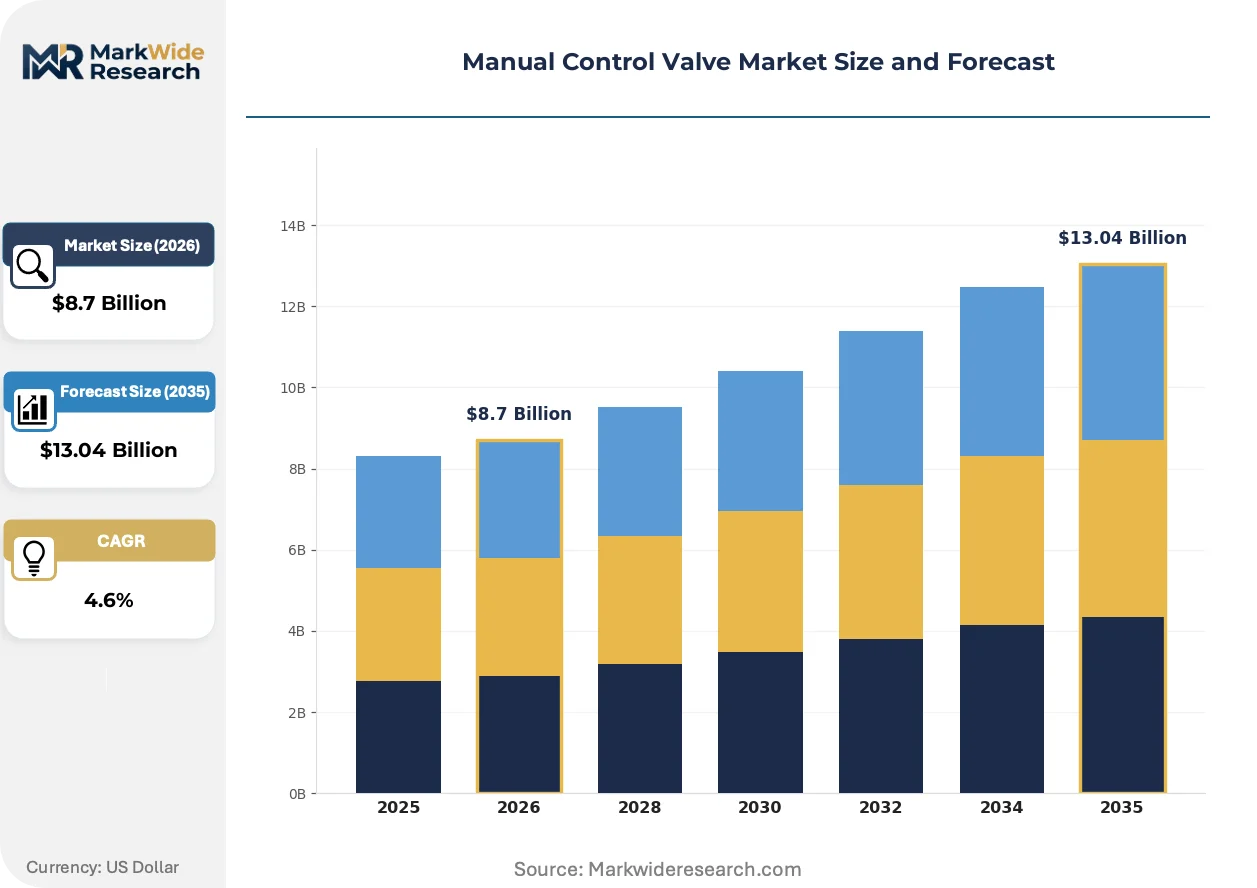
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gate Valve, Globe Valve, Ball Valve, Butterfly Valve, Needle Valve, Diaphragm Valve Material: Cast Iron, Stainless Steel, Brass, Bronze, Carbon Steel, Alloy Steel Application: Oil & Gas Processing, Water Treatment, Power Generation, Chemical Processing, Food & Beverage, Pulp & Paper End User Industry: Petrochemical Companies, Utility Providers, Refining Plants, Manufacturing Units, Packaging Companies, Energy Producers |
| Companies Covered | Pisco, Festo, Eaton, Parker Hannifin, Camozzi Automation, Bosch Rexroth, SMC Corporation, Emerson, Flowserve, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Manual Control Valve Market Trends and Innovations
Surface engineering and material science advances are redefining performance benchmarks across manual valve categories, while regulatory chemistry restrictions and buyer consolidation are restructuring competitive priorities.
Super duplex and hyper duplex stainless grades are supplanting standard 316L in offshore and sour gas applications where chloride-induced stress corrosion cracking threatens standard alloys. North Sea operators and Middle East sour field developers are specifying these materials for critical isolation points despite 40-60% cost premiums. The shift is compressing market share for commodity stainless suppliers while elevating metallurgical qualification requirements.
REACH restrictions on lead content and ECHA scrutiny of alloy compositions are eliminating traditional leaded bronze valve bodies from European potable water systems. Manufacturers must now certify lead-free copper alloys and document full material traceability through smelter origins. German and French municipal buyers are prioritizing suppliers with established EU-notified body certifications, marginalizing non-compliant import sources.
Consolidated utility procurement is compressing vendor lists and unbundling aftermarket service from initial equipment supply. Large water authorities in the United States and United Kingdom are mandating multi-year total cost of ownership evaluations that weight spare parts availability and technical support responsiveness above unit price. This favors integrated manufacturers with regional stocking locations over catalog distributors.
Manual Control Valve Market Segmentation
Manual control valve procurement patterns diverge sharply across technical specifications, with material chemistry and pressure ratings determining qualification for regulated applications. Segment boundaries are hardening as EPA, REACH, and NSF/ANSI 61 mandates disqualify legacy compositions from municipal and potable water systems.
Product Type:
Quarter-turn isolation designs face intensifying substitution pressure from automated actuation in remote hydrocarbon facilities, while linear-motion valves retain defensible positions in throttling and fine-flow applications.
- Gate Valve:Linear-motion design with rising or non-rising stem configurations provides full-bore flow path for slurry and wastewater handling. Demand concentrates in United States municipal water treatment facilities where NSF/ANSI 61 compliance requirements are forcing systematic replacement of legacy cast iron bodies with bronze and stainless steel alternatives.
- Globe Valve:S-pattern or angle-pattern body geometry enables precise throttling control across moderate pressure differentials. German chemical processors specify globe configurations for steam and condensate regulation in batch reactor systems, though compact ball valve alternatives are encroaching on traditional maintenance budgets.
- Ball Valve:Quarter-turn spherical closure element delivers bubble-tight sealing in high-cycle isolation service. United States refineries and pipeline operators dominate procurement for floating and trunnion-mounted designs in hydrocarbon transfer.
- Butterfly Valve:Wafer or lug-style thin-profile disc rotates within flow stream for cost-effective large-bore isolation. Water treatment infrastructure in China and India specifies rubber-lined and metal-seated variants for filtration and distribution networks.
- Needle Valve:Conical-tipped stem provides micrometer-precision flow control for instrumentation and sampling lines. Laboratory and analytical equipment manufacturers in Japan and Switzerland specify high-pressure needle designs for chromatography systems.
- Diaphragm Valve:Flexible elastomer or PTFE membrane isolates working fluid from bonnet mechanics for sterile and corrosive applications. Pharmaceutical and biotechnology processors in Ireland and Singapore specify weir-type and straight-through diaphragm configurations for aseptic transfer operations.
Ball valve configurations anchor the volume base across hydrocarbon and water infrastructure while diaphragm designs gain share at the steepest rate in pharmaceutical and food safety applications.
Material:
Alloy selection now functions as a regulatory compliance gateway, with traceability documentation and smelter certification determining vendor qualification for European and North American utility procurement.
- Cast Iron:Gray and ductile iron compositions retain cost advantage in low-pressure HVAC and drainage applications. Brazilian and Indian industrial distributors still specify cast iron for non-potable services, though EPA lead-free mandates have collapsed United States demand for potable water installations.
- Stainless Steel:Austenitic 304/316L grades and super duplex variants deliver corrosion resistance for chloride-bearing and high-purity fluids. United States municipal utilities facing Safe Drinking Water Act enforcement are accelerating procurement of 316L ball valves for distribution system upgrades.
- Brass:Lead-free copper-zinc alloys satisfy NSF/ANSI 61 potable water requirements with machinability advantages for small-bore plumbing valves. German and French municipal buyers prioritize brass-bodied quarter-turn valves for building service connections.
- Bronze:Copper-tin and lead-free silicon bronze compositions resist dezincification in seawater and brackish environments. Desalination plants in Saudi Arabia and the UAE specify aluminum bronze gate and globe valves for intake and brine discharge systems.
- Carbon Steel:ASTM A216 WCC and A105 forged grades handle high-pressure steam and hydrocarbon service at moderate cost. Russian and Kazakh pipeline operators specify carbon steel ball valves for crude oil transmission at class 600-900 ratings.
- Alloy Steel:Chrome-molybdenum compositions withstand elevated temperatures in power generation and refining. Indian supercritical thermal power projects specify WC9 and C12A alloy steel valves for main steam isolation at 600°C operating conditions.
Stainless steel grades dominate specification value while lead-free brass and bronze alloys expand most quickly in European and North American municipal compliance cycles.
Application:
End-use concentration varies by regional industrial structure, with energy infrastructure maintenance cycles and water treatment capital programs generating distinct procurement timing patterns.
- Oil & Gas Processing:Upstream production, midstream pipelines, and downstream refining require severe-service isolation for sour gas and high-pressure hydrocarbons. United States Permian Basin operators and Middle East national oil companies specify super duplex ball valves for wellhead and manifold isolation.
- Water Treatment:Municipal filtration, disinfection, and distribution networks demand corrosion-resistant alloys with potable water certification. Chinese and Indian urban water authorities are expanding procurement of stainless steel butterfly and ball valves for smart meter integration and pressure zone management.
- Power Generation:Thermal, nuclear, and renewable facilities require steam isolation, feedwater regulation, and cooling water control. French EDF nuclear maintenance programs and German coal phase-out schedules are reshaping valve replacement timelines across divergent technology paths.
- Chemical Processing:Batch and continuous reactors handle aggressive acids, caustics, and solvents requiring material compatibility verification. BASF and Dow chemical complexes in Germany and the United States specify PTFE-lined and alloy valves for phosgene and chlorine handling.
- Food & Beverage:Dairy, brewing, and processed food applications mandate sanitary surface finishes and clean-in-place compatibility. Brazilian meat processors and Indian dairy cooperatives are adopting 316L stainless steel diaphragm and butterfly valves with 3A and EHEDG certifications.
- Pulp & Paper:Kraft pulping, bleaching, and stock preparation expose valves to black liquor and chlorine dioxide. Finnish and Swedish mill operators specify titanium and duplex stainless valves for digester and recovery boiler isolation.
Water treatment infrastructure anchors the installed base volume while food and beverage hygiene upgrades climb the fastest in specification intensity.
End User Industry:
Buyer consolidation and procurement centralization are restructuring vendor relationships, with integrated service contracts displacing transactional equipment purchases across utility and energy sectors.
- Petrochemical Companies:Olefins, aromatics, and polymer producers operate continuous processes requiring reliable isolation for catalyst changeouts and emergency shutdowns. SABIC in Saudi Arabia and Sinopec in China specify severe-service ball and gate valves for ethylene cracker maintenance turnarounds.
- Utility Providers:Electric, gas, and water distribution utilities manage extensive buried and above-ground infrastructure with regulatory compliance obligations. United Kingdom water companies and California water districts are consolidating vendor lists around multi-year total cost of ownership frameworks.
- Refining Plants:Fluid catalytic cracking, hydrocracking, and coking units demand high-temperature, high-pressure isolation with fire-safe certification. Reliance Industries in India and PBF Energy in the United States schedule valve replacements during 3-5 year turnaround cycles.
- Manufacturing Units:General industrial facilities require utility isolation, compressed air control, and process cooling water regulation. Mexican and Vietnamese automotive component suppliers specify brass ball valves for pneumatic and hydraulic distribution.
- Packaging Companies:Aseptic filling, capping, and sterilization lines demand hygienic valve configurations with rapid changeover capability. Tetra Pak supply chain partners in Italy and Germany specify compact diaphragm valves for ultra-clean packaging lines.
- Energy Producers:Renewable and conventional power generators balance cycling duty with baseload reliability requirements. Ørsted offshore wind farms and NextEra solar thermal plants specify marine-grade stainless valves for cooling and fire suppression systems.
Utility providers retain the largest installed base position while petrochemical companies are expanding procurement share fastest through turnaround and greenfield investment cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized foundry capacity for high-pressure valve bodies clusters in Germany, China, and the United States, creating lead time vulnerability when energy sector maintenance cycles synchronize. Municipal water infrastructure spending and refining turnaround schedules generate divergent procurement timing across major demand centers.
United States
EPA Safe Drinking Water Act enforcement and NSF/ANSI 61 certification mandates are compelling municipal utilities to replace legacy cast iron inventories with lead-free bronze and stainless steel alternatives. The Permian Basin and Gulf Coast refining corridors generate severe-service demand for super duplex ball valves during scheduled turnarounds. California water districts and Texas municipal authorities anchor procurement volume for compliant alloy specifications.
Germany
REACH material restrictions and ECHA scrutiny of alloy compositions are eliminating traditional leaded bronze from European potable water systems. Chemical processors in the Rhine-Ruhr region specify globe valve configurations for steam regulation in batch reactor systems. Bavarian automotive suppliers and North Rhine-Westphalian water utilities drive demand for precision-manufactured quarter-turn isolation valves.
China
Urban water authority expansion and smart meter integration programs are accelerating stainless steel butterfly and ball valve procurement for distribution networks. National standards under SAMR and MEE oversight shape material traceability requirements for municipal infrastructure. Yangtze River Delta manufacturing clusters and Pearl River Delta water treatment facilities concentrate specification activity for corrosion-resistant alloys.
India
Supercritical thermal power projects specify WC9 and C12A alloy steel valves for main steam isolation at elevated temperatures. Dairy cooperatives and meat processors adopt 316L stainless steel diaphragm valves with 3A and EHEDG certifications. Maharashtra industrial corridors and Gujarat chemical complexes anchor demand for high-pressure isolation equipment.
Brazil
Food and beverage hygiene protocols are driving adoption of surface-finished stainless steel valves in meat processing and brewing applications. Petrobras turnaround schedules and pre-salt field development generate replacement cycles for hydrocarbon service valves. São Paulo state water utilities and Rio Grande do Sul agricultural processing clusters concentrate procurement for sanitary and industrial specifications.
Manual Control Valve Market Competitive Landscape
Concentration sits with diversified industrial conglomerates and specialized fluid power manufacturers serving distinct specification tiers. The vendor base spans integrated multinationals with severe-service metallurgical capabilities, distributed manufacturers competing on lead time compression, and compact precision specialists for automated process skids. Strategic moves center on multi-year total cost of ownership contracting with utility consolidators and backward integration into captive foundry capacity for alloy traceability documentation.
Among diversified industrial technology groups, Emerson and Parker Hannifin occupy positions spanning severe-service refining applications and distributed energy infrastructure supply. SMC Corporation exemplifies the compact precision archetype targeting automated chemical processing skids. Festo and Bosch Rexroth represent European-origin fluid power specialists with integrated automation portfolios. Pisco, Camozzi Automation, Eaton, and Flowserve sit within tiered competitive positions across geographic and application-specific market segments.
| Leading Market Players |
|---|
| Pisco |
| Festo |
| Eaton |
| Parker Hannifin |
| Camozzi Automation |
| Bosch Rexroth |
| SMC Corporation |
| Emerson |
| Flowserve |
| Others |
Pricing and Supply Chain Analysis
NSF/ANSI 61 certification gates both supplier qualification and price stratification across municipal procurement, forcing documented alloy traceability as a non-negotiable cost component while compressing margins on non-compliant inventory.
Pricing Analysis
EPA Safe Drinking Water Act amendments dictate the pricing tier structure across manual valve categories, separating premium-certified stainless steel and lead-free bronze from economy-grade cast iron alternatives. Price differentiation hinges on certification documentation burden and material grade, with super duplex alloys commanding substantial premiums over standard 316L for sour gas service. Pricing pressure stems from nickel and chromium volatility feeding directly into stainless steel production costs, squeezing distributor margins. Municipal utilities exhibit highest price sensitivity due to consolidated procurement frameworks, while offshore oil operators prioritize performance over unit cost.
Supply Chain Analysis
Inventory cycles and lead time vulnerability concentrate around synchronized energy sector maintenance windows, creating demand surges that strain specialized foundry capacity. Supply concentrates in Germany, China, and the United States for high-pressure valve body casting, with raw material draws from nickel mines in Indonesia and chromium sources in South Africa. Single-source vulnerability sits with orbital welding certification scarcity for high-purity installation. Distribution runs through integrated manufacturers with regional stocking locations serving consolidated utility buyers, displacing traditional catalog distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is approaching a platform-economics inflection as digital specification tools and direct-to-engineer channels unbundle distributor layers, with interoperability between valve configuration software and plant asset management systems reshaping procurement workflows.
For Market Incumbents: Compound metallurgical qualification advantages by deepening captive foundry capacity for alloy traceability documentation, defending against emerging compact precision specialists encroaching on automated process skid applications. Prioritize multi-year total cost of ownership contracting with consolidating water authorities to lock out catalog competitors. Invest in severe-service R&D for super duplex and hyper duplex grades as sour gas applications displace commodity stainless.
For New Entrants and Emerging Players: Aftermarket service responsiveness gaps in consolidated utility procurement create entry points for regional specialists with rapid spare parts availability. Target Brazilian food and beverage hygiene upgrades and Indian dairy cooperative certifications as penetrable segments with less entrenched incumbent relationships. Pursue direct specification platform partnerships to bypass traditional distributor layers on standard catalog products.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across certified alloy foundry capacity as traceability documentation requirements deepen, favoring integrated manufacturers over assembly-only competitors. Long-term viability centers on backward integration into smelter relationships and EU-notified body certification assets. Watch for state-level lead service line replacement mandate acceleration as the signal for compliance-driven replacement cycle inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Foundry Capacity | Secures alloy traceability documentation for EPA and REACH compliance, marginalizing non-integrated competitors. |
| Multi-Year Total Cost of Ownership Contracting | Aligns vendor relationships with consolidated utility procurement frameworks in California and Texas water districts. |
| Super Duplex Metallurgical Qualification Investment | Captures premium positioning in North Sea and Middle East sour gas isolation applications. |
| Digital Specification Platform Development | Compresses distributor layers by enabling direct engineer-to-manufacturer configuration for standard products. |
| Regional Stocking Location Expansion | Meets consolidated utility spare parts availability requirements weighted in procurement evaluations. |
Research Methodology
Operator-level perspectives from maintenance directors, plant engineers, OEM procurement teams, and aftermarket service heads anchored the qualitative base, combined with secondary validation from customs trade data, SEC filings, industry association reports, and regulatory certification databases. Bottom-up demand modeling triangulated against top-down macroeconomic indicators established volume and value parameters.
Sensitivity analysis tested forecast robustness across material price volatility scenarios and regulatory acceleration cases throughout the projection horizon. Segmentation dimensions spanned product type, material grade, application, and end-user industry concentration. CAGRs derived from replacement cycle analysis, infrastructure spending patterns, and compliance-driven upgrade timelines. Industry-specific inputs included refinery turnaround schedules, municipal water authority capital programs, and food safety certification adoption curves.
Underlying assumptions cover regulatory enforcement continuity, foundry capacity stability, and alloy price correlation patterns, with deviation risk concentrated in tariff exposure on nickel and chromium imports. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Valves
Air Vent Heads Market
Valves
Fluid Handling Systems Market
Valves
Reciprocating Compressor Components Market
Valves
Global Control Valves Market
Valves
Industrial Valves Market
Valves
Construction Valve Seat Insert Market
Valves
Expansion Valves Market
Valves
Sliding Sleeves Market
Valves
Hot Blast Valves Market
Valves
Explosion Vents Market
Valves
Three Way Ball Valve Market
Valves
Emergency Shut Down Valves (ESDV) Market
Valves
Gate Impellers Market
Valves
Global Flow Control Market
Valves
Gas Equipment Market
Valves
Explosion Isolation Valves Market