
 Hot Blast Valves Market | 2026-2036
Hot Blast Valves Market Size, Share, and Industry Trends Forecast 2026-2036
Hot Blast Valves Market Foresight
Modular valve-train configurations is broadening procurement options for blast furnace operators seeking component-level replacement rather than full-system overhaul. Paul Wurth leverages its long-standing dominance in blast furnace engineering to bundle hot blast valves with combustion system packages. ANDRITZ AG sustains competitive positioning through specialized metallurgical flow control technologies. Danieli Corus anchors its presence in European steel retrofit markets with application-specific valve designs.
Hot blast valves are high-temperature isolation and control devices engineered to withstand gas temperatures exceeding 1,200°C while maintaining tight sealing against pressurized combustion gases in ironmaking operations. These valves typically incorporate refractory-lined bodies, water-cooled seats, and specialized alloy construction to prevent thermal deformation during cyclic opening and closing sequences. Stainless steel valve bodies command premium positioning due to superior oxidation resistance in aggressive hot blast environments, while cast iron variants occupy cost-sensitive maintenance and repair segments. Steel production applications dominate absolute demand volumes, though chemical processing represents the fastest-growing application category as petrochemical crackers adopt modified hot blast technologies for process heating.
EPA emissions standards under the Clean Air Act shape valve sealing requirements and drive replacement demand at US integrated mills. China's MEE enforces GB energy-efficiency standards that mandate upgraded hot blast system performance, while REACH compliance in Europe restricts certain refractory material compositions used in valve linings. Stakeholders must weigh material certification investments against the operational lifespan advantages of next-generation alloy constructions as regulatory thresholds tighten across multiple jurisdictions.
Market Dynamics
Blast furnace operators face compressed replacement cycles as EPA emissions rules and China's GB energy-efficiency mandates force simultaneous upgrades to sealing performance and thermal durability. Modular valve-train configurations now allow component-level procurement rather than full-system overhauls.
Growth Catalysts
- EPA Clean Air Act enforcement:Tightened emissions thresholds at US integrated steel mills are accelerating valve replacement schedules to maintain compliance.
- India's steel corridor expansion:New blast furnace capacity in Odisha and Jharkhand is generating concentrated demand for modern hot blast systems.
- Refractory alloy advancement:Next-generation materials are extending operational lifespan under cyclic thermal stress above 1,200°C.
Market Restraints
- Specialized alloy input costs:Nickel and cobalt price volatility directly impacts stainless steel valve body production economics.
- European supplier concentration:REACH-compliant refractory lining sources cluster among limited certified foundries in Germany and Austria.
- Technical sealing limitations:Existing water-cooled seat designs face durability ceilings under extended high-pressure cycling regimes.
Strategic Opportunities
- Petrochemical cracker adoption:Modified hot blast technologies for process heating represent an emerging application vertical outside traditional steelmaking.
- Component-level procurement channels:Direct valve-train sourcing is bypassing bundled combustion system vendors for maintenance spend.
- China's dual carbon goals:MEE-mandated efficiency upgrades are creating replacement demand at older integrated mills.
Industry Challenges
- Refractory engineering talent scarcity:Specialized expertise in high-temperature material behavior remains concentrated among retiring cohorts in Pittsburgh and Duisburg.
- Legacy system integration complexity:Retrofitting modular valves into 1980s-era blast furnace infrastructure requires custom adapter fabrication.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hot Blast Valves Market |
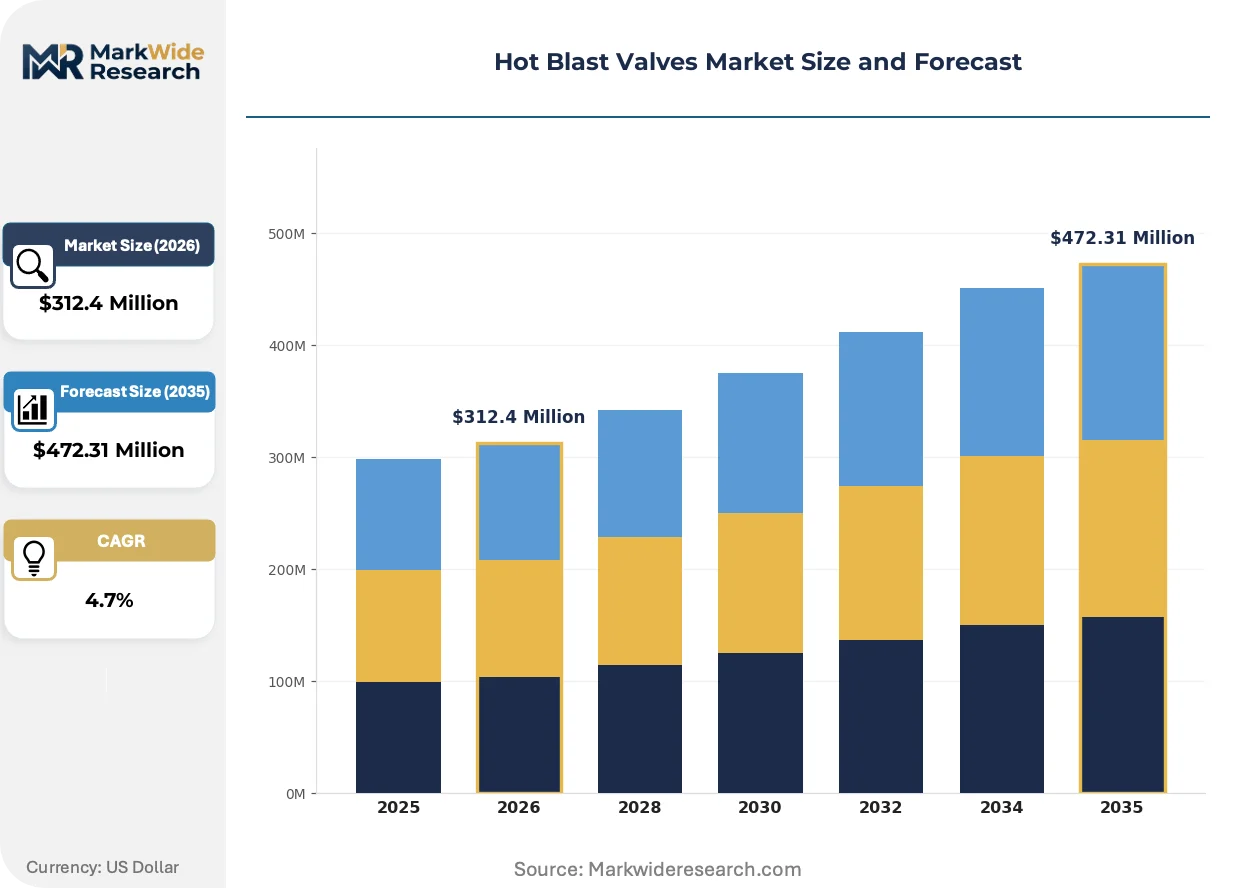
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $472.31 Million |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Manual, Automatic, Pneumatic, Electric Material: Stainless Steel, Cast Iron, Alloy Steel, Brass Application: Steel Production, Heating Systems, Chemical Processing, Power Generation Size: Small, Medium, Large, Custom |
| Companies Covered | Paul Wurth, ANDRITZ AG, Danieli Corus, Primetals Technologies, L&T Valves, Metso Outotec, VCL, Kurimoto, Z&J, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hot Blast Valves Market Shifts & Advancements
Digital instrumentation and predictive maintenance protocols are restructuring how operators manage valve lifecycle costs. Material science advances and procurement model evolution are simultaneously reshaping competitive positioning.
Sensor-integrated valve monitoring is automating condition-based maintenance scheduling at integrated steel mills. ArcelorMittal and Nippon Steel are deploying acoustic emission and thermal imaging arrays on critical hot blast lines. This technology is automating the shift from calendar-based replacement to failure-predictive intervention, compressing unplanned outage frequency.
China's GB standards revision is mandating upgraded hot blast system thermal efficiency benchmarks. The Ministry of Ecology and Environment (MEE) is enforcing compliance timelines that coincide with scheduled reline windows. Stainless steel valve bodies with enhanced oxidation resistance are capturing preference share among mills facing accelerated inspection cycles.
After-sales service unbundling is fragmenting traditional vendor-customer relationships. Blast furnace operators in India's expanding steel corridor are separating valve supply contracts from installation and commissioning scope. This pattern is most visible in Odisha, where Tata Steel and JSW are building captive technical teams for in-house maintenance execution.
Hot Blast Valves Market Segmentation
Hot blast valve procurement decisions hinge on thermal durability specifications, integration complexity with existing blast furnace infrastructure, and regulatory compliance timelines. Segmentation reveals divergent buyer priorities across operational scale, material certification requirements, and application environments.
Type:
Actuation mechanism selection determines capital expenditure profiles and maintenance staffing requirements for blast furnace operators.
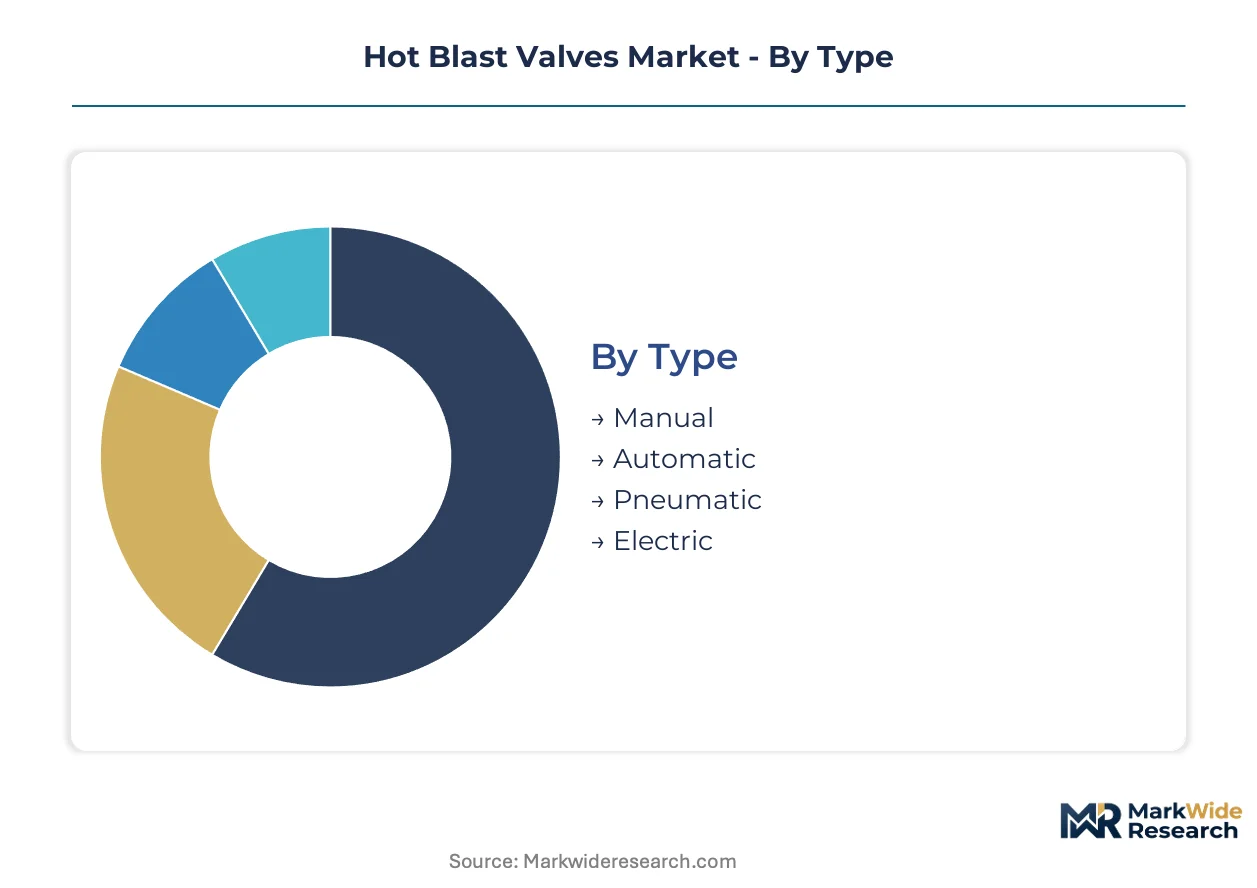
- Manual:Hand-wheel operated designs with mechanical locking mechanisms serve isolated maintenance access points and emergency isolation duties. Demand concentrates at older integrated mills in India's Jharkhand corridor where capital constraints limit automation investment, though EPA inspection frequency is forcing gradual replacement.
- Automatic:Programmable logic-controlled actuation enables synchronized sequencing with combustion system cycles. Steel producers in Odisha's new capacity installations specify automatic valves to meet MEE thermal efficiency mandates while minimizing operator exposure to high-temperature zones.
- Pneumatic:Compressed air-driven actuation delivers rapid response times for high-cycling isolation duties in pressurized hot blast lines.
- Electric:Motor-driven precision positioning supports remote operation from central control rooms, reducing on-floor personnel requirements.
Volume sits with Manual types in maintenance replacement channels; growth tilts toward Automatic configurations in greenfield steel capacity.
Material:
Alloy composition directly governs oxidation resistance, thermal fatigue life, and REACH compliance certification costs.
- Stainless Steel:Austenitic and duplex grades with chromium-nickel matrices withstand cyclic thermal stress above 1,200°C without scaling. US integrated mills facing EPA emissions enforcement specify stainless bodies to extend inspection intervals and reduce unplanned reline downtime.
- Cast Iron:Gray and ductile iron variants with lower alloy content occupy cost-sensitive repair segments. Secondary steel producers in India's informal sector favor cast iron for non-critical isolation points where replacement cycles align with annual maintenance shutdowns.
- Alloy Steel:Martensitic and precipitation-hardened grades balance high-temperature strength with machinability for custom seat geometries.
- Brass:Copper-zinc compositions serve low-temperature auxiliary lines and instrument isolation duties in heating system applications.
Procurement volume clusters with Cast Iron in aftermarket channels; specification momentum favors Stainless Steel under tightening emissions inspection regimes.
Application:
End-use environment dictates refractory lining specifications, pressure rating requirements, and sealing surface engineering.
- Steel Production:Blast furnace hot blast isolation duties demand water-cooled seats and refractory-lined bodies to manage thermal shock during cyclic operation. New capacity in Odisha and Jharkhand drives concentrated demand for systems rated above 1,200°C with integrated acoustic emission monitoring.
- Chemical Processing:Modified hot blast technologies for petrochemical cracker process heating require corrosion-resistant sealing surfaces. This application category is expanding most quickly as crackers adopt high-temperature combustion preheat to improve feedstock conversion efficiency.
- Heating Systems:District heating and industrial boiler applications utilize simplified valve architectures with lower pressure ratings.
- Power Generation:Combined cycle and waste-to-energy plants specify hot blast valves for combustion air preheating subsystems.
Absolute demand volume remains with Steel Production; steepest expansion trajectory is emerging in Chemical Processing applications.
Size:
Dimensional classification determines manufacturing batch economics, shipping logistics, and field installation requirements.
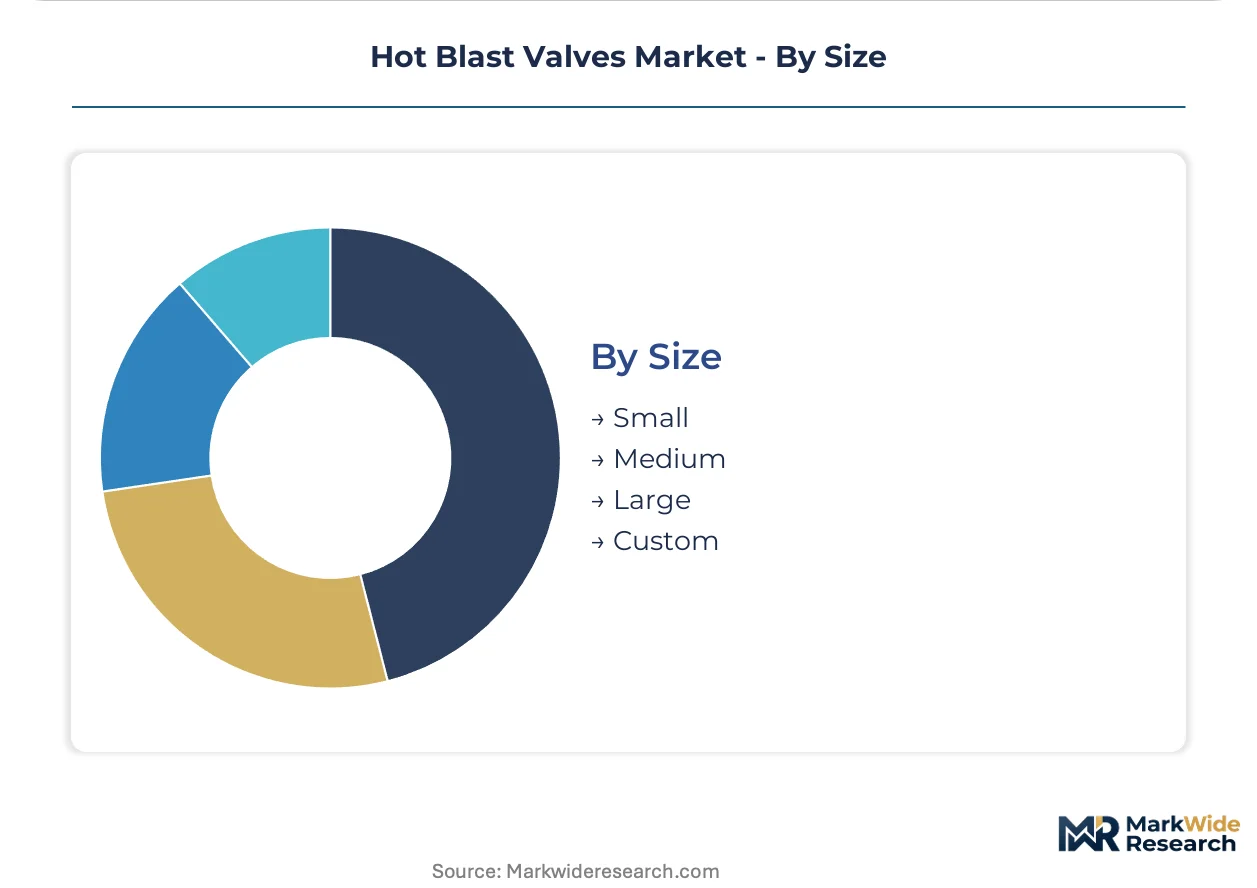
- Large:Nominal diameters exceeding 1,200 millimeters serve main hot blast trunk lines at integrated mills. Blast furnace operators in India's expanding steel corridor specify large valves with modular seat designs to enable in-situ refurbishment without full valve extraction.
- Custom:Engineered-to-order dimensions accommodate legacy infrastructure with non-standard flange spacing or unique centerline elevations. European retrofit markets generate sustained custom demand as mills adapt modular valve trains to 1980s-era furnace configurations.
- Small:Compact designs for instrument lines and sampling points utilize standardized casting patterns.
- Medium:Intermediate diameters serve branch line isolation and auxiliary combustion air distribution.
Revenue concentration favors Large sizes in greenfield procurement; Custom specifications capture premium pricing in European retrofit channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's Special Economic Zones in steel-producing states concentrate new blast furnace investment, drawing valve procurement toward Odisha and Jharkhand industrial corridors.
India
New blast furnace capacity in Odisha and Jharkhand drives concentrated demand for automatic hot blast valves with integrated monitoring systems. The Ministry of Steel's National Steel Policy incentivizes modern hot blast installations at integrated mills. Tata Steel's Kalinganagar complex and JSW's Dolvi expansion anchor procurement volumes for large-diameter valves rated above 1,200°C.
China
MEE-enforced GB energy-efficiency standards accelerate replacement cycles at older integrated mills in Hebei and Jiangsu provinces. The dual carbon goals mandate thermal efficiency upgrades coinciding with scheduled reline windows. Baowu Steel's Shanghai operations and Shougang's Qian'an facility specify stainless steel valve bodies to extend inspection intervals under tightened emissions protocols.
United States
EPA Clean Air Act enforcement compresses replacement schedules at integrated mills around Pittsburgh and Gary to maintain emissions compliance. Tightened sealing requirements drive specification of water-cooled seat designs with enhanced refractory linings. Cleveland-Cliffs' Burns Harbor and Indiana Harbor operations anchor Great Lakes demand for modular valve-train configurations.
Germany
REACH compliance restricts refractory material compositions used in valve linings, concentrating certified foundry supply in North Rhine-Westphalia and Bavaria. ThyssenKrupp's Duisburg complex and Salzgitter's Peine facility drive European retrofit demand for custom-engineered valves adapting modular trains to 1980s-era furnace configurations.
Japan
METI industrial efficiency guidelines shape hot blast system upgrade timelines at Nippon Steel's Nagoya and Kimitsu works. JIS standards certification requirements filter procurement toward established alloy suppliers. Acoustic emission monitoring deployment at JFE Steel's Keihin and Fukuyama complexes exemplifies predictive maintenance adoption in high-cycling isolation duties.
Hot Blast Valves Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across procurement channels. The vendor base clusters around three strategic archetypes: blast furnace engineering bundlers, metallurgical flow control technologists, and component-level valve fabricators. Consolidation pressure intensifies as operators unbundle after-sales service from equipment supply. Geographic expansion and technology licensing represent dominant competitive moves for accessing India's expanding steel corridor.
Among European blast furnace engineering houses, Paul Wurth and Danieli Corus exemplify the bundling archetype, integrating hot blast valves within combustion system packages. ANDRITZ AG occupies a position among specialized metallurgical flow control technologists. Primetals Technologies represents the scale-driven engineering conglomerate tier. These three anchors illustrate how competitive positioning diverges between bundled system vendors and component specialists.
| Leading Market Players |
|---|
| Paul Wurth |
| ANDRITZ AG |
| Danieli Corus |
| Primetals Technologies |
| L&T Valves |
| Metso Outotec |
| VCL |
| Kurimoto |
| Z&J |
| Others |
Supply & Pricing Matrix
Captive foundry integration among European blast furnace engineering houses anchors premium pricing power for stainless steel valve bodies while compressing margins for cast iron fabricators dependent on spot nickel purchases. This vertical control over refractory-lined alloy casting simultaneously insulates bundling vendors from raw material volatility and forces component specialists into transactional pricing for maintenance replacement channels.
Pricing Analysis
Short lead-time premiums dominate contract negotiations as blast furnace operators facing EPA-mandated inspection windows pay substantial markups for expedited stainless steel valve delivery. Three-tier pricing structure across premium, standard, and economy levels separates REACH-certified European foundries from Indian cast iron suppliers and gray-market refurbishment vendors. Pricing pressure stems from nickel and cobalt commodity volatility, which compresses margins for non-integrated fabricators serving cost-sensitive secondary steel producers. Price sensitivity concentrates most acutely among informal sector operators in India's Jharkhand corridor, while integrated mills in Odisha absorb premiums for automatic configurations with integrated monitoring.
Supply Chain Analysis
Refractory alloy supply rests on certified foundries concentrated in Germany, Austria, and select Japanese metallurgical centers with JIS standards accreditation. Nickel and cobalt feedstock draws from Indonesian laterite mines and Canadian sulfide deposits, while specialized chromium sources concentrate in South Africa and Kazakhstan. Single-source vulnerability runs through REACH-compliant refractory lining suppliers, where limited European certification creates procurement bottlenecks for US mills facing accelerated replacement cycles. Distribution runs through bundled combustion system vendors for greenfield projects, while aftermarket channels fragment toward direct component procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sensor-integrated valve monitoring is displacing calendar-based maintenance protocols across integrated steel mills, compressing replacement cycles and restructuring vendor-customer relationships around predictive service contracts rather than equipment transactions.
For Market Incumbents: Lock in long-term service contracts with acoustic emission monitoring subscriptions to defend against component-level procurement unbundling. Deepen captive control over refractory alloy foundry capacity in India to capture replacement demand from Odisha and Jharkhand capacity expansions while insulating margin position from nickel price volatility. For New Entrants and Emerging Players: Direct-to-operator digital platforms for spare valve-train components offer the most penetrable route into India's expanding steel corridor, where Tata Steel and JSW are building in-house maintenance capabilities. Target petrochemical cracker applications with corrosion-resistant sealing surface designs, leveraging modified hot blast technology adoption outside traditional steelmaking to bypass entrenched bundling relationships. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to diversified metallurgical engineering conglomerates seeking Indian market access. Five-to-ten year viability hinges on predictive maintenance technology integration rather than pure fabrication scale. Watch MEE enforcement intensity at older Chinese integrated mills as the signal for replacement cycle acceleration and associated valve demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Technology Integration | Acoustic emission monitoring at ArcelorMittal and Nippon Steel compresses unplanned outage frequency and locks in recurring service revenue. |
| Backward Integration into Refractory Alloy Foundry Capacity | Captive supply of REACH-certified stainless steel valve bodies insulates margin position from nickel price volatility and European supplier concentration. |
| Component-Level Procurement Channel Development | Direct valve-train sourcing bypasses bundled combustion system vendors and captures maintenance spend from unbundling operators in India's steel corridor. |
| Petrochemical Cracker Application Expansion | Modified hot blast technologies for process heating open demand outside traditional steelmaking with corrosion-resistant sealing requirements. |
| Indian Greenfield Capacity Partnership Structuring | Tie-ups with Tata Steel Kalinganagar and JSW Dolvi anchor procurement volumes for large-diameter automatic valves with integrated monitoring systems. |
Research Methodology
Multi-period observation of blast furnace reline schedules, EPA inspection frequency, and MEE enforcement intensity anchored the trend analysis, supplemented by interviews with maintenance directors at integrated steel mills, procurement leads from blast furnace engineering houses, refractory material suppliers, and aftermarket service heads. Secondary validation drew from EPA Clean Air Act filings, Chinese GB standards documentation, SEC 10-K disclosures from diversified metallurgical engineering conglomerates, and customs data tracking stainless steel valve imports into India. Bottom-up project pipeline enumeration across Odisha and Jharkhand Special Economic Zones was triangulated against top-down steel capacity expansion forecasts.
Input-output matrix modeling connected blast furnace hot blast system specifications to valve material requirements, actuation type preferences, and dimensional classifications across the projection horizon. Segmentation dimensions included valve type, alloy composition, application environment, and size classification alongside regional regulatory cluster differentiation. CAGRs were derived from installed base depreciation curves, replacement cycle compression factors, and greenfield capacity commissioning schedules. Industry-specific forecast inputs incorporated nickel price volatility scenarios and REACH compliance cost escalation assumptions.
The model holds under steady EPA and MEE enforcement intensity; deviation in emissions regulation relaxation or refractory material substitution breakthroughs would shift replacement cycle assumptions. Forecasts reflect documented base-case assumptions regarding regulatory trajectory and alloy performance durability. Nickel-cobalt price correlation breakdown, Chinese dual carbon goal revision, and acoustic emission monitoring technology cost reduction represent the small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Valves
Pressure Gauge Market
Valves
Bend Restrictors and Stiffeners Market
Valves
North America Industrial Valves Market
Valves
Europe Valves Market
Valves
Pipeline Pigging Equipment Market
Valves
Cryogenic Valve Market
Valves
North America Irrigation Valves Market
Valves
Christmas Tree Valves Market
Valves
Europe Medium Voltage Switchgear Market
Valves
Dense Phase Vessels Market
Valves
Sanitary Valves Market
Valves
Pressure Control Equipment Market
Valves
Flow Computer Market
Valves
Transmission Overload Protectors Market
Valves
Valve Driver Market
Valves
Steel Cylinder Market