
 Engineered Polymers in Electric Charging Infrastructure Market | 2026-2036
Engineered Polymers in Electric Charging Infrastructure Market Size, Share, and Industry Trends Forecast 2026-2036
Engineered Polymers in Electric Charging Infrastructure Market Intelligence
China's polymer compounding corridor is rewriting supply geography for EV charging-grade materials. BASF SE leverages its Ludwigshafen integrated sites to sustain flame-retardant polyamide output for European connector OEMs. SABIC anchors high-heat polycarbonate production for Middle Eastern charging station deployments. Covestro AG differentiates through polyurethane encapsulant formulations that compete on thermal cycling performance.
Engineered polymers in electric charging infrastructure comprise high-performance thermoplastics, conductive compounds, and composite matrices formulated for dielectric strength exceeding 20 kV/mm, thermal stability above 150°C, and UL 94 V-0 flammability ratings; these materials insulate high-voltage conductors, seal connector interfaces, and structurally reinforce charging hardware against mechanical load and environmental degradation. Thermoplastics dominate current volume for injection-molded casings and connector bodies where cost-efficient scalability meets IEC 61851 safety requirements. Conductive polymers represent the fastest-expanding technology segment as resistive heating elements and EMI shielding layers gain traction in next-generation power electronics. Composite materials occupy premium positioning for structural reinforcements in DC fast-charging pylons where glass-fiber loading ratios above 40 percent deliver torsional rigidity.
The US EPA and NHTSA coordinate tailpipe-emission phase-outs that indirectly mandate charging infrastructure density, while China's MIIT enforces GB/T standards for connector material compatibility that dictate polymer selection. The EU ECHA REACH framework restricts halogenated flame retardants in casings, forcing reformulation toward phosphorus-nitrogen systems. Stakeholders must monitor how evolving interoperability standards between regional charging protocols reshape material qualification timelines and supplier certification burdens.
Market Dynamics
Fast-charging power levels above 350 kW are forcing polymer suppliers to reformulate thermal management compounds, compressing qualification cycles from 18 months to under 12 months for connector OEMs.
Growth Catalysts
- EU F-Gas Regulation:Phase-down of fluorinated gases in cooling systems drives demand for polymer-based passive thermal management in charging modules, expanding addressable market for high-heat thermoplastics.
- China's coastal manufacturing clusters:NEV charging network build-outs in Jiangsu and Guangdong provinces require localized polymer compounding capacity, pulling regional supply chain investment.
- Conductive polymer formulations:Resistive heating elements and EMI shielding layers in next-generation power electronics are displacing metal components, opening new specification categories.
Market Restraints
- Flame-retardant precursor costs:Phosphorus-nitrogen systems replacing halogenated compounds carry 15-25% raw material premiums, squeezing margin at mid-tier compounders.
- Specialized resin concentration:High-heat polycarbonate and polyamide supply for charging-grade applications clusters among integrated petrochemical complexes in Germany and Saudi Arabia.
- Dielectric performance ceiling:Current thermoplastic formulations face thermal runaway risks above 180°C continuous operation, limiting deployment in 800V architectures without ceramic hybridization.
Strategic Opportunities
- India's PLI scheme for charging infrastructure:Domestic manufacturing incentives create first-mover advantage for polymer suppliers establishing local compounding operations ahead of 2026 localization mandates.
- Polyurethane encapsulant convergence:Integration of thermal cycling performance with vibration damping opens modular charging station designs previously requiring multi-material assemblies.
- Direct OEM contracting:Charging hardware manufacturers are bypassing distributors to specify custom flame-retardant grades, compressing channel margins but deepening technical relationships.
Industry Challenges
- UL 94 V-0 certification timelines:Reformulated phosphorus-nitrogen systems require 8-14 month approval cycles, misaligning with compressed product development schedules.
- Multi-protocol material qualification:Concurrent validation against GB/T, IEC 61851, and SAE standards strains technical resources at specialty compounders serving export markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Engineered Polymers in Electric Charging Infrastructure Market |
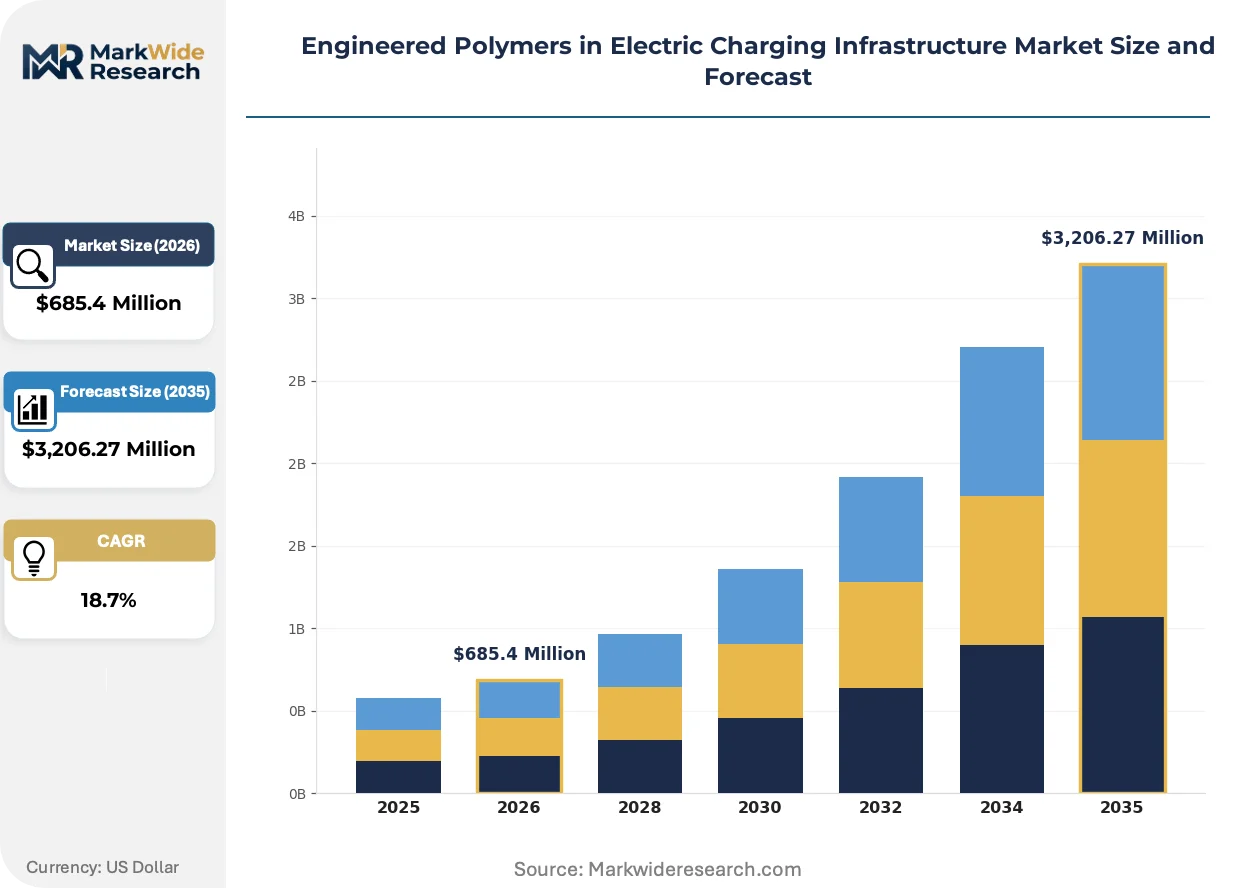
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $3,206.27 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Insulation, Connectors, Casings, Reinforcements Application: Charging Stations, EV Power Supply, Infrastructure Components, Safety Devices Technology: Conductive Polymers, Thermoplastics, Polyurethane, Composite Materials End User: Automotive Manufacturers, Utility Providers, Infrastructure Developers, Research Institutions |
| Companies Covered | BASF SE, SABIC, Covestro AG, DuPont de Nemours, Solvay S.A., Evonik Industries AG, LG Chem, Lanxess AG, Celanese Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Engineered Polymers in Electric Charging Infrastructure Market Strategic Shifts & Innovations
Material science advances and regulatory chemistry restrictions are converging to reshape specification priorities across charging infrastructure tiers, with thermal performance now displacing cost as the primary selection criterion in premium segments.
Glass-fiber reinforced polyamide connector housings are migrating from 30% loading ratios toward 45-50% formulations to achieve torsional rigidity in DC fast-charging pylons without metal inserts. Tier-1 connector OEMs in Germany and China are qualifying these grades for 500,000-cycle mechanical durability. The shift is compressing demand for lower-loaded compounds in structural applications while expanding specification premiums for high-performance tiers.
ECHA REACH restrictions on halogenated flame retardants are forcing compounders to validate phosphorus-nitrogen systems for UL 94 V-0 ratings at sub-1.6mm wall thicknesses. European casing manufacturers face 12-18 month reformulation cycles to maintain CE marking compliance. Charging station deployers in the EU are absorbing 8-12% material cost increases to secure supply of compliant grades ahead of 2025 enforcement deadlines.
Utility procurement teams are consolidating supplier relationships around compounders offering integrated material-plus-certification packages, displacing fragmented sourcing across resin, additive, and testing vendors. This concentration is visible most acutely in Germany's fast-charging hub deployments, where E.ON and EnBW have reduced approved polymer supplier lists from 12 to 4 vendors since 2023. The model is spreading to China's State Grid tenders, where technical qualification documentation now weighs heavier than unit pricing in bid scoring.
Engineered Polymers in Electric Charging Infrastructure Market Segmentation
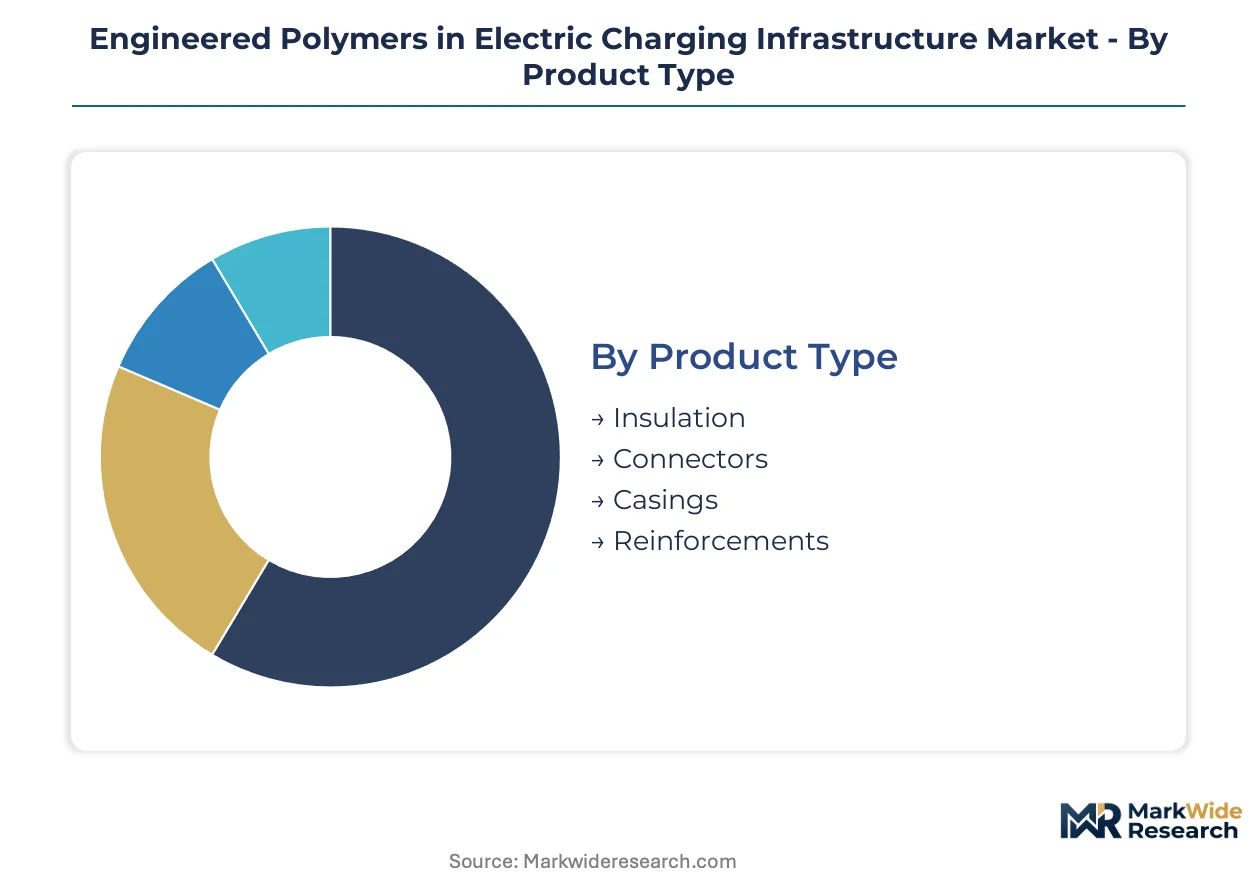
Segmentation in engineered polymers for charging infrastructure reveals how material specifications diverge across thermal, mechanical, and electrical performance tiers. Procurement cycles vary dramatically by segment, from 6-month connector replacements to 15-year infrastructure pylons.
Product Type:
Insulation compounds turn over fastest due to thermal degradation under continuous high-voltage load, while reinforcements cycle slowest given structural certification requirements.
- Insulation:Dielectric formulations exceeding 20 kV/mm shield high-voltage conductors from arc tracking and environmental moisture. Demand clusters in China's coastal manufacturing corridors where NEV charging network build-outs require localized supply of GB/T-compliant grades.
- Connectors:Glass-fiber loaded polyamide housings achieve IEC 61851 mechanical durability across 500,000 mating cycles. German utility procurement of thermoplastic connector bodies for fast-charging hubs is compressing qualification timelines from 18 months toward 12 months.
- Casings:Flame-retardant enclosures meeting UL 94 V-0 ratings at sub-1.6mm wall thicknesses face ECHA REACH reformulation cycles.
- Reinforcements:Structural composite matrices with 40%+ fiber loading deliver torsional rigidity in DC fast-charging pylons.
Connectors dominate installed base volume. Insulation is where expansion concentrates as 800V architectures proliferate.
Application:
Cost tiering separates premium DC fast-charging hardware from standardized AC equipment, with material specifications widening accordingly.
- Charging Stations:Integrated assemblies combining passive thermal management, EMI shielding, and structural housings command specification premiums. EU F-Gas Regulation phase-down of fluorinated cooling systems is pulling polymer-based thermal solutions into German fast-charging hub deployments.
- EV Power Supply:Onboard charging modules require compact, high-heat thermoplastics with continuous operation stability above 150°C. China's MIIT enforcement of GB/T connector material compatibility dictates polymer selection across Jiangsu and Guangdong manufacturing clusters.
- Infrastructure Components:Grid interconnection hardware utilizes flame-retardant casings under tightening REACH compliance.
- Safety Devices:Emergency disconnect systems rely on arc-resistant insulation formulations.
Charging stations capture the steepest expansion trajectory. EV power supply holds the deepest installed base.
Technology:
Volume concentration favors injection-moldable thermoplastics, while margin accrues to specialized conductive and composite formulations.
- Thermoplastics:Cost-efficient, injection-moldable resins dominate connector bodies and casings where scalability meets IEC 61851 safety requirements. BASF SE's Ludwigshafen integrated sites sustain flame-retardant polyamide output for European connector OEMs facing compressed procurement cycles.
- Conductive Polymers:Resistive heating elements and EMI shielding layers displace metal components in next-generation power electronics. SABIC anchors high-heat polycarbonate production for Middle Eastern charging station deployments where thermal management specifications exceed standard grades.
- Polyurethane:Covestro AG differentiates through encapsulant formulations competing on thermal cycling performance.
- Composite Materials:Glass-fiber matrices occupy premium positioning for structural reinforcements in DC fast-charging pylons.
Thermoplastics dominate current volume. Conductive polymers are where specification premiums expand fastest.
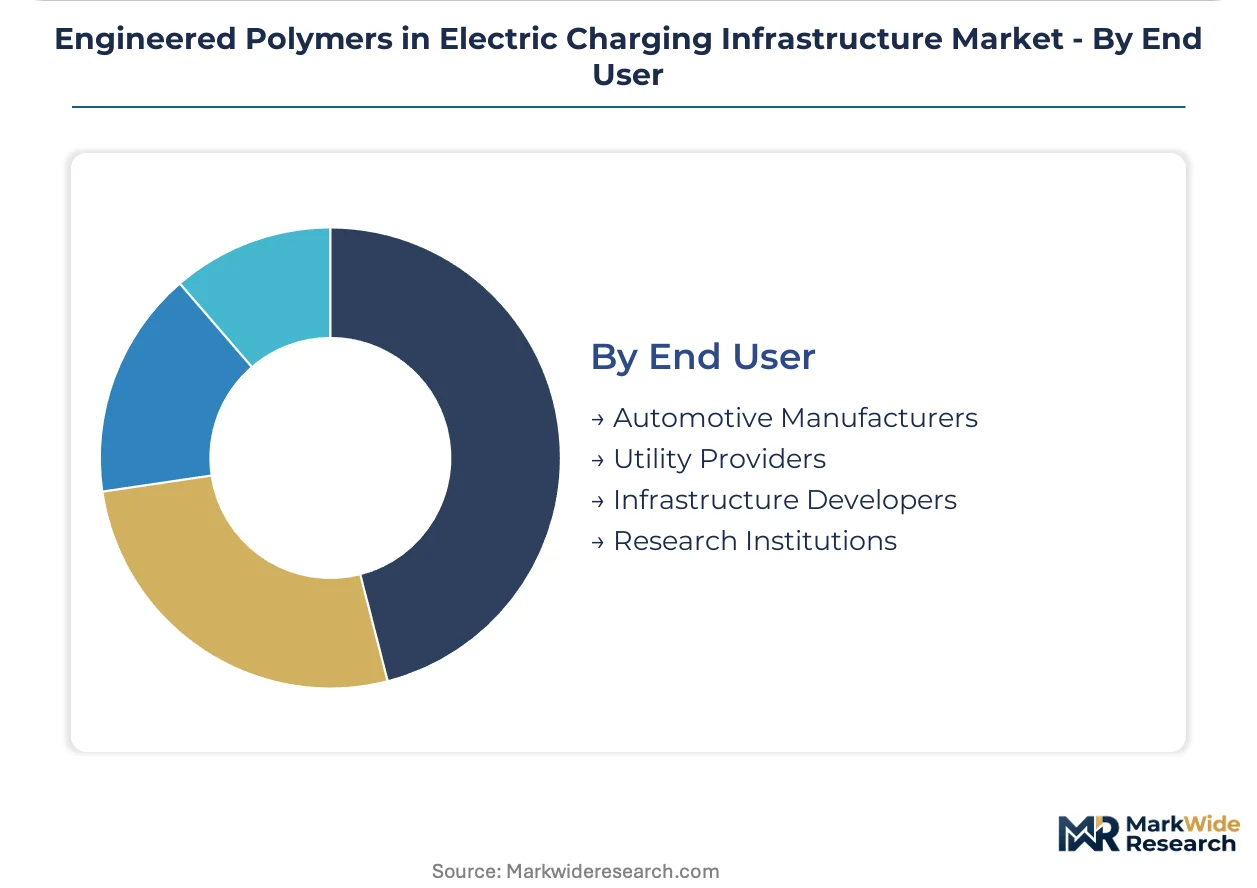
End User:
Customer type determines technical documentation burdens and contract structures, with utilities consolidating supplier relationships around integrated certification packages.
- Utility Providers:Grid operators specify custom flame-retardant grades through direct OEM contracting, bypassing distributors to compress channel margins. E.ON and EnBW in Germany have reduced approved polymer supplier lists from 12 to 4 vendors since 2023, concentrating procurement around compounders offering material-plus-certification integration.
- Automotive Manufacturers:Charging hardware divisions qualify polymers against multi-protocol standards including GB/T, IEC 61851, and SAE, straining technical resources at specialty compounders.
- Infrastructure Developers:Project financiers prioritize unit pricing in bid scoring where technical qualification documentation carries lighter weight.
- Research Institutions:Pilot programs test ceramic-hybrid formulations for 800V thermal runaway mitigation.
Utility providers anchor premium-grade demand. Infrastructure developers drive volume scale in standardized applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Integrated petrochemical complexes in Germany and Saudi Arabia concentrate high-heat polycarbonate and polyamide supply for charging-grade applications. China's coastal manufacturing clusters in Jiangsu and Guangdong provinces anchor compounding capacity for NEV charging network build-outs. Regional regulatory divergence around flame-retardant chemistry and thermal management specifications is fragmenting material qualification pathways.
China
NEV charging network expansion in Jiangsu and Guangdong provinces drives localized polymer compounding investment. MIIT enforces GB/T standards for connector material compatibility that dictate polymer selection across manufacturing clusters. State Grid procurement tenders now weight technical qualification documentation above unit pricing in bid scoring.
Germany
E.ON and EnBW utility procurement of thermoplastic connector housings compresses qualification timelines from 18 months toward 12 months. ECHA REACH restrictions on halogenated flame retardants force 12-18 month reformulation cycles for CE marking compliance. Ludwigshafen integrated sites sustain flame-retardant polyamide output for European connector OEMs.
United States
EPA and NHTSA coordination on tailpipe-emission phase-outs indirectly mandates charging infrastructure density expansion. UL 94 V-0 certification timelines for phosphorus-nitrogen systems require 8-14 month approval cycles. California utility procurement teams consolidate supplier relationships around integrated material-plus-certification packages.
Saudi Arabia
SABIC anchors high-heat polycarbonate production for Middle Eastern charging station deployments where thermal specifications exceed standard grades. The country's national industrial development programs incentivize petrochemical downstream integration into specialty polymer grades. Domestic compounding capacity serves Gulf Cooperation Council fast-charging infrastructure rollouts.
India
PLI scheme domestic manufacturing incentives create first-mover advantage for polymer suppliers establishing local compounding operations ahead of 2026 localization mandates. BIS standards for electrical safety equipment impose material qualification requirements on imported charging hardware. Maharashtra and Gujarat industrial corridors attract regional supply chain investment for NEV charging components.
Engineered Polymers in Electric Charging Infrastructure Market Key Industry Players
Integrated petrochemical conglomerates and specialized compounders split the market between scale-driven commodity supply and performance-tier customization. Three strategic archetypes dominate: European integrated chemical majors with backward control over resin feedstocks, Asian diversified material science groups leveraging regional demand proximity, and mid-tier compounders competing on certification speed and formulation agility. Capacity expansion and direct OEM contracting represent the dominant competitive moves, with charging hardware manufacturers bypassing distributors to specify custom flame-retardant grades.
Within the integrated chemical major tier, BASF SE exemplifies European feedstock-integrated positioning, while SABIC anchors Middle Eastern petrochemical-to-specialty conversion. Covestro AG occupies a differentiated position among polyurethane-focused material science specialists. These three entities represent contrasting geographic and technological anchoring strategies without implying specific market share or operational claims.
| Leading Market Players |
|---|
| BASF SE |
| SABIC |
| Covestro AG |
| DuPont de Nemours |
| Solvay S.A. |
| Evonik Industries AG |
| LG Chem |
| Lanxess AG |
| Celanese Corporation |
| Others |
Cost & Logistics Intelligence
Ludwigshafen's integrated petrochemical complexes concentrate flame-retardant polyamide capacity, granting BASF SE and European compounders pricing leverage over connector OEMs facing compressed 12-month qualification cycles. This supply-side concentration interacts with REACH-mandated reformulation costs to stratify material tiers across premium certification-integrated grades and commodity substitutes.
Pricing Analysis
ECHA REACH dictates the pricing tier structure by forcing 15-25% raw material premiums onto phosphorus-nitrogen flame-retardant systems replacing halogenated compounds. Pricing stratifies across UL 94 V-0 certified grades, standard IEC 61851-compliant formulations, and uncertified economy resins. Cost compression in mid-tier compounds is intensifying because utility procurement consolidation from 12 to 4 approved vendors since 2023 has concentrated volume leverage. Infrastructure developers remain most price-sensitive, while German utilities absorbing 8-12% material cost increases demonstrate lowest sensitivity to secure compliant supply ahead of enforcement deadlines.
Supply Chain Analysis
Contract manufacturing for polymer compounding concentrates among integrated petrochemical complexes in Germany, Saudi Arabia, and China's Jiangsu-Guangdong corridor. Raw material dependencies rest on caprolactam feedstocks for polyamide, bisphenol-A for polycarbonate, and phosphorus-based flame-retardant precursors increasingly sourced from Chinese specialty chemical producers. Single-source vulnerability concentrates around high-heat polycarbonate grades where SABIC's Middle Eastern production anchors regional supply. Distribution runs through direct OEM contracting channels that bypass traditional distributors, compressing channel margins while deepening technical qualification relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market's defensive moat rests on regulatory entrenchment: REACH-compliant formulation portfolios require 8-14 month UL certification cycles that lock in incumbent compounders and deter rapid competitive entry.
For Market Incumbents: Pre-empt margin erosion from phosphorus-nitrogen raw material premiums by anchoring backward integration into flame-retardant precursor supply or captive compounding capacity in China's coastal manufacturing clusters. Certification investment represents the critical lever—deepening UL 94 V-0 documentation packages to match utility procurement consolidation toward integrated material-plus-certification vendors. For New Entrants and Emerging Players: Establish a beachhead in India's PLI scheme window ahead of 2026 localization mandates, where domestic compounding operations face limited incumbent presence. Polyurethane encapsulant formulations for modular charging station designs offer penetrable white space given Covestro AG's differentiated positioning and limited direct competition. A technical partnership route with Maharashtra or Gujarat industrial corridor developers accelerates BIS qualification timelines. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors compounders with REACH-compliant portfolios and direct utility relationships over resin producers lacking certification integration. Long-term viability hinges on 800V architecture material qualification capabilities. The signal to watch is ceramic-hybrid formulation adoption rates for thermal runaway mitigation above 180°C continuous operation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Flame-Retardant Precursors | Secures margin control against phosphorus-nitrogen raw material premiums squeezing mid-tier compounders. |
| Direct OEM Contracting Bypass | E.ON and EnBW procurement consolidation from 12 to 4 vendors rewards technical relationship depth over distributor networks. |
| India PLI Localization Buildout | Maharashtra and Gujarat industrial corridors attract first-mover regional supply chain investment ahead of 2026 mandates. |
| Polyurethane Encapsulant R&D Expansion | Covestro AG's thermal cycling performance differentiation opens modular charging station multi-material replacement opportunities. |
| Multi-Protocol Certification Investment | Concurrent GB/T, IEC 61851, and SAE validation strains specialty compounder resources, favoring integrated documentation capabilities. |
Research Approach
Findings reconcile primary fieldwork against secondary review of customs/trade data, SEC 10-K filings, and European Chemical Industry Council reports through structured interviews with polymer compounding plant managers, charging hardware procurement leads at Tier 1 connector OEMs, utility technical qualification officers, and distribution channel partners. Bottom-up volume modeling from individual compounder capacity disclosures triangulates against top-down demand estimates derived from NEV charging network deployment pipelines.
Forecast inputs incorporate grade tier segmentation across flame-retardant, high-heat, and conductive formulations; end-use industry splits between charging stations, onboard power electronics, and grid infrastructure; and regional production hub clustering around Ludwigshafen, Jubail, and China's coastal manufacturing corridors. CAGRs derive from elasticity-adjusted adoption curves mapped to regulatory enforcement timelines and fast-charging power level trajectories across the analysis window.
Sensitivities concentrate around REACH enforcement acceleration, 800V architecture proliferation rates, and raw material precursor supply disruptions. Quarterly review of UL certification backlog durations, utility procurement tender scoring weights, and ceramic-hybrid formulation pilot program announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicle Charging
Micro Mobility Charging Infrastructure Market
Electric Vehicle Charging
EV Charging Infrastructure Market
Electric Vehicle Charging
Solar Charging Station Market
Electric Vehicle Charging
Italy Electric Vehicle Charging Equipment Market
Electric Vehicle Charging
Thermal Conductive Polymer Material for Electric Vehicles Market
Electric Vehicle Charging
Second Life Electric Vehicle Battery Market
Electric Vehicle Charging
EV Charging Kiosk Market
Electric Vehicle Charging
Electric Vehicle Supply Equipment (EVSE) Market
Electric Vehicle Charging
EV Charging Management Software Platform Market
Electric Vehicle Charging
Public EV Charging Pile Market
Electric Vehicle Charging
Electric Vehicle Coin Charging Station Market
Electric Vehicle Charging
EV Charging System Test and Certification Equipment Market
Electric Vehicle Charging
Home Charging Piles Market
Electric Vehicle Charging
EV Charging Networks Market
Electric Vehicle Charging
Electric Vehicle Charger and Charging Station Market
Electric Vehicle Charging
Japan Electric Vehicles (EV) Charging Equipment Market