
 Global Plug Valve Market | 2026-2036
Global Plug Valve Market Size, Share, and Industry Trends Forecast 2026-2036
Global Plug Valve Market Foresight
Veteran foundry machinist availability is collapsing across North American valve manufacturing hubs, forcing original equipment manufacturers to redesign casting workflows and accelerate automated finishing cell deployment. Emerson Electric Company leverages captive foundry capacity in Texas to sustain uninterrupted delivery schedules for severe-service plug valve orders. Flowserve Corporation competes through differentiated alloy metallurgy programs that extend operational life in high-cycle chemical processing environments. Schlumberger Limited anchors its plug valve portfolio to subsea completion systems, occupying a specialized niche where pressure ratings exceed conventional pipeline specifications.
A plug valve is a quarter-turn rotary valve employing a tapered or cylindrical plug with a central port to start, stop, or throttle fluid flow, typically manufactured from ductile iron, carbon steel, or stainless steel castings with PTFE or metal-seated sealing surfaces. Its primary industrial purpose is to provide bubble-tight shutoff in pipelines handling abrasive, corrosive, or high-viscosity media across oil and gas gathering networks and chemical process trains. Non-lubricated plug valves lead unit shipments in municipal water treatment applications where maintenance intervals must stretch across decades of buried service. Eccentric plug valves represent the fastest-growing product configuration in wastewater management, as offset plug geometry eliminates seat abrasion during cycling. Pneumatic actuation dominates the actuation method mix in petrochemical plants, where remote valve operation from control rooms reduces personnel exposure to hazardous process areas.
API 6D pipeline valve standards and ISO 14313 petroleum and natural gas industry specifications govern pressure-containing boundaries and fugitive emission limits for plug valves deployed in hydrocarbon service. EPA methane emission regulations and EU F-Gas Regulation compliance requirements are forcing valve manufacturers to redesign packing sets and seal geometries to achieve lower leakage classes. OSHA process safety management directives in the United States mandate documented valve integrity programs for facilities handling threshold quantities of highly hazardous chemicals. Stakeholders must monitor evolving hydrogen infrastructure codes as blending ratios climb, since embrittlement-resistant material selections will separate qualified plug valve suppliers from legacy product lines.
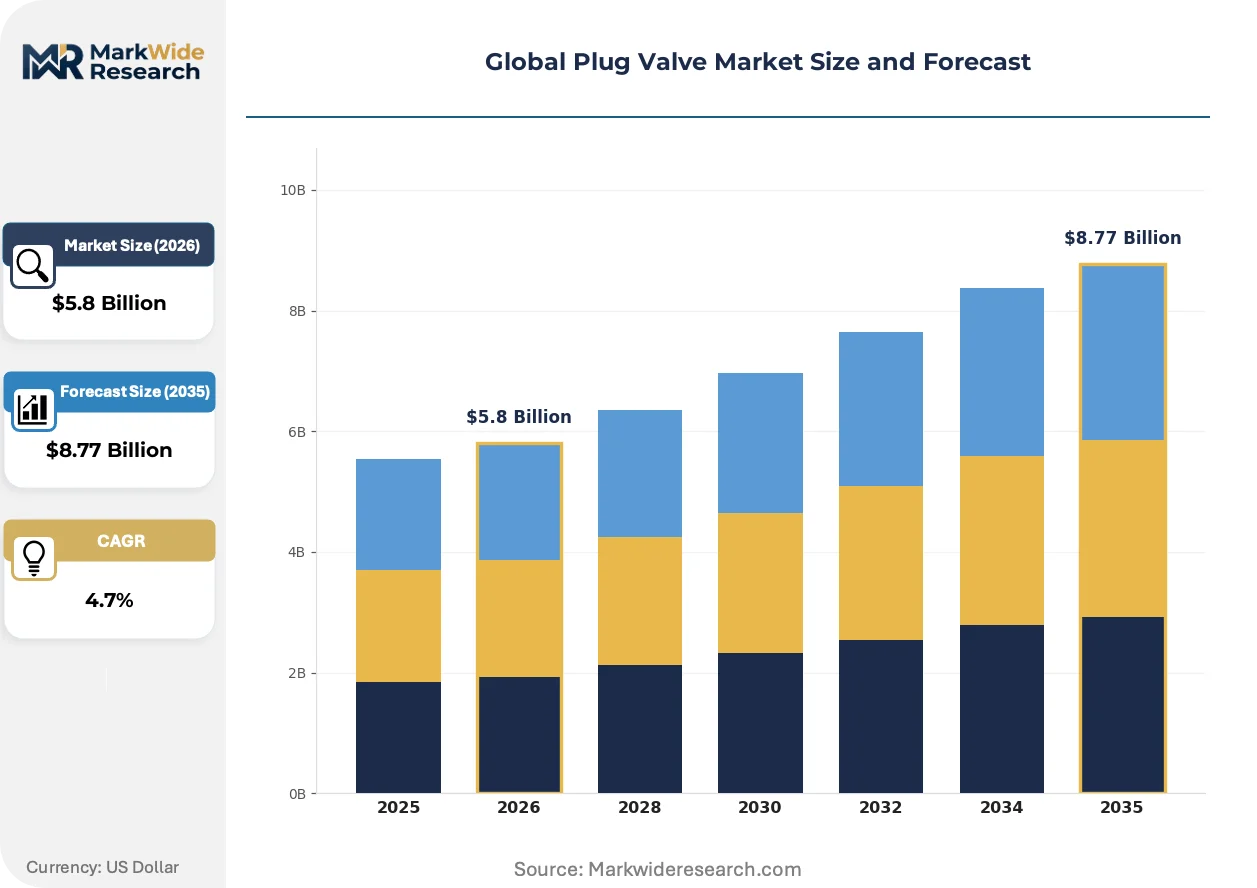
Market Dynamics
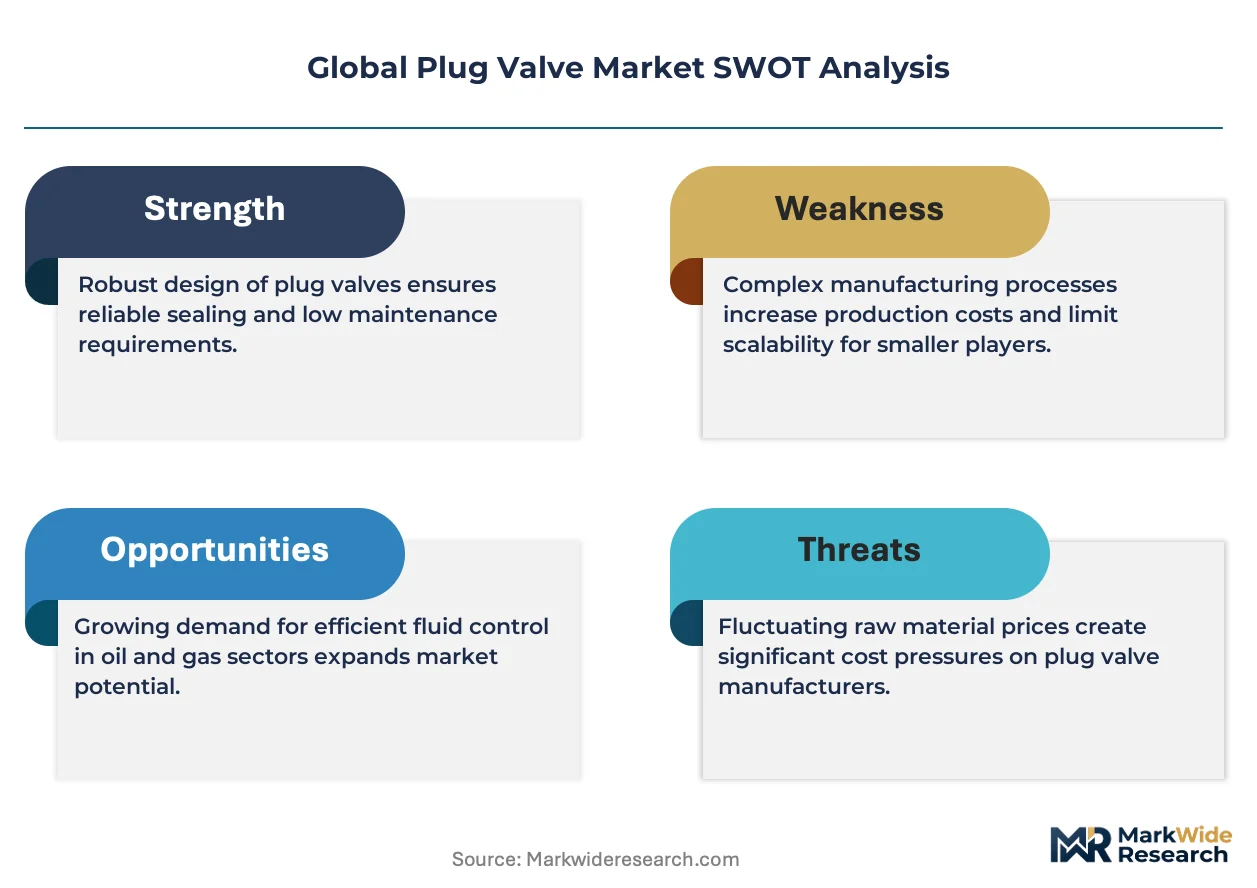
Plug valve procurement is bifurcating between severe-service specifications for sour gas pipelines and standardized commodity configurations for water infrastructure, compressing mid-tier suppliers unable to bridge both certification regimes.
Growth Catalysts
- EPA Methane Regulations:Fugitive emission limits are forcing pipeline operators to replace legacy packed valves with low-leakage plug valve designs, accelerating replacement cycles in US gathering systems.
- Sour Gas Processing Expansion:Hydrogen sulfide-resistant alloy demand from Permian Basin operators is pulling specialized foundry capacity toward NACE MR0175-compliant material programs.
- Desalination Buildout:Saudi Arabia's utility-scale reverse osmosis plants are specifying super-duplex plug valves for seawater intake systems, creating dedicated supply chains for chloride-resistant metallurgy.
Market Restraints
- Foundry Labor Scarcity:Veteran patternmakers and machinists in Texas and Louisiana foundry clusters are retiring faster than apprenticeship programs replace them, constraining casting throughput.
- Nickel Price Volatility:Stainless steel and super-alloy plug valve bodies face margin compression when London Metal Exchange nickel futures spike, forcing material substitution or price pass-through delays.
- Butterfly Valve Substitution:Triple-offset butterfly designs are displacing plug valves in cryogenic LNG transfer lines where weight reduction and automation compatibility outweigh shutoff precision requirements.
Strategic Opportunities
- Hydrogen Blending Infrastructure:Germany's F-Gas Regulation amendments and national hydrogen backbone plans are creating first-mover advantage for valve suppliers certifying embrittlement-resistant sealing systems.
- Digital Twin Integration:Convergence of IIoT sensor packages with predictive maintenance platforms allows plug valve OEMs to capture recurring revenue through condition-monitoring subscriptions rather than one-time hardware sales.
- India Water Mission:Jal Jeevan Mission rural distribution networks represent underpenetrated demand for resilient iron-bodied plug valves in buried municipal service, distinct from industrial procurement patterns.
Industry Challenges
- API 6D Certification Timelines:Third-party witness testing and quality system audits for pipeline valve qualification stretch 14-18 months, freezing engineering resources and delaying revenue recognition.
- Legacy System Integration:Petrochemical plants with 1970s-era pneumatic control architectures face retrofit complexity when specifying smart positioner-equipped plug valves, requiring custom signal conditioning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Plug Valve Market |
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $8.77 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lubricated, Non-Lubricated, Eccentric Plug Valve, Expanding Plug Valve, Others Actuation Method: Manual, Electric, Pneumatic, Hydraulic, Solenoid Application: Oil & Gas, Chemical Processing, Water Treatment, Power Generation, Mining End User Industry: Energy Production, Petrochemical Plants, Wastewater Management, Metal Extraction, Municipal Services |
| Companies Covered | Emerson Electric Company, Flowserve Corporation, Schlumberger Limited, Val-Matic Valve & Mfg. Corporation, 3Z Corporation, Crane Co., AZ Armaturen, Henry Pratt Company, KITZ Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Plug Valve Market Shifts & Advancements
Material science advances and regulatory stringency are compressing product lifecycles while opening premium tiers for certified severe-service configurations. Digitalization of valve monitoring is shifting value capture toward data-driven service models.
Additive manufacturing of nickel-alloy plug valve components is bifurcating supply chains between conventionally cast bodies and printed internal trim geometries. Offshore platform operators in the North Sea are qualifying laser-powder-bed-fusion seat rings for rapid spare part fulfillment. This technology is compressing inventory carrying costs while enabling lot-size-one production economics previously unattainable in forged metal-seated valve construction.
EU F-Gas Regulation phase-down schedules are forcing refrigerant system designers toward lower-global-warming-potential working fluids with distinct material compatibility requirements. Plug valve manufacturers serving cold-chain infrastructure must recertify PTFE and PEEK seal compounds against novel hydrofluoroolefin chemistries. European commercial refrigeration OEMs are consolidating supplier lists to those demonstrating full material traceability through revised REACH documentation.
Integrated valve-actuator packages with embedded diagnostics are displacing separately procured pneumatic positioners in Middle Eastern petrochemical expansions. Saudi Aramco and ADNOC specification sheets now mandate HART protocol compatibility and partial-stroke testing capability as baseline requirements. This specification escalation favors suppliers with captive actuator design capabilities over pure-play valve manufacturers dependent on third-party automation partners.
Global Plug Valve Market Segmentation
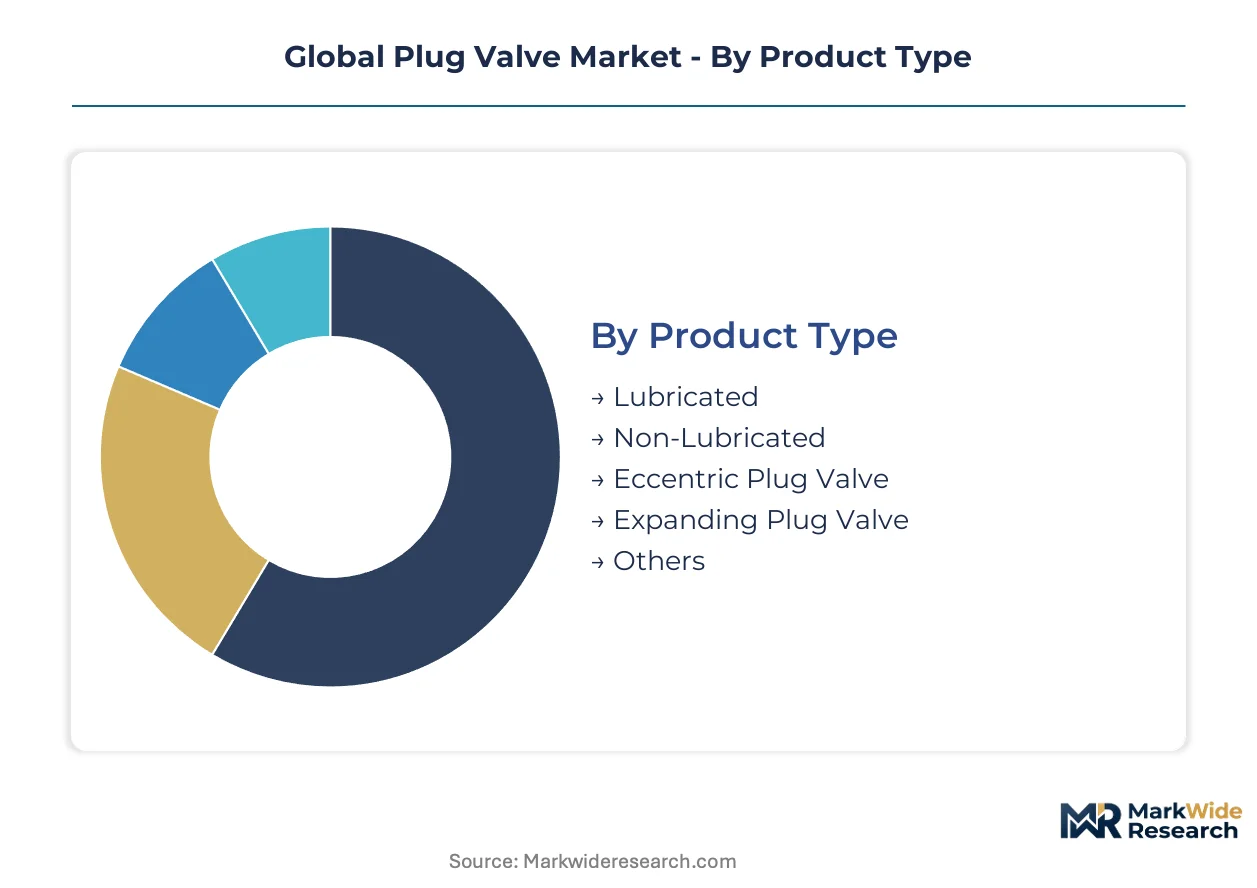
Plug valve procurement patterns diverge sharply across industrial applications, with specification requirements ranging from decades-long buried water service to high-cycle chemical processing. Understanding segment-level substitution pressures and certification thresholds enables suppliers to align metallurgy programs and actuator portfolios with profitable demand pockets.
Product Type:
Triple-offset butterfly valves and ball valve designs are encroaching most aggressively on standardized plug valve configurations, forcing differentiation through severe-service metallurgy and extended maintenance intervals.
- Non-Lubricated:PTFE or elastomer sleeve-sealed construction eliminates periodic lubricant injection, reducing lifecycle operating costs. Demand concentrates in United States municipal water distribution networks where buried service intervals must exceed thirty years without excavation. EPA lead and copper rule compliance is accelerating cast iron body replacement programs across aging infrastructure.
- Eccentric Plug Valve:Offset plug geometry lifts the sealing surface clear of the seat during rotation, eliminating abrasion in high-cycle wastewater applications. German municipal utilities specify these configurations for combined sewer overflow systems where actuation frequency exceeds ten thousand cycles annually. EU Urban Waste Water Treatment Directive compliance timelines are driving replacement of legacy gate valve installations.
- Lubricated:Sealing compound injection maintains bubble-tight shutoff in abrasive crude oil gathering lines. Tar sand extraction operators in Alberta specify these for slurry service where particulate erosion degrades conventional elastomer seals.
- Expanding Plug Valve:Mechanically expanded plug design achieves double block and bleed isolation for pipeline maintenance. Offshore platform operators in the North Sea deploy these for hydrocarbon containment during pigging operations.
- Others:Specialty configurations including multi-port divert valves and cryogenic extended bonnet designs serve niche process requirements. LNG liquefaction trains in Qatar specify these for jetty loading manifold isolation.
Non-lubricated designs anchor the volume base while eccentric plug valves gain share at the steepest rate.
Actuation Method:
Cost tier stratification separates commodity manual operators from integrated smart actuator packages, with mid-range electric and pneumatic configurations capturing the majority of industrial procurement value.
- Pneumatic:Compressed air-powered diaphragm or piston actuators dominate petrochemical plant specifications where explosion-proof requirements preclude electric motor enclosures. Saudi Aramco downstream specifications mandate these for hydrocarbon service areas with classified electrical atmospheres. Integrated positioner diagnostics are becoming baseline requirements rather than premium options.
- Electric:Motor-driven multi-turn or quarter-turn actuators serve remote water treatment facilities without reliable instrument air supply. Australian desalination plants specify these for reverse osmosis train isolation where solar-powered operation eliminates pneumatic infrastructure.
- Manual:Handwheel or lever operators persist in low-cycle isolation service where capital cost minimization outweighs remote operation benefits. India Jal Jeevan Mission rural distribution networks specify these for branch line isolation points.
- Hydraulic:High-force fluid power actuation serves subsea wellhead and manifold applications where external pressure exceeds pneumatic capability depths. Brazilian pre-salt field developments specify these for seabed production system isolation.
- Solenoid:Direct-acting electromagnetic operators enable rapid emergency shutdown response in packaged equipment skids. Compressor station OEMs in the United States specify these for blowdown valve automation.
Pneumatic actuation retains the largest installed base while electric configurations expand most quickly in water infrastructure applications.
Application:
Geographic concentration of end-use demand creates distinct supply chain requirements, with oil and gas procurement favoring API-certified foundries and water applications prioritizing ductile iron casting capacity.
- Oil & Gas:Pipeline gathering, processing, and transmission applications specify NACE MR0175-compliant materials for sour gas compatibility. Permian Basin operators in Texas and New Mexico are expanding procurement of super duplex stainless steel bodies for high-chloride produced water service.
- Water Treatment:Potable water and wastewater applications emphasize corrosion-resistant iron bodies with fusion-bonded epoxy coatings. United Kingdom water utilities specify these for AMP7 regulatory period infrastructure renewal programs.
- Chemical Processing:High-cycle catalytic reactor and distillation column service demands metal-seated configurations with hardened plug and seat geometries. BASF Ludwigshafen complex specifications drive demand for specialty alloy castings.
- Power Generation:Boiler feedwater and cooling water isolation applications balance pressure rating requirements against cost constraints. South Korean combined cycle plant builders specify these for heat recovery steam generator drain service.
- Mining:Slurry tailings and process water applications prioritize abrasion-resistant materials and large bore configurations. Chilean copper concentrators specify these for thickener underflow isolation.
Oil and gas applications anchor revenue concentration while water treatment procurement expands at the most rapid clip.
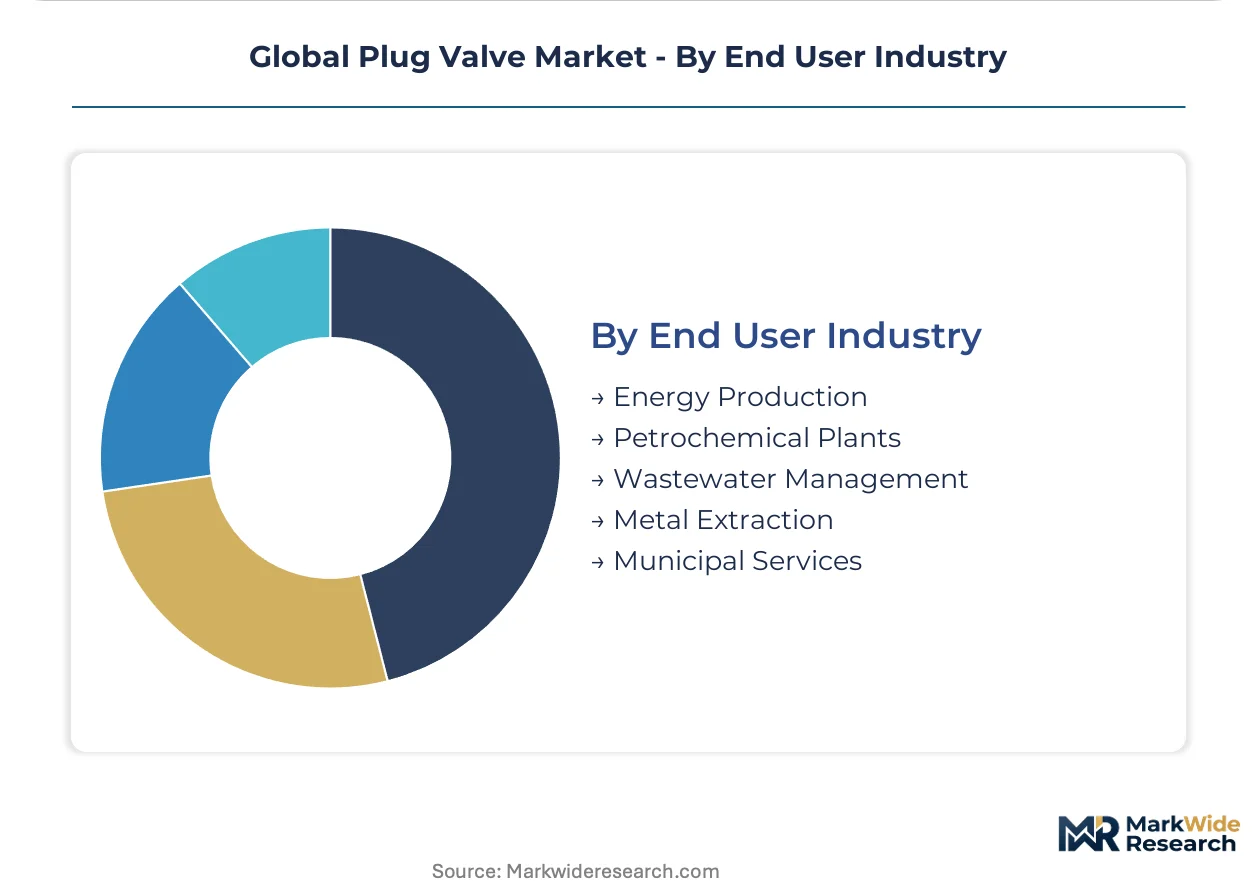
End User Industry:
Customer scale and specification sophistication create tiered supply relationships, with multinational petrochemical operators consolidating vendor lists while municipal buyers fragment procurement across regional foundries.
- Petrochemical Plants:Integrated refining and chemical complex operators specify severe-service configurations with extensive material traceability documentation. ADNOC Ruwais Derivatives Complex requirements are pulling supply chain capacity toward full API 6D and ISO 14313 compliance.
- Wastewater Management:Municipal and industrial treatment facility operators prioritize total lifecycle cost over initial capital expenditure. Netherlands water authorities specify eccentric plug valves for energy-neutral sewage treatment plant upgrades.
- Energy Production:Upstream oil and gas producers and downstream refiners drive demand for high-pressure ratings and sour gas compatibility. Nigerian National Petroleum Corporation pipeline specifications influence West African procurement patterns.
- Municipal Services:City water distribution departments emphasize decades-long service intervals and buried installation compatibility. Japanese water utilities specify earthquake-resistant ductile iron configurations for seismic zone resilience.
- Metal Extraction:Hard rock and solution mining operations demand abrasion-resistant large bore valves for slurry handling. South African platinum concentrators specify these for dense medium separation circuit isolation.
Petrochemical plant procurement generates the highest value per unit while wastewater management applications demonstrate the steepest volume expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Plug valve consumption patterns diverge sharply by geography, with United States procurement emphasizing severe-service sour gas specifications while Asian buyers prioritize corrosion-resistant water infrastructure configurations.
United States
Permian Basin operators drive super duplex stainless steel demand for high-chloride produced water service. EPA methane regulations accelerate replacement of legacy packed valves with low-leakage designs across Texas and New Mexico gathering systems. Houston-Gulf Coast petrochemical corridor concentrates procurement for ADNOC and Saudi Aramco export specifications.
Germany
Municipal utilities specify eccentric plug valves for combined sewer overflow systems exceeding ten thousand annual cycles. EU F-Gas Regulation amendments force recertification of seal compounds against hydrofluoroolefin chemistries. BASF Ludwigshafen complex anchors specialty alloy casting demand for high-cycle catalytic reactor service.
Saudi Arabia
Utility-scale reverse osmosis plants specify super-duplex plug valves for seawater intake systems. Saudi Aramco downstream specifications mandate HART protocol compatibility and partial-stroke testing as baseline requirements. Jubail Industrial City concentrates foundry capacity serving Middle Eastern petrochemical expansions.
China
Desalination buildout along eastern coastal provinces pulls chloride-resistant metallurgy programs. National hydrogen backbone plans create certification urgency for embrittlement-resistant sealing systems. Yangtze River Delta manufacturing clusters automate finishing cells to offset retiring veteran machinist populations.
India
Jal Jeevan Mission rural distribution networks generate underpenetrated demand for resilient iron-bodied buried service valves. BIS standards compliance separates qualified municipal suppliers from industrial-grade fabricators. Gujarat foundry clusters expand ductile iron casting capacity for branch line isolation points.
Global Plug Valve Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with captive foundry capacity and alloy metallurgy programs defining competitive separation. The structure compresses mid-tier suppliers unable to bridge API 6D certification and commodity water infrastructure procurement simultaneously. Three archetypes dominate: vertically integrated majors with captive casting, alloy specialists with NACE-compliant material programs, and subsea-focused niche players with pressure ratings exceeding conventional specifications. Capacity expansion and strategic partnerships represent the dominant competitive moves, as third-party witness testing stretches 14-18 months and freezes engineering resources.
Among United States-based integrated manufacturers, Emerson Electric Company exemplifies the captive-foundry archetype with Texas-based casting capacity sustaining severe-service delivery schedules. Flowserve Corporation occupies the alloy-specialist position, differentiated through metallurgy programs extending operational life in high-cycle chemical processing. Schlumberger Limited anchors the subsea-niche tier, where pressure ratings and completion system integration create defensible positioning. These three represent distinct capability vectors rather than direct product competition, with specification requirements determining which archetype captures individual procurement decisions.
| Leading Market Players |
|---|
| Emerson Electric Company |
| Flowserve Corporation |
| Schlumberger Limited |
| Val-Matic Valve & Mfg. Corporation |
| 3Z Corporation |
| Crane Co. |
| AZ Armaturen |
| Henry Pratt Company |
| KITZ Corporation |
| Others |
Supply & Pricing Matrix
Foundry capacity utilization above eighty percent across Texas and Louisiana clusters compresses supply elasticity and hardens price floors for API 6D-certified castings. This scale concentration forces mid-tier fabricators toward spot market alloy purchases while integrated majors lock in eighteen-month nickel price hedges.
Pricing Analysis
Long-term offtake contracts dominate procurement for Permian Basin pipeline operators, insulating severe-service suppliers from London Metal Exchange nickel volatility while spot-market transactions govern municipal water infrastructure purchases. Price differentiation rests on NACE MR0175 certification tier and captive foundry integration, with super-duplex alloy bodies commanding substantial premia over standard carbon steel configurations. Cost compression in commodity ductile iron tiers is intensifying as Indian foundries expand export capacity. Municipal water authorities exhibit highest price sensitivity, whereas offshore platform operators prioritize lifecycle reliability over initial capital expenditure.
Supply Chain Analysis
Strategic stockpiling of nickel alloy ingots characterizes severe-service procurement patterns, contrasting with just-in-time resin-coated sand deliveries for standard iron castings. Supply concentrates in United States Gulf Coast, Germany's Ruhr foundry belt, and India's Gujarat clusters. Raw material flows draw from Indonesian nickel laterite, Chilean copper concentrate, and Brazilian ferroalloy feeds. Single-source vulnerability permeates super-duplex forging capacity for subsea applications. Distribution runs through authorized stocking distributors for aftermarket replacement, bypassing direct OEM channels for emergency spares.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The plug valve market is recovering from a cyclical trough as sour gas processing expansion in North American shale basins reactivates deferred maintenance schedules. Capital expenditure normalization across Middle Eastern petrochemical complexes reinforces this trajectory.
For Market Incumbents: Fortify captive foundry utilization through multi-year service contracts with Permian Basin operators, locking in alloy volume commitments before Indonesian nickel export restrictions tighten. Accelerate automated finishing cell deployment to offset retiring veteran machinist populations in Texas and Louisiana. Prioritize API 6D certification maintenance as third-party witness testing timelines extend.
For New Entrants and Emerging Players: API 6D fast-track partnerships with established testing laboratories enable rapid qualification for hydrogen infrastructure procurement as Germany's F-Gas Regulation amendments create first-mover windows. Target India's Jal Jeevan Mission rural distribution networks where BIS compliance separates qualified municipal suppliers from fragmented regional fabricators. Pursue joint venture structures with Gujarat foundry clusters to bypass capital-intensive greenfield casting investments.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors alloy specialists with NACE-compliant material programs over commodity casting operations exposed to nickel price volatility. Five-to-ten year viability hinges on hydrogen embrittlement-resistant sealing system certification as blending ratios climb. Watch for German and Chinese national hydrogen backbone procurement timelines as inflection indicators for premium tier demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Captive Foundry Expansion | Emerson Electric's Texas casting capacity sustains uninterrupted severe-service delivery schedules. |
| Alloy Metallurgy Program Investment | Flowserve Corporation extends operational life in BASF Ludwigshafen high-cycle reactor service. |
| Hydrogen Certification Fast-Track | First-mover advantage accrues to suppliers qualifying embrittlement-resistant sealing systems under EU F-Gas amendments. |
| Digital Twin Integration | IIoT sensor convergence captures recurring condition-monitoring revenue from Saudi Aramco specifications. |
| Regional Foundry Joint Venture | Gujarat cluster partnerships penetrate India's Jal Jeevan Mission without greenfield capital deployment. |
Research Methodology
Cross-validation between primary field interviews and secondary regulatory filings anchors the qualitative findings in this analysis. Plant managers at Permian Basin gathering facilities, procurement leads at ADNOC and Saudi Aramco, maintenance directors at German municipal utilities, and aftermarket service heads at North Sea platform operators contributed operational perspectives. These interviews were triangulated against API 6D certification databases, EPA methane emission enforcement records, SEC 10-K filings from listed valve manufacturers, and customs trade data for nickel alloy imports. Bottom-up segmentation modeling and top-down macroeconomic calibration ensure internal consistency.
Sensitivity analysis around nickel price trajectories and foundry labor availability shapes the projection framework across the analysis window. Segmentation dimensions include product type configuration, actuation method tier, application severity grade, and regional regulatory cluster. CAGRs were derived from installed base replacement cycles and new infrastructure buildout pipelines. Hydrogen blending ratio assumptions and API 6D certification timeline distributions constitute industry-specific forecast inputs.
Decision-makers should treat outputs as directional under stable regulatory enforcement and commodity price assumptions; material deviation would warrant model refresh. Revision becomes warranted when EPA methane regulation stringency or EU F-Gas phase-down schedules cross implementation thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Valves
Insulation Flanges Market
Valves
Harmonic Dampers Market
Valves
Hot Blast Valves Market
Valves
North America Residential Ball Valves Market
Valves
Water Draw Off Valves Market
Valves
Pipeline Pigging Equipment Market
Valves
Sandblast Valves Market
Valves
Hydraulic Valves Market
Valves
Subsea Valves Market
Valves
Valve Cover Gasket Market
Valves
Fin Tube Market
Valves
Hydraulic Diaphragm Valve Market
Valves
Reciprocating Compressor Components Market
Valves
Global Valves Market
Valves
Global Valve Positioners Market
Valves
HVAC Valves Market