
 Power Quality Meter Market | 2026-2036
Power Quality Meter Market Size, Share, and Industry Trends Forecast 2026-2036
Power Quality Meter Market Intelligence
Aftermarket service revenue from calibration and firmware updates is narrowing the margin gap between hardware sales and recurring income streams. Schneider Electric leverages its EcoStruxure platform to bundle metering hardware with cloud-based analytics subscriptions. Siemens anchors its position through deep integration with grid automation portfolios across European utility accounts. ABB competes by specializing in IEC 61850-compliant meters for substation digitization projects.
A power quality meter is an electrical instrument that measures voltage fluctuations, harmonic distortion, power factor, and transient events with precision class 0.2S or better to protect equipment and ensure grid compliance. These devices serve industrial, utility, and commercial users by identifying disturbances that cause downtime, equipment degradation, or regulatory penalties. Digital meters now dominate the product landscape due to real-time Ethernet connectivity and multi-parameter analytics that analog architectures cannot deliver. Harmonic analysis technology captures the fastest growth as inverter-based renewable generation and variable-frequency drives proliferate across factory floors. Fixed installation meters occupy the deepest margin pools in utility-scale deployments where long-term monitoring contracts lock in recurring revenue.
The EU F-Gas Regulation and IEC 61000-4-30 standards mandate Class A measurement accuracy for grid interconnection, forcing manufacturers to certify products through notified bodies before market access. EMA and national regulators across Europe enforce electromagnetic compatibility directives that shape product design cycles and testing budgets. The US EPA and FCC impose parallel constraints on meter electronics through energy efficiency guidelines and radio-frequency emission limits. Stakeholders must monitor how IEC 61000-4-30 Edition 3 revisions redefine measurement windows and trigger replacement cycles across installed bases.
Market Dynamics
Harmonic analysis-capable meters are displacing basic power monitoring as data center operators and renewable integrators demand sub-cycle disturbance detection that analog architectures cannot deliver.
Growth Catalysts
- Data center load protection:Hyperscale facilities in Germany and the Netherlands are mandating Class A meters for server rack protection against voltage sags from grid-tied inverter systems.
- IEC 61000-4-30 Edition 3:The revised standard's tightened measurement windows are forcing replacement cycles across utility-scale installed bases, creating hardware refresh demand.
- Industrial electrification:Manufacturing clusters across the Ruhr Valley are deploying fixed-installation meters to monitor variable-frequency drive harmonics and prevent motor winding degradation.
Market Restraints
- Precision sensor cost volatility:Class 0.2S current transformers rely on specialized magnetic alloys whose pricing fluctuates with rare earth supply constraints from Chinese processing facilities.
- Certification timeline friction:EU F-Gas Regulation compliance requires notified body validation that extends product launch cycles by 8-14 months for grid-interconnection hardware.
- Technical integration limits:Legacy substation communication protocols lack native IEC 61850 support, forcing parallel infrastructure investment during meter deployment.
Strategic Opportunities
- Cloud analytics bundling:Hardware vendors can capture recurring revenue by embedding meters within subscription-based power quality monitoring platforms for commercial building portfolios.
- Substation digitization mandates:German transmission system operators are accelerating IEC 61850-compliant meter procurement as part of grid automation roadmaps through 2030.
- Edge computing convergence:Meters with onboard AI inference engines for real-time disturbance classification are opening premium pricing tiers in semiconductor fabrication facilities.
Industry Challenges
- Embedded systems talent scarcity:Firmware development for real-time harmonic analysis requires specialized signal processing expertise that competes with automotive and aerospace sectors for limited engineering pools.
- Multi-standard certification complexity:Products must simultaneously satisfy IEC 61000-4-30 Class A, FCC Part 15 emissions, and national electromagnetic compatibility directives, multiplying testing overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Power Quality Meter Market |
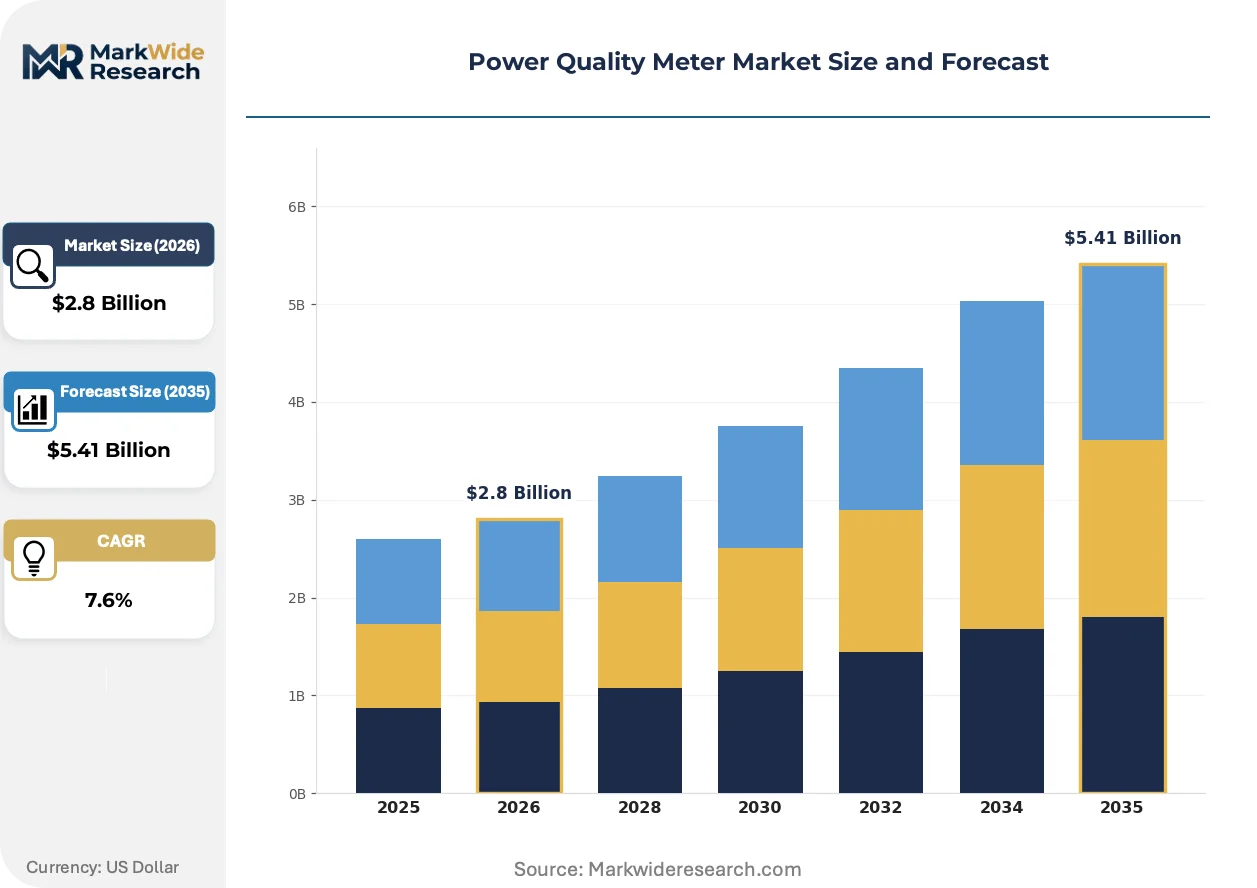
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.41 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analog Meters, Digital Meters, Portable Meters, Fixed Meters Technology: Voltage Monitoring, Harmonic Analysis, Power Factor Measurement, Data Logging End User: Utilities, Industrial Facilities, Commercial Buildings, Residential Users Installation Type: Onshore, Offshore, Indoor, Outdoor |
| Companies Covered | Schneider Electric, Siemens, ABB, Eaton, GE Vernova, Fluke Corporation, Emerson Electric, Honeywell International, Accuenergy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Power Quality Meter Market Strategic Shifts & Innovations
Ethernet-connected digital architectures are compressing the functional gap between utility-grade and commercial-grade meters, while regulatory precision mandates and service model unbundling reshape competitive positioning.
Edge-native power quality analytics is hybridizing meter hardware with localized machine learning inference. Semiconductor fabs and pharmaceutical cleanrooms in Germany and Switzerland are adopting these devices to classify voltage disturbances without cloud latency. The technology is hybridizing traditional meter vendors into software-defined platform providers, compressing margins on standalone hardware while expanding addressable spend per installation.
The EU F-Gas Regulation's measurement accuracy mandates are tightening enforcement timelines for grid-connected equipment. Industrial facilities face penalties for non-compliant interconnection hardware, accelerating replacement of pre-2020 installed bases. German manufacturing clusters and Dutch port industrial zones are responding with bulk procurement of Class A certified meters to preempt regulatory exposure.
Service unbundling is fragmenting traditional hardware-plus-maintenance contracts. Data center operators and utility asset managers are separating meter procurement from calibration and firmware update services, pressuring vendors to compete on transparent lifecycle cost rather than bundled pricing. This pattern is most visible in German utility accounts where long-term monitoring contracts are being re-tendered with discrete service line items.
Power Quality Meter Market Segmentation
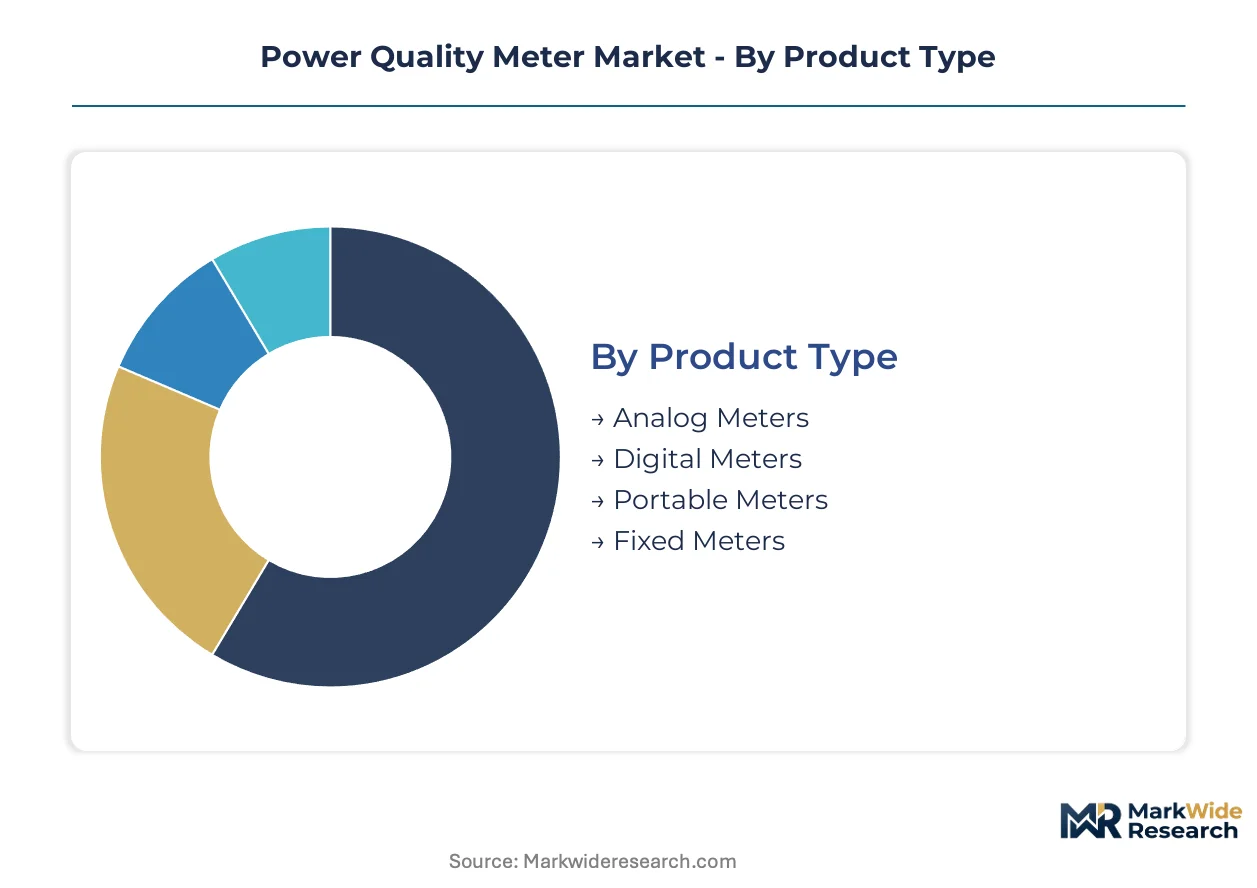
Power quality meter segmentation reveals how technical specifications, deployment contexts, and user requirements fragment procurement patterns across the value chain. Vendors must align product architectures with the precision, connectivity, and durability demands of each category to capture margin pools effectively.
Product Type:
Use-case spectrum spans from legacy maintenance workflows to permanent grid infrastructure monitoring, with digital architectures displacing analog alternatives across all tiers.
- Digital Meters:Ethernet-connected architectures with real-time multi-parameter analytics and IEC 61000-4-30 Class A certification. Data center operators in Germany and the Netherlands mandate these for server rack protection against inverter-induced voltage sags.
- Fixed Meters:Permanent installation devices designed for utility-scale substations and industrial switchgear with 20-year operational lifecycles. German transmission system operators lock in long-term monitoring contracts that generate recurring calibration revenue.
- Analog Meters:Electromechanical displays without data connectivity, retained in legacy industrial maintenance workflows where capital replacement cycles lag regulatory pressure.
- Portable Meters:Handheld diagnostic instruments for field troubleshooting and commissioning verification, deployed by electrical contractors across manufacturing clusters.
The dominant share belongs to Digital Meters, while Fixed Meters is closing the gap fastest.
Technology:
Cost tier stratification separates basic monitoring functions from premium analytics capabilities, with harmonic analysis commanding price premiums due to embedded signal processing complexity.
- Harmonic Analysis:Sub-cycle disturbance detection algorithms identifying inverter-based renewable generation and variable-frequency drive distortion patterns. Semiconductor fabrication facilities in Germany adopt edge-native variants with onboard AI inference for real-time classification.
- Voltage Monitoring:Continuous RMS measurement with sag/swell detection thresholds, forming the baseline functionality across commercial building portfolios and utility distribution networks.
- Power Factor Measurement:Reactive power quantification for industrial capacitor bank control and utility tariff compliance, concentrated in manufacturing electrification projects.
- Data Logging:Event recording with timestamped waveform capture for post-incident forensic analysis, required by IEC 61000-4-30 Edition 3 for grid interconnection certification.
Harmonic Analysis captures the steepest expansion trajectory as inverter penetration accelerates, while Voltage Monitoring retains the largest installed base.
End User:
Customer type determines precision requirements, with industrial and utility procurement governed by regulatory certification timelines that extend 8-14 months for grid-interconnection hardware.
- Industrial Facilities:Manufacturing clusters deploying fixed-installation meters to monitor variable-frequency drive harmonics and prevent motor winding degradation, particularly across the Ruhr Valley.
- Utilities:Transmission and distribution operators requiring IEC 61850-compliant meters for substation digitization roadmaps through 2030, with German TSOs accelerating procurement.
- Commercial Buildings:Facility managers adopting cloud-analytics-bundled metering for portfolio-wide power quality monitoring, with service unbundling pressuring transparent lifecycle cost competition.
- Residential Users:Limited penetration due to cost thresholds, with deployment concentrated in high-value distributed generation interconnection points.
Industrial Facilities command the deepest margin pools, while Utilities is gaining share fastest through regulatory-mandated replacement cycles.
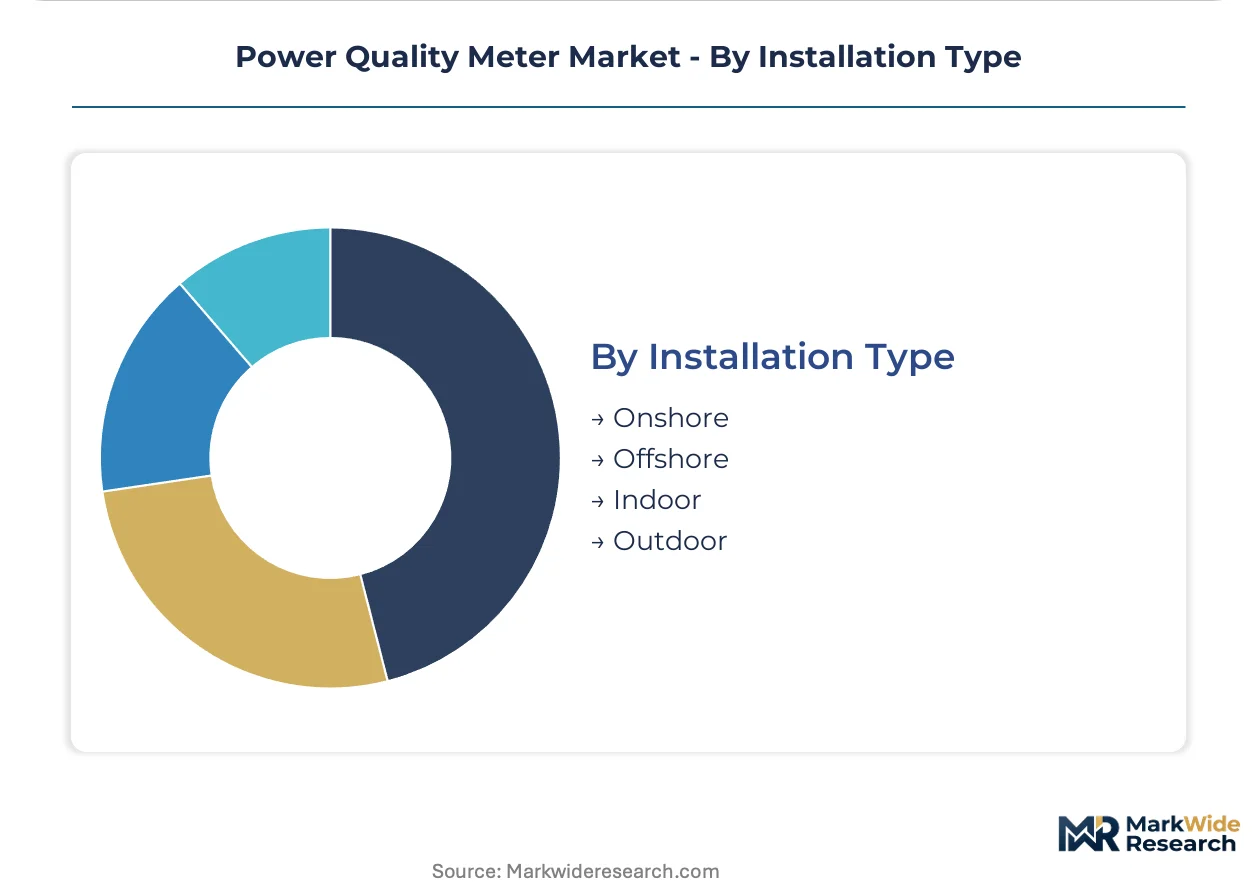
Installation Type:
Volume concentration favors indoor deployments where environmental protection costs are minimized and Ethernet infrastructure is readily accessible.
- Indoor:Climate-controlled environments including data centers, manufacturing floors, and substation control houses where precision sensors operate within calibrated temperature ranges.
- Outdoor:Pole-mounted and pad-mounted installations requiring IP65+ enclosures and extended temperature specifications for utility distribution automation.
- Onshore:Land-based industrial and utility infrastructure across German manufacturing zones and Dutch port industrial areas.
- Offshore:Marine and coastal applications with corrosion-resistant housings, limited to specialized wind farm interconnection and port electrification projects.
Indoor deployment dominates current procurement, while Outdoor is expanding most quickly through utility distribution automation investments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity concentrates in commercial building procurement across Southern Europe, while German and Dutch industrial buyers absorb premium pricing for Class A certification without volume elasticity. Utility-scale tenders in Nordic markets sit between these poles, demanding precision at scale but squeezing service margins.
Germany
Ruhr Valley manufacturing clusters and Bavarian semiconductor fabs drive fixed-installation meter demand for variable-frequency drive monitoring. The EU F-Gas Regulation mandates Class A measurement accuracy through notified body certification. Transmission system operators in North Rhine-Westphalia are accelerating IEC 61850-compliant procurement through 2030 grid automation roadmaps.
Netherlands
Hyperscale data centers in Amsterdam and Rotterdam mandate harmonic analysis-capable meters for server rack protection against inverter-induced voltage sags. The country's national energy regulator enforces electromagnetic compatibility directives aligned with IEC 61000-4-30 Edition 3. Port industrial zones in the Randstad are deploying bulk Class A certified meters to preempt regulatory penalties.
United States
Utility distribution automation investments across Texas and California are expanding outdoor meter deployment for grid resilience. The EPA and FCC impose parallel constraints through energy efficiency guidelines and radio-frequency emission limits. Pacific Northwest semiconductor fabrication facilities are piloting edge-native meters with onboard AI inference for real-time disturbance classification.
China
Dual carbon goals and renewable integration targets are driving substation digitization projects across the Yangtze River Delta. MIIT enforces GB standards for electromagnetic compatibility that shape product design cycles. Manufacturing electrification in the Pearl River Delta is accelerating harmonic analysis meter deployment for motor protection.
India
Industrial electrification under the PLI scheme is concentrating meter demand in Gujarat and Maharashtra manufacturing corridors. The Central Electricity Authority mandates power quality monitoring for grid interconnection of large commercial and industrial loads. Karnataka's data center clusters in Bengaluru are adopting Class A meters for server infrastructure protection.
Power Quality Meter Market Key Industry Players
Capability concentration sits with specialized meter vendors possessing embedded systems and signal processing expertise; scale advantage sits with diversified electrical equipment conglomerates leveraging distribution breadth and utility relationships. The market exhibits tiered structure with premium positions held by platform-integrated providers, mid-tier occupied by component specialists, and value tier served by regional fabricators. Dominant competitive moves include cloud analytics bundling to capture recurring revenue and backward integration into precision sensor manufacturing to hedge magnetic alloy cost volatility.
Within the platform-integrated tier, Schneider Electric SE and Siemens AG exemplify vendors bundling metering hardware with subscription-based monitoring services. ABB Ltd represents the substation-specialist archetype, anchoring positions through IEC 61850 compliance and grid automation integration. These three companies collectively illustrate how competitive positioning stratifies across service model depth, regulatory certification breadth, and vertical integration into precision sensing components.
| Leading Market Players |
|---|
| Schneider Electric |
| Siemens |
| ABB |
| Eaton |
| GE Vernova |
| Fluke Corporation |
| Emerson Electric |
| Honeywell International |
| Accuenergy |
| Others |
Cost & Logistics Intelligence
Ruhr Valley sensor manufacturing clusters anchor magnetic alloy transformer supply, with their capacity utilization rates directly transmitting into downstream pricing power for Class 0.2S precision meters. German industrial buyers absorb premium positioning for IEC 61000-4-30 Edition 3 certified hardware, while Southern European commercial procurement exhibits sharper elasticity to hardware cost movements.
Pricing Analysis
Aftermarket calibration and firmware update contracts now drive lifetime value capture, with Schneider Electric's EcoStruxure subscriptions demonstrating how recurring revenue pools exceed standalone hardware margins. Three-tier pricing structure across premium Class A certified, standard digital, and economy analog levels separates utility-scale buyers from commercial building portfolios. Cost compression in the analog tier is intensifying because data center operators and renewable integrators are abandoning basic monitoring for harmonic-capable architectures. Commercial building facility managers show greatest price sensitivity, while German transmission system operators accept premium positioning without volume negotiation.
Supply Chain Analysis
Tariff exposure between Chinese rare earth processing facilities and European meter assembly plants dominates supply risk planning for precision current transformer sourcing. Manufacturing concentration spans Germany for high-precision assembly, China for magnetic alloy raw material processing, and Mexico for North American market fulfillment. Component dependencies rest on neodymium-iron-boron magnetic alloys, precision voltage reference ICs, and IP65-rated enclosure polymers. Single-source vulnerability concentrates in Chinese rare earth separation capacity for Class 0.2S transformer cores. Distribution runs through authorized electrical distributor networks for industrial accounts and direct utility procurement channels for transmission system operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Power quality meter incumbents face substitution pressure from edge-native AI inference devices that bypass traditional hardware architectures entirely, requiring defensive repositioning around platform integration and certification moats.
For Market Incumbents: Insulate installed base relationships by embedding meters within subscription-based power quality monitoring platforms that raise switching costs for data center and utility accounts. Deepen backward integration into precision current transformer manufacturing to hedge magnetic alloy cost volatility from Chinese processing concentration. Prioritize IEC 61850 certification breadth to defend against substation-specialist competitors targeting German transmission system operator roadmaps. For New Entrants and Emerging Players: Build out edge-native meter offerings with onboard AI inference for real-time disturbance classification, targeting semiconductor fabrication facilities in Germany and Switzerland where latency-sensitive applications command premium pricing. Penetrate the commercial building portfolio monitoring segment through cloud-analytics-bundled propositions, exploiting service unbundling trends that separate hardware procurement from calibration contracts. Pursue white-label partnerships with established electrical distributors to bypass direct certification timeline barriers. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance-recurring-revenue play because IEC 61000-4-30 Edition 3 mandates and EU F-Gas Regulation enforcement create forced replacement cycles with predictable hardware refresh demand. Target acquisition candidates with embedded systems firmware expertise and existing notified body certification relationships that compress time-to-market for new product introductions. Monitor German transmission system operator procurement acceleration signals as inflection indicators for utility-scale demand expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud Analytics Bundling | Captures recurring revenue from data center operators separating meter procurement from calibration services. |
| IEC 61850 Certification Investment | Locks in German transmission system operator procurement through substation digitization roadmaps. |
| Backward Integration into Precision Sensing | Hedges Class 0.2S current transformer cost volatility from Chinese rare earth processing concentration. |
| Edge-Native AI Inference Development | Opens premium pricing tiers in semiconductor fabrication facilities requiring real-time disturbance classification. |
| Service Unbundling Response | Competes on transparent lifecycle cost as utility asset managers re-tender long-term monitoring contracts. |
Research Approach
A spread of perspectives from utility planning officers, data center infrastructure directors, industrial maintenance managers, and precision sensor procurement leads converged on the working assumptions that shaped this analysis. Primary field engagement combined structured interviews with secondary validation against SEC filings from electrical equipment conglomerates, IEC standard revision documentation, and EIA grid interconnection data. Bottom-up segment sizing triangulated against top-down market envelope estimates from customs records and transmission system operator procurement disclosures.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with segmentation modeled by product architecture, certification tier, end-user vertical, and regional regulatory cluster. CAGRs were derived from installed base replacement cycle analysis and greenfield deployment tracking across data center and renewable integration projects. Forecast inputs incorporated IEC 61000-4-30 Edition 3 enforcement timelines and German industrial electrification project pipelines without year-specific milestone assumptions.
The forecast holds incumbent behavior within observed patterns; aggressive platform integration moves by industrial automation conglomerates or accelerated edge-AI substitution by semiconductor equipment vendors would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Meters
Residential RF Smart Electric Meter Market
Smart Meters
Residential Smart Water Metering Market
Smart Meters
Smart Water Metering Market
Smart Meters
Smart Gas Meter Market
Smart Meters
South and Central America Smart Metering Market
Smart Meters
Smart Meter Antenna Market
Smart Meters
Smart Meter Battery Market
Smart Meters
Europe Water Meter Market
Smart Meters
Global Digital Power Meter Market
Smart Meters
Power Monitoring System Market
Smart Meters
US Smart Meter Data Management Market
Smart Meters
Watt Meter Market
Smart Meters
Plug in Power Meter Market
Smart Meters
Gas Meters Market
Smart Meters
Digital Gas Meter Market
Smart Meters
Commercial Non IC Card Gas Smart Meter Sales Market