
 China Explosion-Proof Equipment Market | 2026-2036
China Explosion-Proof Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
China Explosion-Proof Equipment Market Outlook
Industrial distributor networks serving state-owned energy groups is reconfiguring as procurement centralizes under national oil company frameworks. Warom Technology Incorporated Company leverages its certification breadth to anchor large refinery contracts across Bohai Bay installations. Tormin Lighting competes through specialized marine-grade enclosures for offshore platform operators. CESP Lighting sustains manufacturing scale advantages in flameproof lighting fixture production for chemical processing corridors.
China explosion-proof equipment encompasses electrical apparatus engineered to contain or isolate ignition sources in hazardous atmospheres, typically rated for gas groups IIA through IIC and temperature classes T1 to T6 under GB 3836 standards. Flameproof enclosures withstand internal explosions while preventing flame transmission to surrounding explosive atmospheres, serving as the primary protective architecture for oil and gas gathering stations. Intrinsic safety technology leads in instrumentation applications where low-energy circuits eliminate ignition capability, while purge and pressurization systems command premium positioning in analytical shelter deployments across pharmaceutical cleanrooms. Lighting fixtures dominate volume throughput due to universal installation requirements, whereas sensors represent the fastest structural expansion as digitalization mandates proliferate through Sinopec and PetroChina facility upgrades.
MIIT administers explosion-proof product certification under CCC mandatory requirements, while SAMR enforces GB standard compliance through factory audits that determine market access eligibility. NMPA parallel requirements for pharmaceutical manufacturing environments create dual-certification obligations that filter domestic supplier capabilities. Stakeholders must monitor evolving GB 3836 revision timelines and state-owned enterprise consolidation patterns to anticipate procurement concentration shifts.
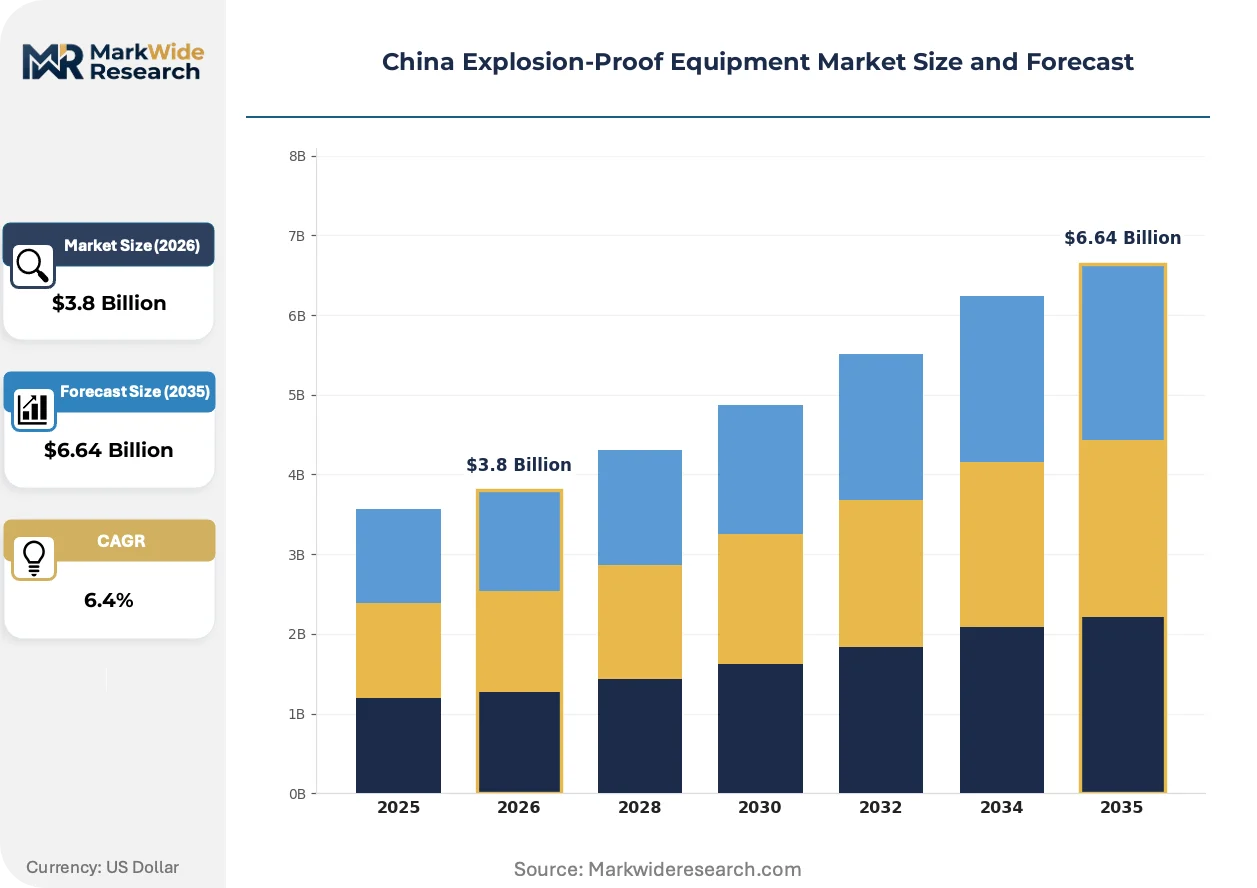
Market Dynamics
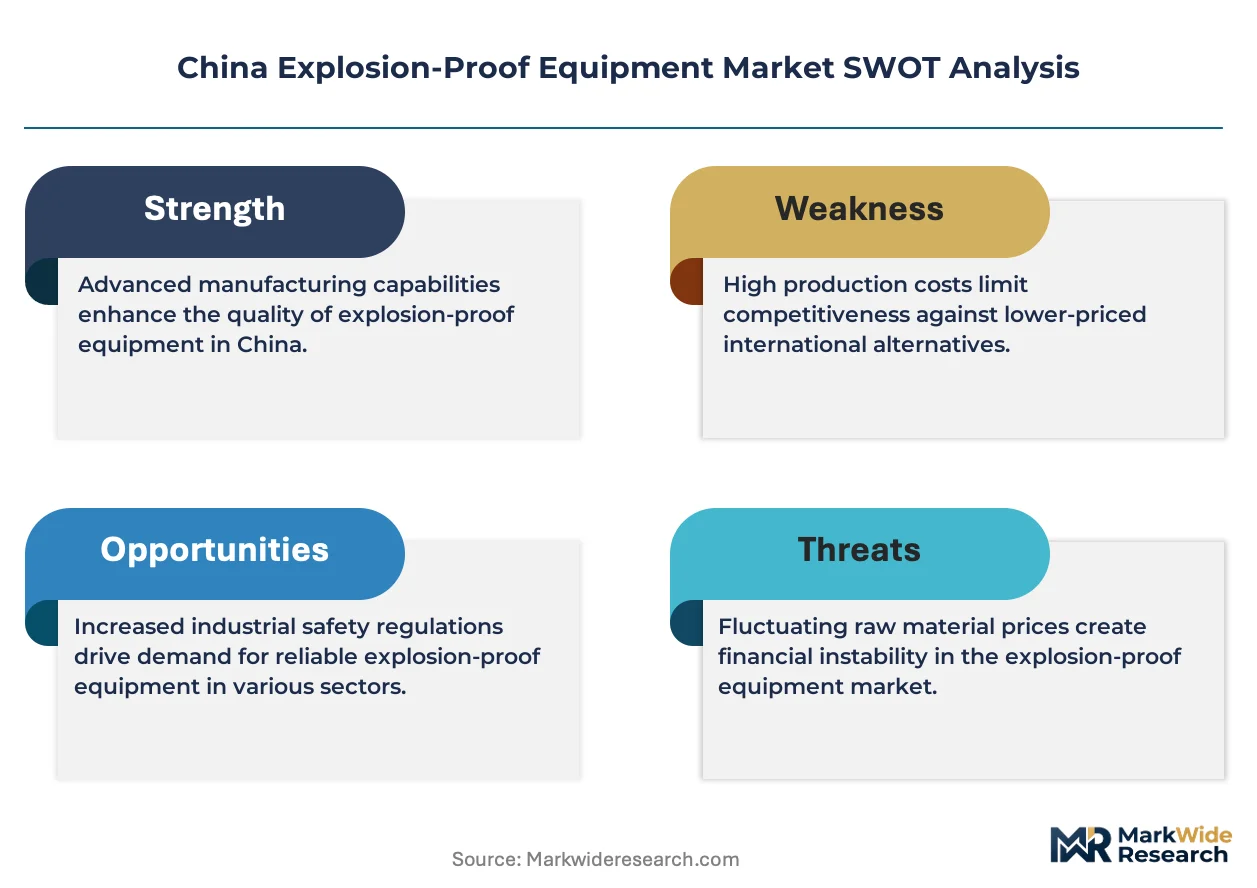
State-owned refinery consolidation under Sinopec and PetroChina procurement frameworks concentrates buying power while MIIT certification mandates force technical upgrades across domestic manufacturing bases.
Growth Catalysts
- MIIT CCC Certification Mandates:Mandatory product certification under GB 3836 standards compels legacy flameproof system replacements across Shandong petrochemical corridors.
- Offshore Platform Expansion:Bohai Bay drilling installations drive marine-grade enclosure demand for submersible electrical apparatus in gas groups IIB and IIC environments.
- Intrinsic Safety Architecture:Low-energy circuit designs eliminate ignition capability in instrumentation applications, displacing conventional flameproof systems in Jiangsu chemical processing zones.
Market Restraints
- Copper and Aluminum Price Volatility:Raw material cost swings compress margins for enclosure fabricators serving state-owned energy procurement frameworks.
- Coastal Manufacturing Concentration:Production gravity centers on Jiangsu and Zhejiang provinces, exposing supply chains to typhoon disruption and port congestion.
- Dual-Certification Burden:Parallel NMPA pharmaceutical manufacturing requirements and MIIT industrial mandates filter domestic supplier capabilities.
Strategic Opportunities
- Digital Sensor Integration:Convergence of explosion-proof housings with IIoT sensing modules opens analytical shelter deployments in pharmaceutical cleanrooms.
- Central China Industrial Corridors:Underpenetrated Hubei and Henan chemical clusters present whitespace for certified distributors beyond coastal saturation.
- Dual Carbon Policy Tailwinds:MEE emissions enforcement drives refinery upgrades, accelerating procurement of energy-efficient LED flameproof lighting fixtures.
Industry Challenges
- GB Standard Revision Uncertainty:Pending updates to GB 3836.1 and GB 3836.2 create certification timeline ambiguity for manufacturers retooling production lines.
- Intrinsic Safety Engineering Scarcity:Shortage of certified engineers capable of designing low-energy circuits limits domestic capability expansion.
- Legacy System Integration Friction:Retrofitting intrinsic safety architectures into existing flameproof installations demands specialized commissioning expertise.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Explosion-Proof Equipment Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Switches, Lighting Fixtures, Enclosures, Sensors Technology: Intrinsic Safety, Flameproof, Purge and Pressurization, Encapsulation Application: Oil & Gas, Chemical Processing, Mining, Pharmaceuticals End User: Manufacturers, Offshore Platforms, Refineries, Industrial Plants |
| Companies Covered | ADTO Group Lighting, Tormin Lighting, Warom Technology Incorporated Company, NJZ Lighting, CESP Lighting, Ouhui Lighting, LEDYi Lighting, Ocean’s King, Zhaochang, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Explosion-Proof Equipment Market Strategic Shifts
Explosion-proof equipment is undergoing fundamental architecture shifts as intrinsic safety circuits displace traditional flameproof enclosures and digital sensing demands reshape product specifications.
LED-integrated flameproof luminaires is hybridizing with photocatalytic self-cleaning coatings to reduce maintenance cycles in corrosive chemical atmospheres. Sinopec facility managers are specifying these hybrid fixtures for new refinery builds in Ningbo and Dalian. The convergence compresses aftermarket service revenue while elevating upfront equipment premiums.
MIIT's pending revision to GB 3836.15 for pressurized enclosures tightens factory audit protocols and extends certification timelines. Domestic manufacturers face working capital pressure from extended SAMR compliance verification periods. Pharmaceutical exporters targeting NMPA-regulated facilities accelerate dual-certification investments ahead of enforcement windows.
Consolidated procurement under national oil company frameworks disaggregates regional distributor relationships. Independent electrical distributors in Tianjin and Qingdao lose direct refinery access as centralized technical specifications favor certified system integrators. The channel compression concentrates margin capture among Beijing and Shanghai-based technical trading houses with MIIT audit credentials.
China Explosion-Proof Equipment Market Segmentation
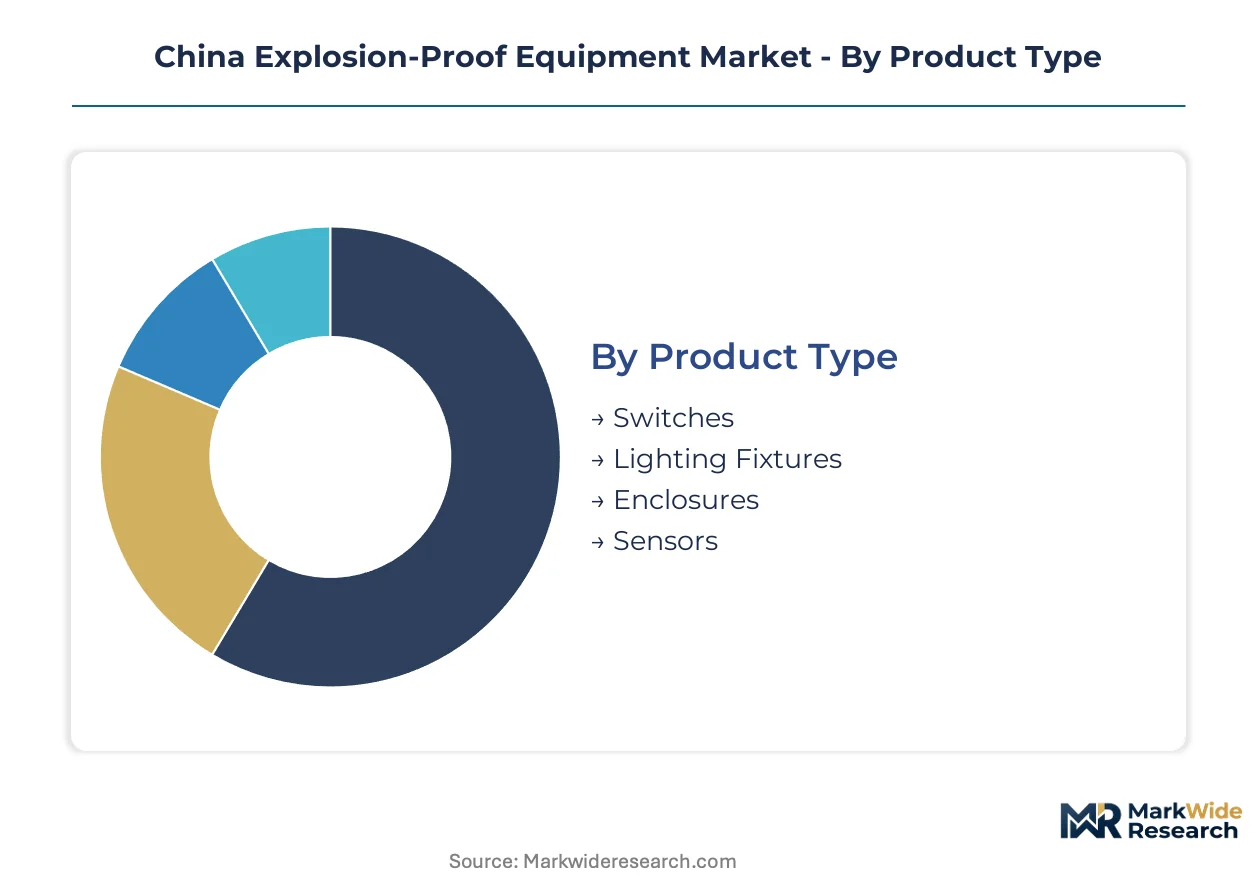
Segmentation in China's explosion-proof equipment market reveals distinct procurement patterns across product architectures and certification tiers. Understanding these divisions exposes where MIIT compliance costs concentrate and which end-use verticals command premium pricing.
Product Type:
After-sales-service intensity varies sharply across product categories, with lighting fixtures requiring frequent lens replacement in corrosive atmospheres while sensors demand calibration contracts.
- Lighting Fixtures:LED-integrated flameproof luminaires with photocatalytic self-cleaning coatings dominate volume throughput. Shandong and Jiangsu petrochemical corridors specify these for new refinery builds, compressing maintenance cycles while elevating upfront equipment premiums.
- Sensors:Digital sensing modules integrated into explosion-proof housings serve IIoT deployments across Sinopec facility upgrades. Jiangsu chemical processing zones drive the steepest expansion trajectory as digitalization mandates proliferate.
- Enclosures:Marine-grade aluminum and stainless steel housings protect electrical apparatus in Bohai Bay offshore installations.
- Switches:Flameproof and intrinsically safe circuit breakers isolate ignition sources in gas groups IIA through IIC environments.
Lighting fixtures hold the largest share; momentum sits with sensors.
Technology:
Cost tier stratification separates mature flameproof architectures from premium intrinsic safety systems requiring specialized engineering.
- Flameproof:Enclosures withstand internal explosions while preventing flame transmission to surrounding atmospheres. Legacy installations across Shandong petrochemical corridors drive replacement demand as MIIT mandates force technical upgrades.
- Intrinsic Safety:Low-energy circuit designs eliminate ignition capability through energy limitation rather than containment. Jiangsu chemical processing zones displace conventional flameproof systems fastest where instrumentation density is highest.
- Purge and Pressurization:Pressurized air systems maintain positive pressure inside enclosures for analytical shelter deployments in pharmaceutical cleanrooms.
- Encapsulation:Resin-sealed components isolate sparking elements in compact electrical devices for space-constrained mining applications.
Flameproof technology retains dominant installed base; intrinsic safety gains share fastest in new builds.
Application:
Application concentration tracks coastal industrial cluster development with state-owned anchor tenants.
- Oil & Gas:Upstream drilling and downstream refining operations require gas group IIC-rated apparatus for hydrogen-rich atmospheres. Bohai Bay offshore platforms anchor capital spending for marine-grade enclosure procurement.
- Chemical Processing:Chlor-alkali and fertilizer production corridors in Shandong specify corrosion-resistant flameproof lighting. Ningbo and Dalian refinery expansions concentrate new equipment demand.
- Pharmaceuticals:NMPA-regulated manufacturing environments create dual-certification obligations with MIIT industrial mandates.
- Mining:Underground coal operations require robust encapsulation for methane-rich atmospheres in Shanxi and Inner Mongolia.
Oil and gas commands the largest procurement volume; pharmaceuticals expand most quickly on dual-certification requirements.
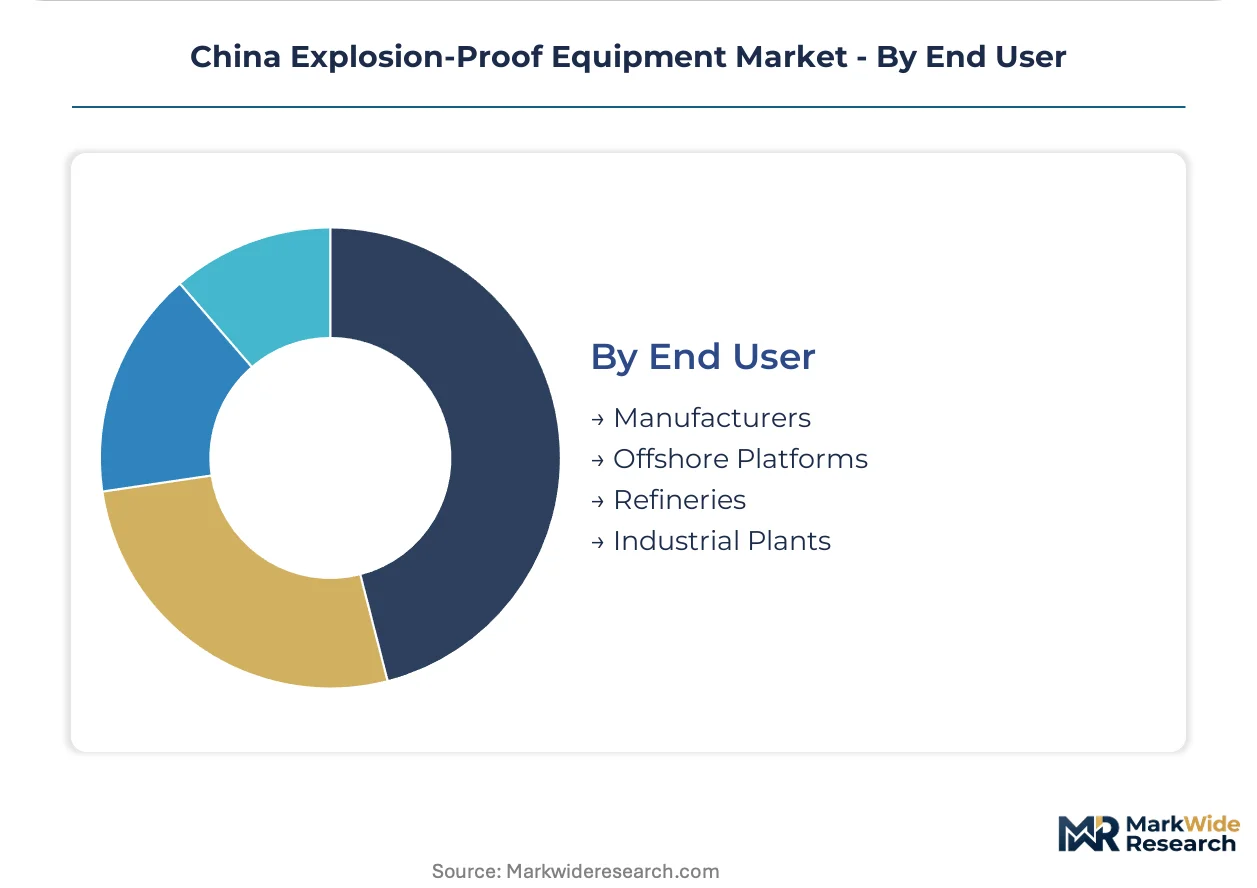
End User:
Customer type determines specification authority and contract structure, with state-owned refineries centralizing technical standards.
- Refineries:Sinopec and PetroChina procurement frameworks consolidate buying power under centralized technical specifications. Tianjin and Qingdao installations specify certified system integrators over independent distributors.
- Offshore Platforms:Bohai Bay drilling contractors demand submersible electrical apparatus rated for gas groups IIB and IIC with specialized marine-grade enclosures.
- Industrial Plants:Provincial chemical processing facilities in Jiangsu and Zhejiang operate under MIIT GB 3836 compliance mandates.
- Manufacturers:OEM equipment builders source certified components for integration into packaged process skids.
Refineries represent the largest end-use segment; offshore platforms climb fastest on Bohai Bay development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in eastern coastal provinces where MIIT certification density and state-owned refinery procurement overlap, while interior manufacturers compete on volume without specification authority.
Shandong Province
Chlor-alkali and petrochemical complexes in Dongying and Zibo drive flameproof lighting replacement cycles. MIIT GB 3836 compliance deadlines compel legacy system upgrades across state-owned refinery frameworks. The province's chemical processing corridors anchor the largest procurement volume for corrosion-resistant enclosures.
Jiangsu Province
Instrumentation density in Nanjing and Nantong chemical zones accelerates intrinsic safety adoption over conventional flameproof architectures. SAMR factory audit protocols filter supplier capabilities as certification timelines extend. The Yangtze River Delta manufacturing belt concentrates sensor-integrated explosion-proof housing production.
Zhejiang Province
Marine-grade enclosure fabricators in Ningbo serve Bohai Bay offshore platform contractors. NMPA dual-certification requirements for pharmaceutical exporters create compliance premiums. The province's lighting fixture manufacturers face working capital pressure from extended MIIT verification periods.
Tianjin Municipality
Centralized Sinopec procurement frameworks displace independent distributors from direct refinery access. GB 3836.15 revision uncertainty delays pressurized enclosure certification for analytical shelter deployments. The Binhai New Area anchors technical trading houses with MIIT audit credentials.
Guangdong Province
Pearl River Delta electronics integrators source explosion-proof components for packaged process skid builders. MEE emissions enforcement under dual carbon policy accelerates LED flameproof lighting procurement. Shenzhen-based system integrators capture margin from specification authority over component vendors.
China Explosion-Proof Equipment Market Competitive Environment
Certification-breadth specialists and manufacturing-scale operators split the market along specification-versus-volume axes. State-owned refinery consolidation concentrates buying power under centralized technical frameworks, compressing regional distributor relationships. Three archetypes dominate: MIIT-certified system integrators with audit credentials, coastal manufacturing-scale players with fixture volume advantages, and specialized marine-grade enclosure fabricators. Competitive moves center on dual-certification investments ahead of NMPA enforcement windows and backward integration into aluminum enclosure casting.
Among certification-breadth players, Warom Technology Incorporated Company occupies a position exemplifying MIIT audit credential leverage across Bohai Bay installations. Tormin Lighting represents the specialized marine-grade enclosure archetype serving offshore platform operators. CESP Lighting sits within the manufacturing-scale tier, anchoring flameproof lighting fixture production volume for chemical processing corridors. These three illustrate how strategic positioning diverges between specification authority, specialized application depth, and production scale.
| Leading Market Players |
|---|
| ADTO Group Lighting |
| Tormin Lighting |
| Warom Technology Incorporated Company |
| NJZ Lighting |
| CESP Lighting |
| Ouhui Lighting |
| LEDYi Lighting |
| Ocean's King |
| Zhaochang |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in Jiangsu and Zhejiang enclosure fabrication facilities compresses supplier margins while concentrating pricing power among MIIT-certified system integrators with audit credentials. Utilization rates below break-even thresholds force coastal manufacturers to absorb copper and aluminum cost swings rather than pass through to state-owned refinery buyers.
Pricing Analysis
Configured-to-order intrinsic safety systems command 40-60% premiums over standard flameproof enclosures due to engineering scarcity and extended certification timelines. Three-tier pricing structure across MIIT-certified premium, GB-compliant standard, and uncertified economy levels stratifies the market. Cost compression in standard flameproof tiers intensifies because raw material volatility outpaces procurement contract adjustments. Provincial chemical processors exhibit highest price sensitivity, while Sinopec centralized frameworks prioritize specification compliance over unit cost.
Supply Chain Analysis
Extended payment terms from state-owned refineries strain working capital for Jiangsu and Zhejiang fabricators, accelerating supplier-financing facility adoption. Production gravity centers on China for aluminum casting and enclosure assembly, with specialty copper alloys drawn from domestic smelters and German precision component suppliers. Single-source vulnerability concentrates in MIIT certification audit capacity, where SAMR-approved assessor scarcity creates bottlenecks. Distribution runs through Beijing and Shanghai technical trading houses with direct national oil company framework access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified intrinsic safety engineering capability sits at a structural deficit relative to digitalization mandates across Sinopec and PetroChina facility upgrades, creating acquisition premiums for qualified design teams.
For Market Incumbents: Build certification-breadth moats by securing NMPA pharmaceutical manufacturing credentials ahead of enforcement windows to capture dual-certification premiums. Deepen backward integration into aluminum enclosure casting to offset copper price volatility compressing margins on standard flameproof fixtures. Channel control through exclusive system integrator relationships defends against procurement centralization disaggregating regional distributors. For New Entrants and Emerging Players: Pursue whitespace in Hubei and Henan chemical corridors where MIIT-certified distributor density remains below coastal saturation levels. Target pharmaceutical cleanroom analytical shelter deployments where dual-certification obligations filter incumbent capabilities. Go-to-market leverage rests on partnering with Beijing-based technical trading houses possessing established SAMR audit relationships. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among sensor-integrated explosion-proof housing providers serving IIoT calibration contracts across Jiangsu chemical zones. Long-term viability favors manufacturers with captive intrinsic safety engineering teams capable of displacing flameproof architectures in new refinery builds. Acquisition priority sits with mid-scale Jiangsu fabricators holding GB 3836.15 pressurized enclosure pre-certification. The signal to watch is SAMR factory audit timeline compression indicating regulatory capacity expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Certification Investment | NMPA pharmaceutical credentials unlock analytical shelter premiums in Zhejiang export corridors. |
| Backward Integration into Aluminum Casting | Captive enclosure production insulates margins from copper volatility in Shandong refinery contracts. |
| Intrinsic Safety Engineering Acquisition | Certified design teams command scarcity premiums as Jiangsu digitalization mandates accelerate. |
| Central China Distribution Expansion | Hubei and Henan corridor penetration captures whitespace beyond coastal saturation. |
| IIoT Sensor Integration Partnership | Convergence with digital sensing modules opens Sinopec facility upgrade procurement. |
Study Parameters
Cross-validation between primary interviews with plant engineers at Sinopec and PetroChina facilities and secondary analysis of MIIT certification databases anchors the qualitative findings. Conversations with SAMR audit assessors, aftermarket service heads at coastal distributors, and procurement leads at Zhejiang pharmaceutical exporters supplemented technical specification review. Bottom-up equipment shipment tracking and top-down refinery capital expenditure analysis triangulate market sizing across the analysis window.
Calibration against historical GB 3836 revision implementation patterns and state-owned enterprise consolidation timelines informs the projection framework. Segmentation dimensions span product architecture, certification tier, end-use vertical, and regional industrial cluster density. CAGRs derive from equipment replacement cycle analysis and digitalization mandate penetration curves. Intrinsic safety adoption velocity and dual-certification compliance rates serve as industry-specific forecast inputs.
Sensitivities concentrate around pending GB 3836.1 and GB 3836.2 revision timelines and SAMR factory audit capacity expansion. Forecasts reflect assumptions regarding state-owned refinery procurement centralization and MEE emissions enforcement intensity. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Valves
Pipeline Integrity Management (PIM) Market
Valves
Blasting Stemming Plugs Market
Valves
Vaneometer Market
Valves
Mechanical Shaft Seal Market
Valves
Global Gate Valve Market
Valves
North America High Voltage Switchgear Market
Valves
Gate Impellers Market
Valves
Chemical Injection Metering Pumps and Valves Market
Valves
Air Vent Heads Market
Valves
Global Automotive Valves Market
Valves
Industrial Valves and Actuators Market
Valves
Global Pressure Relief Valves Market
Valves
High-Purity Fluoropolymer Valves Market
Valves
3-Way Pilot Operated Directional Control Valves Market
Valves
Gas Equipment Market
Valves
Off-Highway Hydraulic Valve Actuator Systems Market