
 Huber Needles Market | 2026-2036
Huber Needles Market Size, Share, and Industry Trends Forecast 2026-2036
Huber Needles Market Intelligence
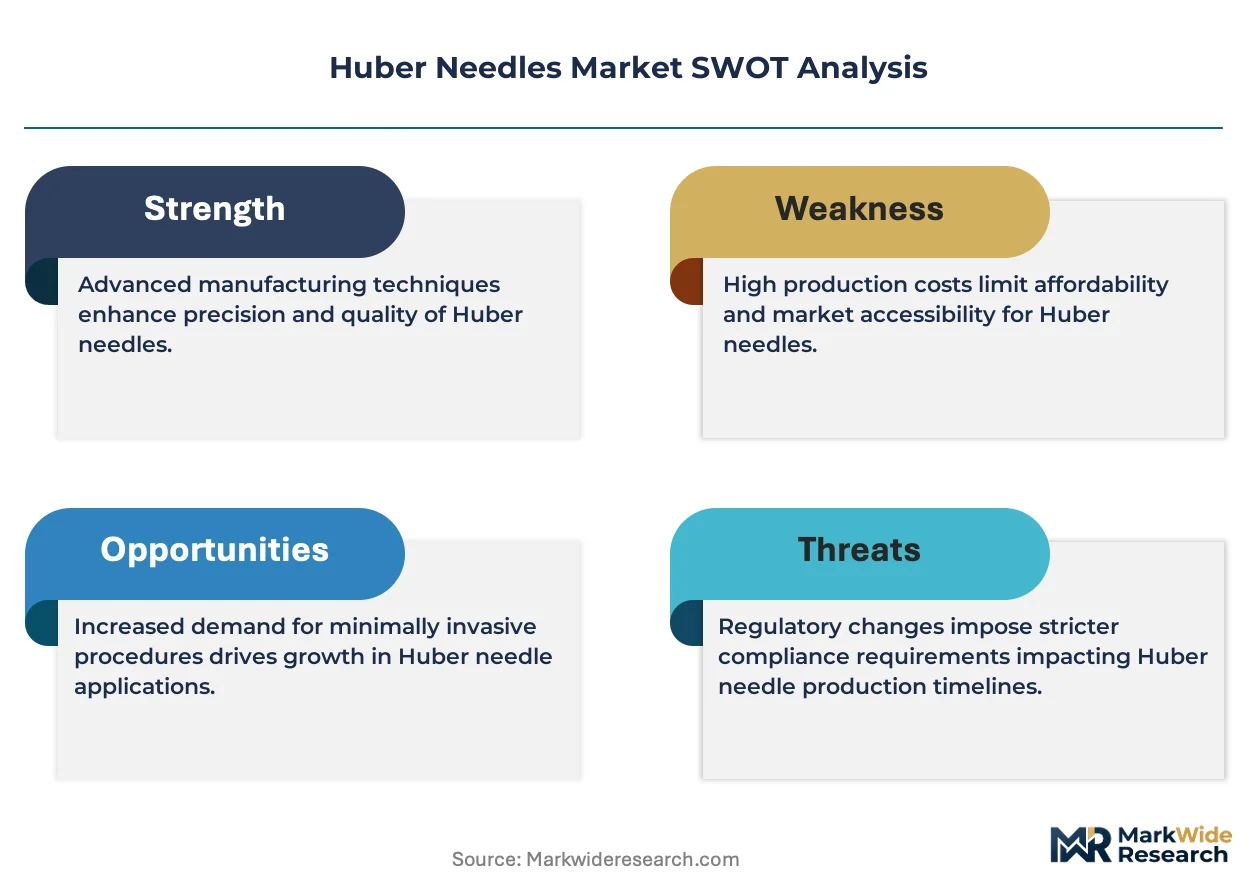
The gap between premium safety-engineered Huber needles and commodity non-coring alternatives is expanding as reimbursement policies harden around needlestick prevention compliance. Becton, Dickinson and Company leverages its integrated safety portfolio to dominate hospital procurement channels. B. Braun Medical Inc. anchors European supply through localized manufacturing and CE-marked safety systems. Nipro Medical Corporation competes on cost-optimized stainless steel designs for emerging clinical settings.
Huber needles are non-coring, right-angled access devices designed to penetrate implanted vascular ports without damaging silicone septums, typically manufactured from medical grade stainless steel with 19-22 gauge diameters and lengths from 0.5 to 1.5 inches for repeated infusion therapy. Safety Huber needles command premium positioning as OSHA compliance mandates drive replacement of conventional designs in U.S. oncology centers. Chemotherapy application volumes sustain the largest revenue pool, while home healthcare providers represent the fastest structural shift as ambulatory infusion protocols expand.
FDA 510(k) clearance pathways and OSHA Bloodborne Pathogens Standard enforcement shape U.S. product entry and safety feature requirements, while the EU MDR transition extends conformity assessment timelines for CE-marked devices. ISO 7864 and ISO 9626 specifications govern cannula performance and material biocompatibility across all regulated markets. Stakeholders must monitor evolving sharps safety legislation and port compatibility standards to align R&D pipelines with procurement criteria that increasingly bundle safety compliance into total cost-of-ownership evaluations.
Market Dynamics
OSHA's sharpened Bloodborne Pathogens Standard enforcement is compressing replacement cycles for conventional Huber needles across U.S. oncology centers, forcing rapid portfolio upgrades toward safety-engineered designs before reimbursement penalties activate.
Growth Catalysts
- Sharps safety mandates:OSHA compliance deadlines in the United States are compelling hospital systems to retire legacy non-safety devices ahead of schedule.
- Home infusion expansion:Ambulatory chemotherapy protocols are extending Huber needle utilization beyond traditional clinical settings into patient-managed environments.
- Port implantation growth:Implantable vascular access device placements are rising in long-term oncology regimens, creating recurring needle replacement demand.
Market Restraints
- Medical-grade stainless steel volatility:Nickel and chromium input cost swings squeeze margin structures for commodity needle manufacturers.
- Single-source sterilization capacity:Gamma irradiation services concentrate in specialized facilities, creating geographic supply bottlenecks during demand surges.
- EU MDR transition friction:Extended conformity assessment timelines delay CE-marked safety product launches, freezing European market access for updated portfolios.
Strategic Opportunities
- Underpenetrated Latin American oncology infrastructure:Brazil and Mexico lack standardized port-based protocols, presenting first-mover education and distribution advantages.
- Smart safety integration:RFID-enabled needle tracking converges with hospital inventory management systems to reduce loss and expiration waste.
- IRAct domestic manufacturing incentives:U.S. production tax credits support reshoring of stainless steel component fabrication and final assembly operations.
Industry Challenges
- Biocompatibility certification bottlenecks:ISO 10993 testing backlogs at notified bodies extend product validation timelines by quarters.
- Legacy port compatibility verification:Silicone septum material variations across implanted device generations complicate universal needle design claims.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Huber Needles Market |
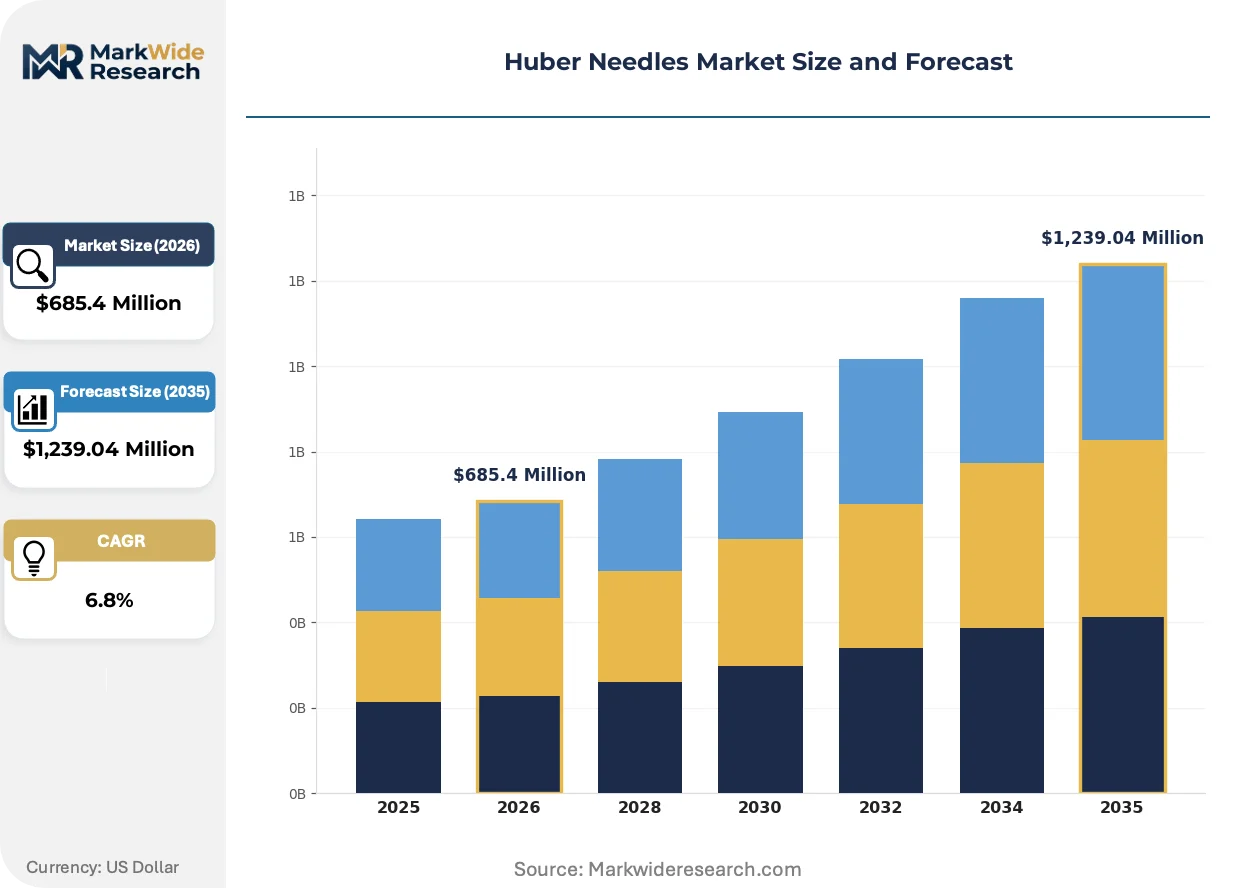
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,239.04 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stainless Steel, Disposable, Coated, Double Lumen, Safety, Non-Coring Application: Chemotherapy, Parenteral Nutrition, Blood Sampling, Intrathecal Therapy, Diagnostic Procedures, Drug Delivery End User: Oncology Centers, Dialysis Clinics, Diagnostic Laboratories, Specialized Treatment Facilities, Home Healthcare Providers Material Type: Medical Grade Stainless Steel, Titanium Alloy, Plastic Components, Silicone Coating, Polycarbonate, Nylon |
| Companies Covered | Becton, Dickinson and Company, B. Braun Medical Inc., Nipro Medical Corporation, Baxter International, Inc., ICU Medical, Inc., AngioDynamics, Inc., Vygon SAS, Smiths Medical, EXELINT International, Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Huber Needles Market Strategic Shifts & Innovations
Active safety mechanisms and connected device architectures are redefining competitive differentiation in vascular access, moving procurement criteria beyond unit cost toward total compliance cost and patient outcome metrics.
Passive safety Huber needle designs incorporating automatic needle shielding upon withdrawal are expanding into high-volume U.S. hospital systems replacing manual safety devices. Oncology centers in the Northeast and Midwest are adopting these systems fastest due to state-level needlestick prevention laws preceding federal enforcement. The technology is expanding into premium pricing tiers as bundled safety compliance becomes a non-negotiable procurement filter.
EU MDR Article 117 requirements for clinical evidence on sharp injury prevention are forcing manufacturers to generate post-market surveillance data on safety feature effectiveness. This regulatory load favors larger portfolios with existing clinical study infrastructure while squeezing mid-tier competitors. German and French notified bodies are processing submissions slowest, creating competitive timing advantages for early filers.
Hospital buying groups are consolidating Huber needle procurement into multi-year safety device contracts spanning infusion therapy portfolios. Group purchasing organizations now weight OSHA compliance verification more heavily than per-unit pricing in supplier scorecards. This behavioral shift is most visible in the United States, where integrated delivery networks capture over half of oncology center purchasing volume.
Huber Needles Market Segmentation
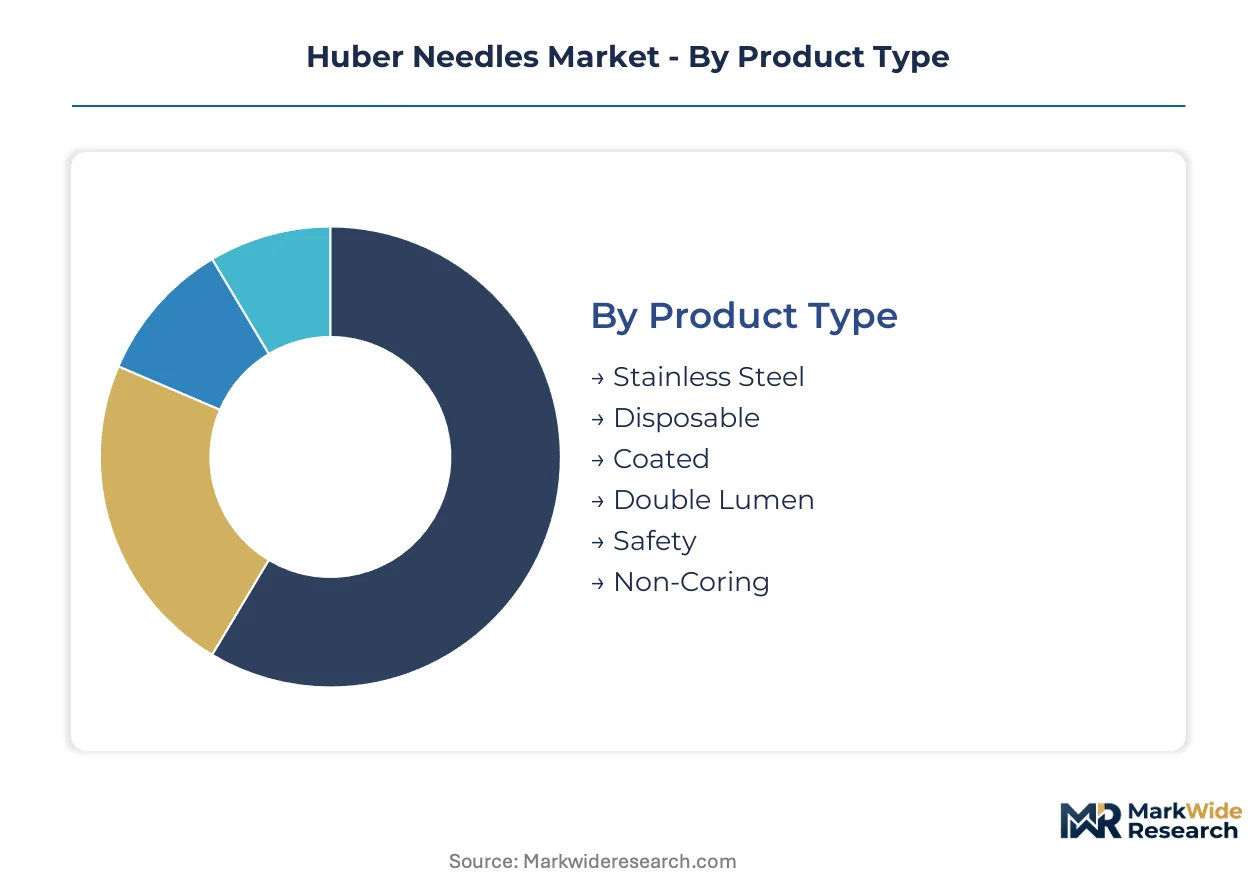
Huber needle procurement patterns diverge sharply across clinical settings, with safety compliance mandates and port compatibility requirements creating distinct buyer profiles. Understanding these segment boundaries clarifies where pricing power concentrates versus where commoditization pressures dominate.
Product Type:
Buyers in this category separate into institutional procurement teams prioritizing OSHA compliance and cost-conscious operators accepting legacy designs.
- Safety:These devices incorporate automatic shielding mechanisms that activate upon needle withdrawal, satisfying OSHA Bloodborne Pathogens Standard requirements. Demand concentrates in United States hospital systems facing compliance deadlines, with Northeast and Midwest oncology centers replacing manual safety devices fastest.
- Stainless Steel:Conventional non-safety designs fabricated from medical-grade stainless steel dominate emerging clinical settings where regulatory enforcement remains uneven. Procurement in Latin American oncology infrastructure favors these cost-optimized alternatives.
- Disposable:Single-use configurations eliminate sterilization logistics for ambulatory infusion providers.
- Coated:Silicone and polymer surface treatments reduce insertion friction for patients requiring frequent port access.
- Double Lumen:Dual-channel designs enable simultaneous infusion and blood sampling in intensive chemotherapy regimens.
- Non-Coring:Right-angled tip geometries preserve silicone septum integrity across repeated vascular port penetrations.
Volume sits with Stainless Steel; growth tilts toward Safety.
Application:
Clinical protocol intensity determines replacement frequency and safety feature requirements across use cases.
- Chemotherapy:Long-term oncology regimens drive the largest revenue pool, with port-based infusion protocols in United States cancer centers creating recurring needle replacement demand. OSHA enforcement compresses replacement cycles toward safety-engineered designs.
- Home Healthcare:Patient-managed ambulatory infusion represents the fastest structural shift, extending Huber needle utilization beyond traditional clinical settings. United States home infusion providers are adopting safety devices as liability frameworks tighten.
- Parenteral Nutrition:Chronic nutritional support requires durable access devices for extended therapy durations.
- Blood Sampling:Diagnostic laboratories prioritize non-coring tip geometries to maintain sample integrity.
- Intrathecal Therapy:CNS drug delivery demands specialized needle specifications for spinal port access.
- Diagnostic Procedures:Imaging contrast injection protocols favor standardized gauge configurations.
Chemotherapy captures current volume leadership; home healthcare applications are climbing the fastest.
End User:
Facility scale and regulatory exposure shape procurement sophistication and contract consolidation patterns.
- Oncology Centers:High-volume chemotherapy administration drives bundled safety device contracts through United States group purchasing organizations. Integrated delivery networks now weight OSHA compliance verification above per-unit pricing in supplier scorecards.
- Home Healthcare Providers:Dispensing pharmacies and visiting nurse services are expanding fastest as ambulatory protocols shift infusion therapy outside hospital walls. United States reimbursement policy changes accelerate this migration.
- Dialysis Clinics:Chronic kidney disease treatment centers require vascular access devices for extended therapy sessions.
- Diagnostic Laboratories:Blood draw and analysis facilities prioritize standardized gauge availability.
- Specialized Treatment Facilities:Pain management and infusion centers need flexible procurement for varied protocols.
Oncology Centers anchor procurement volume; Home Healthcare Providers show the steepest expansion trajectory.
Material Type:
Supply chain concentration and biocompatibility certification requirements differentiate material sourcing strategies.
- Medical Grade Stainless Steel:Nickel-chromium alloys dominate commodity manufacturing, though input cost volatility squeezes margin structures for price-competitive producers. Gamma irradiation sterilization capacity concentrates in specialized facilities, creating geographic supply bottlenecks.
- Titanium Alloy:Premium biocompatibility and reduced magnetic resonance imaging interference command positioning in high-reimbursement settings. ISO 10993 testing backlogs at notified bodies extend validation timelines for these advanced materials.
- Plastic Components:Polycarbonate and nylon elements enable cost reduction in disposable safety mechanisms.
- Silicone Coating:Surface treatment layers reduce tissue trauma during repeated port access.
- Polycarbonate:Engineering polymers provide structural integrity for safety housing components.
- Nylon:Synthetic materials feature in catheter connection interfaces and grip surfaces.
Medical Grade Stainless Steel holds volume dominance; Titanium Alloy is gaining share fastest in premium tiers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Greater Boston's concentration of oncology research centers and vascular access device innovation clusters anchors North American Huber needle procurement sophistication. The metropolitan area's integrated delivery networks establish safety compliance benchmarks that cascade through national hospital procurement channels.
United States
OSHA Bloodborne Pathogens Standard enforcement compresses replacement cycles for conventional devices across hospital systems. The FDA's 510(k) clearance pathway governs safety feature validation timelines for new product launches. Northeast and Midwest oncology centers in Cleveland, Pittsburgh, and Philadelphia lead adoption of passive safety-engineered designs ahead of federal compliance deadlines.
Germany
EU MDR Article 117 requirements extend conformity assessment timelines for CE-marked safety products entering clinical use. German notified bodies process submissions slowest among European regulators, creating competitive timing advantages for early filers. The Baden-Württemberg medical technology corridor around Stuttgart concentrates sterilization service capacity and precision stainless steel component fabrication.
Japan
PMDA regulatory harmonization with ISO standards accelerates safety device approval pathways for domestic manufacturers. METI medical device export promotion programs support penetration of Southeast Asian oncology markets. The Kansai region's Osaka-Kobe industrial zone houses specialized gamma irradiation facilities serving domestic and regional sterilization demand.
Brazil
ANVISA medical device registration requirements create compliance barriers for imported safety-engineered products. Underpenetrated port-based chemotherapy protocols in São Paulo and Rio de Janeiro cancer centers present first-mover education opportunities. The São Paulo state health procurement system favors cost-optimized conventional designs over premium safety alternatives.
India
CDSCO medical device rules under the Drugs and Cosmetics Act classify Huber needles as notified devices requiring import registration or domestic manufacturing licenses. PLI scheme incentives for medical device manufacturing attract stainless steel component fabrication investment. The Maharashtra-Gujarat pharmaceutical corridor around Mumbai and Ahmedabad concentrates oncology center infrastructure and vascular access device distribution networks.
Huber Needles Market Key Industry Players
Capital-heavy producers compete with asset-light designers across the Huber needle supply base. The market structures around three tiers: integrated safety portfolio holders, regional manufacturing specialists, and cost-optimized commodity suppliers. Strategic moves concentrate on M&A for sterilization capacity control and backward integration into medical-grade stainless steel sourcing.
Among integrated safety portfolio holders, Becton, Dickinson and Company and B. Braun Medical Inc. exemplify archetypes with differentiated geographic anchoring. Becton, Dickinson and Company occupies a position aligned with United States hospital procurement consolidation. B. Braun Medical Inc. represents European manufacturing localization strategies. Nipro Medical Corporation sits within the cost-optimized tier serving price-sensitive emerging market segments.
| Leading Market Players |
|---|
| Becton, Dickinson and Company |
| B. Braun Medical Inc. |
| Nipro Medical Corporation |
| Baxter International, Inc. |
| ICU Medical, Inc. |
| AngioDynamics, Inc. |
| Vygon SAS |
| Smiths Medical |
| EXELINT International, Co. |
| Others |
Cost & Logistics Intelligence
Family-owned mid-cap stainless steel component fabricators in Germany and Japan anchor supply discipline through multi-generational tooling investments, translating into pricing power that resists commodity erosion even as hospital procurement consolidates. Their captive relationships with gamma irradiation facilities create bilateral dependency that shields margin structures from spot-market volatility.
Pricing Analysis
Value-based pricing anchored to OSHA compliance outcomes dominates safety-engineered Huber needle procurement, with United States hospital systems paying premiums for needlestick prevention verification. Three-tier pricing structure across premium safety, standard manual-shield, and economy non-safety levels separates United States oncology centers from Latin American emerging clinics and cost-optimized home healthcare providers. Price differentiation hinges on ISO 10993 biocompatibility certification tier and bundled sterilization service inclusion. Cost compression in economy stainless steel tiers is intensifying because nickel and chromium input volatility squeezes commodity manufacturers. Home healthcare providers exhibit highest price sensitivity; integrated delivery networks in the Northeast and Midwest demonstrate lowest sensitivity due to liability framework rigor.
Supply Chain Analysis
Dual-sourcing requirements embedded in United States group purchasing organization contracts mandate multi-supplier qualification for gamma irradiation services, preventing single-facility lock-in. Geographic supply concentration centers on Germany, Japan, and the United States for precision cannula fabrication and safety mechanism assembly. Raw material dependencies draw from medical-grade stainless steel nickel-chromium alloys, polycarbonate housing polymers, and silicone surface coating formulations. Single-source sterilization capacity concentrated in specialized gamma irradiation facilities creates geographic supply bottlenecks during demand surges. Distribution runs through hospital procurement departments, group purchasing organization contracts, and specialized medical device distributors serving ambulatory infusion providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where OSHA Bloodborne Pathogens Standard enforcement creates a barrier-to-entry moat favoring players with existing safety portfolio infrastructure and clinical study capabilities.
For Market Incumbents: Cement procurement channel control through multi-year safety device contracts spanning infusion therapy portfolios before EU MDR Article 117 clinical evidence requirements activate. Deepen backward integration into medical-grade stainless steel sourcing to offset nickel and chromium volatility squeezing commodity competitors. Threat of mid-tier competitors freezing under biocompatibility certification backlogs creates timing advantages for early regulatory filers. For New Entrants and Emerging Players: Home healthcare distributors represent the most penetrable channel partner type for safety-engineered Huber needle market entry, given ambulatory infusion protocol expansion and tightening liability frameworks. White-space targets include underpenetrated Latin American oncology infrastructure in Brazil and Mexico where port-based protocols lack standardization, and patient-managed home infusion settings requiring education-heavy go-to-market approaches. Go-to-market angle should emphasize training and protocol development bundled with device supply. For Investors and Strategic Acquirers: Distressed-cycle entries favor sterilization capacity owners in the United States and Germany where gamma irradiation facility scarcity creates captive supply value. Long-term viability over the analysis window hinges on regulatory compliance infrastructure rather than unit cost positioning. Acquisition target archetype: mid-tier safety device manufacturers with FDA 510(k) clearance pathways but underutilized clinical study infrastructure. Signal to watch: OSHA enforcement penalty activation rates compressing replacement cycles faster than modeled.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR Article 117 compliance unlocks European oncology center procurement channels ahead of mid-tier competitors. |
| Hospital System Partnership | Integrated delivery network contracts bundle safety compliance verification into multi-year infusion therapy portfolios. |
| Backward Integration | In-house medical-grade stainless steel component fabrication insulates margin structures from nickel-chromium volatility. |
| Software Companion Development | RFID-enabled needle tracking converges with hospital inventory management systems to reduce expiration waste. |
| Reimbursement Strategy | OSHA compliance verification alignment with Medicare reimbursement criteria accelerates safety device replacement cycles. |
Research Approach
Multi-period observation of FDA 510(k) clearance timelines, OSHA enforcement penalty rates, and port implantation procedure volumes anchored the trend analysis, supplemented by interviews with hospital procurement managers, GPO contracts specialists, biomedical engineers, and ambulatory infusion providers. Secondary validation drew from FDA device registration databases, CMS Medicare reimbursement filings, hospital procurement contract disclosures, and ISO standard revision notices. Bottom-up demand modeling across chemotherapy, home healthcare, and parenteral nutrition applications triangulated against top-down market sizing from manufacturer revenue disclosures.
Input-output matrix framing connected raw material cost indices for nickel and chromium to finished device pricing tiers across safety-engineered and conventional product categories. Segmentation dimensions modeled included product type, application intensity, end-user facility scale, and material certification tier. CAGRs derived from procedure volume growth rates, replacement cycle compression factors, and safety mandate compliance deadlines. Industry-specific forecast inputs incorporated gamma irradiation capacity utilization rates and notified body processing backlogs for EU MDR conformity assessments.
Caveats apply where OSHA enforcement intensity, EU MDR Article 117 interpretation variance, or gamma irradiation facility capacity constraints could materially shift the outlook. Deviation in stainless steel input cost volatility or port compatibility standardization would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surgical Instruments
Neurosurgical Drills Market
Surgical Instruments
Articulating Paper Forceps Market
Surgical Instruments
Global Bone Wax Market
Surgical Instruments
Cheilectomy Market
Surgical Instruments
Global Laparoscopic Instruments Market
Surgical Instruments
Laparoscopic Gynecological Procedures Market
Surgical Instruments
Endoluminal Suturing Devices Market
Surgical Instruments
US Surgical Sutures Market
Surgical Instruments
Suture Anchor Market
Surgical Instruments
US Ophthalmic Handheld Surgical Instruments Market
Surgical Instruments
US Integrated Operating Rooms Market
Surgical Instruments
Ultrasonic Scalpel Market
Surgical Instruments
Ultrasonic Scissors Market
Surgical Instruments
Americas Suture Needles Market
Surgical Instruments
Neovaginal Surgery Market
Surgical Instruments
Tonsil and Adenoid Removal Products Market