
 Endoluminal Suturing Devices Market | 2026-2036
Endoluminal Suturing Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Endoluminal Suturing Devices Market Analysis
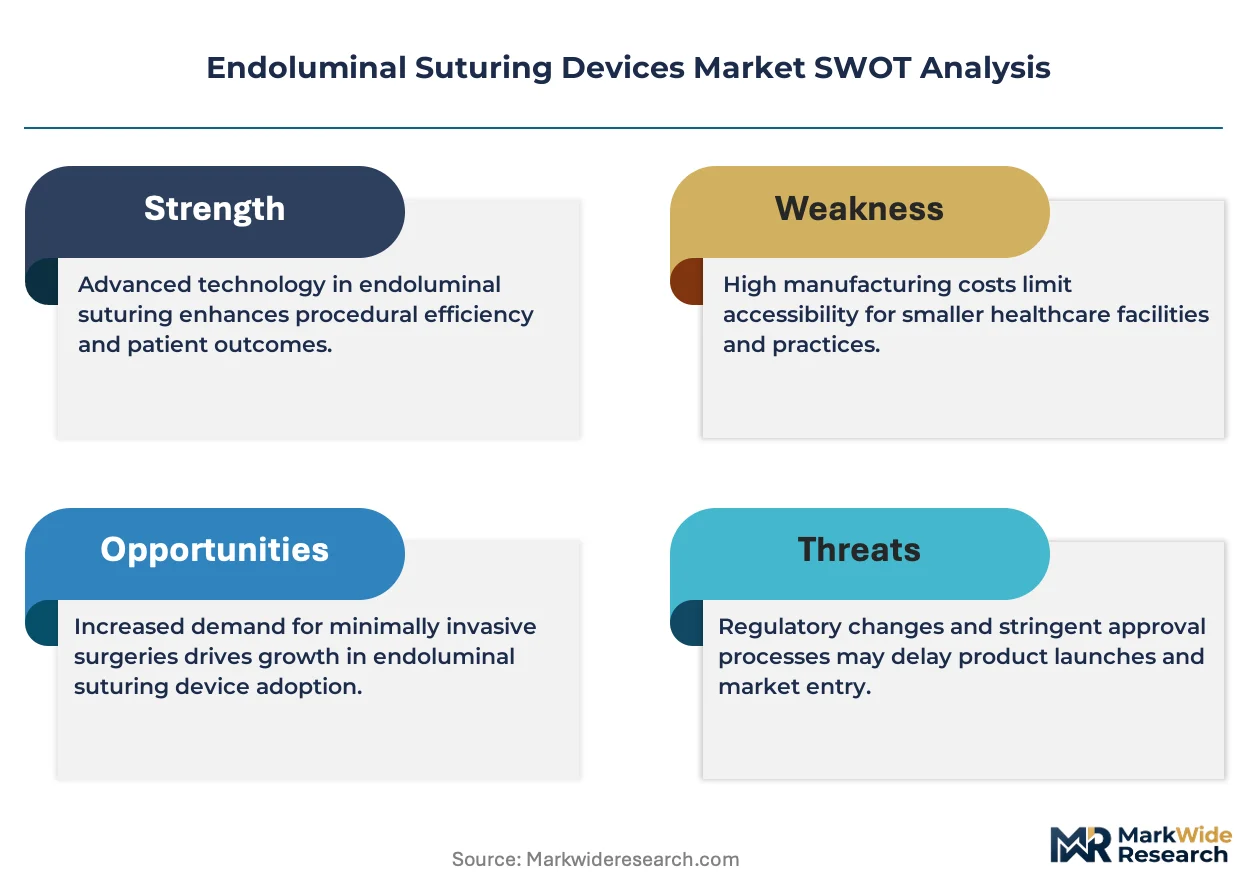
Modular platform designs that separate the suturing mechanism from the endoscope channel is hardening as the dominant procurement preference among hospital systems. Apollo Endosurgery anchors its competitive position through specialized focus on endoluminal tissue apposition systems. Medtronic Plc leverages its broad surgical portfolio to bundle suturing devices with complementary energy platforms. Johnson & Johnson competes through deep channel control across integrated delivery networks in North America.
Endoluminal suturing devices are catheter-based or overtube-delivered systems that place full-thickness sutures through flexible endoscopes, typically utilizing curved needle drivers with 2-0 to 3-0 non-absorbable or absorbable suture materials to achieve tissue approximation without external incisions. These instruments serve the primary commercial purpose of enabling incisionless revision of prior bariatric procedures and closure of gastrointestinal defects in settings where laparoscopic conversion carries elevated risk. Automated devices command premium positioning due to reduced operator-dependent variability in suture placement depth, while single-use configurations are displacing reusable alternatives in ambulatory settings where sterilization infrastructure remains limited. Gastrointestinal procedures represent the most mature application segment, whereas bariatric surgery revisions represent the fastest-growing indication as sleeve gastrectomy volumes from prior years create a downstream maintenance market.
FDA 510(k) pathways and EU MDR technical documentation requirements govern device commercialization, with both frameworks intensifying scrutiny of biocompatibility and mechanical durability testing for reusable instrument components. The EU AI Act and evolving software-as-medical-device classifications in Europe further complicate regulatory strategy for robotic-assisted suturing platforms that incorporate real-time tissue feedback algorithms. Stakeholders must monitor reimbursement determinations from CMS and parallel national bodies, as incisionless bariatric revision codes remain under active clinical evidence review and coverage expansion will determine addressable procedure volumes ahead of technology adoption curves.
Market Dynamics
Modular platform architectures that decouple the suturing mechanism from the endoscope channel are restructuring hospital procurement criteria and compressing vendor switching costs across integrated delivery networks.
Growth Catalysts
- EU MDR technical documentation pathways:Clearance frameworks for novel suturing mechanisms are accelerating device iteration cycles among European manufacturers seeking CE marking for reusable instrument components.
- Ambulatory surgery centers:Single-use configurations are displacing reusable alternatives where sterilization infrastructure remains limited, expanding addressable procedure volumes beyond traditional hospital settings.
- Sleeve gastrectomy revision demand:Prior bariatric procedure volumes from the United States, Germany, and Japan are creating a downstream maintenance market for incisionless tissue apposition.
Market Restraints
- Reimbursement uncertainty:CMS clinical evidence review of incisionless bariatric revision codes is constraining procedure volume expansion ahead of technology adoption curves.
- Biocompatibility testing burdens:FDA 510(k) submissions require intensified mechanical durability documentation for reusable needle drivers, extending development timelines.
- Robotic-assisted platform complexity:EU AI Act software-as-medical-device classifications are complicating regulatory strategy for real-time tissue feedback algorithms.
Strategic Opportunities
- Japan's PMDA accelerated review pathways:METI-supported reimbursement stabilization for endoluminal bariatric revisions is opening premium positioning for automated suturing systems.
- Gastrointestinal defect closure:Laparoscopic conversion risk in high-comorbidity patients is expanding indications beyond bariatric applications into emergency settings.
- Curved needle driver miniaturization:Convergence of 2-0 to 3-0 suture material advances with catheter-based delivery systems is enabling sub-millimeter tissue approximation precision.
Industry Challenges
- Operator-dependent variability mitigation:Training protocols for full-thickness suture placement through flexible endoscopes require specialized gastroenterology fellowship programs that remain undersupplied.
- Reusable component sterilization validation:ISO 17664 documentation for complex needle driver geometries is extending compliance timelines for manufacturers maintaining dual-use product lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Endoluminal Suturing Devices Market |
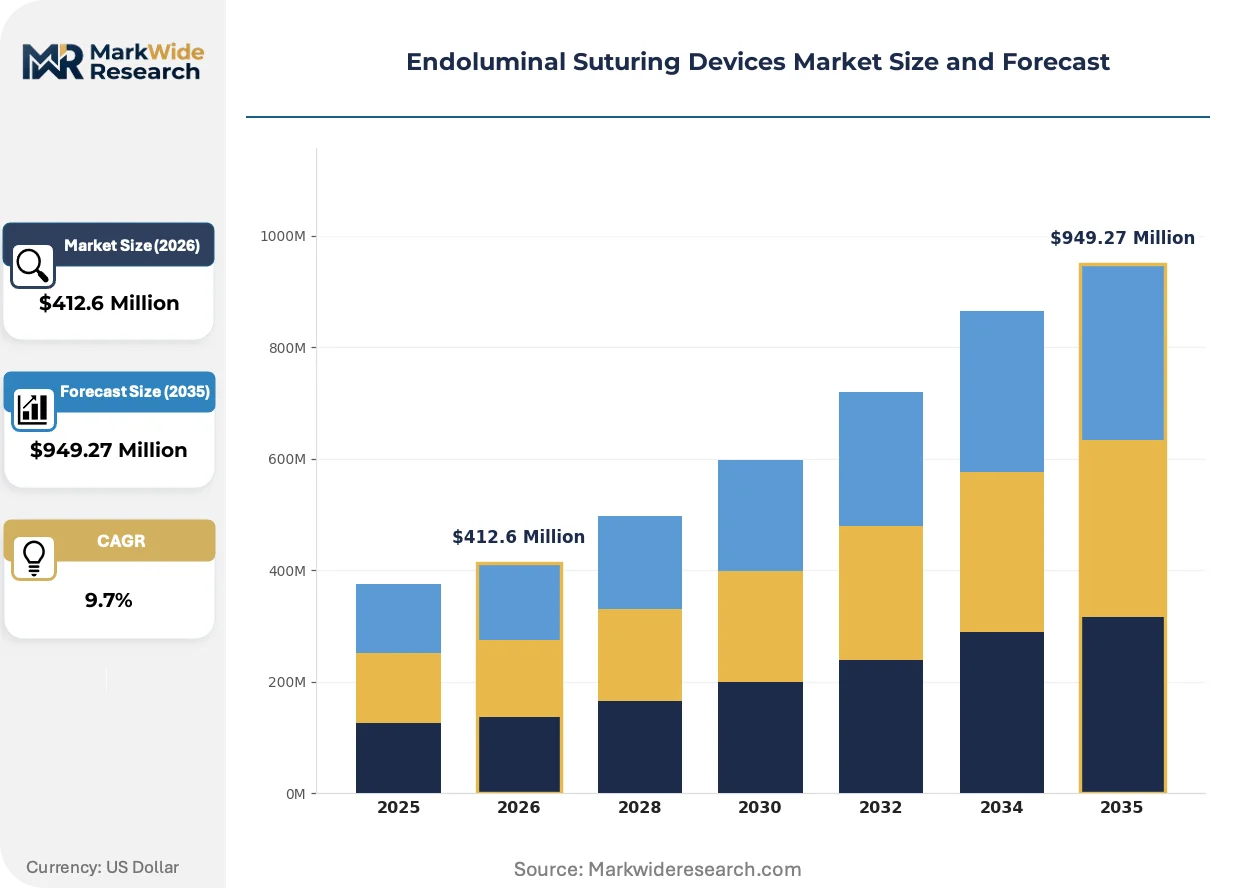
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $949.27 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Devices, Automated Devices, Single-use Devices, Reusable Devices Application: Gastrointestinal Procedures, Bariatric Surgery, Colorectal Surgery, Urological Procedures End User: Hospitals, Ambulatory Surgical Centers, Specialty Clinics, Research Institutions Technology: Endoscopic Techniques, Laparoscopic Techniques, Robotic Assistance, Traditional Suturing |
| Companies Covered | Apollo Endosurgery Inc., Johnson & Johnson, Medtronic Plc, Cook Group Incorporated, Boston Scientific Corporation, Ovesco Endoscopy AG, USGI Medical, Stryker Corporation, Endo Tools Therapeutics S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Endoluminal Suturing Devices Market Emerging Trajectories
Real-time tissue feedback algorithms and automated suture depth control are compressing the operator learning curve and reshaping competitive differentiation in catheter-based tissue apposition systems.
Robotic-assisted suturing platforms incorporating haptic feedback and machine vision guidance are absorbing the technical complexity previously requiring subspecialty endoscopic expertise. Academic medical centers in the United States are piloting these systems for complex revision procedures. The technology is absorbing training bottlenecks that have constrained procedure volume expansion in community hospital settings.
FDA 510(k) pathways are intensifying scrutiny of biocompatibility and mechanical durability testing for reusable instrument components. Submission requirements now mandate extended cyclic loading validation for curved needle drivers. Reusable platform manufacturers are responding by accelerating single-use configuration development to bypass sterilization-related regulatory friction.
Hospital systems are consolidating suturing device procurement through integrated delivery network contracts that bundle endoluminal systems with complementary energy platforms. Specialized tissue apposition vendors are losing direct channel access as purchasing decisions centralize at the IDN level. This concentration is most visible in North American markets where Medtronic and Johnson & Johnson maintain deep network control.
Endoluminal Suturing Devices Market Segmentation
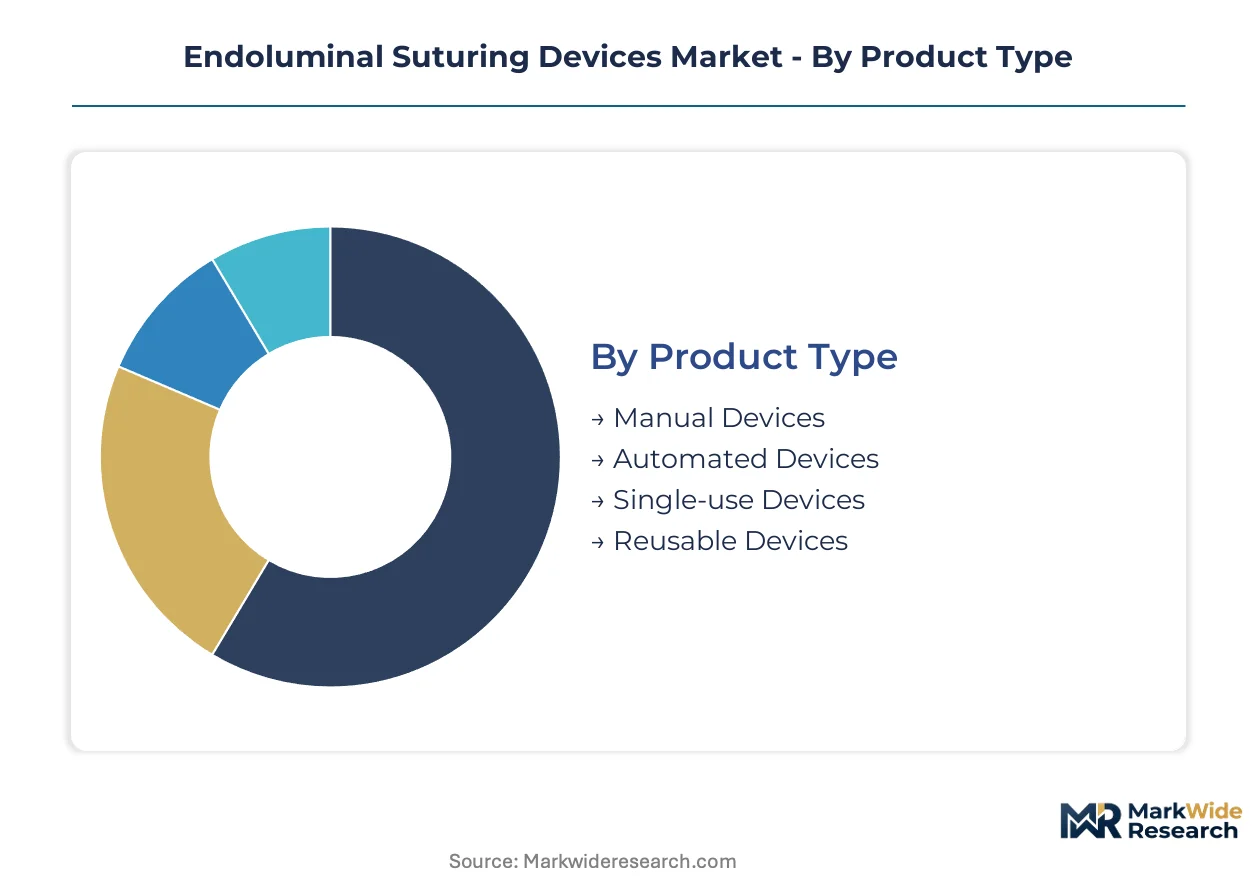
Endoluminal suturing device procurement splits across four distinct decision axes: automation level, clinical application, care setting, and technical delivery mechanism. Hospital systems weight these dimensions differently based on procedure volume, sterilization infrastructure, and subspecialty training depth.
Product Type:
Purchasing committees prioritize total cost of ownership against procedure throughput when selecting between manual and powered platforms.
- Automated Devices:Motorized needle drivers with programmable suture depth control reduce operator-dependent variability in full-thickness placement. United States academic medical centers absorb premium pricing for these systems where fellowship-trained endoscopists perform complex bariatric revisions daily.
- Single-use Devices:Pre-sterilized catheter-based systems eliminate reprocessing validation burdens. German ambulatory surgery centers favor this configuration where ISO 17664 documentation for reusable needle drivers would extend compliance timelines beyond operational capacity.
- Manual Devices:Hand-actuated suturing platforms with curved needle drivers retain installed base in cost-constrained markets.
- Reusable Devices:Durable instrument platforms requiring sterilization infrastructure concentrate in Japanese tertiary hospitals with centralized reprocessing departments.
Automated devices lead on scale; single-use configurations lead on momentum.
Application:
Procedure reimbursement stability determines addressable volume expansion across clinical specialties.
- Bariatric Surgery:Incisionless revision of prior sleeve gastrectomy procedures drives fastest volume expansion. CMS clinical evidence review of dedicated reimbursement codes constrains near-term United States penetration despite downstream maintenance demand from prior procedure volumes.
- Gastrointestinal Procedures:Full-thickness defect closure and tissue apposition represent the most mature commercial segment. Emergency settings with elevated laparoscopic conversion risk concentrate demand in United States and German hospital systems.
- Colorectal Surgery:Endoluminal suturing for rectal defect closure remains investigational outside specialized academic protocols.
- Urological Procedures:Catheter-based tissue approximation for bladder and urethral applications holds nascent positioning with limited dedicated device development.
Gastrointestinal procedures anchor current revenue; bariatric surgery climbs fastest.
End User:
Site-of-care migration patterns reshape distribution channel requirements and service support models.
- Hospitals:Integrated delivery networks consolidate procurement through bundled contracts spanning suturing devices and complementary energy platforms. North American IDNs leverage Johnson & Johnson and Medtronic channel control to centralize purchasing decisions above individual facility level.
- Ambulatory Surgical Centers:Limited sterilization infrastructure drives preference for single-use configurations. These settings expand addressable volumes for incisionless bariatric revision where overnight admission is avoidable.
- Specialty Clinics:Gastroenterology-focused practices with dedicated endoscopy suites concentrate manual device utilization for routine tissue apposition.
- Research Institutions:Academic medical centers pilot robotic-assisted platforms with real-time tissue feedback algorithms ahead of regulatory clearance for broader commercial deployment.
Hospitals dominate transaction value; ambulatory surgical centers gain share fastest.
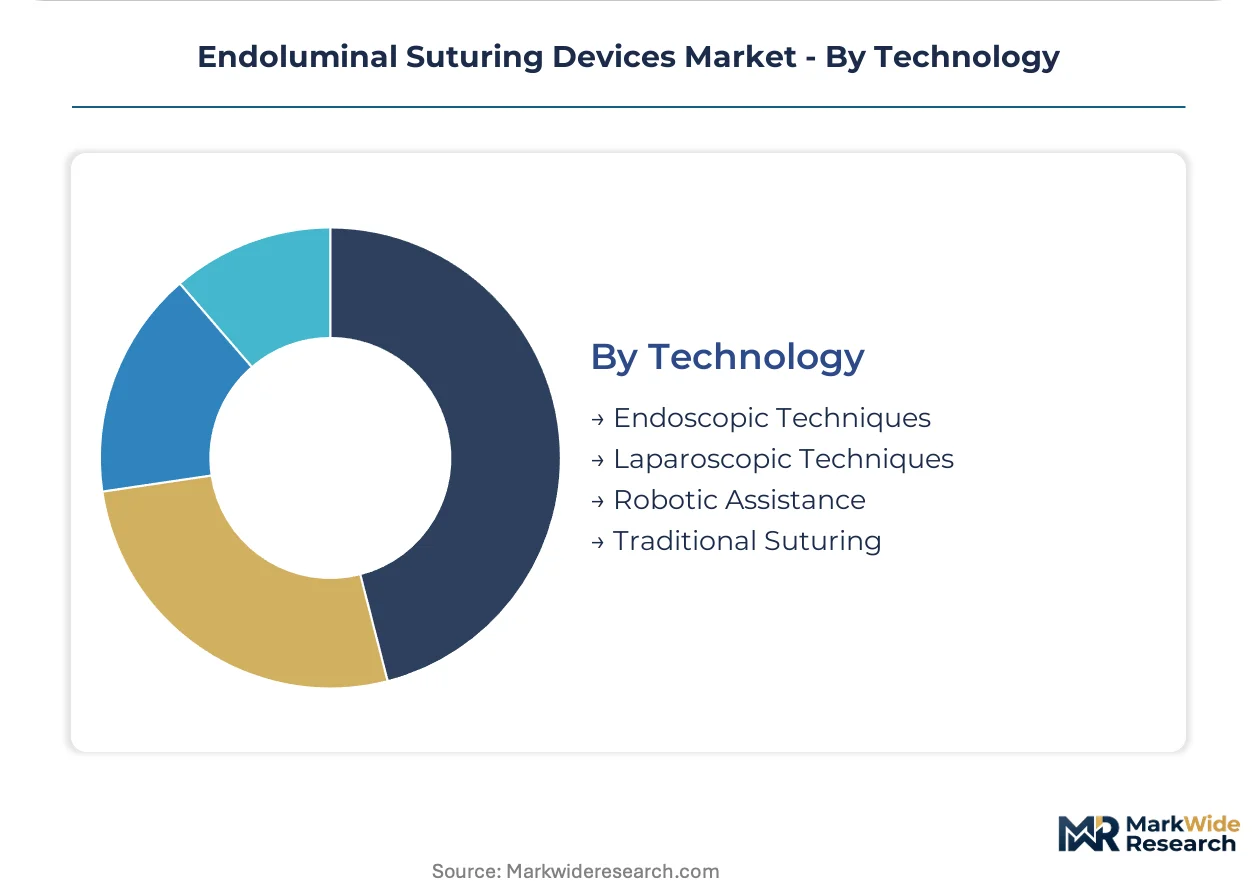
Technology:
Regulatory classification complexity varies sharply across mechanization levels.
- Robotic Assistance:Platforms incorporating haptic feedback and machine vision guidance absorb technical complexity previously requiring subspecialty fellowship training. EU AI Act software-as-medical-device classifications complicate European commercialization strategy for real-time tissue feedback algorithms.
- Endoscopic Techniques:Flexible endoscope-delivered suturing through working channels represents the dominant commercial configuration. FDA 510(k) pathways govern clearance with intensified scrutiny of biocompatibility testing for reusable instrument components.
- Laparoscopic Techniques:Hybrid approaches combining endoluminal access with laparoscopic visualization retain niche positioning for complex revision anatomy.
- Traditional Suturing:Conventional hand-sewn techniques persist in resource-constrained settings without dedicated device procurement budgets.
Endoscopic techniques hold installed base dominance; robotic assistance shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Endoluminal suturing technology first achieved commercial scale in the United States during the early 2000s bariatric surgery expansion, with subsequent regulatory clearances establishing the clinical evidence base that German and Japanese health technology assessment bodies later adopted for reimbursement determination.
United States
Academic medical centers in Boston and Houston drive procedural volume for complex sleeve gastrectomy revisions. FDA 510(k) clearance pathways govern device commercialization with intensified scrutiny of reusable instrument biocompatibility. The Cleveland Clinic and Mayo Clinic anchor multicenter clinical trials for robotic-assisted suturing platforms with real-time tissue feedback algorithms.
Germany
Ambulatory surgery centers in Bavaria and North Rhine-Westphalia favor single-use configurations where ISO 17664 documentation would burden limited sterilization infrastructure. EU MDR technical documentation requirements accelerate device iteration cycles among manufacturers seeking CE marking. The Munich medical technology cluster concentrates reusable platform development for tertiary hospital systems.
Japan
Prior sleeve gastrectomy volumes from Tokyo and Osaka metropolitan areas generate downstream maintenance demand for incisionless tissue apposition. METI-supported reimbursement stabilization through PMDA accelerated review pathways opens premium positioning for automated suturing systems. The Nagoya medical device manufacturing corridor supplies precision curved needle driver components to domestic and export markets.
United Kingdom
National Health Service integrated care boards in London and Manchester consolidate procurement decisions for endoluminal systems through bundled contracts with complementary energy platforms. NICE technology appraisals determine coverage for bariatric revision procedures in secondary care settings. The Cambridge surgical robotics cluster pilots haptic feedback platforms ahead of broader commercial deployment.
Switzerland
Tertiary hospitals in Zurich and Geneva maintain centralized reprocessing departments that sustain reusable instrument utilization despite single-use momentum elsewhere. Swissmedic clearance requirements align with EU MDR standards while offering streamlined pathways for innovative suturing mechanisms. The Basel pharmaceutical-medical device convergence zone attracts specialized tissue apposition vendors seeking European headquarters positioning.
Endoluminal Suturing Devices Market Vendor Landscape
Premium-margin players sit above commodity-margin players across automation sophistication and regulatory documentation depth, with motorized needle drivers commanding price multiples over hand-actuated alternatives. The vendor base organizes into three tiers: diversified surgical conglomerates with integrated delivery network channel control, specialized endoluminal tissue apposition vendors with focused R&D pipelines, and regional fabricators serving cost-constrained markets. Consolidation pressure intensifies as hospital procurement centralization favors bundled contracting, while technology licensing agreements accelerate access to real-time tissue feedback algorithms.
Among diversified surgical conglomerates, Johnson & Johnson and Medtronic Plc occupy positions defined by deep network control across North American integrated delivery networks. Apollo Endosurgery Inc. exemplifies the specialized tissue apposition archetype through concentrated focus on endoluminal suturing mechanisms. These three companies anchor the competitive structure that smaller regional players must navigate through differentiation on automation features or single-use configuration economics.
| Leading Market Players |
|---|
| Apollo Endosurgery Inc. |
| Johnson & Johnson |
| Medtronic Plc |
| Cook Group Incorporated |
| Boston Scientific Corporation |
| Ovesco Endoscopy AG |
| USGI Medical |
| Stryker Corporation |
| Endo Tools Therapeutics S.A. |
| Others |
Supply Flow & Price Mechanics
Single-use configuration adoption in ambulatory surgery centers simultaneously compresses per-procedure cost economics and concentrates supply relationships around sterilization-avoidant manufacturing partners. This shift rewards vendors with pre-sterilized catheter production capabilities while marginalizing reusable platform specialists dependent on hospital reprocessing infrastructure.
Pricing Analysis
Three-tier pricing structure across premium automated, standard manual, and economy reusable levels governs procurement decisions in this market. Price differentiation rests on automation sophistication and FDA 510(k) clearance tier, with premium motorized systems commanding multiples over hand-actuated alternatives. Cost compression in the standard tier is intensifying because ambulatory surgery centers negotiate volume contracts for single-use configurations. Academic medical centers show least price sensitivity for robotic-assisted platforms with real-time tissue feedback algorithms.
Supply Chain Analysis
Precision needle driver manufacturing workforce availability in Nagoya, Munich, and Minneapolis-Saint Paul anchors component supply for this market. Production draws from nitinol alloy wire, medical-grade polymer extrusions, and micro-motor assemblies. Single-source vulnerability concentrates in curved needle driver geometries requiring specialized Swiss and Japanese machining equipment. Distribution runs through integrated delivery network procurement committees that bundle suturing devices with complementary energy platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market rests on automated platform adoption absorbing training costs previously borne by hospital systems, while single-use configurations eliminate sterilization infrastructure overhead for manufacturers.
For Market Incumbents:Cement channel control through integrated delivery network contracts bundling suturing devices with complementary energy platforms. Invest in CE marking documentation ahead of EU MDR intensification for reusable instrument components. Prioritize backward integration into curved needle driver machining capacity to defend against supply disruption.
For New Entrants and Emerging Players:Direct-to-ambulatory-surgery-center digital sales channels offer lowest competitive friction against entrenched hospital procurement relationships. Target German and Japanese outpatient settings where single-use configuration demand outpaces established vendor supply. Lead with sterilization-avoidant value propositions and ISO 17664 documentation relief.
For Investors and Strategic Acquirers:Roll-up economics work for specialized tissue apposition vendors because hospital procurement centralization favors bundled contracting over point-solution independence. Five-to-ten year viability favors automated platform developers with FDA 510(k) clearances and real-time tissue feedback algorithm pipelines. Watch CMS reimbursement determinations for incisionless bariatric revision codes as volume inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical Documentation Investment | Accelerates CE marking timelines for reusable needle driver components ahead of regulatory intensification. |
| Single-Use Configuration Scale-Up | Captures ambulatory surgery center demand where ISO 17664 compliance burdens limit reusable alternatives. |
| Hospital System Partnership | Secures integrated delivery network contract positioning against Medtronic and Johnson & Johnson channel control. |
| Software Companion Development | Enables EU AI Act compliance for robotic-assisted platforms with real-time tissue feedback algorithms. |
| Reimbursement Strategy | Shapes addressable procedure volumes through CMS and PMDA coverage expansion for bariatric revisions. |
Methodological Framework
Coverage spans the United States, Germany, Japan, and Switzerland, with primary inputs from each market informing cross-border pattern identification. The study combines structured interviews with gastroenterologists, hospital purchasing committee members, biomedical engineers, and GPO contracts managers with secondary validation against FDA 510(k) filings, EU MDR technical documentation databases, CMS Medicare reimbursement schedules, and hospital procurement contract registries. Bottom-up procedure volume estimates and top-down manufacturer revenue analysis undergo triangulation to anchor market sizing.
Rate-of-change decomposition separates volume expansion from pricing dynamics across the projection horizon. The analytical framework models automation level, clinical application, care setting, and technical delivery mechanism as core segmentation dimensions, with regulatory clearance tier and reimbursement status as industry-specific forecast inputs. CAGRs derive from procedure volume trajectories weighted by device configuration mix and geographic adoption curves.
The model assumes a particular technology adoption path; alternative pathways for robotic-assisted suturing platforms would alter the outlook if real-time tissue feedback algorithms face EU AI Act classification delays. Forecasts reflect assumptions about CMS reimbursement stabilization and PMDA accelerated review pathway continuity. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surgical Instruments
India General Surgical Devices Market
Surgical Instruments
Global Surgical Scalpel Market
Surgical Instruments
Colorectal Procedure Market
Surgical Instruments
Absorbable Sutures Market
Surgical Instruments
Disposable Ophthalmic Surgical Products Market
Surgical Instruments
Breast Retractors Market
Surgical Instruments
Laparoscopic Power Morcellators Market
Surgical Instruments
Ultrasonic Surgical Cutters Market
Surgical Instruments
Global Gastroenterology Ambulatory Surgery Center Market
Surgical Instruments
Global Hernia Repair Market
Surgical Instruments
Endoscopic Closure Systems Market
Surgical Instruments
Surgical Stapling Devices Market
Surgical Instruments
Iraq Healthcare (Surgical Procedures) Market
Surgical Instruments
France General Surgical Devices Market
Surgical Instruments
Cheilectomy Market
Surgical Instruments
Global Surgical Instruments Market