
 US Surgical Sutures Market | 2026-2036
US Surgical Sutures Market Size, Share, and Industry Trends Forecast 2026-2036
US Surgical Sutures Market Insights
Specialized surgical nursing and operating room technician capacity is rotating toward outpatient settings faster than training pipelines can replenish hospital-based rosters. Ethicon leverages its integrated suture-needle combinations and broad absorbable portfolio to sustain dominance across academic medical centers. Medtronic anchors its position through vascular and cardiac surgery specialization where polydioxanone and polypropylene sutures command premium placement.
US surgical sutures are sterile, implantable threads manufactured from synthetic polymers or biological materials, typically sized USP 5-0 to 2-0 for soft tissue approximation, designed to maintain tensile strength for defined wound-healing periods before absorption or permanent retention. Absorbable polyglycolic acid and polydioxanone sutures lead hospital procurement volumes for internal closures, while non-absorbable polypropylene dominates cardiovascular and orthopedic applications where long-term mechanical support outweighs bioresorption benefits. Barbed sutures without knots are gaining fastest in laparoscopic and robotic procedures across ambulatory surgical centers, though monofilament nylon still occupies the largest margin pool in cosmetic and dermatological closures.
FDA 510(k) clearance pathways and USP monograph standards govern material biocompatibility and tensile performance claims, while OSHA bloodborne pathogen protocols shape sterile handling requirements in operating suites. The Joint Commission accreditation standards for ambulatory facilities are tightening instrument sterilization and implant traceability rules, pushing smaller ASC chains toward vendor consolidation. Stakeholders must monitor whether Medicare outpatient procedure reimbursement expansion accelerates suture format shifts toward procedure packs and disposable kits optimized for same-day discharge settings.
Market Dynamics
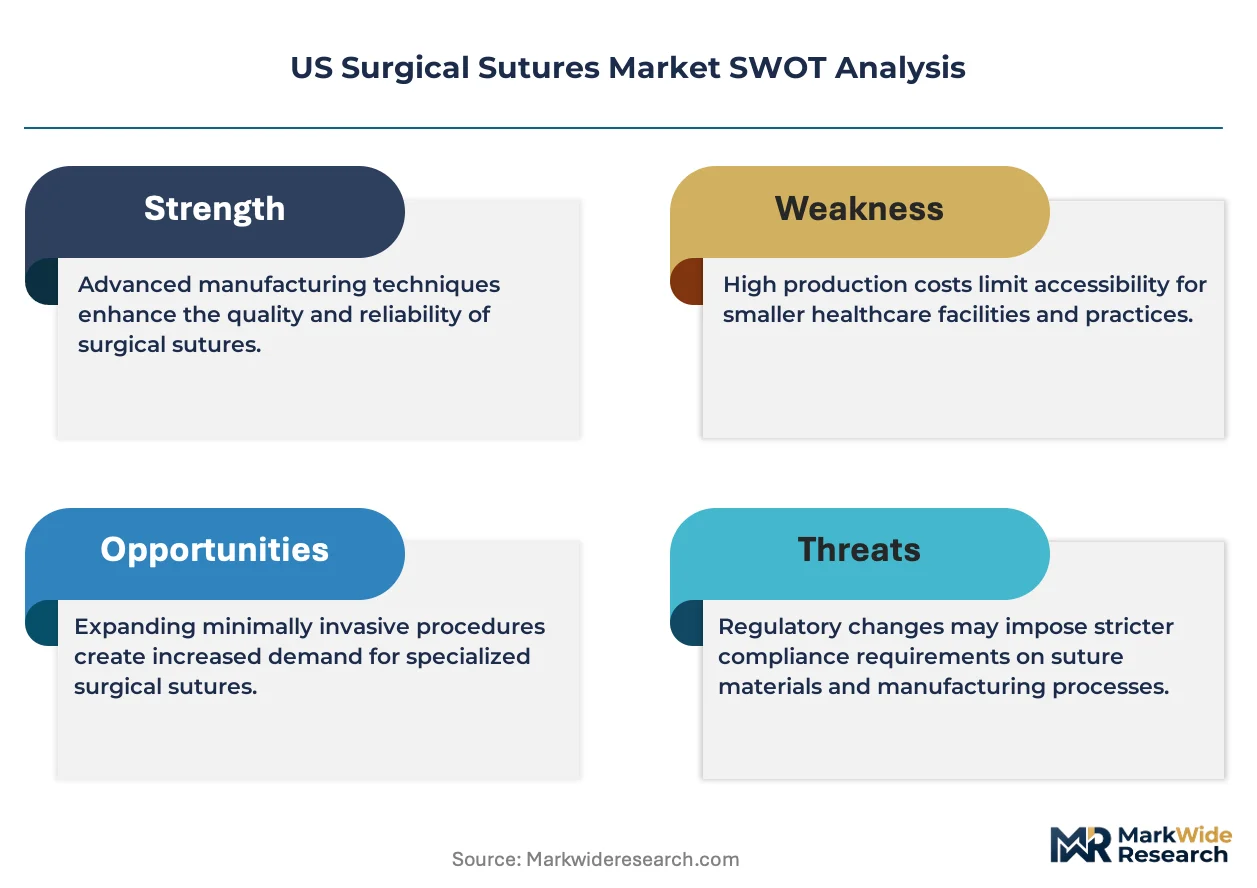
Ambulatory surgical centers are capturing procedure volume from hospital-based operating rooms, forcing suture manufacturers to redesign packaging, sterilization protocols, and training support for decentralized settings.
Growth Catalysts
- Medicare outpatient reimbursement expansion:CMS payment parity for same-day procedures accelerates ASC facility construction across Texas and Florida surgical corridors.
- Barbed suture technology:Knotless closure systems reduce operative time in laparoscopic hernia repair and robotic-assisted hysterectomy, driving replacement of conventional interrupted suturing.
- Southeast population concentration:Migration-driven surgical demand in Georgia, North Carolina, and Tennessee outpaces national hospital bed expansion rates.
Market Restraints
- Polymer feedstock volatility:Medical-grade polyglycolic acid and polydioxanone monomer supply concentrates among three European chemical suppliers, exposing margin compression risks.
- FDA 510(k) evidentiary burden:Substantial equivalence demonstrations for novel absorbable formulations extend clearance timelines by 14-22 months versus historical averages.
- Surgical adhesive substitution:Cyanoacrylate tissue sealants capture superficial closure volume in dermatology and ophthalmology outpatient settings.
Strategic Opportunities
- Procedure-specific sterile packs:Pre-configured suture-needle combinations tailored to arthroscopy and endoscopy kits reduce OR turnover time for ASC nursing staff.
- Texas ASC infrastructure buildout:Dallas-Fort Worth and Houston metropolitan surgical facility permits exceed national permit issuance rates by substantial margins.
- OSHA bloodborne pathogen compliance automation:RFID-enabled suture tray tracking systems address Joint Commission traceability mandates while reducing documentation labor.
Industry Challenges
- Perioperative nurse staffing compression:ASC hiring competition for certified surgical technologists drains hospital-based training programs, extending onboarding cycles for complex suture handling protocols.
- Legacy sterilization equipment incompatibility:Ethylene oxide alternatives for moisture-sensitive synthetic sutures require capital conversion at smaller ASC chains with constrained equipment budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Surgical Sutures Market |
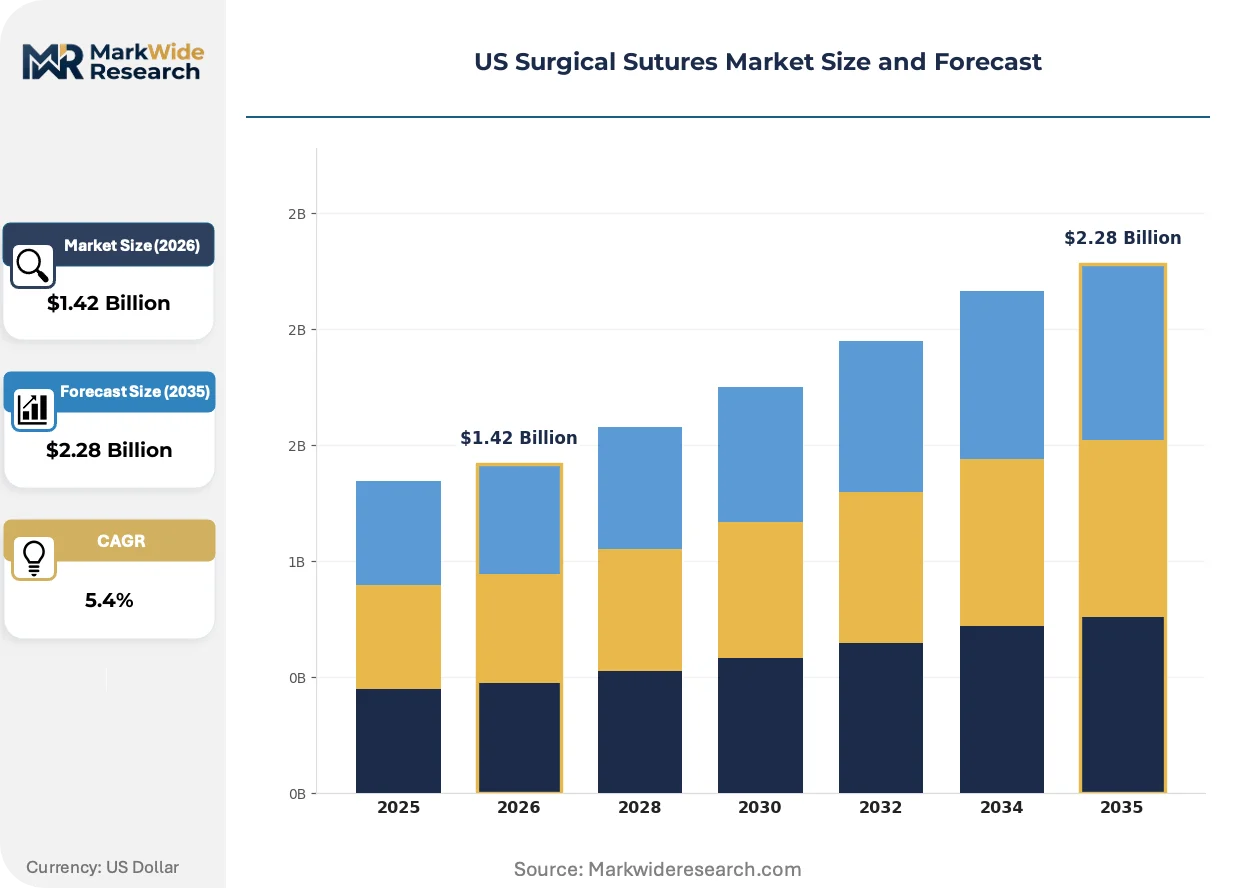
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.28 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Absorbable, Non-Absorbable, Barbed, Multifilament, Monofilament Material: Polyglycolic Acid, Nylon, Silk, Polypropylene, Polydioxanone, Polyester Application: General Surgery, Cardiovascular, Orthopedic, Gynecological, Neurosurgical End User: Hospitals, Ambulatory Surgical Centers, Specialty Clinics, Academic Medical Centers |
| Companies Covered | Ethicon (Johnson & Johnson), Medtronic, B. Braun, Smith & Nephew, Teleflex Medical, DemeTECH Corporation, Boston Scientific, Arthrex, Covidien, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Surgical Sutures Market Trends and Innovations
Suture technology is fragmenting into procedure-optimized formats while regulatory traceability requirements and site-of-care migration reshape commercialization priorities.
Barbed knotless sutures is bifurcating soft tissue closure methodology between high-speed laparoscopic applications and traditional interrupted techniques. Academic medical centers and multi-specialty ASCs in the Midwest and Southeast are adopting barbed polydioxanone for fascial closure at rates exceeding conventional braided absorbable uptake. The technology is bifurcating procurement decisions into speed-optimized premium tiers versus cost-minimized standard portfolios.
FDA 510(k) premarket notification pathways for Class II surgical sutures are tightening clinical evidence requirements for absorbable synthetic materials. Manufacturers now submit extended biocompatibility profiles and tensile strength degradation data beyond historical USP monograph baselines. Absorbable polydioxanone and polyglycolic acid formulations face the steepest documentation escalation, compressing development timelines for mid-cap competitors.
Same-day discharge protocols are consolidating purchasing authority at ASC management company headquarters, displacing hospital materials management autonomy. Large ASC chains in Florida and Arizona now negotiate master suture agreements covering 40-60 facilities, extracting volume discounts unavailable to independent surgery centers. This concentration is visible most acutely in cosmetic and orthopedic ambulatory segments where procedure standardization enables format commoditization.
US Surgical Sutures Market Segmentation
Suture procurement patterns diverge sharply across material technologies and care settings, with FDA absorption profiles and USP tensile standards governing reimbursement eligibility. Manufacturers must align formulation portfolios to the specific closure demands of cardiac, orthopedic, and minimally invasive procedures.
Product Type:
FDA 510(k) clearance pathways differentiate absorbable and non-absorbable categories through distinct biocompatibility testing protocols and degradation documentation requirements.
- Absorbable:Polyglycolic acid and polydioxanone formulations degrade through hydrolysis, eliminating removal procedures for internal closures. Hospital procurement volumes concentrate here for gastrointestinal and obstetric applications where suture retention beyond 90 days provides no therapeutic benefit.
- Non-Absorbable:Polypropylene and polyester threads maintain tensile integrity indefinitely, serving cardiovascular anastomoses and orthopedic tendon repairs where mechanical support must outlast wound remodeling. Texas and Florida cardiac surgery corridors drive premium placement for these permanent implants.
- Barbed:Knotless closure systems reduce operative time in laparoscopic hernia repair and robotic-assisted hysterectomy.
- Multifilament:Braided constructions offer superior handling and knot security for interrupted suturing techniques.
- Monofilament:Smooth surfaces minimize tissue drag and bacterial adherence in contaminated wound environments.
Established volume favors Absorbable; emerging adoption favors Barbed.
Material:
Raw material sourcing economics stratify procurement tiers, with European polymer feedstock concentration exposing margin volatility across synthetic categories.
- Polyglycolic Acid:Rapid absorption kinetics (60-90 days) suit subcutaneous closures and pediatric procedures where foreign body minimization matters. Southeast ASC networks favor this material for same-day discharge protocols requiring minimal follow-up intervention.
- Polydioxanone:Extended strength retention (180+ days) addresses fascial closures and high-tension wound planes. Academic medical centers in the Midwest specify this polymer for complex abdominal wall reconstructions where wound dehiscence carries mortality risk.
- Nylon:Permanent monofilament dominates dermatological and cosmetic closures with minimal tissue reactivity.
- Silk:Natural protein fiber retains use in ophthalmic and microsurgical applications requiring exceptional handling.
- Polypropylene:Inert monofilament anchors cardiovascular and hernia mesh fixation with lifetime durability.
- Polyester:Braided synthetic provides high tensile strength for orthopedic ligament repairs.
Procurement scale concentrates with Polyglycolic Acid; performance premiums attach to Polydioxanone.
Application:
Procedure reimbursement codes and operative site complexity determine suture specification authority, with cardiac and orthopedic segments commanding specialized handling protocols.
- General Surgery:Appendectomy, cholecystectomy, and herniorrhaphy generate the highest suture consumption volumes across US hospital systems. Standard absorbable formats dominate here, with barbed technologies gaining fastest in laparoscopic approaches.
- Cardiovascular:Coronary artery bypass grafting and valve replacement demand non-absorbable monofilament with documented long-term patency. FDA premarket notification requirements for cardiovascular indications impose the steepest clinical evidence burdens.
- Orthopedic:Ligament reconstruction and tendon repair require high-strength permanent fixation.
- Gynecological:Hysterectomy and pelvic floor procedures drive absorbable braided uptake.
- Neurosurgical:Dural closure and microvascular anastomosis demand ultra-fine caliber precision.
Volume gravity centers on General Surgery; margin expansion concentrates in Cardiovascular.
End User:
Site-of-care migration is restructuring purchasing authority, with ASC consolidation displacing hospital materials management autonomy.
- Hospitals:Traditional inpatient facilities retain complex procedure portfolios and resident training programs requiring broad suture inventories. OR technician staffing compression here extends onboarding cycles for advanced handling protocols.
- Ambulatory Surgical Centers:Same-day discharge protocols in Florida, Arizona, and Texas are consolidating procurement at corporate headquarters. Large ASC chains negotiate master agreements covering 40-60 facilities, extracting volume discounts unavailable to independent centers.
- Specialty Clinics:Dermatology and ophthalmology outpatient settings favor procedure packs and disposable kits.
- Academic Medical Centers:Teaching hospitals anchor premium suture adoption through fellowship training and research protocols.
Procurement scale favors Hospitals; growth velocity concentrates in Ambulatory Surgical Centers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Surgical suture consumption patterns diverge sharply between high-volume ambulatory corridors and academic medical centers, with Texas and Florida ASC networks driving format shifts toward disposable procedure packs while Midwest teaching hospitals anchor premium absorbable adoption.
Southeast
Georgia, North Carolina, and Tennessee absorbable suture volumes outpace national averages due to migration-driven population expansion and ASC facility construction. CMS outpatient reimbursement parity accelerates same-day discharge protocols across Florida surgical corridors. Atlanta and Charlotte metropolitan clusters concentrate barbed suture adoption for laparoscopic hernia repair networks.
Texas
Dallas-Fort Worth and Houston metropolitan surgical permits exceed national issuance rates, concentrating cardiovascular and orthopedic procedure growth. Texas Medical Center cardiac surgery volumes anchor non-absorbable polypropylene demand for permanent anastomoses. San Antonio and Austin ASC chains negotiate master procurement agreements covering 40-60 facilities.
Midwest
Academic medical centers in Illinois, Ohio, and Michigan specify extended-strength polydioxanone for complex abdominal wall reconstructions. Resident training programs require broad suture inventories spanning absorbable braided to microsurgical monofilament formats. Cleveland Clinic and Mayo Clinic procurement standards influence regional hospital purchasing committees.
West Coast
California cosmetic and dermatology clinics drive monofilament nylon consumption for superficial closures with minimal tissue reactivity. Silicon Valley robotic surgery adoption concentrates barbed suture uptake in laparoscopic prostatectomy and hysterectomy procedures. Los Angeles ASC networks favor procedure-specific sterile packs reducing OR turnover time.
Northeast
New York and Massachusetts teaching hospitals retain complex trauma and transplant portfolios requiring specialized handling protocols. Boston academic medical centers anchor premium suture adoption through fellowship training and research protocols. Philadelphia and Baltimore metropolitan areas concentrate orthopedic ligament reconstruction demand.
US Surgical Sutures Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with the upper tier commanding hospital system contracting authority and the specialist layer occupying niche procedure segments. The market structure reflects procurement consolidation at ASC management companies alongside persistent fragmentation in microsurgical and veterinary applications. Three archetypes dominate: diversified medical device conglomerates with suture-needle integration, mid-scale polymer specialists with regional ASC focus, and single-product innovators in barbed knotless formats. Competitive moves center on vendor consolidation for Joint Commission traceability compliance and backward integration into medical-grade polymer feedstock.
Within the diversified conglomerate tier, Ethicon and Medtronic exemplify integrated leaders whose hospital contracting scale displaces smaller competitors from academic medical center formularies. B. Braun occupies a position bridging premium hospital supply and mid-tier ASC procurement, representing the European-based fabrication archetype with US distribution infrastructure. DemeTECH Corporation exemplifies the domestic specialist tier, sitting within the mid-cap segment focused on cost-optimized absorbable formats for high-volume ambulatory procedures.
| Leading Market Players |
|---|
| Ethicon (Johnson & Johnson) |
| Medtronic |
| B. Braun |
| Smith & Nephew |
| Teleflex Medical |
| DemeTECH Corporation |
| Boston Scientific |
| Arthrex |
| Covidien |
| Others |
Pricing and Supply Chain Analysis
Scale economies in ethylene oxide sterilization capacity utilization concentrate pricing power among integrated manufacturers serving large ASC chains, compressing margin floors for mid-tier competitors dependent on third-party sterilization services. Hospital system contracting leverage and polymer feedstock volatility jointly shape procurement cost structures across absorbable and non-absorbable categories.
Pricing Analysis
Long-term offtake agreements dominate procurement between large ASC management companies and integrated suture-needle manufacturers, displacing spot purchasing at independent facilities. Three-tier pricing structure across premium, standard, and economy levels differentiates by FDA clearance tier and sterile packaging complexity, with barbed knotless formats commanding premium placement. Pricing pressure stems from surgical adhesive substitution in superficial closure applications, eroding nylon monofilament margins. Independent surgery centers exhibit highest price sensitivity; academic medical centers anchor premium tier demand through fellowship training protocols.
Supply Chain Analysis
Inventory lead times for medical-grade polyglycolic acid and polydioxanone monomers stretch 14-22 weeks due to European chemical supplier concentration in Germany, Belgium, and the Netherlands. Raw material sourcing draws from petroleum-derived glycolide and dioxanone monomers, plus surgical-grade stainless steel for needle fabrication. Single-source vulnerability in polymer feedstock exposes manufacturers to commodity price volatility and currency fluctuation risks. Distribution runs through GPO contracts and direct hospital system agreements, with ASC chains consolidating procurement at corporate headquarters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach opportunities in sterile procedure pack configuration and OR technician training subscriptions expand faster than standalone suture hardware sales, as ASC nursing staff compression drives demand for turnkey closure solutions.
For Market Incumbents: Secure backward integration into medical-grade polymer feedstock to insulate margins from European supplier volatility and ethylene oxide sterilization bottlenecks. Anchor hospital system contracting authority through integrated suture-needle combinations while building ASC-dedicated training infrastructure to defend against mid-tier competitors offering cost-optimized formats. For New Entrants and Emerging Players: ASC inventory management software gaps present white-space entry points where incumbents under-serve smaller independent facilities with RFID-enabled traceability compliance. Target Texas and Florida ASC networks with procedure-specific sterile packs for laparoscopic hernia repair, leveraging master procurement agreement structures to bypass hospital GPO gatekeeping. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors barbed knotless specialists with FDA 510(k) clearances in robotic-assisted applications, as procedure format shifts accelerate replacement of conventional interrupted suturing. Acquisition candidates with captive polymer supply and ASC-focused distribution infrastructure offer strongest long-term viability. Monitor Medicare outpatient reimbursement expansion rates as inflection signal for ASC facility construction velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Feedstock | Captive supply of medical-grade polyglycolic acid reduces exposure to European chemical supplier concentration. |
| ASC Training Infrastructure Buildout | OR technician certification programs address Joint Commission compliance while locking in procedure pack adoption. |
| RFID-Enabled Traceability Systems | OSHA bloodborne pathogen automation satisfies Joint Commission mandates for smaller ASC chains. |
| Barbed Suture FDA 510(k) Expansion | Extended indications in robotic-assisted hysterectomy accelerate replacement of conventional interrupted formats. |
| Master Procurement Agreement Structuring | Corporate-level contracting with 40-60 facility ASC chains extracts volume discounts unavailable to independents. |
Research Methodology
Cross-validation between primary interviews with hospital purchasing committees, GPO contracts managers, biomedical engineers, and ASC operations directors anchors the qualitative findings against secondary validation from FDA 510(k) filings, CMS Medicare reimbursement databases, hospital procurement records, and USP monograph standards. Bottom-up facility-level procedure volume estimates triangulate with top-down polymer consumption data from medical-grade chemical suppliers.
Sensitivity analysis across material technology adoption curves, ASC facility construction permits, and Medicare reimbursement policy scenarios shapes the analytical framework over the projection horizon. Segmentation dimensions modeled include absorbable versus non-absorbable categories, barbed versus conventional formats, general surgery versus cardiovascular versus orthopedic applications, and hospital versus ASC versus specialty clinic end users. CAGRs derive from procedure volume elasticity to demographic migration patterns and surgical site-of-care migration rates.
Underlying assumptions cover CMS outpatient reimbursement parity maintenance, European polymer feedstock supply continuity, and FDA 510(k) clearance timeline stability, with deviation risk concentrated in surgical adhesive substitution acceleration and ASC nurse staffing compression severity. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surgical Instruments
Laparoscopic Power Morcellators Market
Surgical Instruments
Surgical Hemostats Market
Surgical Instruments
Surgical Sphincteroplasty Market
Surgical Instruments
Heavy Power Surgical Tools Market
Surgical Instruments
Middle East and Africa Lancet and Pen Needles Market
Surgical Instruments
Cleft Lip and Palate Repair Surgical Instrument Package Market
Surgical Instruments
Germany General Surgical Devices Market
Surgical Instruments
Spain General Surgical Devices Market
Surgical Instruments
Global Microsurgery Market
Surgical Instruments
Global Pain Management and Surgical Devices Market
Surgical Instruments
Gynecology Surgical Instruments Market
Surgical Instruments
Global Bipolar Electrosurgical Devices Market
Surgical Instruments
High Flow Needle Sets Market
Surgical Instruments
United Arab Emirates General Surgical Devices Market
Surgical Instruments
Minimally Invasive Gastrointestinal Surgical System Market
Surgical Instruments
Global Hernia Repair Market