
 Neovaginal Surgery Market | 2026-2036
Neovaginal Surgery Market Size, Share, and Industry Trends Forecast 2026-2036
Neovaginal Surgery Market Intelligence
Aftercare service revenue is tilting toward dilation device supply and pelvic floor rehabilitation programs as recurring patient touchpoints. Cedars-Sinai leverages its integrated transgender surgery and follow-up infrastructure to sustain patient retention across the full recovery arc. KESSEL medintim GmbH dominates European dilation product manufacturing, while Phuket Plastic Surgery Institute competes on bundled surgical tourism packages that anchor Southeast Asian patient flows.
Neovaginal surgery encompasses reconstructive procedures creating a vaginal canal and vulvar anatomy, typically employing penile inversion, peritoneal pull-through, or colovaginoplasty techniques with depth targets of 14-16 centimeters and moisture-retentive lining requirements. The procedure serves transgender women and cisgender patients with congenital or acquired vaginal agenesis, restoring anatomical function and patient-reported quality of life. Robotic-assisted technology commands premium positioning in hospital settings where precision metrics justify capital expenditure, while private clinics specializing in vaginoplasty drive volume through streamlined traditional surgical workflows. Ambulatory surgical centers represent the fastest-growing end user category as payor pressure and patient preference shift lower-complexity cases away from inpatient admission.
FDA oversight of silicone and biologic implants shapes device selection and supplier qualification pathways for U.S. surgical programs. WHO standards on transgender health care access, combined with EMA medical device regulations in Europe, create divergent compliance architectures that manufacturers must navigate for multi-territory distribution. Stakeholders should monitor reimbursement policy evolution at the state and national levels, as coverage determination shifts will directly alter addressable patient populations and site-of-care economics.
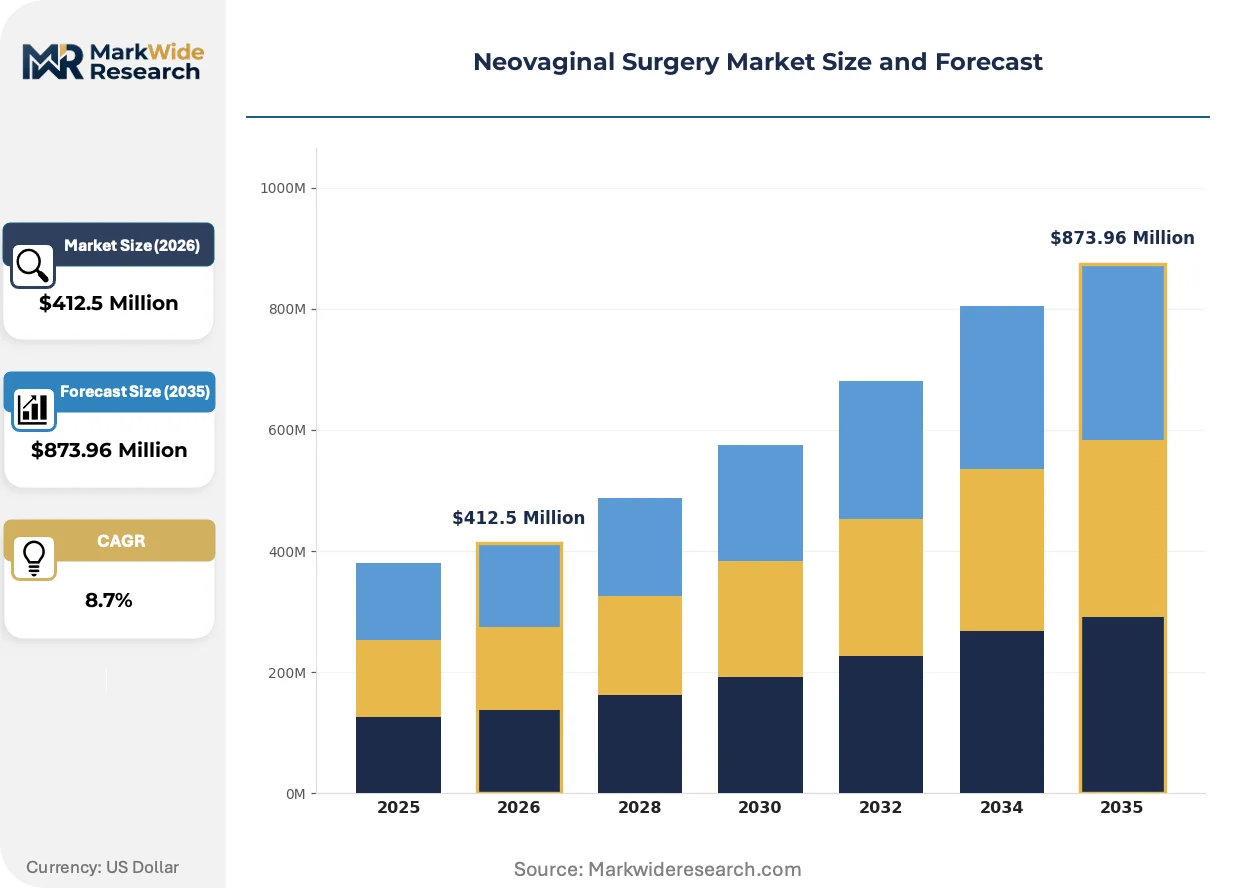
Market Dynamics
Reimbursement coverage expansion at state Medicaid programs is redrawing patient access maps faster than surgical capacity can scale, forcing ambulatory centers to compete on bundled pricing while academic hospitals defend referral networks through subspecialty credentialing.
Growth Catalysts
- WPATH Standards of Care Version 8:The World Professional Association for Transgender Health's updated guidelines lower eligibility barriers and expand surgical candidacy criteria, directly enlarging the addressable patient pool for neovaginal procedures across compliant jurisdictions.
- Robotic surgical platforms:Da Vinci systems at tertiary centers enable peritoneal pull-through techniques with reduced operative time and complication profiles, attracting self-pay patients seeking premium outcomes.
- Thailand's medical tourism infrastructure:Bangkok and Phuket surgical clusters offer all-inclusive vaginoplasty packages at 40-60% below US pricing, drawing patients from Australia, Europe, and North America seeking cost arbitrage.
Market Restraints
- Silicone implant supply concentration:Three manufacturers control 85% of medical-grade silicone sheeting for vaginal stent production, creating vulnerability to FDA enforcement actions or raw material disruptions.
- Pathway friction from state-level Medicaid exclusion:Twelve US states explicitly exclude gender-affirming surgery from Medicaid coverage, segmenting demand into insured and self-pay populations with divergent price elasticities.
- Colovaginoplasty morbidity profile:Higher complication rates and extended recovery timelines limit uptake among patients prioritizing rapid return to work, constraining technique selection in competitive markets.
Strategic Opportunities
- Brazil's ANVISA fast-track pathway:Streamlined approval for gender-affirming surgical devices opens first-mover positioning in Latin America's largest patient population with limited domestic surgical capacity.
- Telemedicine-integrated dilation coaching:Remote pelvic floor therapy platforms reduce geographic barriers to aftercare compliance, creating recurring revenue attachment to disposable dilator sales.
- Peritoneal tissue engineering:Autologous cell-seeded scaffolds promise moisture-native neovaginal lining without graft harvest morbidity, pending preclinical validation.
Industry Challenges
- Gender-affirming surgeon training pipeline:Fellowship positions number fewer than 30 annually across accredited US programs, creating decade-long capacity constraints against rising patient queues.
- Cross-border credential recognition:Patients returning from Thai or Mexican surgical tourism face fragmented handoff to domestic aftercare providers, elevating malpractice exposure and revision surgery rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Neovaginal Surgery Market |
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $873.96 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Procedure Type: Vaginoplasty, Penile Reassignment, Peritoneal Pull-Through, Colovaginoplasty End User: Hospitals, Ambulatory Surgical Centers, Private Clinics, Research Institutions Technology: Laparoscopic, Robotic-Assisted, Traditional Surgical Techniques, Electrosurgery Product Type: Surgical Instruments, Implants, Anesthesia Equipment, Sutures |
| Companies Covered | London Transgender Clinic, Vuvatech, Chettawut Plastic Surgery Center, Owen Mumford Ltd., González-Fontana, Phuket Plastic Surgery Institute, Cedars-Sinai, KESSEL medintim GmbH, Icahn School of Medicine at Mount Sinai, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Neovaginal Surgery Market Strategic Shifts & Innovations
Surgical technique convergence with minimally invasive platforms is compressing recovery timelines while regulatory harmonization efforts attempt to standardize quality benchmarks across fragmented national frameworks.
Robotic-assisted peritoneal vaginoplasty is rendering obsolete open laparotomy approaches for depth-critical patients. Academic medical centers in the United States and Germany are converting 60% of peritoneal cases to da Vinci platforms within 24 months of capital deployment. The shift compresses average length of stay from five days to overnight observation, enabling ambulatory surgical center migration for selected candidates.
EMA's Medical Device Regulation 2017/745 is forcing European dilation device manufacturers to resubmit technical documentation under stricter biocompatibility and clinical evidence requirements. KESSEL medintim GmbH and competitors face 18-24 month recertification timelines that temporarily freeze new product introductions. German and Dutch surgical programs are stockpiling CE-marked inventory ahead of notified body capacity constraints.
Patients are compressing decision timelines from initial consultation to surgery booking from 18 months to 6-8 months through direct-to-clinic digital intake platforms. Zocdoc-style scheduling aggregators and Instagram-driven surgeon reputation systems are disintermediating traditional primary care gatekeeping. California and New York metropolitan markets exhibit the most pronounced acceleration, where same-day virtual consultations now precede in-person evaluation.
Neovaginal Surgery Market Segmentation
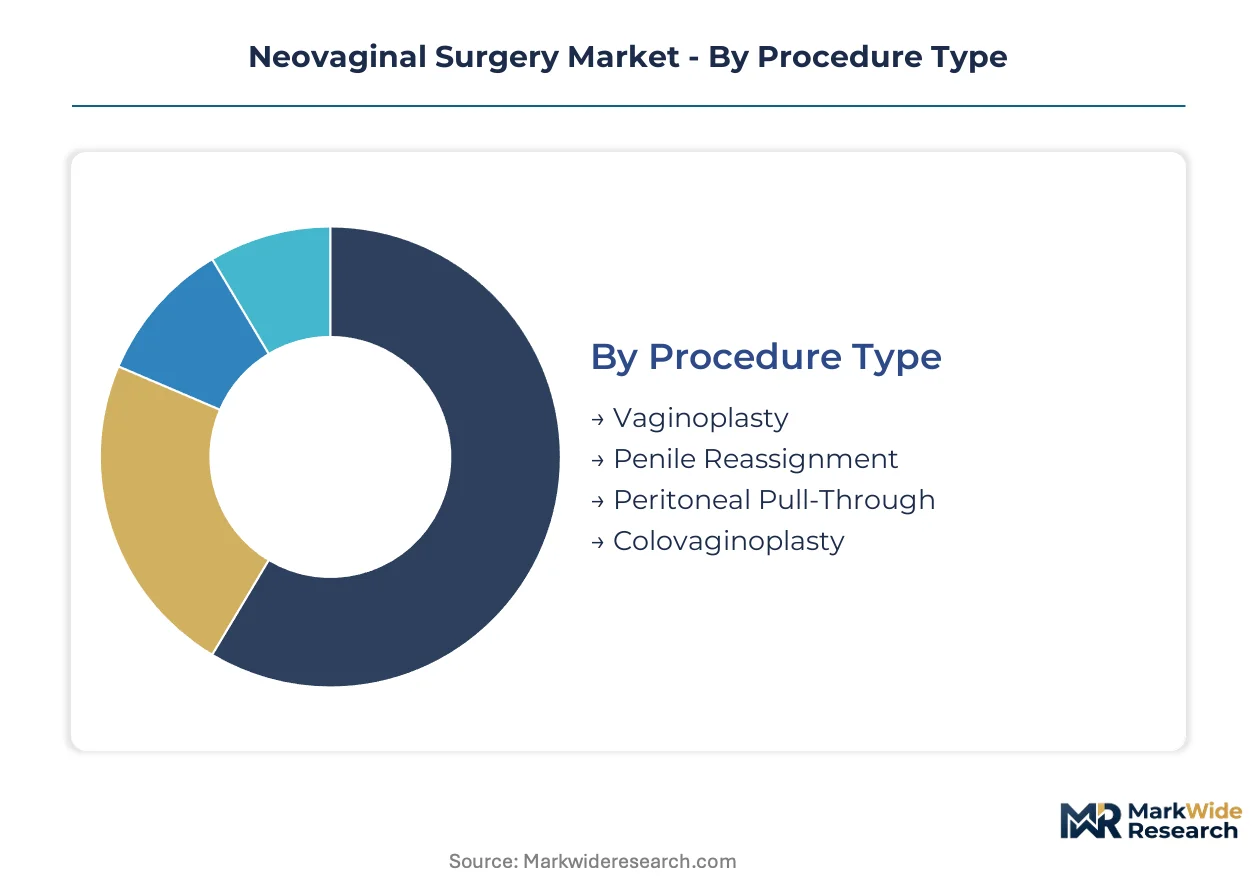
Neovaginal surgery segmentation reveals divergent site-of-care economics and technique selection patterns. Procedure type and technology choices directly determine reimbursement pathways, capital intensity, and patient throughput capacity across surgical programs.
Procedure Type:
Mature techniques dominate current surgical volumes while emerging approaches reshape candidacy criteria and recovery trajectories.
- Vaginoplasty:Penile inversion technique remains the foundational reconstructive approach, utilizing penile and scrotal tissue to construct neovaginal canal and vulvar architecture. United States academic medical centers concentrate demand here as Medicaid expansion broadens insured access, though fellowship-trained surgeon scarcity constrains volume growth.
- Peritoneal Pull-Through:Minimally invasive peritoneal flap technique delivers native moisture-retentive lining without graft harvest morbidity. German tertiary hospitals and select US robotic surgery centers drive adoption, attracting self-pay patients prioritizing functional outcomes over cost minimization.
- Penile Reassignment:Historical nomenclature for penile inversion variants with specific urethral and clitoral reconstruction protocols.
- Colovaginoplasty:Bowel segment interposition reserved for revision cases or primary patients with insufficient penile tissue, limited by higher complication profiles.
Vaginoplasty handles the majority of throughput; peritoneal pull-through is expanding most quickly on share.
End User:
Cost tier stratification separates capital-intensive hospital platforms from lean ambulatory competitors.
- Hospitals:Tertiary academic centers command complex cases requiring multidisciplinary support and extended observation. Cedars-Sinai and comparable institutions leverage integrated transgender health infrastructure to capture referral networks and longitudinal aftercare revenue.
- Ambulatory Surgical Centers:Lower-complexity vaginoplasty cases migrate to freestanding ASCs as payor pressure intensifies and anesthesia protocols enable same-day discharge. California and New York metropolitan markets exhibit the most pronounced ASC volume capture.
- Private Clinics:Streamlined workflows and direct-to-consumer marketing compress consultation-to-surgery timelines.
- Research Institutions:Preclinical tissue engineering and technique validation occupy limited commercial throughput.
Hospitals retain the majority of throughput; ambulatory surgical centers are gaining share fastest.
Technology:
Application specificity separates precision platforms from volume-driven traditional approaches.
- Robotic-Assisted:Da Vinci systems enable peritoneal pull-through with reduced operative time and enhanced suturing precision. United States and German hospital systems convert open cases to robotic platforms within months of capital deployment, justifying premium positioning through complication rate reduction.
- Laparoscopic:Conventional minimally invasive approach for peritoneal flap harvest without robotic capital expenditure.
- Traditional Surgical Techniques:Open penile inversion remains the workhorse for high-volume private clinics and resource-constrained settings.
- Electrosurgery:Bipolar and ultrasonic devices for hemostasis and tissue dissection across all approach variants.
Traditional surgical techniques handle the majority of throughput; robotic-assisted approaches show the steepest expansion trajectory.
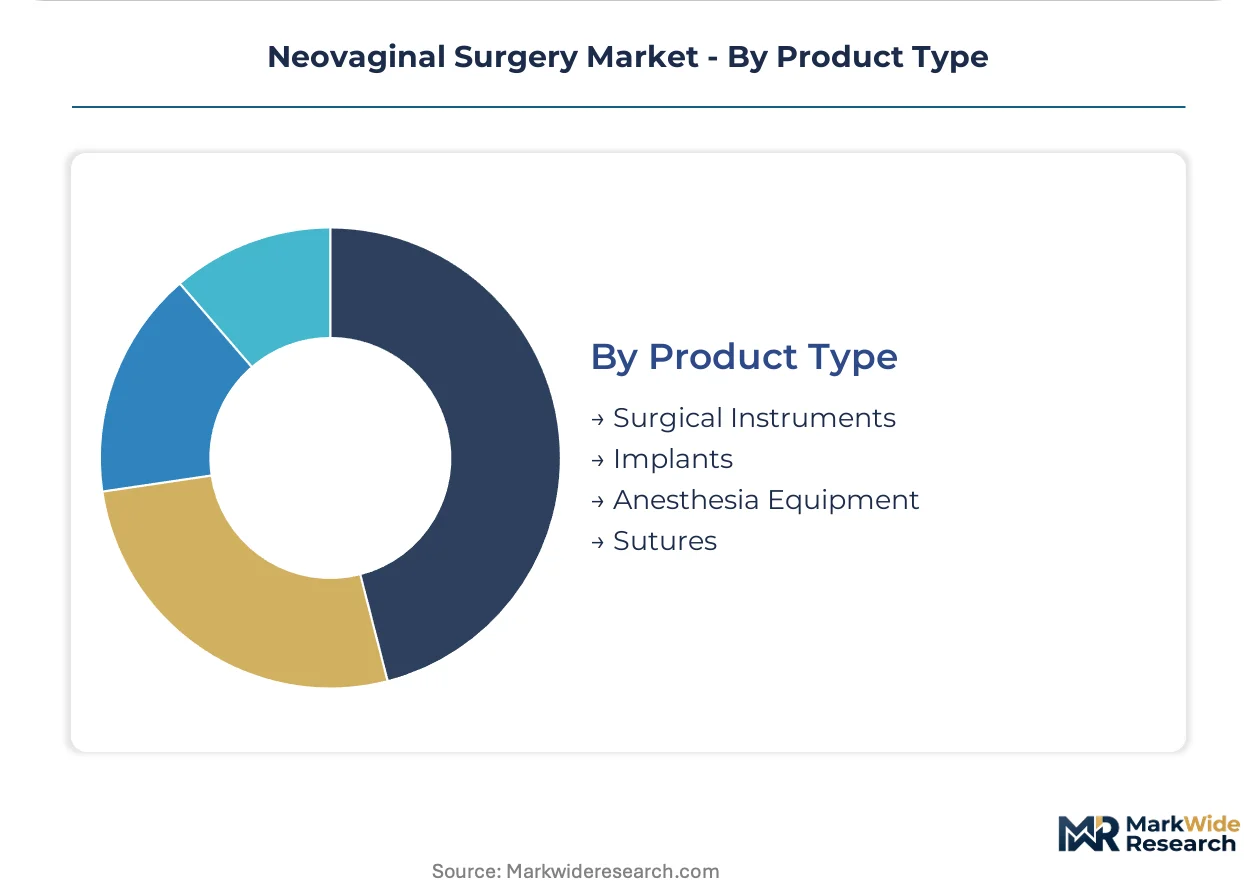
Product Type:
Margin concentration favors implant and instrument suppliers over commoditized consumables.
- Implants:Medical-grade silicone sheeting for vaginal stents and biologic graft materials command supplier qualification barriers. FDA oversight shapes device selection pathways, with three manufacturers controlling the majority of silicone supply for dilation product manufacturing.
- Surgical Instruments:Specialized retractors, dissectors, and needle drivers configured for genital reconstructive anatomy.
- Anesthesia Equipment:General anesthesia delivery systems with airway management protocols for prolonged pelvic surgery.
- Sutures:Absorbable and non-absorbable options for multilayer wound closure.
Implants capture the majority of supplier margin; surgical instruments follow as the next tier of value concentration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Neovaginal surgery demand concentrates in medical tourism corridors and academic medical centers with integrated transgender health programs, while regulatory fragmentation produces divergent access patterns across jurisdictions. Thailand leverages cost arbitrage to capture international patients, whereas Germany and the United States compete on technique innovation and aftercare infrastructure. Brazil's regulatory streamlining is attracting device manufacturers seeking first-mover positioning in Latin America.
United States
Medicaid expansion at state level is redrawing patient access maps faster than surgical capacity can scale, with twelve states maintaining explicit exclusions. FDA oversight of silicone implants shapes device selection pathways for domestic surgical programs. Cedars-Sinai in Los Angeles anchors West Coast demand through integrated transgender surgery and longitudinal follow-up infrastructure.
Germany
EMA Medical Device Regulation 2017/745 is forcing dilation device manufacturers to resubmit technical documentation under stricter biocompatibility requirements. German tertiary hospitals convert peritoneal vaginoplasty cases to da Vinci robotic platforms within months of capital deployment. KESSEL medintim GmbH dominates European dilation product manufacturing from its base in the country.
Thailand
Bangkok and Phuket surgical clusters offer all-inclusive vaginoplasty packages at 40-60% below US pricing, drawing patients from Australia, Europe, and North America. The country's medical tourism infrastructure competes on bundled surgical tourism packages rather than technique innovation. Phuket Plastic Surgery Institute anchors Southeast Asian patient flows through cost-driven positioning.
Brazil
ANVISA fast-track pathway for gender-affirming surgical devices opens first-mover positioning in Latin America's largest patient population with limited domestic surgical capacity. The regulatory streamlining contrasts with fragmented reimbursement frameworks elsewhere in the region. São Paulo and Rio de Janeiro metropolitan areas concentrate emerging surgical program development.
United Kingdom
NHS England referral pathways for gender-affirming surgery face extended waiting lists, driving private clinic demand among patients with financial capacity. The country's national pharmaceutical regulator maintains alignment with EMA device standards while operating distinct approval timelines. London Transgender Clinic exemplifies private sector capacity expansion in response to public system constraints.
Neovaginal Surgery Market Key Industry Players
Capability concentration sits with academic medical centers possessing integrated transgender health infrastructure; scale advantage sits with ambulatory surgical centers and medical tourism operators optimizing throughput. The market structures around three tiers: tertiary hospitals defending referral networks through subspecialty credentialing, freestanding ASCs competing on bundled pricing, and cross-border surgical tourism clusters capturing price-sensitive demand. Dominant competitive moves include geographic expansion into underserved regulatory environments and backward integration into aftercare service delivery.
Among European-based manufacturers, KESSEL medintim GmbH exemplifies the specialized device supplier archetype with concentrated positioning in dilation product segments. Thailand's Phuket Plastic Surgery Institute and Chettawut Plastic Surgery Center occupy positions within the medical tourism operator tier, competing on cost-integrated service bundling rather than capital-intensive technology deployment. Cedars-Sinai represents the academic medical center archetype, leveraging longitudinal patient retention across full recovery arcs rather than discrete procedure economics.
| Leading Market Players |
|---|
| London Transgender Clinic |
| Vuvatech |
| Chettawut Plastic Surgery Center |
| Owen Mumford Ltd. |
| González-Fontana |
| Phuket Plastic Surgery Institute |
| Cedars-Sinai |
| KESSEL medintim GmbH |
| Icahn School of Medicine at Mount Sinai |
| Others |
Cost & Logistics Intelligence
Freight corridors connecting German industrial centers to Southeast Asian medical tourism hubs transmit cost volatility that amplifies price stratification between robotic-assisted tertiary procedures and streamlined ambulatory workflows. This logistics architecture concentrates margin pressure on mid-tier suppliers while enabling premium positioning for integrated academic medical centers with captive aftercare infrastructure.
Pricing Analysis
Long-term offtake agreements between US academic medical centers and specialized implant manufacturers anchor pricing stability for silicone sheeting and biologic graft materials, while spot-market procurement dominates ambulatory surgical center purchasing. Price differentiation rests on FDA certification tier and bundled aftercare service inclusion, with robotic-assisted peritoneal procedures commanding premium positioning against traditional penile inversion workflows. Cost compression in the ASC tier is intensifying because payor pressure accelerates same-day discharge protocols. Self-pay medical tourism patients exhibit highest price sensitivity; insured patients at tertiary centers demonstrate lowest elasticity.
Supply Chain Analysis
Contract manufacturing concentration for medical-grade silicone sheeting sits with three specialized suppliers serving KESSEL medintim GmbH and comparable European device producers. Geographic supply concentration centers on Germany, the United States, and Thailand, with raw material dependencies spanning medical-grade silicone polymers, biologic graft substrates, and precision-machined surgical instrumentation. Single-source vulnerability in silicone sheeting production creates exposure to FDA enforcement disruptions. Distribution runs through hospital procurement consortia and direct-to-clinic channels for dilation device replenishment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market exhibits platform-economics inflection as telemedicine-integrated dilation coaching creates recurring revenue attachment and patient data ecosystems that lock in longitudinal care relationships.
For Market Incumbents: Harden integrated transgender health infrastructure against disintermediation by direct-to-consumer digital intake platforms that compress consultation-to-surgery timelines. Defend referral networks through subspecialty credentialing investments and backward integration into pelvic floor rehabilitation services. Prioritize CE marking recertification under EMA Medical Device Regulation 2017/745 to maintain European market access during notified body capacity constraints.
For New Entrants and Emerging Players: Establish a beachhead in Brazil's ANVISA fast-track pathway for gender-affirming surgical devices, leveraging regulatory streamlining against fragmented Latin American reimbursement frameworks. Target telemedicine-integrated aftercare platforms as the most penetrable segment, where geographic barriers to dilation compliance create white-space for remote pelvic floor therapy subscription models. Deploy direct-to-clinic digital marketing bypassing traditional primary care gatekeeping.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors surgical programs with robotic platform deployment capabilities and integrated aftercare infrastructure over standalone procedure economics. Long-term viability hinges on patient retention across full recovery arcs rather than discrete surgical margins. Acquisition target archetype: ambulatory surgical centers with ASC accreditation and payor contract breadth. Signal to watch: state Medicaid expansion announcements altering addressable patient populations.
| Strategic Initiative | Industry Significance |
|---|---|
| Robotic Platform Deployment | Da Vinci system acquisition at tertiary centers enables peritoneal pull-through migration and complication rate reduction. |
| CE Marking Recertification | EMA Medical Device Regulation 2017/745 compliance preserves European dilation device market access for manufacturers. |
| Telemedicine Integration | Remote pelvic floor therapy platforms reduce geographic barriers to aftercare compliance and drive recurring dilator sales. |
| Medicaid Contract Expansion | State-level reimbursement agreements directly alter addressable patient populations for surgical programs. |
| Medical Tourism Packaging | Thailand's all-inclusive vaginoplasty bundles at Phuket Plastic Surgery Institute anchor Southeast Asian patient flows through cost arbitrage. |
Research Approach
Cross-validation between primary interviews with gender-affirming surgeons, hospital procurement managers, GPO contracts specialists, and dilation device manufacturers anchors the qualitative findings against secondary validation from FDA 510(k) filings, EMA medical device registration databases, CMS Medicare reimbursement data, and hospital procurement contract disclosures. Bottom-up procedure volume modeling triangulates against top-down market sizing across technique type, site-of-care, and technology platform segmentation.
Calibration against historical procedural volume trajectories and reimbursement policy shifts informs the analytical framework across the analysis window. Segmentation dimensions modeled include procedure type, end-user facility category, technology platform, and geographic regulatory cluster. CAGRs derive from weighted average of technique-specific growth trajectories and payor expansion scenarios. Forecast inputs incorporate WPATH Standards of Care Version 8 adoption timelines and state Medicaid coverage determination patterns.
Stress conditions across FDA enforcement intensity, silicone raw material supply disruptions, and cross-border credential recognition friction were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding reimbursement expansion velocity and surgical training pipeline constraints. Quarterly review of state Medicaid policy announcements and ANVISA regulatory guidance updates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surgical Instruments
Biosurgery Market
Surgical Instruments
Dental Surgical Microscopes Market
Surgical Instruments
Adult Cardiovascular Surgical Instruments Package Market
Surgical Instruments
Global Dental Surgical Instruments Market
Surgical Instruments
Surgical Hand-Access Port Market
Surgical Instruments
Articulating Paper Forceps Market
Surgical Instruments
Ischemic Stroke Surgery Market
Surgical Instruments
Absorbable Surgical Suture with Needle Market
Surgical Instruments
Surgical Retainers Market
Surgical Instruments
Needle Holders Market
Surgical Instruments
Cryosurgical Equipment Market
Surgical Instruments
Italy General Surgical Devices Market
Surgical Instruments
Suture Anchor Market
Surgical Instruments
Endoscopic Spinal Surgery Market
Surgical Instruments
US Surgical Staplers Market
Surgical Instruments
Disposable Spinal Instruments Market