
 Suture Anchor Market | 2026-2036
Suture Anchor Market Size, Share, and Industry Trends Forecast 2026-2036
Suture Anchor Market Intelligence
Knotless and all-suture anchor specifications are unwinding older titanium and PEEK-based standards across shoulder and foot-ankle repair protocols. Smith & Nephew leverages its London-based R&D campus to sustain innovation in resorbable polymer formulations. Stryker anchors its North American position through captive distribution into integrated delivery networks. Arthrex differentiates via surgeon training academies that lock in preference for its FiberWire and SwiveLock systems.
A suture anchor is a fixation device, typically manufactured from PEEK, titanium, or biocomposite polymers, that secures soft tissue to bone through an eyelet or suture-retention mechanism using either preloaded or manually threaded high-strength suture. The device functions primarily in arthroscopic and open orthopedic procedures where tendon or ligament reattachment to cortical or cancellous bone is required. Biodegradable anchors are gaining share fastest as surgeons prioritize elimination of secondary removal surgeries, though metal anchors still dominate revision cases where pull-out strength is paramount. Minimally invasive surgery technology now drives the majority of new product registrations, while ambulatory surgical centers represent the fastest-growing end-user channel as outpatient migration accelerates.
FDA 510(k) clearances govern market entry in the United States, while the EU Medical Device Regulation and CE marking requirements have lengthened conformity assessment timelines for European launches. ISO 13485 quality management systems and ASTM material standards further constrain supplier qualification, particularly for bioresorbable formulations where degradation kinetics must be validated. Stakeholders must monitor how FDA orthopedic advisory panel deliberations and EU notified body capacity constraints reshape competitive access timelines for novel anchor geometries.
Market Dynamics
Biodegradable polymer formulations are fragmenting established titanium and PEEK anchor standards as surgeons prioritize elimination of secondary removal surgeries across ambulatory surgical centers.
Growth Catalysts
- EU Medical Device Regulation:The MDR's extended conformity timelines are filtering out marginal competitors, concentrating procurement among qualified suppliers with validated ISO 13485 systems.
- Arthroscopic technique proliferation:Sports medicine departments at tertiary hospitals are expanding shoulder repair volumes as patient expectations shift toward faster recovery protocols.
- Bioresorbable material science:Poly-lactic acid and polyglycolic acid composites with tunable degradation kinetics are displacing permanent metal constructs in European surgical practice.
Market Restraints
- Raw material concentration:Medical-grade PEEK resin supply concentrates among three European polymer compounders, exposing manufacturers to input cost volatility and allocation risk.
- Pull-out strength limitations:Biodegradable anchors still fail to match titanium mechanical performance in revision cases where cortical bone quality is compromised.
- Regulatory friction:FDA 510(k) orthopedic advisory panel deliberations have lengthened clearance timelines for novel anchor geometries, delaying commercialization by 8-14 months.
Strategic Opportunities
- Foot-ankle segment expansion:Achilles tendon repair and lateral ankle ligament reconstruction remain underpenetrated relative to shoulder applications, offering volume growth potential.
- Ambulatory surgical center channel:Outpatient migration for rotator cuff procedures creates demand for simplified instrumentation and disposable kits tailored to ASC cost structures.
- Japan's aging surgical population:PMDA streamlined review pathways for priority medical devices are accelerating market entry for knotless anchor systems in Asia-Pacific's fastest-aging orthopedic market.
Industry Challenges
- Degradation kinetics validation:Bioresorbable anchor developers must demonstrate consistent mechanical retention through 12-week bone incorporation windows, requiring extended preclinical testing protocols.
- Surgeon retraining requirements:Knotless and all-suture systems demand modified arthroscopic technique, creating adoption friction among established practitioners.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Suture Anchor Market |
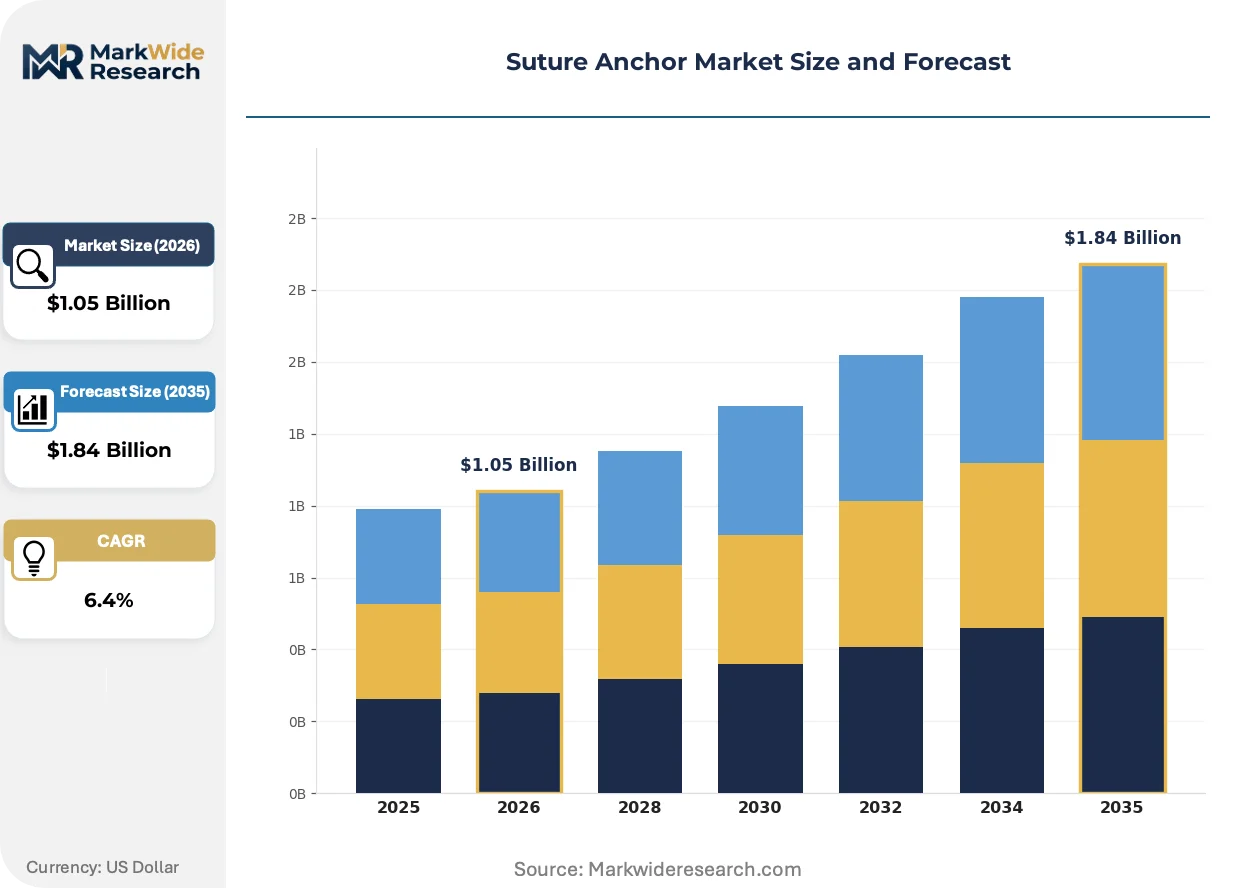
| Market Size in 2026 | $1.05 Billion |
| Market Size in 2035 | $1.84 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic Anchors, Metal Anchors, Biodegradable Anchors, Self-Drilling Anchors Application: Orthopedic Surgery, Sports Medicine, Reconstructive Surgery, General Surgery End User: Hospitals, Ambulatory Surgical Centers, Specialty Clinics, Research Institutes Technology: Open Surgery, Minimally Invasive Surgery, Arthroscopic Surgery, Hybrid Surgery |
| Companies Covered | Arthrex, Smith & Nephew, Stryker, Zimmer Biomet, Johnson & Johnson, CONMED Corporation, Enovis Corporation, Parcus Medical, DePuy Synthes, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Suture Anchor Market Strategic Shifts & Innovations
Material substitution and procedural simplification are converging to compress product lifecycles and reshape competitive differentiation in soft-tissue fixation.
All-suture anchor construction is fragmenting conventional implant architecture by eliminating rigid bodies entirely. These systems use high-strength FiberWire or equivalent braided polyethylene suture woven through bone tunnels, reducing foreign body volume by 90 percent. Ambulatory surgical centers are adopting all-suture designs fastest where inventory minimization and procedure efficiency outweigh absolute pull-out strength requirements. The technology is fragmenting traditional supplier relationships as suture manufacturers bypass conventional anchor OEMs to capture margin directly.
EU MDR Article 117 requirements for notified body involvement in Class IIa device conformity assessments have extended European launch timelines by 40-60 percent. Manufacturers now face mandatory clinical evaluation report updates and post-market surveillance system overhauls. Bioresorbable anchor portfolios are most affected, as degradation validation data must be refreshed under stricter biological safety standards, compressing competitive windows for first movers.
Integrated delivery networks are consolidating orthopedic procurement decisions at system level rather than surgeon preference. Hospital systems now mandate value analysis committees review suture anchor contracts, replacing individual surgeon brand loyalty with standardized formularies. This concentration is most visible in United States metropolitan markets where IDN penetration exceeds 70 percent, forcing manufacturers to restructure field sales organizations around system-level contracting teams.
Suture Anchor Market Segmentation
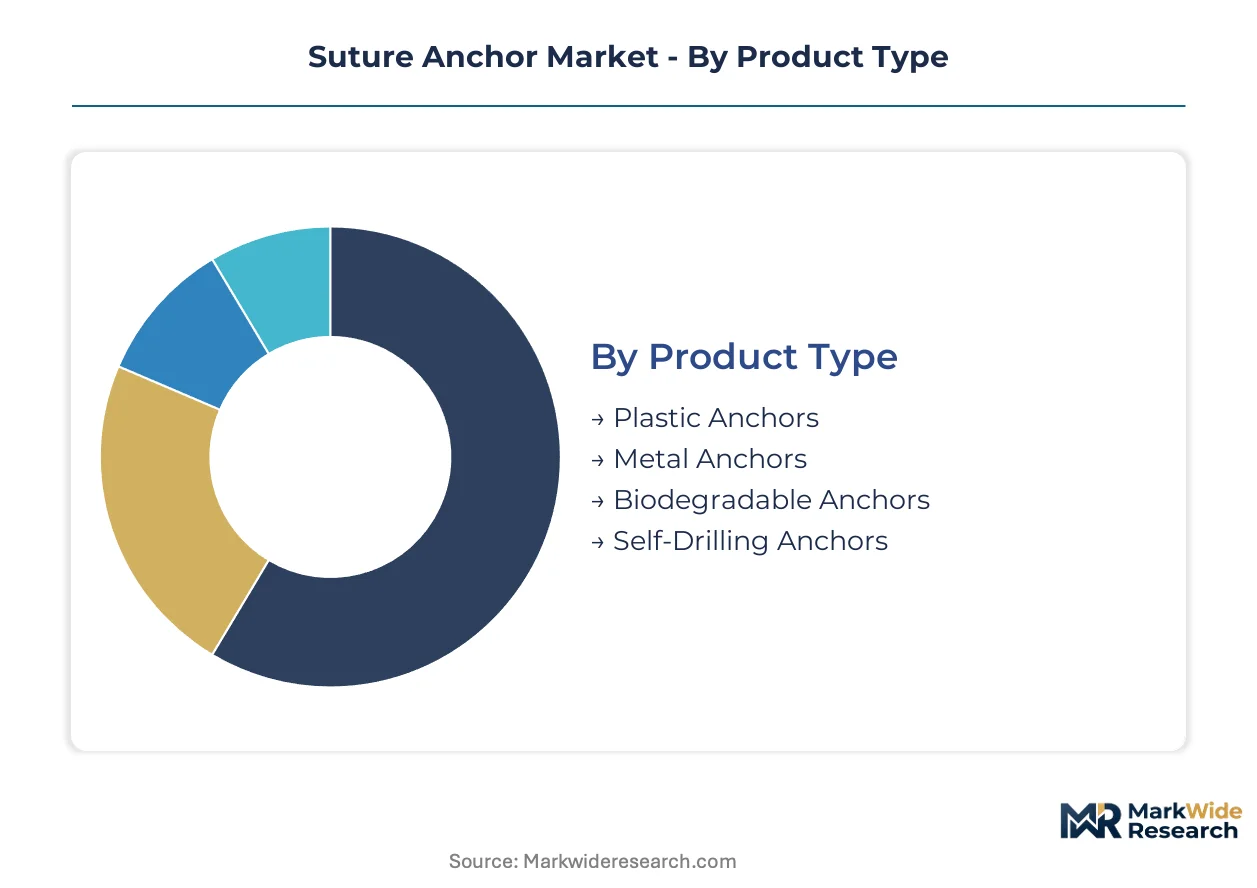
Segmentation in the suture anchor market reveals how material science, procedural setting, and surgical technique intersect to determine procurement patterns. Manufacturers must align product portfolios across four distinct category hierarchies to capture volume in shoulder reconstruction, foot-ankle repair, and emerging ambulatory settings.
Product Type:
Margin pools concentrate in biodegradable formulations where premium pricing offsets extended validation costs and regulatory documentation burdens.
- Plastic Anchors:PEEK polymer constructs deliver radiolucency and mechanical stability for permanent fixation in revision shoulder procedures. United States tertiary hospitals drive procurement volume where radiographic follow-up protocols favor metal-free imaging.
- Metal Anchors:Titanium alloys provide superior pull-out strength in compromised cortical bone and revision scenarios. European surgical practice is retreating from metal-first protocols as EU MDR biocompatibility assessments extend clearance timelines for permanent implants.
- Biodegradable Anchors:Poly-lactic acid and polyglycolic acid composites with tunable degradation kinetics eliminate secondary removal surgeries. Ambulatory surgical centers in Germany and France are adopting these fastest where procedure efficiency and inventory reduction outweigh absolute mechanical performance.
- Self-Drilling Anchors:Integrated drill-tip designs reduce operative steps and instrumentation requirements. Sports medicine departments prioritize these for time-compressed arthroscopic schedules.
The dominant share belongs to plastic anchors, while biodegradable anchors are closing the gap fastest.
Application:
Volume distribution tracks orthopedic subspecialization and the migration of soft-tissue repair into outpatient settings.
- Orthopedic Surgery:Shoulder rotator cuff repair and Achilles tendon reattachment constitute the procedural core. United States ambulatory surgical centers now handle a rising share of these cases as anesthesia protocols and implant instrumentation simplify.
- Sports Medicine:Arthroscopic Bankart repair and SLAP lesion fixation demand knotless and all-suture systems for glenohumeral access. Tertiary hospital sports medicine departments in Japan are expanding arthroscopic volumes fastest among Asia-Pacific markets.
- Reconstructive Surgery:Ligament reconstruction and tendon transfers in post-traumatic settings. European practice favors biodegradable fixation where secondary implant removal risks complicate wound healing.
- General Surgery:Limited penetration in abdominal wall and soft-tissue applications. Standardized open techniques predominate where arthroscopic instrumentation costs are prohibitive.
Orthopedic surgery commands the largest volume base, though sports medicine is expanding most quickly as patient expectations shift toward accelerated recovery.
End User:
Procurement authority is shifting from individual surgeon preference toward system-level contracting as integrated delivery networks consolidate purchasing decisions.
- Hospitals:Tertiary academic centers maintain complex revision capabilities and resident training programs. United States metropolitan markets with IDN penetration exceeding 70 percent now mandate value analysis committee review for suture anchor contracts.
- Ambulatory Surgical Centers:Fastest-growing channel for rotator cuff and simple Bankart procedures. Simplified instrumentation and disposable kit configurations dominate procurement specifications.
- Specialty Clinics:Orthopedic-focused outpatient facilities with limited operative capacity. These settings drive demand for all-suture systems where inventory minimization is paramount.
- Research Institutes:Preclinical testing and degradation kinetics validation for bioresorbable formulations. ISO 13485 quality systems and ASTM material standards constrain supplier qualification for this segment.
Hospitals retain the dominant procurement position, while ambulatory surgical centers are gaining share fastest as outpatient migration accelerates.
Technology:
Procedural modality determines implant design specifications, instrumentation requirements, and reimbursement pathways.
- Open Surgery:Traditional arthrotomy approaches for complex revision and multi-tendon reconstruction. Metal anchors predominate where visual access permits direct fixation strength assessment.
- Minimally Invasive Surgery:Percutaneous and mini-open techniques reducing soft-tissue dissection. Knotless anchor systems minimize suture management in confined operative fields.
- Arthroscopic Surgery:Fully endoscopic soft-tissue fixation through standard portals. This modality now drives the majority of new product registrations and FDA 510(k) clearance activity.
- Hybrid Surgery:Combined arthroscopic and mini-open approaches for complex pathology. Technique demands versatile anchor systems compatible with both visualization modes.
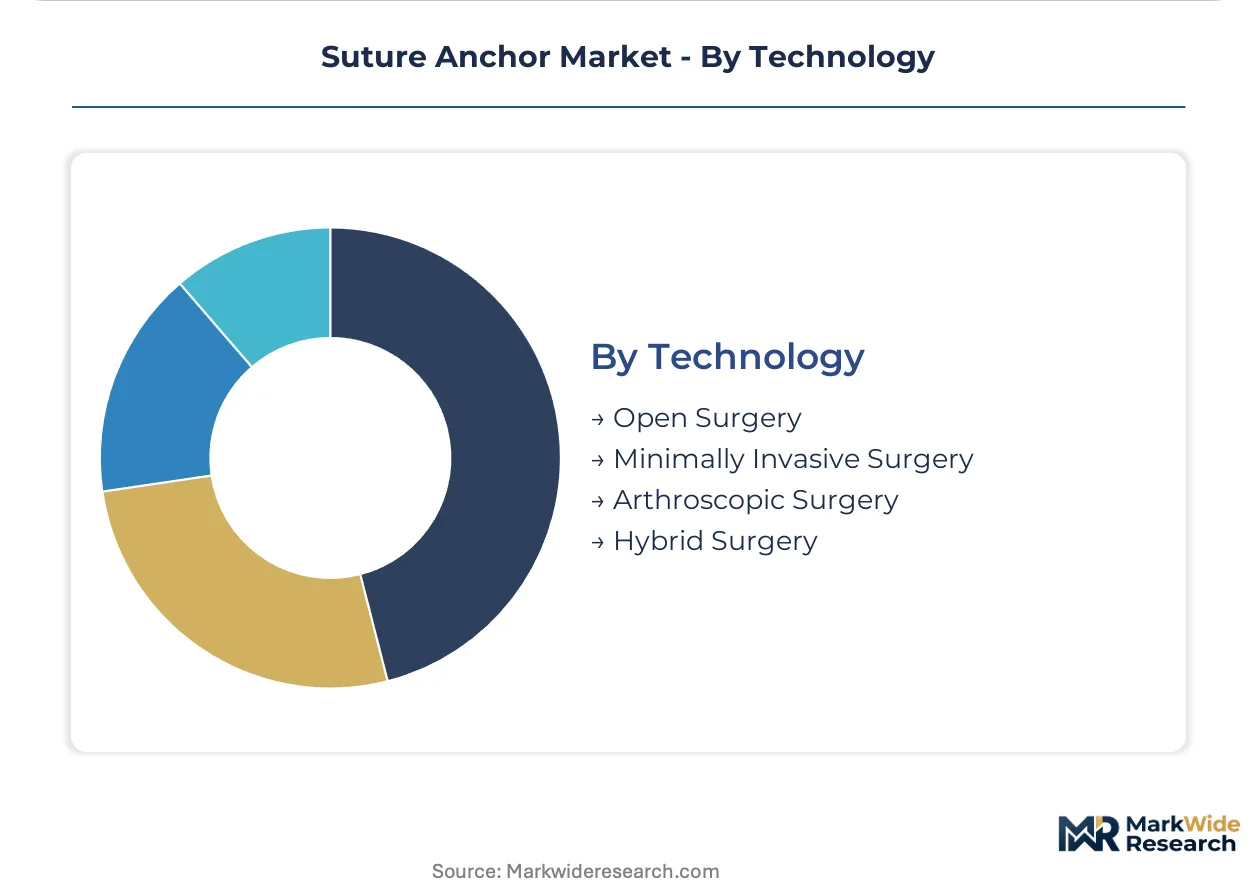
Arthroscopic surgery holds the dominant technology position, though minimally invasive approaches are climbing the fastest as instrumentation and imaging systems advance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ambulatory surgical centers in Germany exhibit the highest price elasticity for biodegradable anchors, while United States tertiary hospitals absorb premium pricing for titanium constructs in revision shoulder cases.
United States
FDA 510(k) clearance volumes for knotless anchor systems concentrate in shoulder and foot-ankle applications as ambulatory surgical centers capture rising shares of rotator cuff procedures. The FDA's orthopedic advisory panel deliberations have lengthened novel geometry approvals. Greater Boston and the Pacific Northwest host the densest clusters of sports medicine research hospitals driving arthroscopic technique adoption.
Germany
Biodegradable polymer formulations displace metal constructs fastest in German surgical practice as procedure efficiency and inventory reduction priorities dominate ASC procurement. EU MDR Article 117 conformity assessments filter marginal competitors from the market. The Rhine-Ruhr and Bavarian medical technology corridors concentrate resorbable anchor manufacturing and notified body consulting capacity.
Japan
PMDA streamlined review pathways for priority medical devices accelerate knotless system market entry in Asia-Pacific's fastest-aging orthopedic market. METI industrial policy supports domestic bioresorbable material development. The Kanto region around Tokyo anchors sports medicine department expansion at tertiary hospitals adopting faster recovery protocols.
France
ANSM oversight of biocompatibility assessments shapes resorbable anchor validation requirements as French ASCs migrate rotator cuff procedures outpatient. EU MDR clinical evaluation report mandates compress competitive windows for first movers. The Paris-Saclay cluster concentrates orthopedic research institutes validating degradation kinetics for poly-lactic acid composites.
United Kingdom
MHRA post-Brexit regulatory autonomy maintains CE marking recognition while streamlining domestic device approvals for biodegradable fixation. NHS procurement consolidation at integrated care system level replaces surgeon brand loyalty with standardized formularies. The Oxford-Cambridge arc hosts preclinical testing facilities serving European anchor developers.
Suture Anchor Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes, with resorbable polymer specialists commanding premium pricing against metal-anchor manufacturers defending share through pull-out strength performance. The market structure consolidates around three tiers: integrated orthopedic conglomerates with captive distribution, mid-scale device specialists with surgeon training lock-in, and regional fabricators supplying private-label ASC contracts. Dominant competitive moves include backward integration into medical-grade polymer compounding and strategic partnerships with ambulatory surgical center chains for exclusive kit configurations.
Among the integrated orthopedic conglomerates, Arthrex, Smith & Nephew, and Stryker occupy positions representing distinct strategic archetypes. Arthrex exemplifies the surgeon-education-driven differentiation model. Smith & Nephew represents European-based resorbable formulation leadership. Stryker anchors North American market presence through integrated delivery network penetration. These three entities collectively illustrate how technology specialization, geographic anchoring, and channel control define competitive positioning in soft-tissue fixation.
| Leading Market Players |
|---|
| Arthrex |
| Smith & Nephew |
| Stryker |
| Zimmer Biomet |
| Johnson & Johnson |
| CONMED Corporation |
| Enovis Corporation |
| Parcus Medical |
| DePuy Synthes |
| Others |
Cost & Logistics Intelligence
Medical-grade PEEK resin capacity utilization among three European polymer compounders creates scale-driven price floors that anchor biodegradable anchor premiums against metal alternatives. This concentration simultaneously limits supply-side flexibility and reinforces tiered pricing stratification across ambulatory surgical centers and tertiary hospital procurement channels.
Pricing Analysis
FDA 510(k) clearance tiers dictate the pricing tier structure across knotless and all-suture anchor portfolios, separating premium bioresorbable formulations from standard PEEK constructs and economy metal alternatives. Price differentiation rests on ISO 13485 certification status and validated degradation kinetics data packages. Cost compression in economy metal anchors is intensifying because raw material allocation risk from European polymer compounders squeezes mid-tier manufacturers. Ambulatory surgical centers exhibit highest price sensitivity, while United States tertiary hospitals absorb premium pricing for titanium constructs in revision shoulder cases.
Supply Chain Analysis
Strait of Hormuz transit vulnerability exposes medical-grade polymer feedstock flows from Middle Eastern petrochemical sources to European compounding facilities. Manufacturing concentrates in Germany, Switzerland, and the United States for PEEK resin processing and final anchor fabrication. Raw material dependencies include poly-lactic acid precursors, titanium alloy bar stock, and high-molecular-weight polyethylene suture fibers. Single-source vulnerability in European notified body capacity for EU MDR conformity assessments constrains new product introduction timelines. Distribution runs through integrated delivery network central procurement offices and ambulatory surgical center group purchasing organizations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Suture anchor procurement is shifting toward platform-based standardization as integrated delivery networks consolidate formulary decisions around interoperable instrumentation systems rather than individual surgeon preference.
For Market Incumbents: Fortify biodegradable polymer supply chains through backward integration into medical-grade resin compounding or exclusive offtake agreements with European suppliers. Lock in ambulatory surgical center channel control via disposable kit configurations that embed proprietary instrumentation. All-suture anchor entrants threaten margin pools by bypassing conventional OEM relationships. For New Entrants and Emerging Players: Differentiate on degradation kinetics validation services bundled with bioresorbable anchor supply, targeting German and French ASCs migrating rotator cuff procedures outpatient. Foot-ankle applications remain underpenetrated relative to shoulder repair, offering volume growth potential without direct confrontation with entrenched sports medicine incumbents. Direct contracting with ASC chains for exclusive kit configurations bypasses IDN value analysis committee gatekeeping. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors resorbable polymer specialists with validated ISO 13485 systems and EU MDR Article 117 clearance experience over metal-anchor manufacturers defending share through pull-out strength performance. Acquisition targets should demonstrate notified body relationships that compress European launch timelines. The signal to watch is FDA orthopedic advisory panel staffing levels and 510(k) clearance velocity for novel anchor geometries.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Article 117 Compliance Investment | Notified body capacity constraints filter marginal competitors from European market access. |
| Bioresorbable Polymer Backward Integration | Captive supply of medical-grade PLA/PGA resin reduces exposure to European compounder allocation risk. |
| Ambulatory Surgical Center Kit Partnership | Exclusive disposable configurations lock in procurement decisions at IDN value analysis committee level. |
| Surgeon Training Academy Expansion | Technique lock-in for knotless systems creates switching costs against all-suture anchor alternatives. |
| PMDA Priority Review Pathway Utilization | Streamlined Japanese regulatory access captures Asia-Pacific's fastest-aging orthopedic surgical population. |
Research Approach
Desk research of FDA 510(k) clearance databases, EU MDR notified body technical documentation, and hospital procurement contract filings preceded structured interviews with orthopedic surgeons, biomedical engineers, GPO contracts managers, and ambulatory surgical center operations directors. Secondary validation drew from ASTM material standards publications, ISO 13485 audit records, and orthopedic device trade association shipment data. Bottom-up procedure volume estimates triangulated against top-down manufacturer revenue allocations across material and technology segments.
Variance decomposition across product type, application, end user, and technology dimensions anchored the analytical framework over the projection horizon. CAGRs derived from segmented procedure volume growth rates applied to implant intensity per procedure, cross-referenced against material substitution curves for bioresorbable penetration. Industry-specific inputs included EU MDR Article 117 implementation timelines and PMDA priority review pathway approval velocities.
Forecasts assume regulatory continuity in FDA 510(k) orthopedic advisory panel operations and EU MDR notified body capacity; material policy shifts would require re-modeling. Practitioners should keep alternative scenarios live as bioresorbable degradation validation standards and ASC reimbursement pathways evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surgical Instruments
Minimally Invasive Surgical Instruments Market
Surgical Instruments
Global Surgical Scalpel Market
Surgical Instruments
Surgical Lamps Market
Surgical Instruments
Surgical Tubing Market
Surgical Instruments
Americas Suture Needles Market
Surgical Instruments
Italy General Surgical Devices Market
Surgical Instruments
Global Plastic Surgery Instruments Market
Surgical Instruments
Retractable Needles Market
Surgical Instruments
Neovaginal Surgery Market
Surgical Instruments
Surgical Hemostats Market
Surgical Instruments
Ultrasonic Scalpel Market
Surgical Instruments
Global Gastroenterology Ambulatory Surgery Center Market
Surgical Instruments
Surgical Hand-Access Port Market
Surgical Instruments
Europe General Surgical Devices Market
Surgical Instruments
High Flow Needle Sets Market
Surgical Instruments
Colorectal Procedure Market