
 Global Bone Wax Market | 2026-2036
Global Bone Wax Market Size, Share, and Industry Trends Forecast 2026-2036
Global Bone Wax Market Foresight
CE marking under the EU Medical Device Regulation is reorganizing competitive access across Europe, forcing smaller suppliers to rebuild technical files or exit. Medtronic plc leverages its broad surgical portfolio to sustain hospital contracting leverage, while Zimmer Biomet Holdings Inc. anchors its position through deep orthopedic channel relationships. Baxter International Inc. differentiates via integrated blood management platforms that bundle hemostasis with bone wax applications.
Bone wax comprises a blend of beeswax, paraffin, and softening agents designed to achieve mechanical hemostasis by occluding bone canals and venous sinusoids during procedures where electrocautery proves ineffective. Standard bone wax retains dominant volume due to low unit cost and surgeon familiarity, yet resorbable bone wax captures accelerating interest as facilities seek to eliminate foreign-body retention and associated inflammatory complications. Synthetic bone wax occupies a narrowing mid-tier as polymer-based alternatives demonstrate superior absorption kinetics in spinal fusion sites.
The FDA enforces biocompatibility testing under ISO 10993 for hemostatic devices, while the EU MDR mandates clinical evidence for resorbable classifications that grandfathered products must now generate. Japan's PMDA imposes additional local stability studies that extend registration timelines for imported formulations. Stakeholders must monitor how notified body capacity constraints in Europe reshape launch sequencing and whether US hospital value-analysis committees begin penalizing non-resorbable options in bundled payment structures.
Market Dynamics
Resorbable polymer formulations are restructuring procurement criteria across hospital systems, as value-analysis committees elevate absorption kinetics and inflammatory response profiles above unit cost in vendor selection matrices. This shift compresses margins for legacy beeswax-paraffin suppliers while rewarding manufacturers with clinical evidence packages.
Growth Catalysts
- EU Medical Device Regulation:MDR clinical evidence mandates for resorbable classifications are accelerating hospital adoption of documented formulations over grandfathered products lacking absorption data.
- Spinal fusion caseloads:Complex deformity corrections and revision surgeries in tertiary centers are expanding mechanical hemostasis requirements beyond electrocautery limitations.
- Beeswax supply concentration:Apiculture volatility in Eastern European and South American sourcing regions is prompting formulation diversification toward synthetic polymer backbones.
Market Restraints
- Paraffin cost volatility:Petrochemical feedstock fluctuations directly impact standard bone wax manufacturing economics, compressing margin buffers for price-sensitive hospital contracts.
- Notified body capacity constraints:European certification bottlenecks are extending EU MDR technical file review timelines by 12-18 months for resorbable submissions.
- Topical hemostatic sprays:Fibrin sealant and thrombin-based alternatives are capturing select cranial and soft-tissue applications previously served by bone wax.
Strategic Opportunities
- Brazil's ANVISA pathway:Streamlined registration for Class II hemostatic devices is opening private hospital procurement channels ahead of full MDR compliance in Europe.
- Bioresorbable polymer convergence:Integration of polycaprolactone and polylactic acid platforms from orthopedic implant supply chains is enabling next-generation absorption profiles.
- Direct-to-hospital distribution:Bypassing traditional surgical distributor markups through GPO-integrated digital procurement platforms is capturing 8-12 point margin recovery.
Industry Challenges
- Biocompatibility testing backlog:ISO 10993 cytotoxicity and sensitization study capacity at contract research organizations is creating 6-9 month delays for new formulation launches.
- Surgeon retraining requirements:Resorbable application techniques differ substantially from traditional bone wax handling, necessitating hands-on proctoring programs that strain medical education resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Bone Wax Market |
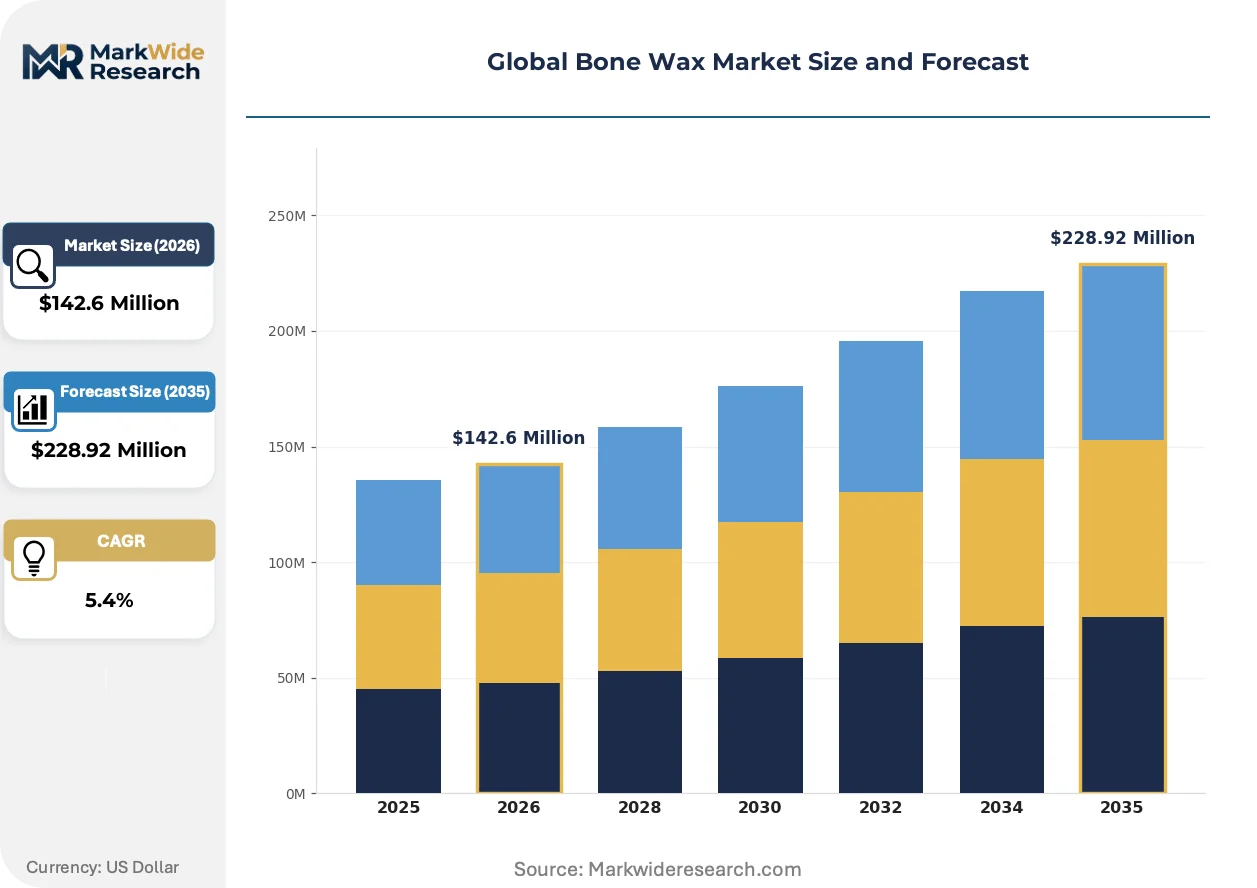
| Market Size in 2026 | $142.6 Million |
| Market Size in 2035 | $228.92 Million |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Bone Wax, Synthetic Bone Wax, Resorbable Bone Wax, Polymer-Based Bone Wax Application: Neurosurgery, Orthopedic Surgery, Cardiothoracic Surgery, Dental Surgery, Spinal Procedures End User: Surgical Centers, Specialty Clinics, Hospitals, Ambulatory Surgical Facilities Form: Stick, Paste, Powder, Sheet |
| Companies Covered | Medtronic plc, Zimmer Biomet Holdings Inc., Baxter International Inc., Abyrx Inc., Stryker Corporation, Johnson & Johnson, Medline Industries Inc., Teleflex Incorporated, B. Braun Melsungen AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Bone Wax Market Shifts & Advancements
Formulation chemistry and regulatory evidence standards are converging to redefine competitive advantage, with absorption kinetics and inflammatory markers displacing unit cost as primary purchasing criteria. Hospital value-analysis committees now demand longitudinal clinical data that legacy suppliers struggle to generate retroactively.
Polycaprolactone-based synthetic bone wax is displacing beeswax-paraffin formulations in spinal fusion applications where complete resorption within 90 days eliminates foreign-body granuloma risk. Academic medical centers in Germany and Japan are piloting these polymers in complex deformity cases, compressing addressable volume for non-resorbable alternatives despite their 40-60% price premium.
CE marking under the EU Medical Device Regulation is elevating technical documentation burdens for hemostatic agents, forcing grandfathered products to generate clinical evidence or exit European markets. Manufacturers with pre-MDR resorbable portfolios are consolidating hospital contracting leverage, while smaller suppliers redirect resources toward notified body relationship-building or geographic market prioritization.
Hospital procurement committees are unbundling hemostasis from broader surgical supply agreements, creating standalone bone wax category contracts with absorption-profile specifications. This pattern concentrates in US academic medical centers and German university hospitals, where value-analysis frameworks penalize non-resorbable options in bundled spinal payment structures.
Global Bone Wax Market Segmentation
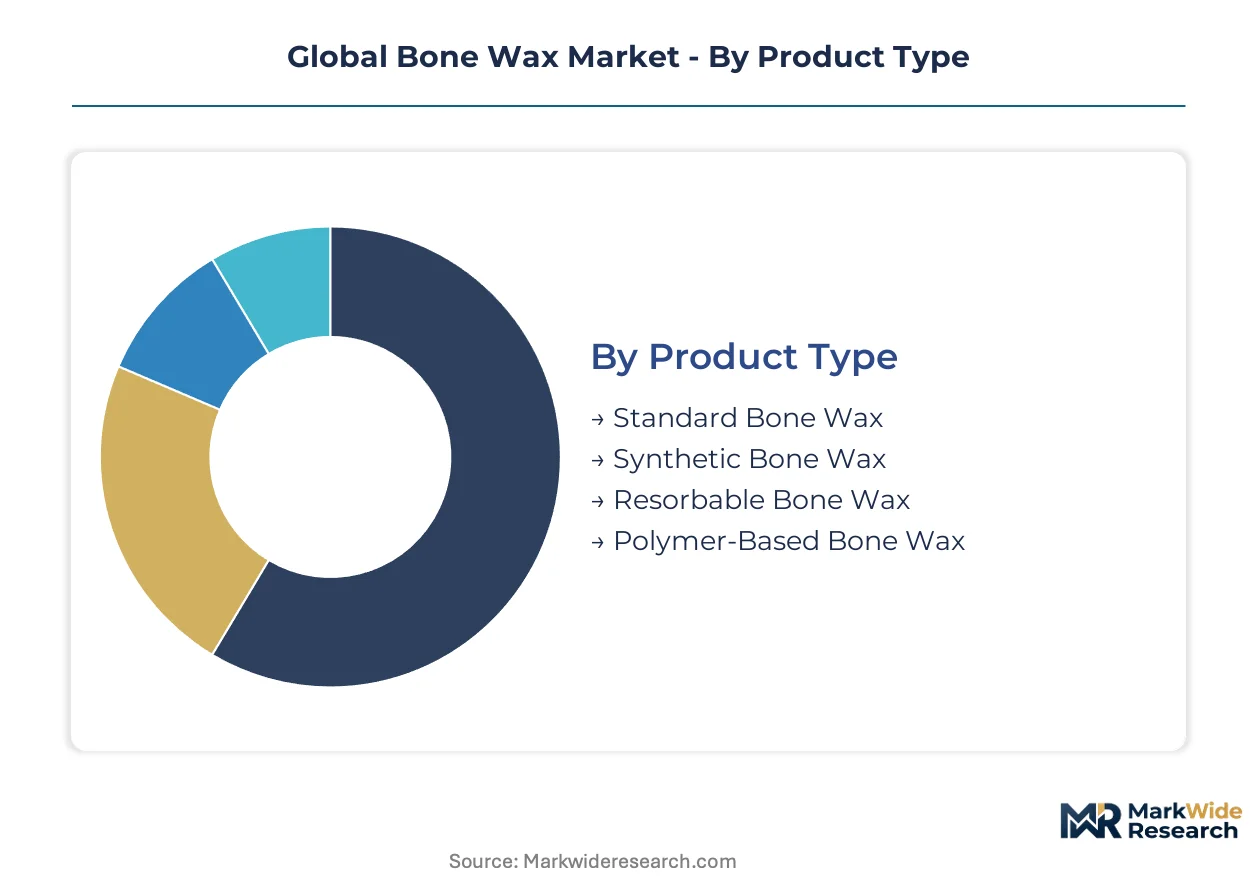
Segmentation in the bone wax market tracks how procurement criteria diverge across surgical specialties and facility tiers. Channel dynamics reveal where resorbable formulations command premium positioning versus where standard compositions retain volume dominance.
Product Type:
Channel mix varies sharply by formulation chemistry, with resorbable and polymer-based variants flowing through specialized surgical distributors while standard bone wax moves through high-volume GPO contracts.
- Standard Bone Wax:Beeswax-paraffin blends remain the default in cost-sensitive hospital systems and ambulatory settings. German university hospitals and US community hospitals continue bulk purchasing through integrated delivery networks, though procurement committees increasingly question foreign-body retention risks in spinal applications.
- Resorbable Bone Wax:Absorbable formulations incorporating polycaprolactone or polylactic acid platforms are capturing standalone contracts in academic medical centers. Japan's PMDA stability requirements and EU MDR clinical evidence mandates favor suppliers with pre-existing orthopedic implant polymer expertise.
- Synthetic Bone Wax:Petrochemical-derived alternatives occupy narrowing mid-tier positioning as polymer platforms demonstrate superior absorption kinetics.
- Polymer-Based Bone Wax:Next-generation materials leverage supply chain convergence with orthopedic implant manufacturers.
By volume, Standard Bone Wax leads. By growth pace, Resorbable Bone Wax is climbing the fastest.
Application:
Procedure complexity determines absorption-profile requirements, with deformity corrections and revision surgeries driving specification upgrades.
- Spinal Procedures:Complex fusion and deformity cases in tertiary centers are mandating complete resorption within 90-day windows. German orthopedic suites and Japanese academic hospitals pilot polymer platforms specifically to eliminate granuloma risk in instrumented fusions.
- Orthopedic Surgery:Trauma and joint reconstruction applications split between standard mechanical hemostasis in community settings and resorbable specifications in high-volume referral centers.
- Neurosurgery:Cranial applications demand precise handling characteristics with minimal inflammatory response.
- Cardiothoracic Surgery:Sternotomy closure procedures prioritize rapid hemostasis over absorption profiles.
- Dental Surgery:Oral and maxillofacial applications represent price-sensitive volume concentrated in private practice and ambulatory settings.
Orthopedic Surgery generates the largest absolute volume. Spinal Procedures show the steepest specification upgrade trajectory.
End User:
Facility tier correlates directly with formulation sophistication, as value-analysis committee sophistication increases with procedural complexity.
- Hospitals:Tertiary and academic medical centers in the United States, Germany, and Japan unbundle bone wax from surgical supply agreements to specify absorption kinetics. Bundled payment structures in US Medicare Advantage plans increasingly penalize non-resorbable options in spinal episodes.
- Surgical Centers:High-volume orthopedic and spinal specialty centers concentrate resorbable adoption where revision rate economics justify premium positioning.
- Ambulatory Surgical Facilities:Cost-minimization drives standard formulation dominance in outpatient arthroscopy and minor orthopedic procedures.
- Specialty Clinics:Oral surgery and limited-scope orthopedic practices represent fragmented price-sensitive demand.
Hospitals absorb the majority of resorbable volume. Surgical Centers are expanding share fastest among premium-formulation adopters.
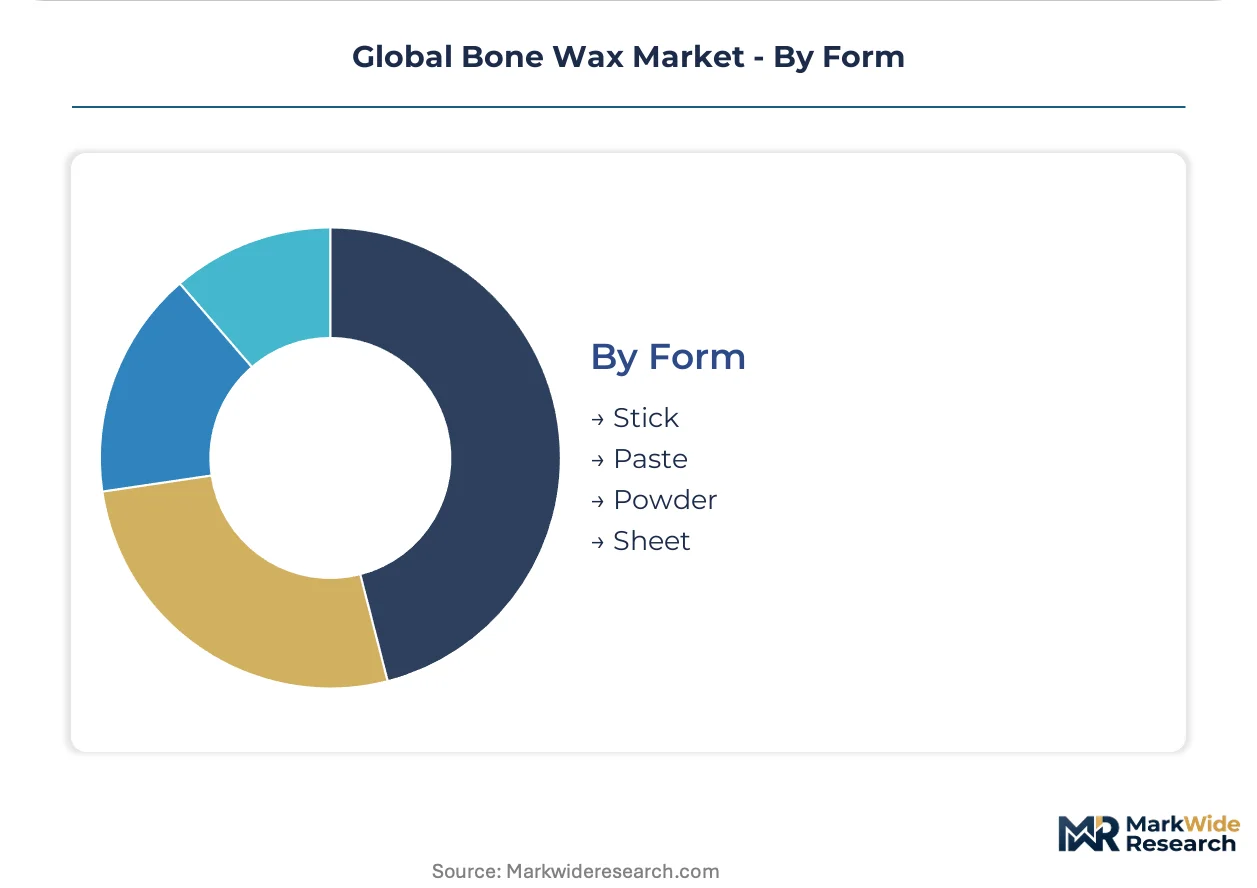
Form:
Physical configuration shapes application technique and surgeon retraining requirements, with paste and stick formats dominating distinct procedural contexts.
- Stick:Traditional beeswax-paraffin sticks remain standard in open procedures requiring manual molding. Surgeon familiarity and low unit cost sustain volume in cardiothoracic and general orthopedic applications across US and German community hospitals.
- Paste:Pre-softened formulations reduce application time in minimally invasive approaches. Japanese and German spine centers pilot paste resorbables where instrumented fusion corridors limit manual manipulation space.
- Powder:Emerging format for topical application in cranial and facial applications.
- Sheet:Specialized configurations for sternotomy and large-surface hemostasis.
Stick formats retain volume leadership. Paste configurations are gaining share fastest as minimally invasive spinal techniques expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Academic medical centers and tertiary hospitals in the United States, Germany, and Japan concentrate resorbable bone wax procurement, while value-analysis committees in these markets elevate absorption kinetics above unit cost in vendor selection.
United States
Medicare Advantage bundled payment structures penalize non-resorbable options in spinal episodes, driving specification upgrades. The FDA enforces ISO 10993 biocompatibility testing for hemostatic devices. Boston and Baltimore academic medical centers pilot polycaprolactone formulations in complex deformity corrections.
Germany
University hospital orthopedic suites expand procurement of documented resorbable formulations to reduce revision rates. EU MDR clinical evidence mandates force grandfathered products to generate absorption data or exit. The Rhine-Ruhr and Bavarian medical technology clusters concentrate notified body relationships and polymer supply chain integration.
Japan
PMDA stability requirements extend registration timelines for imported formulations, favoring suppliers with pre-existing orthopedic implant polymer expertise. Tokyo and Osaka spine centers pilot paste-format resorbables where instrumented fusion corridors limit manual manipulation space.
Brazil
ANVISA streamlined registration for Class II hemostatic devices opens private hospital procurement channels ahead of full MDR compliance in Europe. São Paulo and Rio de Janeiro surgical distributors build direct-to-hospital digital platforms capturing margin recovery from bypassed traditional markups.
United Kingdom
NHS value-analysis frameworks increasingly question foreign-body retention risks in spinal applications, compressing volume for standard beeswax-paraffin blends. The MHRA aligns with EU MDR technical documentation standards post-Brexit. London and Manchester academic centers unbundle bone wax from surgical supply agreements to specify absorption-profile contracts.
Global Bone Wax Market Competitive Landscape
Player mix skews toward diversified surgical conglomerates with broad hemostatic portfolios, compressing margin buffers for single-product specialists. Tiered competitive positioning separates premium resorbable suppliers with clinical evidence packages from cost-driven standard formulation vendors. Strategic archetypes include integrated blood management platforms, orthopedic channel specialists, and polymer supply chain integrators. Dominant competitive moves center on M&A to capture resorbable formulation expertise and strategic partnerships with orthopedic implant manufacturers.
Within the diversified surgical conglomerate tier, Medtronic plc, Zimmer Biomet Holdings Inc., and Baxter International Inc. represent distinct positioning archetypes. Medtronic exemplifies the broad surgical portfolio leverage model, Zimmer Biomet anchors orthopedic channel relationships, and Baxter occupies the integrated blood management platform position. These three entities collectively illustrate how hospital contracting power concentrates with suppliers capable of bundling hemostasis across multiple surgical applications.
| Leading Market Players |
|---|
| Medtronic plc |
| Zimmer Biomet Holdings Inc. |
| Baxter International Inc. |
| Abyrx Inc. |
| Stryker Corporation |
| Johnson & Johnson |
| Medline Industries Inc. |
| Teleflex Incorporated |
| B. Braun Melsungen AG |
| Others |
Supply & Pricing Matrix
Ninety-day inventory cycles for beeswax-paraffin formulations concentrate pricing power with Eastern European and South American apiculture suppliers, while hospital GPO contracts force absorption-profile specifications that compress margins for non-resorbable tiers. This tension between raw material lead-time volatility and procurement committee technical requirements shapes supplier positioning across formulation categories.
Pricing Analysis
Cost-plus contracts indexed to petrochemical feedstock benchmarks dominate standard bone wax procurement, with paraffin cost volatility passing through to German and US hospital systems. Price differentiation rests on ISO 10993 biocompatibility certification tiers and absorption kinetics documentation, with EU MDR-compliant resorbable formulations commanding premium positioning. Cost compression in standard formulations is intensifying as value-analysis committees penalize foreign-body retention risks. Ambulatory surgical centers exhibit highest price sensitivity, while academic medical centers prioritize absorption profiles over unit economics.
Supply Chain Analysis
Inventory concentration for beeswax raw materials centers on Poland, Brazil, and Argentina, where apiculture output fluctuations create 60-90 day supply uncertainty. Formulation chemistry draws from polycaprolactone and polylactic acid feedstocks anchored in German and Japanese orthopedic implant supply chains. Single-source vulnerability in Eastern European beeswax regions elevates risk for standard formulation manufacturers. Distribution runs through specialized surgical distributors for resorbable tiers and high-volume GPO contracts for standard compositions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The bone wax market functions as a regulatory-entrenchment defensive moat, where EU MDR clinical evidence mandates and FDA biocompatibility requirements create switching costs that protect incumbent positions while raising barriers for grandfathered product survival.
For Market Incumbents: Fortify hospital contracting leverage through integrated blood management platform bundling and backward integration into polycaprolactone polymer supply chains. Resorbable formulation expertise represents the critical defensive asset as notified body capacity constraints delay competitor submissions. Prioritize CE marking technical file completion for legacy portfolios before grandfathering deadlines expire. For New Entrants and Emerging Players: Brazil's ANVISA Class II fast-track pathway offers the most penetrable regulatory entry point ahead of full EU MDR compliance requirements. Target private hospital procurement channels in São Paulo and Rio de Janeiro through direct-to-hospital digital platforms that bypass traditional distributor markups. Lead with paste-format resorbable applications for minimally invasive spinal techniques where instrumented fusion corridors limit manual manipulation space. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because polymer supply chain convergence with orthopedic implant manufacturers will concentrate formulation expertise among diversified surgical conglomerates. Acquisition targets should display pre-MDR resorbable portfolios with existing notified body relationships. Monitor notified body capacity constraints in Europe as the inflection signal for competitive repositioning timing.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | MDR technical file completion secures European hospital access ahead of grandfathered product exits. |
| Hospital System Partnership | GPO-integrated contracts specify absorption kinetics that lock out non-resorbable competitors. |
| Backward Integration | Captive polycaprolactone supply from orthopedic implant channels reduces polymer cost volatility. |
| Software Companion Development | Digital procurement platforms capture margin recovery from bypassed surgical distributor markups. |
| Reimbursement Strategy | Medicare Advantage bundled payment alignment penalizes non-resorbable options in spinal episodes. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with orthopedic surgeons, hospital purchasing committee members, biomedical engineers, and GPO contracts managers; and secondary validation against FDA 510(k) filings, EU MDR technical documentation databases, hospital procurement records, and customs trade data for beeswax and polymer feedstocks. Bottom-up formulation demand modeling and top-down surgical procedure volume estimates were triangulated to constrain forecast variance.
Across the projection horizon, the analytical framework segmented volume and value outputs by formulation chemistry, application complexity, facility tier, and regional regulatory cluster. CAGRs were derived from procedure growth elasticities and formulation substitution curves. Industry-specific forecast inputs included spinal fusion caseload trajectories at tertiary centers and notified body certification throughput assumptions.
Underlying assumptions cover EU MDR implementation pace, apiculture supply stability, and polymer platform adoption curves, with deviation risk concentrated in notified body capacity bottlenecks and beeswax harvest volatility. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surgical Instruments
Ultrasonic Surgical Cutters Market
Surgical Instruments
Surgical Lamps Market
Surgical Instruments
Absorbable Surgical Suture with Needle Market
Surgical Instruments
Surgical Sutures Market
Surgical Instruments
Cleft Lip and Palate Repair Surgical Instrument Package Market
Surgical Instruments
US Surgical Staplers Market
Surgical Instruments
Global Surgical Booms Market
Surgical Instruments
Cheilectomy Market
Surgical Instruments
Suture Needles Market
Surgical Instruments
Japan General Surgical Devices Market
Surgical Instruments
Ultrasonic Scalpel Market
Surgical Instruments
Cryosurgery Market
Surgical Instruments
United Arab Emirates General Surgical Devices Market
Surgical Instruments
Operating Room Smoke Aspirators Market
Surgical Instruments
Minimally Invasive Gastrointestinal Surgical System Market
Surgical Instruments
Non-Absorbable Sutures Market