
 Americas Suture Needles Market | 2026-2036
Americas Suture Needles Market Size, Share, and Industry Trends Forecast 2026-2036
Americas Suture Needles Market Analytics
Hospital procurement consortiums across the Americas is fragmenting as regional buying groups gain leverage over national distributors. Medtronic leverages its integrated surgical portfolio to sustain direct contracting relationships with major health systems. Johnson & Johnson anchors its position through Ethicon's specialized needle-suture combinations for minimally invasive procedures. B. Braun Melsungen AG competes on manufacturing scale, operating high-volume stainless steel needle production facilities serving Latin American markets.
Americas suture needles are precision-engineered surgical instruments manufactured from surgical-grade stainless steel or proprietary alloys, with tip geometries ranging from taper-point to cutting-edge configurations designed to penetrate specific tissue densities without excessive trauma. Their primary purpose is to guide suture material through tissue layers during wound closure, with curved variants dominating abdominal and cardiovascular applications due to ergonomic handling in confined anatomical spaces. Single-use curved needles lead volume demand across hospitals and ambulatory surgical centers, while coated stainless steel variants command premium positioning in orthopedic and cardiovascular segments where reduced tissue drag improves surgical precision. Reusable needle categories face structural decline as infection control protocols tighten, though veterinary practices sustain modest demand for sterilizable instruments.
FDA 510(k) clearance pathways and ISO 13485 quality management standards govern device approval and manufacturing compliance across the United States, while Brazil's ANVISA and Mexico's COFEPRIS impose parallel registration requirements that shape market access timelines for imported products. The MDR transition in European supplier countries indirectly affects Americas sourcing strategies as manufacturers reallocate regulatory resources. Stakeholders must monitor how CMS reimbursement shifts for outpatient procedures reshape procurement volume toward ambulatory settings versus traditional hospital channels.
Market Dynamics
Hospital procurement consortiums across the Americas are fragmenting as regional buying groups gain leverage over national distributors, reshaping how suture needle manufacturers contract with end-users. This structural decentralization coincides with tightening FDA device classification rules and evolving ISO 13485 quality standards that elevate compliance costs for market participants.
Growth Catalysts
- Ambulatory Surgical Center Expansion:Brazil and Mexico are witnessing accelerated facility licensing for outpatient procedures, driving volume demand for single-use curved needles in minimally invasive settings.
- ISO 13485 Quality Mandates:Updated sterilization and traceability requirements are compelling manufacturers to upgrade production lines, inadvertently filtering out marginal competitors and consolidating viable supply.
- Cardiovascular Procedure Volumes:Southeastern US hospital clusters and São Paulo's private surgical networks are expanding catheterization lab capacity, increasing consumption of premium-coated needles for vascular closure.
Market Restraints
- Surgical-Grade Stainless Steel Volatility:Nickel and chromium price fluctuations in commodity markets compress margin predictability for needle producers operating at scale.
- Import Registration Timelines:Brazil's ANVISA and Mexico's COFEPRIS impose parallel registration requirements that extend market access delays for non-domestic manufacturers.
- Reusable Needle Substitution Collapse:Structural decline in sterilizable instrument categories eliminates a once-stable revenue stream as infection control protocols tighten across hospital systems.
Strategic Opportunities
- Veterinary Practice Undersupply:Sterilizable needle demand persists in animal health segments where regulatory pressure for single-use conversion remains lighter than human medicine.
- Needle-Suture Combination Integration:Convergence of precision needle engineering with advanced suture materials enables premium positioning in orthopedic and cardiovascular segments.
- Direct-to-Health-System Contracting:Bypassing traditional distributor tiers through integrated surgical portfolio offerings captures margin currently absorbed by intermediaries.
Industry Challenges
- Regulatory Resource Reallocation:European MDR transition requirements divert compliance personnel from Americas market registration timelines, delaying product launches.
- CMS Reimbursement Uncertainty:Shifting outpatient procedure payment classifications complicate volume forecasting for manufacturers serving mixed hospital-ambulatory customer bases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Americas Suture Needles Market |
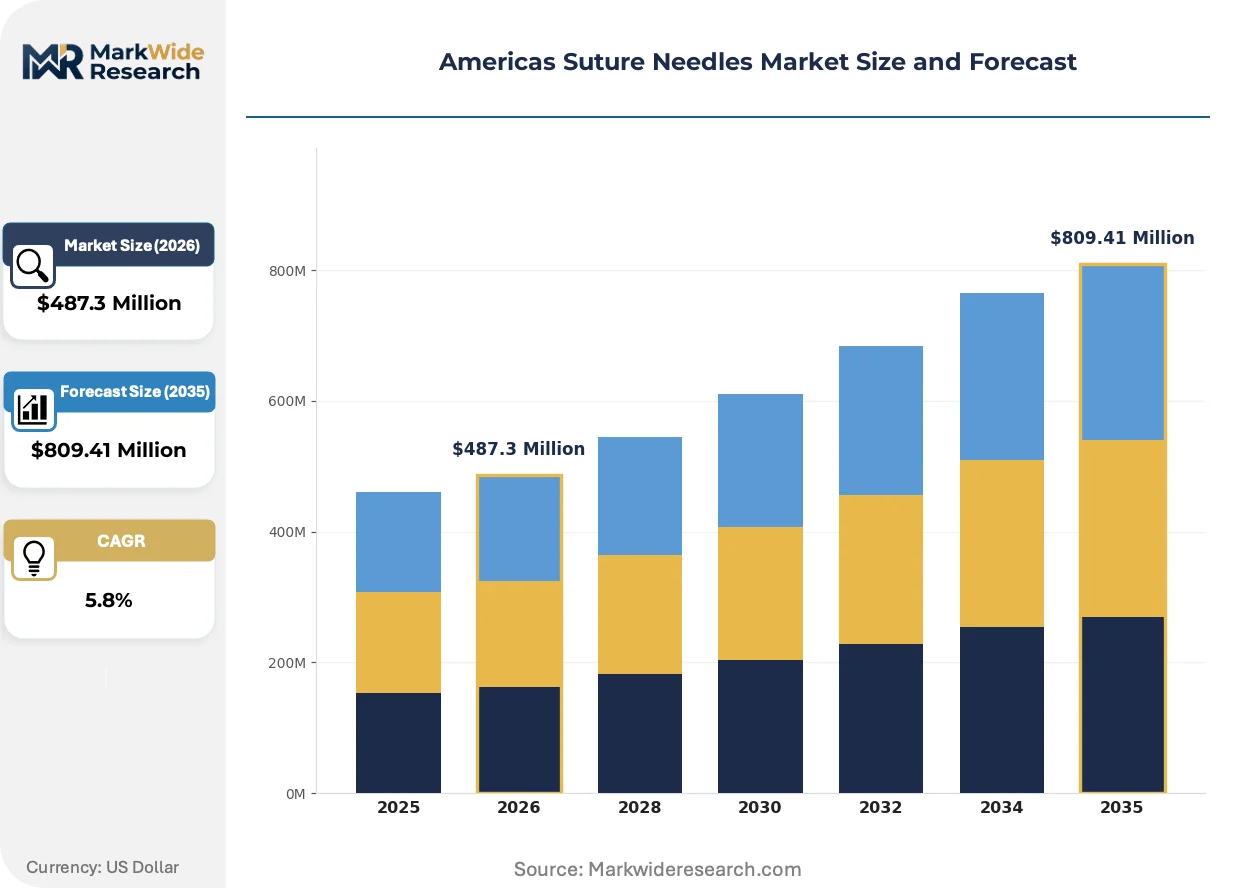
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $809.41 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Use, Reusable, Straight, Curved End User: Hospitals, Clinics, Ambulatory Surgical Centers, Veterinary Practices Material: Stainless Steel, Coated, Absorbable, Non-Absorbable Application: General Surgery, Orthopedic, Cardiovascular, Dental |
| Companies Covered | Medtronic, Teleflex Incorporated, Johnson & Johnson, Smith & Nephew, Hu-Friedy Mfg. Co., LLC, B. Braun Melsungen AG, Boston Scientific Corporation, CONMED Corporation, Ethicon, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Americas Suture Needles Market Evolving Landscape
Precision engineering and materials science are converging to redefine suture needle performance benchmarks across the Americas, with tip geometry optimization and surface coating technologies commanding disproportionate R&D investment from established suppliers.
Coated stainless steel variants with proprietary polymer layers are migrating from niche cardiovascular applications toward broader abdominal and orthopedic procedures. Academic medical centers in the southeastern United States are piloting these surfaces at accelerated adoption curves. The technology is migrating from premium positioning toward standard-of-care expectations as tissue drag reduction becomes a measurable quality metric in surgical outcomes.
FDA 510(k) clearance pathways are tightening evidentiary requirements for substantial equivalence determinations in needle device categories. Manufacturers now face expanded biocompatibility testing documentation and sterilization validation protocols. Single-use curved needle segments bear the heaviest compliance burden as FDA scrutinizes reprocessing claims and shelf-life stability data more aggressively than historical norms.
Regional buying coalitions are consolidating procurement authority away from national distributor networks. Hospital systems in Texas and Florida are forming multi-institutional contracting entities that negotiate directly with manufacturers. This concentration is most visible in metropolitan clusters where integrated delivery networks control substantial surgical volume and can mandate sole-source agreements for needle-suture combinations.
Americas Suture Needles Market Segmentation
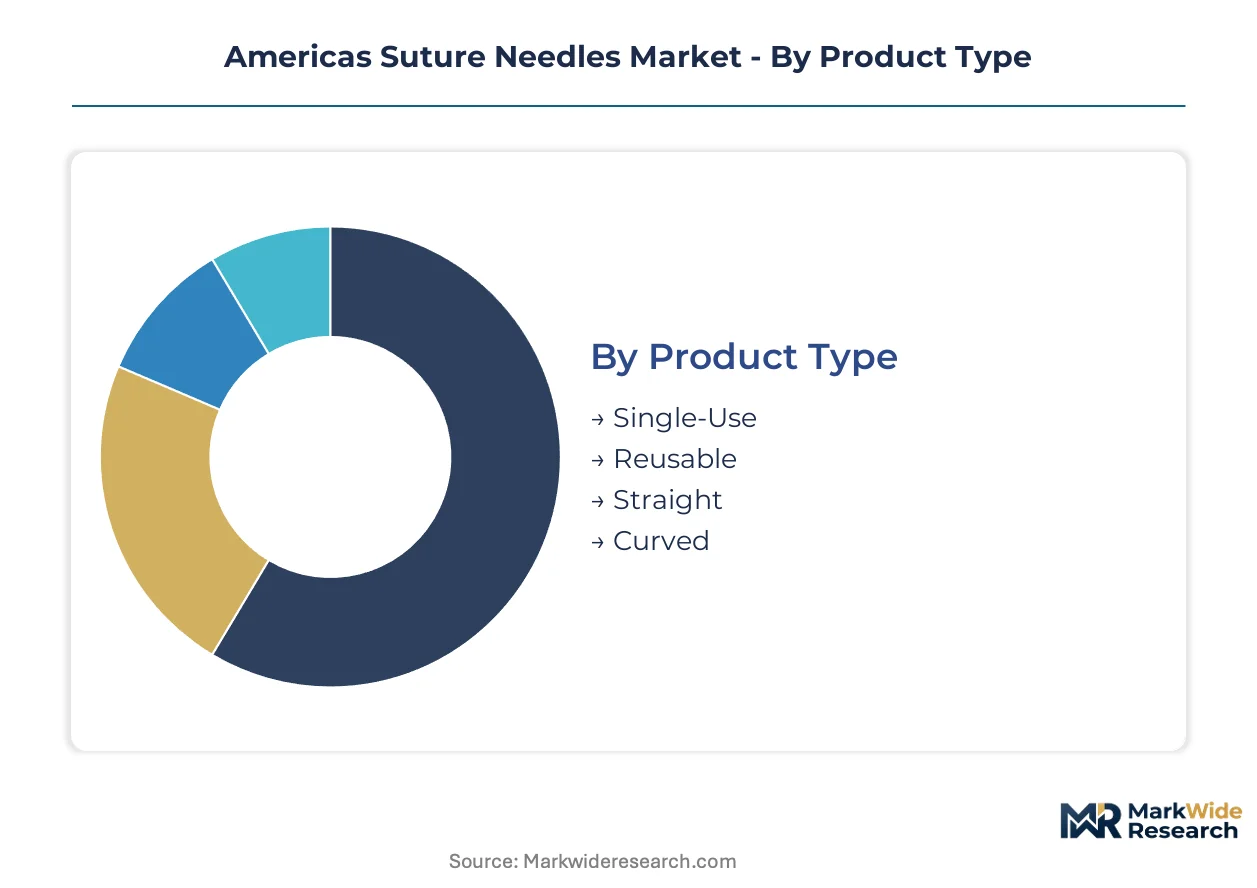
Suture needle segmentation in the Americas reflects divergent clinical economics and regulatory pressure gradients. Procurement patterns split sharply between institutional volume buyers and specialty practices where technical performance commands premium positioning.
Product Type:
Volume concentration across the Americas tilts decisively toward single-use formats as infection control protocols harden in hospital systems.
- Single-Use:Curved configurations dominate abdominal and cardiovascular applications where ergonomic handling in confined anatomical spaces reduces surgeon fatigue. Demand concentrates in southeastern US hospital clusters and São Paulo's private surgical networks expanding catheterization lab capacity.
- Curved:Precision-engineered variants with taper-point to cutting-edge geometries penetrate specific tissue densities without excessive trauma. Ambulatory surgical centers across Brazil and Mexico are accelerating facility licensing for outpatient procedures, driving volume uptake in minimally invasive settings.
- Straight:Limited applications in superficial skin closure and ophthalmic procedures where tissue depth permits linear needle paths.
- Reusable:Structural decline accelerates as FDA device classification rules tighten sterilization validation requirements; veterinary practices sustain modest demand for sterilizable instruments where regulatory pressure for single-use conversion remains lighter.
Single-use curved variants command the established base. The steepest expansion runs through single-use formats in ambulatory settings.
End User:
Customer type determines contracting leverage and price sensitivity across the Americas procurement landscape.
- Hospitals:Integrated delivery networks in Texas and Florida are forming multi-institutional contracting entities that negotiate directly with manufacturers, bypassing traditional distributor tiers. Regional buying coalitions consolidate procurement authority away from national distributor networks.
- Ambulatory Surgical Centers:Brazil and Mexico are witnessing accelerated facility licensing for outpatient procedures. These settings prioritize single-use curved needles for minimally invasive interventions where rapid turnover and infection control protocols favor disposable formats.
- Clinics:Smaller volume purchasers dependent on distributor relationships with limited direct manufacturer access.
- Veterinary Practices:Sterilizable needle demand persists in animal health segments where regulatory pressure for single-use conversion remains lighter than human medicine, creating a residual market for reusable instrument categories.
Hospitals anchor volume concentration. Ambulatory surgical centers are climbing the fastest as outpatient procedure migration accelerates.
Material:
Material selection tracks procedure complexity and tissue interaction requirements across surgical specialties.
- Coated:Proprietary polymer layers reduce tissue drag and improve surgical precision in vascular closure applications. Academic medical centers in the southeastern United States are piloting these surfaces at accelerated adoption curves as tissue drag reduction becomes a measurable quality metric.
- Stainless Steel:Surgical-grade alloys form the baseline for general surgical applications where cost containment dominates procurement decisions. Nickel and chromium price fluctuations in commodity markets compress margin predictability for producers operating at scale.
- Absorbable:Limited needle applications where suture material absorption parallels tissue healing timelines.
- Non-Absorbable:Permanent retention applications in cardiovascular and orthopedic procedures requiring long-term structural support.
Stainless steel variants hold the established base. Coated configurations are gaining share fastest as performance metrics harden in premium surgical segments.
Application:
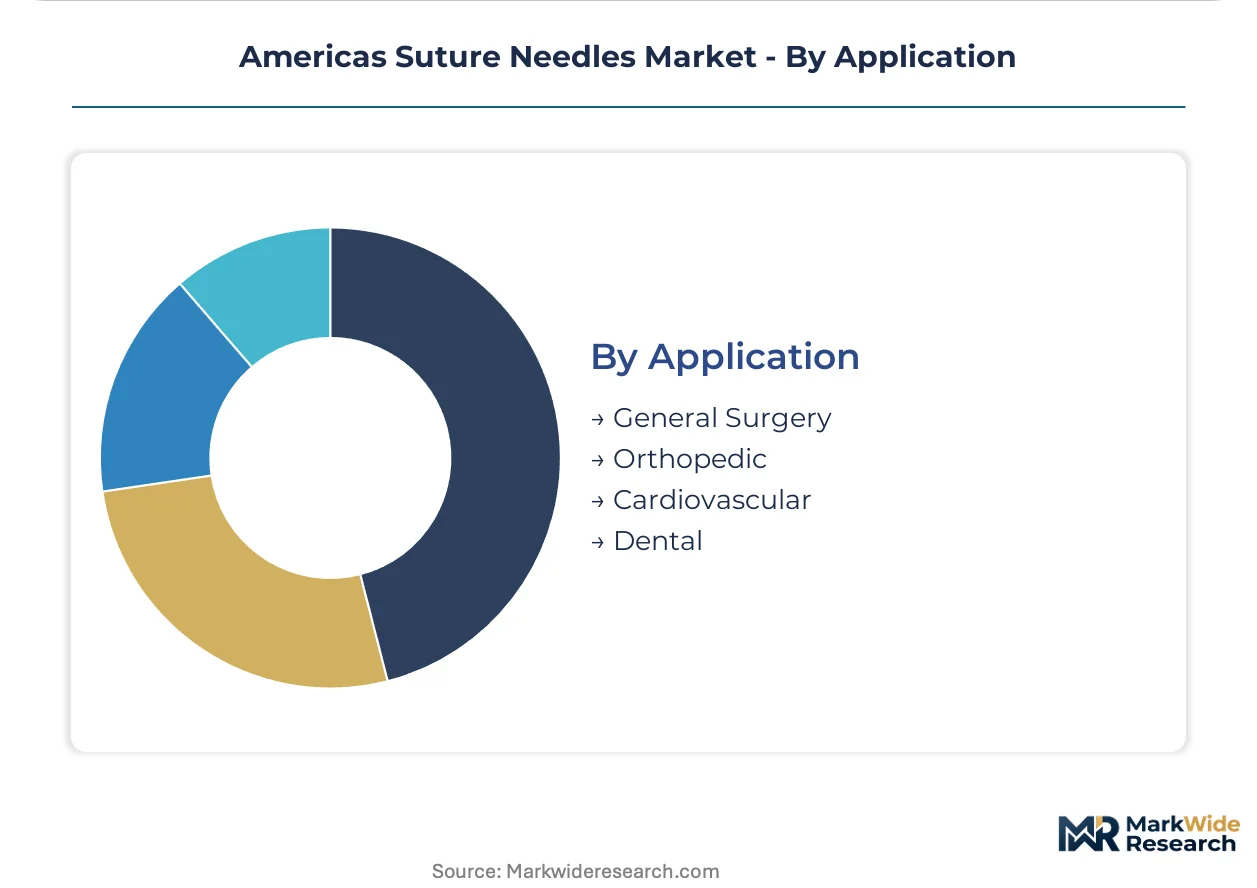
Procedure type dictates needle geometry specifications and coating requirements across the Americas surgical landscape.
- Cardiovascular:Premium-coated needles command positioning in catheterization lab procedures where reduced tissue drag improves precision in vascular closure. São Paulo's private surgical networks and southeastern US hospital clusters are expanding capacity in this segment.
- Orthopedic:Cutting-edge configurations penetrate dense connective tissue and bone-adjacent structures. Needle-suture combination integration enables premium positioning where precision engineering converges with advanced suture materials.
- General Surgery:Broad abdominal applications where curved single-use needles dominate due to ergonomic handling requirements.
- Dental:Specialized micro-needle formats for oral soft tissue procedures with limited volume relative to major surgical categories.
General surgery anchors volume concentration. Cardiovascular applications are expanding most quickly as regional hospital clusters invest in catheterization infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Miami's pharmaceutical logistics hub underwrites the southeastern United States' role as the primary distribution gateway for surgical consumables entering Latin American markets.
United States
FDA 510(k) clearance pathways tighten evidentiary requirements for substantial equivalence determinations in needle device categories. Southeastern hospital clusters in Texas and Florida form multi-institutional contracting entities that negotiate directly with manufacturers. Academic medical centers across Georgia and North Carolina pilot coated stainless steel variants at accelerated adoption curves.
Brazil
ANVISA registration timelines extend market access delays for non-domestic manufacturers seeking entry into Latin America's largest surgical consumables market. São Paulo's private surgical networks expand catheterization lab capacity, increasing consumption of premium-coated needles for vascular closure. Ambulatory surgical centers accelerate facility licensing across Minas Gerais and Rio de Janeiro.
Mexico
COFEPRIS imposes parallel registration requirements that shape procurement timelines for imported suture needle products. Northern border states leverage maquiladora infrastructure for regional distribution into southwestern US hospital systems. Mexico City metro area concentrates private surgical network expansion targeting medical tourism segments.
Canada
Health Canada device licensing aligns with ISO 13485 quality management standards, streamlining approval pathways for manufacturers already compliant with US FDA requirements. Ontario and Quebec hospital procurement consortiums consolidate purchasing authority away from national distributor networks. Greater Toronto surgical centers drive volume demand for single-use curved configurations.
Argentina
The country's national pharmaceutical regulator maintains registration requirements that filter marginal competitors from the import-dependent surgical consumables market. Buenos Aires anchors private healthcare infrastructure investment amid macroeconomic volatility affecting procurement predictability. Córdoba and Rosario sustain secondary demand concentrations for general surgical applications.
Americas Suture Needles Market Competitive Landscape
On the supply side, the industry is consolidating around integrated surgical portfolio providers capable of bypassing traditional distributor tiers through direct health-system contracting. Three strategic archetypes dominate: diversified medical technology conglomerates with broad surgical portfolios, specialized needle-suture combination manufacturers, and regional scale producers serving Latin American price-sensitive segments. Competitive moves concentrate on portfolio diversification through needle-suture integration and geographic expansion via regulatory registration acceleration in Brazil and Mexico.
Within the diversified medical technology tier, Medtronic and Johnson & Johnson exemplify integrated portfolio positioning. B. Braun Melsungen AG occupies a distinct scale-driven archetype with German-originated manufacturing operations. These three entities represent the primary competitive anchors structuring procurement relationships across hospital systems and ambulatory surgical centers throughout the Americas.
| Leading Market Players |
|---|
| Medtronic |
| Teleflex Incorporated |
| Johnson & Johnson |
| Smith & Nephew |
| Hu-Friedy Mfg. Co., LLC |
| B. Braun Melsungen AG |
| Boston Scientific Corporation |
| CONMED Corporation |
| Ethicon |
| Others |
Value Network & Pricing Analysis
São Paulo's surgical consumables manufacturing corridor anchors Latin American supply capacity, with its production scale dynamics translating directly into downstream pricing leverage across Brazilian and Mexican procurement markets. Regional buying coalitions in Texas and Florida exploit this concentration to extract volume concessions from distributors serving ambulatory surgical centers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates coated cardiovascular needles from general surgical stainless steel variants from basic curved configurations. Price differentiation rests on ISO 13485 certification tier and surgical-grade alloy composition. Pricing pressure stems from nickel and chromium commodity volatility compressing margin predictability for high-volume producers. Ambulatory surgical centers in Brazil and Mexico exhibit highest price sensitivity; academic medical centers in the southeastern United States show lowest sensitivity due to outcome-based procurement metrics.
Supply Chain Analysis
Supplier-financing facilities extended by German and US manufacturers to Latin American distributors ease working capital constraints across extended ANVISA and COFEPRIS registration timelines. Manufacturing concentrates in Germany, the United States, and Costa Rica for precision needle production serving Americas demand. Raw material dependencies draw from surgical-grade stainless steel feedstock, proprietary polymer coating inputs, and sterilization packaging materials. Single-source vulnerability runs through nickel supply concentration. Distribution runs through Port of Miami pharmaceutical logistics hubs into southeastern US hospital clusters and onward to São Paulo distribution centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity concentrates in veterinary sterilizable instruments and regional ambulatory surgical center networks, with outpatient procedure migration from hospital systems creating niche supply gaps outside integrated portfolio coverage.
For Market Incumbents: Build regulatory moat through accelerated FDA 510(k) pathway investment and ISO 13485 certification depth that marginal competitors cannot replicate. Consolidate position via direct contracting with Texas and Florida multi-institutional buying coalitions, bypassing distributor margin absorption. Counter threat from regional scale producers in Latin America by anchoring hospital system relationships through needle-suture combination bundles. For New Entrants and Emerging Players: Build out veterinary practice supply networks in Brazil and Mexico where sterilizable instrument demand persists under lighter single-use conversion pressure. Target ambulatory surgical center procurement in Minas Gerais and Rio de Janeiro accelerated licensing zones. Penetrate via COFEPRIS registration acceleration services paired with regional distribution partnerships. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because procurement authority fragmentation favors integrated surgical portfolio providers capable of bypassing distributor tiers. Acquisition target archetype: specialized needle-suture combination manufacturers with ISO 13485 depth and existing ANVISA registrations. Signal to watch: CMS outpatient reimbursement reclassification velocity indicating ambulatory volume inflection.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 13485 Certification Acceleration | Filters marginal competitors as sterilization validation requirements tighten across FDA and ANVISA jurisdictions. |
| Needle-Suture Combination Integration | Captures premium positioning in orthopedic and cardiovascular segments where precision engineering converges with advanced materials. |
| Direct Hospital System Contracting | Bypasses distributor margin absorption in Texas and Florida multi-institutional buying coalitions. |
| Veterinary Practice Supply Network | Exploits residual sterilizable instrument demand where regulatory pressure for single-use conversion remains lighter. |
| COFEPRIS Registration Acceleration | Compresses market access timelines for imported products targeting Mexico City medical tourism expansion. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with hospital procurement managers, GPO contracts specialists, biomedical engineers, and regulatory affairs leads at manufacturers; and secondary validation through FDA 510(k) filings, ANVISA registration databases, CMS Medicare reimbursement data, and hospital procurement consortium contract disclosures. Bottom-up demand modeling from ambulatory surgical center licensing data and catheterization lab capacity expansion triangulated against top-down surgical procedure volume estimates.
Forecast inputs span product type segmentation across single-use curved, straight, and reusable formats; material tiers from surgical-grade stainless steel to coated variants; and end-user categories from integrated delivery networks to independent clinics. CAGRs derive from procedure volume elasticity to outpatient migration trends and premium coated needle adoption curves in cardiovascular applications. Modeled variables include ISO 13485 compliance cost trajectories and nickel price volatility transmission effects.
The forecast holds incumbent behavior within observed patterns; aggressive direct contracting moves by diversified medical technology conglomerates would shift outcomes beyond projected ranges. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surgical Instruments
Lumpectomy Market
Surgical Instruments
Global Surgical Suction Instruments Market
Surgical Instruments
Pneumoperitoneum Market
Surgical Instruments
Huber Needles Market
Surgical Instruments
Electrocautery Enhanced Delivery System Market
Surgical Instruments
Plastic Wound Retractor Market
Surgical Instruments
Cryosurgical Equipment Market
Surgical Instruments
Monopolar Electrosurgery Instrument Market
Surgical Instruments
Global Powered Surgical Instruments Market
Surgical Instruments
Thoracic Surgery Market
Surgical Instruments
Ophthalmic Handheld Surgical Instruments Market
Surgical Instruments
Iraq Healthcare (Surgical Procedures) Market
Surgical Instruments
France General Surgical Devices Market
Surgical Instruments
Retractable Needles Market
Surgical Instruments
Cheilectomy Market
Surgical Instruments
Global Surgical Instrument Tracking System Market