
 Laparoscopic Gynecological Procedures Market | 2026-2036
Laparoscopic Gynecological Procedures Market Size, Share, and Industry Trends Forecast 2026-2036
Laparoscopic Gynecological Procedures Market Intelligence
Software-defined surgical visualization platforms is restructuring how hospitals procure laparoscopic ecosystems, shifting capital expenditure toward recurring subscription models for image enhancement and AI-assisted anatomy mapping. Medtronic leverages its integrated surgical workflow portfolio to anchor multi-year service contracts with major health systems. Intuitive Surgical competes through proprietary ecosystem lock-in around its robotic-assisted delivery architecture. Karl Storz SE & Co. KG differentiates via open-platform instrumentation that interoperates across third-party imaging stacks.
Laparoscopic gynecological procedures encompass minimally invasive surgical techniques employing trocar access, insufflation, and video-guided instrumentation to access the pelvic cavity for diagnostic and therapeutic interventions, typically requiring 5-12 mm port diameters and CO2 pneumoperitoneum maintenance at 12-15 mmHg. These procedures reduce perioperative morbidity, shorten hospital stays, and enable same-day discharge for interventions such as hysterectomy and ovarian cystectomy. Hysterectomy procedures occupy the largest procedural volume segment while robotic-assisted delivery modes capture disproportionate value per procedure due to capital intensity and disposable instrument attach rates. Electrosurgery technology leads margin pools through consumable blade and generator cartridge replenishment cycles.
FDA 510(k) clearance pathways govern device entry in the United States while EU MDR technical documentation requirements extend conformity assessment timelines for laparoscopic instruments and imaging systems. Japan's PMDA enforces stringent clinical evidence standards for novel energy devices used in myomectomy and endometriosis excision, creating differentiated market access conditions across regulatory jurisdictions. Stakeholders must monitor evolving reimbursement coding for single-incision and natural orifice approaches as these modalities challenge established fee schedules.
Market Dynamics
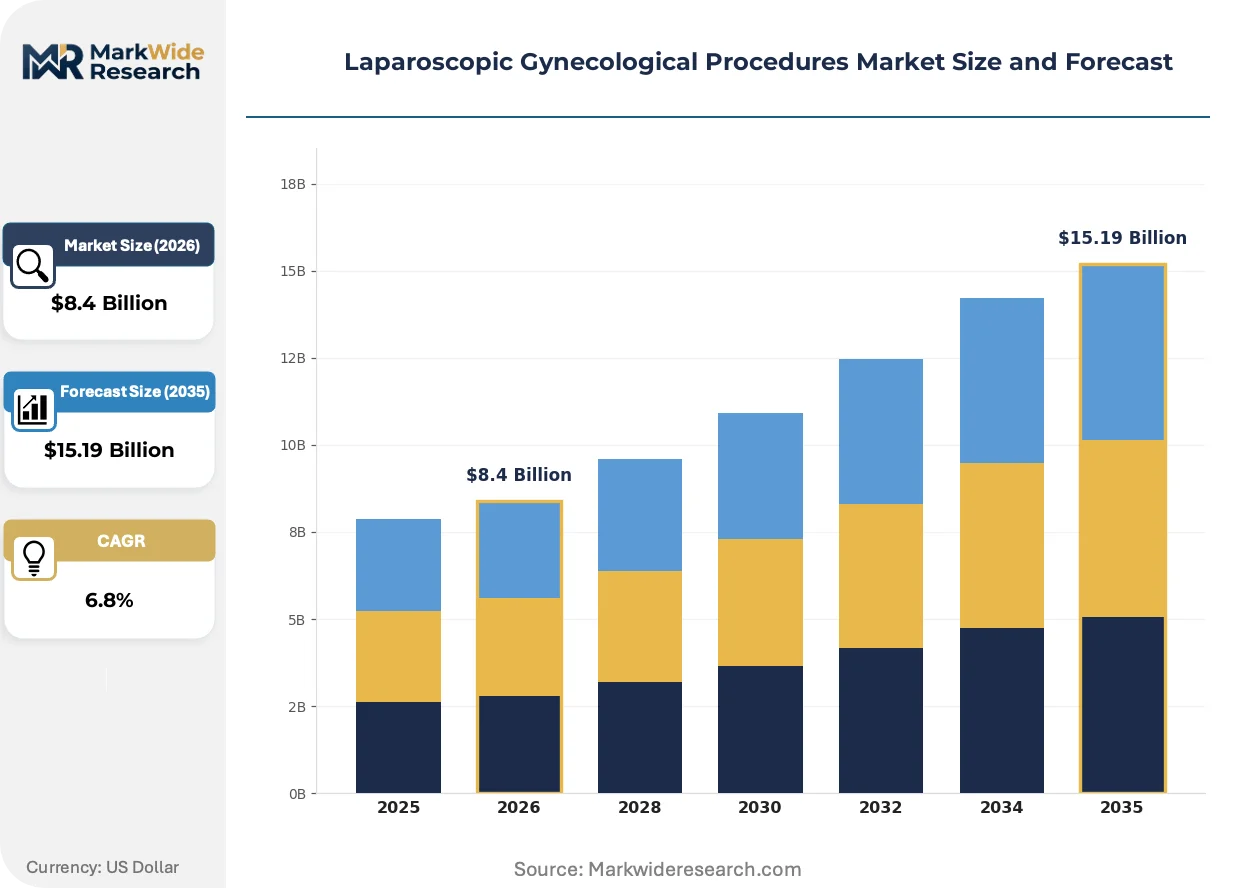
Software-defined surgical visualization platforms are restructuring hospital procurement patterns, converting capital-intensive imaging purchases into recurring subscription commitments for AI-assisted anatomy mapping and real-time image enhancement capabilities.
Growth Catalysts
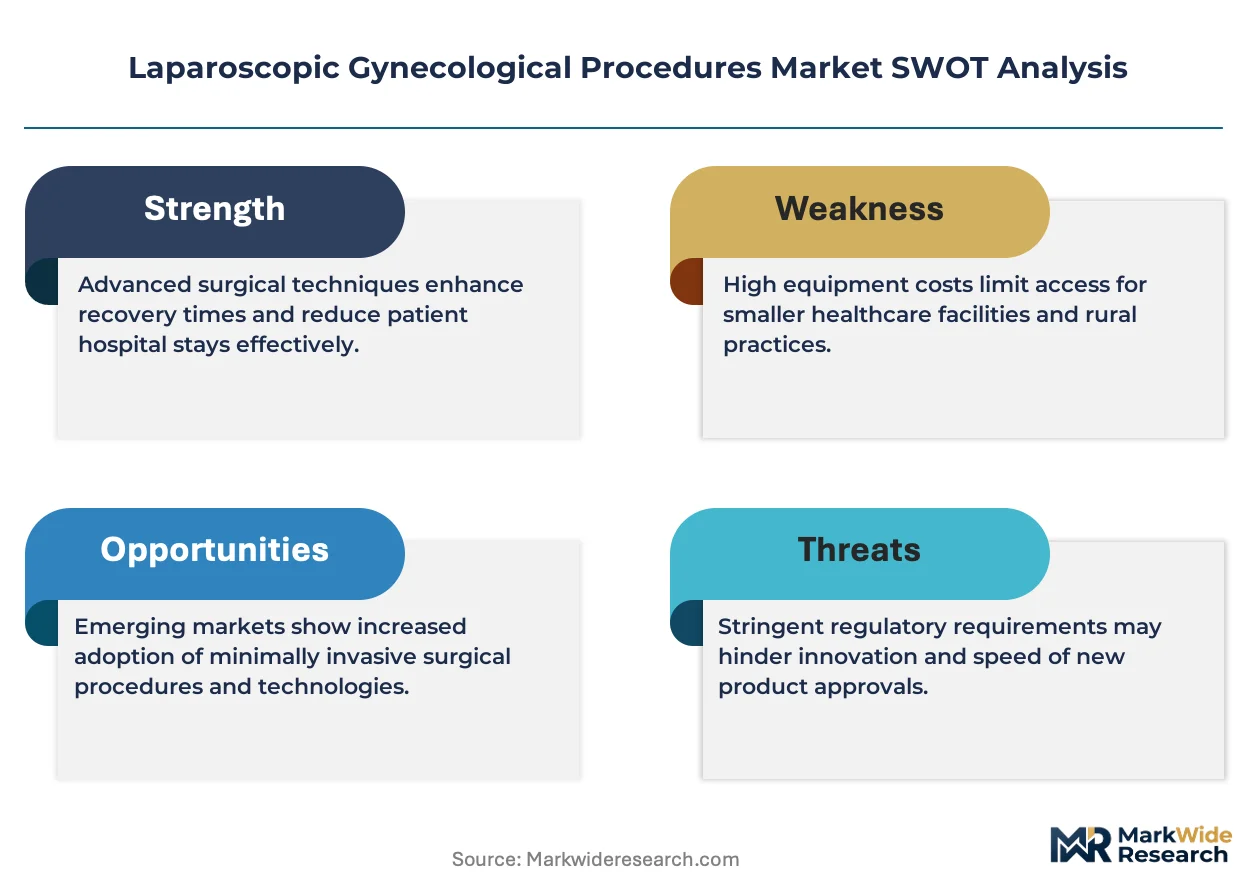
- EU MDR certification pathways:Extended conformity assessment timelines for laparoscopic instruments are filtering marginal competitors and elevating quality benchmarks across the European surgical device landscape.
- Outpatient surgical migration:United States health systems are repurposing inpatient beds toward higher-acuity cases, channeling hysterectomy and ovarian cystectomy volumes into ambulatory surgical centers equipped for same-day discharge protocols.
- Carbon dioxide insufflation systems:Advanced pressure-regulated pneumoperitoneum maintenance at 12-15 mmHg is reducing postoperative shoulder-tip pain and accelerating recovery trajectories in myomectomy patients.
Market Restraints
- Capital intensity of robotic-assisted platforms:Multi-million dollar installation requirements and proprietary disposable instrument attach rates constrain adoption outside tier-one academic medical centers.
- PMDA clinical evidence standards:Japan's pharmaceutical and medical device agency mandates extensive domestic trial data for novel energy devices, extending commercialization timelines for myomectomy and endometriosis excision technologies.
- Single-use instrument cost structure:Electrosurgery blade and generator cartridge replenishment cycles generate per-procedure consumable burdens that challenge outpatient reimbursement margins.
Strategic Opportunities
- Germany's outpatient reimbursement frameworks:Favorable fee schedules for minimally invasive gynecological interventions are attracting capital deployment toward dedicated laparoscopic surgery suites in Rhineland and Bavaria.
- Natural orifice specimen extraction:Convergence of single-incision access techniques with transvaginal retrieval pathways is eliminating abdominal wall extraction sites and reducing incisional hernia risks.
- Japan's aging demographic profile:Rising prevalence of uterine fibroids and endometriosis in perimenopausal populations is expanding addressable procedural volumes for diagnostic and therapeutic laparoscopy.
Industry Challenges
- Surgeon training pipelines:Prolonged learning curves for suturing and tissue manipulation in confined pelvic spaces limit the pool of practitioners qualified for complex endometriosis excision.
- EU MDR technical documentation:Expanded clinical evaluation requirements and notified body capacity constraints are delaying market entry for imaging system upgrades and energy device iterations.
- Legacy OR integration:Hospital information system interoperability gaps between proprietary robotic platforms and third-party electronic health records complicate surgical workflow documentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Laparoscopic Gynecological Procedures Market |
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $15.19 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Procedure Type: Hysterectomy, Myomectomy, Ovarian Cystectomy, Endometriosis Excision Delivery Mode: Robotic-Assisted, Single Incision, Standard Laparoscopy, Natural Orifice End User: Hospitals, Surgical Centers, Ambulatory Surgery Facilities, Gynecologists Technology: Video Laparoscopy, Electrosurgery, Laparoscopic Imaging, Instruments |
| Companies Covered | Johnson & Johnson, CONMED Corporation, Medtronic, The Cooper Companies, B. Braun SE, Stryker, Olympus Corporation, Intuitive Surgical, Karl Storz SE & Co. KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Laparoscopic Gynecological Procedures Market Strategic Shifts & Innovations
Artificial intelligence integration is penetrating surgical visualization stacks, converting raw laparoscopic feeds into annotated anatomical maps that reduce cognitive load during complex pelvic dissections.
4K-3D hybrid visualization systems are consolidating operating room imaging infrastructure around unified display architectures. Academic medical centers in Germany and Japan are prioritizing these platforms for residency training programs. The technology is consolidating vendor relationships by tethering hardware purchases to multi-year software service agreements.
FDA 510(k) clearance pathways are tightening evidentiary standards for substantial equivalence claims in laparoscopic energy devices. Manufacturers must now submit comparative thermal spread data and vessel sealing burst pressure metrics. Electrosurgery instrument lines face elongated review cycles as the agency scrutinizes predicate device lineage.
Hospital procurement committees are unbundling after-sales service contracts from capital equipment purchases. Independent third-party service organizations are capturing preventive maintenance and repair volumes for insufflation pumps and camera control units. This fragmentation is most visible in United States regional health systems seeking to reduce total cost of ownership for aging laparoscopic fleets.
Laparoscopic Gynecological Procedures Market Segmentation
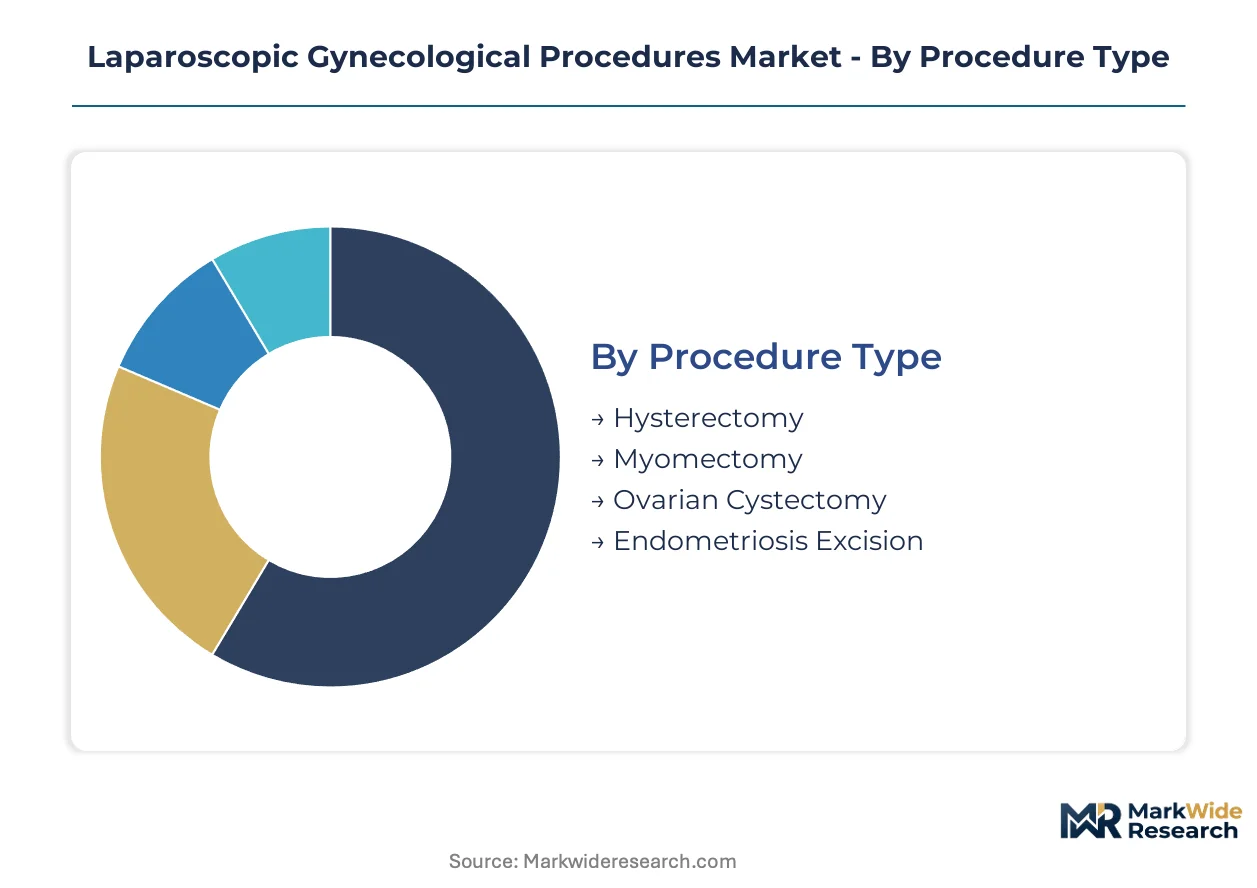
Segmentation in laparoscopic gynecological procedures reveals how capital allocation, reimbursement structures, and clinical complexity intersect to determine vendor strategies and health system procurement priorities.
Procedure Type:
Capital intensity varies sharply across pelvic interventions, with hysterectomy suites requiring the most substantial infrastructure investment while diagnostic procedures demand minimal fixed assets.
- Hysterectomy:Total uterine removal via laparoscopic approach requires dedicated insufflation systems, multi-port trocar arrays, and vessel sealing platforms. United States ambulatory surgery centers in Texas and Florida are consolidating hysterectomy volumes as reimbursement shifts favor same-day discharge protocols over inpatient stays.
- Myomectomy:Uterine-preserving fibroid excision demands advanced suturing instrumentation and hemostatic control systems for multi-layer closure. Japan's PMDA maintains stringent thermal spread documentation requirements for energy devices deployed in myomectomy, extending approval timelines for novel electrosurgical platforms.
- Ovarian Cystectomy:Cyst wall dissection and ovarian preservation techniques utilize bipolar forceps and irrigation-aspiration systems.
- Endometriosis Excision:Deep infiltrating disease resection requires specialized scissors and thermal ablation probes for peritoneal surface treatment.
Hysterectomy absorbs the bulk of installed capacity; endometriosis excision is expanding most quickly as diagnostic awareness improves and delayed fertility planning extends the reproductive window for intervention.
Delivery Mode:
Volume concentration tilts toward established multi-port techniques, though capital deployment increasingly targets platforms promising reduced abdominal wall trauma.
- Robotic-Assisted:Computer-enhanced instrumentation with wristed articulation and 3D visualization commands premium per-procedure economics through proprietary instrument attach rates. Germany's statutory health insurance framework reimburses robotic-assisted hysterectomy at elevated fee schedules, concentrating adoption in Rhineland university hospitals.
- Standard Laparoscopy:Conventional multi-port access with 5-12 mm trocar placement remains the workhorse modality for general gynecologists. United States community hospitals in Ohio and Pennsylvania prioritize standard laparoscopy suites for cost containment amid capital budget constraints.
- Single Incision:Umbilical access through specialized multi-channel ports eliminates lateral port sites.
- Natural Orifice:Transvaginal specimen extraction and instrument delivery avoids all abdominal incisions.
Standard laparoscopy retains dominant procedural share; single-incision platforms are climbing the fastest as port-site hernia concerns drive cosmetic and functional demand.
End User:
Procurement authority and reimbursement capture determine how device vendors structure sales territories and service contracts.
- Hospitals:Academic medical centers and community hospitals maintain centralized purchasing committees negotiating multi-year capital equipment agreements. Japan's university hospitals in Tokyo and Osaka anchor regional referral networks for complex endometriosis excision.
- Surgical Centers:Dedicated outpatient facilities optimize throughput for high-volume hysterectomy and cystectomy procedures. United States freestanding surgical centers in Arizona and Nevada exploit favorable Medicare Ambulatory Surgical Center fee schedules for same-day discharge protocols.
- Ambulatory Surgery Facilities:Hospital-affiliated outpatient units balance convenience with emergency backup capacity.
- Gynecologists:Solo and group practices with office-based surgical suites drive demand for compact, portable insufflation and imaging systems.
Hospitals control the majority of capital expenditure; surgical centers are gaining share fastest as case migration accelerates.
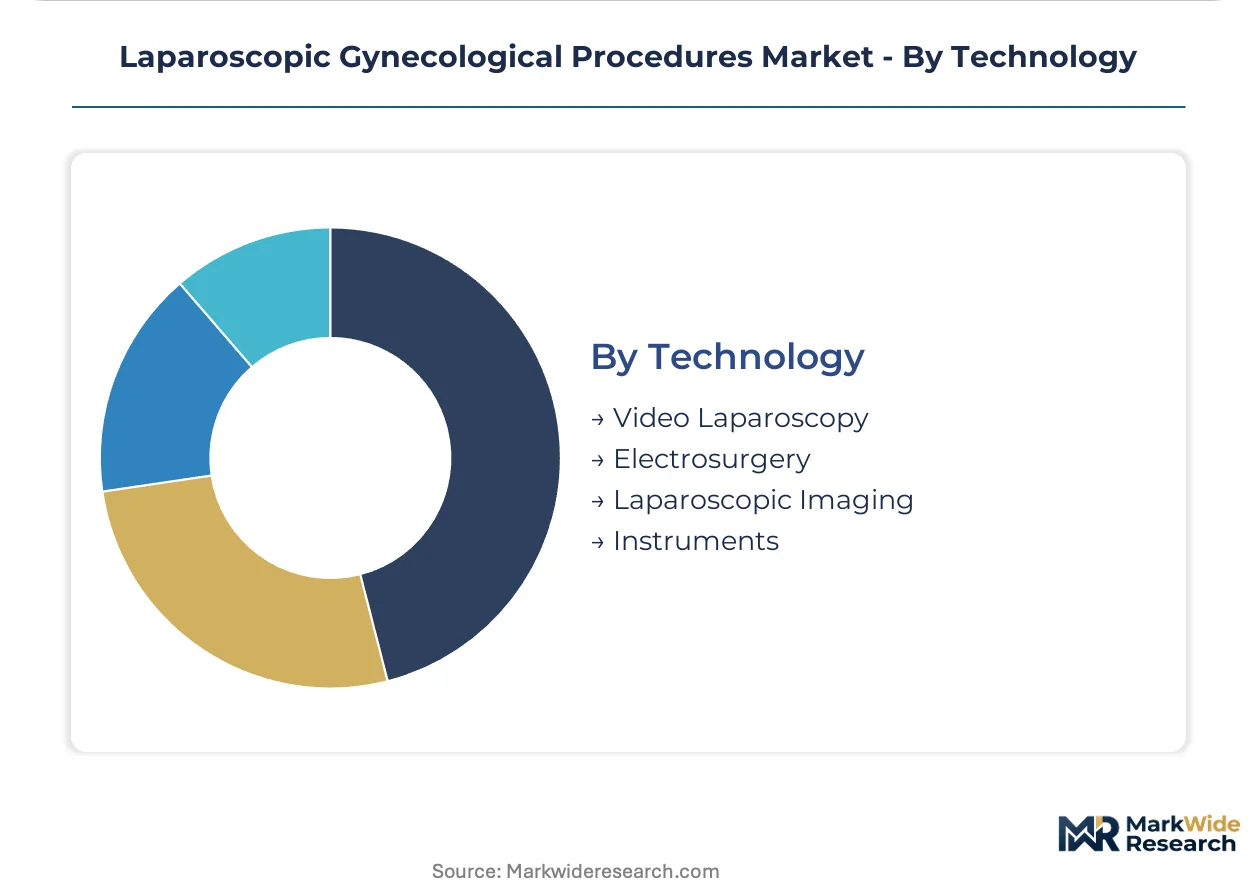
Technology:
Margin pools concentrate in consumable-dependent modalities where recurring revenue offsets capital equipment price erosion.
- Electrosurgery:Radiofrequency-based cutting and coagulation systems generate recurring revenue through disposable electrode and cartridge replenishment. Germany's outpatient clinics in Bavaria prioritize advanced bipolar vessel sealers for myomectomy hemostasis.
- Video Laparoscopy:Camera control units and light source systems form the visualization backbone for all pelvic procedures. Japan's Ministry of Health, Labour and Welfare reimbursement coding differentiates standard from high-definition imaging, influencing upgrade cycles.
- Laparoscopic Imaging:4K and 3D display architectures require display panel and processor hardware replacement.
- Instruments:Graspers, scissors, and needle drivers constitute the foundational mechanical toolkit.
Electrosurgery captures the largest consumable revenue stream; laparoscopic imaging is expanding fastest as visualization upgrades drive replacement demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Device manufacturing concentrates in Germany and the United States, while procedural demand clusters in aging societies with established outpatient surgical infrastructures. Consumption patterns diverge sharply between fee-for-service systems incentivizing capital deployment and single-payer frameworks optimizing throughput.
United States
Ambulatory surgery centers in Texas and Florida are consolidating hysterectomy volumes as Medicare reimbursement shifts favor same-day discharge. FDA 510(k) clearance pathways govern device entry, with tightened evidentiary standards for electrosurgical energy devices. Major health systems in Ohio and Pennsylvania anchor regional procurement networks for standard laparoscopy suites.
Germany
Statutory health insurance frameworks reimburse robotic-assisted hysterectomy at elevated fee schedules, concentrating adoption in Rhineland university hospitals. EU MDR certification timelines extend conformity assessments for laparoscopic instruments, filtering marginal competitors. Outpatient clinics in Bavaria prioritize advanced bipolar vessel sealers for myomectomy hemostasis.
Japan
Rising prevalence of uterine fibroids and endometriosis in perimenopausal populations expands addressable procedural volumes for diagnostic and therapeutic laparoscopy. PMDA mandates extensive domestic trial data for novel energy devices, extending commercialization timelines. University hospitals in Tokyo and Osaka anchor regional referral networks for complex endometriosis excision.
United Kingdom
NHS England procurement frameworks emphasize total cost of ownership for laparoscopic imaging upgrades, consolidating vendor relationships around multi-year service agreements. MHRA post-Brexit regulatory autonomy maintains alignment with EU MDR technical standards. London teaching hospitals drive adoption of 4K-3D hybrid visualization platforms for residency training programs.
India
Private hospital chains in Maharashtra and Karnataka are deploying compact laparoscopic suites for elective gynecological procedures targeting medical tourism segments. CDSCO regulates device imports through import license requirements and quality testing protocols. Corporate hospital networks in Delhi-NCR negotiate bundled procurement contracts for electrosurgery generators and disposable instruments.
Laparoscopic Gynecological Procedures Market Key Industry Players
Top-tier vendors anchor integrated surgical ecosystems, while mid-tier specialists compete on open-platform interoperability and regional service density. The vendor base stratifies across capital-intensive robotic platforms, visualization hardware incumbents, and consumable-dependent electrosurgery suppliers. Strategic archetypes include ecosystem orchestrators pursuing multi-year hospital contracts, open-platform instrumentation specialists, and regional service organizations capturing aftermarket maintenance volumes. Competitive moves center on unbundling service contracts from capital sales and backward integration into disposable instrument manufacturing.
Among diversified medical technology conglomerates, Johnson & Johnson and Medtronic exemplify ecosystem orchestrators leveraging integrated surgical workflow portfolios to anchor long-term health system relationships. Stryker occupies a position within the orthopedic-crossover tier, applying capital equipment leasing expertise to laparoscopic visualization and powered instrumentation. Karl Storz SE & Co. KG represents the open-platform archetype, differentiating via instrumentation interoperability across third-party imaging stacks rather than proprietary ecosystem lock-in.
| Leading Market Players |
|---|
| Johnson & Johnson |
| CONMED Corporation |
| Medtronic |
| The Cooper Companies |
| B. Braun SE |
| Stryker |
| Olympus Corporation |
| Intuitive Surgical |
| Karl Storz SE & Co. KG |
| Others |
Cost & Logistics Intelligence
Backward integration into electrosurgery blade manufacturing anchors pricing power for tier-one vendors while compressing margins for pure-play instrument suppliers dependent on outsourced component sourcing. This integration choice separates vendors capable of multi-year hospital service contracts from competitors locked into transactional equipment sales with limited consumable attach rates.
Pricing Analysis
Margin tightening in standard laparoscopy equipment traces to hospital procurement committees unbundling service contracts from capital purchases and soliciting third-party maintenance bids. Three-tier pricing structure across premium robotic-assisted, standard multi-port, and economy diagnostic levels differentiates by software integration depth and instrument articulation capability. Cost-down pressure on imaging hardware accelerates as 4K-3D hybrid platforms commoditize and subscription-based visualization software captures recurring revenue. Ambulatory surgery centers exhibit highest price sensitivity due to fixed-fee reimbursement constraints, while academic medical centers prioritize ecosystem lock-in over unit economics.
Supply Chain Analysis
Direct-to-hospital channels handle capital equipment demand for robotic platforms and integrated visualization suites, while distributor networks manage consumable replenishment for electrosurgery instruments and trocar arrays. Manufacturing concentrates in Germany for precision optical components, the United States for electrosurgery generators, and Japan for advanced camera control units. Supply chains draw from specialized optical glass foundries, radiofrequency generator component suppliers, and medical-grade polymer processors. Single-source vulnerability persists for 4K image sensor modules sourced from concentrated semiconductor fabrication clusters. Distribution runs through regional medical device distributors with GPO contract access in the United States and direct sales forces in Germany and Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a consolidation play as EU MDR certification timelines and FDA evidentiary standard tightening force marginal competitors without clinical trial infrastructure toward exit or acquisition.
For Market Incumbents: To counter proprietary robotic ecosystem lock-in by Intuitive Surgical and Medtronic, Karl Storz SE & Co. KG and open-platform specialists should deepen backward integration into disposable instrument manufacturing and secure multi-year visualization software subscriptions. Channel control through exclusive GPO contracts with United States regional health systems provides defensive moats against emerging single-incision platform vendors. For New Entrants and Emerging Players: Enter via Japan's PMDA approval pathway for novel energy devices in myomectomy applications, where domestic trial requirements filter multinational competitors and create white-space for specialized thermal spread documentation capabilities. Target Germany's outpatient clinic segment in Bavaria and Rhineland, where favorable statutory insurance reimbursement for minimally invasive hysterectomy supports premium pricing for advanced bipolar vessel sealers. A go-to-market angle emphasizing open-platform interoperability with existing hospital imaging infrastructure reduces switching costs versus robotic-assisted platform conversion. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by diversified medtech conglomerates seeking surgical workflow integration capabilities, with IPO viability restricted to platforms demonstrating proprietary AI-assisted anatomy mapping differentiation. Long-term viability favors vendors with captive consumable revenue streams and multi-year hospital service contracts rather than capital equipment pure-plays exposed to replacement cycle volatility. Watch FDA 510(k) clearance velocity for electrosurgical energy devices as an inflection indicator for competitive intensity and predicate device lineage exhaustion.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Certification Pathway | Extended conformity timelines filter marginal competitors and elevate quality benchmarks across European surgical device landscape. |
| Hospital System Partnership | Multi-year service contracts with United States academic medical centers anchor recurring revenue and reduce customer churn. |
| Software Companion Development | AI-assisted anatomy mapping subscriptions convert capital-intensive imaging purchases into recurring revenue streams. |
| Reimbursement Strategy | Coding differentiation for single-incision and natural orifice approaches challenges established fee schedules and enables premium capture. |
| CE Marking Pathway | Technical documentation for laparoscopic instruments requires expanded clinical evaluation and notified body capacity coordination. |
Research Approach
Document review covered FDA 510(k) clearance databases, EU MDR technical documentation requirements, and Japan PMDA approval records, complemented by interviews with hospital purchasing committee directors, GPO contracts managers, biomedical engineers, and laparoscopic surgeons across the United States, Germany, and Japan. Secondary validation drew from hospital procurement databases, CMS Medicare reimbursement coding, statutory health insurance fee schedules, and medical device trade association reports. Bottom-up procedure volume estimates and top-down market sizing triangulated around installed base calculations and replacement cycle assumptions.
Segment-level outputs across procedure type, delivery mode, end user, and technology dimensions were generated through structured modeling across the projection horizon. CAGRs were derived from procedure volume growth trajectories, technology replacement cycles, and reimbursement framework evolution. Forecast inputs incorporated EU MDR certification pipeline delays, PMDA domestic trial requirements for novel energy devices, and ambulatory surgery center case migration patterns in United States regional markets.
Forecast precision tightens around the base case; tail outcomes carry wider variance under prolonged FDA evidentiary standard tightening or accelerated single-incision platform adoption displacing standard multi-port volumes. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surgical Instruments
Suture Anchor Market
Surgical Instruments
Absorbable PGA Surgical Sutures Market
Surgical Instruments
Global Surgical Case Carts Market
Surgical Instruments
Disposable Spinal Instruments Market
Surgical Instruments
Harmonic Scalpel Market
Surgical Instruments
Surgical Drainage Devices Market
Surgical Instruments
Surgical Drains Market
Surgical Instruments
Corneal Transplantation Surgical Instrument Package Market
Surgical Instruments
Articulating Paper Forceps Market
Surgical Instruments
Ischemic Stroke Surgery Market
Surgical Instruments
Dermal Curettes Market
Surgical Instruments
Surgical Suction Pumps Market
Surgical Instruments
Global Microsurgery Market
Surgical Instruments
Retractable Needles Market
Surgical Instruments
Spain General Surgical Devices Market
Surgical Instruments
Global Surgical Lasers Market