
 Opioid Withdrawal Treatment Market | 2026-2036
Opioid Withdrawal Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Opioid Withdrawal Treatment Market Outlook
A capital-intensity divergence between large pharmaceutical manufacturers and specialized addiction therapy developers is reorganizing competitive dynamics in opioid withdrawal care. Indivior PLC leverages its established buprenorphine portfolio to sustain dominance in medication-assisted treatment formulations. Alkermes PLC anchors its position through extended-release naltrexone manufacturing capabilities that differentiate it from conventional short-acting competitors.
Opioid withdrawal treatment encompasses pharmacological interventions, clinical support services, and structured therapeutic protocols designed to manage the physiological and psychological symptoms that emerge upon cessation of opioid use, typically involving tapering schedules, symptom-targeted medications, and psychosocial stabilization over a clinically supervised duration. The primary purpose is to reduce morbidity associated with unassisted withdrawal while enabling transition into longer-term recovery maintenance. Medications command the dominant share of product-type revenue, particularly buprenorphine and naltrexone formulations where patent-protected delivery mechanisms protect margin pools. Telehealth delivery mode is expanding fastest among access channels, as regulatory flexibilities for remote prescribing of controlled substances have permanently altered patient reach for maintenance therapy initiation.
FDA REMS requirements for buprenorphine products and DEA scheduling classifications for opioid partial agonists shape prescriber capacity and pharmacy distribution networks, while state-level Medicaid formularies determine reimbursement breadth for behavioral therapy adjuncts. The Substance Abuse and Mental Health Services Administration certification standards for opioid treatment programs further constrain market entry for new facility-based providers. Stakeholders must monitor evolving federal telehealth prescribing rules and state parity legislation to anticipate shifts in channel economics between in-person and remote care delivery.
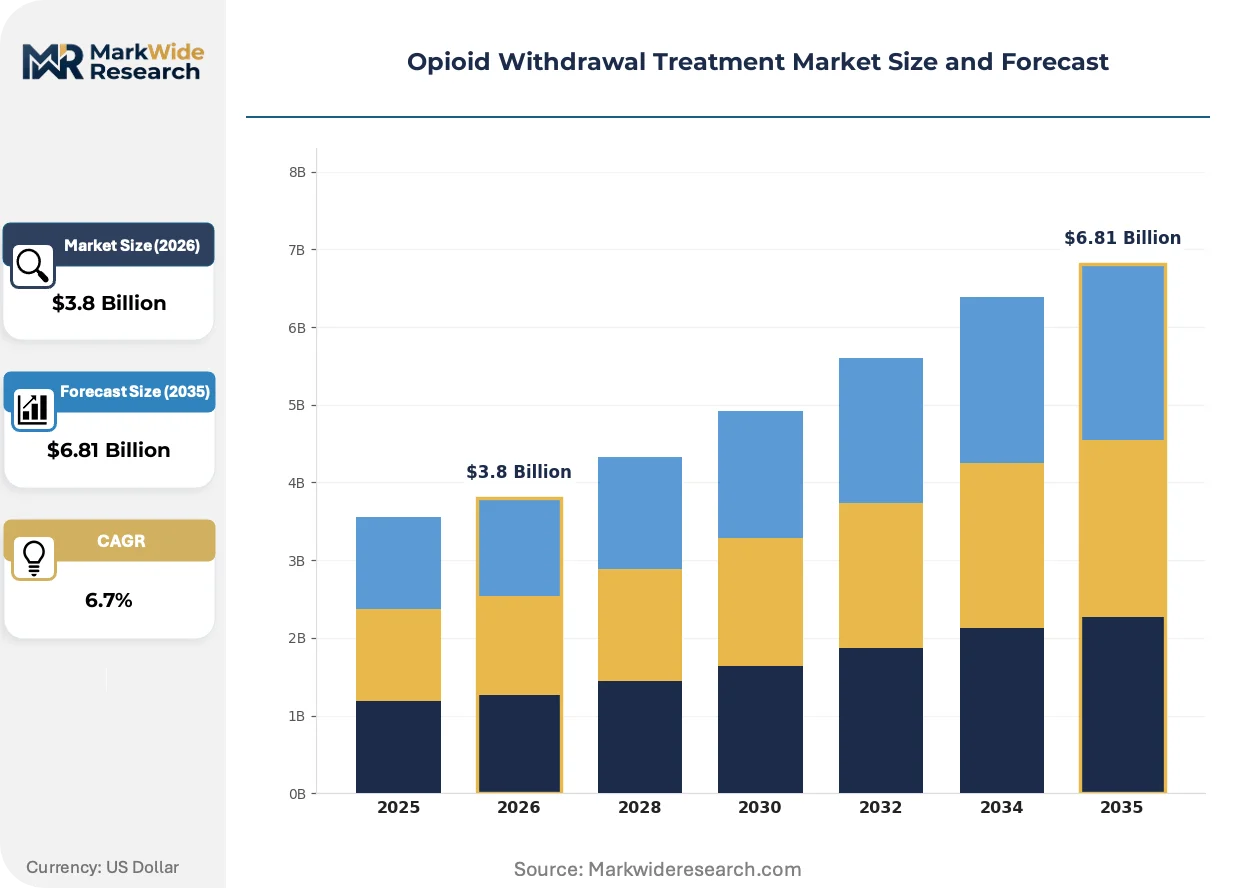
Market Dynamics
FDA REMS certification requirements for buprenorphine prescribers are compressing prescriber capacity while telehealth regulatory flexibilities permanently expand patient reach, creating a structural tension between access expansion and clinical oversight intensity.
Growth Catalysts
- Medicaid Expansion:State-level Medicaid formularies in the United States now reimburse medication-assisted treatment programs, broadening patient access to buprenorphine and naltrexone formulations.
- Telehealth Regulatory Flexibility:DEA scheduling exemptions for remote prescribing of controlled substances enable maintenance therapy initiation without geographic proximity to specialized clinics.
- Hospital Detoxification Capacity:Acute care facilities expand intake protocols for managing severe withdrawal episodes, creating institutional demand for pharmacological interventions.
Market Restraints
- DEA Scheduling Friction:Opioid partial agonist classifications impose pharmacy distribution constraints and inventory tracking burdens that limit retail channel penetration.
- Prescriber Certification Bottleneck:FDA REMS requirements restrict the pool of qualified buprenorphine prescribers, creating geographic access deserts in rural and underserved urban zones.
- Behavioral Therapy Reimbursement Gaps:State Medicaid formularies exhibit inconsistent coverage for psychosocial adjuncts, fragmenting comprehensive care delivery.
Strategic Opportunities
- Rural Access White Space:Federally Qualified Health Centers in underserved counties present deployment targets for telehealth-integrated medication-assisted treatment hubs.
- Extended-Release Formulation Development:Long-acting injectable buprenorphine and naltrexone depot technologies reduce dosing frequency and improve adherence metrics.
- State Parity Legislation Tailwinds:Mental health parity laws in multiple states mandate equivalent reimbursement for addiction treatment relative to other chronic disease management.
Industry Challenges
- Addiction Medicine Specialist Scarcity:Board-certified addiction psychiatrists and waivered prescribers remain concentrated in metropolitan corridors, constraining workforce scaling.
- Integrated Care Coordination Complexity:Electronic health record interoperability gaps between OTPs, emergency departments, and primary care networks impede continuity protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Opioid Withdrawal Treatment Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Medications, Counseling Services, Detoxification Centers, Behavioral Therapies Delivery Mode: In-Patient, Out-Patient, Telehealth, Home-Based Treatment End User: Hospitals, Rehabilitation Facilities, Mental Health Clinics, Private Practices Treatment Approach: Medication-Assisted Treatment, Cognitive Behavioral Therapy, Support Groups, Peer Recovery Services |
| Companies Covered | Indivior PLC, Alkermes PLC, Teva Pharmaceutical Industries Ltd., Pfizer Inc., Orexo AB, BioDelivery Sciences International Inc., Mallinckrodt Pharmaceuticals, Hikma Pharmaceuticals, Sun Pharmaceutical Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Opioid Withdrawal Treatment Market Strategic Shifts
Digital health infrastructure is decomposing traditional site-of-care boundaries while regulatory frameworks adapt to remote service delivery models. Product formulation science advances toward longer-acting depot mechanisms. Payer structures increasingly bundle pharmacological and behavioral components.
Extended-release injectable formulations are decomposing the daily oral dosing paradigm that dominated medication-assisted treatment for two decades. OTPs and correctional health systems adopt monthly buprenorphine and naltrexone depot injections to reduce adherence failure and diversion risk. This shift compresses pharmacy transaction volume while elevating manufacturing complexity and cold-chain logistics requirements.
DEA telehealth prescribing rules for controlled substances underwent permanent modification following emergency flexibilities, enabling initial buprenorphine evaluation via synchronous video platforms without prior in-person examination. This regulatory adaptation expands prescriber effective reach across state lines where licensure compacts permit. Rural counties and carceral settings represent the most affected geographies, with health systems rapidly deploying hybrid care models.
Patient acquisition patterns now favor direct-to-clinic digital scheduling over traditional referral pathways from emergency departments or criminal justice diversion programs. Telehealth platforms and mobile health applications displace conventional intake queues, particularly among working-age populations seeking discrete access. This channel rotation is most visible in states with mature Medicaid managed care contracts that authorize virtual first encounters.
Opioid Withdrawal Treatment Market Segmentation
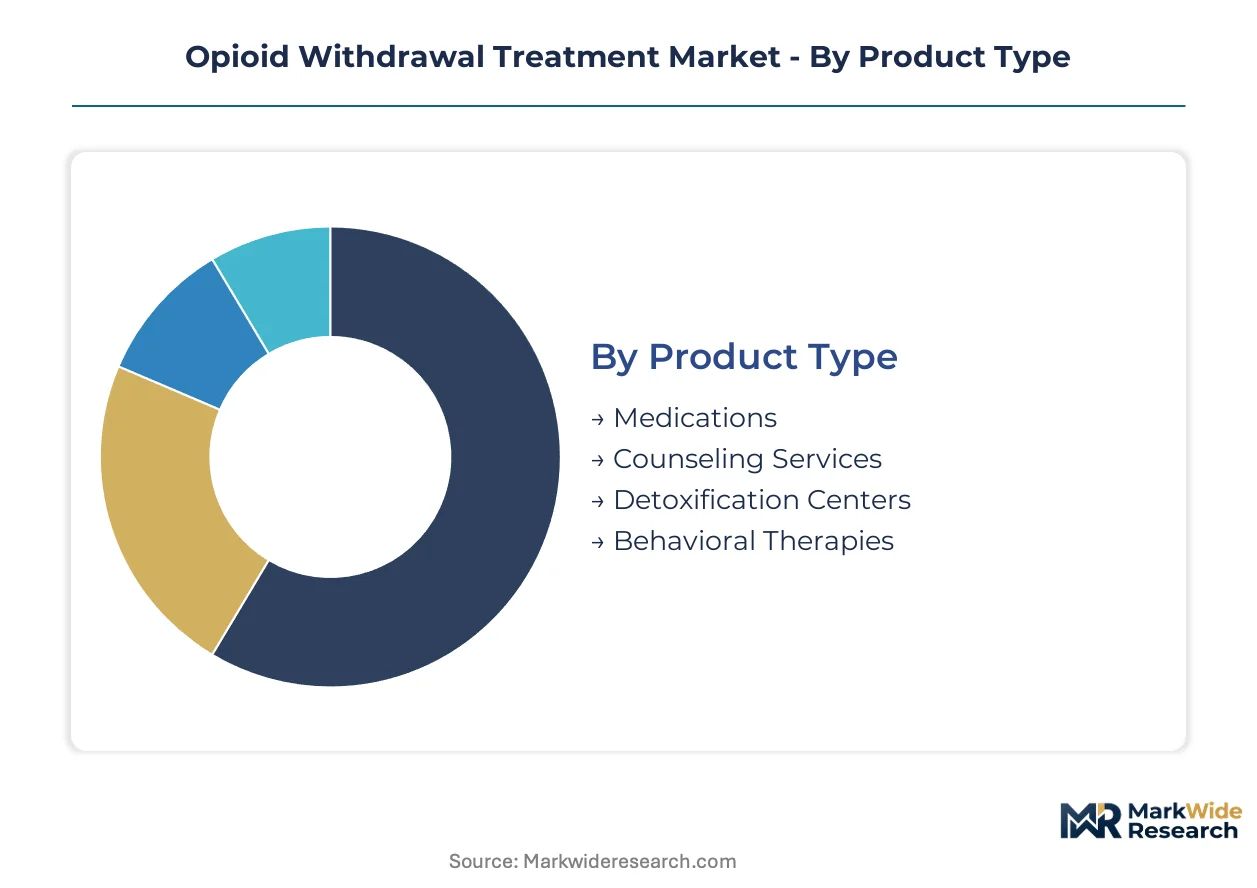
Opioid withdrawal treatment market segmentation reveals distinct margin architectures across product categories and delivery channels. Understanding these structural differences enables targeted resource allocation for manufacturers, providers, and payers navigating FDA REMS constraints and Medicaid reimbursement variability.
Product Type:
Patent-protected medication formulations command the deepest margin pools, while service-based segments compete on volume throughput and payer contract breadth.
- Medications:Buprenorphine and naltrexone formulations dominate revenue concentration, with extended-release injectable variants capturing premium pricing through reduced dosing frequency. Demand concentrates in United States Medicaid expansion states where formularies cover medication-assisted treatment without prior authorization barriers.
- Counseling Services:Licensed clinical social workers and addiction counselors deliver structured psychosocial interventions, typically bundled with pharmacological protocols. Reimbursement rates vary sharply across state Medicaid programs, creating geographic margin disparities that favor states with mental health parity legislation.
- Detoxification Centers:Acute residential facilities manage severe withdrawal episodes under medical supervision.
- Behavioral Therapies:Evidence-based modalities including contingency management and motivational interviewing.
The dominant share belongs to Medications, while Telehealth-integrated Counseling Services is closing the gap fastest.
Delivery Mode:
Channel economics diverge sharply between capital-intensive inpatient infrastructure and scalable virtual platforms.
- Telehealth:Synchronous video platforms enable initial buprenorphine evaluation and maintenance therapy without geographic proximity requirements. DEA scheduling exemptions for remote prescribing of controlled substances have permanently expanded prescriber reach into rural counties and carceral settings previously classified as access deserts.
- In-Patient:Hospital-based detoxification protocols require 24-hour medical monitoring and specialized nursing staff. These facilities concentrate in metropolitan corridors with addiction medicine specialist density, limiting penetration in underserved regions despite highest per-episode reimbursement rates.
- Out-Patient:Opioid Treatment Programs deliver structured medication-assisted treatment on a visit-based schedule.
- Home-Based Treatment:Mobile health teams and visiting nurse services extend care into residential settings.
In-Patient retains the highest revenue per encounter, though Telehealth is expanding most quickly across state lines where licensure compacts permit.
End User:
Institutional procurement patterns favor integrated health systems with electronic health record interoperability and bundled payment contracts.
- Hospitals:Emergency departments serve as critical entry points for acute withdrawal management, with expanding intake protocols creating institutional demand for pharmacological interventions. Hospital systems in states with mature Medicaid managed care contracts increasingly embed medication-assisted treatment navigators to reduce readmission penalties.
- Rehabilitation Facilities:Residential and intensive outpatient programs combine pharmacological support with structured therapeutic environments. These facilities compete for in-network status with commercial payers and Medicaid managed care organizations, with accreditation from the Substance Abuse and Mental Health Services Administration serving as a prerequisite for federal funding eligibility.
- Mental Health Clinics:Community-based settings integrate addiction treatment with psychiatric services.
- Private Practices:Individual prescribers with FDA REMS certification deliver office-based buprenorphine maintenance.
Hospitals anchor institutional volume, while Rehabilitation Facilities are gaining share fastest through Medicaid managed care network expansion.
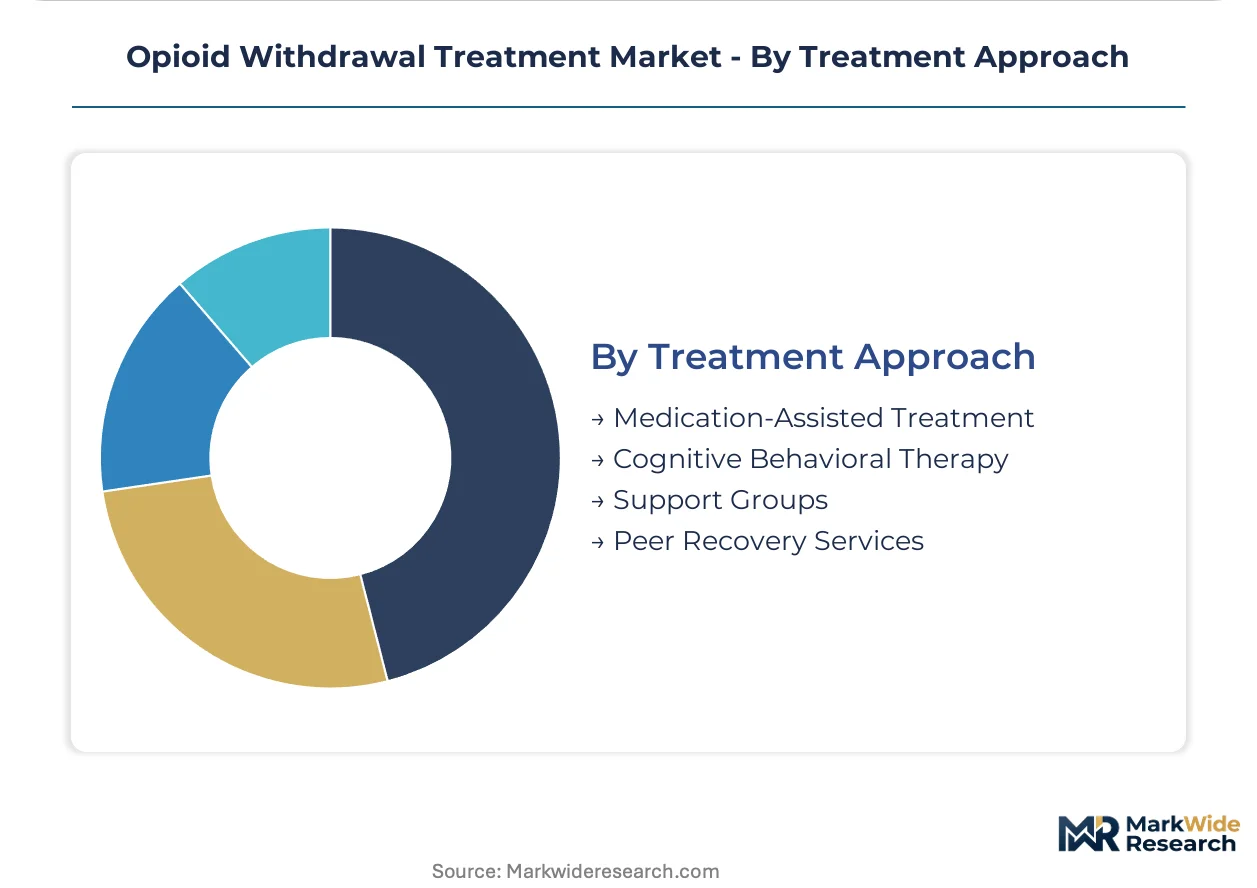
Treatment Approach:
Reimbursement structures increasingly favor combined pharmacological and behavioral protocols over standalone interventions.
- Medication-Assisted Treatment:FDA-approved buprenorphine, methadone, and naltrexone protocols reduce withdrawal severity and block euphoric effects. United States demand concentrates in Federally Qualified Health Centers and correctional health systems adopting monthly depot injections to minimize diversion risk and improve adherence metrics.
- Cognitive Behavioral Therapy:Structured psychotherapy targets maladaptive thought patterns and relapse triggers. Digital delivery platforms and telehealth integration expand reach among working-age populations seeking discrete access outside traditional clinic hours.
- Support Groups:Peer-led facilitation models including 12-step and alternative mutual aid frameworks.
- Peer Recovery Services:Certified peer specialists with lived experience provide navigation and coaching support.
Medication-Assisted Treatment holds the dominant share, while Peer Recovery Services is climbing the fastest through state Medicaid benefit expansions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns for opioid withdrawal treatment diverge sharply across geographies, with the United States emphasizing medication-assisted maintenance therapy through Medicaid-funded programs while European systems prioritize integrated harm-reduction services and hospital-based detoxification protocols.
United States
Medicaid expansion in 40 states now reimburses buprenorphine and naltrexone formulations without prior authorization barriers. FDA REMS certification requirements for prescribers create geographic access deserts in rural counties, though DEA telehealth exemptions permanently expanded remote prescribing capacity. Federally Qualified Health Centers in Appalachian regions and Southwestern border states deploy hybrid care models combining virtual evaluation with mobile health team follow-up.
Germany
Hospital-based detoxification protocols dominate acute withdrawal management, with statutory health insurance covering extended inpatient stays for severe cases. EMA guidelines on opioid substitution therapy shape federal reimbursement policies for methadone and buprenorphine maintenance. Industrial pharmaceutical clusters in North Rhine-Westphalia and Bavaria manufacture generic formulations serving domestic and export markets across Central Europe.
United Kingdom
National Health Service formularies emphasize long-acting injectable buprenorphine to reduce pharmacy transaction frequency and diversion risk. NHS England's Medicines Optimisation Programme mandates adherence monitoring through electronic health record integration. London-based academic medical centers and Manchester's specialized addiction services pilot depot injection protocols for correctional health transitions.
Canada
Provincial health authorities in British Columbia and Ontario operate supervised consumption sites that integrate withdrawal management with immediate pharmacological intervention. Health Canada expedited review pathways for novel buprenorphine formulations address the ongoing public health emergency declaration. Vancouver's Downtown Eastside and Toronto's inner suburbs concentrate specialized addiction medicine capacity.
Australia
Pharmaceutical Benefits Scheme subsidies for opioid substitution therapy require prescriber accreditation through state-based addiction medicine colleges. TGA scheduling classifications for partial agonists impose pharmacy dispensing constraints that limit retail channel penetration. Sydney's specialized opioid treatment programs and Melbourne's community health centers anchor service delivery in southeastern population corridors.
Opioid Withdrawal Treatment Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with large pharmaceutical manufacturers leveraging established distribution networks while focused developers concentrate on formulation science and delivery mechanism patents. The market structure rewards vertical integration into active pharmaceutical ingredient sourcing and cold-chain logistics capabilities. Two dominant strategic archetypes emerge: diversified manufacturers with broad CNS portfolios, and pure-play addiction therapy specialists with concentrated buprenorphine expertise. Competitive moves center on extended-release formulation development and telehealth platform partnerships that expand prescriber reach beyond traditional clinic footprints.
Within the pure-play specialist tier, Indivior PLC and Alkermes PLC exemplify contrasting strategic positions—one anchored in sublingual and injectable buprenorphine portfolios, the other differentiated through extended-release naltrexone manufacturing capabilities. Among diversified pharmaceutical manufacturers, Teva Pharmaceutical Industries Ltd. occupies a position representing generic formulation scale and international distribution breadth. These three entities collectively illustrate the competitive tension between patent-protected delivery mechanisms and volume-driven generic substitution pressures that define margin architecture across product categories.
| Leading Market Players |
|---|
| Indivior PLC |
| Alkermes PLC |
| Teva Pharmaceutical Industries Ltd. |
| Pfizer Inc. |
| Orexo AB |
| BioDelivery Sciences International Inc. |
| Mallinckrodt Pharmaceuticals |
| Hikma Pharmaceuticals |
| Sun Pharmaceutical Industries |
| Others |
Value Chain & Pricing Dynamics
Sixty-to-ninety-day cold-chain inventory cycles for extended-release buprenorphine injectables concentrate pricing power with manufacturers possessing captive distribution networks, while DEA scheduling requirements for partial agonists impose carrying-cost premiums that amplify margin stratification across formulation tiers.
Pricing Analysis
Long-term offtake agreements between Medicaid managed care organizations and depot-injection manufacturers dominate the contract landscape, though spot procurement persists for acute detoxification protocols. Price differentiation hinges on FDA REMS certification tier and volume-scale commitments, with Federally Qualified Health Centers commanding steeper discounts than private rehabilitation networks. Cost compression in oral generic buprenorphine intensifies as Indian and Chinese API suppliers expand capacity, eroding margin pools for non-differentiated formulations. Hospital systems exhibit lowest price sensitivity due to bundled reimbursement structures, while individual prescribers face highest sensitivity from thin Medicaid fee schedules.
Supply Chain Analysis
Just-in-time inventory strategies prevail among retail pharmacy chains handling sublingual tablets, whereas strategic stockpiling characterizes Opioid Treatment Programs securing monthly depot injections to mitigate cold-chain disruption risks. Active pharmaceutical ingredient production draws from India, China, and the United States, with norbuprenorphine base material sourcing concentrated in Gujarat and Zhejiang manufacturing clusters. Single-source vulnerability permeates the extended-release injectable segment where proprietary polymer technologies anchor in Alkermes and Indivior manufacturing facilities. Distribution runs through specialty pharmaceutical wholesalers with controlled-substance licensing, bypassing conventional retail channels for depot formulations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle expansion as DEA telehealth prescribing exemptions permanently expand prescriber reach beyond traditional clinic footprints, accelerating penetration into rural access deserts previously unserved by waivered providers.
For Market Incumbents: Compound formulation patent defenses through next-generation depot delivery mechanisms while securing DEA-registered manufacturing capacity expansion in Appalachian and Southwestern distribution corridors. Generic substitution pressure from Teva and Hikma threatens margin pools in oral buprenorphine segments, demanding backward integration into active pharmaceutical ingredient sourcing to preserve cost position. For New Entrants and Emerging Players: Anchor in Federally Qualified Health Center partnerships across Medicaid expansion states, where reimbursement authorization for telehealth-integrated medication-assisted treatment remains underpenetrated relative to metropolitan OTP density. Rural counties with addiction medicine specialist scarcity present the most penetrable geography, with direct-to-clinic digital scheduling platforms offering the clearest go-to-market angle against incumbent referral-network dependencies. For Investors and Strategic Acquirers: Carve-out targets emerge from large pharmaceutical manufacturers retreating from central nervous system portfolios, particularly divisions with dormant buprenorphine formulation assets and established FDA REMS infrastructure. Long-term viability hinges on regulatory moat sustainability around extended-release injectable patents and telehealth platform integration capabilities. Watch DEA scheduling reclassification proceedings for partial agonists as the critical inflection signal for channel economics disruption.| Strategic Initiative | Industry Significance |
|---|---|
| Extended-Release Formulation Development | Long-acting injectable buprenorphine and naltrexone depot technologies reduce dosing frequency and improve adherence metrics in OTP settings. |
| Telehealth Platform Integration | Synchronous video evaluation capabilities expand prescriber reach into rural counties and carceral settings under DEA exemptions. |
| Backward Integration into API Sourcing | Captive norbuprenorphine production insulates margin pools from Indian and Chinese generic API pricing volatility. |
| Medicaid Managed Care Contracting | In-network status with state Medicaid programs secures volume throughput for medication-assisted treatment reimbursement. |
| FDA REMS Certification Expansion | Waivered prescriber training programs build prescriber density in underserved geographic corridors facing access deserts. |
Study Parameters
Cross-validation between formulary database audits and FDA REMS prescriber registry data anchors the qualitative findings, with primary interviews conducted among addiction medicine specialists, Medicaid pharmacy directors, OTP clinical directors, and DEA-registered wholesale distributors. Secondary sources include FDA Orange Book filings, CMS Medicare Part D claims extracts, state Medicaid managed care contract documents, and SAMHSA Opioid Treatment Program certification records. Bottom-up patient-volume estimates from OTPs and Federally Qualified Health Centers triangulate against top-down pharmaceutical shipment data from wholesalers.
Sensitivity analysis around DEA telehealth prescribing rule permanence and Medicaid expansion state enrollment trajectories informs the analytical framework across the projection horizon. Segmentation dimensions encompass product formulation, delivery mode, end-user institution type, and regional regulatory cluster. CAGRs derive from modeled patient-volume growth rates applied to per-patient medication and service expenditure benchmarks, with extended-release injectable adoption curves and telehealth penetration rates serving as key forecast inputs.
Underlying assumptions cover DEA scheduling stability for partial agonists and Medicaid reimbursement parity for behavioral therapy adjuncts, with deviation risk concentrated in federal telehealth prescribing restrictions and state-level formulary exclusions. Revision becomes warranted when DEA scheduling reclassification or federal telehealth waiver expiration crosses implementation thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Addiction Treatment
Substance Abuse Treatment Market
Addiction Treatment
Opioid Use Disorder (OUD) Market
Addiction Treatment
Cocaine Intoxication Treatment Market
Addiction Treatment
US Ketamine Clinics Market
Addiction Treatment
Opioid Use Disorder Treatment Market
Addiction Treatment
Methadone Market
Addiction Treatment
Opioid Induced Constipation Treatment Market
Addiction Treatment
Alcohol Use Disorder Treatment Market
Addiction Treatment
Nicotine De-Addiction Products Market
Addiction Treatment
Global Substance Use Disorder Treatment Market
Addiction Treatment
US Mental Health and Addiction Treatment Centers Market
Addiction Treatment
Global Addiction Treatment Market
Addiction Treatment
Smokeless Tobacco Treatment Market
Addiction Treatment
Drug Free Depression Treatment Market