
 Global Oral Cancer Rapid Test Kit Market | 2026-2036
Global Oral Cancer Rapid Test Kit Market Size, Share, and Industry Trends Forecast 2026-2036
Global Oral Cancer Rapid Test Kit Market Foresight
ISO 13485 certification is reorganizing competitive standing in the oral cancer rapid test kit landscape by mandating quality management systems for medical device manufacturers. Abbott Laboratories leverages extensive diagnostic infrastructure to sustain broad distribution reach across hospital networks and reference labs. Thermo Fisher Scientific anchors its position through deep molecular biology expertise applied to polymerase chain reaction-based detection platforms. Vigilant Biosciences specializes in salivary biomarker technology, differentiating through non-invasive screening approaches that reduce patient reluctance.
Oral cancer rapid test kits are in vitro diagnostic devices designed to detect malignant or premalignant conditions affecting the oral cavity through biomarker analysis in saliva, blood, or tissue specimens, typically delivering results within fifteen to sixty minutes without centralized laboratory processing. Saliva-based kits command widening clinical preference due to minimal patient discomfort and simplified collection logistics that enable chair-side deployment. Immunoassay technology leads current commercial volume while fluorescence imaging segments attract premium positioning through enhanced specificity in diagnostic confirmation applications. Early detection applications generate the strongest growth trajectory as healthcare systems prioritize stage-one intervention economics over late-stage treatment costs.
FDA premarket notification requirements under the 21st Century Cures Act govern United States market access, while EMA's In Vitro Diagnostic Regulation mandates performance validation standards across European Union member states. Japan's PMDA enforces stringent clinical evidence thresholds that filter entrants but reward compliant manufacturers with stable reimbursement pathways. Stakeholders must monitor evolving harmonization between national regulatory frameworks and WHO prequalification criteria to anticipate competitive access shifts.
Market Dynamics
Point-of-care screening protocols are compressing diagnostic timelines and forcing test kit manufacturers to prioritize chair-side compatibility over laboratory-grade complexity. This structural shift privileges saliva-based collection methods and fifteen-minute result windows over traditional histopathology workflows.
Growth Catalysts
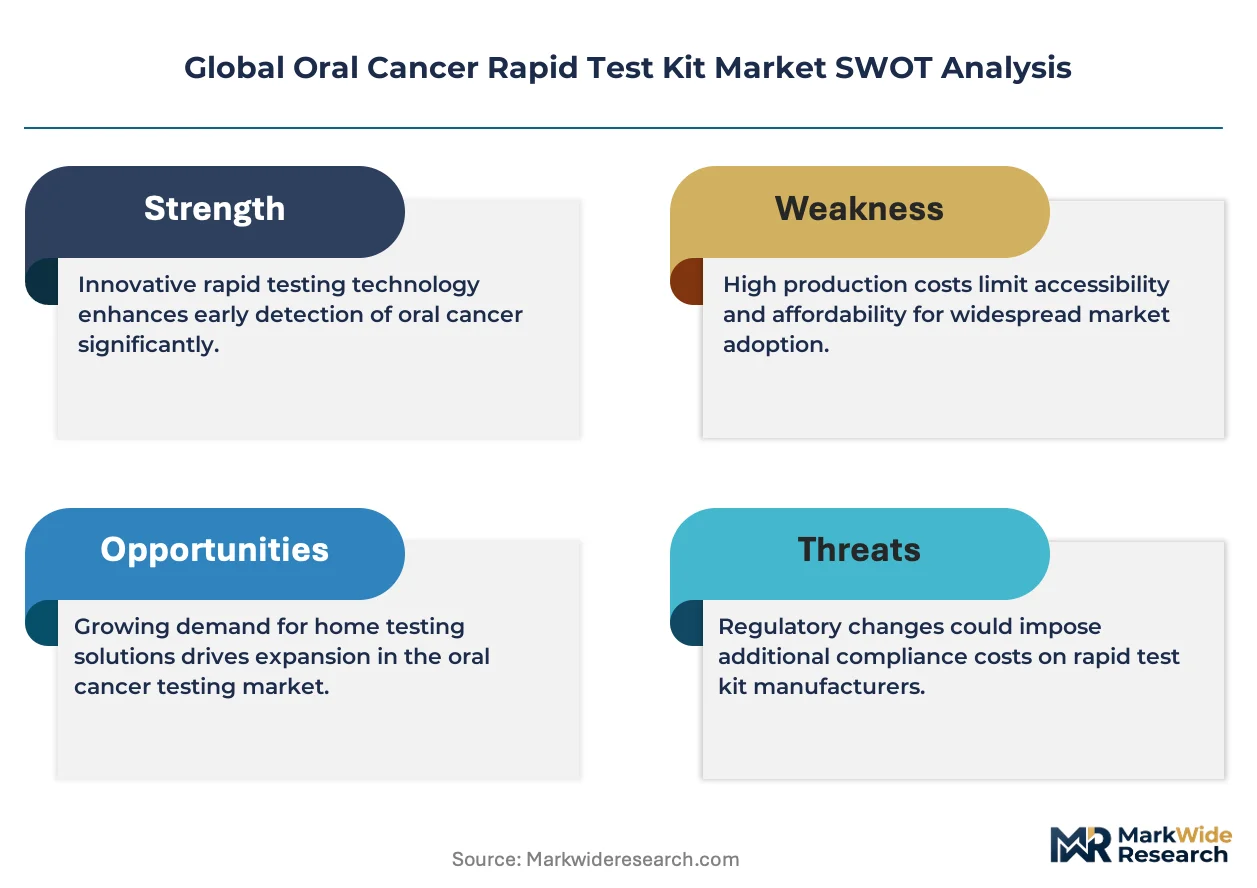
- Japan's PMDA reimbursement pathways:Stable coverage for compliant manufacturers accelerates clinical adoption in aging populations with elevated oral cancer incidence.
- Fluorescence imaging technology:Enhanced specificity in diagnostic confirmation applications drives premium positioning among dental specialists seeking visual tissue differentiation.
- Tobacco-use surveillance programs:Government-mandated screening in Germany and the United States creates institutional procurement volume for preventive care protocols.
Market Restraints
- EMA In Vitro Diagnostic Regulation compliance costs:Performance validation standards across EU member states impose capital-intensive documentation burdens on mid-scale manufacturers.
- Reagent supply concentration:Fluorescent dye and antibody production clusters in specialized chemical suppliers create input vulnerability.
- Histopathology substitution persistence:Tissue biopsy remains the diagnostic gold standard, limiting rapid test penetration in oncology referral networks.
Strategic Opportunities
- India's CDSCO streamlined medical device pathways:Emerging regulatory clarity opens access to a population with rising tobacco consumption and limited specialist density.
- Tele-dentistry integration:Remote consultation platforms create demand for patient-collected saliva specimens shipped to decentralized processing nodes.
- AI-assisted image interpretation convergence:Machine learning algorithms paired with fluorescence imaging reduce specialist interpretation dependency.
Industry Challenges
- ISO 13485 certification timelines:Quality management system implementation delays product launch schedules by twelve to eighteen months for new entrants.
- Biomarker stability engineering:Salivary protein degradation during ambient temperature transport requires reformulation investment and cold-chain alternatives.
- Legacy ELISA workflow integration:Hospital laboratories resist parallel infrastructure for rapid immunoassays when centralized analyzers already handle high-throughput screening.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Oral Cancer Rapid Test Kit Market |
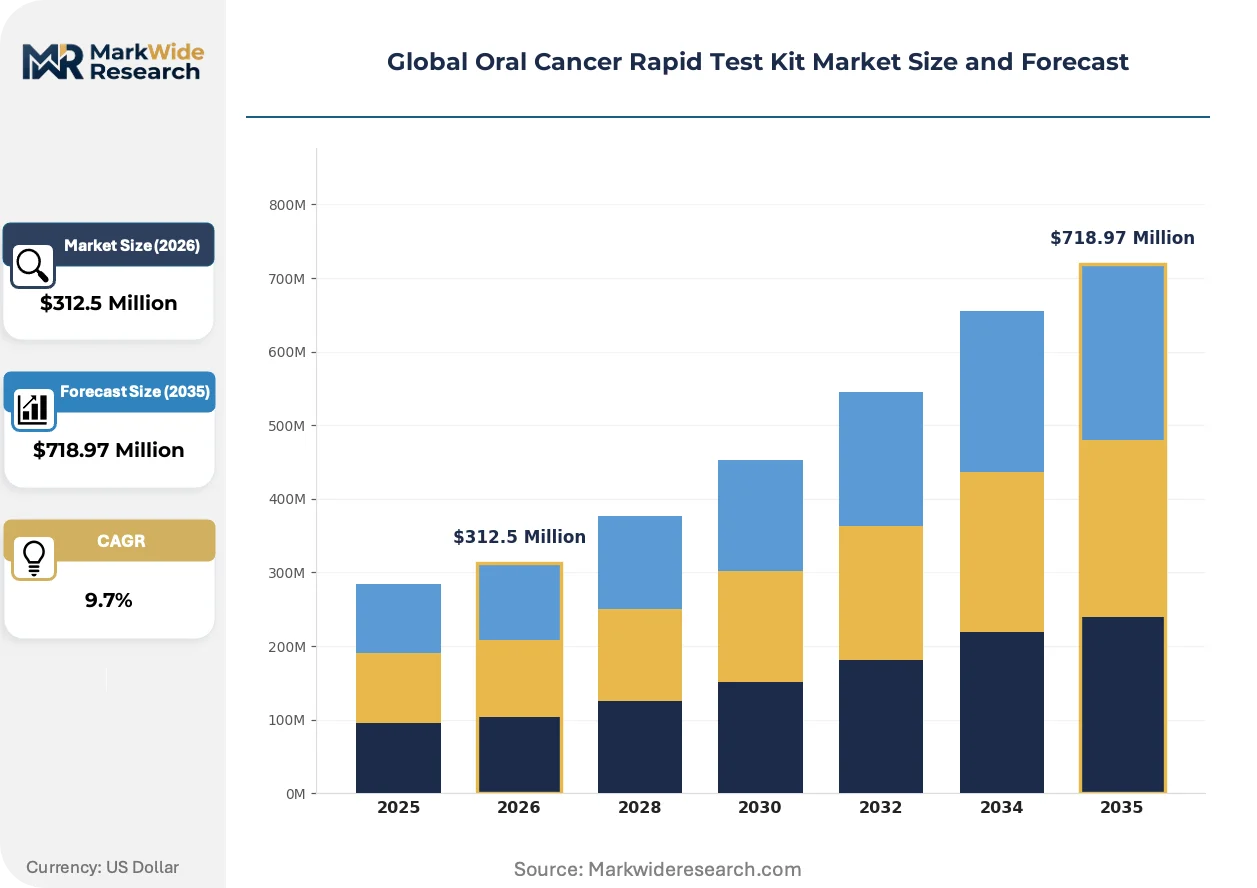
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $718.97 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Saliva-Based Kits, Blood-Based Kits, Tissue-Based Kits, Breath Analyzers Technology: Immunoassay, Enzyme-Linked Immunosorbent Assay, Polymerase Chain Reaction, Fluorescence Imaging Application: Early Detection, Screening, Diagnostic Confirmation, Post-Treatment Monitoring End User: Dental Clinics, Diagnostic Laboratories, Cancer Research Institutes, Home Healthcare Providers |
| Companies Covered | Abbott Laboratories, Becton Dickinson, Thermo Fisher Scientific Inc., Trinity Biotech plc, Viome Life Sciences, Inc., WanTai BioPharm, Quest Diagnostics Incorporated, Siemens Healthineers, Vigilant Biosciences, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Oral Cancer Rapid Test Kit Market Shifts & Advancements
Biomarker detection platforms are converging with digital health infrastructure, creating diagnostic ecosystems where test results feed directly into electronic health records and population surveillance databases.
Lateral flow immunoassay cartridges are miniaturizing. These devices integrate sample collection, reagent storage, and signal generation into single-use cassettes weighing under ten grams. Dental clinics in the United States and Germany are adopting them for same-visit screening protocols. The technology is miniaturizing equipment footprints and eliminating centrifugation steps previously required for saliva processing.
EMA's In Vitro Diagnostic Regulation is tightening clinical evidence requirements for self-declared devices. Manufacturers must now submit prospective performance studies rather than retrospective analytical validations. Class B and C rapid test kits face extended notified body review cycles, compressing competitive windows for first-movers in fluorescence imaging segments.
Group purchasing organizations are consolidating procurement decisions for oral cancer screening supplies across multi-clinic dental networks. Independent practitioners in Japan and the United States increasingly delegate supply selection to centralized purchasing cooperatives. This concentration privileges vendors with ISO 13485 certification and multi-year volume contracts over smaller specialists lacking compliance infrastructure.
Global Oral Cancer Rapid Test Kit Market Segmentation
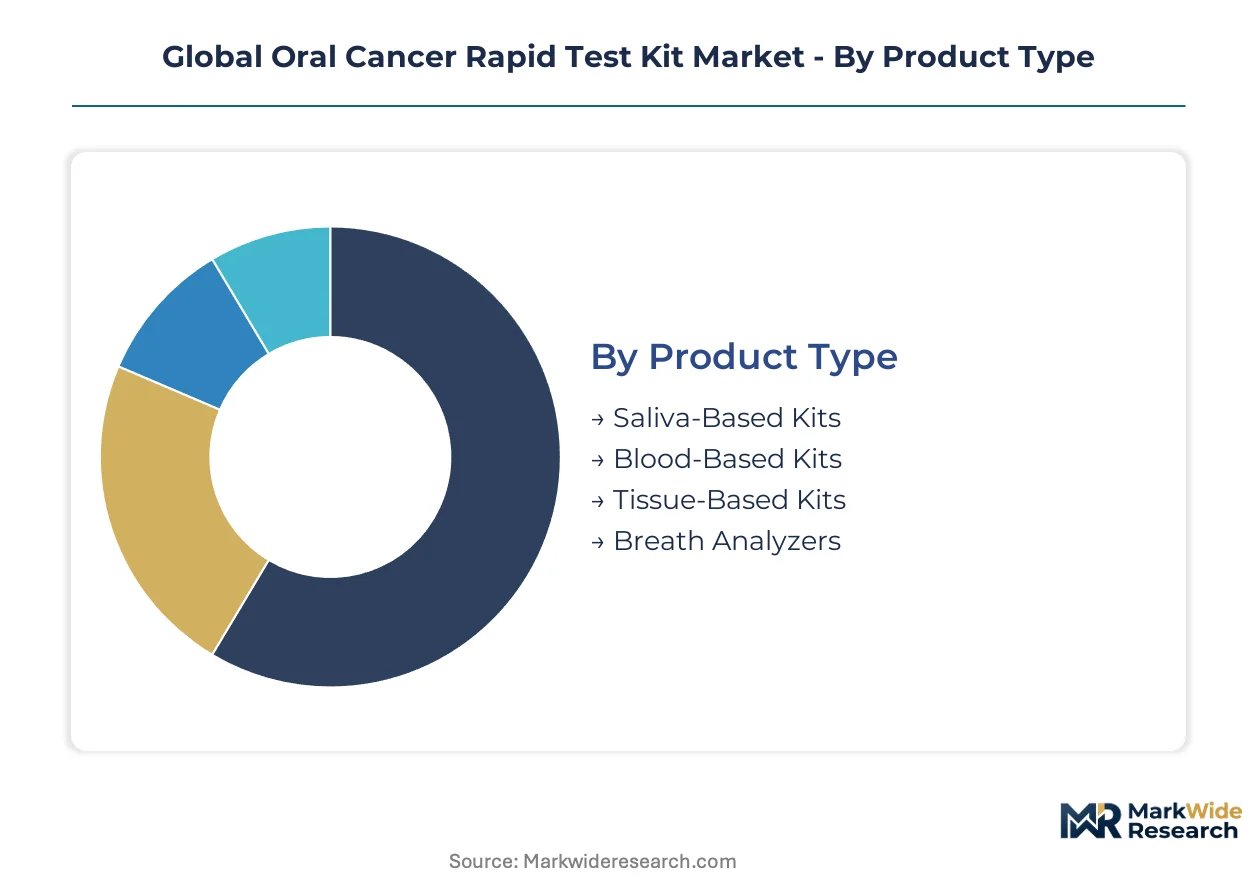
Segmentation in the oral cancer rapid test kit market reveals how product design choices determine channel economics and reimbursement pathways. Each dimension—specimen source, detection chemistry, clinical use case, and care setting—creates distinct margin profiles and regulatory requirements that shape manufacturer strategy.
Product Type:
Saliva-based collection dominates dental clinic procurement, while blood and tissue specimens flow primarily through hospital-affiliated laboratories and oncology networks.
- Saliva-Based Kits:Non-invasive collection devices capture oral fluid for biomarker analysis without needles or tissue extraction. Dental clinics in the United States and Japan favor these for same-visit screening protocols where patient compliance determines program success. Chair-side deployment eliminates centrifugation steps and reduces specialist referral bottlenecks.
- Blood-Based Kits:Serum or plasma specimens enable circulating tumor marker detection with established clinical validation frameworks. Diagnostic laboratories in Germany integrate these into existing phlebotomy workflows, leveraging high-throughput analyzers already deployed for other cancer panels. Reimbursement coding clarity accelerates institutional adoption compared to novel specimen types.
- Tissue-Based Kits:Exfoliative cytology or brush biopsy specimens target cellular morphology assessment. Oral surgery departments use these when visual inspection reveals suspicious lesions requiring immediate sampling.
- Breath Analyzers:Volatile organic compound detection via exhaled breath offers non-invasive metabolic profiling. Research settings pilot these for population-scale screening feasibility studies.
By volume, Saliva-Based Kits lead. By growth pace, Breath Analyzers are expanding most quickly.
Technology:
Detection chemistry determines capital requirements, operator training depth, and result specificity—factors that segment customer bases between resource-constrained clinics and reference laboratories.
- Immunoassay:Antibody-antigen binding reactions on lateral flow strips deliver qualitative results within fifteen minutes without instrumentation. Dental clinics across Japan deploy these for point-of-care screening where equipment minimalism controls overhead costs. Single-use cassettes eliminate maintenance contracts and calibration schedules.
- Fluorescence Imaging:Tissue autofluorescence visualization distinguishes dysplastic from healthy mucosa through wavelength-specific light excitation. Specialist dental practices in Germany adopt these for enhanced specificity in diagnostic confirmation, commanding premium fees for visual differentiation capabilities that reduce unnecessary biopsies.
- Enzyme-Linked Immunosorbent Assay:Colorimetric signal amplification in microplate formats enables quantitative biomarker measurement. Hospital laboratories prefer these for standardized throughput on existing absorbance readers.
- Polymerase Chain Reaction:Nucleic acid amplification detects genetic mutations with analytical sensitivity exceeding protein-based methods. Cancer research institutes utilize these for biomarker discovery and clinical trial stratification.
Immunoassay commands the largest installed base. Fluorescence Imaging gains share fastest among upgrade cycles.
Application:
Clinical use case dictates reimbursement tier, with preventive screening attracting population health budgets while post-treatment monitoring draws oncology service lines.
- Early Detection:Asymptomatic screening protocols target stage-one identification when treatment costs and morbidity remain lowest. Tobacco-use surveillance programs in the United States and Germany mandate these applications, creating institutional procurement volume through public health allocations rather than fee-for-service billing.
- Diagnostic Confirmation:Adjunctive testing following visual suspicious findings reduces false-positive biopsy rates. Oral and maxillofacial surgery departments integrate these to prioritize histopathology resources for highest-probability cases.
- Screening:Routine surveillance of high-risk cohorts—tobacco users, heavy alcohol consumers, betel nut chewers—generates recurring test demand. Occupational health programs in manufacturing sectors with chemical exposure risks pilot these protocols.
- Post-Treatment Monitoring:Surveillance for recurrence following surgical or radiation therapy requires longitudinal biomarker tracking. Oncology networks schedule these at three-to-six-month intervals, creating predictable reagent consumption patterns.
Early Detection generates the highest absolute volume. Diagnostic Confirmation captures the steepest margin expansion.
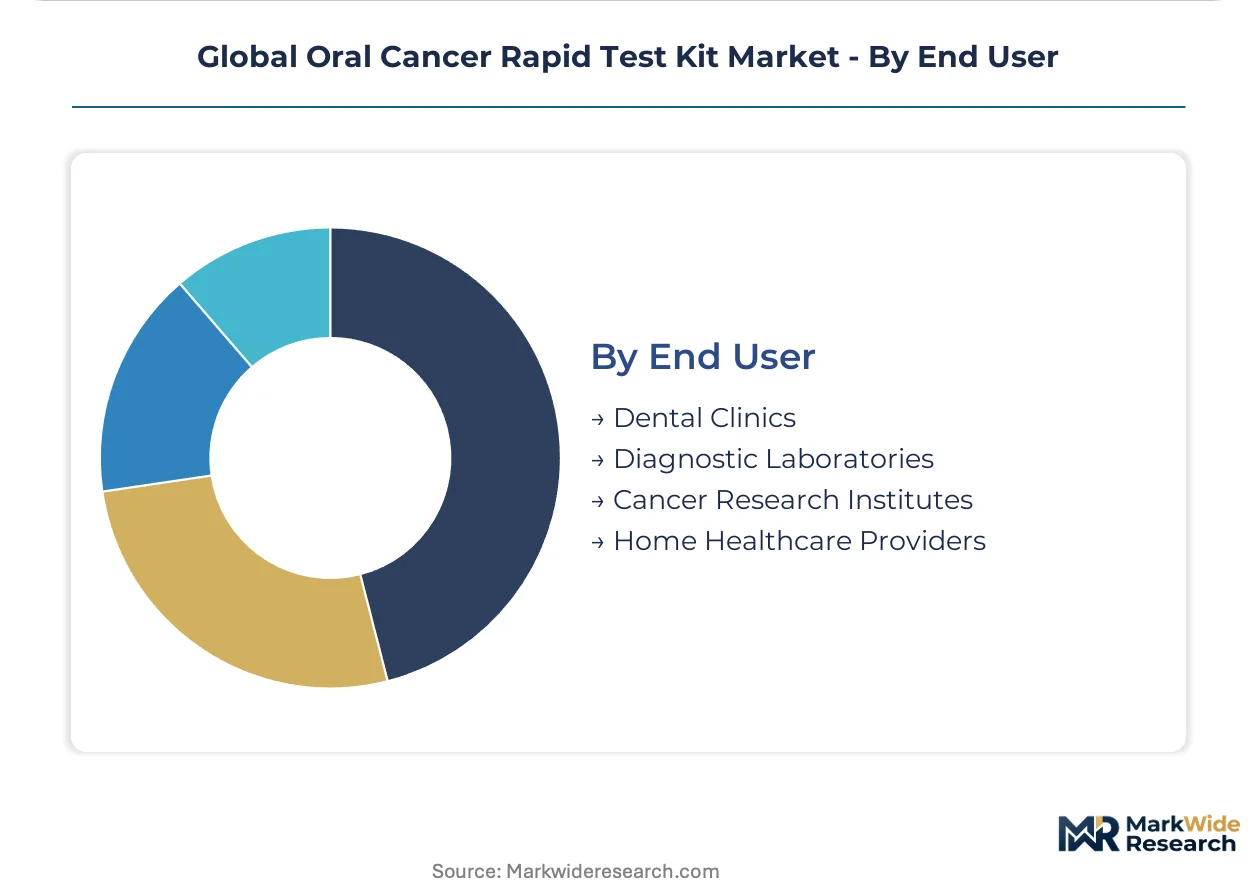
End User:
Customer type segments by procurement sophistication, with centralized purchasing cooperatives dominating multi-site networks and independent practitioners retaining individual vendor relationships.
- Dental Clinics:General and specialist dental practices represent the primary deployment channel for point-of-care protocols. Group purchasing organizations in the United States consolidate supply decisions across multi-clinic networks, privileging vendors with ISO 13485 certification and multi-year volume contracts.
- Diagnostic Laboratories:Reference laboratories and hospital pathology departments handle complex specimens requiring centralized processing. EMA In Vitro Diagnostic Regulation compliance documentation becomes a procurement gate, filtering mid-scale manufacturers lacking notified body certifications.
- Cancer Research Institutes:Academic medical centers and dedicated oncology research facilities drive technology validation and biomarker discovery. These customers prioritize analytical performance over cost minimization, funding pilot studies that establish clinical evidence for broader adoption.
- Home Healthcare Providers:Remote patient monitoring services and tele-dentistry platforms create demand for patient-collected specimens shipped to decentralized processing nodes. India's CDSCO streamlined pathways attract manufacturers targeting this emerging channel.
Dental Clinics account for the largest test volume. Home Healthcare Providers are climbing the fastest as tele-dentistry infrastructure matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA premarket notification pathways and Japan's PMDA reimbursement frameworks are accelerating point-of-care adoption in aging populations. Germany's tobacco-use surveillance mandates and India's CDSCO streamlined medical device registrations are expanding addressable patient pools across distinct regulatory environments.
United States
Tobacco-use surveillance programs in industrial states generate institutional procurement volume for preventive screening protocols. FDA 510(k) clearance requirements under the 21st Century Cures Act shape product development timelines and clinical evidence standards. Dental clinic networks in California and Texas are consolidating purchasing decisions through group purchasing organizations that privilege ISO 13485-certified suppliers.
Germany
Government-mandated occupational health screening for chemical exposure risks drives demand in manufacturing-heavy regions. EMA In Vitro Diagnostic Regulation compliance documentation filters mid-scale manufacturers from hospital laboratory procurement lists. The Baden-Württemberg medical technology cluster anchors fluorescence imaging device development for specialist dental practices seeking enhanced diagnostic specificity.
Japan
Aging demographics with elevated oral cancer incidence intensify screening requirements across prefectural health systems. PMDA stable reimbursement pathways reward compliant manufacturers with predictable revenue streams in the Kanto region. Tokyo-based dental clinic chains are deploying saliva-based rapid tests for same-visit screening protocols that minimize patient referral friction.
India
Rising tobacco consumption in northern and central states expands the high-risk cohort addressable by non-invasive screening. CDSCO streamlined medical device registration pathways reduce time-to-market for manufacturers targeting tele-dentistry integration. The Maharashtra pharmaceutical manufacturing corridor is attracting test kit producers seeking cost-competitive reagent supply chains for export markets.
United Kingdom
NHS long-term plan commitments to early cancer detection are redirecting primary care budgets toward point-of-care diagnostics. MHRA post-Brexit regulatory autonomy is converging toward EMA standards while maintaining distinct notified body relationships. London and Southeast England dental practice networks are piloting patient-collected saliva specimens for decentralized processing nodes.
Global Oral Cancer Rapid Test Kit Market Competitive Landscape
Player mix skews toward diversified diagnostic conglomerates with established regulatory affairs infrastructure and specialized biomarker technology developers. Market structure concentrates around three to five entities with full-stack quality management systems, while mid-scale entrants face twelve-to-eighteen-month ISO 13485 certification delays. Strategic archetypes include molecular biology platform extenders, salivary diagnostics specialists, and hospital laboratory supply incumbents. Dominant competitive moves encompass fluorescence imaging technology licensing partnerships and vertical integration into antibody production to secure reagent supply chains.
Among diversified diagnostic conglomerates, Abbott Laboratories and Thermo Fisher Scientific occupy positions that exemplify platform leverage strategies. Abbott's diagnostic infrastructure spans hospital networks and reference laboratories across multiple continents. Thermo Fisher anchors the polymerase chain reaction-based detection segment through deep molecular biology expertise. Vigilant Biosciences represents the specialized archetype, sitting within the salivary biomarker technology tier where non-invasive screening approaches reduce patient reluctance and enable chair-side deployment. Siemens Healthineers and Becton Dickinson exemplify hospital laboratory supply incumbents with existing procurement relationships that rapid test kit portfolios can extend.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Becton Dickinson |
| Thermo Fisher Scientific Inc. |
| Trinity Biotech plc |
| Viome Life Sciences, Inc. |
| WanTai BioPharm |
| Quest Diagnostics Incorporated |
| Siemens Healthineers |
| Vigilant Biosciences |
| Others |
Supply & Pricing Matrix
Fluorescent dye substitution for traditional enzymatic reagents is compressing input costs while shifting procurement geography toward specialized chemical suppliers in Germany and Japan. This input transition simultaneously elevates quality-tier pricing spreads and concentrates supplier negotiation leverage among ISO 13485-certified manufacturers with multi-year volume commitments.
Pricing Analysis
Certification level creates the primary spread between premium FDA-cleared kits and economy-tier self-declared devices. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 13485 compliance status, with dental clinics in the United States and Japan commanding steepest discounts through group purchasing organization consolidation. Pricing pressure stems from EMA In Vitro Diagnostic Regulation documentation burdens that inflate fixed costs for mid-scale entrants. Hospital laboratories exhibit lowest price sensitivity due to reimbursement clarity, while independent dental practitioners in India face acute cost compression.
Supply Chain Analysis
Germany and Japan anchor fluorescent dye and monoclonal antibody production for diagnostic reagents. The supply chain draws from Chinese chemical intermediates and Indian biologics manufacturing for lateral flow membrane substrates. Single-source vulnerability concentrates in specialized fluorophore suppliers serving fluorescence imaging segments. Distribution runs through group purchasing organizations in consolidated dental networks and direct-to-laboratory contracts for hospital systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents must defend against histopathology workflow persistence and liquid biopsy platform substitution that threaten rapid test kit volume expansion. The market rewards manufacturers who convert point-of-care screening protocols into durable procurement relationships before alternative modalities capture clinical mindshare.
For Market Incumbents: Compound regulatory affairs infrastructure to accelerate FDA 510(k) and EMA In Vitro Diagnostic Regulation parallel submissions, compressing competitive windows for fluorescence imaging segments. Deepen backward integration into antibody production to secure reagent supply chains against fluorescent dye concentration risk. Channel control through multi-year group purchasing organization contracts in the United States and Japan locks out emerging competitors lacking ISO 13485 certification infrastructure.
For New Entrants and Emerging Players: Tele-dentistry platform integration represents the most penetrable service-layer gap where incumbents under-serve patient-collected specimen workflows. India's CDSCO streamlined pathways offer lowest regulatory friction for manufacturers targeting home healthcare provider channels with saliva-based collection devices. A go-to-market angle anchored to AI-assisted image interpretation partnerships reduces specialist dependency and accelerates clinical validation timelines.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed salivary diagnostics specialists possessing FDA-cleared biomarker panels but limited distribution infrastructure. Long-term viability hinges on conversion of research-use-only platforms into clinical diagnostic claims with stable reimbursement pathways. The signal to watch is PMDA reimbursement expansion for chair-side screening protocols in Japan's prefectural health systems.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Parallel Submission | Dual-track FDA and PMDA filings compress regulatory timelines for point-of-care devices in aging markets. |
| Fluorescence Imaging Licensing | Technology partnerships with Baden-Württemberg optical specialists enhance diagnostic specificity for German dental practices. |
| Salivary Biomarker Discovery | Academic collaborations with Tokyo cancer research institutes validate novel protein signatures for stage-one detection. |
| Group Purchasing Organization Consolidation | Multi-year contracts with California and Texas dental networks lock in volume commitments against emerging competitors. |
| Tele-dentistry Platform Integration | Software companion development for Maharashtra-based remote consultation services opens patient-collected specimen channels. |
Research Methodology
A standing panel of diagnostic laboratory directors, dental clinic procurement managers, biomedical engineers, and regulatory affairs specialists provided ongoing calibration across primary interview rounds. Secondary validation drew from FDA 510(k) filings, EMA In Vitro Diagnostic Regulation notified body documentation, PMDA reimbursement databases, and hospital procurement records. Bottom-up test kit volume estimates triangulated against top-down addressable population screening models.
Consistency checks against external benchmarks validated volume and value outputs across the analysis window. Segmentation modeling incorporated specimen source, detection chemistry, clinical application, and care setting dimensions with regional regulatory cluster overlays. CAGRs derived from logistic diffusion curves fitted to point-of-care adoption patterns, with inputs including tobacco-use surveillance program expansion timelines and tele-dentistry infrastructure deployment rates.
Forecasts assume regulatory continuity in FDA premarket notification, EMA In Vitro Diagnostic Regulation, and PMDA reimbursement frameworks; material policy shifts would require re-modeling. Specific risks include ISO 13485 certification timeline delays, fluorescent dye supply disruptions, and histopathology gold standard persistence limiting rapid test penetration. Recalibration cycles align with material shifts in reimbursement pathway announcements and point-of-care protocol adoption rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Fertility Testing Devices Market
Diagnostics
Adenovirus Diagnostic Testing Market
Diagnostics
Food Allergy Diagnostics and Therapeutics Market
Diagnostics
Global Blood Transfusion Diagnostics Market
Diagnostics
United States Melanoma Diagnostics & Therapeutics Market
Diagnostics
Rapid Oral Fluid Screening Device Market
Diagnostics
Cellular Health Screening Market
Diagnostics
Asia Pacific Predictive Disease Analytics Market
Diagnostics
Global Comprehensive Metabolic Panel Market
Diagnostics
Global Meningitis Diagnostic Testing Market
Diagnostics
Global Chemiluminescence Immunoassay (CLIA) Market
Diagnostics
Asia-Pacific Radioimmunoassay Market
Diagnostics
Creatinine Test Market
Diagnostics
Global Hemoglobin A1c Testing Devices Market
Diagnostics
Chile in Vitro Diagnostics Market
Diagnostics
Glaucoma Diagnostics Market