
 Tonsil and Adenoid Removal Products Market | 2026-2036
Tonsil and Adenoid Removal Products Market Size, Share, and Industry Trends Forecast 2026-2036
Tonsil and Adenoid Removal Products Market Analytics
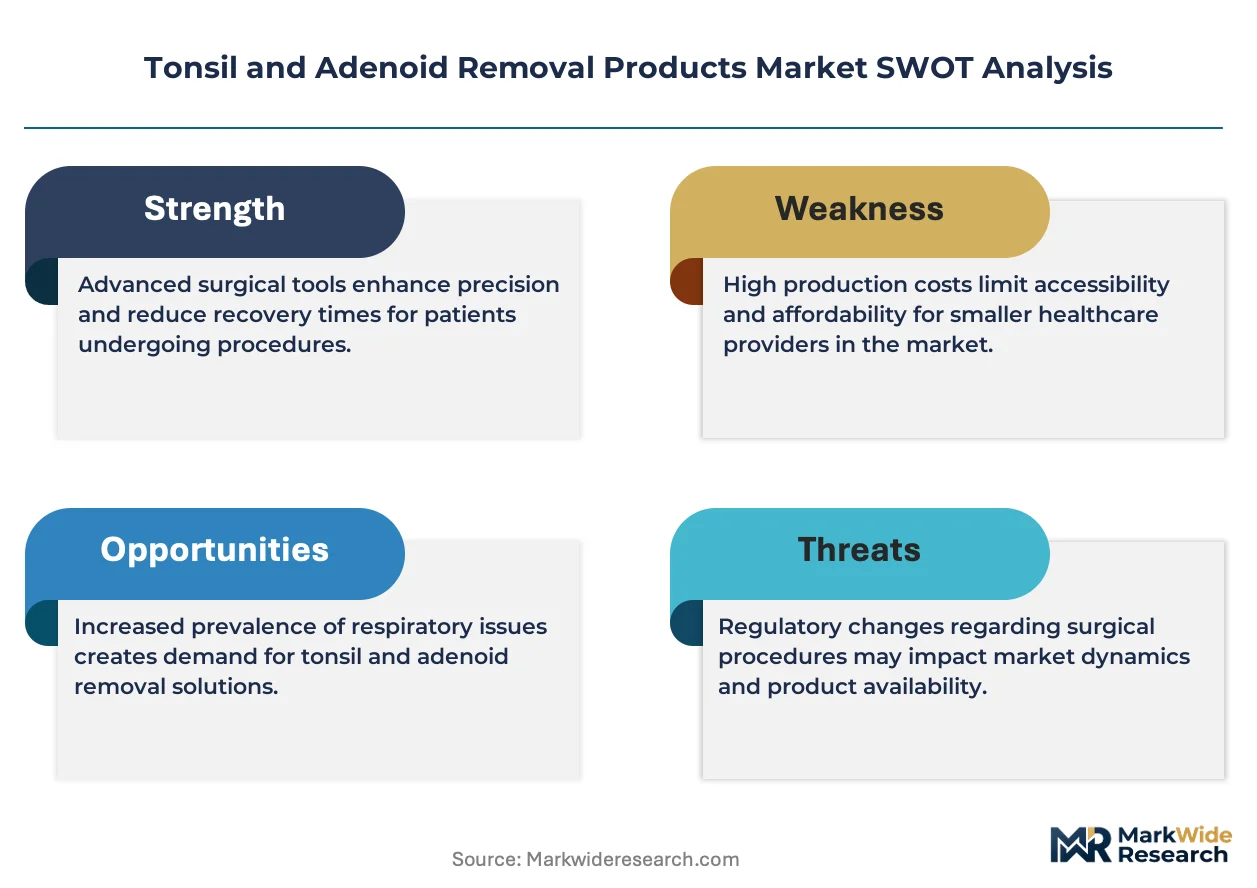
The premium electrosurgical device tier is rebalancing against commodity cold steel instruments as hospitals weigh capital costs against readmission risk. Medtronic leverages its integrated energy platform to sustain high-margin positions in radiofrequency tonsillectomy systems. Smith & Nephew competes on disposable blade economics, while Olympus Corporation anchors the visualization layer with rigid endoscopes optimized for pediatric airway anatomy.
Tonsil and adenoid removal products encompass instruments and energy devices designed for excision or ablation of lymphoid tissue in the oropharynx and nasopharynx, typically manufactured from surgical-grade stainless steel or biocompatible polymers with insulation ratings exceeding 3000V for electrosurgical variants. These products serve otolaryngologists and pediatric surgeons performing procedures to treat recurrent infection, sleep-disordered breathing, or hypertrophy. Electrosurgical devices command the widest installed base due to hemostatic efficiency during adenoidectomy, yet laser technology captures premium pricing in revision cases where precision limits collateral thermal injury. Radiofrequency systems represent the fastest-growing technology segment as outpatient surgery centers adopt coblation platforms that reduce thermal spread to surrounding musculosa.
FDA 510(k) premarket notification and ISO 13485 quality management standards govern device clearance and manufacturing consistency for tonsil and adenoid removal products in the United States, while the EU Medical Device Regulation imposes stricter clinical evidence requirements for reusable electrosurgical handpieces. These frameworks elevate compliance costs for entrants but protect incumbent positions for manufacturers with established predicate device portfolios and notified body relationships. Stakeholders must monitor evolving reimbursement codes for ambulatory tonsillectomy as payers scrutinize site-of-service cost differentials between hospital outpatient departments and freestanding surgery centers.
Market Dynamics
Radiofrequency ablation platforms are compressing thermal injury margins in pediatric airway surgery, forcing hospitals to recalculate capital deployment between disposable cold steel and reusable electrosurgical systems.
Growth Catalysts
- Ambulatory Surgery Center Expansion:United States payers align reimbursement codes with same-day discharge protocols, accelerating site-of-service migration away from hospital inpatient departments.
- FDA 510(k) Predicate Pathways:Established device portfolios enable faster clearance timelines for iterative radiofrequency handpiece improvements, rewarding manufacturers with deep submission histories.
- Pediatric Sleep-Disordered Breeding Protocols:Clinical societies tighten diagnostic thresholds for adenotonsillar hypertrophy, expanding addressable surgical volumes in otolaryngology practices.
Market Restraints
- Capital Equipment Intensity:Coblation console procurement requires six-figure outlays that strain freestanding surgery center budgets, privileging hospital outpatient departments with centralized purchasing power.
- EU MDR Clinical Evidence Burden:Stricter notified body requirements for reusable electrosurgical handpieces extend recertification timelines and elevate documentation costs for European market access.
- Laser Technology Substitution:Revision case precision requirements sustain demand for CO2 laser platforms despite higher per-procedure costs, fragmenting technology commitment among high-volume surgeons.
Strategic Opportunities
- India Outpatient Infrastructure:Tier-2 city surgical centers lack radiofrequency penetration, creating first-mover advantage for platform vendors willing to train local otolaryngology staff.
- Disposable Blade Economics:Smith & Nephew's single-use cold steel instruments demonstrate margin resilience against capital-intensive alternatives, suggesting white space for hybrid portfolio positioning.
- Visualization Integration:Olympus rigid endoscope compatibility with pediatric airway anatomy enables bundled system sales that lock in recurring blade and sheath revenues.
Industry Challenges
- Pediatric Airway Surgical Training:Narrower anatomical tolerances in children demand specialized fellowship exposure that general otolaryngology residencies inadequately provide, constraining qualified operator supply.
- Reimbursement Code Fragmentation:Site-of-service differentials between hospital outpatient departments and ambulatory surgery centers complicate pricing strategy and contract negotiation for device manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tonsil and Adenoid Removal Products Market |
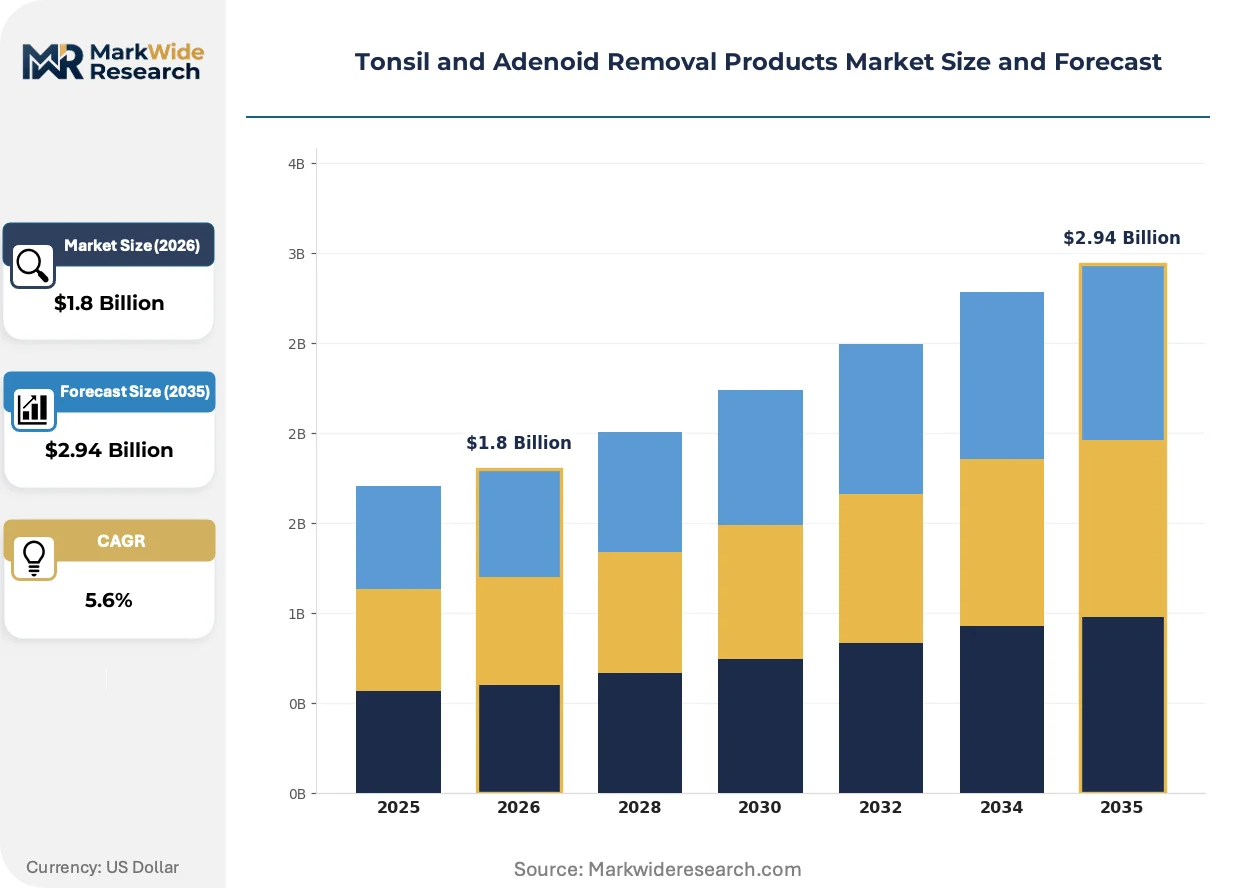
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.94 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Endoscopic Instruments, Electrosurgical Devices, Sutures, Scissors Technology: Laser, Radiofrequency, Cold Steel, Ultrasonic Care Setting: Outpatient Surgery Centers, Hospitals, Specialty Clinics, Homecare Age Group: Pediatric, Adolescent, Adult, Geriatric |
| Companies Covered | B. Braun Melsungen AG, Bausch & Lomb Incorporated, Medtronic, CONMED Corporation, Olympus Corporation, Johnson & Johnson, Smith & Nephew, Integra LifeSciences, Stryker Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tonsil and Adenoid Removal Products Market Evolving Landscape
Technology convergence between energy delivery systems and intraoperative visualization is redefining procedural workflows in tonsil and adenoid surgery, compressing the gap between diagnosis and definitive intervention.
Radiofrequency coblation is consolidating market share in outpatient settings by reducing thermal spread to surrounding musculosa, enabling faster recovery trajectories that ambulatory surgery centers exploit for throughput optimization. Pediatric otolaryngology practices in the United States are replacing legacy electrocautery platforms at accelerated replacement cycles. This consolidation is compressing margins for cold steel instrument manufacturers while elevating service contract importance for energy platform vendors.
EU MDR implementation is tightening clinical evidence requirements for reusable electrosurgical handpieces, forcing manufacturers to commission prospective safety studies that 510(k) predicate pathways in the United States do not mandate. Notified body capacity constraints extend European market entry timelines by twelve to eighteen months. High-volume reusable device suppliers are responding by accelerating predicate device portfolio diversification to grandfather existing clearances before transitional deadlines expire.
Surgeon preference is rotating toward single-use disposable instruments in freestanding surgery centers, where sterilization infrastructure costs and infection control liability reshape procurement evaluation criteria. Hospital outpatient departments retain mixed-use protocols that favor capital equipment amortization. This behavioral divergence is most pronounced in United States metropolitan markets where ambulatory surgery center density exceeds national averages by factor of three.
Tonsil and Adenoid Removal Products Market Segmentation
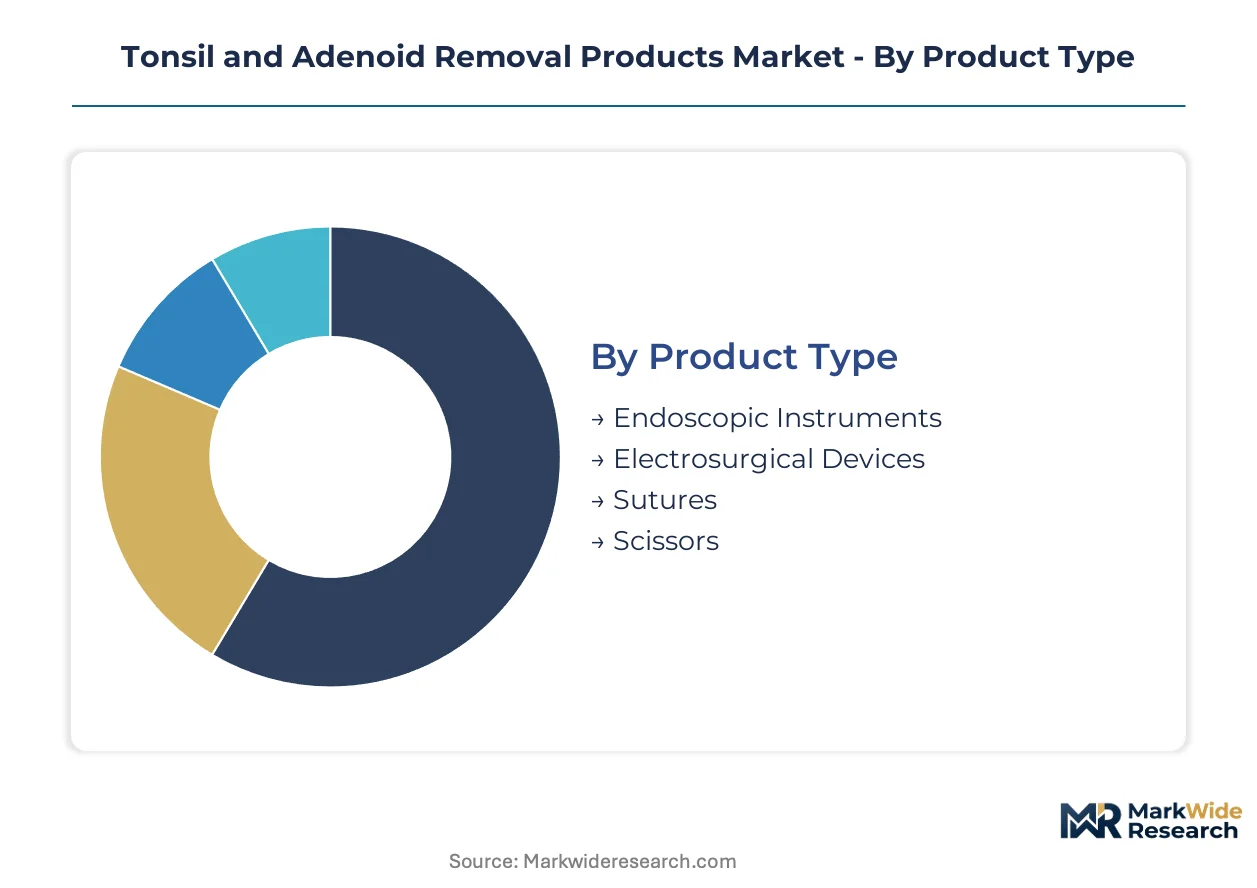
Technology and care setting choices in this market determine capital deployment cycles, reimbursement capture, and operator training requirements. Segmentation reveals where radiofrequency platforms displace legacy instruments and how pediatric volumes concentrate procedure economics.
Product Type:
Electrosurgical devices dominate capital budgets while disposable instruments sustain margin resilience in volume-driven settings.
- Electrosurgical Devices:These systems deliver controlled thermal energy through bipolar or monopolar handpieces with insulation ratings exceeding 3000V. Demand concentrates in United States ambulatory surgery centers where same-day discharge protocols reward hemostatic efficiency. Coblation platforms within this segment reduce thermal spread to surrounding musculosa, accelerating recovery trajectories that surgery centers exploit for throughput optimization.
- Endoscopic Instruments:Rigid endoscopes optimized for pediatric airway anatomy enable visualization during adenoidectomy procedures, with compatibility requirements locking purchasers into bundled system architectures. Olympus Corporation anchors this layer, generating recurring revenues from proprietary blade and sheath configurations that resist third-party substitution.
- Sutures:Absorbable polymer configurations with tensile strength profiles matched to tonsillar fossa healing timelines serve closure requirements in cold steel procedures.
- Scissors:Surgical-grade stainless steel variants with insulated handles protect against capacitive coupling in hybrid electrosurgical environments.
Today's leader: Electrosurgical Devices. Tomorrow's challenger: Endoscopic Instruments.
Technology:
Energy modality selection determines thermal injury margins, recovery trajectories, and capital intensity across care settings.
- Radiofrequency:Coblation platforms operate at lower temperatures than electrocautery, reducing collateral tissue damage in pediatric airway surgery. Outpatient surgery centers in the United States are replacing legacy platforms at accelerated replacement cycles, compressing margins for alternative modalities.
- Cold Steel:Disposable blade economics demonstrate resilience against capital-intensive alternatives, with Smith & Nephew competing on per-procedure cost structures that appeal to freestanding centers with constrained sterilization infrastructure.
- Laser:CO2 laser platforms capture premium positioning in revision cases where precision limits collateral thermal injury to surrounding anatomy.
- Ultrasonic:Harmonic scalpel variants deliver mechanical vibration for tissue transection with simultaneous coagulation, occupying niche applications in adenoidectomy where vessel sealing requirements exceed cold steel capability.
Radiofrequency commands installed base expansion. Laser retains revision case pricing power.
Care Setting:
Site-of-service migration reshapes procurement evaluation criteria and sterilization liability exposure.
- Outpatient Surgery Centers:Freestanding facilities favor single-use disposable instruments where sterilization infrastructure costs and infection control liability reshape capital versus operating expense trade-offs. United States metropolitan markets with ambulatory surgery center density exceeding national averages by factor of three exhibit the most pronounced behavioral divergence from hospital protocols.
- Hospitals:Hospital outpatient departments retain mixed-use protocols that favor capital equipment amortization and centralized purchasing power for six-figure coblation console procurement.
- Specialty Clinics:Otolaryngology practices with in-office surgical suites concentrate diagnostic and intervention workflows, requiring compact energy platforms with reduced footprint requirements.
- Homecare:Postoperative monitoring devices and patient education materials support recovery management outside acute care environments.
Outpatient Surgery Centers drive modality substitution fastest. Hospitals defend capital-intensive positions longest.
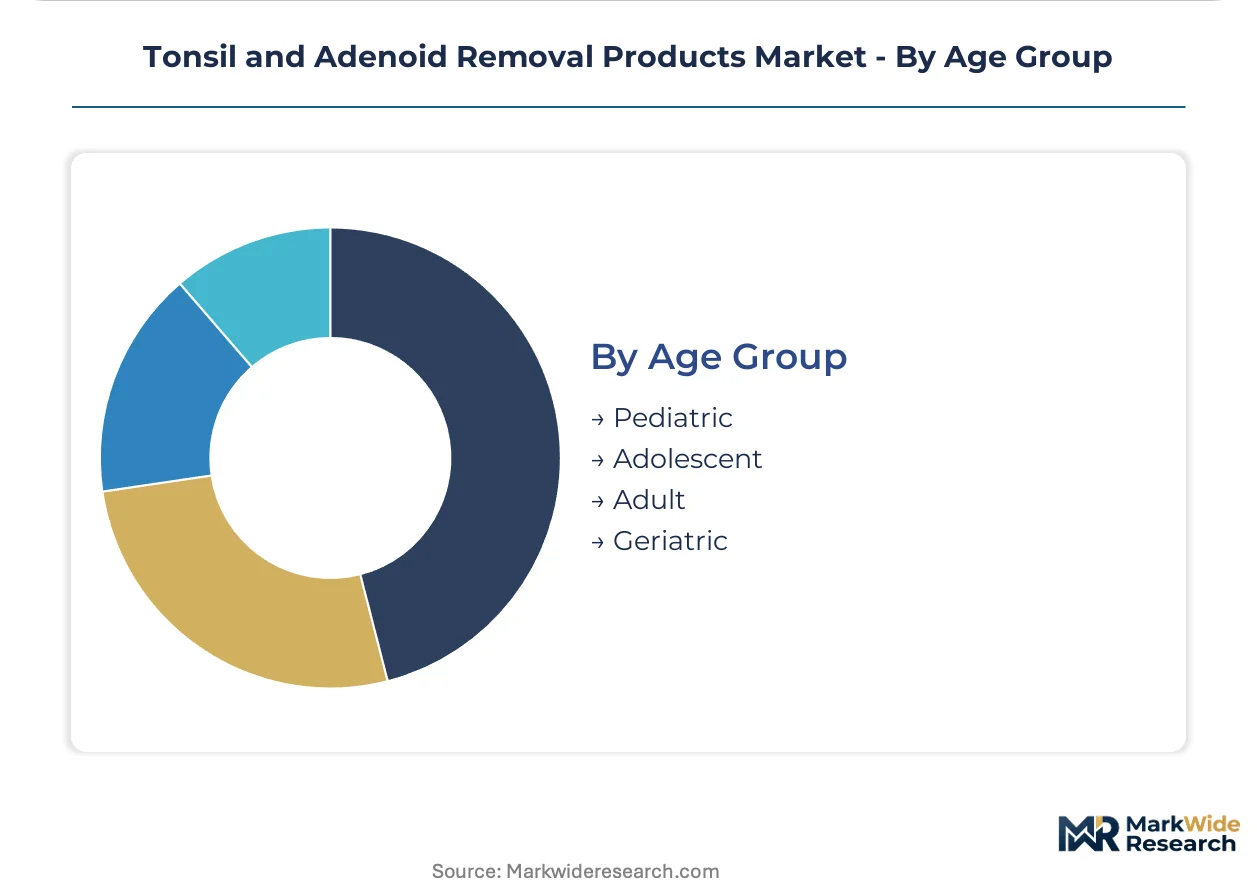
Age Group:
Anatomical tolerance variations and diagnostic protocol thresholds segment addressable surgical volumes.
- Pediatric:Adenotonsillar hypertrophy protocols in otolaryngology practices concentrate procedural volumes here, with sleep-disordered breathing diagnostic thresholds tightening to expand surgical candidacy. Narrower anatomical tolerances demand specialized fellowship exposure that general residency training inadequately provides.
- Adolescent:Transition-age patients present mixed indications spanning infectious recurrence and airway obstruction, with shared decision-making protocols involving both pediatric and adult care pathways.
- Adult:Chronic tonsillitis and peritonsillar abscess management sustain procedural demand, though volumes remain below pediatric peaks.
- Geriatric:Comorbidity burdens and anesthesia risk profiles constrain surgical candidacy, with conservative management protocols preferred in this population.
Pediatric volumes anchor procedure economics. Adolescent transition pathways present integration challenges for care coordination.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pediatric otolaryngology specialists concentrate in metropolitan medical centers across four countries that anchor procedural volume and device procurement decisions.
United States
Ambulatory surgery centers in Dallas, Houston, and Phoenix drive radiofrequency platform adoption as UnitedHealthcare and Anthem align reimbursement with same-day discharge protocols. FDA 510(k) predicate pathways accelerate iterative device clearances for established manufacturers. The Southeast corridor from Atlanta to Miami exhibits surgery center density triple the national average, compressing replacement cycles for legacy electrocautery systems.
Germany
University hospitals in Berlin and Munich maintain mixed-use protocols favoring capital equipment amortization over disposable economics. EU MDR notified body requirements extend recertification timelines for reusable electrosurgical handpieces, elevating documentation burdens for BfArM compliance. The Rhine-Ruhr industrial cluster hosts sterilization infrastructure suppliers serving hospital outpatient departments resisting site-of-service migration.
India
Tier-2 cities including Jaipur, Lucknow, and Indore lack radiofrequency penetration, creating training-dependent expansion opportunities for platform vendors. CDSCO medical device rules impose import licensing requirements that privilege domestic assemblers with established distributor relationships. Maharashtra's Mumbai-Pune corridor concentrates pediatric surgery fellowship programs that constrain qualified operator supply.
Japan
Metropolitan Tokyo and Osaka otolaryngology practices adopt compact energy platforms for in-office surgical suites with reduced footprint requirements. PMDA premarket approval timelines exceed FDA 510(k) pathways by eight to twelve months, filtering market entry to manufacturers with dedicated regulatory affairs capacity. The Kansai region's device trading houses mediate procurement for regional hospitals prioritizing visualization integration.
United Kingdom
NHS England site-of-service differentials between hospital outpatient departments and independent sector treatment centers complicate pricing strategy for device manufacturers. MHRA post-Brexit regulatory autonomy maintains CE marking recognition while diverging from EU MDR implementation timelines. The Thames Valley corridor from London to Oxford anchors pediatric airway surgery fellowship density.
Tonsil and Adenoid Removal Products Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across a consolidated vendor base where integrated energy platforms and disposable blade economics define tiered positioning. Three strategic archetypes dominate: diversified medtech conglomerates with installed base leverage, specialized otolaryngology device houses with visualization lock-in, and commoditized instrument suppliers competing on per-procedure cost. Competitive moves concentrate on M&A for predicate device portfolios and strategic partnerships for ambulatory surgery center distribution.
Among diversified medtech conglomerates, Medtronic and Johnson & Johnson exemplify integrated platform strategies that bundle energy delivery with service contracts. Smith & Nephew occupies a position within disposable instrument economics, representing the asset-light archetype that challenges capital-intensive alternatives. Olympus Corporation anchors the visualization-specialist tier, with rigid endoscope compatibility creating bundled system architectures that resist third-party substitution.
| Leading Market Players |
|---|
| B. Braun Melsungen AG |
| Bausch & Lomb Incorporated |
| Medtronic |
| CONMED Corporation |
| Olympus Corporation |
| Johnson & Johnson |
| Smith & Nephew |
| Integra LifeSciences |
| Stryker Corporation |
| Others |
Value Network & Pricing Analysis
Radiofrequency coblation platform adoption in United States ambulatory surgery centers is compressing per-procedure economics while concentrating procurement power among integrated health systems with centralized capital budgets. This technology transition simultaneously elevates service contract value for energy device vendors and strains disposable instrument margins as buyers prioritize total cost-of-ownership calculations over unit pricing.
Pricing Analysis
Bundled system sales encompassing energy consoles, proprietary handpieces, and multi-year service agreements dominate hospital outpatient departments, while unbundled disposable blade economics prevail in freestanding surgery centers lacking sterilization infrastructure. Three-tier pricing structure across premium radiofrequency platforms, standard electrosurgical systems, and economy cold steel instruments reflects FDA 510(k) predicate depth and visualization integration levels. Pricing pressure stems from ambulatory surgery center migration as UnitedHealthcare and Anthem reimbursement alignment rewards same-day discharge protocols. Freestanding centers exhibit highest price sensitivity due to constrained capital budgets, whereas integrated delivery networks prioritize clinical outcome metrics over per-unit cost.
Supply Chain Analysis
Surgical-grade stainless steel feedstock rests on German and Japanese specialty metallurgical producers with ISO 13485-certified forging capacity. Electrosurgical insulation polymers draw from United States and South Korean chemical manufacturers, while radiofrequency generator components source from Taiwanese electronics assemblers. Single-source vulnerability concentrates in pediatric-specific rigid endoscope optics where Olympus Corporation maintains proprietary lens grinding expertise. Distribution runs through regional medical device distributors with GPO contract administration capabilities, hospital system direct procurement teams, and ambulatory surgery center group purchasing organizations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where EU MDR clinical evidence burdens extend European market entry timelines by twelve to eighteen months, creating valuation discounts for manufacturers with grandfathered CE markings versus FDA-cleared peers facing dual regulatory investment requirements.
For Market Incumbents: Cement predicate device portfolio diversification ahead of EU MDR transitional deadlines to grandfather existing reusable electrosurgical handpiece clearances. Deepen vertical integration into radiofrequency generator component supply to defend margin position against Taiwanese electronics assemblers capturing value from energy platform vendors. Laser technology substitution in revision cases threatens premium positioning; lock in visualization integration partnerships with Olympus Corporation to resist third-party endoscope compatibility erosion. For New Entrants and Emerging Players: Launch via disposable cold steel instrument economics targeting India tier-2 city surgical centers in Jaipur, Lucknow, and Indore where radiofrequency penetration remains underdeveloped. CDSCO import licensing requirements privilege domestic assemblers with established distributor relationships, creating partnership-dependent entry pathways. Training-intensive platform adoption in pediatric otolaryngology practices offers white-space positioning against capital-intensive coblation vendors. For Investors and Strategic Acquirers: Valuations sit cheapest among reusable electrosurgical handpiece manufacturers facing EU MDR recertification cost spikes and extended notified body queue delays. Long-term viability over the next decade hinges on ambulatory surgery center density expansion in United States metropolitan markets exceeding national averages. Watch FDA 510(k) clearance velocity for iterative radiofrequency handpiece improvements as inflection indicator for incumbent competitive moat durability.| Strategic Initiative | Industry Significance |
|---|---|
| Predicate Device Portfolio Expansion | Grandfathered EU MDR clearances protect market access ahead of stricter clinical evidence requirements. |
| Visualization System Bundling | Olympus rigid endoscope compatibility locks purchasers into recurring blade and sheath revenue streams. |
| Ambulatory Surgery Center Distribution Partnership | UnitedHealthcare reimbursement alignment accelerates site-of-service migration toward freestanding facilities. |
| India Tier-2 City Training Infrastructure | CDSCO licensing requirements favor domestic assemblers with established otolaryngology staff training programs. |
| Service Contract Revenue Diversification | Coblation platform vendors capture recurring maintenance income offsetting capital equipment margin compression. |
Research Methodology
Bottom-up ambulatory surgery center procedure volume modeling reconciled against top-down energy platform shipment tracking forms the analytical core of this study. Primary interviews with pediatric otolaryngologists, hospital purchasing committee members, biomedical engineers, and GPO contracts managers combined with secondary validation against FDA 510(k) filings, CMS Medicare reimbursement databases, hospital procurement records, and EU MDR notified body clearance registries. Triangulation between demand-side surgical volume estimates and supply-side manufacturer production data ensures consistency across the analysis window.
Historical trendline analysis of radiofrequency platform replacement cycles, cold steel instrument procurement patterns, and laser technology adoption in revision cases informs the projection framework. Segmentation dimensions modeled encompass technology modality, care setting architecture, age group surgical candidacy, and regional regulatory cluster. CAGRs derive from installed base expansion rates, reimbursement code evolution, and predicate device portfolio depth. Pediatric sleep-disordered breathing diagnostic threshold tightening and ambulatory surgery center density differentials serve as key forecast sensitivity inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under FDA 510(k) pathway disruption or EU MDR notified body capacity collapse scenarios. Forecasts reflect documented assumptions regarding reimbursement alignment persistence, sterilization infrastructure cost trajectories, and fellowship-trained operator supply expansion. Regulatory timeline delays, capital equipment financing availability, and substitute technology performance breakthroughs warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surgical Instruments
Ultrasonic Surgical Cutters Market
Surgical Instruments
Global Plastic Surgery Instruments Market
Surgical Instruments
Surgical Drainage Devices Market
Surgical Instruments
Global Microsurgery Market
Surgical Instruments
Surgical Sutures Market
Surgical Instruments
Brazil General Surgical Devices Market
Surgical Instruments
Endoscopic Closure Systems Market
Surgical Instruments
Medical Penlights Market
Surgical Instruments
Surgical Drains Market
Surgical Instruments
Global Gastroenterology Ambulatory Surgery Center Market
Surgical Instruments
Minimally Invasive Thoracic Surgery Market
Surgical Instruments
Pneumoperitoneum Market
Surgical Instruments
Cold Disposable Biopsy Forceps Market
Surgical Instruments
Italy General Surgical Devices Market
Surgical Instruments
Endoluminal Suturing Devices Market
Surgical Instruments
Dental Surgical Microscopes Market