
 Ultrasonic Scissors Market | 2026-2036
Ultrasonic Scissors Market Size, Share, and Industry Trends Forecast 2026-2036
Ultrasonic Scissors Market Intelligence
The capital-intensity gap between integrated manufacturers and component assemblers is collapsing as piezoelectric transducer costs fall and modular blade architectures proliferate. Ethicon leverages its captive ceramics supply chain to sustain margin structures that pure-play competitors cannot replicate. Medtronic anchors its position through hospital system GPO contracts that lock in multi-year ultrasonic instrument commitments. Soring GmbH differentiates by specializing in veterinary-adapted ultrasonic shears, occupying a defensible niche below the human-surgery radar.
Ultrasonic scissors employ high-frequency mechanical vibration, typically at 20–60 kHz, to thermally coagulate and simultaneously transect tissue through protein denaturation without electrical current passing through the patient. The technology eliminates stray thermal injury risks associated with monopolar electrosurgery, making it indispensable in laparoscopic and open procedures where vessel sealing precision determines clinical outcomes. Handheld scissors dominate current revenue pools across medical procedures, though customizable scissors represent the fastest-growing configuration as ambulatory surgery centers demand instrument sets matched to specialty caseloads. Piezoelectric technology leads the technology dimension with mature supply chains, while hybrid systems integrating electromechanical feedback are capturing early-stage interest from R&D facilities pursuing closed-loop cutting control.
The FDA's 510(k) clearance framework for ultrasonic surgical instruments shapes product development timelines and clinical evidence requirements for US market access, while the EU Medical Device Regulation (MDR) imposes stricter post-market surveillance and notified body scrutiny on European commercialization. Japan's PMDA maintains distinct biocompatibility testing protocols that delay entry for manufacturers lacking prior Japanese pharmaceutical alliances. Stakeholders must monitor how reimbursement authority decisions at Germany's G-BA and France's ANSM on procedure-specific fee schedules will determine whether ultrasonic dissection displaces conventional electrosurgery in routine cholecystectomy and colectomy volumes.
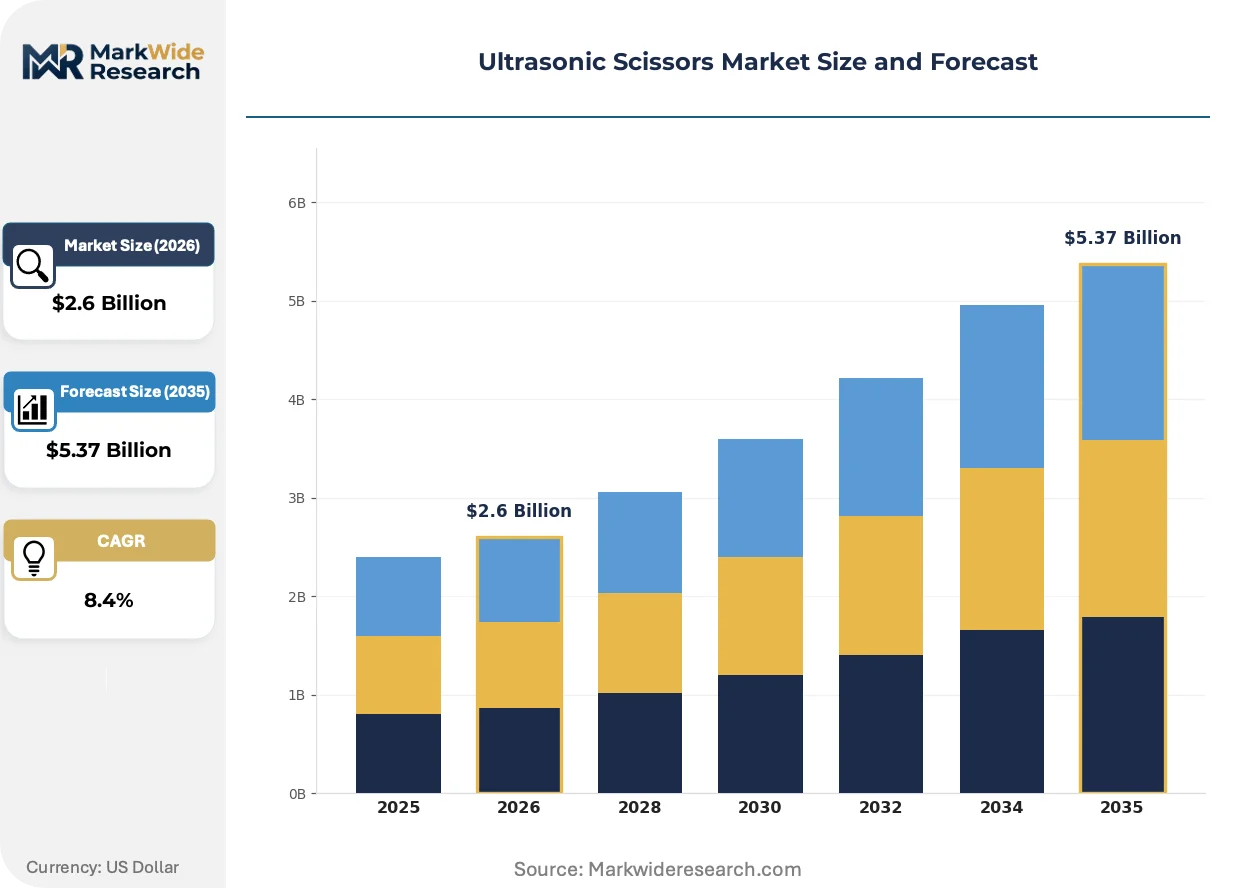
Market Dynamics
Modular piezoelectric transducer architectures are collapsing the capital barrier between integrated manufacturers and component assemblers, redistributing competitive advantage toward firms mastering ceramic sourcing and blade geometry rather than electromechanical system integration.
Growth Catalysts
- EU MDR post-market surveillance mandates:Stricter notified body scrutiny on European commercialization accelerates replacement cycles for legacy electrosurgical instruments as hospitals preempt compliance-driven obsolescence.
- Ambulatory surgery center instrument customization:Specialty-matched scissors configurations command premium positioning as outpatient facilities seek procedure-specific efficiency gains.
- Tuttlingen precision cluster concentration:Germany's dense OEM supply chain ecosystem compresses prototyping-to-production timelines for ultrasonic instrument development.
Market Restraints
- Piezoelectric ceramic supply concentration:Specialty ceramic feedstock dependence on limited high-purity PZT suppliers creates input cost volatility and allocation risk during demand surges.
- Japan PMDA biocompatibility testing protocols:Distinct material qualification requirements delay market entry for manufacturers lacking established Japanese pharmaceutical distribution partnerships.
- Conventional electrosurgery substitution resilience:Monopolar and bipolar systems retain installed base advantages in cost-sensitive hospital procurement through lower per-procedure instrument depreciation.
Strategic Opportunities
- Veterinary surgery adaptation white space:Species-specific blade geometries and coagulation profiles for companion animal laparoscopy remain underserved by human-surgery-focused incumbents.
- Hybrid electromechanical feedback convergence:Integration of real-time tissue impedance sensing with ultrasonic vibration control enables closed-loop cutting precision for vessel sealing applications.
- India CDSCO streamlined Class C device pathways:Regulatory harmonization initiatives reduce notified body bottlenecks for ultrasonic surgical instrument commercialization in South Asian markets.
Industry Challenges
- Cross-functional talent scarcity:Simultaneous mastery of piezoelectric physics, surgical workflow design, and biocompatible materials engineering concentrates in few specialized engineering programs.
- FDA 510(k) clinical evidence timeline compression:Substantial equivalence determinations for novel blade geometries require predicate device matching that extends development cycles.
- Legacy electrosurgical system integration friction:Hospital capital equipment refresh cycles misalign with ultrasonic instrument adoption, forcing dual-inventory maintenance during transition periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ultrasonic Scissors Market |
| Market Size in 2026 | $2.6 Billion |
| Market Size in 2035 | $5.37 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld Scissors, Tabletop Scissors, Customizable Scissors, Industrial Scissors Application: Textile Cutting, Medical Procedures, Packaging, Automotive Assembly Technology: Ultrasonic Wave, Piezoelectric Technology, Electromechanical, Hybrid Systems End User: Healthcare Providers, Manufacturing Industries, Textile Manufacturers, R&D Facilities |
| Companies Covered | Ethicon, Medtronic, Olympus Corporation, Soring GmbH, Misonix, Integra LifeSciences, Stryker, Johnson & Johnson, BOWA-electronic GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ultrasonic Scissors Market Strategic Shifts & Innovations
Real-time tissue sensing capabilities and modular instrument architectures are redefining how ultrasonic scissors integrate into surgical workflows, compressing the gap between high-performance integrated systems and adaptable component platforms.
Closed-loop control systems incorporating electromechanical feedback are fragmenting the traditional boundary between premium integrated consoles and mid-tier portable units. Ambulatory surgery centers in Germany and Japan are piloting these hybrid configurations to reduce capital commitment while preserving precision. The technology is fragmenting vendor market tiers by enabling component suppliers to compete on cutting performance without full system integration.
The EU Medical Device Regulation's intensified post-market surveillance requirements are extending clinical follow-up obligations for ultrasonic surgical instruments from two to ten years. Manufacturers must now maintain active implantable-grade vigilance systems for reusable cutting devices, elevating documentation costs. German notified bodies are experiencing eighteen-month backlog queues, forcing firms to sequence European launches behind US FDA clearances.
Hospital group purchasing organizations are consolidating instrument procurement across multi-hospital systems, compressing supplier negotiation leverage for standalone ultrasonic scissors vendors. Integrated delivery networks in France and the United States are bundling dissection instrument contracts with broader laparoscopic tower commitments. France's ANSM reimbursement authority decisions on procedure-specific fee schedules are determining whether ultrasonic dissection displaces conventional electrosurgery in routine cholecystectomy volumes.
Ultrasonic Scissors Market Segmentation
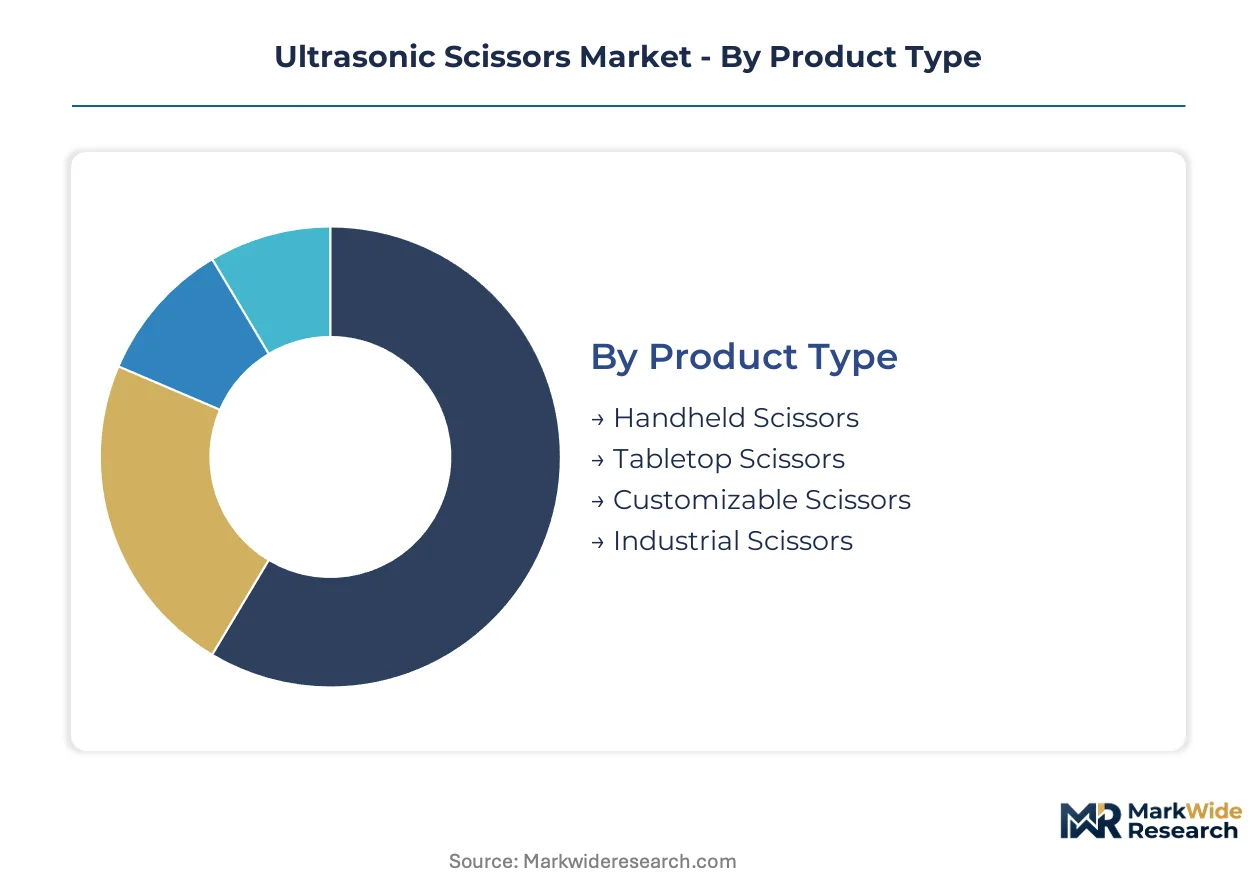
Ultrasonic scissors segmentation reflects divergent regulatory pathways across human surgery, veterinary practice, and industrial fabrication. Product configurations, application environments, and technology architectures each carry distinct certification burdens that reshape vendor competitive positioning.
Product Type:
FDA 510(k) substantial equivalence determinations and EU MDR Class IIa/IIb risk classifications create divergent commercialization timelines across portable, fixed-installation, and specialty-adapted instrument formats.
- Handheld Scissors:Battery-powered or console-tethered instruments dominate laparoscopic and open surgical suites through ergonomic grip geometries and disposable blade cartridges. Demand concentrates in German hospital systems where G-BA reimbursement decisions favor vessel-sealing precision over conventional electrosurgery depreciation costs.
- Customizable Scissors:Modular blade architectures with interchangeable jaw geometries and vibration amplitude profiles enable procedure-specific configuration. Ambulatory surgery centers in France and Japan are adopting these platforms fastest as capital constraints force multi-specialty instrument flexibility.
- Tabletop Scissors:Fixed-base units with integrated irrigation and suction channels serve high-volume industrial cutting applications.
- Industrial Scissors:Heavy-duty transducer assemblies handle composite material severing in aerospace fabrication environments.
Handheld scissors handle the majority of throughput; customizable scissors is the fastest mover on share.
Application:
Cost tier stratification separates premium surgical applications from commoditized industrial cutting, with reimbursement eligibility determining addressable market boundaries.
- Medical Procedures:Laparoscopic cholecystectomy, colectomy, and thoracic dissection demand thermal coagulation without electrical current transmission. France's ANSM and Germany's G-BA fee schedule decisions determine whether ultrasonic dissection displaces monopolar systems in routine volumes.
- Textile Cutting:Synthetic fabric sealing without fraying serves high-speed garment production lines. Demand clusters in South Asian manufacturing hubs where CDSCO streamlined Class C pathways reduce regulatory friction for imported surgical-grade instruments repurposed for industrial use.
- Packaging:Hermetic sealing of thermoplastic films supports pharmaceutical and food-grade containment.
- Automotive Assembly:Composite panel trimming and interior fabric cutting integrate into just-in-time production cells.
Medical procedures generate premium pricing power; textile cutting is expanding most quickly on unit volume.
Technology:
Supply concentration in high-purity PZT ceramics and electromechanical feedback componentry shapes which technology architectures achieve manufacturing scale.
- Piezoelectric Technology:Lead zirconate titanate transducers convert electrical energy to mechanical vibration at 20–60 kHz with established supply chains and mature reliability data. Tuttlingen's precision instrument cluster sustains concentrated OEM feedstock access that compresses prototyping timelines.
- Hybrid Systems:Real-time tissue impedance sensing integrated with vibration amplitude control enables closed-loop cutting precision. R&D facilities in Japan and Germany are piloting these configurations for vessel sealing applications where thermal damage depth must stay within narrow tolerances.
- Ultrasonic Wave:Basic mechanical vibration without feedback modulation serves cost-sensitive industrial severing tasks.
- Electromechanical:Motor-driven blade actuation without thermal coagulation occupies peripheral cutting niches.
Piezoelectric technology commands installed base dominance; hybrid systems are climbing the fastest on development priority.
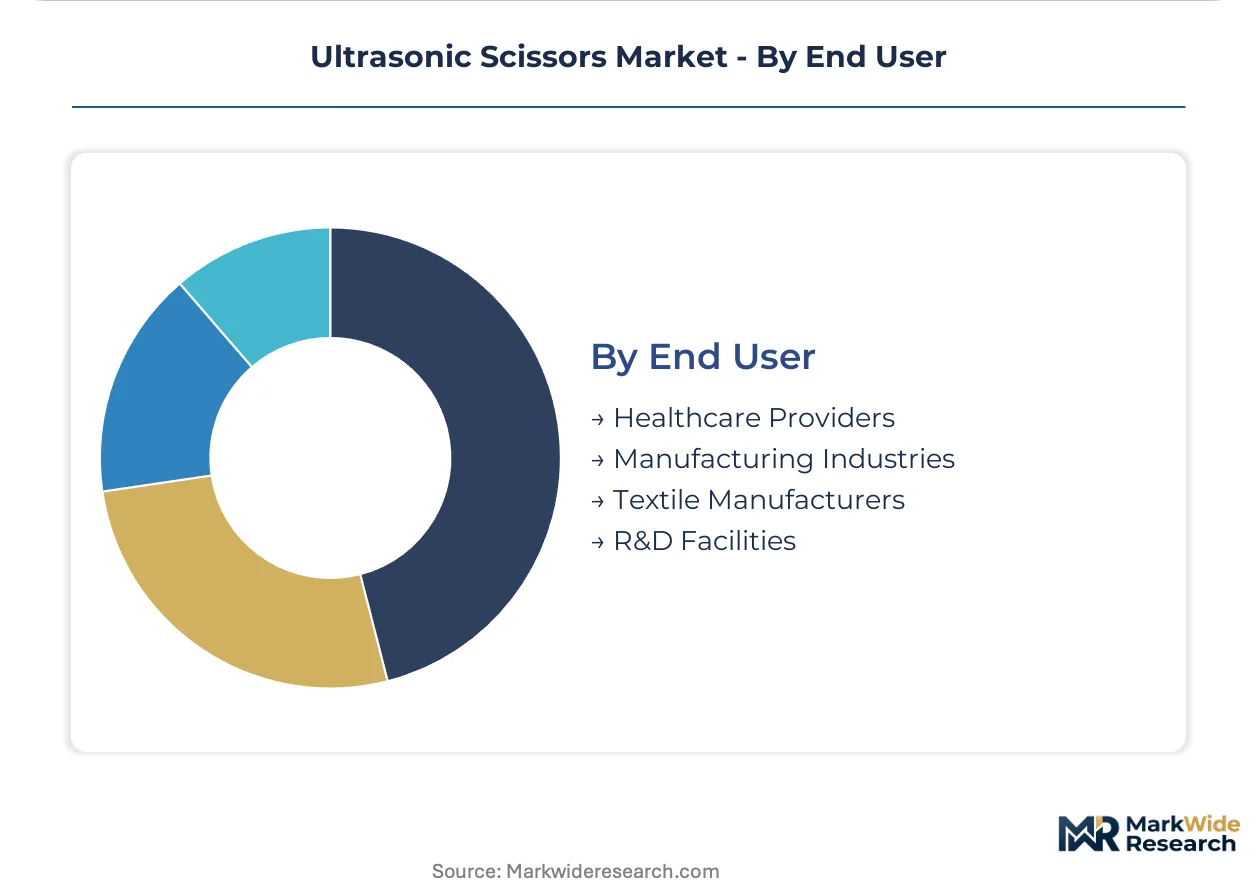
End User:
Customer procurement sophistication spans hospital GPO consolidation, industrial volume contracting, and research institution grant-funded acquisition.
- Healthcare Providers:Integrated delivery networks bundle ultrasonic instrument contracts with laparoscopic tower commitments, compressing standalone vendor negotiation leverage. US hospital GPOs and French public hospital consortia are consolidating procurement across multi-facility systems.
- R&D Facilities:Academic medical centers and corporate innovation labs pursue next-generation closed-loop control algorithms and novel blade metallurgies. Japan's PMDA distinct biocompatibility protocols delay commercial translation for manufacturers lacking established pharmaceutical distribution partnerships.
- Manufacturing Industries:Automotive and aerospace fabricators prioritize cutting speed and consumable cost over precision thermal control.
- Textile Manufacturers:High-speed production lines demand continuous-duty reliability without surgical-grade documentation burdens.
Healthcare providers absorb the dominant revenue share; R&D facilities are gaining priority fastest on technology access.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and Japan absorb premium pricing for precision surgical instruments, while procurement in India and Brazil remains acutely price-sensitive, compressing margins for standard configurations.
United States
Hospital group purchasing organizations consolidate ultrasonic instrument procurement across multi-facility systems, squeezing standalone vendor leverage. FDA 510(k) clearance timelines shape product launch sequencing for manufacturers prioritizing North American access. The Greater Boston corridor hosts R&D facilities piloting closed-loop cutting control algorithms for next-generation vessel sealing applications.
Germany
G-BA reimbursement authority decisions on procedure-specific fee schedules determine whether ultrasonic dissection displaces conventional electrosurgery in routine cholecystectomy volumes. EU MDR post-market surveillance mandates extend clinical follow-up obligations to ten years, elevating documentation burdens. Tuttlingen's precision instrument cluster sustains concentrated OEM supply chains that compress prototyping-to-production timelines.
Japan
PMDA maintains distinct biocompatibility testing protocols that delay commercial entry for manufacturers lacking established pharmaceutical distribution partnerships. METI funding for next-generation surgical robotics indirectly supports ultrasonic instrument integration into automated laparoscopic platforms. The Kansai region around Osaka hosts medical device engineering programs concentrating cross-functional talent in piezoelectric physics and surgical workflow design.
India
CDSCO streamlined Class C device pathways reduce notified body bottlenecks for ultrasonic surgical instrument commercialization. Government PLI scheme incentives for medical device manufacturing attract component suppliers to domestic production zones. Maharashtra's Mumbai-Pune industrial corridor concentrates contract manufacturers serving both surgical-grade and repurposed industrial cutting applications.
France
ANSM reimbursement decisions on fee schedules for laparoscopic procedures determine ultrasonic scissors penetration in public hospital consortia. Hospital procurement bundling ties dissection instrument contracts to broader laparoscopic tower commitments. The Île-de-France region anchors demand from integrated delivery networks consolidating multi-site surgical service lines.
Ultrasonic Scissors Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes, with integrated manufacturers commanding premium positioning through captive ceramics supply chains while modular assemblers compete on configurability. The market structure concentrates around three strategic tiers: diversified medical technology conglomerates with GPO-anchored distribution, precision instrument specialists leveraging regional cluster advantages, and veterinary-adapted niche operators below the human-surgery radar. Dominant competitive moves include backward integration into piezoelectric ceramic feedstock and strategic partnerships with ambulatory surgery center networks seeking capital-light instrument platforms.
Among diversified medical technology conglomerates, Ethicon and Medtronic exemplify archetypes sustaining margin structures through scale advantages and hospital system contracting leverage. Soring GmbH occupies a defensible position as a veterinary-specialized operator, insulating its positioning from direct confrontation with human-surgery incumbents.
| Leading Market Players |
|---|
| Ethicon |
| Medtronic |
| Olympus Corporation |
| Soring GmbH |
| Misonix |
| Integra LifeSciences |
| Stryker |
| Johnson & Johnson |
| BOWA-electronic GmbH |
| Others |
Cost & Logistics Intelligence
Multi-year GPO contracts with take-or-pay provisions lock in ultrasonic instrument supply for hospital systems while anchoring price visibility against ceramic feedstock volatility. These arrangements concentrate purchasing power among integrated delivery networks in the United States and France, compressing margin structures for standalone vendors lacking captive piezoelectric sourcing.
Pricing Analysis
After-sales revenue from disposable blade cartridges and preventive maintenance contracts drives lifetime value for ultrasonic scissors manufacturers. Three-tier pricing structure across premium, standard, and economy levels segments buyers by certification grade and procedure volume commitment. Cost compression in mid-tier configurations is intensifying because modular transducer architectures erode integrated system premiums. Ambulatory surgery centers exhibit acute price sensitivity against hospital systems that absorb premium positioning through bundled laparoscopic tower procurement.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes elevate inbound logistics costs for piezoelectric ceramic feedstock destined for Tuttlingen manufacturing clusters. Supply concentrates in Germany, Japan, and China for high-purity PZT ceramics, precision-machined blade alloys, and electromechanical feedback sensors. Single-source vulnerability in specialty ceramic sintering capacity creates allocation risk during demand surges. Distribution runs through hospital GPOs and veterinary instrument distributors for downstream reach.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The ultrasonic scissors market sits in early-cycle expansion as EU MDR compliance deadlines accelerate replacement of legacy electrosurgical inventories across German and French hospital systems.
For Market Incumbents: Shield margin structures by deepening backward integration into piezoelectric ceramic feedstock and securing multi-year GPO contract renewals before modular assemblers achieve performance parity. The threat of hybrid electromechanical feedback systems from R&D facilities demands accelerated patent filings around closed-loop control algorithms. For New Entrants and Emerging Players: CDSCO streamlined Class C device pathways offer the fastest regulatory on-ramp for penetrating Indian ambulatory surgery centers with capital-light instrument platforms. Veterinary surgery adaptation remains the most penetrable white space, with species-specific blade geometries commanding premium positioning absent from human-surgery procurement radar. A direct-to-clinic service model bypassing traditional distribution layers captures price-sensitive outpatient facilities. For Investors and Strategic Acquirers: Precision instrument specialists with concentrated OEM supply chain access in German manufacturing clusters present asymmetric upside from EU MDR-driven vendor consolidation. Long-term viability hinges on ceramic sourcing relationships and notified body queue positioning. The signal to watch is G-BA reimbursement authority decisions on procedure-specific fee schedules for routine cholecystectomy volumes.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Compliance Pathway | Accelerated CE marking investment captures replacement cycle demand from legacy instrument obsolescence. |
| Hospital System Partnership | GPO contract anchoring with French public hospital consortia locks in multi-year instrument commitments. |
| Backward Integration into Ceramics | In-house PZT transducer production insulates margin structures from specialty feedstock allocation risk. |
| Veterinary Adaptation Launch | Species-specific blade geometries access underserved companion animal laparoscopy below human-surgery competition. |
| Hybrid Feedback R&D Investment | Real-time tissue impedance integration enables closed-loop vessel sealing precision for premium positioning. |
Research Approach
Cross-validation between primary interviews with hospital purchasing committees, biomedical engineers, and GPO contracts managers and secondary validation against FDA 510(k) filings, EU MDR notified body databases, and hospital procurement records anchors the qualitative findings. Bottom-up triangulation across product configuration demand and top-down validation through reimbursement authority fee schedule analysis ensures segmentation integrity.
Sensitivity analysis across the projection horizon tests forecast robustness against ceramic supply disruption scenarios and regulatory timeline slippage. The analytical framework models technology adoption curves, product type migration patterns, end-user procurement sophistication tiers, and regional reimbursement cluster dynamics. CAGRs derive from procedure volume elasticity assumptions and instrument replacement cycle compression under EU MDR mandates.
Decision-makers should treat outputs as directional under sustained G-BA and ANSM reimbursement favorability toward ultrasonic dissection; material deviation would warrant model refresh. Forecasts assume continued PZT ceramic supply access from established Japanese and German feedstock relationships. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surgical Instruments
Medical Tuning Fork Market
Surgical Instruments
Ultrasound Needle Guides Market
Surgical Instruments
Surgical Headband Market
Surgical Instruments
Breast Retractors Market
Surgical Instruments
Harmonic Scalpel Market
Surgical Instruments
Surgical Visualization Market
Surgical Instruments
Global Hernia Repair Market
Surgical Instruments
Ophthalmic Handheld Surgical Instruments Market
Surgical Instruments
Cardiac Surgery Instruments Market
Surgical Instruments
Japan General Surgical Devices Market
Surgical Instruments
Special Purpose Needles Market
Surgical Instruments
Surgical Clips Market
Surgical Instruments
Global Surgical Scissors Market
Surgical Instruments
Surgical Snare Market
Surgical Instruments
Italy General Surgical Devices Market
Surgical Instruments
Ultrasonic Scalpel Market