
 Articulating Paper Forceps Market | 2026-2036
Articulating Paper Forceps Market Size, Share, and Industry Trends Forecast 2026-2036
Articulating Paper Forceps Market Outlook
Disposable instrument manufacturing is fragmenting the traditional reusable forceps supply chain as infection control protocols tighten across outpatient settings. Henry Schein Inc. leverages its North American distribution network to sustain volume leadership in standard and curved configurations. Carl Martin GmbH anchors premium positioning through German-engineered titanium variants with ergonomic handle geometries. Hu Friedy Group competes on specialized angled designs for endodontic access procedures.
Articulating paper forceps are precision grasping instruments featuring jointed jaws with serrated or smooth tips, typically manufactured from surgical-grade stainless steel or lightweight titanium alloys through CNC milling and passivation processes, designed to manipulate articulating paper strips during dental occlusion testing and adjustment. Stainless steel variants dominate unit volume due to cost efficiency and autoclave durability, while titanium segments command premium pricing from weight-sensitive surgical applications. Disposable plastic forceps are gaining share in mobile clinic and veterinary settings where sterilization infrastructure remains limited.
FDA 510(k) premarket notifications and ISO 13485 quality management systems govern device safety and traceability for manufacturers serving the United States, while the EU Medical Device Regulation mandates notified body certification and post-market surveillance across European Economic Area states. These frameworks elevate barriers for unvalidated suppliers and redirect procurement toward documented quality systems. Stakeholders must monitor evolving reprocessing validation requirements as regulators scrutinize claims of single-use equivalency against reusable instrument performance.
Market Dynamics
The articulating paper forceps market is undergoing structural recalibration as disposable polymer instruments penetrate outpatient settings previously dominated by reusable metal variants, compressing traditional sterilization-dependent supply chains while elevating infection control as a procurement priority.
Growth Catalysts
- FDA 510(k) Streamlining:The FDA's updated premarket notification pathways for reusable surgical instruments are accelerating compliance investments among manufacturers serving United States dental clinics.
- Titanium Alloy Adoption:Surgical-grade titanium variants are displacing stainless steel in premium workflows where ergonomic weight reduction improves clinician endurance during extended restorative procedures.
- German Engineering Cluster:Concentrated instrument manufacturing expertise around Solingen and Tuttlingen anchors precision CNC milling capabilities for serrated jaw geometries demanded by European dental schools.
Market Restraints
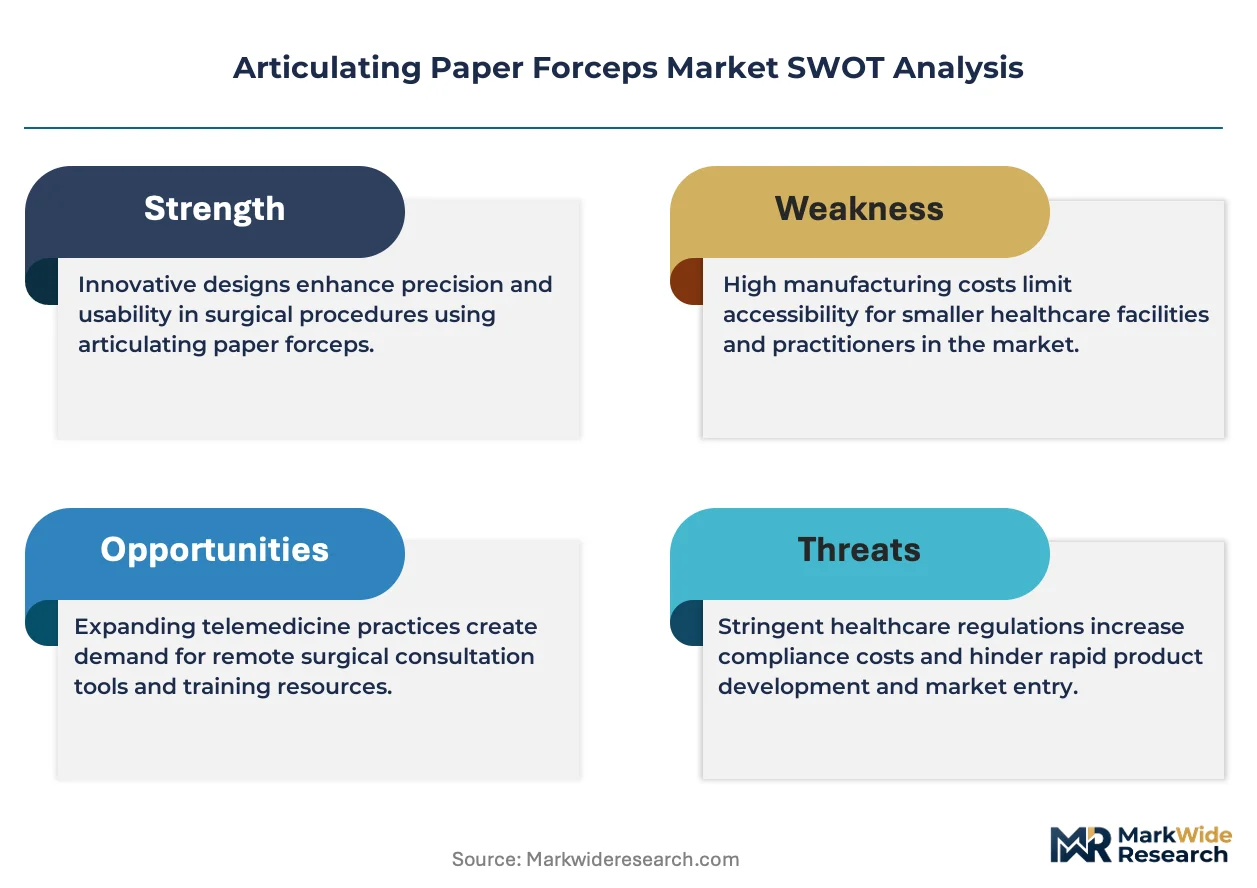
- Surgical-Grade Stainless Input Volatility:Fluctuations in 316L and 17-4 PH stainless steel pricing compress margin stability for mid-tier manufacturers dependent on commodity metal sourcing.
- EU MDR Certification Burden:The European Union Medical Device Regulation's notified body certification requirements extend timeline-to-market for new forceps designs by 12-18 months.
- Single-Use Polymer Substitution:Polypropylene and medical-grade ABS disposable forceps threaten reusable instrument volumes in mobile veterinary and humanitarian dental settings.
Strategic Opportunities
- Indian Outpatient Expansion:Underpenetrated tier-2 and tier-3 cities present whitespace as CDSCO streamlined medical device rules reduce import barriers for certified manufacturers.
- CAD-CAM Workflow Integration:Forceps designed for digital occlusion analysis compatibility are capturing preference among practices investing in intraoral scanning systems.
- Tele-dentistry Channel Development:Direct-to-clinic e-commerce platforms are bypassing traditional dental distributor markups for standardized instrument configurations.
Industry Challenges
- Reprocessing Validation Expertise Gap:Manufacturers lack sufficient sterile processing engineers to document FDA-compliant reusable instrument cleaning validation protocols.
- ISO 13485 Audit Compression:Accelerated recertification timelines for quality management systems strain documentation resources across mid-cap instrument specialists.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Articulating Paper Forceps Market |
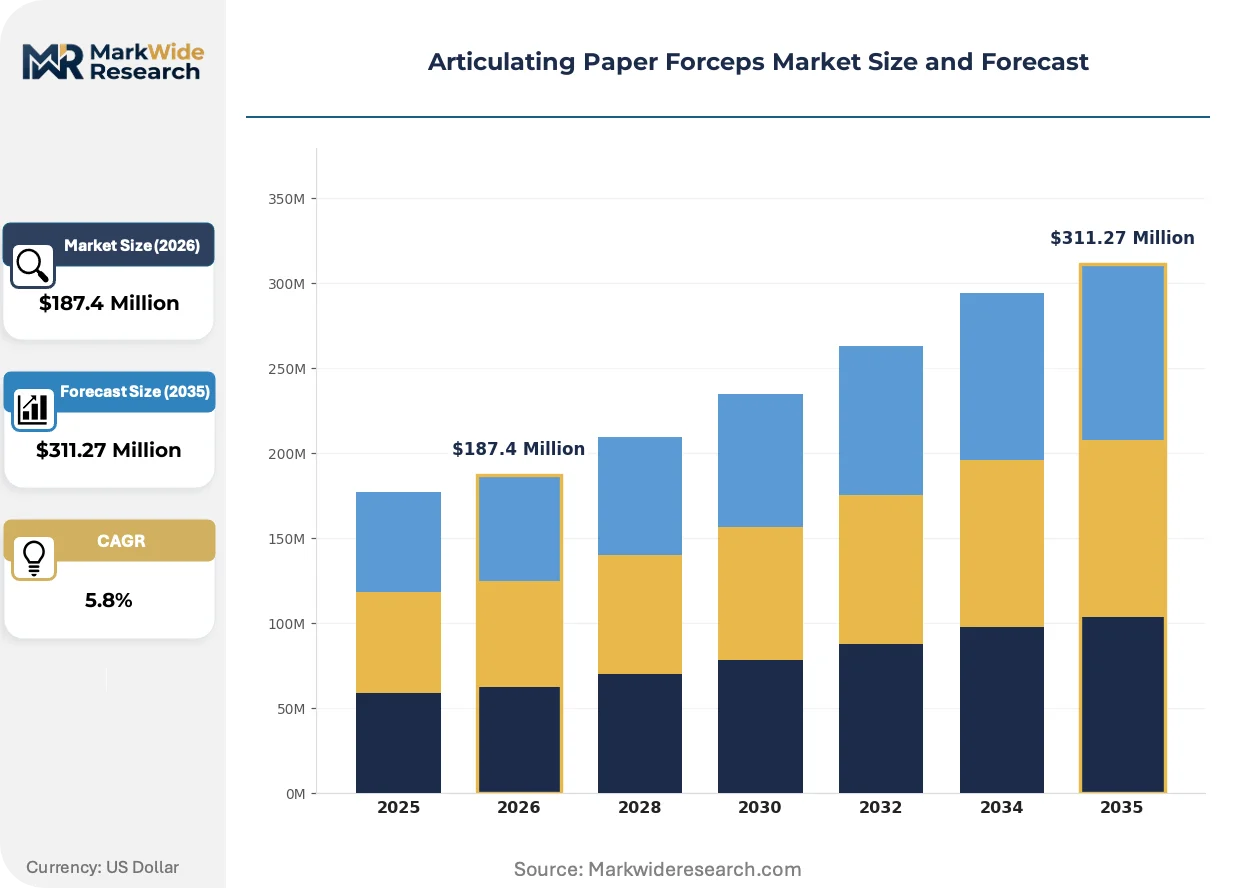
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Forceps, Curved Forceps, Angled Forceps, Disposable Forceps Material: Stainless Steel, Plastic, Titanium, Carbon Fiber End User: Hospitals, Clinics, Research Labs, Educational Institutions Application: Surgical Procedures, Laboratory Experiments, Educational Demonstrations, Veterinary Use |
| Companies Covered | Coltene Holding AG, GC Corporation, Henry Schein Inc., Carl Martin GmbH, Hu Friedy Group, Dentsply Sirona Inc., Brasseler USA Dental LLC, ASA Dental S.p.A., Patterson Dental Supply Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Articulating Paper Forceps Market Strategic Shifts
Digital dentistry workflows and material science advances are converging to reshape instrument specification requirements, with occlusion testing devices now evaluated for interoperability alongside traditional mechanical performance metrics.
Additive manufacturing of titanium forceps components is hybridizing subtractive CNC finishing with selective laser melting for complex internal jaw geometries impossible through conventional milling. University dental hospitals in Switzerland and Japan are piloting these hybrid-produced instruments for research validation. The technology is compressing prototyping cycles from months to weeks while enabling patient-specific grip modifications.
The EU Medical Device Regulation's Unique Device Identification mandates are forcing manufacturers to integrate laser-etched traceability codes directly into forceps handles rather than relying on packaging labels. German and French notified bodies are rejecting legacy marking approaches for Class I reusable instruments. Dental clinics across Denmark and the Netherlands now specify UDI-compliant sourcing as a tender prerequisite.
Consolidated purchasing through dental service organizations is displacing individual practice procurement autonomy across the United States Midwest and Southeast. DSOs operating 50-plus location networks negotiate instrument specifications directly with manufacturers, unbundling traditional Henry Schein and Patterson distributor relationships. Independent practitioners in Texas and Florida report narrowing supplier choice as preferred vendor agreements tighten.
Articulating Paper Forceps Market Segmentation
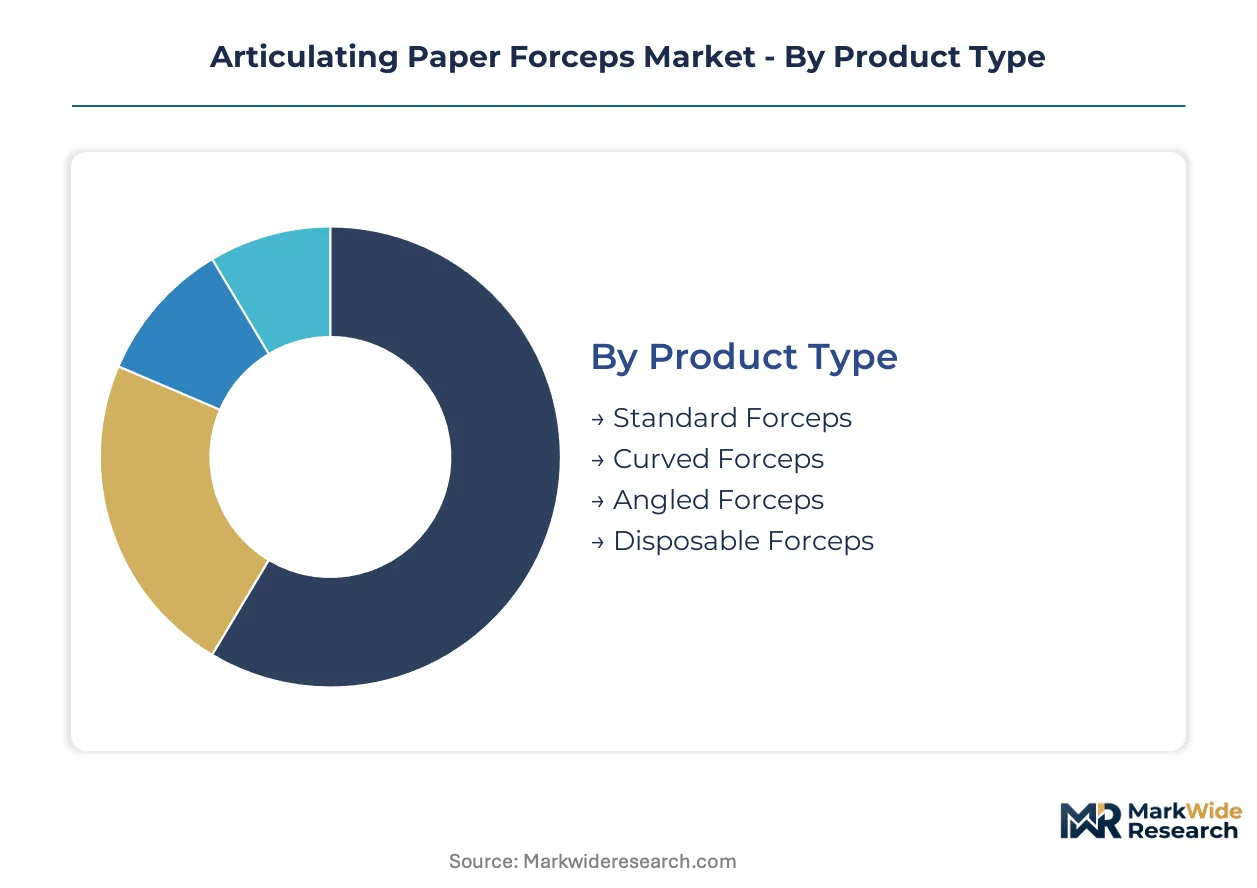
Articulating paper forceps segmentation reveals how material science, clinical setting requirements, and procedural specificity create distinct procurement channels. Manufacturers configure product lines across multiple axes to capture volume in standard restorative workflows while defending premium positions in specialized applications.
Product Type:
Mature configurations dominate installed base volumes while emerging formats exploit infection control protocol shifts.
- Standard Forceps:Straight-jaw designs with serrated grasping surfaces constitute the baseline specification for general dental occlusion testing. Demand concentrates in United States group practices and German university clinics where instrument standardization reduces sterilization complexity. Henry Schein and Patterson Dental sustain volume leadership through distributor-integrated supply contracts.
- Curved Forceps:Convex jaw geometries improve access to posterior quadrants during molar restoration procedures. Adoption is accelerating among Japanese and South Korean prosthodontic specialists investing in ergonomic instrument portfolios. The curvature radius typically ranges from 15 to 30 degrees depending on manufacturer specification.
- Angled Forceps:Compound angle configurations address endodontic access limitations in second and third molar positions. Swiss dental hospitals specify 45-degree variants for undergraduate training programs.
- Disposable Forceps:Single-use polymer instruments eliminate reprocessing overhead in mobile veterinary and humanitarian outreach settings. Polypropylene construction withstands gamma sterilization for pre-packaged distribution.
Standard forceps retain volume leadership; disposable forceps hold the steepest expansion curve.
Material:
Cost tier stratification separates commodity metals from performance-engineered alloys and single-use polymers.
- Stainless Steel:Surgical-grade 316L and 17-4 PH alloys deliver autoclave durability at mid-tier price points. German Solingen manufacturers dominate precision milling for serrated jaw geometries demanded by European dental schools.
- Plastic:Medical-grade polypropylene and ABS formulations serve cost-constrained settings lacking sterilization infrastructure. Indian mobile clinics and Brazilian veterinary practices drive procurement volume.
- Titanium:Ti-6Al-4V alloy variants reduce instrument weight by 40 percent versus stainless steel equivalents. Japanese oral surgeons and United States prosthodontists specify titanium for extended procedure endurance. Carl Martin GmbH anchors premium positioning through German-engineered ergonomic handle geometries.
- Carbon Fiber:Composite-reinforced polymer construction offers radiolucency for intraoperative imaging compatibility. Experimental adoption is limited to Swiss and Japanese university research hospitals evaluating next-generation instrument platforms.
Stainless steel commands installed base dominance; titanium captures the most aggressive pricing premiums.
End User:
Customer type determines volume scale, specification complexity, and procurement channel preference.
- Hospitals:Acute care dental departments and oral surgery units require instrument traceability compliant with Joint Commission and DNV standards. United States health systems negotiate enterprise contracts specifying ISO 13485-certified sourcing.
- Clinics:Outpatient dental practices represent the highest transaction frequency segment. German private practitioners and Japanese dental offices prioritize ergonomic handle designs for repetitive strain prevention.
- Research Labs:Biomechanical testing facilities and materials science departments procure specialized variants for occlusion force measurement studies. Swiss Federal Institute of Technology and Tokyo Medical and Dental University maintain dedicated instrument inventories.
- Educational Institutions:Undergraduate dental programs in India and Brazil specify cost-optimized stainless steel configurations for high-turnover student training environments. CDSCO streamlined import rules are reducing procurement friction for certified manufacturers.
Clinics generate transaction volume leadership; research labs exhibit the most specialized specification requirements.
Application:
Procedural context dictates jaw geometry, material durability, and sterility assurance level requirements.
- Surgical Procedures:Operating room environments demand titanium or stainless steel variants with validated reprocessing protocols. FDA 510(k) clearance pathways govern reusable instrument compliance for United States hospital systems.
- Laboratory Experiments:In vitro occlusion studies utilize standardized forceps for articulating paper positioning under controlled mechanical loading. German and Swiss research institutes specify CNC-milled instruments for measurement repeatability.
- Educational Demonstrations:Teaching laboratories prioritize durability and cost efficiency over precision specifications. Indian and Brazilian dental schools procure high-volume stainless steel contracts.
- Veterinary Use:Companion animal and equine dentistry applications favor disposable polymer instruments where field sterilization infrastructure is unavailable. Mobile veterinary services in Australia and Canada drive single-use procurement.
Surgical applications anchor revenue concentration; veterinary use is gaining share fastest among application categories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyer archetypes concentrate in German precision engineering clusters, United States dental service organizations, and Japanese prosthodontic specialists. These three markets generate divergent specification requirements that reshape regional procurement patterns. Each geography imposes distinct regulatory compliance burdens on instrument manufacturers.
Germany
Solingen and Tuttlingen host dense concentrations of CNC-milled instrument manufacturing for European dental schools. The EU Medical Device Regulation mandates notified body certification and Unique Device Identification laser-etching on forceps handles. Carl Martin GmbH anchors premium titanium production in this cluster, supplying ergonomic variants to university hospitals across Bavaria and Baden-Württemberg.
United States
Dental service organizations operating 50-plus location networks in Texas and Florida negotiate direct manufacturer contracts, displacing traditional distributor relationships. FDA 510(k) premarket notification pathways govern reusable instrument clearance for hospital systems. Henry Schein Inc. leverages its distribution infrastructure to sustain volume leadership across Midwest and Southeast group practices.
Japan
Prosthodontic specialists in Tokyo and Osaka drive specification demand for lightweight titanium variants that reduce clinician fatigue during extended procedures. The Pharmaceuticals and Medical Devices Agency oversees device registration for imported instruments. University dental hospitals in Kanto and Kansai regions pilot hybrid additive manufacturing for complex jaw geometries.
India
Tier-2 and tier-3 cities present expansion whitespace as CDSCO streamlined medical device rules reduce import barriers for certified manufacturers. Dental schools in Maharashtra and Karnataka specify cost-optimized stainless steel configurations for high-turnover student training. Mobile clinics in Gujarat and Tamil Nadu favor disposable polymer instruments where sterilization infrastructure remains limited.
Switzerland
Research hospitals in Zurich and Geneva evaluate carbon fiber-reinforced forceps for radiolucency compatibility with intraoperative imaging. Swissmedic certification requirements align with EU MDR standards for Class I reusable instruments. The Swiss Federal Institute of Technology maintains dedicated instrument inventories for biomechanical occlusion studies.
Articulating Paper Forceps Market Competitive Environment
Channel-controlling players compete with product-specialist players across tiered price bands defined by material certification and ergonomic specification. The vendor base separates into three strategic archetypes: distributor-integrated volume suppliers, German-engineered premium specialists, and disposable polymer entrants. Consolidated purchasing through dental service organizations compresses independent practice autonomy. Capacity expansion in Indian contract manufacturing and technology licensing for hybrid additive production represent dominant competitive moves.
Among distributor-integrated players, Henry Schein Inc. and Patterson Dental Supply Inc. exemplify channel-control archetypes that bundle instrument procurement with practice management systems. German-engineered specialists occupy premium positioning, with Carl Martin GmbH representing precision CNC-milled titanium production anchored in Solingen. Hu Friedy Group sits within the specialized angled-design segment for endodontic access procedures. These three company types illustrate how competitive positioning stratifies across volume, premium, and application-specific vectors.
| Leading Market Players |
|---|
| Coltene Holding AG |
| GC Corporation |
| Henry Schein Inc. |
| Carl Martin GmbH |
| Hu Friedy Group |
| Dentsply Sirona Inc. |
| Brasseler USA Dental LLC |
| ASA Dental S.p.A. |
| Patterson Dental Supply Inc. |
| Others |
Value Chain & Pricing Dynamics
German Solingen and Tuttlingen host the densest concentration of CNC-milled instrument manufacturing for dental forceps, anchoring premium margin pools in titanium variants while compressing mid-tier stainless steel pricing power. This upstream clustering concentrates precision milling expertise and passivation capabilities, forcing downstream buyers to accept tiered pricing structures calibrated to alloy grade and ergonomic specification.
Pricing Analysis
Cost-plus contracts with surgical-grade stainless steel indexation dominate mid-tier procurement, tying forceps pricing to 316L and 17-4 PH commodity movements. Three-tier pricing structure across premium, standard, and economy levels separates titanium ergonomic variants from German-engineered stainless steel configurations and disposable polymer alternatives. Pricing pressure stems from polypropylene single-use substitution in mobile veterinary settings. Price sensitivity concentrates in Indian educational institutions and Brazilian training programs, while Japanese prosthodontists and United States dental service organizations exhibit alloy-grade inelasticity.
Supply Chain Analysis
Tariff exposure between United States and Chinese raw material suppliers dominates supply chain risk assessment for stainless steel input sourcing. Manufacturing concentrates in Germany, China, and India, with Solingen anchoring premium CNC milling and Guangdong province hosting mid-tier contract forging. Raw material dependencies center on surgical-grade 316L stainless, Ti-6Al-4V titanium alloy, and medical-grade polypropylene resin. Single-source vulnerability persists in German precision grinding equipment for serrated jaw geometries. Distribution runs through Henry Schein and Patterson Dental integrated networks across North America, with direct manufacturer contracting displacing traditional distributor markups in United States dental service organization procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sterile processing engineering capability anchors competitive viability in this market, with documented reprocessing validation protocols representing the scarcest specialized skill set. Manufacturers lacking FDA-compliant cleaning validation documentation face exclusion from United States hospital system procurement.
For Market Incumbents: Build regulatory documentation moats through captive sterile processing engineering teams capable of ISO 17665 steam sterilization validation and FDA 510(k) reprocessing protocol submission. Invest in titanium alloy vertical integration to defend margin position against commodity stainless volatility. Additive manufacturing capacity in Switzerland or Japan offers prototyping speed advantages against mid-tier competitors dependent on conventional CNC lead times. For New Entrants and Emerging Players: Build out disposable polymer manufacturing capacity targeting Indian tier-2 cities and Brazilian mobile veterinary services where sterilization infrastructure gaps persist. CDSCO streamlined import rules reduce regulatory friction for certified manufacturers entering Maharashtra and Karnataka dental school procurement. Direct-to-clinic e-commerce platforms bypass entrenched distributor relationships in tele-dentistry channel development. For Investors and Strategic Acquirers: Capital is best deployed toward German-engineered mid-cap specialists with ISO 13485 certification and established notified body relationships under EU MDR. Long-term viability hinges on reprocessing validation expertise scarcity persisting through the analysis window. Watch FDA guidance document revisions on single-use equivalency claims as the critical inflection signal for reusable instrument demand trajectory.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Notified Body Certification | Carl Martin GmbH and Solingen manufacturers leverage CE marking for Bavarian university hospital access. |
| Hybrid Additive Manufacturing Deployment | Swiss and Japanese university hospitals pilot selective laser melting for complex jaw geometries. |
| Direct-to-Clinic E-Commerce Platform | Tele-dentistry channels bypass Henry Schein markups for standardized instrument configurations. |
| Disposable Polypropylene Scale-Up | Indian contract manufacturers capture mobile clinic demand where autoclave infrastructure is absent. |
| Reprocessing Validation Documentation | FDA 510(k) clearance pathways require sterile processing engineering investment for United States hospital access. |
Study Parameters
A spread of perspectives from dental instrument procurement managers, sterile processing engineers, biomedical equipment specialists, and GPO contracts administrators converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation against FDA 510(k) premarket notification databases, ISO 13485 certification registries, CDSCO import approval records, and EU MDR notified body publication logs. Bottom-up demand modeling from clinic procurement volumes and top-down supply assessment from manufacturing capacity declarations were triangulated for convergence.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with segmentation modeled across material alloy tier, jaw geometry configuration, end-user setting, and regional regulatory cluster. CAGRs were derived from installed base turnover rates and replacement cycle analysis. Industry-specific forecast inputs included dental school enrollment trajectories in India and Brazil, dental service organization consolidation velocity in United States Midwest and Southeast regions, and titanium alloy spot price correlation coefficients.
Stress conditions across stainless steel commodity volatility, EU MDR certification timeline extensions, and single-use polymer substitution rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on regulatory pathway efficiency and procurement channel stability. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surgical Instruments
Global Bipolar Electrosurgical Devices Market
Surgical Instruments
Hand-Held Surgical Instruments Market
Surgical Instruments
Surgical Rasps Market
Surgical Instruments
Saudi Arabia General Surgical Devices Market
Surgical Instruments
Spain General Surgical Devices Market
Surgical Instruments
Global Powered Surgical Instruments Market
Surgical Instruments
Surgical Hemostats Market
Surgical Instruments
Japan General Surgical Devices Market
Surgical Instruments
Surgical Drains Market
Surgical Instruments
Global Surgical Suction Instruments Market
Surgical Instruments
Surgical Blades Market
Surgical Instruments
Global Plastic Surgery Instruments Market
Surgical Instruments
Cheilectomy Market
Surgical Instruments
Disposable Laparoscopic Instruments Market
Surgical Instruments
Biosurgery Market
Surgical Instruments
Global Surgical Scissors Market