
 Cell Freezing Media Market | 2026-2036
Cell Freezing Media Market Size, Share, and Industry Trends Forecast 2026-2036
Cell Freezing Media Market Intelligence
Serum-free media is expanding its share in cell freezing formulations as biopharmaceutical manufacturers phase out fetal bovine serum to reduce supply variability and regulatory risk. Thermo Fisher Scientific leverages its cryoprotectant portfolio to anchor North American bioprocessing demand, while Merck KGaA competes through synthetic media R&D intensity in European markets. Lonza Group AG specializes in contract manufacturing-grade freezing media, extending its position across cell therapy CDMO workflows.
Cell freezing media comprises cryoprotectant solutions formulated to maintain cell viability during ultra-low temperature storage, typically incorporating dimethyl sulfoxide or glycerol at concentrations between five and ten percent to prevent intracellular ice crystal formation. These formulations serve the essential commercial purpose of enabling long-term preservation of therapeutic cells, stem cell lines, and blood components for clinical and research applications. Serum-free media commands the formulation technology segment as regulatory pressure tightens on animal-derived inputs, while hydrogel-based cryopreservation represents the fastest-growing sub-area as tissue engineering protocols demand three-dimensional cell matrix stability. Dimethyl sulfoxide retains its dominance in product type share despite ongoing exploration of less toxic alternatives, with trehalose gaining traction in lyophilized powder formats for ambient distribution.
FDA cell and gene therapy guidance shapes product qualification requirements for U.S. manufacturers, while EMA's ATMP framework drives comparable standardization across European markets. ISO 20399 provides international benchmark criteria for ancillary materials in cell processing, directly influencing supplier qualification protocols. Stakeholders must monitor evolving pharmacopeial standards for cryoprotectant purity grades and assess how regional ATMP regulatory divergence affects media formulation registration pathways.
Market Dynamics
Serum-free formulation mandates from EMA and FDA are compressing legacy DMSO-dependent workflows while hydrogel-based cryopreservation protocols open new therapeutic preservation categories. Cell therapy developers face dual pressure to eliminate animal-derived inputs and validate novel matrix-stabilized freezing formats.
Growth Catalysts
- EMA ATMP Framework:The advanced therapy medicinal products classification accelerates regulatory clarity for cryopreserved cell therapies entering European commercial channels.
- Stem cell banking infrastructure:Cord blood repositories and iPSC biobanks in South Korea and Japan are scaling automated cryopreservation lines requiring GMP-grade freezing media.
- Trehalose lyophilization:Sugar-based cryoprotectants enable ambient distribution chains, reducing cold-chain infrastructure burdens for point-of-care cell therapies.
Market Restraints
- DMSO toxicity thresholds:Residual solvent limits in cell therapy products constrain formulation flexibility and complicate downstream purification.
- Fetal bovine serum supply volatility:Bovine spongiform encephalopathy screening protocols and geographic sourcing restrictions create input uncertainty for serum-containing media.
- Glycerol permeability limitations:Slow membrane penetration rates restrict applicability to rapid-freeze protocols demanded by high-throughput cell processing.
Strategic Opportunities
- India CDMO expansion:Contract development organizations serving domestic biopharma are adopting serum-free freezing media to meet export qualification standards.
- Organoid preservation protocols:Three-dimensional tissue models require matrix-embedded cryopreservation formats that conventional suspension media cannot support.
- ISO 20399 harmonization:International ancillary material standards create certification pathways for suppliers seeking multi-jurisdictional cell therapy qualification.
Industry Challenges
- Cryobiology specialist scarcity:Formulation scientists with combined expertise in cell physiology and ice nucleation control command premium compensation and extended hiring timelines.
- Media qualification timelines:Ancillary material validation under FDA cell and gene therapy guidance requires 18-24 month stability studies that delay product launch.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cell Freezing Media Market |
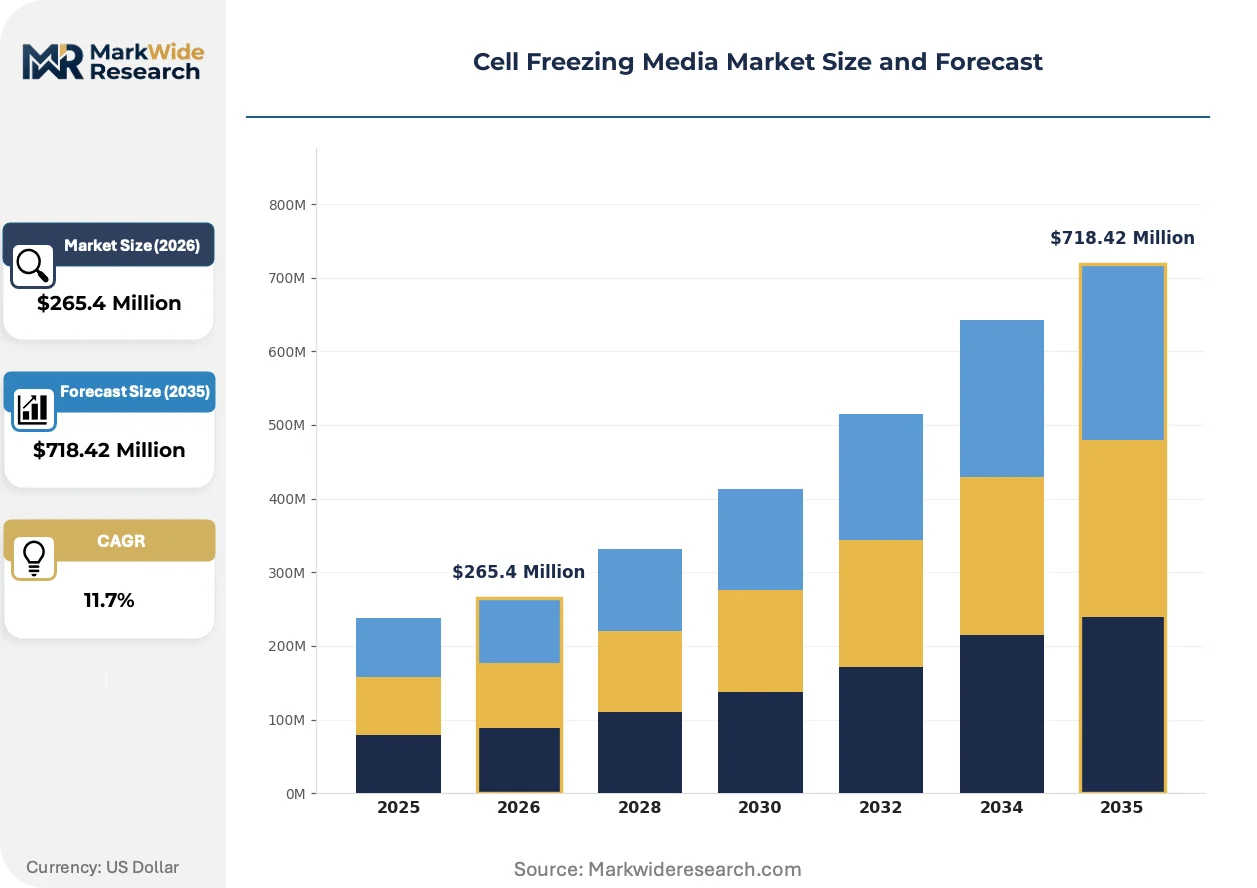
| Market Size in 2026 | $265.4 Million |
| Market Size in 2035 | $718.42 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dimethyl Sulfoxide, Glycerol, Polyethylene Glycol, Ethylene Glycol, Sucrose, Trehalose Application: Stem Cell Preservation, Blood Banking, Fertility Clinics, Tissue Engineering, Regenerative Medicine, Cell Therapy End User: Biopharmaceutical Companies, Research Institutes, Academic Laboratories, Contract Manufacturing Organizations Formulation Technology: Cryoprotectant Solutions, Serum-Free Media, Animal Component-Free, Synthetic Media, Hydrogel-Based, Lyophilized Powders |
| Companies Covered | Sartorius AG, AMSBIO, Thermo Fisher Scientific Inc., Lonza Group AG, Cytiva, Merck KGaA, HiMedia Laboratories, STEMCELL Technologies Inc., BioLife Solutions Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cell Freezing Media Market Strategic Shifts & Innovations
Formulation chemists are converging on synthetic polymer cryoprotectants and programmable freezing profiles that displace static DMSO-glycerol binaries. These advances reshape supplier R&D priorities and end-user equipment procurement.
Hydrogel-encapsulated cryopreservation is expanding into tissue engineering workflows. The technology immobilizes cells within crosslinked polymer networks during freezing. Academic medical centers and organoid developers in Germany and the Netherlands are piloting these formats for liver and neural tissue models. The approach is expanding into commercial preservation service offerings as contract manufacturers seek differentiation in cell therapy logistics.
REACH chemical registration requirements are tightening purity specifications for dimethyl sulfoxide and glycerol entering European biopharmaceutical supply chains. The regulation forces reformulation of legacy media products and accelerates supplier audits for residual solvent documentation. German and Swiss media manufacturers are responding with dedicated pharmaceutical-grade production lines and enhanced certificate of analysis protocols.
Cell therapy developers are consolidating supplier relationships around qualified ancillary material vendors with documented regulatory support files. Large biopharma sponsors now require freezing media suppliers to provide drug master file references and participate in joint regulatory meetings. This concentration is most pronounced in United States and United Kingdom markets where FDA and MHRA inspection histories carry significant weight in vendor selection.
Cell Freezing Media Market Segmentation
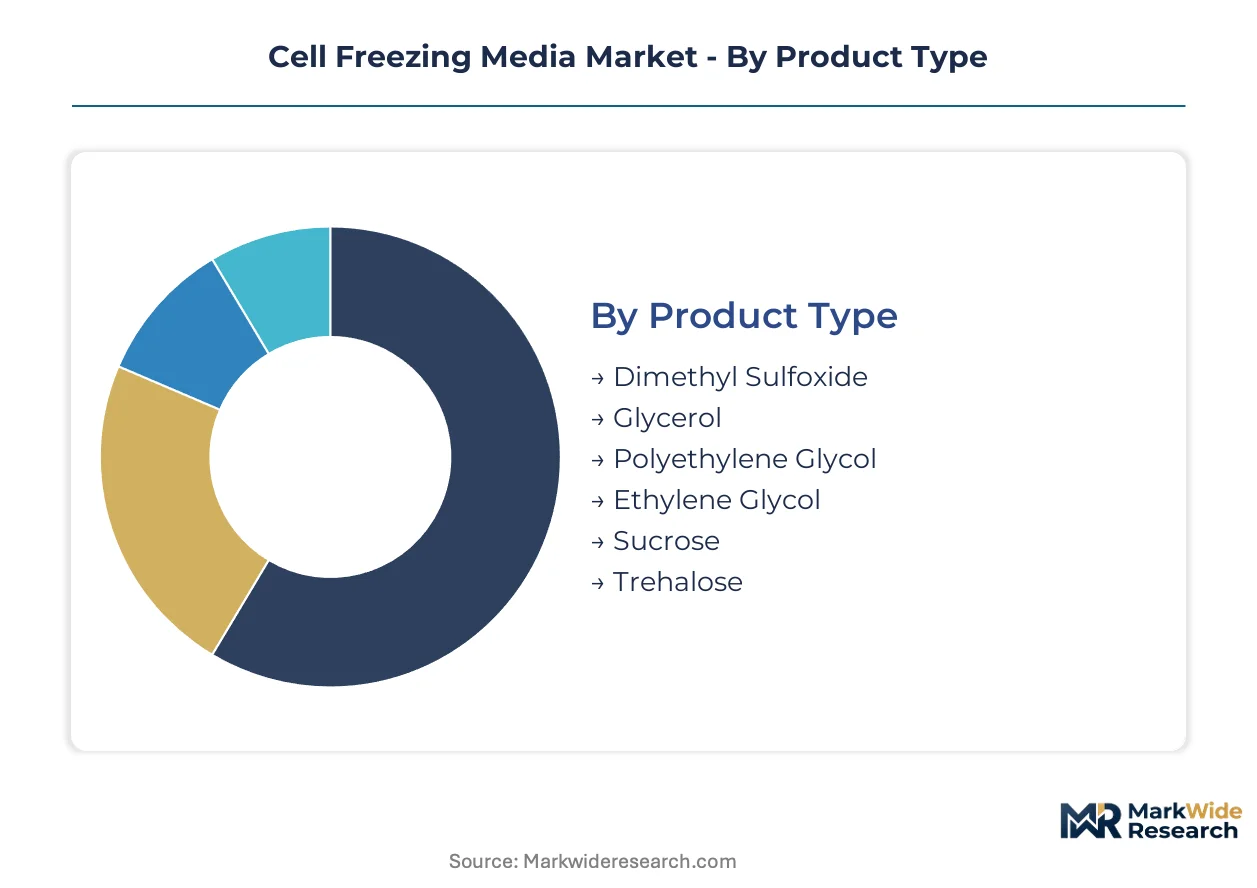
Cell freezing media segmentation reveals how formulation chemistry, therapeutic application, and regulatory compliance intersect to determine procurement priorities. Distinct capital requirements across cryoprotectant types and end-user workflows shape supplier positioning strategies.
Product Type:
Capital intensity varies sharply across cryoprotectant chemistries, with DMSO and glycerol demanding pharmaceutical-grade purification infrastructure while sugar-based alternatives require lyophilization capabilities.
- Dimethyl Sulfoxide:This sulfur-containing solvent penetrates cell membranes to prevent intracellular ice nucleation at concentrations between five and ten percent. Demand concentrates in United States cell therapy manufacturing where FDA guidance mandates documented cryoprotectant purity grades, though residual toxicity thresholds constrain formulation flexibility.
- Glycerol:A trihydroxy alcohol with slower membrane permeation kinetics that suits gradual cooling protocols for blood component preservation. Blood banking networks in Germany and Japan specify glycerol-based formulations for erythrocyte cryopreservation, with automated deglycerolization equipment representing significant ancillary capital investment.
- Polyethylene Glycol:Synthetic polymer cryoprotectants with tunable molecular weights for controlled ice growth modulation.
- Ethylene Glycol:Rapid-penetration alternative deployed in high-throughput stem cell processing workflows.
- Sucrose:Non-permeating sugar cryoprotectant combined with permeating agents in multi-component formulations.
- Trehalose:Disaccharide enabling lyophilized powder formats for ambient distribution chains.
Dimethyl sulfoxide absorbs the bulk of installed capacity; trehalose is expanding most quickly.
Application:
Application segmentation tracks therapeutic value chains from repository banking through commercial cell therapy manufacturing, with capital deployment heaviest in GMP-compliant production environments.
- Stem Cell Preservation:Cord blood repositories and induced pluripotent stem cell biobanks require scalable cryopreservation protocols with validated post-thaw viability metrics. Automated controlled-rate freezers in South Korea and Japan consume specialized media formulations at industrial scale.
- Cell Therapy:Commercial manufacturing of CAR-T and other advanced therapy medicinal products demands serum-free, animal-component-free media with complete regulatory documentation. EMA and FDA qualification timelines of eighteen to twenty-four months concentrate procurement among qualified ancillary material suppliers.
- Blood Banking:Established erythrocyte and platelet preservation protocols with standardized glycerol formulations.
- Fertility Clinics:Oocyte and embryo cryopreservation with specialized slow-freeze and vitrification media.
- Tissue Engineering:Three-dimensional constructs requiring matrix-embedded preservation formats.
- Regenerative Medicine:Diverse cell types with customized cryoprotectant optimization requirements.
Stem cell preservation commands the deepest supplier relationships; cell therapy shows the steepest expansion trajectory.
End User:
Customer type segmentation distinguishes between research-scale flexibility and commercial-scale regulatory rigor, with procurement authority and technical qualification requirements diverging accordingly.
- Biopharmaceutical Companies:Sponsors of approved and investigational cell therapies maintain qualified supplier programs with drug master file requirements and joint regulatory meeting participation. Large developers in the United States and United Kingdom consolidate purchasing around vendors with documented FDA and MHRA inspection histories.
- Contract Manufacturing Organizations:CDMOs serving cell therapy developers adopt serum-free freezing media to meet multi-sponsor qualification standards and differentiate logistics capabilities. Indian contract manufacturers are upgrading to animal-component-free formulations for export market access.
- Research Institutes:Academic and government laboratories with formulation flexibility and cost sensitivity.
- Academic Laboratories:Principal investigator-driven procurement with diverse cryopreservation protocols.
Biopharmaceutical companies dominate value-based procurement; contract manufacturing organizations are gaining share fastest.
Formulation Technology:
Technology segmentation captures the shift from legacy serum-containing formats toward synthetic and matrix-stabilized alternatives, with R&D intensity determining competitive positioning.
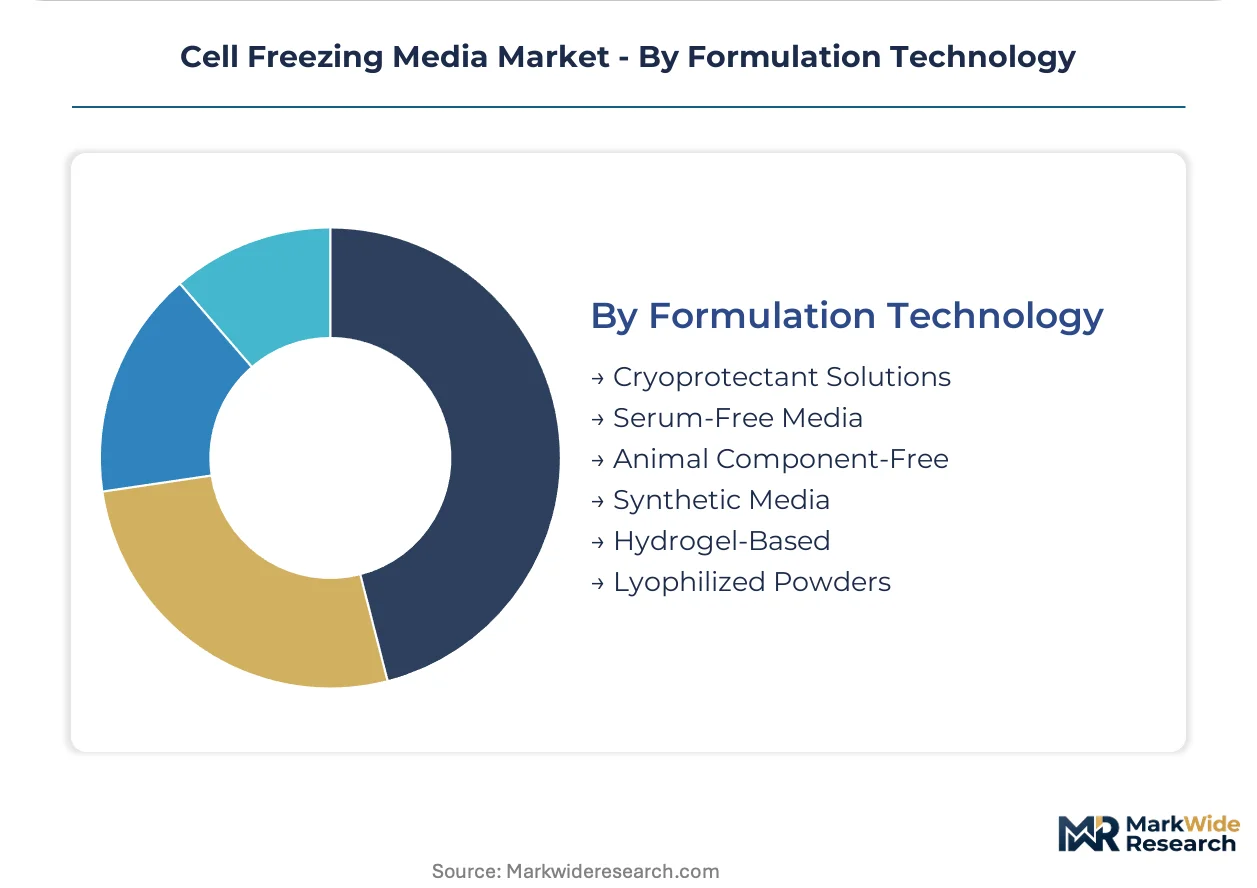
- Serum-Free Media:Chemically defined formulations eliminating fetal bovine serum to reduce supply variability and regulatory risk. EMA-aligned manufacturers in Germany drive specification tightening as animal-component-free compliance becomes mandatory for commercial ATMP production.
- Hydrogel-Based:Crosslinked polymer networks immobilizing cells during freezing for three-dimensional tissue model preservation. Academic medical centers in Germany and the Netherlands pilot these formats for liver and neural organoid applications.
- Cryoprotectant Solutions:Conventional liquid DMSO and glycerol formulations with established handling protocols.
- Animal Component-Free:Media with documented absence of all animal-derived inputs beyond serum.
- Synthetic Media:Fully chemically defined formulations with recombinant protein supplements.
- Lyophilized Powders:Trehalose-based formats enabling ambient storage and distribution.
Serum-free media holds the largest installed base; hydrogel-based formats are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cell freezing media procurement concentrates where cell therapy manufacturing and biobanking infrastructure have achieved regulatory scale. The United States, Germany, Japan, South Korea, and India each present distinct demand profiles shaped by local ATMP frameworks and cold-chain investment cycles.
United States
FDA cell and gene therapy guidance drives qualified supplier programs among commercial CAR-T manufacturers. The agency's eighteen-to-twenty-four month ancillary material validation timelines compress vendor selection to documented inspection histories. Greater Boston and the San Francisco Bay Area anchor domestic demand, with biopharma sponsors consolidating procurement around vendors holding active drug master files.
Germany
EMA-aligned manufacturers are eliminating fetal bovine serum from freezing formulations ahead of formal animal-component-free mandates. REACH chemical registration requirements tighten DMSO and glycerol purity specifications entering pharmaceutical supply chains. Academic medical centers in Heidelberg and Munich pilot hydrogel-encapsulated preservation for liver and neural organoid applications.
Japan
PMDA oversight of regenerative medicine products accelerates GMP-grade freezing media qualification for iPSC-derived therapies. Cord blood repositories and stem cell biobanks deploy automated controlled-rate freezers at industrial scale. The Kanto region around Tokyo concentrates domestic manufacturing demand, with METI funding supporting cryopreservation infrastructure modernization.
South Korea
MFDS fast-track pathways for cell therapies compress development timelines, forcing parallel qualification of serum-free freezing media. National investment in stem cell banking infrastructure drives automated cryopreservation line deployment. The Seoul Capital Area hosts the majority of domestic CDMO capacity upgrading to animal-component-free formulations for export market access.
India
CDSCO export qualification requirements push contract manufacturers toward serum-free media adoption. Domestic biopharma sponsors serving European and North American markets face ancillary material documentation demands absent from legacy supplier relationships. Maharashtra and Gujarat concentrate upgrading CDMO capacity, with Bangalore-based research institutes driving formulation flexibility at smaller scale.
Cell Freezing Media Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with serum-free formulation expertise commanding premium positioning in commercial cell therapy workflows. The vendor base organizes around three strategic archetypes: diversified life science conglomerates with cryoprotectant portfolios, CDMO-aligned media specialists, and research-grade suppliers scaling GMP capabilities. Consolidation pressure is accelerating as large biopharma sponsors reduce qualified vendor lists. Technology licensing and geographic expansion represent the dominant competitive moves, with European and North American players seeking manufacturing proximity to Asian cell therapy hubs.
Among diversified conglomerates, Thermo Fisher Scientific Inc. and Merck KGaA exemplify contrasting geographic emphases. Lonza Group AG occupies a distinct position as a CDMO-anchored specialist. Thermo Fisher Scientific Inc. leverages North American bioprocessing demand through its cryoprotectant portfolio breadth. Merck KGaA competes via synthetic media R&D intensity in European markets. Lonza Group AG extends its contract manufacturing-grade freezing media across cell therapy CDMO workflows. These three patterns—portfolio breadth, R&D intensity, and CDMO integration—structure competitive differentiation as regulatory qualification requirements tighten.
| Leading Market Players |
|---|
| Sartorius AG |
| AMSBIO |
| Thermo Fisher Scientific Inc. |
| Lonza Group AG |
| Cytiva |
| Merck KGaA |
| HiMedia Laboratories |
| STEMCELL Technologies Inc. |
| BioLife Solutions Inc. |
| Others |
Cost & Logistics Intelligence
EMA animal-component-free mandates are compressing formulation flexibility and forcing suppliers toward pharmaceutical-grade purification infrastructure that commands premium positioning. This specification tightening concentrates procurement authority among qualified ancillary material vendors with documented regulatory support files, amplifying price premiums for serum-free and hydrogel-based formats while squeezing legacy DMSO-dependent products.
Pricing Analysis
Volume-margin splits favor high-volume blood banking contracts at compressed returns versus cell therapy formulations at elevated premiums. Three-tier pricing structure across pharmaceutical-grade, GMP-certified, and research-use levels separates qualification depth and documentation rigor. Pricing pressure stems from CDMO consolidation around qualified vendor lists, compressing margins for non-specialized suppliers. Research institutes exhibit highest price sensitivity; commercial cell therapy sponsors prioritize regulatory documentation over unit cost.
Supply Chain Analysis
Regional distribution centers in Germany, the United States, and Japan anchor hub-and-spoke patterns for temperature-sensitive media fulfillment. Manufacturing concentration rests on German chemical synthesis infrastructure for DMSO and glycerol purification, Swiss pharmaceutical-grade production lines, and North American formulation facilities. Raw material dependencies include pharmaceutical-grade dimethyl sulfoxide, recombinant protein supplements, and synthetic polymer precursors. Single-source vulnerability for fetal bovine serum alternatives elevates risk exposure. Distribution runs through qualified ancillary material suppliers with drug master file capabilities and cold-chain logistics partners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is becoming a vertical-integration race as suppliers pursue backward control over pharmaceutical-grade DMSO and glycerol purification to secure margin capture and regulatory documentation continuity.
For Market Incumbents: Deploy drug master file deepening to defend qualified supplier status against emerging synthetic polymer specialists. Incumbents should expand regulatory affairs capacity to support joint FDA and EMA meetings with cell therapy sponsors, while securing captive supply of pharmaceutical-grade cryoprotectant inputs to offset REACH-driven purity cost escalation. For New Entrants and Emerging Players: Begin with organoid preservation protocol development to exploit matrix-embedded cryopreservation white space in Germany and the Netherlands academic medical centers. Hydrogel-based formats for three-dimensional tissue models represent the most penetrable segment, with go-to-market traction through contract manufacturing organization pilot programs offering logistics differentiation. For Investors and Strategic Acquirers: Re-rating potential sits with CDMO-anchored media specialists given EMA ATMP framework acceleration and sponsor vendor consolidation. Long-term viability favors suppliers with demonstrated FDA inspection histories and synthetic formulation R&D depth. Watch for ISO 20399 certification adoption rates as the signal indicating qualification barrier height and competitive moat durability.| Strategic Initiative | Industry Significance |
|---|---|
| Pharmaceutical-Grade Purification Capacity Expansion | REACH compliance and EMA purity mandates force dedicated production line investment in Germany and Switzerland. |
| Synthetic Polymer Cryoprotectant R&D Partnership | Academic collaborations in the Netherlands accelerate hydrogel-encapsulated protocol validation for organoid applications. |
| Drug Master File Deepening Program | FDA cell and gene therapy guidance elevates documented regulatory support files to vendor selection threshold. |
| CDMO Logistics Integration | Indian contract manufacturers adopt serum-free formulations to meet CDSCO export qualification for European and North American markets. |
| Trehalose Lyophilization Scale-Up | Ambient distribution chain demand from point-of-care cell therapies drives powder format production investment. |
Research Approach
FDA guidance documents, EMA ATMP framework publications, and ISO 20399 ancillary material standards formed the secondary backbone for regulatory requirement mapping. Primary interviews with cell therapy development executives, regulatory affairs leads at biopharmaceutical sponsors, CDMO procurement managers, and cryobiology formulation scientists combined with secondary validation across pharmacopeial compendia and chemical registration databases. Bottom-up segment sizing and top-down market reconciliation anchored demand quantification.
Historical trendline analysis of cryoprotectant formulation adoption, serum-free media penetration, and hydrogel-based protocol development informed projection modeling across the analysis window. Segmentation dimensions included cryoprotectant chemistry, therapeutic application, end-user type, and formulation technology tier. CAGRs derived from regression-adjusted growth rate calibration against stem cell banking infrastructure investment cycles and cell therapy manufacturing capacity expansion. Industry-specific inputs incorporated automated controlled-rate freezer deployment rates and GMP-grade media qualification timeline data.
Underlying measurement precision varies by segment; cell therapy application and serum-free formulation technology carry tighter precision than research-grade and conventional cryoprotectant solution categories. Forecasts reflect documented assumption sets regarding regulatory timeline stability and cryoprotectant chemistry substitution elasticity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Single-Use Sterilization Wraps Market
Medical Supplies
Global Hot and Cold Therapy Packs Market
Medical Supplies
Disposable Bed Sheets Market
Medical Supplies
Safety Needles Market
Medical Supplies
Europe Ostomy Drainage Bags Market
Medical Supplies
Global Dialysis Concentrate Market
Medical Supplies
Oral Syringes Market
Medical Supplies
GCC Syringes and Needles Market
Medical Supplies
Enteral Syringes Market
Medical Supplies
Knife Sterilizer Market
Medical Supplies
Retractable Needle Safety Syringes Market
Medical Supplies
Asia-Pacific Human Fibrin Glue Market
Medical Supplies
Catheter Tip Syringe Market
Medical Supplies
Global Nasal Aspirator Market
Medical Supplies
Middle East and Africa Medical Rubber and Balloon Products Market
Medical Supplies
Ostomy Care Market