
 Cheilectomy Market | 2026-2036
Cheilectomy Market Size, Share, and Industry Trends Forecast 2026-2036
Cheilectomy Market Analysis
The EU Medical Device Regulation is shifting the cost-of-entry calculus for cheilectomy implant manufacturers, requiring expanded clinical documentation and quality management audits. DePuy Synthes leverages its broad orthopedic portfolio to navigate these compliance layers across European markets. Zimmer Biomet anchors its position through specialized foot and ankle hardware lines with established surgeon training networks. Stryker competes by integrating cheilectomy instruments into its broader arthroscopy ecosystem, reducing hospital vendor consolidation friction.
Cheilectomy denotes surgical removal of bone spurs from the dorsal aspect of the first metatarsophalangeal joint, typically performed with osteotomes, burrs, or powered instrumentation to restore joint motion and relieve impingement pain. The procedure addresses hallux rigidus, a degenerative condition where dorsal osteophytes limit dorsiflexion and generate mechanical symptoms during gait. Among delivery modes, minimally invasive surgery and arthroscopy represent the fastest-growing categories as surgeons seek reduced soft-tissue disruption and faster rehabilitation protocols. Instruments dominate product type revenue due to recurrent replacement cycles and sterilization wear, while implants command premium positioning in revision cases requiring concomitant arthrodesis or resurfacing.
FDA 510(k) clearance pathways shape cheilectomy device commercialization timelines in the United States, while the EU MDR and ISO 13485 quality standards govern European market access and post-market surveillance obligations. Health Canada's Medical Devices Bureau and Australia's TGA impose parallel but distinct classification requirements that fragment regulatory strategy for multinational manufacturers. Stakeholders must monitor evolving reimbursement codes for outpatient hallux procedures and anticipate how robotic surgery technology integration alters capital equipment purchasing decisions across hospital systems.
Market Dynamics
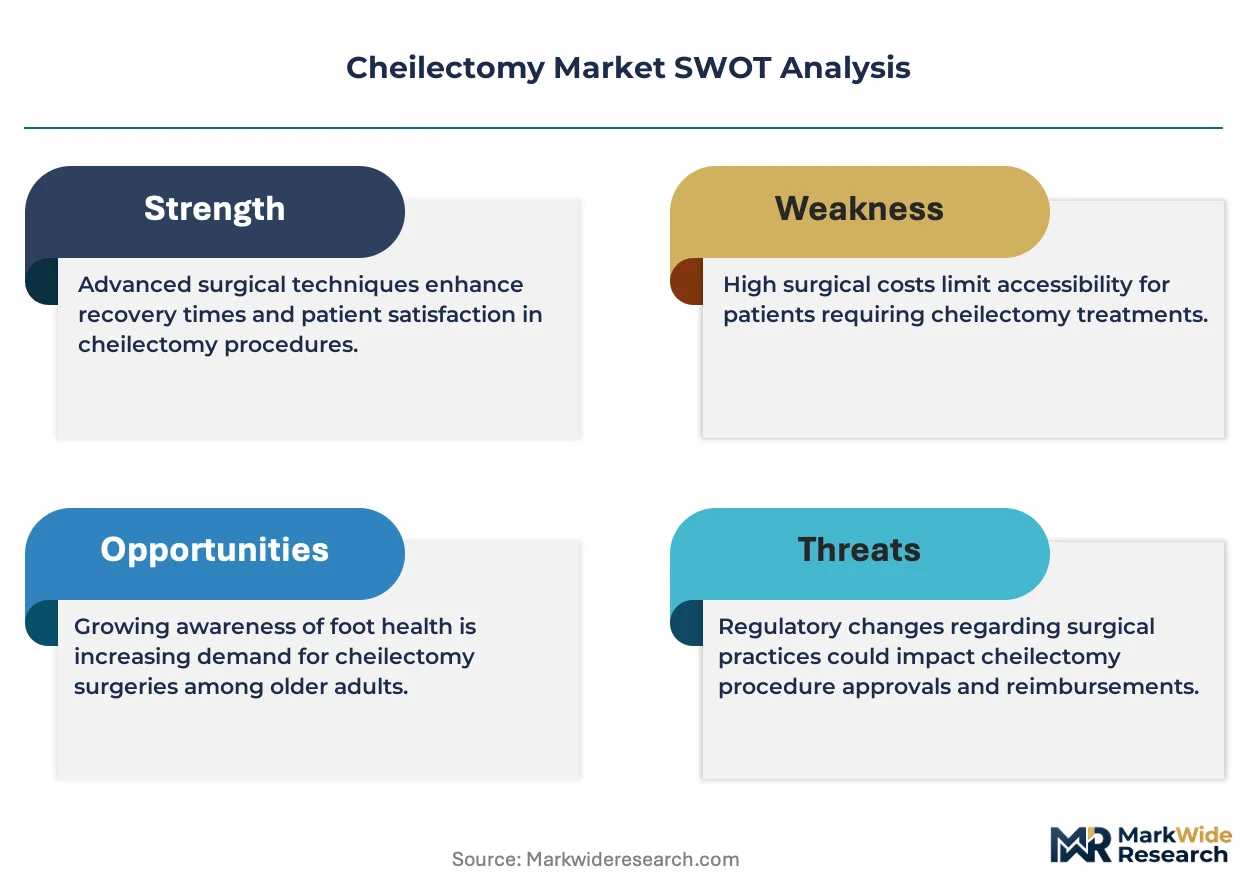
The cheilectomy market pivots on the EU MDR's expanded clinical evidence mandates, which are compressing commercialization timelines and forcing manufacturers to front-load quality management investments before European market entry.
Growth Catalysts
- Ambulatory surgical center expansion:Outpatient migration for foot and ankle procedures accelerates instrument turnover rates and drives demand for compact, sterilization-durable toolsets.
- MDR compliance infrastructure:The EU Medical Device Regulation's post-market surveillance requirements create competitive moats for manufacturers with established quality systems.
- Powered instrumentation adoption:High-speed burrs and precision osteotomes reduce operative time and soft-tissue trauma, expanding surgeon willingness to perform cheilectomy in younger patient cohorts.
Market Restraints
- Titanium and stainless steel input volatility:Raw material price swings compress margins on reusable instrument lines that dominate product-type revenue.
- European notified body concentration:Fewer designated conformity assessment bodies under MDR extend certification queues and delay product launches.
- Non-operative substitute availability:Custom orthotics, intra-articular injections, and physical therapy protocols capture early-stage hallux rigidus cases before surgical intervention.
Strategic Opportunities
- Minimally invasive technique penetration:Percutaneous and arthroscopic approaches remain underdeveloped in community hospital settings, offering white-space expansion for training-intensive platforms.
- Australian TGA parallel approval pathways:Health technology assessment alignment with European CE marking creates efficient secondary market entry for MDR-compliant portfolios.
- Implant-arthroscopy convergence:Hybrid systems combining cheilectomy instruments with cartilage resurfacing implants address revision cases and command premium positioning.
Industry Challenges
- Podiatric surgical training pipeline:Fellowship program capacity constraints limit the rate at which new surgeons adopt advanced arthroscopic techniques.
- Legacy sterilization infrastructure:Hospital central sterile departments face workflow friction integrating powered instrumentation with existing autoclave cycles and tracking systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cheilectomy Market |
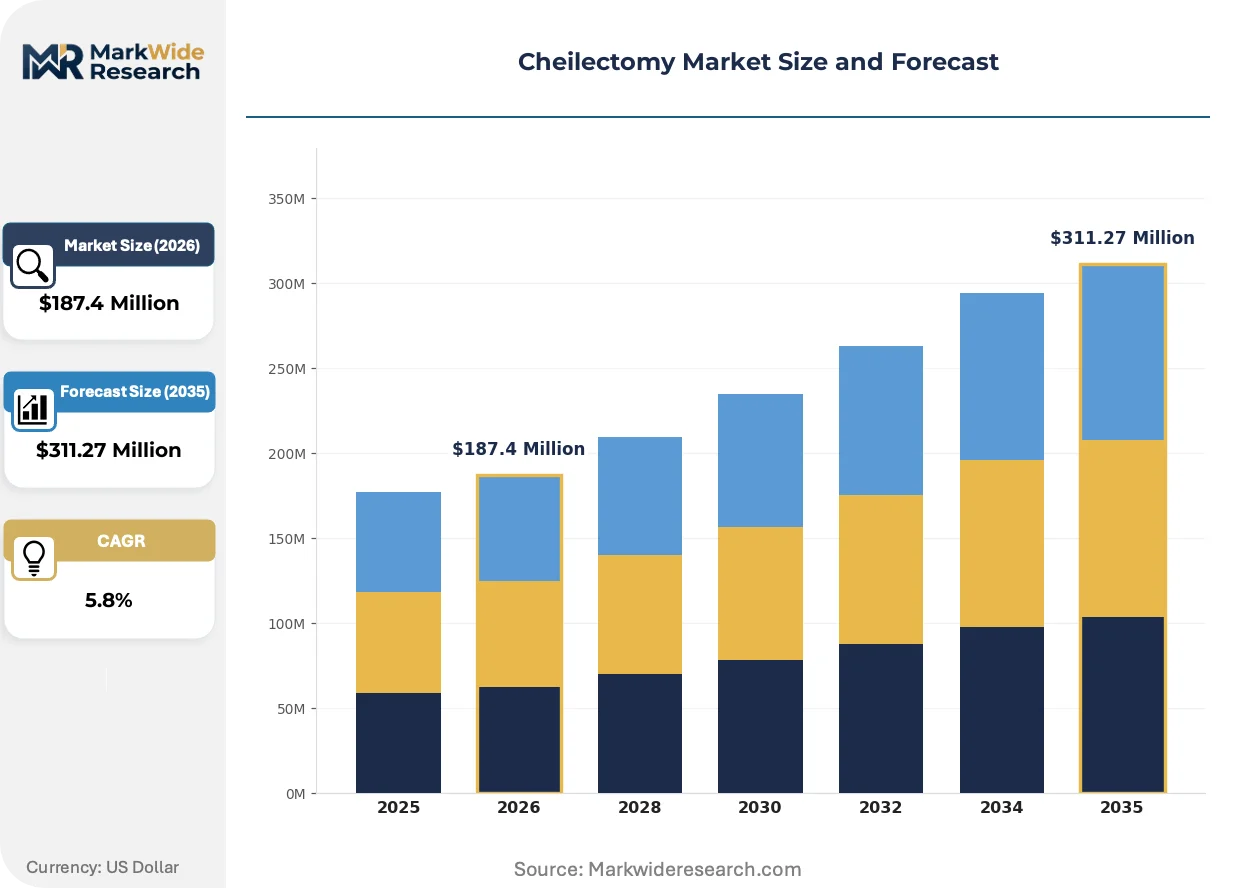
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Instruments, Implants, Sutures, Consumables Delivery Mode: Open Surgery, Minimally Invasive Surgery, Arthroscopy, Endoscopy End User: Hospitals, Clinics, Ambulatory Surgical Centers, Rehabilitation Centers Technology: Laser Surgery, Ultrasound, Robotic Surgery, Traditional Surgery |
| Companies Covered | DePuy Synthes, Acumed, Zimmer Biomet, STERIOD S.p.A., Henry Schein, Wright Medical Group, Integra LifeSciences Corporation, Arthrex, Stryker, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cheilectomy Market Emerging Trajectories
Technological convergence between arthroscopy and implantable resurfacing systems is redefining procedural boundaries in hallux rigidus treatment, while regulatory harmonization pressures reshape competitive positioning across developed markets.
Arthroscopic cheilectomy systems with integrated irrigation and visualization modules are electrifying the standard of care for dorsal impingement cases. Academic medical centers and high-volume foot and ankle specialists are transitioning these platforms from niche applications to routine use. The shift is compressing demand for traditional open approaches and forcing instrument manufacturers to bundle arthroscopy-compatible toolsets.
REACH substance restrictions and EU MDR biocompatibility requirements are tightening material specifications for implantable components. Manufacturers must reformulate surface coatings and validate new sterilization residuals profiles. The implant segment bears the heaviest compliance burden, with revision arthrodesis hardware facing extended technical documentation reviews.
Hospital purchasing consortia are consolidating vendor relationships for orthopedic capital equipment. Independent ambulatory centers and physician-owned surgery facilities are bypassing traditional distribution tiers through direct manufacturer agreements. The United States exhibits the most pronounced channel compression, where integrated delivery networks leverage procedure volume guarantees for pricing concessions on instrument replacement cycles.
Cheilectomy Market Segmentation
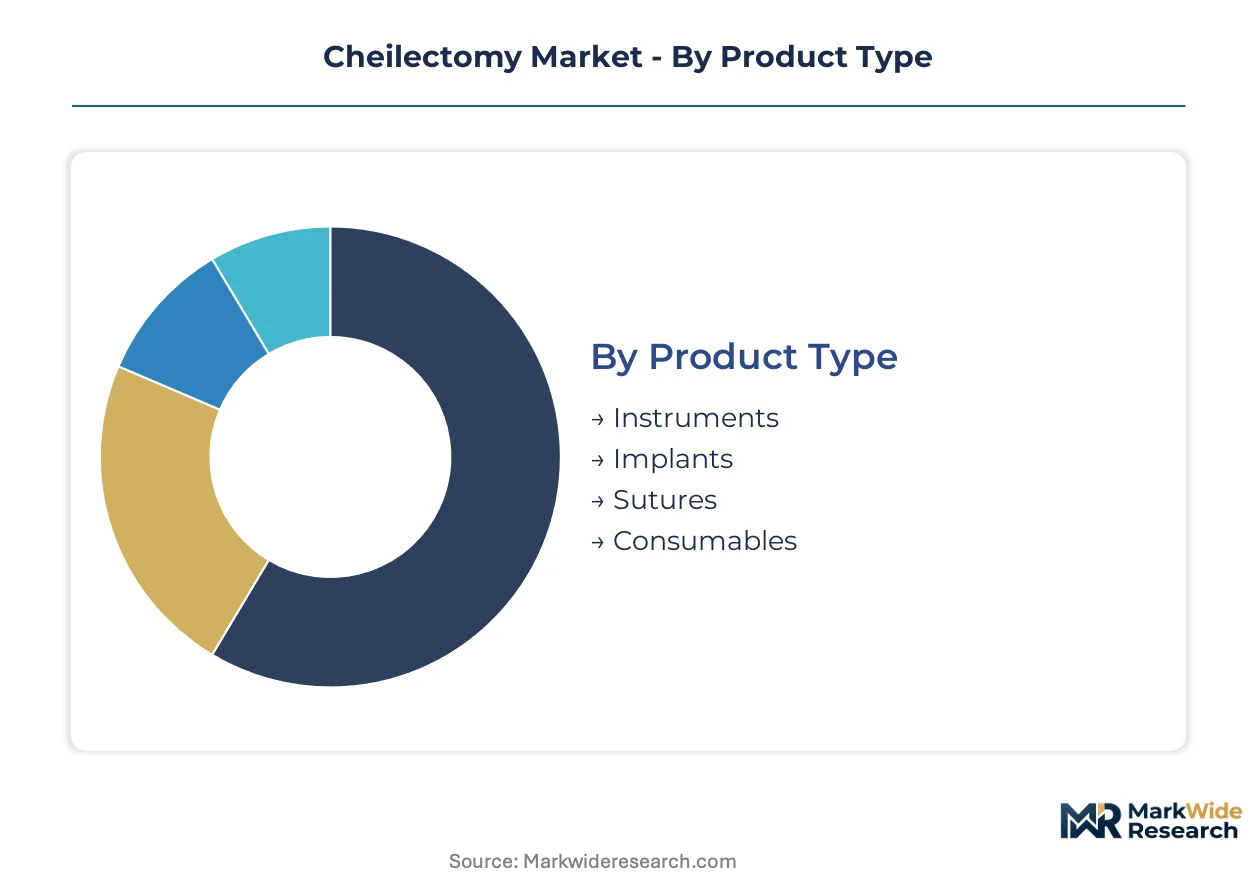
Cheilectomy market segmentation reveals how surgical technique evolution and care setting migration reshape procurement priorities. Manufacturers must align product portfolios across instrument durability, implant biocompatibility, and capital equipment integration to capture value across diverging clinical workflows.
Product Type:
Supply concentration in reusable instrument manufacturing creates margin pressure from raw material volatility, while implant producers face heavier regulatory documentation burdens under MDR and FDA pathways.
- Instruments:Osteotomes, burrs, and powered handpieces fabricated from surgical-grade stainless steel or titanium alloys dominate replacement cycle revenue. Hospital central sterile departments in the United States drive demand for autoclave-compatible designs with integrated tracking chip compatibility.
- Implants:Compression screws, plates, and resurfacing components for concomitant arthrodesis command premium positioning in revision cases. EU MDR technical documentation requirements and REACH substance restrictions compress commercialization timelines for European market entry.
- Sutures:Absorbable and non-absorbable fixation materials for soft-tissue reattachment following osteophyte removal.
- Consumables:Irrigation fluids, drapes, and single-use protective sheaths for powered instrumentation.
Today's leader: Instruments. Tomorrow's challenger: Implants.
Delivery Mode:
Cost tier stratification separates capital-intensive arthroscopy platforms from lower-infrastructure open procedures, with minimally invasive techniques occupying a mid-tier expansion zone.
- Open Surgery:Traditional dorsal approach using direct visualization and manual osteotomes. Community hospitals in rural United States regions sustain demand for lower-capital alternatives where arthroscopy infrastructure remains underdeveloped.
- Minimally Invasive Surgery:Percutaneous techniques through limited incisions with fluoroscopic guidance. Ambulatory surgical centers in Florida and Texas are expanding fastest as outpatient migration accelerates instrument turnover for compact toolsets.
- Arthroscopy:Joint visualization with integrated irrigation and powered shaver systems. Academic medical centers anchor adoption, though fellowship training pipeline constraints limit community penetration.
- Endoscopy:Alternative visualization platforms with distinct optical pathways for select anatomical presentations.
Volume concentrates in open surgery. Steepest expansion trajectory belongs to minimally invasive techniques.
End User:
Customer type fragmentation splits procurement authority between integrated delivery networks with volume-based contracting and independent ambulatory centers seeking direct manufacturer relationships.
- Hospitals:Inpatient and outpatient departments with comprehensive orthopedic service lines. United States hospital purchasing consortia leverage procedure guarantees for pricing concessions on instrument replacement cycles.
- Clinics:Office-based settings with limited surgical capacity, primarily diagnostic and post-operative follow-up.
- Ambulatory Surgical Centers:Physician-owned facilities specializing in same-day discharge protocols. These centers bypass traditional distribution tiers through direct agreements, compressing channel margins fastest in California and Arizona markets.
- Rehabilitation Centers:Post-operative physical therapy and gait retraining facilities with minimal direct product procurement.
Procurement authority rests with hospitals. Fastest volume migration targets ambulatory surgical centers.
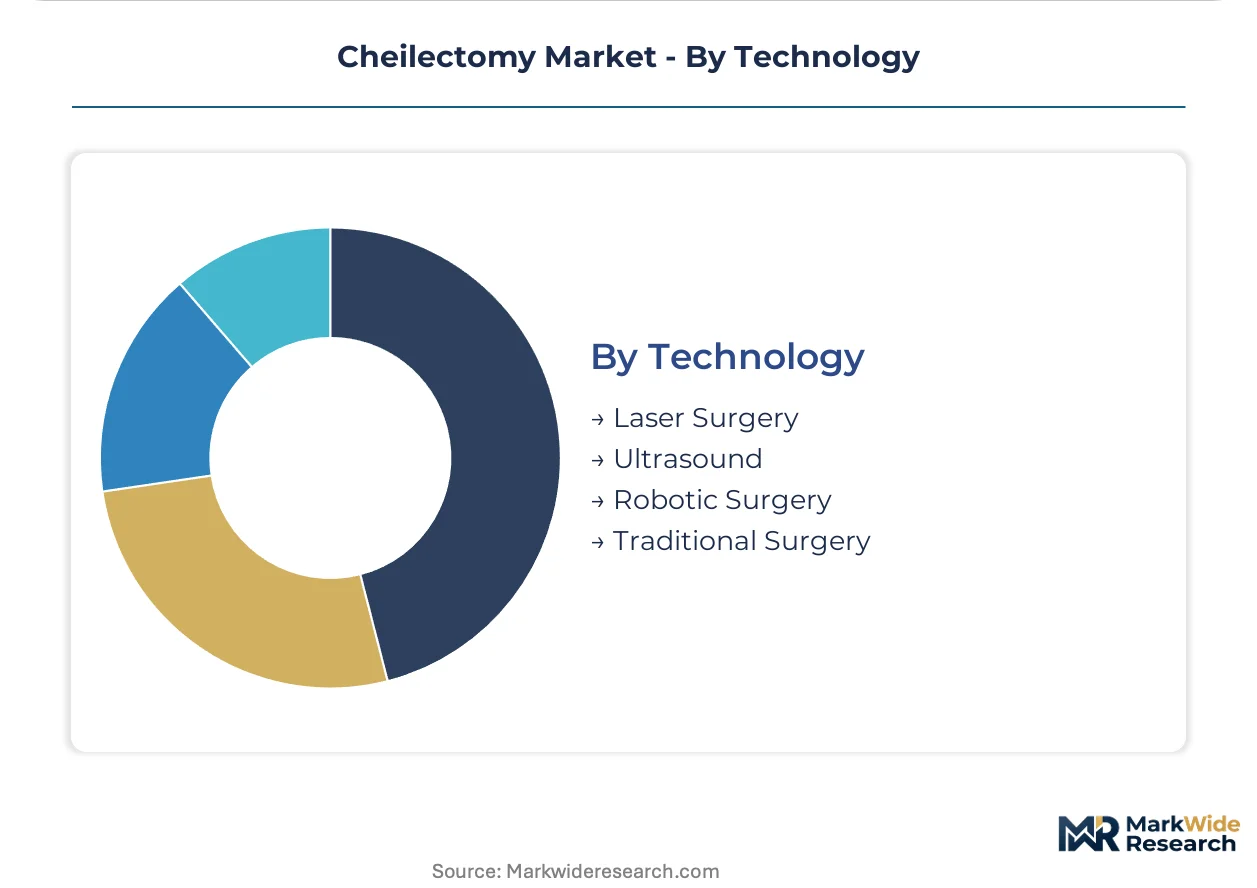
Technology:
Maturity gradients separate established traditional techniques from emerging capital platforms, with robotic systems requiring longest adoption horizons due to training infrastructure demands.
- Laser Surgery:Precision bone ablation with reduced thermal necrosis risk. Limited adoption due to capital equipment costs and specialty training requirements.
- Ultrasound:Piezoelectric cutting systems for selective bone removal with soft-tissue preservation. European clinics in Germany and Switzerland show early adoption for revision cases.
- Robotic Surgery:Computer-navigated osteophyte resection with preoperative planning integration. Academic medical centers in Massachusetts and Pennsylvania pilot systems, though podiatric fellowship capacity constraints delay scalable deployment.
- Traditional Surgery:Manual instrumentation without powered or navigated assistance. Dominates procedure volume globally due to minimal capital requirements and universal surgeon familiarity.
Traditional surgery holds volume dominance. Robotic platforms present the longest-term substitution threat.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cheilectomy techniques originated in German orthopedic surgery during the early twentieth century, with dorsal approach methodologies refined at university clinics in Munich and Berlin before spreading to North American academic centers.
United States
Aging demographics and high procedure volumes sustain market momentum across the Midwest and Southeast. FDA 510(k) clearance pathways shape commercialization timelines for powered instrumentation. The Texas Medical Center in Houston anchors adoption of minimally invasive techniques through fellowship training expansion.
Germany
Academic medical centers in Bavaria and Baden-Württemberg drive arthroscopic technique refinement. EU MDR technical documentation requirements compress commercialization timelines for implant manufacturers. The Stuttgart-Tübingen corridor concentrates sterilization-durable instrument fabrication.
United Kingdom
NHS procurement frameworks favor cost-efficient reusable instrument lines over capital-intensive arthroscopy platforms. MHRA post-market surveillance obligations align with EU MDR transitional provisions. London teaching hospitals pilot ultrasound-guided percutaneous approaches.
Australia
TGA parallel approval pathways with European CE marking create efficient market entry for MDR-compliant portfolios. Private ambulatory surgical centers in Queensland and New South Wales bypass traditional distribution tiers. The Sydney orthopedic cluster advances arthroscopic irrigation system integration.
Switzerland
Swissmedic quality standards exceed baseline EU requirements for implant biocompatibility validation. University Hospital Basel anchors revision arthrodesis technique development. The Basel-Zurich corridor concentrates precision osteotome manufacturing for export markets.
Cheilectomy Market Vendor Landscape
The competitive structure tilts toward diversified orthopedic conglomerates with established regulatory compliance infrastructure. Tier-one participants leverage broad foot and ankle portfolios to amortize EU MDR quality management investments across multiple product lines. Three archetypes dominate: full-spectrum orthopedic conglomerates, specialized foot and ankle hardware firms, and arthroscopy ecosystem integrators. M&A activity concentrates on minimally invasive technique platforms, while geographic expansion targets Australian TGA parallel approval pathways.
Among diversified orthopedic conglomerates, DePuy Synthes and Stryker occupy positions reflecting scale-driven regulatory navigation capabilities. Zimmer Biomet exemplifies the specialized foot and ankle hardware archetype through dedicated surgeon training network investments. Arthrex represents arthroscopy ecosystem integration, anchoring visualization and powered instrumentation convergence. These three firms collectively illustrate how compliance infrastructure, technique specialization, and capital equipment bundling define competitive positioning under tightening European clinical evidence mandates.
| Leading Market Players |
|---|
| DePuy Synthes |
| Acumed |
| Zimmer Biomet |
| STERIOD S.p.A. |
| Henry Schein |
| Wright Medical Group |
| Integra LifeSciences Corporation |
| Arthrex |
| Stryker |
| Others |
Supply Flow & Price Mechanics
Arthroscopy-capable instrument premiums against open-procedure commodity alternatives bifurcate the cheilectomy market, with the former commanding pricing power through bundled visualization systems while the latter faces margin compression from stainless steel input volatility and sterilization-durable design mandates. This tier divergence manifests in divergent supply chain configurations: premium platforms anchor in German and Swiss precision manufacturing clusters with EU MDR-certified quality systems, whereas economy instrument lines draw from consolidated stainless steel forging networks in the United States and China.
Pricing Analysis
Bundled arthroscopy service packages against unbundled instrument-only transactions define the dominant pricing split, with three-tier pricing structure across premium, standard, and economy levels differentiating by visualization integration and surgeon training support. Price differentiation hinges on FDA 510(k) clearance tier and autoclave-cycle durability certification, with ambulatory surgical centers exhibiting highest price sensitivity due to direct manufacturer contracting leverage while academic medical centers absorb premium positioning for fellowship training access. Cost compression in economy reusable instrument lines is intensifying because titanium and stainless steel commodity volatility feeds through fabrication contracts.
Supply Chain Analysis
Workforce availability constraints in Bavarian and Baden-Württemberg machining clusters tether premium osteotome manufacturing to German apprenticeship pipeline capacity, while Tuttlingen-area instrument fabrication draws from Swiss cross-border technical labor pools. Raw material dependencies center on surgical-grade stainless steel from German mills, titanium sponge from Japanese and Russian suppliers, and precision bearings from Swedish specialty manufacturers. Single-source vulnerability concentrates in EU MDR-designated notified body certification queues, which extend lead times for sterilization validation documentation. Distribution runs through hospital purchasing consortia in the United States and direct manufacturer agreements with physician-owned ambulatory centers in California and Arizona.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cheilectomy market functions as a geographic-arbitrage play where EU MDR compliance infrastructure investments in Germany and Switzerland create exportable quality credentials for Australian TGA parallel approval pathways, exploiting regulatory equivalence to bypass redundant clinical documentation costs.
For Market Incumbents: Acquire minimally invasive technique training platforms to consolidate surgeon adoption pathways before fellowship pipeline constraints harden competitive moats. Defend instrument replacement cycle revenue through backward integration into surgical-grade stainless steel forging capacity, mitigating raw material margin volatility. Anchor positioning by embedding powered handpieces within hospital central sterile department workflow integration contracts, raising switching costs against arthroscopy ecosystem competitors. For New Entrants and Emerging Players: Begin with percutaneous cheilectomy instrument sets targeting Florida and Texas ambulatory surgical centers, where outpatient migration concentrates demand for compact, fluoroscopy-compatible toolsets. White-space expansion opportunity sits in community hospital settings across rural United States regions where arthroscopy infrastructure remains underdeveloped and open-procedure alternatives sustain volume. Go-to-market leverage emerges through direct manufacturer agreements bypassing traditional orthopedic distribution tiers, capturing margin compression from channel consolidation. For Investors and Strategic Acquirers: Consolidation pressure builds where EU MDR quality management infrastructure amortization favors diversified orthopedic conglomerates over specialized foot and ankle hardware firms with single-product regulatory exposure. Long-term viability across the analysis window favors acquisition targets possessing parallel approval pathway alignment across FDA, TGA, and Swissmedic jurisdictions, with surgeon training network density as defensible intangible assets. Signal to monitor: fellowship program expansion rates at Texas Medical Center and academic clusters in Massachusetts, which indicate scalable arthroscopic technique adoption velocity.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical Documentation Investment | CE marking pathway acceleration compresses European market entry timelines against notified body queue congestion. |
| Surgeon Training Network Expansion | Fellowship program partnerships at Houston and Philadelphia academic centers lock in arthroscopic technique adoption. |
| Ambulatory Surgical Center Direct Contracting | Bypassing distribution tiers captures California and Arizona outpatient migration volume with margin preservation. |
| Powered Instrumentation Sterilization Integration | Autoclave-cycle compatibility with central sterile department workflows raises hospital switching costs. |
| Australian TGA Parallel Approval Pathway | Regulatory equivalence with European CE marking enables efficient secondary market entry for compliant portfolios. |
Methodological Framework
Bottom-up ambulatory surgical center and hospital procurement modeling reconciled against top-down instrument and implant manufacturing tracking forms the analytical core of this study. Primary interviews with foot and ankle fellowship directors, hospital purchasing committee members, biomedical engineers at central sterile departments, and GPO contracts managers combined with secondary validation against FDA 510(k) filings, EU MDR technical documentation databases, hospital procurement records, and CMS Medicare procedure data. Triangulation across stakeholder inputs and regulatory filings grounds volume estimates in documented clinical adoption patterns.
Historical trendline analysis of procedure migration from inpatient to outpatient settings, coupled with arthroscopic technique diffusion curves from academic to community hospital settings, informs the projection framework. Segmentation dimensions span product type, delivery mode, end user, and technology tier, with CAGRs derived from fitted adoption curves and replacement cycle dynamics. Forecast inputs incorporate EU MDR compliance timeline compression, ambulatory surgical center construction permits in Florida and Texas, and fellowship program capacity expansion at named academic medical centers.
Several conditions sit outside the modeled scope, including robotic surgery platform technical maturation timelines, REACH substance restriction amendments affecting implant coatings, and tariff regime shifts affecting titanium alloy imports. Forecasts reflect assumptions regarding sustained outpatient migration preference and stable EU MDR notified body designation counts. Practitioners should monitor fellowship training pipeline expansion rates, ambulatory center construction permitting velocity, and raw material contract renegotiation cycles for early signals of trajectory revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surgical Instruments
Endometrial Ablation Market
Surgical Instruments
Endoscopic Spinal Surgery Market
Surgical Instruments
Special Purpose Needles Market
Surgical Instruments
Neurosurgical Drills Market
Surgical Instruments
Suture Needles Market
Surgical Instruments
Iris Retractors Market
Surgical Instruments
Electrosurgery Market
Surgical Instruments
Huber Needles Market
Surgical Instruments
Surgical Hand-Access Port Market
Surgical Instruments
Endoluminal Suturing Devices Market
Surgical Instruments
Minimally Invasive Thoracic Surgery Market
Surgical Instruments
Surgical Pliers Market
Surgical Instruments
Middle East and Africa Lancet and Pen Needles Market
Surgical Instruments
Disposable Ophthalmic Surgical Products Market
Surgical Instruments
Equine Surgical Equipment Market
Surgical Instruments
Surgical Tubing Market