
 Ultrasonic Scalpel Market | 2026-2036
Ultrasonic Scalpel Market Size, Share, and Industry Trends Forecast 2026-2036
Ultrasonic Scalpel Market Intelligence
Titanium is expanding its share in ultrasonic scalpel blade substrates, displacing legacy stainless steel assemblies and improving fatigue resistance at high oscillation frequencies. Johnson & Johnson leverages its endomechanical portfolio to bundle ultrasonic generators with stapling platforms across integrated health networks. Medtronic anchors its position through proprietary adaptive tissue sensing algorithms that modulate energy delivery in real time. Stryker Corporation differentiates via its surgical equipment franchise, linking ultrasonic handpieces with operating room integration systems to lock in hospital capital budgets.
An ultrasonic scalpel is a surgical instrument that converts electrical energy into high-frequency mechanical vibrations, typically operating at 55.5 kHz, to cut tissue and coagulate blood vessels simultaneously through protein denaturation without thermal spread to adjacent structures. Its primary purpose is to enable precise dissection with minimal collateral damage in confined anatomical spaces. Handheld devices command the dominant share of product type revenue, though tabletop generator systems capture disproportionate margin pools through multi-year service contracts. Gynecological surgery represents the fastest-growing application segment, driven by rising minimally invasive hysterectomy volumes. Piezoelectric transducer technology leads the technology dimension, while digital control architectures are gaining traction for their programmable tissue-response curves.
The FDA governs ultrasonic scalpels as Class II medical devices under 21 CFR 878.4400, requiring substantial equivalence demonstrations for 510(k) clearances that shape product iteration cycles. The EU Medical Device Regulation imposes stricter clinical evidence thresholds for reusable energy devices, elevating compliance costs for market entrants. China's NMPA mandates domestic type testing for imported ultrasonic surgical systems, creating localization pressure for multinational manufacturers. Stakeholders must monitor how evolving reprocessing validation standards in major jurisdictions determine the economic viability of disposable versus reusable blade strategies.
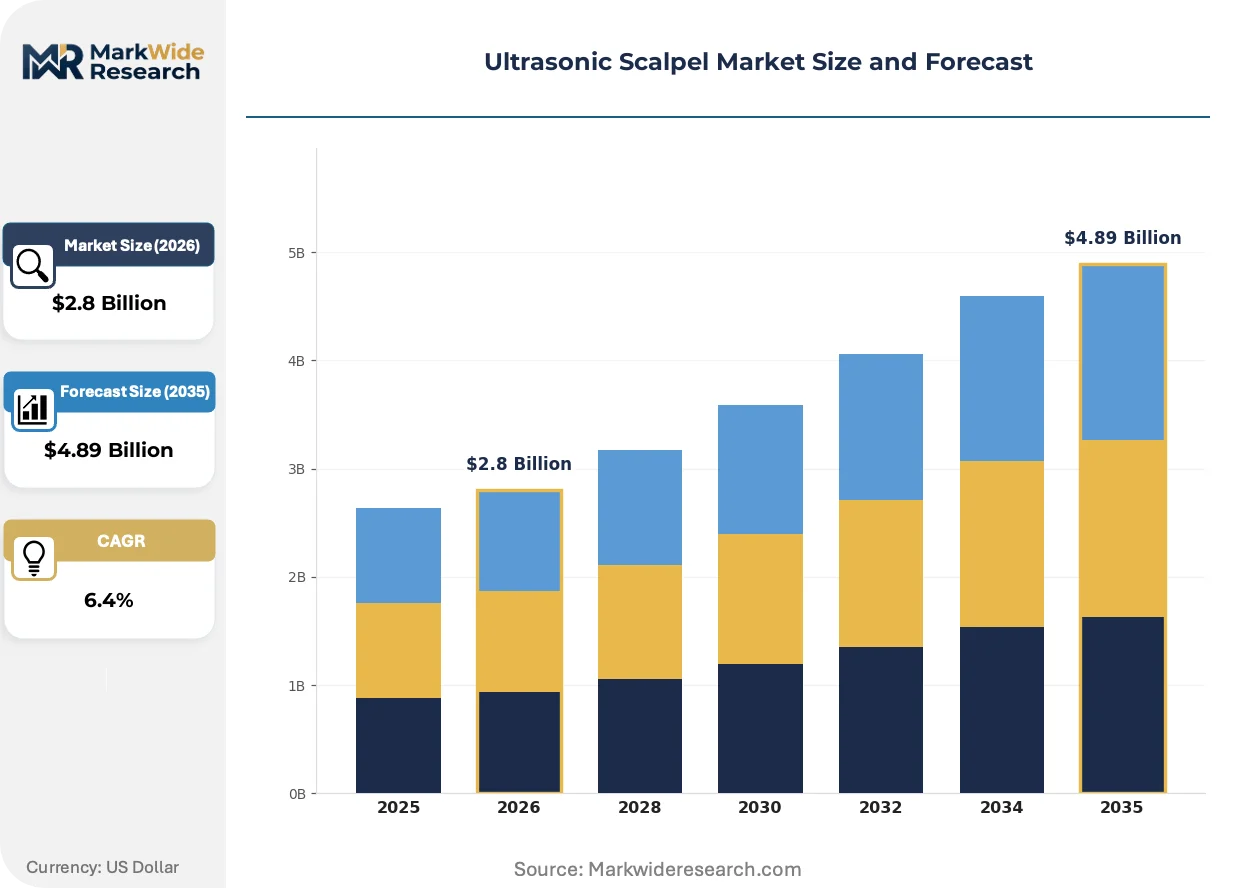
Market Dynamics
The ultrasonic scalpel market is being restructured by the FDA's updated reprocessing guidelines for reusable energy devices, which are forcing manufacturers to redesign validation protocols and compress product development timelines for 510(k) clearances.
Growth Catalysts
- EU MDR Clinical Evidence Thresholds:Stricter requirements for reusable energy devices are accelerating hospital procurement of validated single-use blade systems in European tertiary centers.
- Gynecological Surgery Volumes:Rising minimally invasive hysterectomy procedures are expanding addressable demand for precision coagulation instruments in confined pelvic anatomy.
- Piezoelectric Transducer Advances:Improved ceramic compositions are extending blade fatigue life and reducing thermal spread profiles in high-frequency oscillation regimes.
Market Restraints
- Raw Material Concentration:High-purity piezoelectric ceramics rely on concentrated rare earth processing capacity in East Asian supply chains, creating input vulnerability.
- Capital Equipment Replacement Cycles:Extended depreciation schedules for tabletop generator systems in US integrated delivery networks delay platform upgrade decisions.
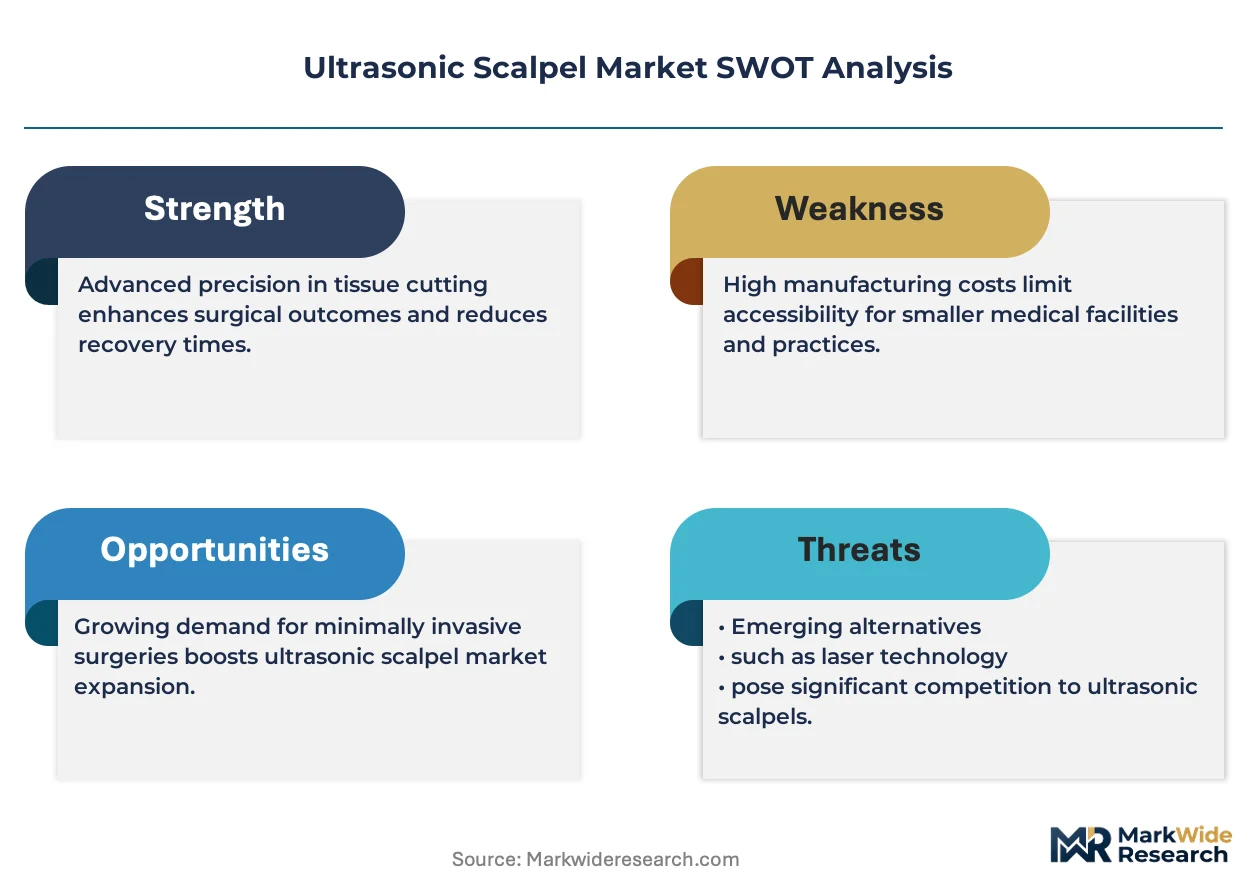
- Electrosurgical Substitution:Radiofrequency-based vessel sealing devices compete on lower per-procedure cost in price-sensitive ambulatory surgical centers.
Strategic Opportunities
- China NMPA Localization Mandates:Domestic type testing requirements for imported surgical systems create partnership openings for joint manufacturing ventures with local device firms.
- Adaptive Tissue Sensing Convergence:Integration of real-time impedance feedback algorithms with digital control architectures enables next-generation programmable response curves.
- Rural Hospital Penetration:Underserved secondary hospitals in India's tier-2 cities present expansion potential for compact, lower-throughput generator configurations.
Industry Challenges
- Biomedical Engineering Talent Scarcity:Shortage of specialists combining acoustic physics expertise with clinical validation experience constrains R&D pipeline velocity.
- Reprocessing Validation Complexity:FDA 510(k) substantial equivalence demonstrations for reusable blade sterilization protocols extend regulatory submission timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ultrasonic Scalpel Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld Devices, Tabletop Systems, Accessories, Software Application: General Surgery, Orthopedic Surgery, Gynecological Surgery, Cardiovascular Surgery End User: Hospitals, Clinics, Ambulatory Surgical Centers, Research Centers Technology: Piezoelectric, Electromagnetic, Ultrasonic Wave, Digital Control |
| Companies Covered | Stryker Corporation, BOWA-Electronic GmbH & Co. KG, Johnson & Johnson, Bioventus Inc., Wuhan BBT Mini-Invasive Medical Tech. Co., Ltd, Medtronic, Axon Medical Solutions, Surgnova Healthcare Technologies, Olympus Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ultrasonic Scalpel Market Strategic Shifts & Innovations
Digital control architectures and adaptive feedback systems are transforming how ultrasonic energy platforms respond to tissue impedance variations, compressing the gap between open and minimally invasive surgical precision.
Adaptive tissue sensing algorithms are decentralizing energy delivery authority from fixed generator outputs to real-time blade-tissue interaction models. General surgery departments in US tertiary hospitals are adopting these systems to reduce lateral thermal damage in laparoscopic dissection. This capability compression is decentralizing procurement decisions from capital equipment committees to individual surgeon preference cards.
The EU Medical Device Regulation's stricter clinical evidence thresholds for reusable energy devices are elevating compliance costs for market entrants. Manufacturers must now generate prospective clinical data for blade reprocessing validation, reshaping product portfolio economics. Disposable blade strategies are gaining favor among European distributors seeking to bypass reusable device regulatory complexity.
Integrated delivery networks in the United States are consolidating procurement authority through system-wide advanced energy platform contracts. Independent ambulatory surgery centers are losing negotiating leverage as hospital networks leverage volume commitments for generator placement and exclusive blade supply agreements. This concentration is most visible in the southeastern US, where regional IDNs have captured majority share of new ultrasonic scalpel installations.
Ultrasonic Scalpel Market Segmentation
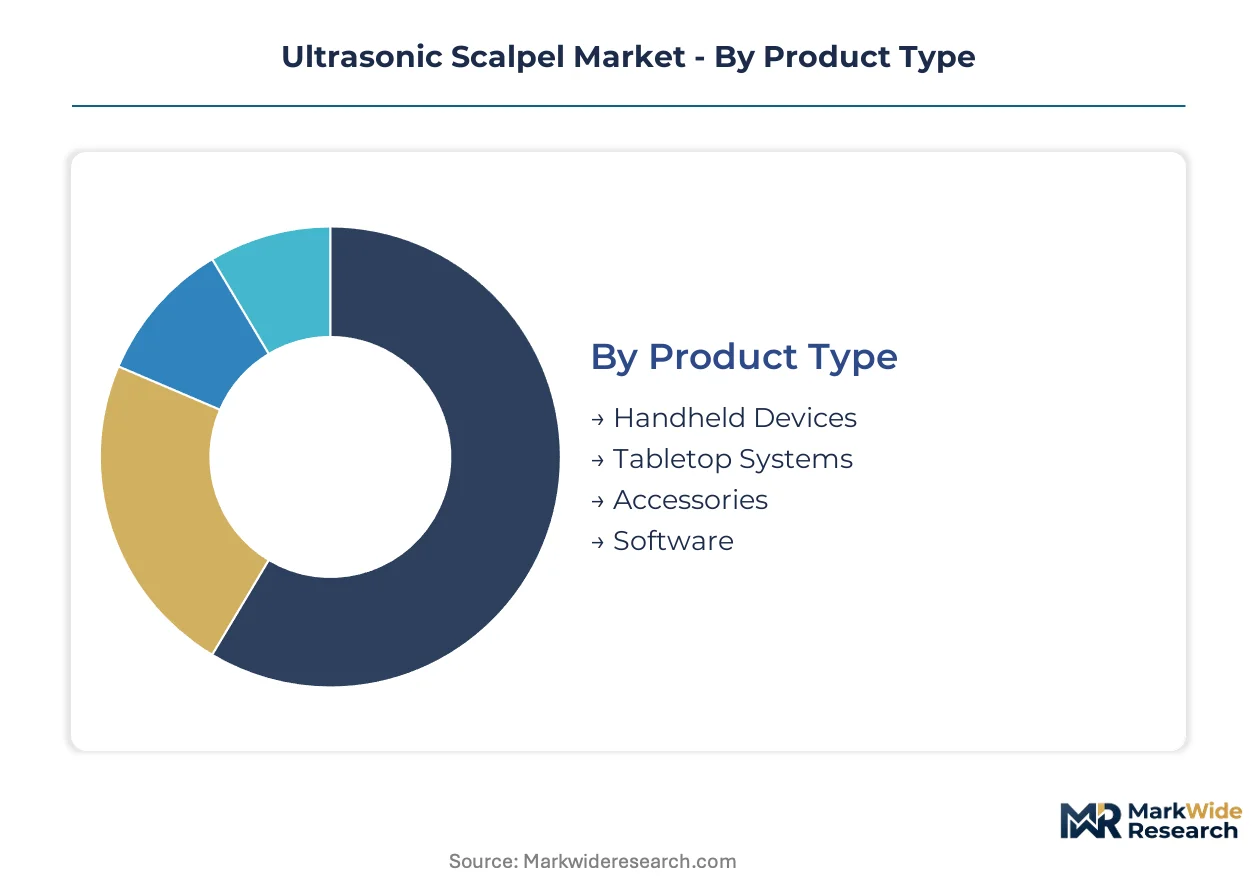
Ultrasonic scalpel manufacturers calibrate portfolio investments across four distinct axes: physical form factor, anatomical use case, care delivery setting, and energy conversion mechanism. Each dimension carries divergent margin profiles, regulatory pathways, and replacement cycle dynamics that reshape competitive positioning.
Product Type:
Form factor determines capital intensity, service contract attach rates, and hospital procurement committee jurisdiction.
- Handheld Devices:Battery-powered or cable-connected instruments deliver 55.5 kHz oscillation directly to tissue via titanium blade assemblies. Tertiary hospital general surgery departments in the United States concentrate procurement authority for these devices through integrated delivery network standardization programs.
- Tabletop Systems:Generator consoles with multi-port output capacity anchor operating room energy platforms through multi-year service agreements. Extended depreciation schedules in US integrated delivery networks compress upgrade frequency and lock in blade supply exclusivity.
- Accessories:Blade cartridges, torque wrenches, and sterilization trays extend per-procedure revenue capture.
- Software:Firmware updates and programmable tissue-response algorithms differentiate generator performance.
Handheld devices lead on scale; software leads on momentum.
Application:
Anatomical specialization dictates blade curvature, shaft length, and thermal spread tolerance specifications.
- General Surgery:Laparoscopic cholecystectomy and colectomy procedures demand precision coagulation in confined spaces. US tertiary hospitals accelerate adoption of adaptive tissue sensing systems to reduce lateral thermal damage.
- Gynecological Surgery:Minimally invasive hysterectomy volumes are climbing the fastest among all application segments, expanding addressable demand for curved blade configurations in pelvic anatomy.
- Orthopedic Surgery:Soft tissue dissection around bone requires specialized blade coatings to prevent ceramic degradation.
- Cardiovascular Surgery:Sternotomy and vascular anastomosis applications prioritize hemostasis reliability over cutting speed.
General surgery leads on scale; gynecological surgery leads on momentum.
End User:
Capital availability and procedure volume stratify purchasing behavior across care settings.
- Hospitals:Tertiary medical centers with dedicated minimally invasive surgery suites command the dominant share of tabletop generator placements. System-wide contracts with integrated delivery networks in the southeastern United States consolidate procurement authority.
- Ambulatory Surgical Centers:Price-sensitive outpatient facilities favor lower-throughput generator configurations and compete on per-procedure cost against radiofrequency alternatives.
- Clinics:Limited procedure volumes restrict capital equipment acquisition to handheld-only configurations.
- Research Centers:Academic medical centers drive early validation of digital control architectures and adaptive feedback algorithms.
Hospitals lead on scale; ambulatory surgical centers lead on momentum.
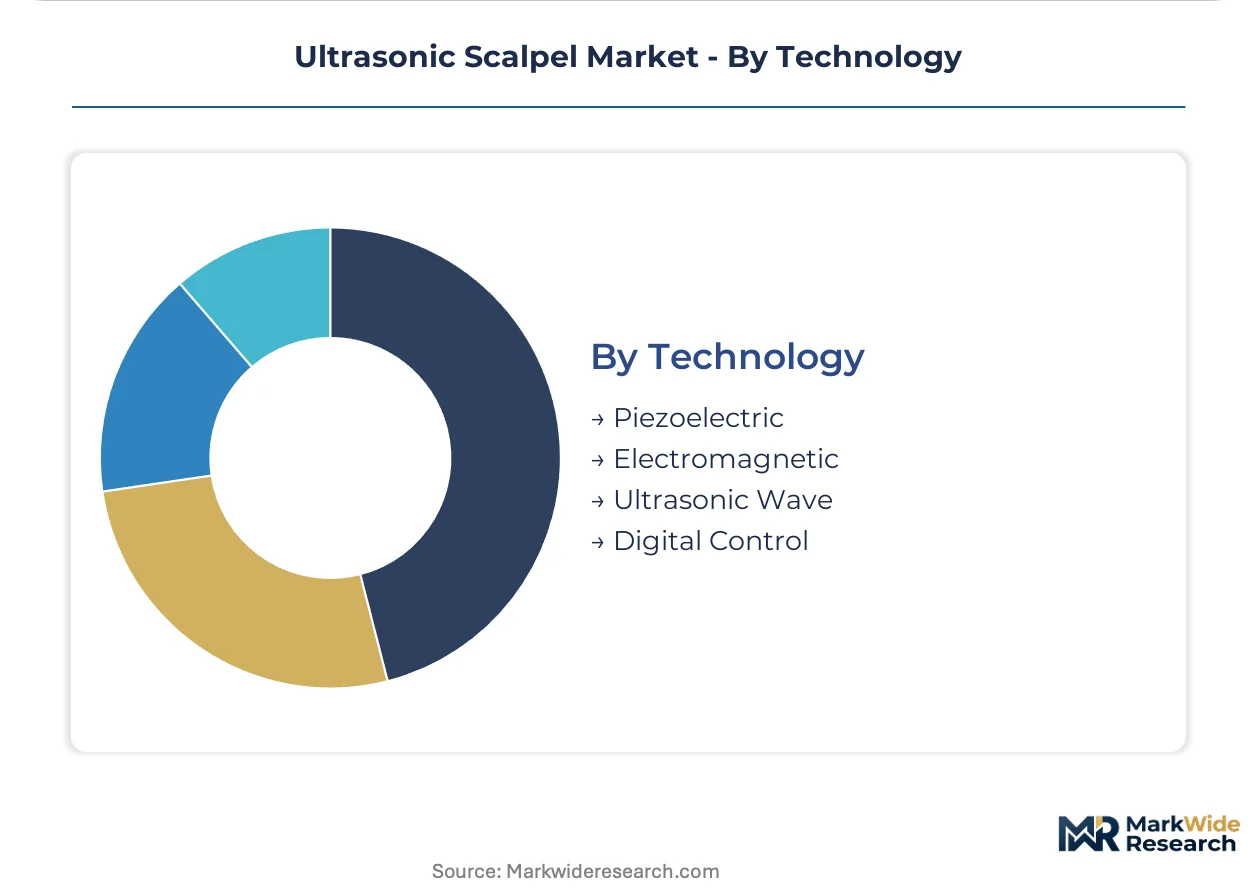
Technology:
Energy conversion mechanisms determine oscillation stability, thermal efficiency, and regulatory classification complexity.
- Piezoelectric:Lead zirconate titanate ceramics convert electrical to mechanical energy with high frequency precision. Improved ceramic compositions extend blade fatigue life and reduce thermal spread profiles.
- Digital Control:Programmable tissue-response curves enable real-time impedance feedback modulation. These architectures are gaining share fastest as manufacturers integrate adaptive sensing algorithms.
- Electromagnetic:Magnetostrictive transducers offer alternative oscillation generation for specialized applications.
- Ultrasonic Wave:Waveguide transmission systems optimize energy delivery to distal blade tips.
Piezoelectric leads on scale; digital control leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Integrated delivery networks in the United States concentrate procurement authority for advanced energy platforms, while regulatory divergence across major jurisdictions reshapes manufacturing localization strategies.
United States
Tertiary hospital general surgery departments drive tabletop generator placements through system-wide IDN contracts. FDA updated reprocessing guidelines for reusable energy devices compress 510(k) clearance timelines. The southeastern United States captures majority share of new ultrasonic scalpel installations as regional networks consolidate procurement.
Germany
EU MDR clinical evidence thresholds for reusable energy devices accelerate single-use blade adoption in European tertiary centers. Stricter validation requirements elevate compliance costs for market entrants. Industrial clusters in Baden-Württemberg host precision ceramics processing for piezoelectric transducer components.
China
NMPA domestic type testing mandates for imported surgical systems create localization pressure for multinational manufacturers. Rising minimally invasive procedure volumes expand addressable demand. Manufacturing concentration in the Yangtze River Delta supports domestic blade assembly and generator production.
Japan
PMDA regulatory pathways emphasize clinical validation for high-frequency oscillation devices in confined anatomical applications. Academic medical centers in Tokyo and Osaka drive early adoption of digital control architectures. Kanto region hospitals anchor demand for precision coagulation instruments in laparoscopic surgery.
India
Secondary hospitals in tier-2 cities present expansion potential for compact generator configurations. CDSCO import regulations shape market entry strategies for foreign device manufacturers. Maharashtra and Karnataka host emerging distribution networks for handheld ultrasonic instruments in outpatient surgical settings.
Ultrasonic Scalpel Market Key Industry Players
Global majors compete with regional champions across generator technology and blade supply ecosystems. The vendor base stratifies between integrated surgical platform providers and specialized energy device fabricators. Three archetypes dominate: diversified medical technology conglomerates with endomechanical bundling capabilities, pure-play ultrasonic energy specialists, and regional champions serving price-sensitive ambulatory markets. Competitive moves concentrate on exclusive blade supply agreements and adaptive tissue sensing algorithm development.
Among diversified platform providers, Johnson & Johnson and Medtronic occupy positions anchoring integrated delivery network procurement. Stryker Corporation exemplifies the surgical equipment franchise archetype, linking generator placements with operating room integration systems. BOWA-Electronic GmbH & Co. KG represents European specialist engineering, while Wuhan BBT Mini-Invasive Medical Tech. Co., Ltd anchors Chinese domestic manufacturing capabilities.
| Leading Market Players |
|---|
| Stryker Corporation |
| BOWA-Electronic GmbH & Co. KG |
| Johnson & Johnson |
| Bioventus Inc. |
| Wuhan BBT Mini-Invasive Medical Tech. Co., Ltd |
| Medtronic |
| Axon Medical Solutions |
| Surgnova Healthcare Technologies |
| Olympus Corporation |
| Others |
Cost & Logistics Intelligence
High-purity lead zirconate titanate ceramic feedstock prices cascade through ultrasonic scalpel manufacturing into three-tier pricing structures across premium, standard, and economy levels. Tertiary hospital procurement committees in the United States leverage integrated delivery network volume commitments to compress generator placement costs while locking in exclusive blade supply agreements.
Pricing Analysis
Input-cost pass-through from rare earth processing capacity in East Asian supply chains intensifies pricing pressure on piezoelectric transducer assemblies. Three-tier pricing structure across premium, standard, and economy levels differentiates by FDA 510(k) clearance tier and adaptive tissue sensing capability inclusion. Margins are tightening due to extended depreciation schedules for tabletop generator systems in US integrated delivery networks. Ambulatory surgical centers exhibit highest price sensitivity, while academic medical centers prioritize performance specifications over per-procedure cost.
Supply Chain Analysis
Dual-sourcing requirements from US integrated delivery networks mandate multi-supplier qualification for titanium blade substrates and piezoelectric ceramic components. Manufacturing concentration centers on China for rare earth processing, Japan for high-frequency transducer fabrication, and Germany for precision generator assembly. Raw material dependencies include high-purity lead zirconate titanate ceramics, medical-grade titanium alloys, and rare earth elements. Single-source vulnerability concentrates in East Asian rare earth supply chains. Distribution runs through hospital procurement committees and group purchasing organizations in the United States, with exclusive supply agreements locking in blade cartridge revenue streams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The ultrasonic scalpel market functions as a regulatory compounder where FDA updated reprocessing guidelines for reusable energy devices accelerate hospital procurement of validated single-use blade systems. This regulatory milestone reshapes product portfolio economics and procurement authority distribution.
For Market Incumbents: To counter electrosurgical substitution in price-sensitive ambulatory surgical centers, deepen backward integration into piezoelectric ceramic production to secure input cost stability. Anchor hospital capital budgets through operating room integration system bundling that links generator placements with multi-year exclusive blade supply agreements.
For New Entrants and Emerging Players: Rural secondary hospitals in India's tier-2 cities represent the most penetrable buyer archetype for compact, lower-throughput generator configurations. Target this segment through distribution partnerships with emerging medical device networks in Maharashtra and Karnataka, bypassing established integrated delivery network procurement barriers in mature markets.
For Investors and Strategic Acquirers: Asymmetric upside sits with pure-play ultrasonic energy specialists possessing proprietary adaptive tissue sensing algorithms and established CE marking pathways under EU MDR. Watch for inflection signals in China NMPA joint venture announcements indicating successful localization of domestic type testing capabilities.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Clearance timelines compress as reprocessing validation requirements tighten for reusable blade protocols. |
| CE Marking Pathway | EU MDR clinical evidence thresholds elevate compliance costs and favor disposable blade strategies. |
| Hospital System Partnership | Integrated delivery networks in the southeastern United States consolidate procurement authority through exclusive agreements. |
| Software Companion Development | Digital control architectures with programmable tissue-response curves differentiate generator performance tiers. |
| Reimbursement Strategy | CMS coding alignment for minimally invasive hysterectomy procedures expands addressable gynecological surgery demand. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and regulatory affairs specialists with secondary validation against FDA 510(k) filings, EU MDR technical documentation, hospital procurement databases, and CMS Medicare reimbursement data. Bottom-up segment sizing and top-down market reconciliation ensured cross-verification of value estimates.
Comparable-period anchoring anchored projections to historical reference periods across the analysis window, modeling dimensions including product type, application specialty, end-user setting, and technology architecture alongside procedural volume trajectories and capital equipment replacement cycles. CAGRs derived from regression analysis of installed base expansion and per-procedure utilization rates incorporated piezoelectric transducer cost curves and regulatory submission timelines as industry-specific inputs.
Underlying measurement precision varies by segment; handheld device revenue estimates carry tighter precision than software valuation due to disclosed procurement contract visibility. Forecasts reflect documented assumptions regarding IDN consolidation pace and NMPA localization enforcement intensity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surgical Instruments
Monopolar Electrosurgery Instrument Market
Surgical Instruments
Endoscopic Spinal Surgery Market
Surgical Instruments
Global Surgical Lasers Market
Surgical Instruments
Laparoscopic Gynecological Procedures Market
Surgical Instruments
Iraq Healthcare (Surgical Procedures) Market
Surgical Instruments
India Surgical Sutures Market
Surgical Instruments
Electrosurgery Market
Surgical Instruments
Cleft Lip and Palate Repair Surgical Instrument Package Market
Surgical Instruments
US Veterinary Surgical Instruments Market
Surgical Instruments
Suture Anchor Market
Surgical Instruments
Absorbable PGA Surgical Sutures Market
Surgical Instruments
Asia Pacific Surgical Equipment Market
Surgical Instruments
United Arab Emirates General Surgical Devices Market
Surgical Instruments
Global Surgical Booms Market
Surgical Instruments
Needle Holders Market
Surgical Instruments
Absorbable Surgical Suture with Needle Market