
 US Integrated Operating Rooms Market | 2026-2036
US Integrated Operating Rooms Market Size, Share, and Industry Trends Forecast 2026-2036
US Integrated Operating Rooms Market Intelligence
Modular platform bundling is realigning procurement decisions across US hospital systems. Stryker leverages its endoscopy and surgical navigation portfolio to anchor integrated suite contracts in academic medical centers. Steris competes through sterilization-to-integration workflows that extend its presence across the perioperative continuum. Olympus dominates the visualization layer, specializing in 4K and 3D camera systems that occupy critical positions within vendor-neutral architectures.
Integrated operating rooms combine surgical visualization, data routing, device control, and audio-video collaboration into unified environments managed from centralized touchpoints. These systems typically incorporate 4K Ultra HD imaging with sub-10ms latency requirements, fiber-optic signal management, and IP-based routing to enable real-time surgical streaming and documentation. Imaging Systems and Integration Platforms command the largest installed base, while Artificial Intelligence-enabled platforms represent the fastest-expanding technology segment as hospitals prioritize predictive analytics and automated device orchestration. Minimally Invasive Surgery applications sustain the deepest penetration of fully integrated suites, though Orthopedic Interventions are gaining share as robotic-assisted procedures proliferate.
FDA 510(k) premarket notification requirements govern surgical device and software approvals, while HIPAA mandates constrain data architecture choices for cloud-connected operating rooms. The Centers for Medicare & Medicaid Services reimbursement frameworks indirectly shape adoption velocity by defining eligible procedural settings. Stakeholders must monitor evolving FDA guidance on AI/ML-based surgical decision support, as clearance standards will determine which integration platforms achieve scalable deployment across US health systems.
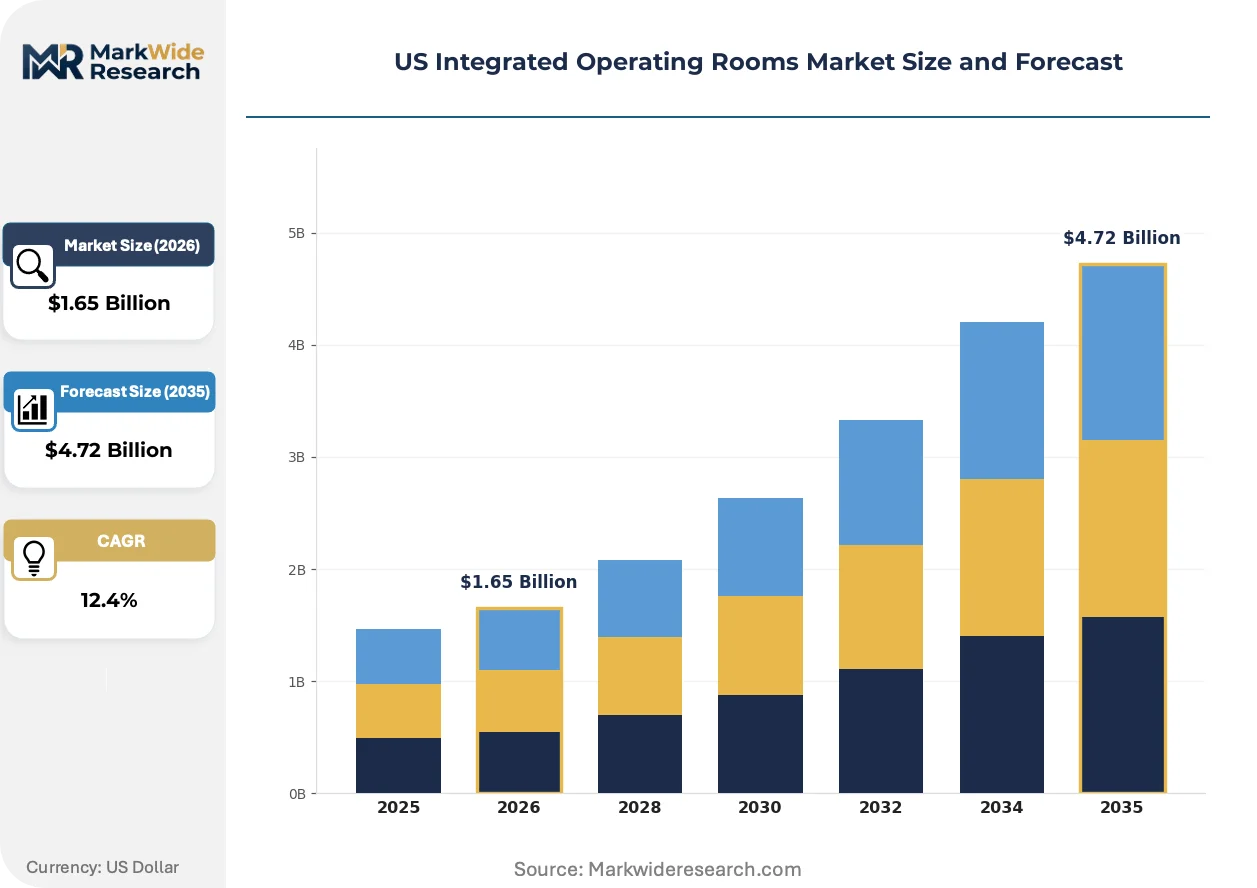
Market Dynamics
Health system consolidation is compressing vendor selection cycles and favoring integrated suite providers capable of delivering enterprise-scale perioperative infrastructure across multiple hospital sites.
Growth Catalysts
- CMS reimbursement incentives:Medicare reimbursement frameworks now favor outpatient and ambulatory surgical settings, accelerating demand for integrated OR infrastructure that supports same-day discharge protocols.
- Minimally invasive surgery expansion:Robotic-assisted procedures require synchronized visualization, navigation, and device control that only fully integrated platforms deliver.
- AI-enabled surgical decision support:FDA 510(k) clearance pathways for machine learning-based visualization tools are compressing commercialization timelines for predictive analytics platforms.
Market Restraints
- Capital intensity:Full-suite installations require $2-4 million per operating room, constraining adoption among independent community hospitals and limiting addressable market expansion.
- Specialized technician scarcity:Biomedical engineering programs produce insufficient graduates trained in fiber-optic signal management and IP-based surgical routing systems.
- Legacy infrastructure incompatibility:Existing surgical equipment from disparate manufacturers often lacks standardized communication protocols, forcing costly rip-and-replace decisions.
Strategic Opportunities
- Southeastern health system consolidation:Large regional networks in Florida, Georgia, and Texas are centralizing perioperative infrastructure, creating concentrated demand for multi-site integrated suite deployments.
- Cloud-connected documentation:HIPAA-compliant cloud architectures enable remote surgical streaming and real-time consultation, opening revenue streams from telepresence and medical education licensing.
- Orthopedic intervention expansion:Robotic-assisted joint replacement procedures are migrating from inpatient to ambulatory settings, requiring compact integrated platforms designed for smaller footprints.
Industry Challenges
- Interoperability certification delays:FDA and IEC 62304 software lifecycle standards create extended validation timelines for multi-vendor integration platforms, stretching product development cycles.
- Surgical workflow retraining:Nursing staff and surgeons require substantial adaptation periods to centralized touchpoint control systems, temporarily reducing operative efficiency during rollout phases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Integrated Operating Rooms Market |
| Market Size in 2026 | $1.65 Billion |
| Market Size in 2035 | $4.72 Billion |
| CAGR (2026 – 2036) | 12.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Imaging Systems, Surgical Displays, Control Consoles, Integration Platforms, Signal Management, Collaboration Tools Technology: 4K Ultra HD, 3D Visualization, Wireless Connectivity, Voice Control, Augmented Reality, Artificial Intelligence Application: Minimally Invasive Surgery, Cardiothoracic Procedures, Neurosurgery, Orthopedic Interventions, Urological Surgery, General Surgery End User: Specialty Surgical Centers, Academic Medical Centers, Multispecialty Hospitals, Ambulatory Surgery Facilities, Government Hospitals, Private Clinics |
| Companies Covered | Steris, Stryker, Olympus, Karl Storz, Getinge, Barco, Arthrex, Skytron, Hill-Rom, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Integrated Operating Rooms Market Strategic Shifts & Innovations
Artificial intelligence is penetrating surgical visualization layers, converting raw imaging data into actionable anatomical guidance and compressing the gap between diagnostic imaging and operative decision-making.
AI-powered surgical analytics is absorbing predictive capabilities previously confined to preoperative planning software. Academic medical centers in the southeastern United States are deploying these platforms to automate device orchestration and reduce cognitive load during complex procedures. The technology is absorbing functions from standalone surgical navigation systems, consolidating vendor relationships and favoring platforms with native machine learning architectures.
FDA guidance on AI/ML-based medical device software is clarifying predicate selection criteria for 510(k) submissions involving continuously learning algorithms. This regulatory development is enabling faster clearance pathways for surgical decision support tools while imposing documentation burdens on training dataset provenance. Integration platform vendors are responding by establishing captive regulatory affairs functions and pre-submission engagement protocols.
Health system procurement committees are consolidating vendor relationships around enterprise-scale contracts that bundle capital equipment, software licensing, and technical service across multiple surgical specialties. This buying-pattern shift is displacing single-device purchasing autonomy previously held by individual department chairs. The concentration is most visible among southeastern US health systems executing multi-hospital perioperative standardization initiatives.
US Integrated Operating Rooms Market Segmentation
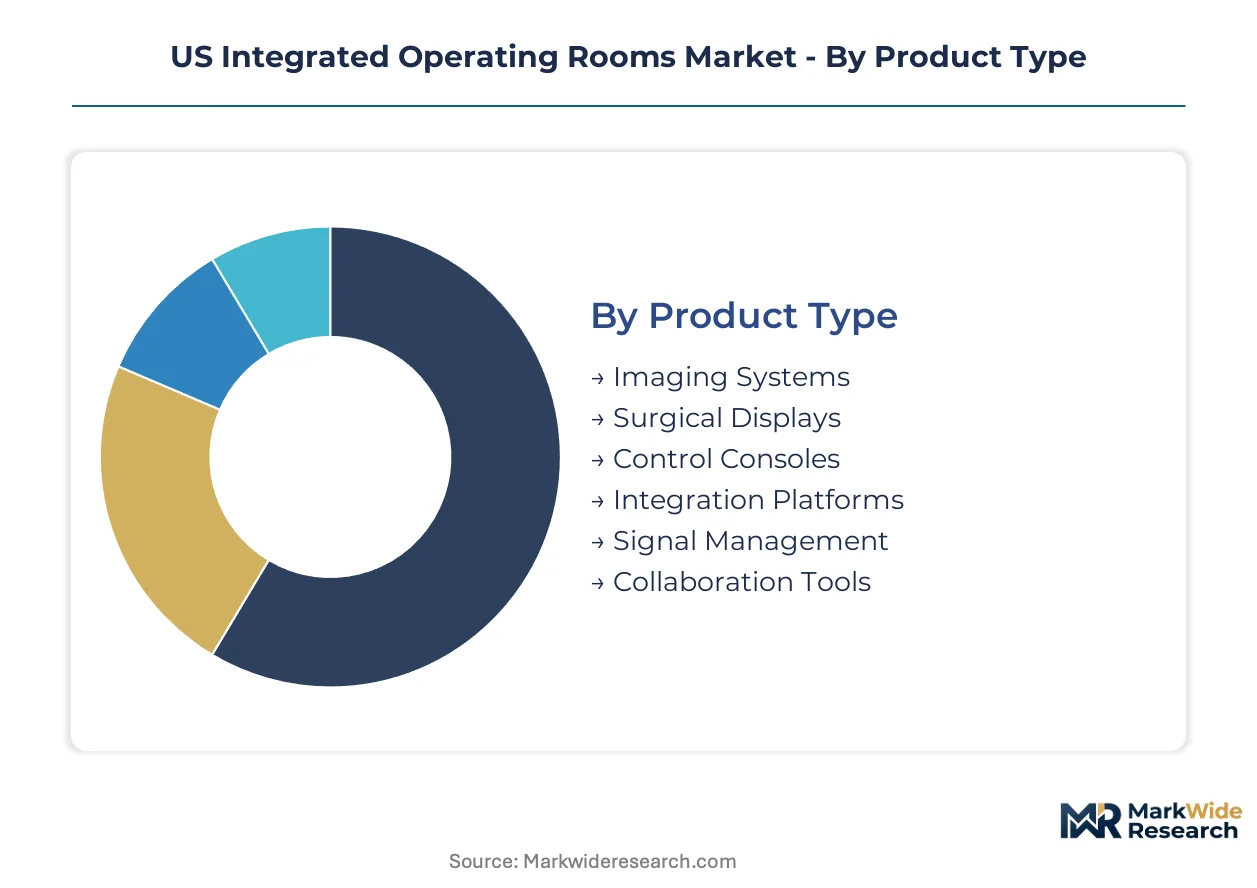
Segmentation reveals how technology specifications, procedural requirements, and facility economics fragment procurement patterns across the US perioperative landscape. Each axis exposes distinct vendor positioning strategies and capital allocation priorities among health system buyers.
Product Type:
Technical architecture determines integration depth and capital commitment levels across surgical suite installations.
- Imaging Systems:4K and 3D camera systems with sub-10ms latency requirements anchor visualization workflows. Academic medical centers in the southeastern United States prioritize these for robotic-assisted procedure expansion.
- Integration Platforms:Centralized software architectures orchestrate device control, data routing, and audio-video collaboration from unified touchpoints. Large health systems consolidating perioperative infrastructure across Florida, Georgia, and Texas demand these for multi-site standardization.
- Surgical Displays:Medical-grade monitors with HDR calibration and anti-glare coatings support operative visualization.
- Control Consoles:Touchscreen interfaces manage room environment, equipment positioning, and documentation capture.
- Signal Management:Fiber-optic and IP-based routing infrastructure enables real-time surgical streaming with minimal latency.
- Collaboration Tools:Audio-video systems facilitate remote consultation and medical education broadcasting.
Mature deployment sits with Imaging Systems. Newer deployment is concentrated in Integration Platforms.
Technology:
Resolution, connectivity, and intelligence layers define competitive differentiation and pricing architecture.
- 4K Ultra HD:3840×2160 resolution imaging with 60Hz refresh rates delivers anatomical detail for minimally invasive procedures. FDA 510(k) clearance pathways for visualization tools are accelerating adoption across academic medical centers.
- Artificial Intelligence:Machine learning algorithms convert raw imaging into predictive guidance and automated device orchestration. Southeastern health systems deploying these platforms are reducing cognitive load during complex interventions.
- 3D Visualization:Stereoscopic imaging enhances depth perception for laparoscopic and endoscopic procedures.
- Wireless Connectivity:Elimination of fiber-optic tethers improves surgical team mobility and room configuration flexibility.
- Voice Control:Hands-free command interfaces reduce sterile field contamination risks during procedures.
- Augmented Reality:Overlay of diagnostic imaging onto live surgical views fuses preoperative planning with operative execution.
4K Ultra HD commands the deepest installed base. Artificial Intelligence is gaining share fastest as hospitals prioritize predictive analytics.
Application:
Procedural complexity and reimbursement economics shape integration platform specifications.
- Minimally Invasive Surgery:Laparoscopic and endoscopic procedures demand synchronized visualization, insufflation control, and electrosurgical device management. This application sustains the deepest penetration of fully integrated suites across US hospital systems.
- Orthopedic Interventions:Robotic-assisted joint replacement procedures require navigation integration and implant positioning verification. CMS reimbursement frameworks favoring ambulatory settings are pushing these into smaller-footprint integrated platforms.
- Cardiothoracic Procedures:High-stakes interventions requiring perfusion monitoring and imaging fusion.
- Neurosurgery:Navigation precision demands sub-millimeter tracking and multimodal imaging correlation.
- Urological Surgery:Endoscopic platforms with integrated laser and irrigation management.
- General Surgery:Versatile configurations accommodating diverse procedure types.
Minimally Invasive Surgery represents the most mature integration segment. Orthopedic Interventions show the steepest expansion trajectory as robotic systems proliferate.
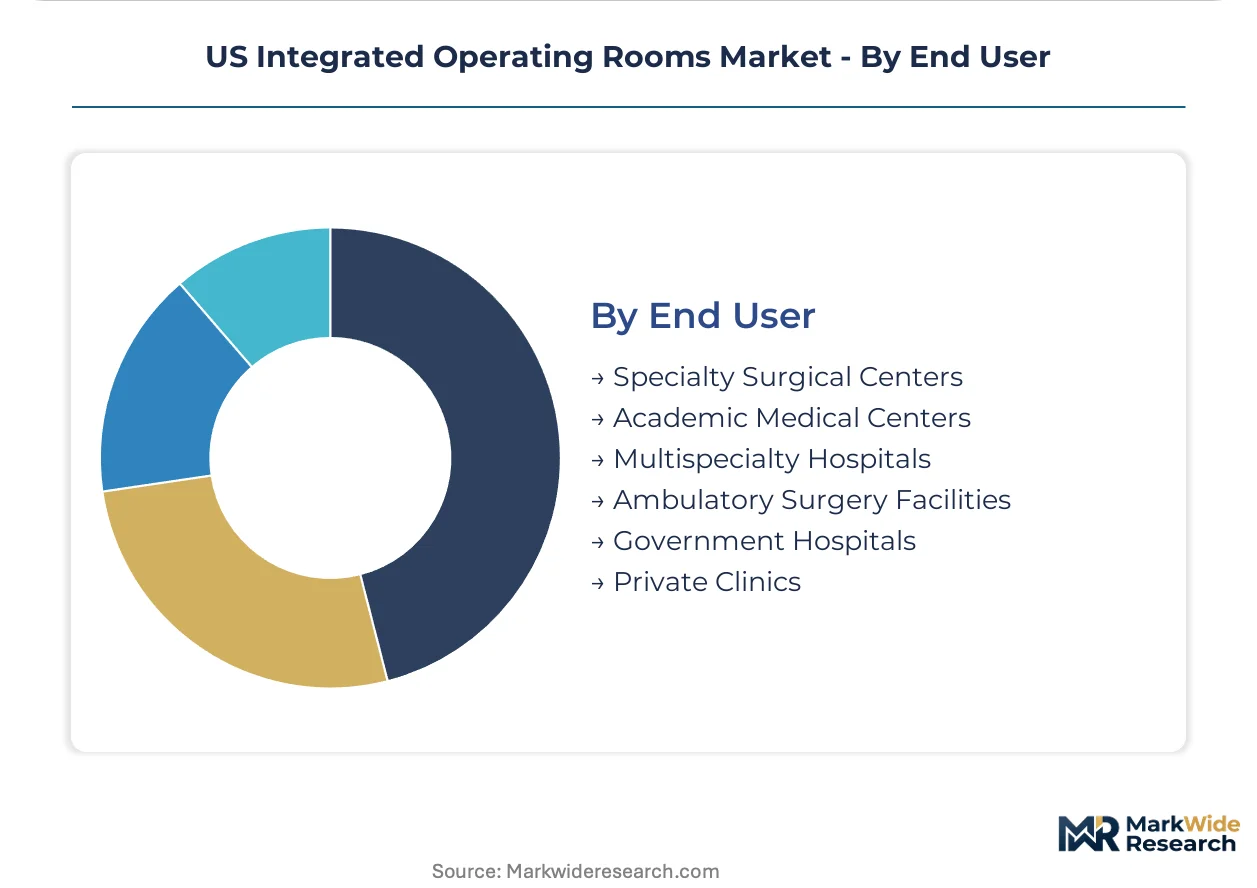
End User:
Capital availability and procedure volume determine suite configuration sophistication.
- Academic Medical Centers:Research and training missions drive demand for AI-enabled analytics, telepresence capabilities, and vendor-neutral architectures. These institutions lead adoption of FDA-cleared surgical decision support platforms.
- Ambulatory Surgery Facilities:Same-day discharge protocols require compact, cost-efficient integrated systems. CMS reimbursement incentives for outpatient settings are accelerating procurement among independent ASC operators.
- Specialty Surgical Centers:Focused procedure volumes enable standardized, single-vendor configurations.
- Multispecialty Hospitals:Diverse service lines demand flexible, modular integration architectures.
- Government Hospitals:Federal procurement constraints and veteran-specific care requirements shape specifications.
- Private Clinics:Limited capital budgets restrict adoption to essential visualization and documentation components.
Academic Medical Centers anchor premium platform deployment. Ambulatory Surgery Facilities represent the fastest-climbing adoption tier.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Opportunity Zones and hospital construction tax credits in the southeastern United States are concentrating perioperative infrastructure investment. Federal incentive programs accelerate capital deployment for integrated surgical suites across high-growth metropolitan corridors.
Southeast
Florida and Georgia health systems execute multi-hospital standardization initiatives requiring enterprise-scale integration platforms. CMS reimbursement frameworks favoring ambulatory surgery accelerate procurement in Tampa and Atlanta medical corridors. Academic medical centers in Miami and Emory-affiliated networks deploy AI-enabled surgical analytics for robotic-assisted procedure expansion.
Southwest
Texas medical centers consolidate perioperative infrastructure across Dallas-Fort Worth and Houston metropolitan clusters. State-level hospital construction bonds support integrated OR modernization in San Antonio and Austin health networks. Large regional systems centralize vendor contracts for multi-site surgical suite deployments.
Mid-Atlantic
Philadelphia and Baltimore academic medical centers prioritize FDA-cleared surgical decision support platforms. NIH-funded research institutions drive demand for vendor-neutral architectures supporting telepresence and medical education. Pennsylvania health systems leverage federal rural hospital grants for integration platform adoption.
Pacific
California academic medical centers in Los Angeles and San Francisco lead adoption of 4K and 3D visualization systems. State digital health mandates accelerate HIPAA-compliant cloud architecture deployment for remote surgical streaming. Stanford and UCSF-affiliated networks pioneer AI-enabled device orchestration in orthopedic intervention suites.
Northeast
Massachusetts and New York health systems focus on legacy infrastructure modernization with modular integration platforms. Boston academic medical centers deploy fiber-optic signal management for sub-10ms latency requirements. New York-Presbyterian and Mass General Brigham networks consolidate perioperative vendor relationships across metropolitan hospital clusters.
US Integrated Operating Rooms Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across the US integrated operating rooms market. Tiered concentration prevails: multinational medical technology corporations anchor premium platform segments, while regional equipment fabricators serve cost-constrained facilities. Three strategic archetypes dominate — full-stack integrators bundling visualization, control, and connectivity; visualization-layer specialists supplying camera and display systems; and sterilization-to-integration workflow providers extending perioperative presence. Competitive moves center on enterprise contract consolidation and modular platform bundling to capture multi-hospital health system procurement.
Among full-stack integration providers, Steris and Stryker occupy positions representing divergent strategic approaches — the former exemplifying sterilization-to-integration workflow extension, the latter anchoring surgical navigation and endoscopy portfolio bundling. Olympus sits within the visualization specialist tier, its 4K and 3D camera systems occupying critical positions in vendor-neutral architectures across academic medical centers. These three entities collectively illustrate how market participants align with distinct procurement committee priorities: enterprise standardization, specialty procedure focus, or imaging-layer dominance.
| Leading Market Players |
|---|
| Steris |
| Stryker |
| Olympus |
| Karl Storz |
| Getinge |
| Barco |
| Arthrex |
| Skytron |
| Hill-Rom |
| Others |
Cost & Logistics Intelligence
Private-equity-rolled-up specialists in surgical visualization and device control have compressed vendor margins while extending payment terms to upstream component suppliers, creating asymmetric pricing power that favors buyers with multi-hospital contract scale. This ownership concentration reshapes both procurement leverage and supply chain resilience across the US integrated operating rooms landscape.
Pricing Analysis
Cost compression in economy-tier installations accelerates as independent community hospitals defer full-suite upgrades amid capital budget constraints. Pricing stratifies across premium enterprise contracts, standard mid-tier bundles, and economy visualization-only configurations. Price differentiation rests on FDA 510(k) clearance tier and after-sales service bundling rather than hardware specifications alone. Academic medical centers demonstrate lowest price sensitivity due to research funding insulation, while ambulatory surgery centers face acute margin pressure from CMS reimbursement compression.
Supply Chain Analysis
FDA 510(k) premarket notification and IEC 62304 software lifecycle standards gate component qualification timelines, elongating supplier onboarding for AI-enabled surgical modules. Manufacturing concentrates in the United States, Germany, and Japan for precision imaging sensors and fiber-optic routing hardware. Raw material dependencies include germanium substrates for infrared optics, high-purity silica for fiber cables, and specialized FPGA chipsets for signal processing. Single-source vulnerability sits with Japanese suppliers of 4K image sensors. Distribution runs through GPO contracts and direct hospital system agreements rather than traditional medical device distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US integrated operating rooms market is becoming a vertical-integration race, with platform vendors pursuing captive control over AI/ML algorithm development to differentiate beyond commodity hardware margins.
For Market Incumbents: Cement enterprise-scale contract renewals by embedding sterilization-to-integration workflow services that raise switching costs for southeastern health systems. Invest in FDA pre-submission engagement protocols to accelerate 510(k) clearance timelines for AI-enabled surgical decision support, countering emerging pure-play analytics specialists. Prioritize backward integration into fiber-optic signal management components to defend margin position against Asian sensor suppliers. For New Entrants and Emerging Players: Begin with compact, cost-efficient integrated platforms targeting independent ambulatory surgery centers in Texas and Florida metropolitan corridors underserved by full-stack vendors. White-space opportunities concentrate in orthopedic intervention suites requiring smaller-footprint robotic integration. Pursue hospital-at-home and remote surgical streaming licensing as a go-to-market angle distinct from capital equipment sales. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap surgical visualization specialists with captive FDA clearance expertise and southeastern health system relationships. Long-term viability hinges on platform recurring revenue models displacing transactional equipment sales. Watch FDA guidance evolution on continuously learning AI/ML algorithms as the inflection signal determining which integration architectures achieve scalable deployment.| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Enterprise contracts with Florida and Georgia networks consolidate multi-site perioperative standardization and displace single-device purchasing autonomy. |
| FDA 510(k) Submission | Premarket notification pathways for AI-enabled surgical visualization compress commercialization timelines for predictive analytics platforms. |
| Software Companion Development | Native machine learning architectures absorb functions from standalone surgical navigation systems and consolidate vendor relationships. |
| Reimbursement Strategy | CMS outpatient surgery incentives accelerate procurement among ambulatory facilities seeking same-day discharge protocol enablement. |
| CE Marking Pathway | European regulatory clearance supports vendor diversification beyond US health system concentration in southeastern metropolitan corridors. |
Research Approach
FDA 510(k) premarket notification databases, CMS Medicare reimbursement filings, and hospital procurement contract records formed the secondary backbone, cross-referenced with primary interviews conducted with biomedical engineering directors, perioperative services executives, GPO contracts managers, and surgical robotics program coordinators. Bottom-up triangulation across equipment installation records and top-down validation against health system capital expenditure disclosures anchored market sizing. Primary fieldwork captured workflow retraining timelines and interoperability certification delays affecting product development cycles.
Bottom-up modeling segmented the market by product type, technology layer, application specialty, and end-user facility tier, with value outputs derived from contract value analysis across the projection horizon. CAGRs were computed from installed base expansion rates and replacement cycle compression in robotic-assisted procedure suites. Forecast inputs incorporated FDA clearance velocity assumptions for AI/ML-based surgical decision support and southeastern health system consolidation trajectories.
Underlying measurement precision varies by segment; imaging systems and integration platforms carry tighter precision than emerging AI-enabled categories where commercial deployment remains concentrated in academic medical centers. Forecasts reflect documented assumptions regarding CMS reimbursement stability and FDA guidance continuity. A model refresh is warranted upon material change in FDA AI/ML-based medical device software predicate selection criteria.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surgical Instruments
Endometrial Ablation Market
Surgical Instruments
Ultrasonic Scissors Market
Surgical Instruments
Surgical Hemostats Market
Surgical Instruments
Cardiac Surgery Instruments Market
Surgical Instruments
Ultrasonic Surgical Cutters Market
Surgical Instruments
Ischemic Stroke Surgery Market
Surgical Instruments
Skin Graft Blades Market
Surgical Instruments
Surgical Headband Market
Surgical Instruments
Saudi Arabia General Surgical Devices Market
Surgical Instruments
Surgical Pliers Market
Surgical Instruments
Hand-Held Surgical Instruments Market
Surgical Instruments
Absorbable Sutures Market
Surgical Instruments
Global Bipolar Electrosurgical Devices Market
Surgical Instruments
Italy General Surgical Devices Market
Surgical Instruments
India General Surgical Devices Market
Surgical Instruments
Special Purpose Needles Market