
 HPV Associated Disorders Market | 2026-2036
HPV Associated Disorders Market Size, Share, and Industry Trends Forecast 2026-2036
HPV Associated Disorders Market Intelligence
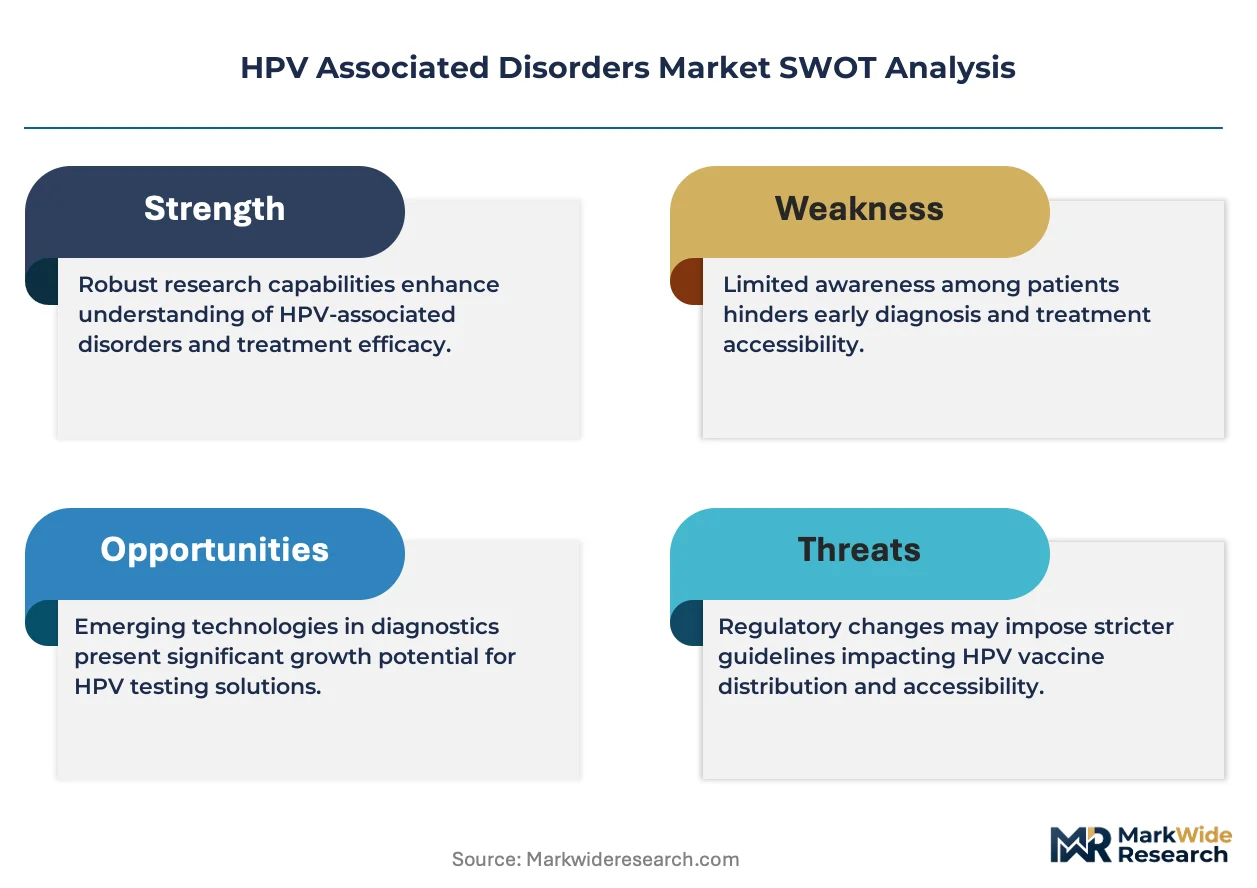
A widening R&D scale divergence between pharmaceutical giants is reorganizing competitive hierarchy in HPV therapeutics. Merck & Co., Inc. leverages its established vaccine infrastructure to anchor oncology pipeline development. GlaxoSmithKline plc sustains differentiated positions through specialized immunotherapy investments. F. Hoffmann-La Roche Ltd competes via diagnostic-therapeutic integration across cervical and oropharyngeal cancer pathways.
HPV associated disorders encompass a spectrum of oncogenic and benign conditions triggered by persistent human papillomavirus infection, with cervical cancer representing the most prevalent malignant manifestation requiring histopathological confirmation and molecular HPV genotyping. These conditions drive substantial clinical intervention through surgery, chemotherapy, radiation therapy, and emerging immunotherapy modalities aimed at viral clearance and lesion regression. Immunotherapy represents the fastest-expanding treatment approach as checkpoint inhibitors and therapeutic vaccines reshape standard-of-care protocols, while diagnostic methods cluster around HPV testing and Pap smear combinations that dominate screening volumes. Hospitals absorb the largest share of end-user demand due to complex surgical and radiation therapy requirements, though specialty clinics are capturing growing immunotherapy administration volumes.
FDA oncology center guidance on HPV-targeted drug development, EMA's MDR framework for companion diagnostics, and WHO cervical cancer elimination targets collectively elevate product standards and accelerate market access for novel therapeutics. These regulatory architectures pressure manufacturers to align clinical trial endpoints with screening integration requirements rather than isolated efficacy metrics. Stakeholders must monitor immunotherapy reimbursement decisions in concentrated demand markets to anticipate volume shifts between hospital and specialty clinic channels.
Market Dynamics
Checkpoint inhibitor integration into cervical cancer protocols is compressing treatment timelines and shifting site-of-care economics toward outpatient infusion centers, forcing hospitals to reconfigure oncology service lines around immunotherapy administration rather than traditional surgical staging.
Growth Catalysts
- FDA Accelerated Approval Pathways:Oncology Center guidance for HPV-targeted biologics truncates Phase II-to-III transitions, compressing development cycles for therapeutic vaccines and enabling earlier commercialization of novel mechanisms.
- Japan's Expanded Screening Mandates:METI-coordinated national programs for cervical cancer elimination are driving diagnostic volume expansion and creating downstream therapeutic demand concentrated in Tokyo and Osaka medical clusters.
- Therapeutic Vaccine Platforms:mRNA-based HPV immunotherapies are advancing through clinical pipelines, attracting specialized manufacturing investment and reshaping competitive positioning among biologics developers.
Market Restraints
- Cold Chain Infrastructure Gaps:Biologics distribution requires continuous temperature monitoring from manufacturing through infusion, constraining market penetration in regions lacking validated logistics networks.
- Companion Diagnostic Fragmentation:EMA's MDR framework for HPV genotyping assays creates regulatory heterogeneity across member states, delaying harmonized market access for integrated diagnostic-therapeutic bundles.
- Reimbursement Compression:Payer scrutiny of immunotherapy cost-effectiveness in Germany's G-BA assessment framework is narrowing indication-specific coverage and extending access negotiation timelines.
Strategic Opportunities
- Oropharyngeal Cancer Indications:Rising HPV16-driven head and neck malignancy incidence in the United States is opening addressable patient populations beyond cervical pathology, with academic medical centers pioneering multimodal protocols.
- Home-Based Specimen Collection:Self-sampling HPV testing kits are penetrating preventive care channels, creating upstream diagnostic access in underserved US regions and reducing clinic dependency for initial screening.
- WHO Elimination Targets:The organization's 90-70-90 cervical cancer benchmarks are catalyzing public procurement contracts in low- and middle-income settings, opening volume opportunities for affordable vaccine and diagnostic platforms.
Industry Challenges
- Immuno-oncology Talent Scarcity:Clinical trial design for HPV-targeted therapies requires specialized expertise in viral oncology biomarkers, creating recruitment bottlenecks for mid-stage development programs.
- Legacy System Integration:Electronic health record interoperability between pathology laboratories and oncology clinics impedes real-time HPV genotyping data flow, complicating treatment pathway optimization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | HPV Associated Disorders Market |
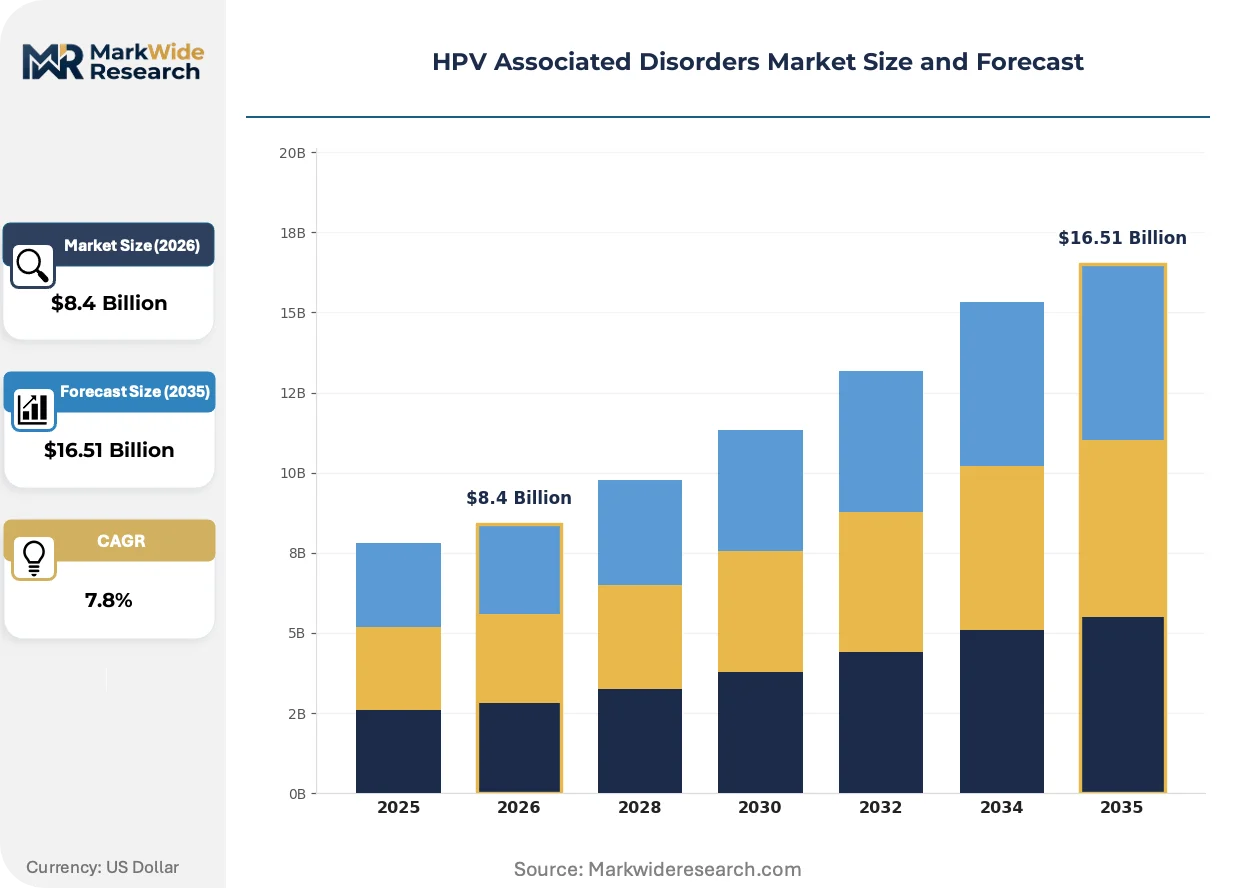
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $16.51 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Cervical Cancer, Anal Cancer, Oropharyngeal Cancer, Genital Warts Treatment Approach: Surgery, Chemotherapy, Radiation Therapy, Immunotherapy End User: Hospitals, Specialty Clinics, Research Laboratories, Homecare Settings Diagnostic Method: Pap Smear, HPV Testing, Biopsy, Imaging Techniques |
| Companies Covered | Merck & Co., Inc., GlaxoSmithKline plc, F. Hoffmann-La Roche Ltd, Pfizer Inc., AstraZeneca, Biocon Ltd., Bristol-Myers Squibb Company, Eli Lilly and Company, AbbVie Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
HPV Associated Disorders Market Strategic Shifts & Innovations
Artificial intelligence is penetrating cervical cytology workflows, compressing diagnostic interpretation timelines while regulatory frameworks adapt to algorithm-based screening protocols. These intersecting developments are redrawing competitive boundaries between diagnostic manufacturers and therapeutic developers.
Next-generation sequencing-based HPV genotyping is supplanting hybrid capture methods in high-volume screening programs. Academic medical centers in the United States and Japan are adopting these platforms for simultaneous viral load quantification and integration site mapping. The technology is enabling risk-stratified triage protocols that redirect low-risk patients toward extended surveillance intervals, compressing colposcopy referral volumes.
EMA's MDR implementation for in vitro diagnostic devices is elevating clinical evidence requirements for HPV assays marketed in Europe. Manufacturers must now demonstrate analytical validity through prospective studies rather than retrospective bridging, extending certification timelines by twelve to eighteen months. German and French notified bodies are prioritizing review capacity for oncology companion diagnostics, creating geographic concentration in regulatory submission strategies.
Hospital procurement committees are consolidating vendor relationships for integrated diagnostic-therapeutic bundles, displacing standalone product purchasing. Oncology service line administrators in US health systems now require proof of pathway cost-effectiveness across screening, diagnosis, and treatment phases. This behavioral shift is most visible in integrated delivery networks spanning Texas and California, where single-source contracting for HPV-related care is compressing supplier margins.
HPV Associated Disorders Market Segmentation
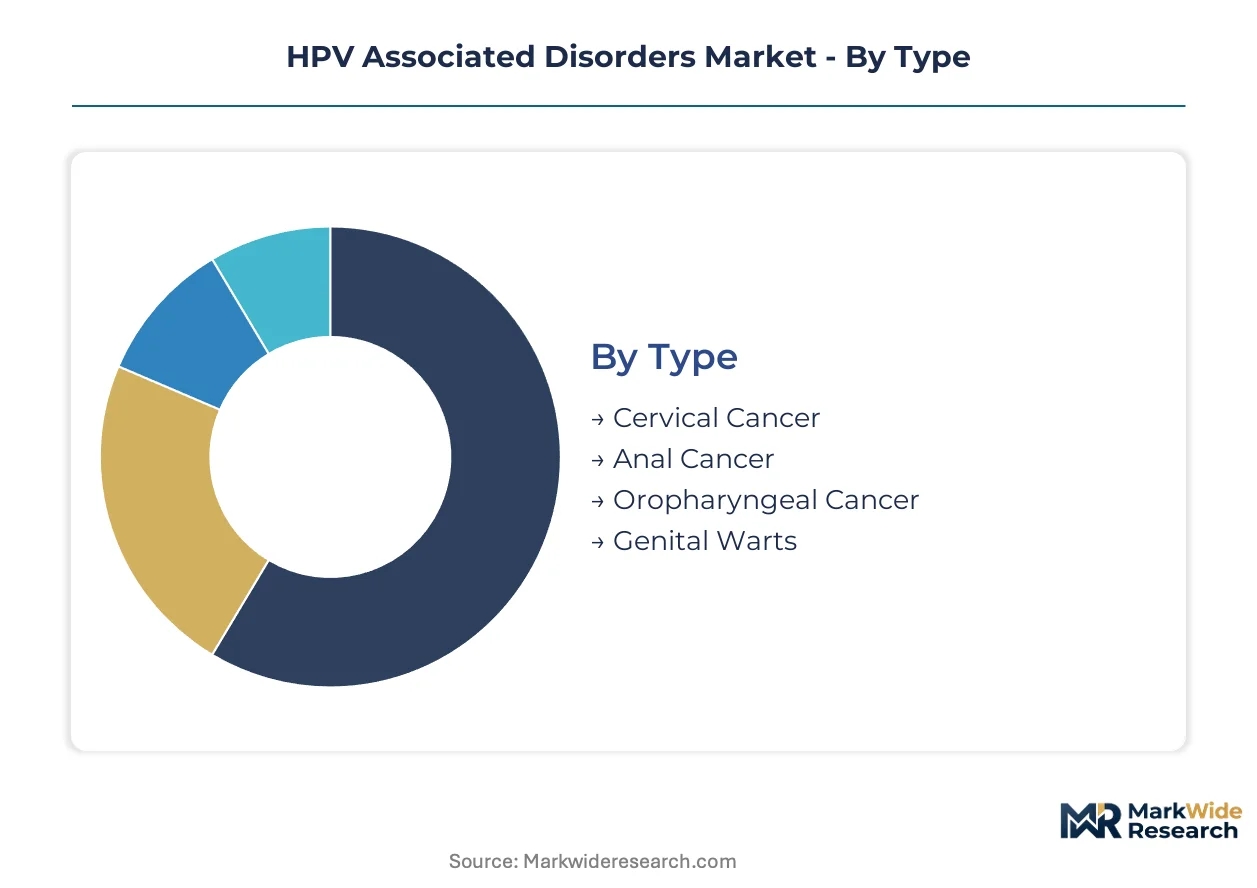
HPV associated disorders span oncogenic and benign pathologies with divergent clinical pathways. Treatment intensity, diagnostic complexity, and site-of-care requirements vary dramatically across segments, reshaping vendor targeting strategies and procurement patterns.
Type:
Cervical cancer dominates domestic demand concentration in screening-intensive markets, while oropharyngeal malignancies show stronger export-led therapeutic development.
- Cervical Cancer:Persistent HPV16/18 infection drives malignant transformation requiring histopathological confirmation and molecular genotyping. Demand concentrates in United States, Germany, and Japan where national screening programs expand diagnostic volumes and downstream therapeutic intervention.
- Oropharyngeal Cancer:HPV16-driven head and neck malignancies exhibit rising incidence in Western populations, particularly among males. Academic medical centers in the United States pioneer multimodal protocols combining radiation with immunotherapy, attracting specialized pharmaceutical investment.
- Anal Cancer:Immunocompromised populations sustain specialized clinical demand concentrated in metropolitan oncology centers.
- Genital Warts:Benign manifestations drive high-volume outpatient procedures with localized treatment protocols dominating primary care channels.
Cervical cancer commands the established base. The steepest expansion runs through oropharyngeal cancer indications.
Treatment Approach:
Cost tier stratification separates capital-intensive radiation infrastructure from outpatient-administered biologics, redrawing site-of-care economics.
- Immunotherapy:Checkpoint inhibitors and therapeutic vaccines reshape standard-of-care protocols through viral antigen targeting. Specialty clinics in Tokyo, Houston, and Munich capture growing administration volumes as FDA and EMA accelerate approval pathways for HPV-targeted biologics.
- Surgery:Radical hysterectomy and local excision procedures retain dominance in early-stage cervical pathology. German and Japanese hospital systems maintain high surgical throughput through established gynecologic oncology service lines.
- Chemotherapy:Platinum-based regimens persist as backbone therapy in combination protocols across advanced disease settings.
- Radiation Therapy:External beam and brachytherapy modalities require substantial capital investment concentrated in tertiary hospital networks.
Surgery commands the established base. Immunotherapy is climbing the fastest as checkpoint inhibitors compress treatment timelines.
End User:
Customer type fragmentation splits between acute-care hospitals managing complex staging and outpatient channels capturing preventive and maintenance volumes.
- Hospitals:Integrated delivery networks absorb complex surgical and radiation therapy requirements through dedicated oncology service lines. Texas and California health systems consolidate vendor relationships for diagnostic-therapeutic bundles across screening-to-treatment pathways.
- Specialty Clinics:Outpatient infusion centers capture growing immunotherapy administration volumes as checkpoint inhibitors shift site-of-care economics away from inpatient settings.
- Research Laboratories:Academic medical centers drive next-generation sequencing adoption for HPV genotyping and integration site mapping.
- Homecare Settings:Self-sampling HPV testing kits penetrate preventive care channels, reducing clinic dependency for initial screening access.
Hospitals command the established base. Specialty clinics are gaining share fastest through immunotherapy administration expansion.
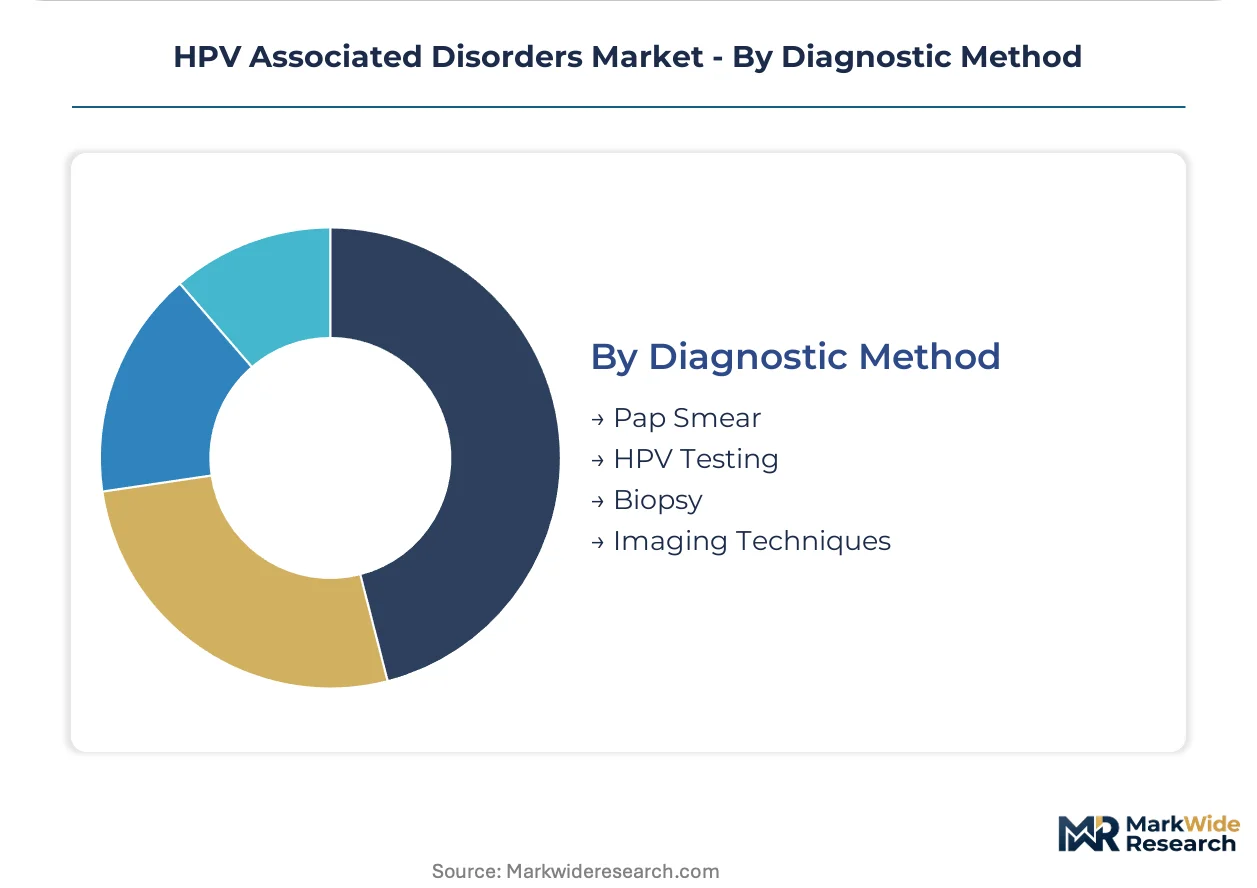
Diagnostic Method:
Maturity gradients separate decades-old cytology workflows from emerging molecular platforms reshaping screening economics.
- HPV Testing:Nucleic acid amplification and hybrid capture methods dominate high-volume screening programs. Next-generation sequencing platforms enable simultaneous viral load quantification and genotyping, compressing colposcopy referral volumes through risk-stratified triage.
- Pap Smear:Conventional cytology retains substantial installed base in resource-constrained settings despite sensitivity limitations. Artificial intelligence penetration accelerates interpretation workflows in United States and Japanese laboratory networks.
- Biopsy:Histopathological confirmation remains mandatory for cancer diagnosis, driving pathology laboratory throughput.
- Imaging Techniques:MRI and PET-CT staging protocols concentrate in tertiary referral centers managing advanced disease.
Pap smear commands the established base. HPV testing is expanding most quickly as molecular platforms displace cytology in screening programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in the United States exceeds that in Germany by substantial margins, reflecting divergent reimbursement architectures and immunotherapy access protocols. Japan commands premium positioning in Asia-Pacific therapeutic procurement. Concentrated demand clusters in metropolitan medical centers across all three markets.
United States
FDA accelerated approval pathways for HPV-targeted biologics compress development timelines and expand addressable patient populations. The agency's Oncology Center guidance enables earlier commercialization of therapeutic vaccines and checkpoint inhibitors. Houston and Dallas medical clusters pioneer multimodal protocols combining radiation with immunotherapy, attracting specialized pharmaceutical investment.
Germany
G-BA assessment frameworks scrutinize immunotherapy cost-effectiveness, narrowing indication-specific coverage and extending access negotiation timelines. EMA's MDR framework for companion diagnostics creates regulatory heterogeneity across member states. Munich and Berlin oncology centers maintain high surgical throughput through established gynecologic oncology service lines.
Japan
METI-coordinated national programs for cervical cancer elimination drive diagnostic volume expansion and downstream therapeutic demand. PMDA streamlined review processes for oncology biologics accelerate market entry. Tokyo and Osaka medical clusters capture growing immunotherapy administration volumes as checkpoint inhibitors shift site-of-care economics.
United Kingdom
NHS England's national cervical cancer screening program expansion increases diagnostic volumes and therapeutic intervention requirements. MHRA post-Brexit regulatory autonomy enables tailored approval pathways for HPV-targeted therapies. London and Manchester academic medical centers drive next-generation sequencing adoption for HPV genotyping and integration site mapping.
India
CDSCO streamlined approval processes for oncology biologics expand access to immunotherapy in metropolitan markets. National health mission programs for cervical cancer screening create volume opportunities for affordable diagnostic platforms. Mumbai and Bangalore medical institutions pioneer risk-stratified triage protocols redirecting low-risk patients toward extended surveillance intervals.
HPV Associated Disorders Market Key Industry Players
Concentration sits with diversified pharmaceutical conglomerates leveraging established vaccine infrastructure and oncology pipelines. The market structure reflects tiered competition between vaccine-origin players, diagnostic-therapeutic integrators, and emerging biologics specialists. Two strategic archetypes dominate: legacy vaccine manufacturers repurposing immunization platforms for therapeutic development, and precision oncology firms advancing checkpoint inhibitor protocols. Competitive moves center on diagnostic-therapeutic bundle consolidation and accelerated regulatory pathway navigation.
Within the diversified pharmaceutical tier, Merck & Co., Inc. and GlaxoSmithKline plc exemplify vaccine-origin competitive positioning, while F. Hoffmann-La Roche Ltd anchors diagnostic-therapeutic integration strategies. These entities occupy distinct market positions reflecting divergent historical capabilities—vaccine manufacturing scale versus molecular diagnostics depth—rather than convergent therapeutic approaches.
| Leading Market Players |
|---|
| Merck & Co., Inc. |
| GlaxoSmithKline plc |
| F. Hoffmann-La Roche Ltd |
| Pfizer Inc. |
| AstraZeneca |
| Biocon Ltd. |
| Bristol-Myers Squibb Company |
| Eli Lilly and Company |
| AbbVie Inc. |
| Others |
Cost & Logistics Intelligence
mRNA platform substitution for conventional protein-based manufacturing is redrawing supply geography toward specialized biologics clusters while compressing pricing premiums for HPV-targeted immunotherapies as production scale economies mature.
Pricing Analysis
The customization-premium spread between patient-specific therapeutic vaccines and standard-of-care checkpoint inhibitors reaches three-to-one in US oncology centers. Three-tier pricing structure across premium, standard, and economy levels separates branded biologics from biosimilar entrants and public procurement tenders in low-income settings. Price differentiation hinges on FDA breakthrough designation status and cold chain logistics bundling. Pricing pressure stems from Germany's G-BA cost-effectiveness assessments narrowing reimbursement margins. Hospital procurement committees demonstrate highest price sensitivity; academic medical centers with research funding exhibit lowest.
Supply Chain Analysis
Inventory lead times for HPV therapeutic vaccines stretch eighteen to twenty-four months due to fill-finish capacity constraints at contract manufacturing organizations. Active pharmaceutical ingredient production concentrates in Switzerland, Ireland, and Singapore where biologics infrastructure clusters. Supply chains draw from plasmid DNA, lipid nanoparticles, and sterile vial components as critical inputs. Single-source vulnerability in lipid nanoparticle supply creates exposure to pharmaceutical raw material allocation decisions. Distribution runs through validated cold chain networks terminating at hospital pharmacies and specialty infusion centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
HPV therapeutics function as a service-attach opportunity where companion diagnostic integration and patient monitoring subscriptions expand recurring revenue faster than drug product sales alone.
For Market Incumbents: Secure diagnostic-therapeutic bundle contracts with integrated delivery networks before biosimilar entry erodes pricing power. Deepen backward integration into next-generation sequencing manufacturing to capture margin from HPV genotyping workflows. Anchor capacity in Singapore and Ireland to mitigate EMA MDR certification bottlenecks. For New Entrants and Emerging Players: Lead with home-based specimen collection platforms targeting underserved US regions where clinic access barriers persist. Capture white-space in oropharyngeal cancer indications where academic medical centers pioneer multimodal protocols. Pursue WHO prequalification pathway for cervical cancer elimination procurement contracts. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed specialty clinic networks consolidating immunotherapy administration volumes in Tokyo and Houston. Five-to-ten year viability rests on checkpoint inhibitor pipeline durability beyond cervical indications. Monitor FDA accelerated approval conversion rates to full approval as inflection signal for therapeutic vaccine platform valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Diagnostic-Therapeutic Bundle Consolidation | Hospital procurement committees in Texas and California now require single-source contracting across screening-to-treatment pathways. |
| Therapeutic Vaccine Platform Scale-Up | mRNA manufacturing investment in Singapore and Ireland addresses eighteen-month fill-finish bottlenecks constraining supply. |
| Companion Diagnostic CE Marking Pathway | EMA MDR implementation demands prospective clinical evidence extending HPV assay certification timelines. |
| Oropharyngeal Cancer Indication Expansion | HPV16-driven head and neck malignancy protocols at US academic medical centers attract specialized pharmaceutical investment. |
| Home-Based Specimen Collection Launch | Self-sampling HPV testing kits reduce clinic dependency and penetrate preventive care channels in underserved regions. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with oncology service line administrators, specialty clinic operations directors, diagnostic laboratory managers, and biologics manufacturing executives. Secondary validation drew from FDA oncology guidance documents, EMA MDR certification databases, ClinicalTrials.gov HPV protocol registrations, and hospital procurement contract disclosures. Bottom-up patient volume modeling and top-down pharmaceutical revenue triangulation anchored market sizing across the analysis window.
Across the modeling period, forecast segmentation incorporated treatment approach, cancer indication type, diagnostic method platform, and regional regulatory cluster. CAGRs were derived from patient volume trajectory analysis and pricing elasticity modeling specific to immunotherapy reimbursement frameworks. Forecast inputs included national cervical cancer screening program expansion timelines and therapeutic vaccine clinical pipeline advancement rates.
Underlying assumptions cover immunotherapy adoption curves and diagnostic platform substitution rates, with deviation risk concentrated in payer coverage determination delays and cold chain infrastructure buildout pacing. Revision becomes warranted when checkpoint inhibitor conversion from accelerated to full approval crosses regulatory thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Mental Retardation Treatment Market
Specialty Medicine
Glucagon Therapy Market
Specialty Medicine
Alport Syndrome Treatment Market
Specialty Medicine
Phenylketonuria Therapeutics Market
Specialty Medicine
Ovarian Cancer Therapeutics Market
Specialty Medicine
Marfan Syndrome Management Market
Specialty Medicine
Nonalcoholic Steatohepatitis Market
Specialty Medicine
Cutaneous T-Cell Lymphoma (CTLC) Market
Specialty Medicine
Hepatitis C Treatment Market
Specialty Medicine
Hemangioma Treatment Market
Specialty Medicine
Treatment-Resistance Depression Treatment Market
Specialty Medicine
Chronic Urticaria Market
Specialty Medicine
Hereditary Angioedema Market
Specialty Medicine
Asperger Syndrome Market
Specialty Medicine
Eosinophilic Granulomatosis Market
Specialty Medicine
Hemangioma Market