
 Ovarian Cancer Therapeutics Market | 2026-2036
Ovarian Cancer Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Ovarian Cancer Therapeutics Market Outlook
Gynecologic oncology fellowship training capacity is collapsing across North American academic centers, constraining the specialist pipeline needed to administer complex biologic regimens. AstraZeneca leverages its PARP inhibitor portfolio to sustain leadership in maintenance therapy settings. Roche anchors European clinical trial networks through its broad oncology diagnostics franchise. Merck & Co. competes in the PD-1 checkpoint space with differentiated endometrial and ovarian combination protocols.
Ovarian cancer therapeutics encompass systemic agents designed to eliminate or control malignant epithelial ovarian tumors, including platinum-based cytotoxics, poly ADP-ribose polymerase inhibitors, and vascular endothelial growth factor antagonists administered via intravenous infusion or oral dosing schedules. These interventions aim to extend progression-free survival and overall survival in patients with newly diagnosed or recurrent disease across FIGO stages I through IV. Targeted therapy occupies the fastest-expanding margin pool as PARP inhibitors and anti-angiogenics displace conventional chemotherapy in front-line maintenance. Immunotherapy remains structurally immature in ovarian indications, with checkpoint inhibitors showing limited single-agent efficacy but growing investigator interest in rational combination designs. Intravenous delivery dominates current revenue, though oral formulations are gaining share in maintenance settings where patient convenience drives adherence.
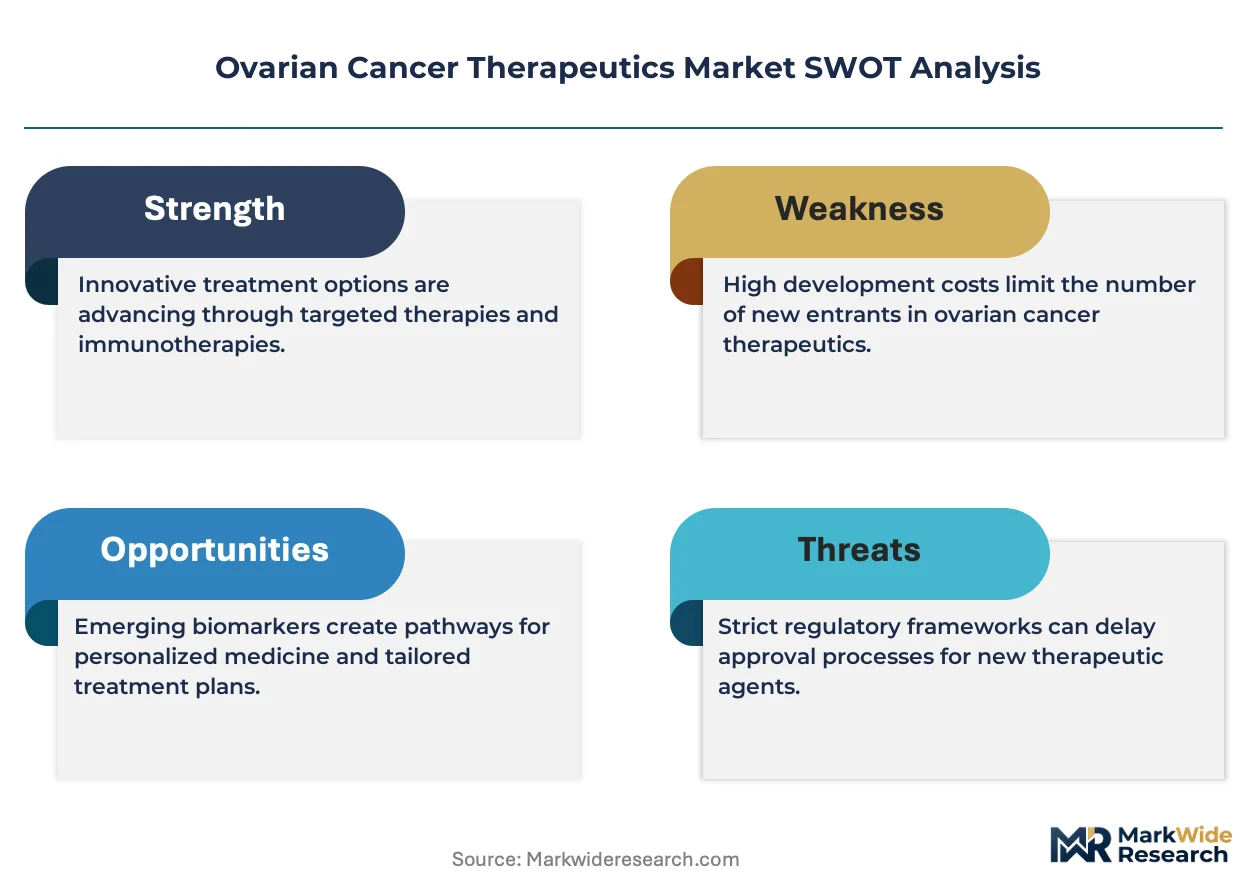
The FDA's accelerated approval and breakthrough therapy designation programs compress development timelines for novel ovarian agents, while EMA's PRIME scheme shapes European launch sequencing for oncology innovators. REACH and RoHS frameworks indirectly influence manufacturing standards for active pharmaceutical ingredients and device components used in drug-device combination products. Stakeholders must monitor evolving biomarker-driven trial designs and companion diagnostic requirements that will determine which therapeutic platforms secure sustainable market access.
Market Dynamics
The FDA's accelerated approval pathways compress commercialization timelines for PARP inhibitors and anti-angiogenic agents, while hospital-based oncology departments restructure care delivery around maintenance therapy protocols that extend treatment duration and reorder prescribing hierarchies.
Growth Catalysts
- Breakthrough Therapy Designation:The FDA's expedited review pathway compresses development timelines for novel ovarian agents, enabling faster patient access to maintenance therapies that extend progression-free survival.
- Biomarker-Driven Patient Selection:Homologous recombination deficiency testing identifies BRCA-mutant and HRD-positive populations, expanding addressable patient pools for targeted PARP inhibitor regimens in front-line settings.
- Academic Medical Center Infrastructure:United States-based comprehensive cancer centers anchor phase III trial networks, generating real-world evidence that accelerates payer reimbursement decisions for premium-priced biologics.
Market Restraints
- Platinum Supply Concentration:Cytotoxic backbone therapies depend on platinum group metal refining concentrated in South Africa and Russia, exposing manufacturers to geopolitical supply disruptions and input cost volatility.
- Gynecologic Oncologist Pipeline Collapse:North American fellowship training capacity constraints limit the specialist workforce required to administer complex biologic regimens and manage immune-related adverse events.
- EMA Parallel Scientific Advice Complexity:Divergent evidentiary requirements between FDA and EMA for companion diagnostic co-development create regulatory friction that delays European market entry.
Strategic Opportunities
- HRD-Negative Population Expansion:Clinical trials in homologous recombination proficient tumors represent an underpenetrated segment where anti-angiogenic and immunotherapy combinations could establish new maintenance standards.
- Oral Formulation Convenience Premium:Patient adherence advantages in United States community oncology practices drive share capture from intravenous delivery, particularly in extended maintenance settings.
- IRA Price Negotiation Exemption Window:Orphan drug status for ovarian indications provides temporary protection from Medicare price controls, preserving pricing power for recently launched agents.
Industry Challenges
- Companion Diagnostic Integration Complexity:CDx assay standardization across multiple platform vendors creates operational friction in pathology workflows, delaying treatment initiation.
- Immunotherapy Biomarker Elusiveness:Absence of predictive signatures for checkpoint inhibitor response in ovarian cancer forces expensive combination trial designs with uncertain regulatory outcomes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ovarian Cancer Therapeutics Market |
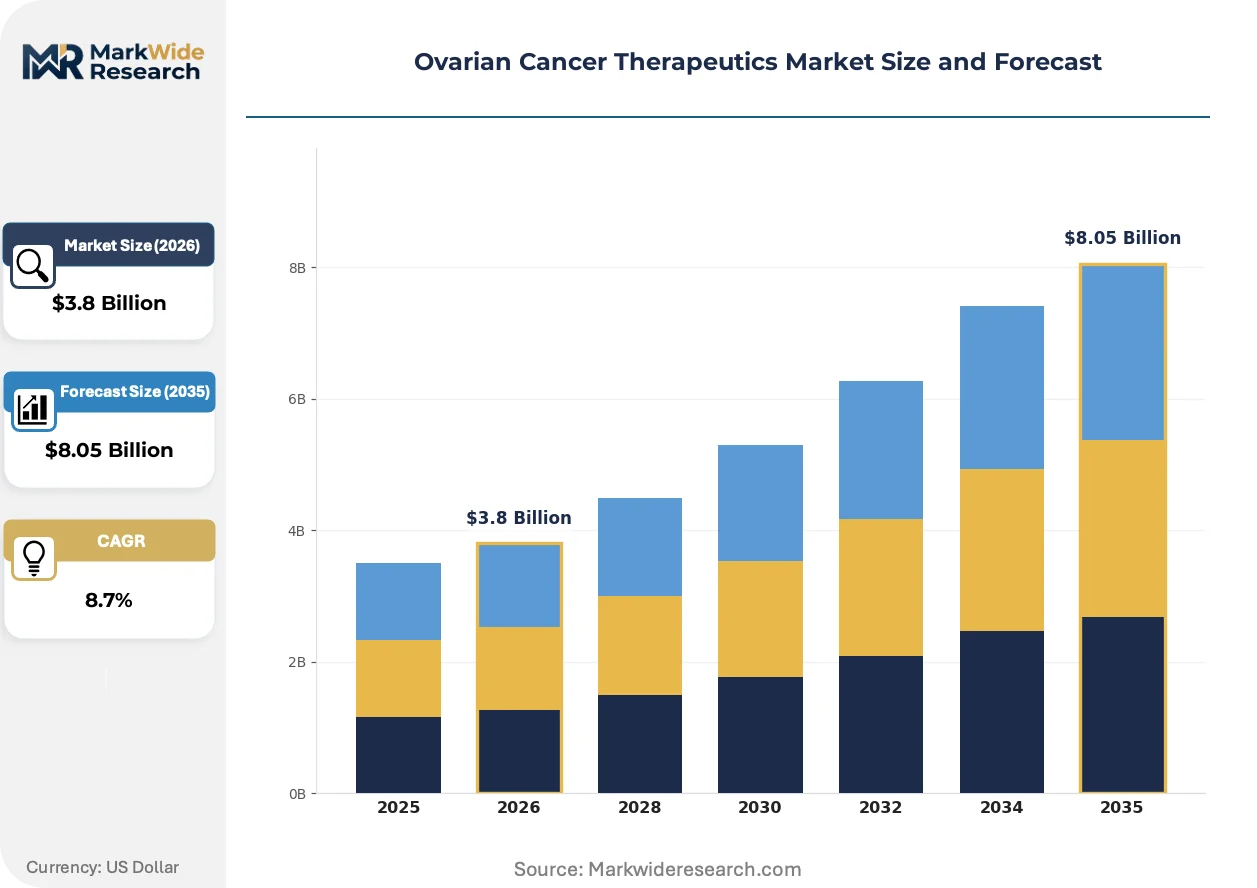
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chemotherapy, Targeted Therapy, Immunotherapy, Hormonal Therapy Delivery Mode: Intravenous, Oral, Subcutaneous, Topical End User: Hospitals, Clinics, Homecare Settings, Research Institutes Treatment Stage: Adjuvant Therapy, Neoadjuvant Therapy, Palliative Care, Maintenance Therapy |
| Companies Covered | Roche, AstraZeneca, GlaxoSmithKline, Johnson & Johnson, Pfizer, Merck & Co., Novartis, Bristol Myers Squibb, AbbVie, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ovarian Cancer Therapeutics Market Strategic Shifts
Maintenance therapy protocols are reordering competitive positioning in ovarian cancer, as oral PARP inhibitors and anti-angiogenics displace intravenous cytotoxics from front-line treatment sequences and reshape prescriber behavior across academic and community settings.
Antibody-drug conjugates targeting folate receptor alpha are bifurcating the recurrent platinum-resistant segment, with mirvetuximab soravtansine gaining accelerated approval and forcing chemotherapy standards to retreat toward later lines. Community oncology practices in the United States are adopting these agents ahead of academic centers, compressing the historical lag between regulatory approval and community penetration. The structural consequence is a narrowing window for conventional cytotoxic salvage regimens.
REACH and RoHS frameworks are tightening manufacturing standards for active pharmaceutical ingredients and device components in drug-device combination products, forcing suppliers to requalify excipient sources and packaging materials. European contract manufacturers face the steepest compliance costs, with ECHA substance-of-very-high-concern listings triggering reformulation cycles for established parenteral formulations. Oncology innovators are responding by consolidating supplier audits and pre-qualifying dual-source API manufacturers.
Patient advocacy networks are compressing clinical trial enrollment timelines by embedding research-naive community sites into phase III networks, displacing the historical concentration of ovarian cancer trials at academic medical centers. United States-based gynecologic oncology cooperative groups are expanding satellite site activation, reducing geographic barriers for rural and underserved populations. This behavioral shift is most visible in the Southeast and Mountain West regions, where community hospital participation in GOG Foundation protocols has tripled.
Ovarian Cancer Therapeutics Market Segmentation
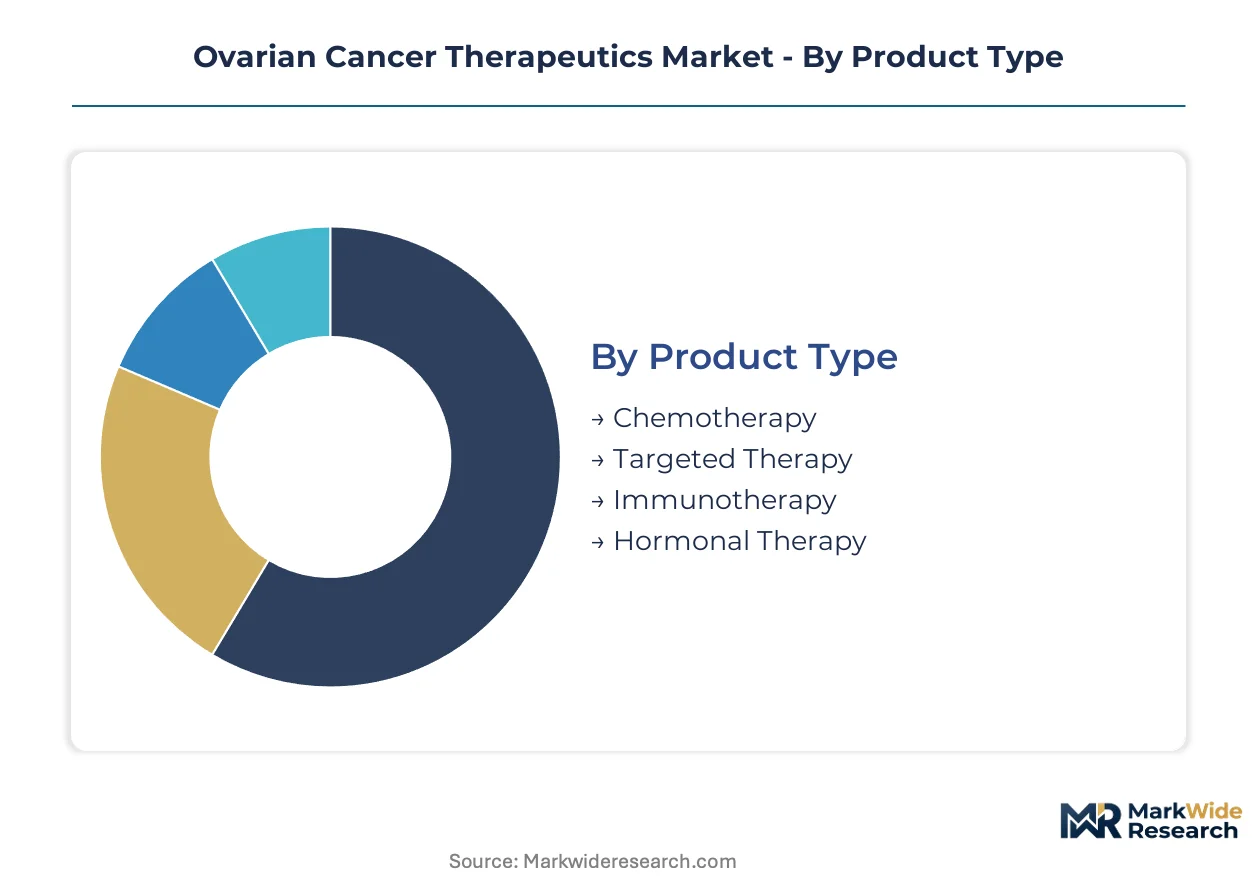
Segmentation in ovarian cancer therapeutics reveals how treatment modalities, delivery formats, and care settings fragment the addressable patient population. Each dimension carries distinct reimbursement profiles, regulatory pathways, and competitive dynamics that reshape manufacturer resource allocation.
Product Type:
Domestic formulation dominates chemotherapy and hormonal therapy production, while targeted therapy and immunotherapy segments depend heavily on imported active pharmaceutical ingredients from European and Asian contract manufacturers.
- Targeted Therapy:PARP inhibitors and anti-angiogenic agents constitute precision medicine platforms with companion diagnostic requirements. United States academic medical centers concentrate demand for these premium-priced oral regimens, driven by biomarker-driven patient selection protocols and maintenance therapy expansion.
- Chemotherapy:Platinum-based cytotoxics and taxanes remain the structural backbone of first-line treatment despite displacement pressures. Manufacturing concentrates in Indian and Chinese API suppliers, exposing finished dose formulators to supply chain volatility from South African platinum refining concentration.
- Immunotherapy:Checkpoint inhibitors show limited single-agent efficacy but growing investigator interest in rational combination designs with PARP inhibitors.
- Hormonal Therapy:Aromatase inhibitors and selective estrogen receptor modulators occupy niche applications in low-grade serous histologies.
Chemotherapy commands the established base. The steepest expansion runs through Targeted Therapy.
Delivery Mode:
Cost tier stratification separates premium oral formulations from standard intravenous infusion, with subcutaneous delivery emerging as a mid-tier convenience play and topical routes occupying minimal oncology applications.
- Oral:PARP inhibitors and small molecule tyrosine kinase inhibitors enable outpatient maintenance therapy with superior adherence profiles. United States community oncology practices drive share capture from hospital-based infusion centers, particularly in extended treatment durations where patient convenience dictates prescribing decisions.
- Intravenous:Cytotoxic backbone therapies require supervised administration in hospital or clinic settings with nursing oversight for infusion reactions. European EMA manufacturing standards and REACH compliance frameworks impose higher qualification costs on parenteral formulation suppliers than oral dose manufacturers face.
- Subcutaneous:Anti-angiogenic agents and biosimilar monoclonal antibodies are migrating to subcutaneous formulations to reduce chair time and facility costs.
- Topical:Minimal relevance in systemic ovarian cancer treatment, confined to palliative skin metastasis management.
Intravenous delivery anchors current revenue. Oral formulations are climbing the fastest as maintenance protocols extend treatment duration.
End User:
Customer type fragmentation splits volume between institutional purchasers with centralized pharmacy and therapeutics committees versus decentralized homecare settings where patient self-administration reshapes compliance monitoring.
- Hospitals:Academic medical centers and comprehensive cancer networks anchor phase III trial participation and premium biologic adoption. United States hospital-based oncology departments are restructuring care delivery around maintenance therapy protocols that reorder prescribing hierarchies and extend treatment duration.
- Homecare Settings:Oral PARP inhibitor regimens enable administration outside institutional settings, reducing facility costs but requiring remote patient monitoring infrastructure. Patient advocacy networks are embedding research-naive community sites into phase III networks, expanding homecare-accessible trial participation in United States Southeast and Mountain West regions.
- Clinics:Community oncology practices adopt novel agents ahead of academic centers, compressing historical approval-to-penetration lag.
- Research Institutes:GOG Foundation and European cooperative groups coordinate multicenter protocol execution with specialized biorepository requirements.
Hospitals command the established base. Homecare Settings are gaining share fastest as oral maintenance protocols displace infusion-dependent regimens.
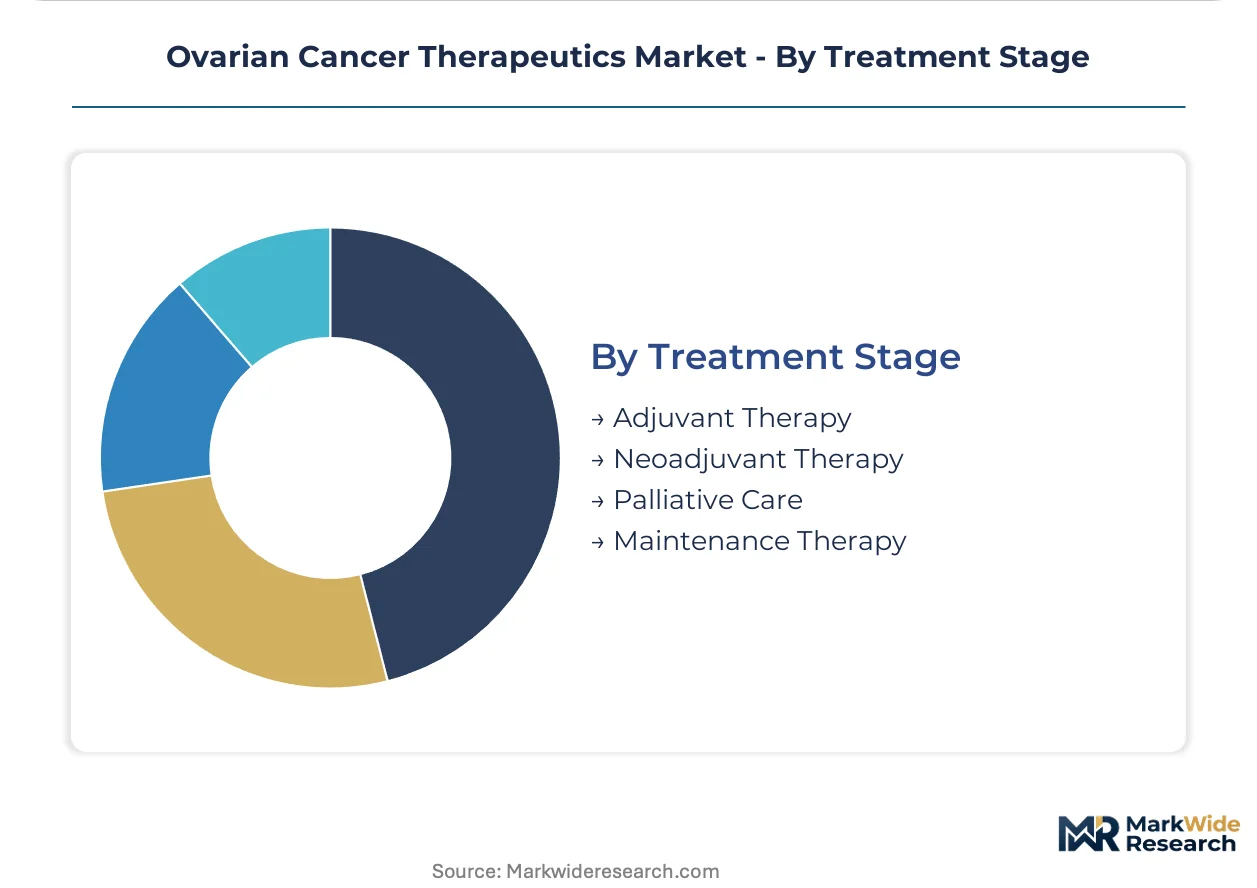
Treatment Stage:
Maturity differentiation separates well-established adjuvant and neoadjuvant applications from the rapidly evolving maintenance therapy segment where FDA breakthrough designations are compressing commercialization timelines.
- Maintenance Therapy:Oral PARP inhibitors and anti-angiogenics displace intravenous cytotoxics from front-line treatment sequences, reshaping prescriber behavior across academic and community settings. FDA accelerated approval pathways for breakthrough oncology therapies are reshaping commercialization timelines for agents in this category.
- Adjuvant Therapy:Post-surgical cytotoxic consolidation remains standard of care despite biomarker-driven de-escalation trials. Platinum-based regimens dominate, with homologous recombination deficiency testing increasingly influencing whether patients transition to PARP inhibitor maintenance.
- Neoadjuvant Therapy:Interval cytoreduction protocols use platinum-taxane combinations to reduce tumor burden before surgery.
- Palliative Care:Recurrent platinum-resistant disease management incorporates antibody-drug conjugates and experimental immunotherapy combinations.
Adjuvant Therapy commands the established base. Maintenance Therapy is expanding most quickly as front-line protocols reorder around progression-free survival extension.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States academic medical centers deploy PARP inhibitors in front-line maintenance at rates exceeding European hospital systems, while Japan's universal coverage framework accelerates post-approval access compared to fragmented European reimbursement negotiations.
United States
FDA breakthrough therapy designations compress commercialization timelines for PARP inhibitors and antibody-drug conjugates. The IRA's orphan drug exemption window preserves pricing power for recently launched maintenance agents. The MD Anderson-GOG Foundation corridor in Houston anchors phase III trial networks generating real-world evidence for payer negotiations.
Germany
EMA parallel scientific advice complexity delays companion diagnostic co-development timelines versus FDA pathways. The country's statutory health insurance funds negotiate reimbursement for premium biologics through the Federal Joint Committee. The Heidelberg-Mannheim oncology cluster concentrates biomarker-driven trial infrastructure for HRD testing standardization.
Japan
PMDA's sakigake designation accelerates access for innovative maintenance therapies ahead of Western markets. The Ministry of Health, Labour and Welfare's centralized pricing reviews create predictable reimbursement pathways for oral PARP inhibitors. The Tokyo-Osaka corridor hosts concentrated phase I/II investigator-initiated trials in platinum-resistant combinations.
United Kingdom
NICE technology appraisals impose cost-effectiveness thresholds that filter access to premium-priced targeted therapies. The NHS Cancer Drugs Fund provides managed access agreements for PARP inhibitors pending final evidence collection. The Manchester-Liverpool axis expands community oncology site activation for GOG Foundation satellite protocols.
China
NMPA's priority review pathways for oncology innovations are compressing approval lags versus historical timelines. National Reimbursement Drug List negotiations impose substantial price reductions for marketed PARP inhibitors. The Beijing-Shanghai corridor concentrates domestic biotech development of folate receptor alpha-targeted modalities.
Ovarian Cancer Therapeutics Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with oncology-focused pharmaceutical conglomerates controlling PARP inhibitor portfolios while midsize biotechs populate the antibody-drug conjugate and immuno-oncology combination spaces. The upper tier consolidates around maintenance therapy leadership through vertically integrated diagnostic-therapeutic pairings. Three archetypes dominate: diversified oncology majors with companion diagnostic franchises, precision medicine specialists with biomarker-driven development engines, and immuno-oncology players pursuing rational combination designs. Competitive moves concentrate on M&A for ADC platform access and strategic partnerships to embed HRD testing into standard pathology workflows.
Within the integrated oncology major tier, AstraZeneca and Roche exemplify divergent geographic anchoring strategies, with the former concentrating United States maintenance therapy share and the latter leveraging European diagnostic networks. Merck & Co. occupies a distinct position in the checkpoint inhibitor combination space. These three entities represent the structural poles around which competitive dynamics in ovarian cancer therapeutics currently organize.
| Leading Market Players |
|---|
| Roche |
| AstraZeneca |
| GlaxoSmithKline |
| Johnson & Johnson |
| Pfizer |
| Merck & Co. |
| Novartis |
| Bristol Myers Squibb |
| AbbVie |
| Others |
Value Chain & Pricing Dynamics
Ninety-day API inventory buffers at European formulation sites now govern contracting terms for platinum-taxane combinations, concentrating pricing power with South African and Russian refiners while forcing finished dose manufacturers to absorb geopolitical risk premiums into long-term supply agreements. This lead-time structure rewards backward-integrated oncology majors with captive platinum sourcing while squeezing margin positions for pure-play formulators dependent on spot market API purchases.
Pricing Analysis
Long-term offtake contracts anchor PARP inhibitor supply agreements between API manufacturers and Big Pharma oncology divisions, with three-tier pricing structure across premium, standard, and economy levels differentiated by FDA breakthrough therapy designation status and companion diagnostic bundling. Price differentiation rests on biomarker testing integration and volume scale commitments from United States academic medical centers versus European hospital systems. Cost compression in the chemotherapy tier intensifies as Indian and Chinese API suppliers expand platinum-taxane capacity. Community oncology practices exhibit highest price sensitivity due to Medicare reimbursement lag, while academic centers with pharmacy and therapeutics committees demonstrate lowest sensitivity due to trial revenue offsets.
Supply Chain Analysis
Inventory lead-times for folate receptor alpha-targeted antibody-drug conjugates stretch to one hundred twenty days due to mammalian cell culture production constraints, creating vulnerability windows for manufacturers without dual-source bioreactor capacity. Active pharmaceutical ingredient production draws from India, China, and Switzerland for small-molecule oncology agents, with biological manufacturing anchored in United States, Ireland, and Singapore facilities. Platinum group metal refining dependence on South African and Russian sources exposes cytotoxic backbone therapies to tariff exposure and export restriction risk. Distribution runs through hospital-based specialty pharmacy channels for intravenous formulations, with oral maintenance agents migrating toward specialty distributor networks serving community oncology practices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The collapsing gynecologic oncologist fellowship pipeline constrains administration capacity for complex biologic regimens, creating scarcity premiums for manufacturers with patient support infrastructure and remote monitoring platforms that extend specialist reach.
For Market Incumbents: Compound diagnostic-therapeutic integration advantages by embedding homologous recombination deficiency testing into standard pathology workflows, defending against biosimilar PARP inhibitor entrants through real-world evidence generation at GOG Foundation trial sites and backward integration into companion diagnostic assay development. For New Entrants and Emerging Players: Anchor in the HRD-negative maintenance therapy segment where anti-angiogenic and immunotherapy combinations lack established standards, targeting United States community oncology practices in the Southeast and Mountain West regions with oral formulation convenience plays and satellite site activation partnerships. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified pharmaceutical conglomerates seeking to divest non-core oncology assets, particularly antibody-drug conjugate platforms with folate receptor alpha targeting mechanisms. Long-term viability hinges on biomarker-driven patient selection capabilities and IRA orphan drug exemption positioning. Watch FDA accelerated approval conversion rates as the signal for portfolio quality differentiation.| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Integration | Embedding HRD testing into pathology workflows secures PARP inhibitor prescribing preference at academic centers. |
| Oral Formulation Development | Patient adherence advantages in extended maintenance settings capture share from intravenous infusion centers. |
| Community Site Activation | GOG Foundation satellite partnerships compress approval-to-penetration lag in research-naive geographies. |
| Dual-Source API Qualification | REACH and RoHS compliance demands pre-qualification of European and Asian contract manufacturers. |
| Patient Support Infrastructure | Remote monitoring platforms offset gynecologic oncologist scarcity and extend specialist reach to underserved regions. |
Study Parameters
Initial hypotheses were tested against primary input from gynecologic oncology fellowship program directors, hospital pharmacy and therapeutics committee chairs, payer access specialists, and regulatory affairs leads at PARP inhibitor developers, then refined through secondary validation against FDA breakthrough therapy designation filings, EMA parallel scientific advice records, ClinicalTrials.gov protocol registrations, and CMS Medicare reimbursement databases. Bottom-up patient flow modeling and top-down pharmaceutical revenue triangulation anchored segmentation estimates.
Variance decomposition across treatment stage, delivery mode, and regional regulatory cluster dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from patient population incidence projections, therapy adoption curve assumptions, and pricing trajectory modeling for maintenance versus adjuvant settings. Forecast inputs incorporated biomarker testing penetration rates, companion diagnostic co-development timelines, and IRA price negotiation exemption windows for orphan-designated indications.
Material uncertainties — FDA accelerated approval conversions, EMA companion diagnostic evidentiary requirement shifts, and platinum supply disruptions — sit outside the modeled envelope. Forecasts reflect documented assumptions subject to revision from these factors. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Global Addison's Disease Treatment Market
Specialty Medicine
Desmoid Tumor Market
Specialty Medicine
Cerebral Vein Thrombosis Treatment Market
Specialty Medicine
Leukocytoclastic Vasculitis Market
Specialty Medicine
Global Primary Angle-Closure Glaucoma Market
Specialty Medicine
Parathyroid Disorders Market
Specialty Medicine
Global Wolff Parkinson White Syndrome Market
Specialty Medicine
Specialty Generics Market
Specialty Medicine
Bronchiectasis Market
Specialty Medicine
Sports Medicine Market
Specialty Medicine
Systemic Scleroderma Treatment Market
Specialty Medicine
Multiple Sclerosis Market
Specialty Medicine
Castrate Resistant Prostate Cancer Therapeutics Market
Specialty Medicine
Wet Age-Related Macular Degeneration (Wet AMD) Market
Specialty Medicine
Breakthrough Therapy Designation Market
Specialty Medicine
Vesicoureteral Reflux Market