
 Hepatitis C Treatment Market | 2026-2036
Hepatitis C Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Hepatitis C Treatment Market Outlook
Sofosbuvir-based regimens is restructuring hepatitis C economics by displacing older interferon-alpha protocols across both developed and emerging reimbursement systems. Gilead Sciences Inc. anchors the branded direct-acting antiviral segment through manufacturing scale and intellectual property depth. AbbVie Inc. competes with differentiated combination offerings that target genotype-specific patient populations. Teva Pharmaceutical Industries Ltd. leverages generic sofosbuvir availability to sustain price-accessibility in public procurement channels.
Hepatitis C treatment encompasses pharmacological protocols designed to eradicate hepatitis C virus infection through targeted suppression of viral replication proteins, with modern direct-acting antivirals achieving sustained virologic response in over 95 percent of compliant patients after 8-12 weeks of oral administration. The oral delivery mode dominates prescription volume due to patient adherence advantages and outpatient administration feasibility, while the interferon-free treatment regimen category captures the fastest growth as tolerability improvements expand eligibility to compensated cirrhosis and previously excluded comorbid populations. Hospitals remain the primary end user channel where formulary control and specialist oversight concentrate margin pools, though home care settings are gaining share as simplified dosing enables decentralized treatment initiation.
The FDA maintains stringent chemistry, manufacturing, and controls requirements for hepatitis C antivirals that shape product development costs and approval timelines, while the EMA's centralized marketing authorization process governs access across European Union member states with coordinated health technology assessment protocols. WHO prequalification standards influence procurement eligibility for low-income country programs funded through global health initiatives. Stakeholders must monitor evolving national elimination program budgets and biosimilar entry timelines to calibrate portfolio positioning between originator defense and volume-access strategies.
Market Dynamics
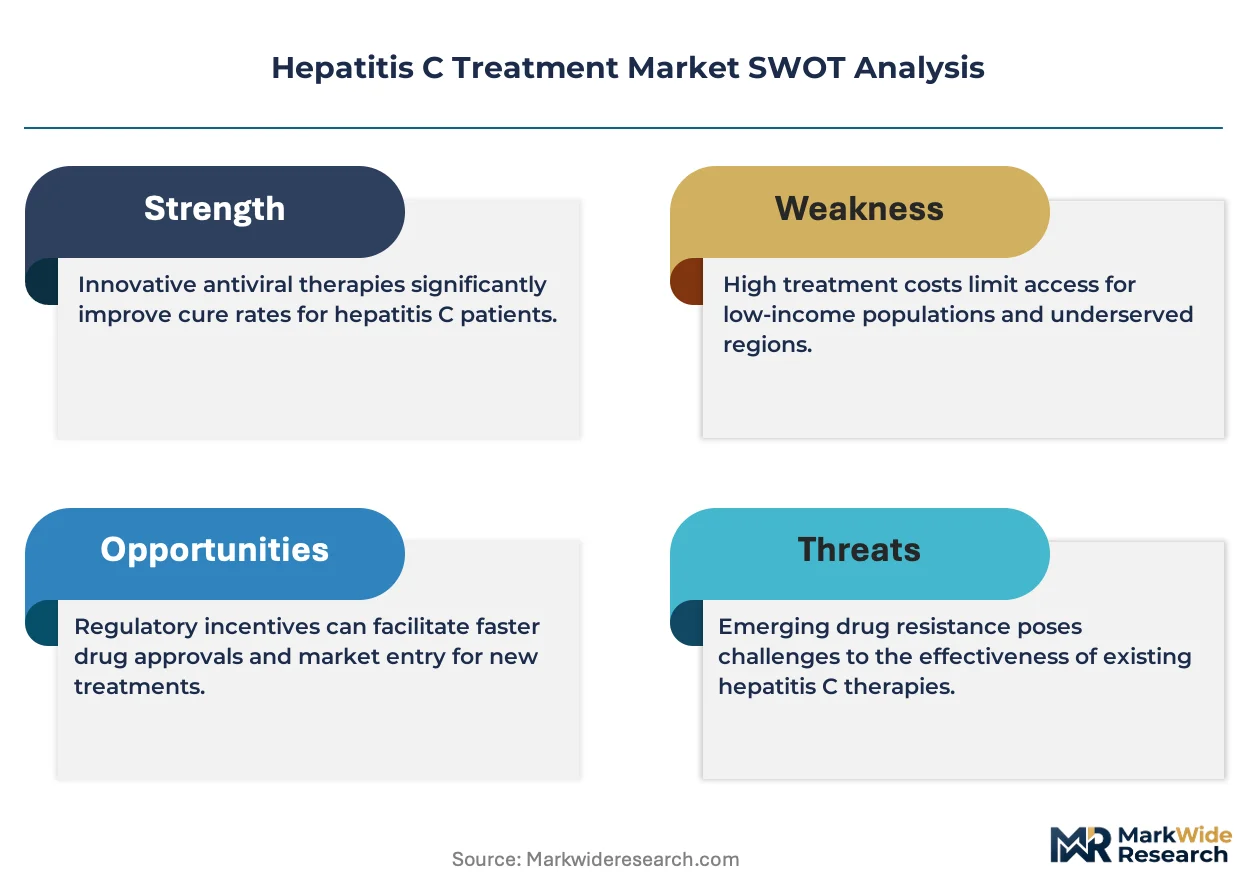
Direct-acting antiviral regimens are compressing treatment duration from 48 weeks to 8-12 weeks while eliminating interferon side effects, fundamentally restructuring patient eligibility criteria and prescriber workflows across reimbursement systems.
Growth Catalysts
- Medicaid Expansion:State-level program enrollment growth in the United States sustains high-volume prescribing for previously uninsured patient populations.
- FDA Breakthrough Therapy Designation:Accelerated review pathways compress development timelines for novel combination regimens targeting resistant genotypes.
- Pan-genotypic Formulations:Single-tablet regimens eliminate pre-treatment genotyping requirements, expanding treatment initiation in resource-limited clinical settings.
Market Restraints
- Active Pharmaceutical Ingredient Concentration:Manufacturing of key sofosbuvir intermediates concentrates in Asian chemical clusters, exposing supply chains to single-source vulnerability.
- Reimbursement Ceiling Compression:State Medicaid programs impose mandatory supplemental rebates that compress net pricing below cost-recovery thresholds for originator manufacturers.
- Virologic Relapse Mechanisms:NS5A resistance-associated substitutions limit retreatment options for patients failing first-line direct-acting antiviral therapy.
Strategic Opportunities
- Micro-elimination Programs:Targeted screening and treatment protocols for incarcerated populations and people who inject drugs offer concentrated prevalence pools in the United States.
- Decentralized Care Models:Primary care prescribing authority expansion enables treatment initiation outside hepatology specialist networks.
- Generic Substitution Windows:Patent cliff transitions for sofosbuvir and velpatasvir create procurement flexibility for public health programs in low-income countries.
Industry Challenges
- Hepatology Workforce Constraints:Specialist physician shortages in rural and underserved regions create treatment access bottlenecks despite simplified regimens.
- Real-world Adherence Monitoring:Direct-acting antiviral therapy requires 95 percent plus compliance to achieve sustained virologic response, demanding patient support infrastructure that strains pharmacy budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hepatitis C Treatment Market |
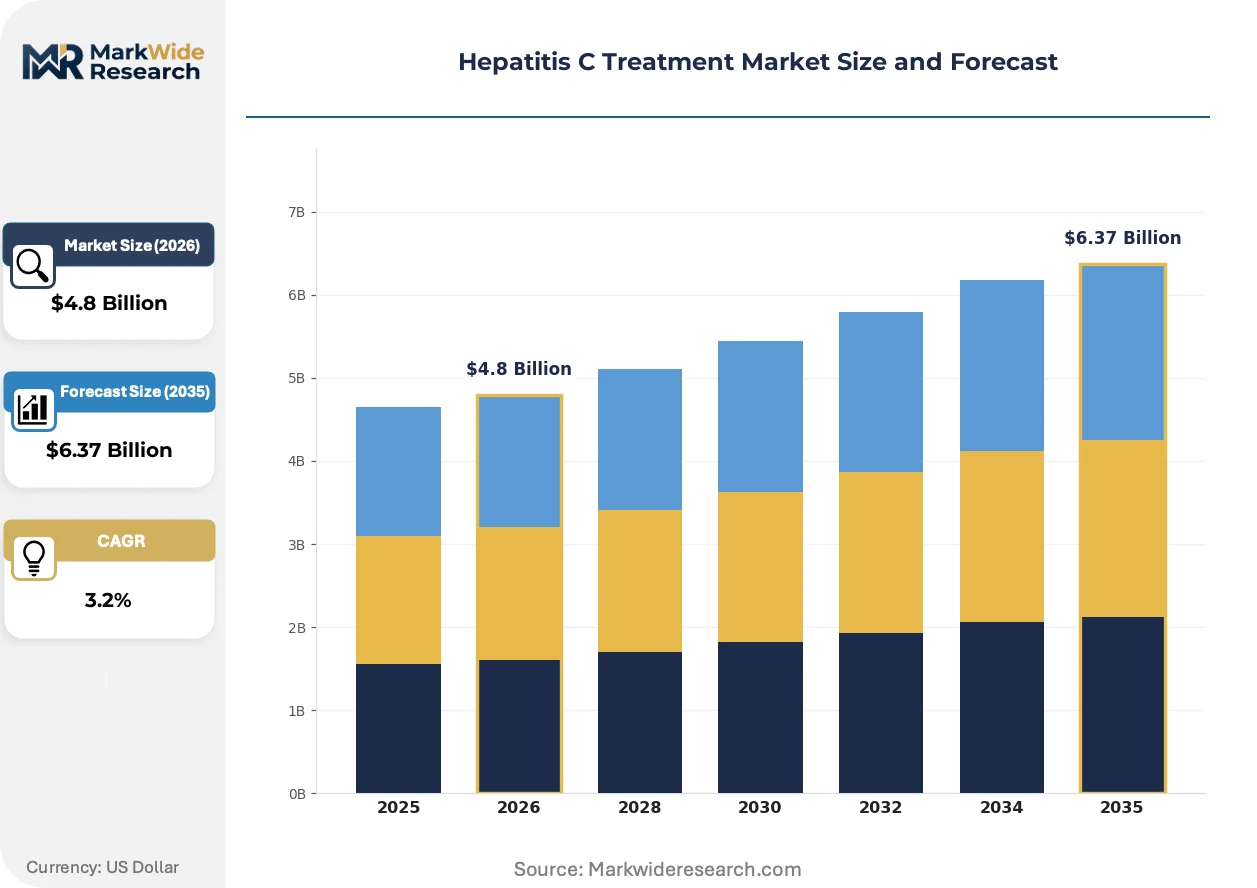
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.37 Billion |
| CAGR (2026 – 2036) | 3.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sofosbuvir, Velpatasvir, Ledipasvir, Ribavirin Delivery Mode: Oral, Injectable, Intravenous, Subcutaneous End User: Hospitals, Clinics, Home Care, Rehabilitation Centers Treatment Regimen: Washout, Interferon-free, Triple Therapy, Combination Therapy |
| Companies Covered | Gilead Sciences Inc., AbbVie Inc., Merck & Co., Inc., Bristol-Myers Squibb Company, F. Hoffmann-La Roche Ltd, Janssen Pharmaceuticals, Inc., Vertex Pharmaceuticals Incorporated, Teva Pharmaceutical Industries Ltd., GSK plc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hepatitis C Treatment Market Strategic Shifts
Oral direct-acting antivirals are displacing parenteral interferon protocols across all patient risk strata, while regulatory pressure and procurement innovation simultaneously reshape competitive positioning and channel economics.
Pan-genotypic single-tablet regimens containing sofosbuvir-velpatasvir combinations are absorbing prescriber preference across genotype 1-6 patient populations. Gastroenterology and primary care practices in the United States and European Union member states are transitioning the majority of naive patients to these formulations within 18-24 months of formulary inclusion. This absorption is compressing demand for genotype-specific alternatives and reducing laboratory infrastructure requirements for pre-treatment testing.
The FDA's Risk Evaluation and Mitigation Strategy for direct-acting antivirals mandates prescriber certification and patient counseling documentation for certain combination products. This regulatory framework elevates compliance costs for manufacturers while creating formulary control leverage for hospital pharmacy and therapeutics committees. Medicaid programs in the United States are responding by implementing prior authorization protocols that restrict dispensing to certified prescribers and designated specialty pharmacies.
Hospital procurement consortia are consolidating purchasing authority for direct-acting antiviral regimens through multi-year sole-source agreements with manufacturers. These arrangements displace open formulary competition in favor of volume-commitment contracts that bundle rebates with clinical outcome guarantees. The Veterans Health Administration and integrated delivery networks in the United States represent the most visible adopters of this consolidated purchasing model.
Hepatitis C Treatment Market Segmentation
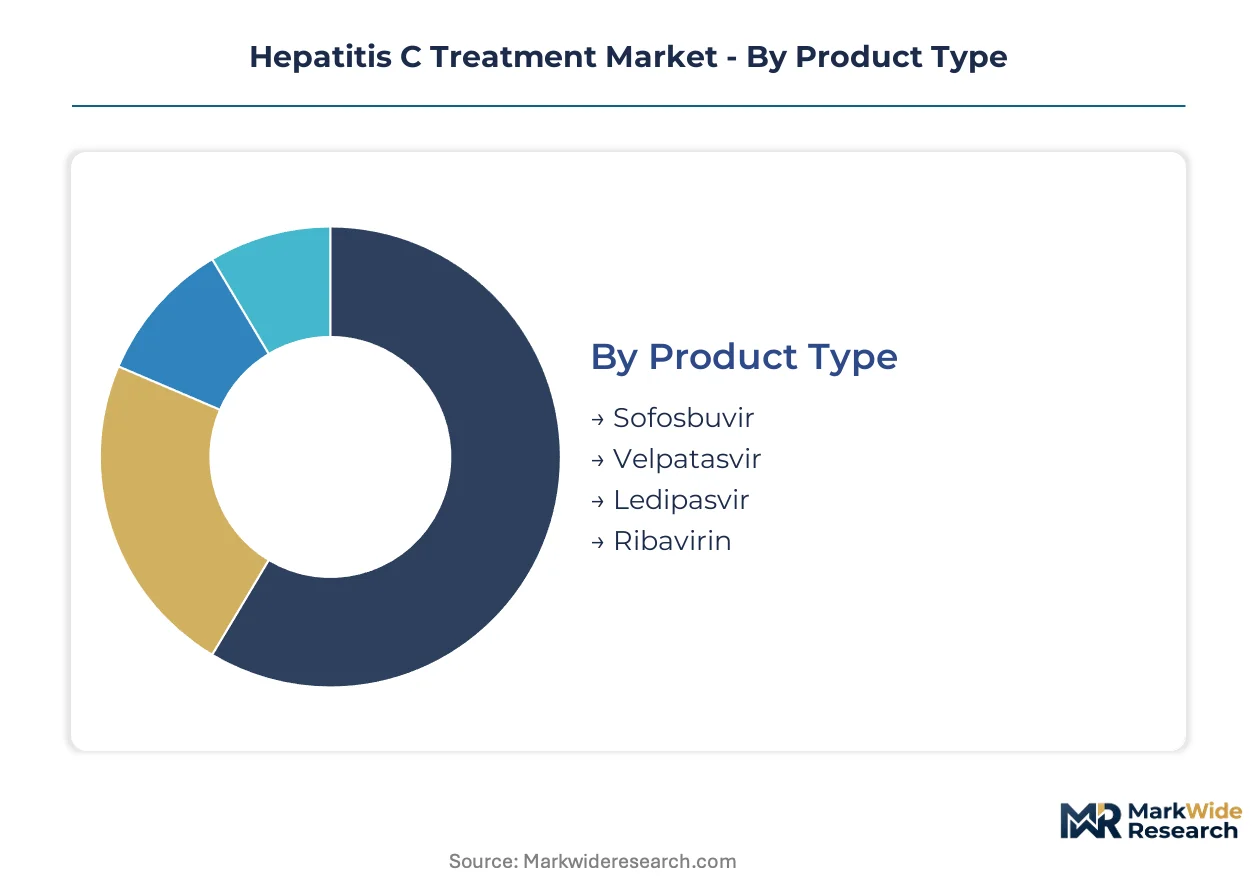
Hepatitis C treatment segmentation reveals how procurement authority, patient acuity, and regimen complexity fragment demand across channels. Manufacturers must align portfolio depth with the specific compliance infrastructure and reimbursement mechanics governing each category.
Product Type:
Prescriber preference differentiates by resistance profile, prior treatment history, and formulary tier placement rather than list price alone.
- Sofosbuvir:Nucleotide analog polymerase inhibitor forming the backbone of most modern regimens. Demand concentrates in United States Medicaid programs and Veterans Health Administration formularies where pan-genotypic utility simplifies prior authorization workflows.
- Velpatasvir:NS5A inhibitor co-formulated with sofosbuvir in single-tablet regimens. Prescription volume tilts toward integrated delivery networks seeking to minimize specialist referrals through primary care prescribing expansion.
- Ledipasvir:Genotype 1-4 focused NS5A inhibitor with established real-world efficacy data. Retains formulary position in European hospital consortia with mature health technology assessment protocols.
- Ribavirin:Nucleoside analog now reserved for retreatment scenarios and specific compensated cirrhosis protocols. Procurement persists in public health programs managing salvage therapy populations.
Volume sits with sofosbuvir-based combinations; growth tilts toward velpatasvir co-formulations as primary care prescribing authority expands.
Delivery Mode:
Route selection hinges on patient adherence capacity, outpatient infrastructure availability, and pharmacy benefit design for self-administration support.
- Oral:Once-daily tablet administration enabling decentralized treatment initiation. Demand clusters in United States commercial and Medicaid plans where 8-12 week completion rates exceed 95 percent with adequate patient support.
- Injectable:Parenteral interferon protocols now largely displaced except for specific coinfection scenarios. Remaining volume concentrates in correctional health systems with directly observed therapy requirements.
- Intravenous:Hospital-administered formulations for acute decompensation or peri-transplant management. Utilization tracks liver transplant center procedure volumes and acute care admission patterns.
- Subcutaneous:Self-injection protocols for patients with swallowing dysfunction or malabsorption syndromes. Niche demand from gastroenterology practices managing advanced cirrhosis populations.
Oral formulations absorb the dominant prescription share; intravenous delivery maintains position in transplant center ecosystems.
End User:
Channel selection reflects prescriber certification requirements, prior authorization complexity, and patient support infrastructure investment thresholds.
- Hospitals:Academic medical centers and community hospitals with hepatology specialist networks. Formulary control concentrates procurement authority through pharmacy and therapeutics committee gatekeeping.
- Clinics:Federally qualified health centers and gastroenterology practices with prescriber certification. Volume expansion follows state-level primary care prescribing authority liberalization.
- Home Care:Specialty pharmacy dispensing with telehealth monitoring for stable patients. Growth tracks simplified regimen adoption enabling treatment initiation outside traditional specialist channels.
- Rehabilitation Centers:Substance use disorder treatment facilities integrating hepatitis C screening and treatment. Demand concentrates in micro-elimination programs targeting people who inject drugs.
Hospitals retain the dominant volume position; home care and rehabilitation centers are climbing the fastest as decentralized models proliferate.
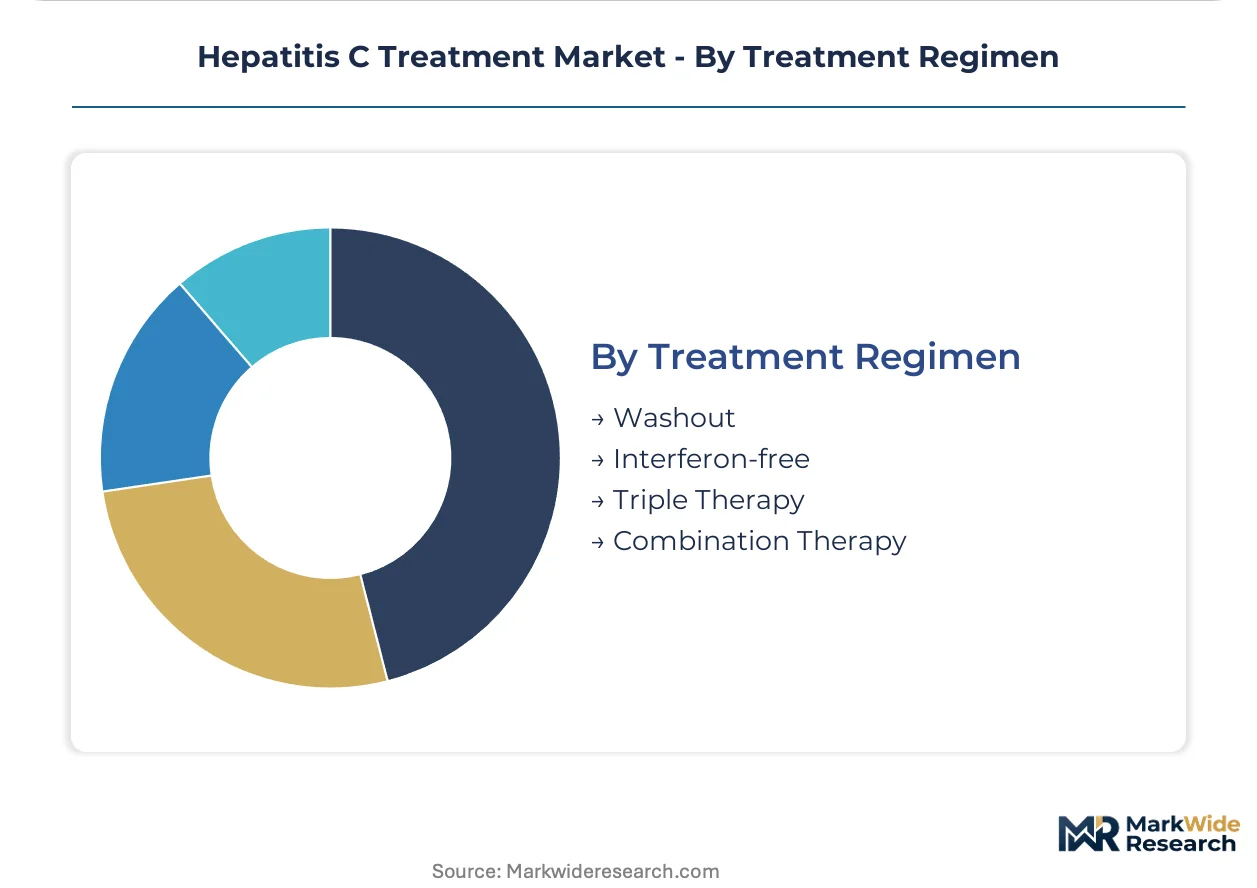
Treatment Regimen:
Regimen selection stratifies by prior treatment exposure, resistance testing availability, and payer step therapy requirements.
- Interferon-free:Direct-acting antiviral combinations eliminating parenteral side effects. Prescription dominance in United States and European Union markets where tolerability drives expanded eligibility.
- Combination Therapy:Multi-mechanism regimens targeting resistant genotypes or retreatment scenarios. Utilization concentrates in referral centers managing virologic failure cases.
- Triple Therapy:Protease inhibitor plus polymerase inhibitor plus NS5A inhibitor for salvage indications. Reserved for patients with documented resistance-associated substitutions.
- Washout:Structured treatment interruption protocols for adverse event management or drug-drug interaction resolution. Niche application in complex comorbidity populations.
Interferon-free regimens command the volume base; combination therapy for resistant cases shows the steepest expansion trajectory as retreatment populations accumulate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Research Triangle Park in North Carolina concentrates hepatitis C clinical trial infrastructure, attracting sponsor investment through state tax credits for infectious disease research. This concentration pattern repeats across specialized biomedical zones worldwide.
United States
Medicaid expansion in 40 states sustains high-volume prescribing for previously uninsured populations. The FDA's breakthrough therapy designation compresses development timelines for novel combination regimens. Baltimore's Johns Hopkins hepatology cluster anchors micro-elimination program design for incarcerated populations.
Germany
EMA centralized marketing authorization governs formulary access across federal states with coordinated health technology assessment. The G-BA's benefit assessment protocols determine reimbursement levels for pan-genotypic regimens. Munich's university hospital consortium consolidates procurement authority through multi-year sole-source agreements.
Japan
PMDA's sakigake designation accelerates review for direct-acting antivirals targeting resistant genotypes. METI's healthcare export promotion supports domestic manufacturer expansion into Southeast Asia. Tokyo's hepatology specialist networks concentrate retreatment protocol development for virologic failure cases.
United Kingdom
NICE technology appraisals set cost-effectiveness thresholds for NHS England procurement of interferon-free regimens. The UK Health Security Agency's elimination program targets people who inject drugs through community pharmacy testing. London's integrated care systems pilot decentralized prescribing authority for primary care physicians.
India
CDSCO accelerated approval pathways enable generic sofosbuvir market entry under compulsory licensing provisions. The National Viral Hepatitis Control Program expands public procurement through pooled state purchasing. Hyderabad's active pharmaceutical ingredient cluster supplies key sofosbuvir intermediates to domestic formulation manufacturers.
Hepatitis C Treatment Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with originator firms defending intellectual property depth while generic producers capture volume in public procurement channels. The market structure concentrates around three strategic archetypes: pan-genotypic regimen developers, genotype-specific combination specialists, and high-volume generic manufacturers. Consolidation through sole-source hospital contracts and strategic licensing agreements for patent cliff transitions represents the dominant competitive dynamic.
Among originator-tier developers, Gilead Sciences Inc., AbbVie Inc., and Merck & Co., Inc. exemplify contrasting strategic positions. Gilead Sciences Inc. anchors the branded segment through manufacturing scale and sofosbuvir patent estate depth. AbbVie Inc. occupies a differentiated position with genotype-specific combination offerings. Merck & Co., Inc. represents the diversified pharmaceutical archetype with hepatitis C assets integrated within broader infectious disease portfolios.
| Leading Market Players |
|---|
| Gilead Sciences Inc. |
| AbbVie Inc. |
| Merck & Co., Inc. |
| Bristol-Myers Squibb Company |
| F. Hoffmann-La Roche Ltd |
| Janssen Pharmaceuticals, Inc. |
| Vertex Pharmaceuticals Incorporated |
| Teva Pharmaceutical Industries Ltd. |
| GSK plc. |
| Others |
Value Chain & Pricing Dynamics
Originator-generic divergence in hepatitis C antivirals creates a bifurcated market where patent-protected pan-genotypic regimens command formulary premiums against commodity-priced sofosbuvir generics, with this tier split manifesting in concentrated API sourcing from Asian chemical clusters versus distributed finished-dose manufacturing for high-income market access.
Pricing Analysis
Volume-margin splits separate branded originators from generic manufacturers across procurement channels. Three-tier pricing structure across premium, standard, and economy levels tracks FDA breakthrough designation status, WHO prequalification tier, and Medicaid supplemental rebate exposure. Cost compression in the originator tier intensifies because state Medicaid programs extract mandatory rebates exceeding 50 percent off list price. Public procurement programs in low-income countries exhibit the highest price sensitivity, while integrated delivery networks in the United States demonstrate the lowest due to outcome-based contracting guarantees.
Supply Chain Analysis
Single-source vulnerability sits with Chinese and Indian API manufacturers for key sofosbuvir intermediates including pyrimidine nucleoside analogs and phosphoramidate prodrug precursors. Finished formulation draws from United States, European Union, and Indian facilities with divergent GMP certification tiers. Tariff exposure on active pharmaceutical ingredient imports threatens margin stability for European formulation sites. Distribution runs through hospital procurement consortia and specialty pharmacy networks with cold-chain requirements for limited biologic alternatives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The hepatitis C treatment market functions as a cost-of-compliance story where FDA Risk Evaluation and Mitigation Strategy certification requirements create barrier-to-entry moats that protect incumbent formulary positions against unqualified competitors.
For Market Incumbents: Anchor manufacturing scale advantages through backward integration into pyrimidine nucleoside supply, securing captive production of key sofosbuvir intermediates against Asian API supply disruptions. Defend against generic erosion by expanding prescriber certification networks that embed REMS compliance costs into competitor entry economics.
For New Entrants and Emerging Players: Rural primary care practices with delegated prescribing authority represent the most penetrable buyer archetype for interferon-free generic regimens, bypassing hepatology specialist gatekeeping that concentrates incumbent volume. Target micro-elimination programs for incarcerated populations through correctional health system procurement channels, leveraging simplified eight-week protocols that reduce patient support infrastructure requirements.
For Investors and Strategic Acquirers: Exit pathways concentrate in specialty pharmaceutical roll-ups seeking hepatitis C assets as cash-flow anchors within broader infectious disease portfolios. Long-term viability hinges on patent cliff navigation for velpatasvir and sofosbuvir estate transitions. Watch for FDA guidance on retreatment protocols for NS5A-resistant populations as the signal indicating next-generation combination therapy investment timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Accelerated FDA breakthrough designation compresses development timelines for resistant genotype regimens. |
| Regulatory Approval Pathway | WHO prequalification unlocks pooled procurement eligibility for low-income country elimination programs. |
| Manufacturing Scale-Up | API capacity expansion in Hyderabad cluster reduces single-source dependency for sofosbuvir intermediates. |
| Licensing Agreement | Patent cliff transitions for velpatasvir create generic substitution windows in public procurement channels. |
| Pipeline Diversification | NS5A inhibitor combinations for virologic failure populations address accumulating retreatment demand. |
Study Parameters
Document review covered FDA REMS documentation, EMA centralized marketing authorization filings, and WHO prequalification records, complemented by interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists. Secondary validation drew from ClinicalTrials.gov registries, CMS Medicaid drug rebate data, and formulary database extracts. Bottom-up prescription volume modeling and top-down market sizing triangulated across these sources.
Cross-reference between historical Medicaid utilization patterns and expert panel input on primary care prescribing expansion informed the analytical framework across the analysis window. Segmentation dimensions included treatment line, delivery mode, end-user channel, and regional regulatory cluster. CAGRs derived from patient population prevalence projections, reimbursement policy trajectories, and generic entry timeline assumptions. Forecast inputs incorporated hepatology workforce density and micro-elimination program budget allocations.
Revisions become necessary when FDA guidance on retreatment protocols materializes, compulsory licensing decisions alter generic access timelines, or API supply disruptions from concentrated Asian manufacturing clusters persist. Deviation in state Medicaid supplemental rebate negotiations would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Acromegaly Market
Specialty Medicine
Benign Positional Vertigo Market
Specialty Medicine
Anaplastic Large Cell Lymphoma (ALCL) Therapeutics Market
Specialty Medicine
Global Acquired Aplastic Anemia Market
Specialty Medicine
Post-Traumatic Stress Disorder Treatment Market
Specialty Medicine
Angioimmunoblastic T-Cell Lymphoma (AILT) Market
Specialty Medicine
Breakthrough Therapy Designation Market
Specialty Medicine
Leukocyte Adhesion Deficiency Management Market
Specialty Medicine
Myelofibrosis Market
Specialty Medicine
Bartter Syndrome Treatment Market
Specialty Medicine
Adult Malignant Glioma Therapeutics Market
Specialty Medicine
Eosinophilia Therapeutics Market
Specialty Medicine
Global Lichen Nitidus Treatment Market
Specialty Medicine
Global Eye Allergy Therapeutics Market
Specialty Medicine
Adenomyosis Market
Specialty Medicine
Dural Arteriovenous Fistulas Treatment Market