
 Chronic Urticaria Market | 2026-2036
Chronic Urticaria Market Size, Share, and Industry Trends Forecast 2026-2036
Chronic Urticaria Market Intelligence
The EU Green Deal is repositioning pharmaceutical manufacturing standards across Europe, pushing chronic urticaria drug makers toward lower-carbon production audits. Sanofi leverages its established biologics infrastructure to sustain European supply continuity. Novartis anchors its position through deep R&D investment in next-generation monoclonal antibodies. AbbVie competes aggressively on manufacturing scale for injectable formulations.
Chronic urticaria denotes a recurrent inflammatory skin condition characterized by wheals and angioedema persisting beyond six weeks, driven by mast cell activation and histamine release. Biologics targeting IgE and IL-5 pathways now command the fastest expansion within product type segmentation, while antihistamines retain volume leadership in mild-to-moderate cases. Homecare delivery is gaining structural share among end user segments as self-administered injectable formats reduce hospital dependency.
The FDA, EMA, and Japan's PMDA each enforce distinct biologics licensing and post-market surveillance requirements that shape development timelines and commercial access strategies. REACH compliance in Europe adds material traceability burdens for active pharmaceutical ingredient sourcing. Stakeholders must monitor evolving biosimilar entry pathways and payer negotiation frameworks across these three regulatory jurisdictions.
Market Dynamics
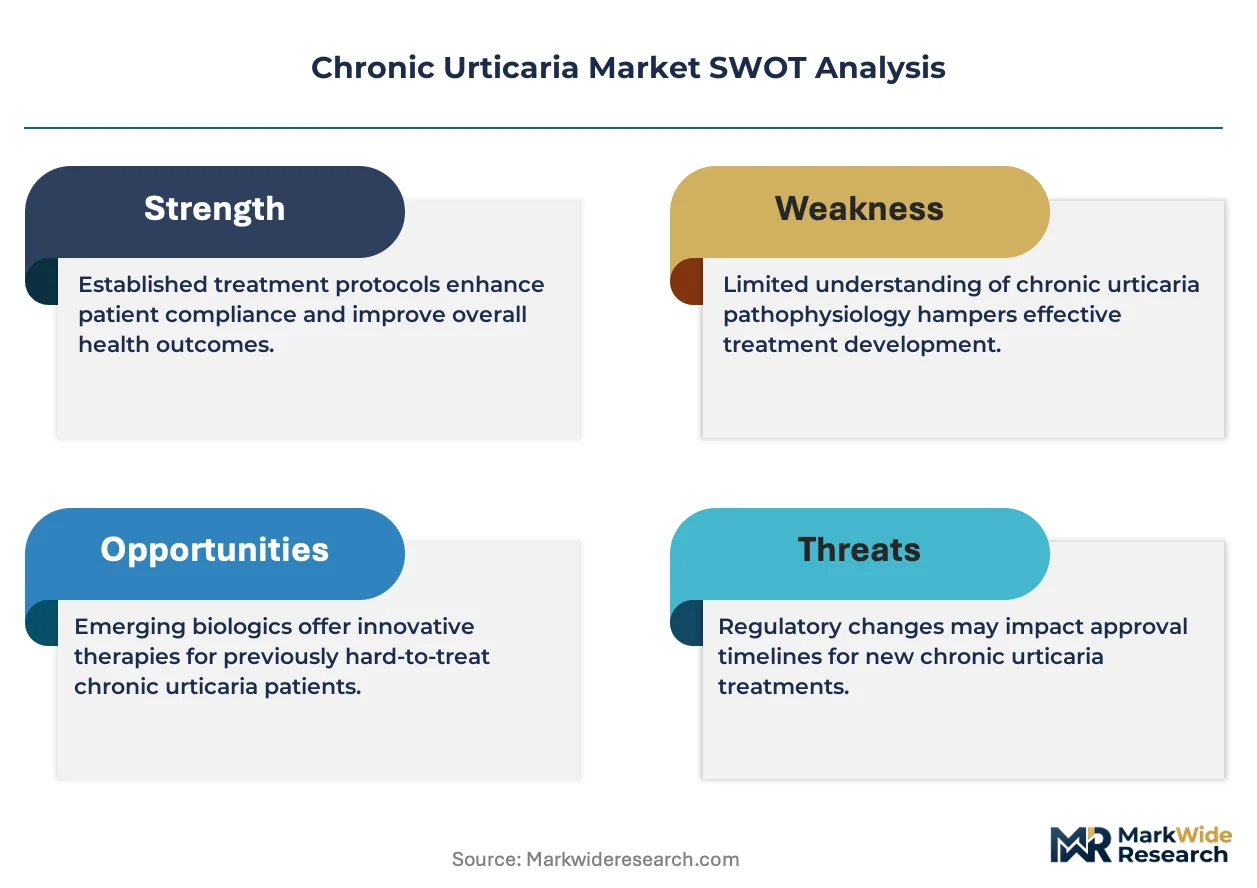
Biologics targeting mast cell pathways are compressing treatment paradigms as hospital infusion programs expand capacity and payer formularies narrow toward high-efficacy injectables.
Growth Catalysts
- FDA Accelerated Approval:The FDA's streamlined biologics pathway compresses development timelines for IgE and IL-5 inhibitors, enabling faster commercialization of next-generation monoclonal antibodies.
- Homecare Delivery Models:Self-administered subcutaneous formulations are displacing hospital-based infusions, reducing systemic cost burdens and expanding addressable patient pools.
- Specialized Care Networks:Germany, the United States, and Japan are building dedicated urticaria treatment centers that concentrate prescriber expertise and biologic prescribing authority.
Market Restraints
- Biologic Manufacturing Concentration:Contract manufacturing organizations in Switzerland and Ireland control critical fill-finish capacity for temperature-sensitive injectables, creating single-source vulnerabilities.
- REACH Compliance Burden:ECHA traceability requirements for active pharmaceutical ingredients add 12-18 month qualification timelines to European supply chains.
- Antihistamine Substitution:Generic second-generation H1 antagonists retain formulary preference in mild-to-moderate cases, limiting biologic penetration in primary care settings.
Strategic Opportunities
- Pediatric Indication Expansion:Unmet need in adolescent chronic urticaria creates whitespace for biologics with established adult efficacy to pursue supplementary approvals.
- EU Green Deal Alignment:Lower-carbon production audits position compliant manufacturers for preferred procurement status under European hospital sustainability mandates.
- Biosimilar Entry Pathways:Evolving EMA and FDA guidance on biologic interchangeability opens channel for follow-on biologics to capture volume in post-patent markets.
Industry Challenges
- Cold Chain Integrity:Temperature excursion risks during last-mile distribution to homecare patients require specialized logistics partnerships and real-time monitoring infrastructure.
- Immunogenicity Surveillance:Post-market anti-drug antibody monitoring demands extended pharmacovigilance commitments that strain regulatory affairs capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chronic Urticaria Market |
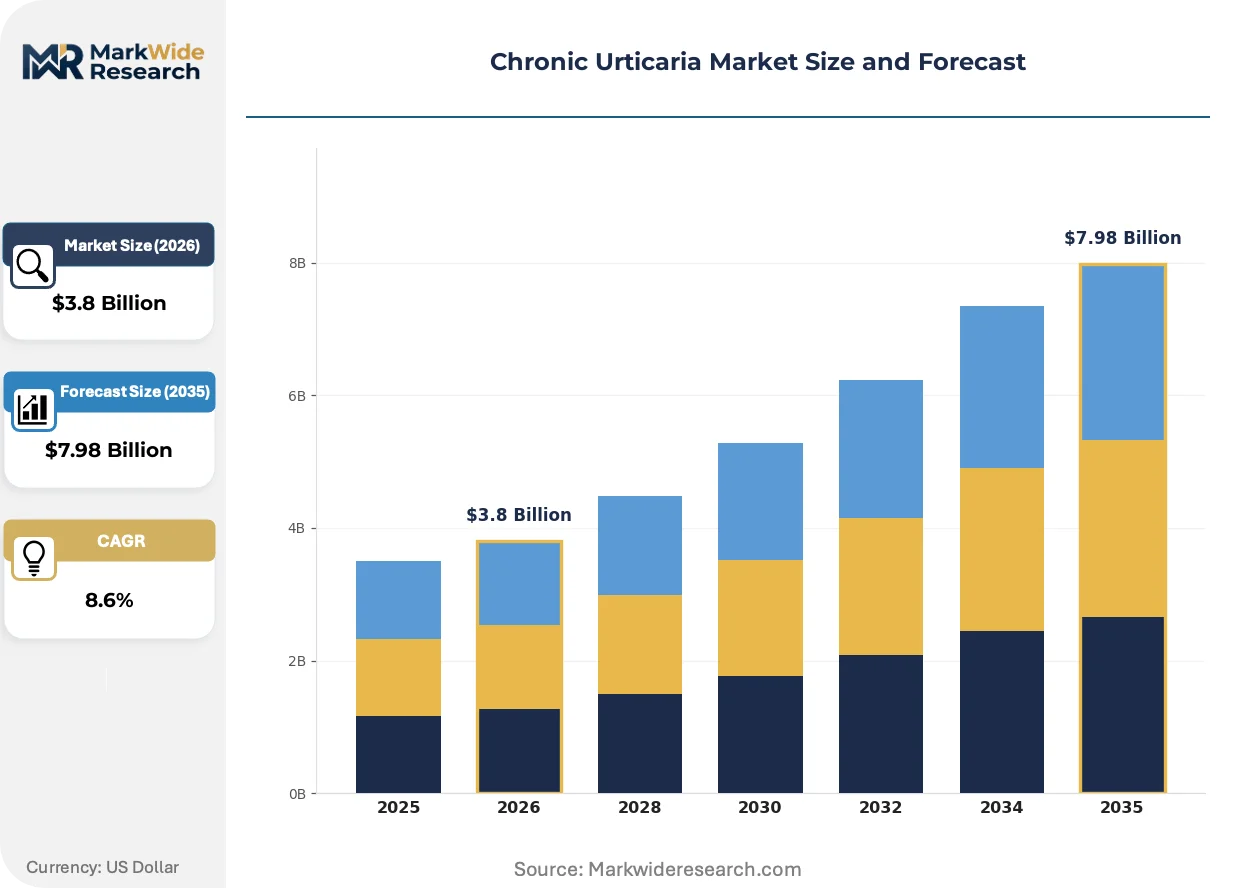
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.98 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antihistamines, Corticosteroids, Biologics, Immunosuppressants End User: Hospitals, Clinics, Homecare, Pharmacies Treatment Method: Oral, Injectable, Topical, Combination Therapy Severity Level: Mild, Moderate, Severe, Chronic |
| Companies Covered | F. Hoffmann-La Roche Ltd., Merck & Co., Inc., Sanofi, Teva Pharmaceutical Industries Ltd., AbbVie Inc., Novartis AG, Bayer AG, Celldex Therapeutics, GlaxoSmithKline, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chronic Urticaria Market Strategic Shifts & Innovations
Three intersecting forces are restructuring how chronic urticaria therapies reach patients: biologic modality evolution, regulatory acceleration mechanisms, and care setting migration.
Subcutaneous autoinjector platforms are electrifying patient autonomy by eliminating infusion center dependency. Rheumatology and dermatology practices are adopting these devices at accelerating rates, compressing the traditional hospital-centric delivery model into ambulatory and home-based administration.
EMA's adaptive licensing pilots are compressing Phase III-to-approval timelines for biologics demonstrating strong early efficacy signals. This regulatory innovation is reshaping competitive entry sequences, with European launch timelines now frequently preceding full FDA approval for targeted indications.
Hospital pharmacy committees are consolidating biologic purchasing through centralized tendering mechanisms. This procurement concentration is displacing individual physician preference in Germany and France, with formulary decisions increasingly tied to outcome-based rebate structures rather than list pricing alone.
Chronic Urticaria Market Segmentation
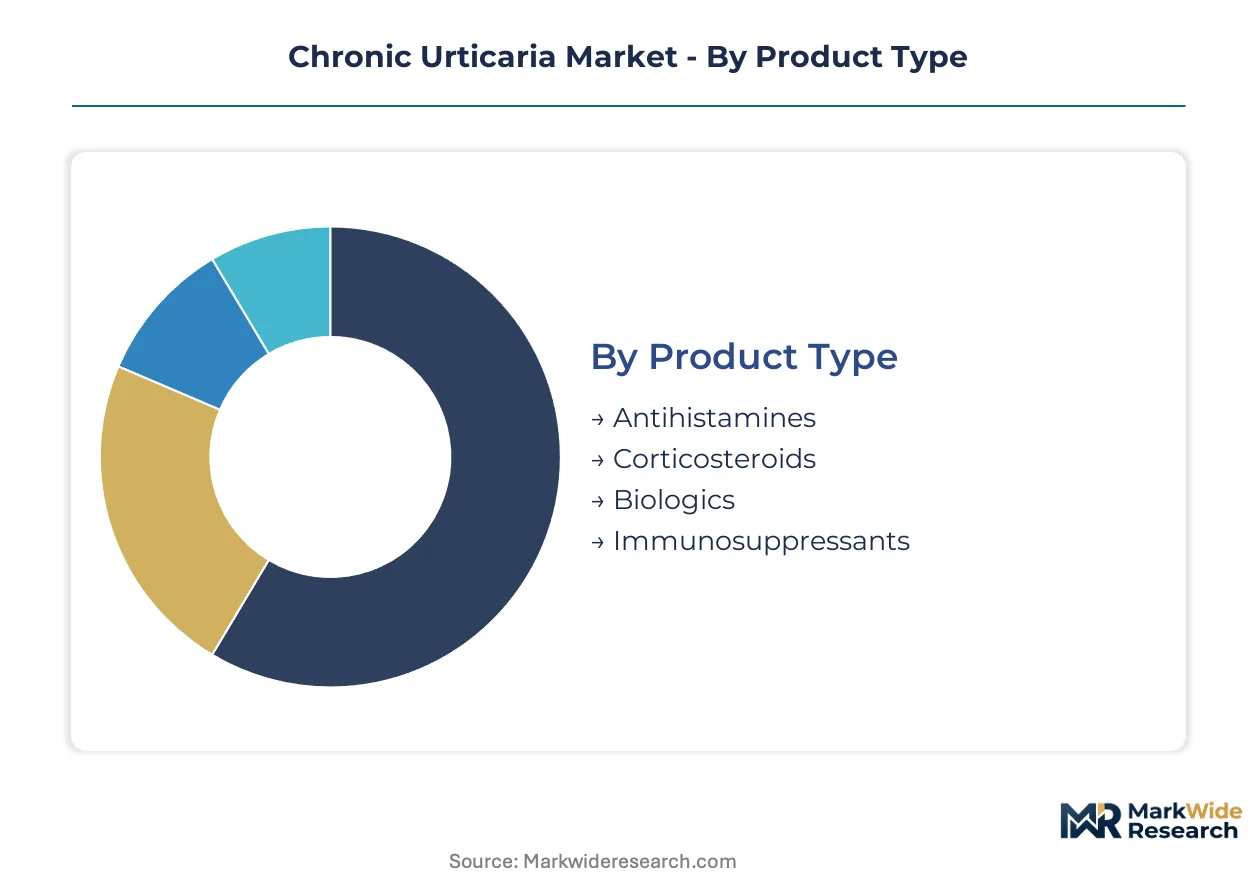
Segmentation in chronic urticaria reveals how treatment selection cascades through prescriber specialty, patient severity, and reimbursement tier. Understanding these splits exposes where biologic manufacturers can bypass antihistamine commoditization and where formulation innovation unlocks access.
Product Type:
Prescribers anchor therapy selection on efficacy thresholds versus cost containment pressures, with biologics commanding premium positioning where histamine blockade fails.
- Antihistamines:Second-generation H1 antagonists remain the volume foundation across primary care, with cetirizine and fexofenadine formulations dominating mild-to-moderate cases through generic substitution. Germany's statutory health insurers maintain formulary preference for these molecules, constraining biologic penetration in first-line settings.
- Biologics:Monoclonal antibodies targeting IgE and IL-5 pathways are compressing hospital infusion schedules and displacing corticosteroid bursts in refractory populations. The United States concentrates demand through specialty pharmacy networks that manage prior authorization complexity.
- Corticosteroids:Short-course oral and intramuscular formulations address acute flares where rapid mast cell suppression outweighs long-term safety concerns.
- Immunosuppressants:Cyclosporine and methotrexate reserve indications preserve niche positioning for patients failing both antihistamine escalation and biologic therapy.
Antihistamines lead on scale; biologics lead on momentum.
End User:
Care setting migration follows reimbursement incentives and self-administration feasibility, with homecare gaining structural share where subcutaneous formats eliminate infusion dependency.
- Hospitals:Academic medical centers in Japan and the United States anchor biologic initiation through infusion programs that manage anaphylaxis risk and document outcomes for payer contracts. These institutions concentrate prescribing authority for omalizumab and emerging IL-5 inhibitors.
- Homecare:Autoinjector platforms are displacing hospital-based administration across Germany and France, with specialty pharmacies managing cold chain logistics and patient training. This shift reduces systemic cost burdens while expanding addressable pools in rural geographies.
- Clinics:Dermatology and allergy practices in urban clusters handle dose escalation and combination therapy decisions.
- Pharmacies:Retail channels dominate antihistamine dispensing with limited clinical intervention.
Hospitals retain authority on initiation; homecare captures volume on maintenance.
Treatment Method:
Route selection balances onset speed against patient autonomy, with injectable formats commanding premium positioning where oral bioavailability limits efficacy.
- Injectable:Subcutaneous and intravenous biologics deliver targeted mast cell pathway inhibition with dosing intervals extending to monthly or quarterly schedules. EMA's centralized approval pathways accelerate European commercialization of these formats ahead of full FDA clearance.
- Oral:Antihistamine tablets and corticosteroid tapers retain dominance in mild-to-moderate severity strata where patient preference favors home administration without cold chain constraints.
- Topical:Corticosteroid creams and calcineurin inhibitors address localized wheal patterns with limited systemic exposure.
- Combination Therapy:Stacked antihistamine dosing and biologic add-on protocols reserve positioning for refractory cases exceeding single-agent response thresholds.
Oral formats lead on scale; injectable formats lead on expansion velocity.
Severity Level:
Stratification by disease burden determines reimbursement tier and prescriber specialty, with severe chronic populations qualifying for biologic access through documented quality-of-life impairment.
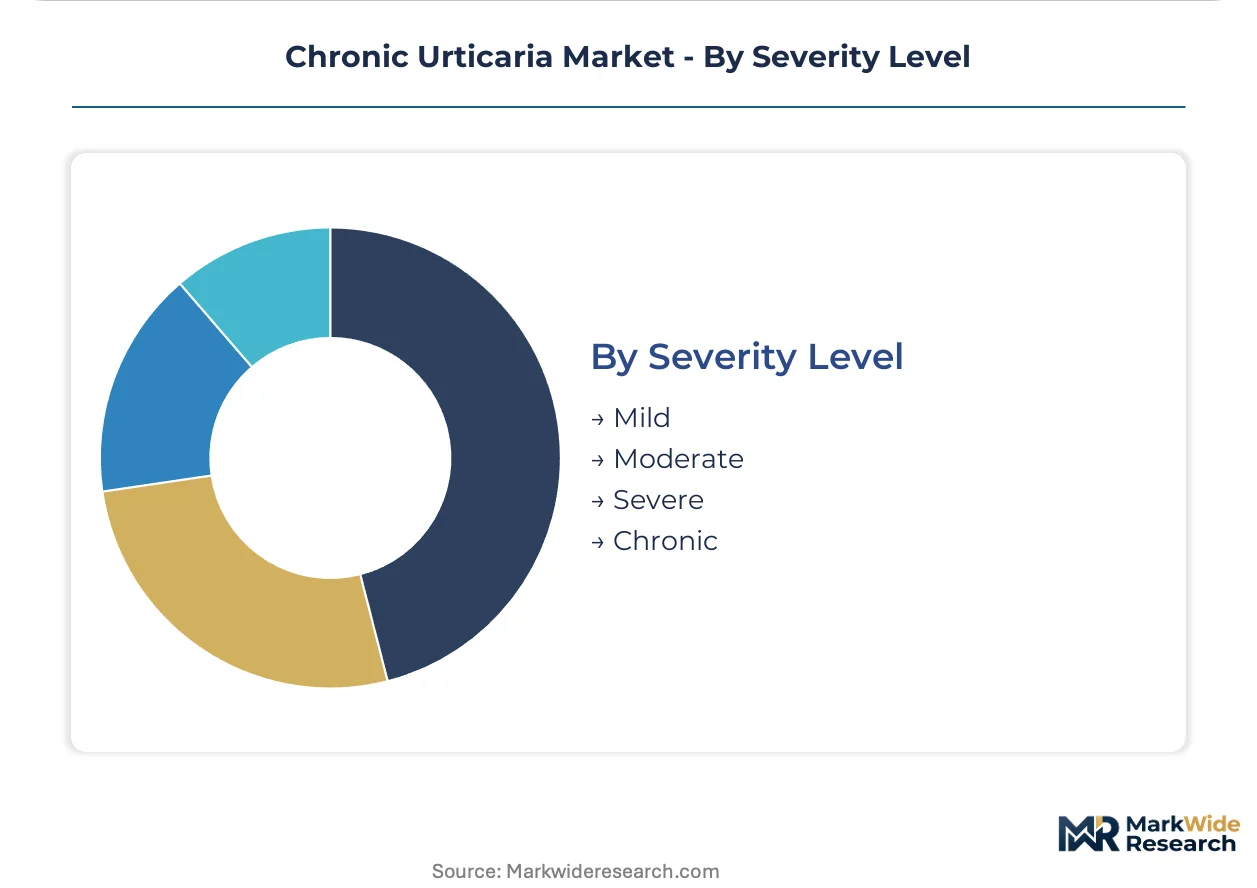
- Severe:Patients with angioedema requiring emergency intervention or continuous corticosteroid dependence qualify for biologic therapy under FDA and PMDA guidelines. Japan's specialized urticaria centers concentrate these cases through referral networks that validate UAS7 scoring for prior authorization.
- Chronic:Persistent wheal activity beyond six weeks defines the addressable population for disease-modifying therapy, with diagnostic delays in primary care creating unmet need in undifferentiated cases.
- Mild:Intermittent symptoms managed through trigger avoidance and as-needed antihistamine use.
- Moderate:Regular antihistamine prophylaxis with occasional corticosteroid rescue.
Chronic classification defines market scope; severe classification defines revenue concentration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The chronic urticaria therapeutics industry traces its modern biologic foundation to Swiss and German pharmaceutical innovation hubs that pioneered monoclonal antibody manufacturing for mast cell-mediated diseases. From these origins, commercialization networks now concentrate in five national markets where specialized care infrastructure and reimbursement frameworks determine patient access to advanced therapies.
United States
FDA accelerated approval pathways compress development timelines for IgE and IL-5 inhibitors, attracting biologic developers seeking first-mover positioning. The agency's breakthrough therapy designation creates regulatory leverage for candidates demonstrating strong early efficacy signals. Specialty pharmacy networks in Boston and the Research Triangle Park corridor manage prior authorization complexity and cold chain distribution for self-administered injectables.
Germany
Statutory health insurers maintain formulary preference for second-generation antihistamines, constraining biologic penetration in primary care despite established efficacy data. EU Green Deal compliance requirements for lower-carbon production audits reshape procurement criteria under hospital sustainability mandates. The Rhine-Main biopharma cluster anchors European supply continuity through integrated fill-finish capacity for temperature-sensitive formulations.
Japan
PMDA guidelines concentrate severe chronic urticaria cases within specialized treatment centers that validate UAS7 scoring for biologic prior authorization. METI industrial policy supports domestic manufacturing of autoinjector platforms to reduce import dependency for maintenance therapy delivery. Tokyo and Osaka academic medical centers anchor referral networks that centralize prescribing authority for omalizumab and emerging pipeline candidates.
Switzerland
Swissmedic maintains stringent post-market surveillance requirements that extend pharmacovigilance commitments for biologics targeting mast cell pathways. The country's contract manufacturing organizations control critical fill-finish capacity for European supply chains, creating single-source vulnerabilities during demand surges. Basel and Zürich pharmaceutical corridors concentrate R&D investment in next-generation monoclonal antibodies with extended dosing intervals.
United Kingdom
NICE technology appraisals determine NHS reimbursement for biologic therapies based on cost-per-quality-adjusted-life-year thresholds that favor established antihistamine regimens in mild-to-moderate populations. The MHRA's independent regulatory pathway post-Brexit accelerates approval timelines for candidates with EMA precedent. London and Cambridge biotech clusters specialize in pediatric indication expansion for therapies with established adult efficacy profiles.
Chronic Urticaria Market Key Industry Players
Premium-margin players sit above commodity-margin players across the efficacy-certification divide, with biologic developers commanding price multiples over generic antihistamine manufacturers. The market exhibits tiered concentration: a handful of integrated pharmaceutical conglomerates control biologic commercialization infrastructure while numerous regional formulators compete on antihistamine volume. Three archetypes dominate positioning: biologic originators with autoinjector platforms, generic antihistamine specialists with pharmacy channel dominance, and emerging immunotherapy developers targeting refractory populations. Competitive moves center on pediatric label expansion and outcome-based contracting with hospital pharmacy committees.
Among Swiss and German integrated pharmaceutical conglomerates, F. Hoffmann-La Roche Ltd., Novartis AG, and Bayer AG exemplify the biologic originator archetype. These Basel- and Leverkusen-based entities anchor European supply infrastructure through captive manufacturing networks and deep R&D investment in mast cell pathway modulation. Sanofi and AbbVie Inc. occupy complementary positions within the injectable formulation tier, with Paris- and North Chicago-based operations competing on manufacturing scale and self-administration platform development. Teva Pharmaceutical Industries Ltd. represents the generic-specialist archetype, with Petah Tikva-based operations maintaining pharmacy channel presence through second-generation H1 antagonist portfolios.
| Leading Market Players |
|---|
| F. Hoffmann-La Roche Ltd. |
| Merck & Co., Inc. |
| Sanofi |
| Teva Pharmaceutical Industries Ltd. |
| AbbVie Inc. |
| Novartis AG |
| Bayer AG |
| Celldex Therapeutics |
| GlaxoSmithKline |
| Others |
Cost & Logistics Intelligence
Captive biologics manufacturing networks in Switzerland and Ireland anchor supply positions for temperature-sensitive injectables while enabling premium pricing power through fill-finish scarcity. This integration pattern concentrates cost control among originators with in-house capacity, forcing contract-dependent competitors into price concessions during tender negotiations.
Pricing Analysis
Outcome-based rebate structures with hospital pharmacy committees now dominate biologic procurement in Germany and France, displacing list-price competition. Price differentiation rests on UAS7 scoring thresholds and pediatric label status, with severe-refractory indications commanding multiples over maintenance therapy. Cost compression in antihistamine tiers intensifies because statutory insurers enforce generic substitution for second-generation H1 antagonists. Primary care prescribers exhibit highest price sensitivity; academic medical center formulary directors prioritize efficacy metrics over unit cost.
Supply Chain Analysis
Direct-to-specialty-pharmacy channels handle autoinjector distribution for homecare patients across the United States and Germany, bypassing wholesale consolidation. Manufacturing concentrates in Switzerland, Ireland, and the United States, where contract organizations control critical cold chain capacity for monoclonal antibodies. Active pharmaceutical ingredient sourcing draws from Indian and Chinese chemical synthesis hubs, creating tariff exposure under evolving trade frameworks. Single-source vulnerabilities in fill-finish capacity intensify during demand surges for quarterly-dosing biologics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story: prescriber expertise concentrates in specialized urticaria centers that demand documented efficacy outcomes, shifting procurement toward premium biologics with robust real-world evidence packages.
For Market Incumbents: Deploy outcome-based contracting to lock hospital pharmacy committee relationships before biosimilar entry accelerates. Expand autoinjector platform manufacturing in the Rhine-Main cluster to reduce Swiss fill-finish dependency. Deepen pediatric indication data packages to extend exclusivity windows against follow-on biologics targeting adult-only labels.
For New Entrants and Emerging Players: Rural homecare patients in Germany and France face autoinjector training gaps that create whitespace for specialized nursing support services. Target adolescent chronic urticaria populations where established adult therapies lack supplementary approvals. Pursue EMA adaptive licensing pilots to compress European commercialization timelines ahead of FDA precedent.
For Investors and Strategic Acquirers: Roll-up economics work for mid-cap immunotherapy developers because prescriber concentration in specialized centers reduces customer acquisition costs for novel mechanisms. Five-to-ten year viability hinges on IL-5 pathway validation and mast cell-targeting platform breadth. Watch FDA breakthrough therapy designation velocity as inflection signal for competitive entry sequencing.
| Strategic Initiative | Industry Significance |
|---|---|
| Pediatric Indication Expansion | Supplementary approvals in adolescent populations extend exclusivity against biosimilar pressure. |
| Autoinjector Platform Development | Self-administration formats reduce hospital dependency and expand rural patient access. |
| EU Green Deal Compliance Certification | Lower-carbon production audits unlock preferred procurement under European hospital sustainability mandates. |
| Outcome-Based Rebate Structuring | UAS7-scored contracts align pricing with documented quality-of-life improvements for formulary directors. |
| Cold Chain Logistics Partnership | Specialized last-mile distribution mitigates temperature excursion risks for homecare patients. |
Research Approach
Multiple input streams — regulatory filings, clinical trial registries, and hospital procurement databases — were reconciled through bottom-up and top-down triangulation. Primary interviews captured perspectives from drug development executives, regulatory affairs leads, formulary directors, and payer access specialists across the United States, Germany, and Japan. Secondary validation drew from FDA filings, EMA submissions, ClinicalTrials.gov records, and statutory health insurer formulary databases.
Historical volume trajectories were cross-referenced against panel input from hospital pharmacy committees and specialty pharmacy networks to construct the analytical framework. Segmentation dimensions modeled include treatment line, administration route, patient severity stratification, and regional regulatory cluster. CAGRs were derived through trend extrapolation adjusted for pipeline entry probabilities and biosimilar erosion curves. Forecast inputs incorporated prior authorization approval rates and cold chain infrastructure expansion timelines.
Inputs from EMA centralized approval pathways and PMDA specialized center networks were available through the study window; gaps in real-world UAS7 scoring data from primary care settings introduce uncertainty bands around patient identification rates. Forecasts reflect assumptions regarding regulatory acceleration mechanism stability and biologic interchangeability guidance evolution. Periodic stress-testing of base assumptions against biosimilar launch sequencing and REACH compliance timeline shifts is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Global Acquired Aplastic Anemia Market
Specialty Medicine
Necrobiosis Lipoidica Diabeticorum Market
Specialty Medicine
Global Huntingtons Disease Treatment Market
Specialty Medicine
Behcet's Syndrome Market
Specialty Medicine
Middle East and Africa Primary Angle-Closure Glaucoma Market
Specialty Medicine
Diamond-Blackfan Anemia Syndrome Therapeutics Market
Specialty Medicine
Global Targeted Cancer Therapy Market
Specialty Medicine
Dravet Syndrome Treatment Market
Specialty Medicine
Atrophic Vaginitis Treatment Market
Specialty Medicine
Intramedullary Osteosarcoma Treatment Market
Specialty Medicine
Serotonin Syndrome Market
Specialty Medicine
Cutaneous Radiation Injury Treatment Market
Specialty Medicine
Osteomyelitis Market
Specialty Medicine
Global Addison's Disease Treatment Market
Specialty Medicine
Fibrodysplasia Ossificans Progressiva (FOP) Treatment Market
Specialty Medicine
Cellulitis Management Market