
 Treatment-Resistance Depression Treatment Market | 2026-2036
Treatment-Resistance Depression Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Treatment-Resistance Depression Treatment Market Analytics
Ketamine is repositioning treatment economics by displacing chronic oral antidepressant regimens with acute intravenous protocols that command premium reimbursement. Eli Lilly and Company leverages its endocrinology-neuroscience crossover platform to sustain pipeline momentum in glutamatergic modulation. Janssen Pharmaceuticals anchors the esketamine nasal spray segment through controlled distribution networks. Pfizer Inc. competes by extending its neuropsychiatry portfolio into novel NMDA-targeting mechanisms.
Treatment-Resistance Depression Treatment encompasses therapeutic interventions for patients who fail at least two adequate antidepressant trials, typically requiring biomarker-guided patient selection and structured outcome measurement to justify invasive or high-cost modalities. The primary purpose is remission induction rather than maintenance, with electroconvulsive therapy retaining dominance in catatonic and life-threatening presentations while transcranial magnetic stimulation captures outpatient volume through its favorable cognitive side-effect profile. Ketamine infusion represents the fastest-growing treatment type as private payers expand coverage for refractory cases, though psychotherapy maintains the deepest margin pool through scalable digital delivery formats. Patient profile segmentation shows chronic depression occupying the largest addressable base, with bipolar depression representing the most underserved subset due to mania-risk exclusion criteria.
FDA breakthrough therapy designation and EMA priority medicines status shape competitive timelines by compressing Phase III-to-approval intervals for novel mechanisms. The EU AI Act and FDA software-as-medical-device guidance are forcing teletherapy platforms to validate algorithmic patient-triage tools through prospective clinical studies. Stakeholders must monitor how CMS national coverage determinations for at-home ketamine administration will redistribute volume between hospitals and remote care providers.
Market Dynamics
The FDA breakthrough therapy designation for rapid-acting antidepressants is compressing clinical development timelines and forcing established psychiatric service lines to restructure around acute intervention protocols rather than chronic disease management.
Growth Catalysts
- EMA adaptive pathway reforms:Accelerated conditional approvals for novel glutamatergic agents reduce time-to-market for European biopharma developers, expanding prescriber choice in refractory depression.
- Specialty psychiatric clinics:Outpatient neurostimulation centers in the United States and Germany are scaling transcranial magnetic stimulation capacity to capture patients failing oral antidepressant trials.
- Biomarker-guided patient selection:Inflammatory and neuroimaging stratification tools are improving response prediction, justifying premium reimbursement for targeted ketamine protocols.
Market Restraints
- Reimbursement volatility:CMS national coverage determinations for at-home esketamine administration remain unresolved, creating payment uncertainty for remote care providers.
- Supply concentration in controlled substances:DEA quota restrictions on ketamine API limit compounding pharmacy capacity and create bottlenecks for infusion center expansion.
- Cognitive side-effect liability:Electroconvulsive therapy's memory impairment profile restricts outpatient adoption despite superior remission rates in catatonic presentations.
Strategic Opportunities
- Japan's aging population:METI reimbursement reforms for interventional psychiatry create entry pathways for neurostimulation device manufacturers in an underpenetrated market.
- Digital therapeutic convergence:Algorithm-guided cognitive behavioral therapy platforms paired with pharmacotherapy are opening scalable margin pools outside traditional service delivery.
- EMA priority medicines status:Expedited regulatory review for novel NMDA-targeting mechanisms offers first-mover positioning in European rapid-acting antidepressant segments.
Industry Challenges
- Interventional psychiatry workforce gaps:Certified anesthesiologists and psychiatric nurses trained in ketamine administration remain concentrated in urban academic medical centers.
- Integration complexity with electronic health records:Structured outcome measurement tools required for prior authorization do not interface with legacy hospital information systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Treatment-Resistance Depression Treatment Market |
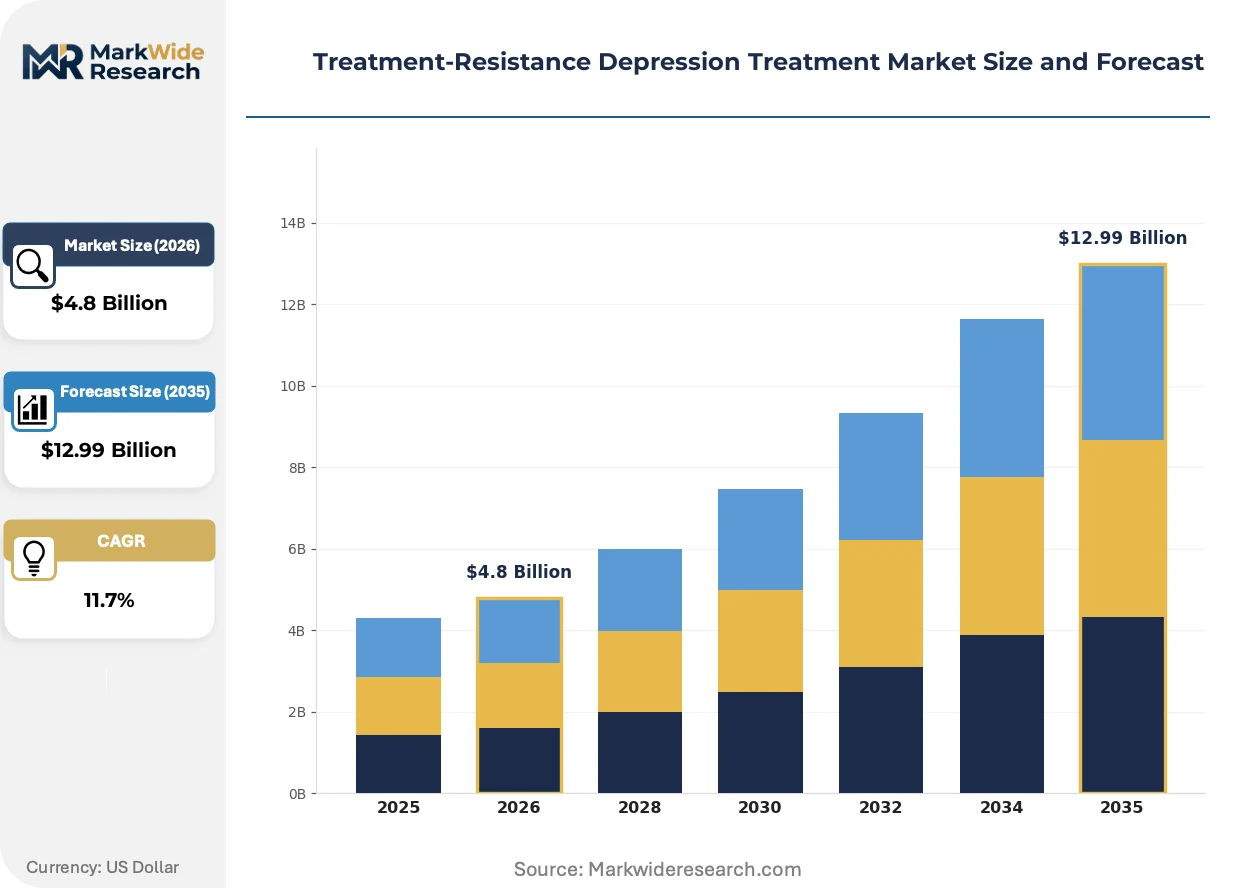
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Treatment Type: Psychotherapy, Electroconvulsive Therapy, Transcranial Magnetic Stimulation, Ketamine Infusion Patient Profile: Chronic Depression, Major Depressive Disorder, Bipolar Disorder, Generalized Anxiety Disorder Delivery Mode: Inpatient, Outpatient, Teletherapy, Home-Based Care End User: Clinics, Hospitals, Private Practices, Remote Care Providers |
| Companies Covered | Eli Lilly and Company, GlaxoSmithKline, Pfizer Inc., Janssen Pharmaceuticals, AbbVie Inc., AstraZeneca, H. Lundbeck A/S, Otsuka Pharmaceutical Co., Ltd., Sandoz International GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Treatment-Resistance Depression Treatment Market Evolving Landscape
Neurostimulation hardware and algorithmic patient monitoring are converging to reshape how treatment-resistant depression is managed outside traditional inpatient settings.
Closed-loop transcranial magnetic stimulation systems are automating real-time EEG feedback to adjust pulse parameters during sessions. Outpatient psychiatric clinics in Germany and the United States are piloting these platforms to reduce technician oversight requirements. The technology is automating protocol standardization that previously depended on operator judgment, compressing training costs for clinic expansion.
The EU AI Act's risk classification framework for software-as-medical-device is forcing teletherapy platforms to validate algorithmic triage tools through prospective clinical studies. European digital therapeutic developers must now document clinical equivalence to human-delivered cognitive behavioral therapy before CE marking. Remote patient monitoring segments face the steepest compliance burden, with several platforms restructuring data governance architectures to meet conformity assessment requirements.
Private payer prior authorization departments are unbundling episode-based reimbursement for ketamine infusion from facility fees. United States employers and regional health plans are negotiating direct contracts with freestanding psychiatric clinics, bypassing hospital outpatient department markups. This channel disintermediation is most visible in Texas and Florida, where certificate-of-need restrictions on neurostimulation equipment do not apply.
Treatment-Resistance Depression Treatment Market Segmentation
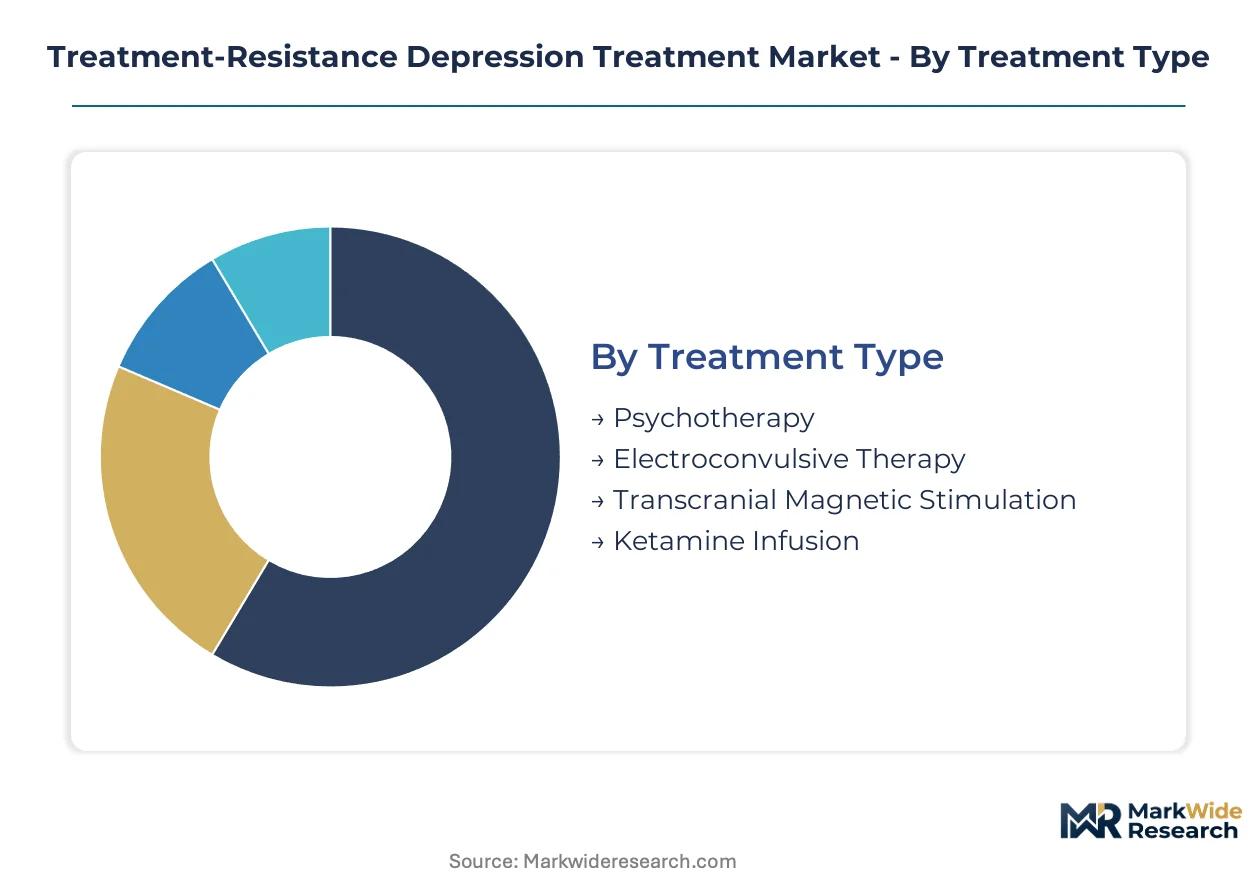
Segmentation in treatment-resistant depression reveals how reimbursement pathways and clinical infrastructure shape access to high-cost interventions. Patient stratification and delivery mode selection determine whether novel therapies reach refractory populations or remain concentrated in academic medical centers.
Treatment Type:
Mechanism of action and regulatory classification separate acute intervention protocols from maintenance-oriented modalities.
- Ketamine Infusion:Intravenous racemic ketamine protocols leverage NMDA receptor antagonism to induce rapid symptom relief within hours. United States private payers in Texas and Florida are expanding prior authorization frameworks for freestanding clinics, though DEA quota restrictions on API supply constrain compounding pharmacy capacity.
- Transcranial Magnetic Stimulation:Non-invasive magnetic coil systems deliver focal cortical stimulation without anesthesia requirements. German outpatient psychiatric centers are scaling technician-light protocols through automated pulse-parameter systems, capturing patients who fail oral antidepressant trials.
- Electroconvulsive Therapy:Anesthesia-mediated seizure induction remains the standard for catatonic and life-threatening presentations despite cognitive side-effect liability.
- Psychotherapy:Cognitive behavioral and dialectical behavior protocols maintain the deepest margin pool through scalable digital delivery formats.
Psychotherapy leads on scale; ketamine infusion leads on momentum.
Patient Profile:
Disease chronicity and comorbidity burden dictate eligibility for invasive or high-cost modalities.
- Chronic Depression:Patients with recurrent episodes exceeding two years represent the largest addressable base for maintenance neurostimulation protocols. United States Medicare Advantage plans are piloting episode-based reimbursement for transcranial magnetic stimulation in this population.
- Bipolar Disorder:Mania-risk exclusion criteria leave this subset the most underserved, with ketamine protocols generally restricted to depressive phases under psychiatric monitoring.
- Major Depressive Disorder:First-line pharmacotherapy failures in this category drive demand for rapid-acting antidepressant alternatives.
- Generalized Anxiety Disorder:Comorbid presentations complicate treatment selection and require combined pharmacotherapy-psychotherapy approaches.
Chronic depression dominates volume; bipolar disorder presents the steepest unmet need.
Delivery Mode:
Site-of-care economics and regulatory risk classification determine channel expansion feasibility.
- Outpatient:Freestanding psychiatric clinics in Germany and the United States are capturing volume through lower facility fees compared to hospital outpatient departments.
- Teletherapy:Algorithm-guided platforms face EU AI Act compliance burdens requiring prospective clinical validation for CE marking.
- Inpatient:Reserved for catatonic presentations, severe suicidality, and electroconvulsive therapy requiring anesthesia support.
- Home-Based Care:CMS national coverage determinations for at-home esketamine administration remain unresolved, creating payment uncertainty.
Outpatient channels capture the greatest share expansion; home-based care faces the steepest regulatory climb.
End User:
Capital intensity and workforce certification requirements concentrate advanced modalities in specific provider categories.
- Clinics:Specialty psychiatric clinics in the United States and Germany are scaling transcranial magnetic stimulation and ketamine infusion capacity through direct payer contracts.
- Hospitals:Academic medical centers retain dominance in electroconvulsive therapy and complex case management requiring multidisciplinary teams.
- Private Practices:Individual psychiatric practices are adopting digital therapeutic platforms to extend reach without capital equipment investment.
- Remote Care Providers:Telehealth platforms are restructuring data governance architectures to meet EU AI Act conformity assessment requirements.
Clinics are gaining share fastest; hospitals retain the highest-acuity cases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialty psychiatric clinics in the United States anchor the treatment-resistant depression treatment market through advanced neurostimulation infrastructure and ketamine infusion capacity. Germany and Japan follow with mature reimbursement frameworks for interventional psychiatry. Regulatory divergence across FDA, EMA, and PMDA pathways shapes competitive access timelines for novel rapid-acting antidepressants.
United States
Freestanding psychiatric clinics in Texas and Florida are scaling ketamine infusion capacity through direct payer contracts that bypass hospital outpatient department markups. FDA breakthrough therapy designations for esketamine and novel glutamatergic agents compress Phase III-to-approval intervals. The Greater Boston cluster concentrates academic medical centers deploying biomarker-guided patient selection for transcranial magnetic stimulation protocols.
Germany
Outpatient psychiatric centers are automating transcranial magnetic stimulation through closed-loop EEG feedback systems that reduce technician oversight requirements. EMA adaptive pathway reforms accelerate conditional approvals for novel antidepressant mechanisms. The Bavaria region hosts device manufacturers piloting real-time pulse-parameter adjustment platforms for clinic network expansion.
Japan
METI reimbursement reforms for interventional psychiatry are creating entry pathways for neurostimulation device manufacturers in an underpenetrated market. PMDA streamlined review pathways for digital therapeutics paired with pharmacotherapy are reshaping prescriber workflows. The Kanto region around Tokyo concentrates psychiatric hospitals integrating electroconvulsive therapy with structured outcome measurement systems.
United Kingdom
NHS England's pilot programs for esketamine nasal spray in specialist mental health services are establishing prior authorization frameworks for rapid-acting antidepressants. MHRA recognition of FDA breakthrough therapy data accelerates parallel import and early access schemes. The London-Southeast corridor anchors private psychiatric clinic chains negotiating direct contracts with employer health plans.
Canada
Health Canada priority review status for NMDA-targeting antidepressants aligns regulatory timelines with FDA and EMA pathways. Provincial formularies in Ontario and British Columbia are expanding coverage for transcranial magnetic stimulation in treatment-resistant cases. The Toronto-Waterloo corridor concentrates telehealth platforms restructuring data governance to meet prospective clinical validation requirements.
Treatment-Resistance Depression Treatment Market Competitive Landscape
Portfolio diversification into glutamatergic modulation dominates the current landscape as established neuropsychiatry players reposition around rapid-acting antidepressant mechanisms. The market structure concentrates around large-cap pharmaceutical developers with cross-functional neuroscience platforms and specialty psychiatric service providers scaling interventional protocols. Three archetypes define competitive positioning: endocrinology-neuroscience crossover specialists, controlled-distribution network operators, and NMDA-targeting mechanism pioneers. M&A activity targets digital therapeutic platforms with validated algorithmic triage tools, while strategic partnerships between device manufacturers and clinic networks accelerate neurostimulation capacity deployment.
Within the large-cap pharmaceutical tier, Eli Lilly and Company and Pfizer Inc. occupy positions leveraging established neuroscience infrastructure for novel mechanism development. Janssen Pharmaceuticals exemplifies the controlled-distribution archetype through esketamine nasal spray channel management. These three companies represent distinct strategic vectors: crossover platform exploitation, portfolio extension into NMDA targeting, and restricted-access network optimization for scheduled compounds.
| Leading Market Players |
|---|
| Eli Lilly and Company |
| GlaxoSmithKline |
| Pfizer Inc. |
| Janssen Pharmaceuticals |
| AbbVie Inc. |
| AstraZeneca |
| H. Lundbeck A/S |
| Otsuka Pharmaceutical Co., Ltd. |
| Sandoz International GmbH |
| Others |
Value Network & Pricing Analysis
Closed-loop neurostimulation automation is compressing per-session labor costs while concentrating device manufacturing expertise in Germany and the United States, simultaneously lowering clinic expansion barriers and tightening supply control among EEG-integrated hardware developers.
Pricing Analysis
API cost pass-through from DEA-controlled ketamine quotas directly shapes infusion protocol economics, with compounding pharmacies absorbing margin compression when bulk supply tightens. Pricing stratifies across academic medical centers, freestanding specialty clinics, and teletherapy platforms based on anesthesia staffing requirements and outcome measurement infrastructure. Downward pressure runs through digital therapeutic segments as EU AI Act compliance costs force platform consolidation. Employer health plans exhibit highest price sensitivity, while Medicare Advantage programs prioritize episode-based value over per-unit costs.
Supply Chain Analysis
Dual-sourcing mandates from United States hospital systems and German outpatient networks require qualified suppliers for both magnetic coil hardware and controlled-substance APIs, spreading procurement across domestic manufacturers and Swiss pharmaceutical compounders. Ketamine API production concentrates in India and the United States, while neurostimulation device assembly anchors in Germany and Japan. Supply chain risk centers on DEA quota volatility for scheduled compounds. Distribution runs through controlled distribution networks for esketamine and direct manufacturer-to-clinic contracts for TMS hardware.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Treatment-resistant depression functions as a stable compounder anchored by irreversible psychiatry workforce specialization and reimbursement framework maturation in interventional protocols.
For Market Incumbents: Hedge against ketamine supply disruption by securing long-term API offtake agreements with Indian and United States manufacturers before DEA quota tightening accelerates. Deepen vertical integration into automated TMS hardware production to capture clinic network expansion economics and defend against device manufacturer direct-to-provider sales models. For New Entrants and Emerging Players: Enter via Japan's underpenetrated neurostimulation market where METI reimbursement reforms have created first-mover windows for closed-loop TMS platforms. Target bipolar depression protocols as the most underserved patient profile, leveraging digital therapeutic pairing strategies to bypass mania-risk exclusion barriers that constrain incumbent ketamine offerings. For Investors and Strategic Acquirers: Valuations sit cheapest among digital therapeutic developers with validated algorithmic triage tools and prospective clinical data packages. Long-term viability across the analysis window hinges on CMS national coverage determination outcomes for home-based esketamine administration. Watch FDA breakthrough therapy designation velocity for novel glutamatergic mechanisms as the primary inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | FDA breakthrough therapy designation compresses Phase III-to-approval intervals for rapid-acting antidepressants. |
| Reimbursement Strategy | CMS national coverage determinations for at-home esketamine administration would redistribute volume to remote care providers. |
| Hospital System Partnership | Academic medical center alliances secure high-acuity case flow and biomarker-guided patient selection infrastructure. |
| Software Companion Development | Algorithm-guided CBT platforms paired with pharmacotherapy open scalable margin pools outside traditional service delivery. |
| CE Marking Pathway | EU AI Act compliance requires prospective clinical validation for algorithmic triage tools before European market entry. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with drug development executives, regulatory affairs leads, formulary directors at United States payers, and hospital procurement managers with secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov records, and CMS Medicare reimbursement databases. Bottom-up clinic capacity modeling and top-down pharmaceutical revenue triangulation anchored market sizing.
Comparable historical periods across neurostimulation adoption curves and ketamine reimbursement expansions anchored the projection horizon, with segmentation modeling across treatment type, patient profile, delivery mode, and end user. CAGRs derived from clinician interview-based adoption rate assumptions and payer coverage trajectory analysis, incorporating DEA quota policy scenarios and EMA adaptive pathway reform timelines as scenario inputs.
Inputs from FDA, EMA, and PMDA regulatory databases were available through the study window; gaps in real-time private payer prior authorization volume introduce uncertainty bands around outpatient channel forecasts. Deviation in CMS national coverage determinations for at-home esketamine administration would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Sports Medicine Market
Specialty Medicine
Solid Tumor Therapeutics Market
Specialty Medicine
Neuromuscular Disorders Treatment Market
Specialty Medicine
Global Alopecia Market
Specialty Medicine
Impetigo Therapeutic Market
Specialty Medicine
Severe Hypertriglyceridemia (SHTG) Treatment Market
Specialty Medicine
Gingivostomatitis Market
Specialty Medicine
Marfan Syndrome Management Market
Specialty Medicine
Granulomatosis with Polyangiitis Treatment Market
Specialty Medicine
Eosinophilia Therapeutics Market
Specialty Medicine
Postmenopausal Osteoporosis Treatment Market
Specialty Medicine
Asperger Syndrome Market
Specialty Medicine
Listeriosis Treatment Market
Specialty Medicine
Dermatomyositis Treatment Market
Specialty Medicine
Rumination Syndrome Market
Specialty Medicine
Bronchiectasis Market